
 Cardiac Rhythm Management Devices Market | 2026-2036
Cardiac Rhythm Management Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Rhythm Management Devices Market Analysis
Project finance for electrophysiology suite upgrades is narrowing the competitive field to institutions with capital deployment capacity. Medtronic leverages its integrated cath lab ecosystem to sustain service contracts across major hospital networks. Abbott differentiates through leadless pacemaker platforms that reduce complication rates in frail populations. Boston Scientific Corporation anchors its position with subcutaneous defibrillator technology that eliminates transvenous lead risks.
Cardiac rhythm management devices comprise implantable and external systems that monitor, regulate, or restore normal cardiac electrical activity through programmed electrical stimulation, often operating at 2.8V pulse amplitudes with sub-millisecond pulse widths. These systems treat bradyarrhythmias, tachyarrhythmias, and heart failure by detecting abnormal rhythms and delivering corrective pulses or shocks. Pacemakers dominate installed volume due to decades of clinical validation and streamlined implant workflows. Leadless technology represents the fastest-growing segment as it eliminates lead-related infections and extraction morbidity. Wireless monitoring platforms concentrate margin pools through recurring remote monitoring subscription revenues.
FDA premarket approval requirements and the EU Medical Device Regulation shape product development timelines and clinical evidence burdens for manufacturers seeking market access. The EPA governs disposal protocols for lithium-iodine batteries contained in explanted devices, adding compliance costs to hospital supply chains. Stakeholders must weigh capital intensity against reimbursement velocity when allocating R&D across next-generation battery chemistries and AI-integrated diagnostic algorithms.
Market Dynamics
Leadless pacemaker platforms are compressing traditional transvenous system volumes while hospital capital allocation constraints concentrate purchasing power among integrated delivery networks with dedicated electrophysiology infrastructure.
Growth Catalysts
- Germany's statutory health insurance expansion:Broader reimbursement for cardiac resynchronization therapy devices has unlocked patient access across previously excluded risk categories, accelerating implant volumes in tertiary centers.
- Remote monitoring subscription models:Wireless telemetry platforms generate recurring revenue streams that offset upfront device margins, creating financial incentives for manufacturer investment in cloud infrastructure and predictive analytics.
- Electrophysiology lab capacity buildouts:US hospital systems are channeling capital into dedicated arrhythmia suites, expanding addressable procedure volumes and creating captive demand for compatible device ecosystems.
Market Restraints
- Lithium-iodine battery supply concentration:Explant disposal protocols governed by the EPA impose compliance burdens on hospital supply chains, elevating total cost of ownership for implantable devices.
- FDA premarket approval timelines:Extended clinical evidence requirements for leadless systems delay technology transitions and compress R&D return windows for novel battery chemistries.
- Transvenous lead extraction morbidity:Historical complications from legacy systems create physician hesitancy and patient preference shifts that strand installed base upgrade revenues.
Strategic Opportunities
- AI-integrated diagnostic algorithms:Machine learning rhythm classification is converging with implantable sensors to enable preemptive intervention before acute decompensation events.
- Subcutaneous defibrillator penetration:Elimination of transvenous lead risks opens addressable populations previously excluded from implantable cardioverter-defibrillator therapy due to vascular access limitations.
- EU Medical Device Regulation harmonization:Streamlined CE marking pathways for next-generation platforms accelerate market access across member states relative to historical national approval processes.
Industry Challenges
- Electrophysiologist training pipeline constraints:Fellowship program capacity limits specialist availability to operate expanded lab infrastructure, creating procedure bottlenecks despite capital deployment.
- Legacy system integration complexity:Hospital IT architectures require costly middleware development to unify data streams from heterogeneous device manufacturers into centralized monitoring dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Rhythm Management Devices Market |
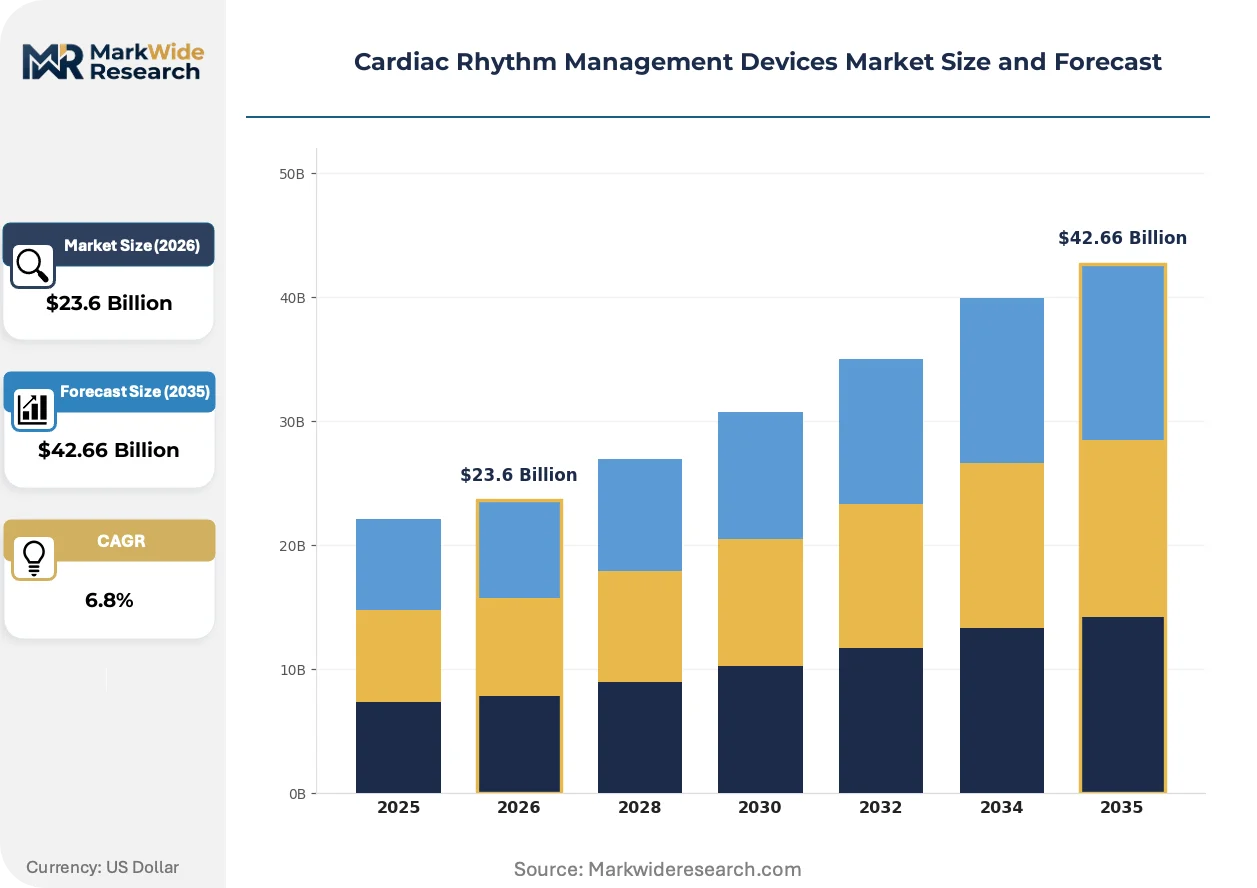
| Market Size in 2026 | $23.6 Billion |
| Market Size in 2035 | $42.66 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pacemakers, Defibrillators, Monitors, Sensors End User: Hospitals, Clinics, Home Care Settings, Cardiac Rehabilitation Centers Technology: Transvenous, Subcutaneous, Leadless, Wireless Application: Atrial Fibrillation, Heart Failure, Arrhythmias, Syncope |
| Companies Covered | BIOTRONIK SE & Co. KG, Koninklijke Philips N.V., Medtronic, LivaNova PLC, ZOLL Medical Corporation, Boston Scientific Corporation, Stryker Corporation, GE HealthCare, Abbott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Rhythm Management Devices Market Emerging Trajectories
Device architecture is fragmenting across miniaturization, energy harvesting, and computational integration axes, with each trajectory demanding distinct manufacturing competencies and regulatory strategies.
Leadless pacemaker technology is hybridizing cardiac stimulation with vascular access elimination. Electrophysiology suites at major academic medical centers in the United States and Germany are adopting these systems for frail patients with compromised venous anatomy. The technology is compressing service line economics by reducing lead extraction procedures and associated complication management costs.
REACH and RoHS substance restrictions are tightening material specifications for implantable electronics across European manufacturing. Component suppliers are reformulating solder compositions and eliminating restricted substances from battery housings to maintain market access. Subcutaneous defibrillator manufacturers face accelerated redesign cycles to comply with evolving substance thresholds.
Hospital purchasing consortia are consolidating device procurement decisions across multi-hospital networks. Integrated delivery networks in the United States are unbundling device selection from implanting physician preference, centralizing contract negotiations with manufacturers offering ecosystem-wide service agreements. This concentration shifts bargaining power toward institutions with electrophysiology volume scale and remote monitoring platform integration capabilities.
Cardiac Rhythm Management Devices Market Segmentation
Segmentation in cardiac rhythm management devices reveals how clinical requirements, anatomical constraints, and care delivery settings fragment purchasing decisions across incompatible technology platforms. Manufacturers must align R&D portfolios against distinct reimbursement pathways and implanting physician specializations that govern adoption velocity.
Product Type:
Cost tier stratification separates commodity implantables from premium systems commanding service contract premiums and remote monitoring subscriptions.
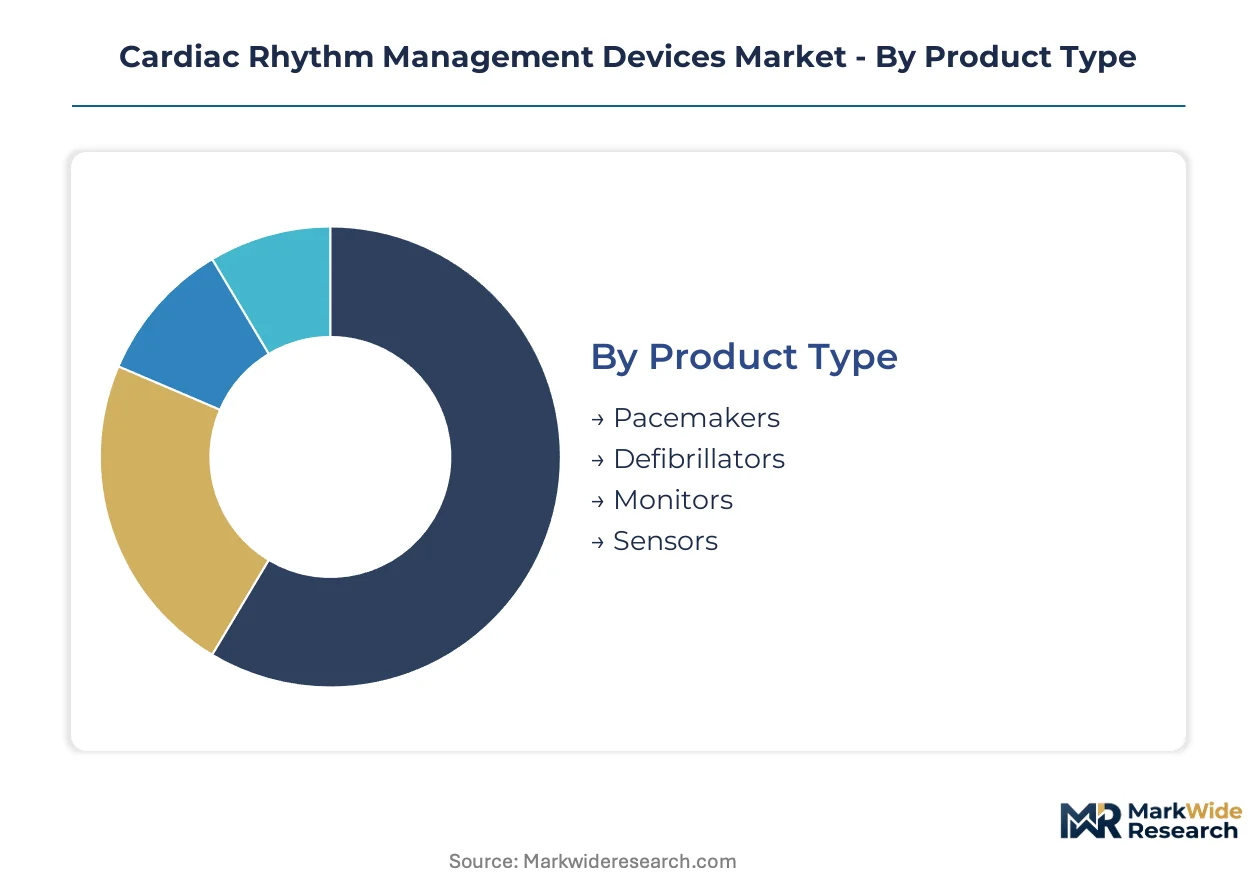
- Pacemakers:Dual-chamber and single-chamber systems deliver programmed electrical stimulation at 2.8V pulse amplitudes with sub-millisecond pulse widths to correct bradyarrhythmias. Demand concentrates in Germany's tertiary centers where statutory health insurance reimbursement has broadened access across risk categories, though lead-related infection management costs pressure margin structures.
- Defibrillators:Implantable cardioverter-defibrillator systems detect ventricular tachyarrhythmias and deliver high-voltage shocks for termination. Subcutaneous variants eliminate transvenous lead risks and open therapy to patients with compromised vascular access in United States academic medical centers, creating differentiation against traditional transvenous platforms.
- Monitors:External and implantable cardiac monitors capture extended rhythm data for cryptogenic stroke evaluation.
- Sensors:Hemodynamic and accelerometer-based sensors enable physiologic rate response and heart failure monitoring.
Pacemakers command the established base. The steepest expansion runs through defibrillators.
End User:
Customer type determines capital intensity requirements, procedure volume economics, and remote monitoring infrastructure investment thresholds.
- Hospitals:Integrated delivery networks in the United States channel capital into dedicated electrophysiology suites with catheterization lab ecosystems. These institutions centralize procurement decisions across multi-hospital networks, unbundling device selection from implanting physician preference and demanding ecosystem-wide service agreements.
- Clinics:Ambulatory surgical centers and cardiology practices perform straightforward pacemaker implants with streamlined workflows.
- Home Care Settings:Remote monitoring platforms and wearable defibrillator systems enable post-acute rhythm management outside institutional walls.
- Cardiac Rehabilitation Centers:Post-implant exercise tolerance testing and device interrogation during structured rehabilitation programs.
Hospitals capture the revenue concentration. Home care settings gain share fastest through wireless telemetry expansion.
Technology:
Maturity gradients separate legacy transvenous platforms from next-generation architectures eliminating historical complication profiles.
- Leadless:Self-contained miniaturized devices anchor directly in the right ventricle via catheter delivery, eliminating lead-related infections and extraction morbidity. Electrophysiology labs at major United States academic centers and German tertiary hospitals deploy these systems for frail patients with compromised venous anatomy, compressing service line economics through reduced complication management.
- Transvenous:Traditional lead-based systems remain dominant in installed volume due to decades of clinical validation.
- Subcutaneous:Defibrillator systems place sensing and shocking electrodes entirely outside the thoracic vasculature.
- Wireless:Telemetry platforms transmit device data to cloud infrastructure without patient-initiated interrogation.
Transvenous technology holds the installed base. Leadless systems climb the fastest as extraction morbidity drives technology transitions.
Application:
Clinical indication severity governs device selection urgency, reimbursement coding, and specialist referral patterns.
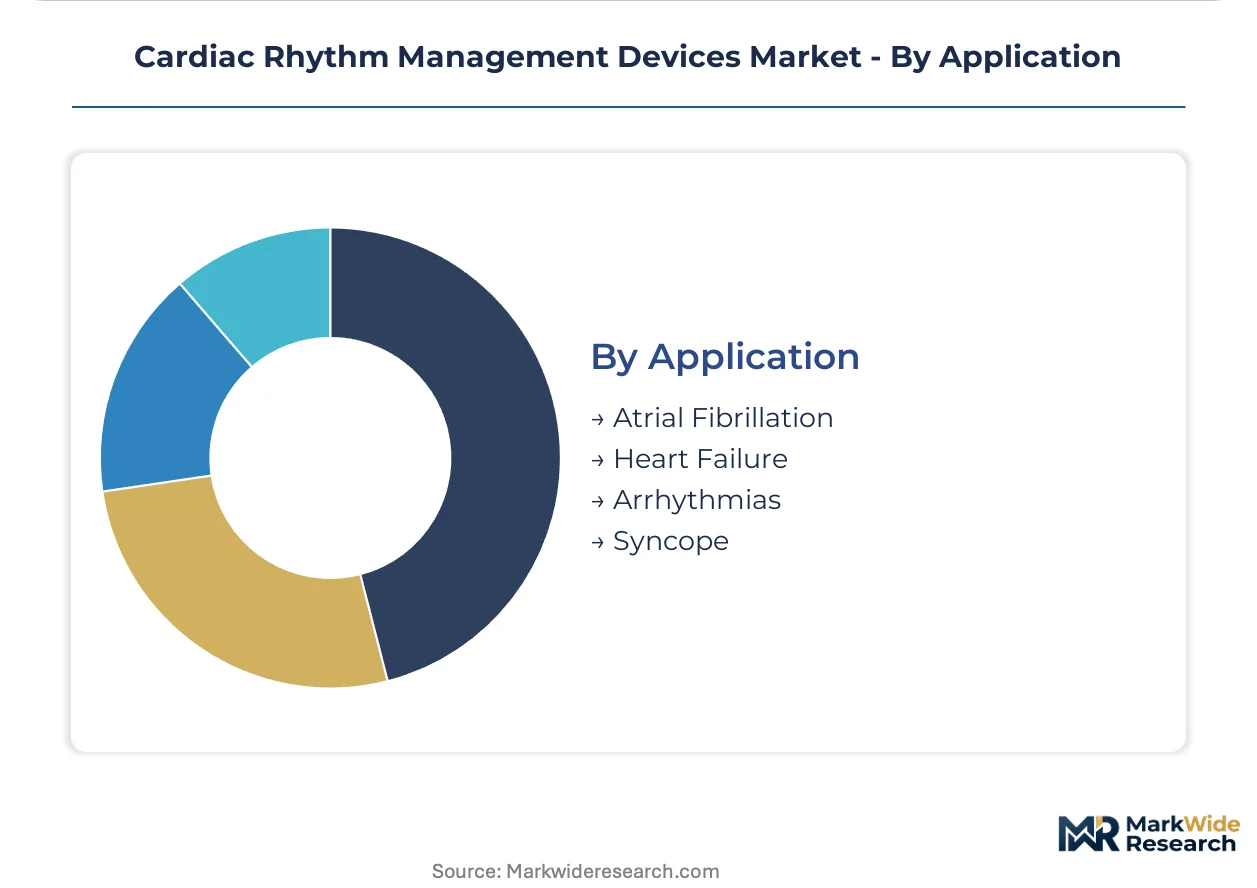
- Atrial Fibrillation:The most prevalent sustained arrhythmia drives ablation procedure volumes and anticoagulation management alongside device therapy for rate or rhythm control. United States hospital systems expanding electrophysiology lab capacity target this indication for catheter ablation and concomitant pacemaker implant when sinus node dysfunction coexists.
- Heart Failure:Cardiac resynchronization therapy devices coordinate biventricular pacing to improve ejection fraction.
- Arrhythmias:Encompassing bradyarrhythmias and tachyarrhythmias beyond atrial fibrillation requiring device intervention.
- Syncope:Recurrent unexplained loss of consciousness prompting loop recorder implantation for rhythm correlation.
Arrhythmias anchor the procedure volume. Atrial fibrillation applications expand most quickly through ablation-device combination therapies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated delivery networks with dedicated electrophysiology infrastructure concentrate purchasing power in the United States and Germany, while tertiary hospital systems in Japan and the United Kingdom expand catheterization lab capacity to capture rising arrhythmia procedure volumes.
United States
Hospital systems channel capital into dedicated electrophysiology suites with catheterization lab ecosystems, expanding addressable procedure volumes for implantable devices. FDA premarket approval pathways for leadless pacemaker systems accelerate technology transitions while compressing R&D return windows. Major academic medical centers in Boston and Cleveland adopt leadless systems for frail patients with compromised venous anatomy.
Germany
Statutory health insurance reimbursement for cardiac resynchronization therapy has broadened patient access across previously excluded risk categories, accelerating implant volumes in tertiary centers. EU Medical Device Regulation shapes product development timelines and clinical evidence burdens for manufacturers seeking CE marking. Electrophysiology labs in Berlin and Munich concentrate leadless pacemaker adoption for complication reduction.
Japan
PMDA regulatory frameworks govern market access timelines for next-generation battery chemistries and AI-integrated diagnostic algorithms. Aging demographics drive demand for cardiac rhythm management devices in metropolitan hospital systems. Tokyo and Osaka academic medical centers anchor subcutaneous defibrillator penetration for patients with vascular access limitations.
United Kingdom
NHS procurement frameworks consolidate device purchasing decisions across hospital networks, centralizing contract negotiations with manufacturers offering ecosystem-wide service agreements. MHRA post-Brexit regulatory pathways diverge from EU MDR harmonization efforts. London and Manchester electrophysiology suites expand capacity to manage rising atrial fibrillation caseloads.
India
CDSCO regulatory requirements shape import and domestic manufacturing pathways for implantable cardiac devices. Private hospital chains in metropolitan centers deploy capital into electrophysiology infrastructure to capture medical tourism flows. Delhi-NCR and Mumbai tertiary institutions concentrate leadless pacemaker adoption among self-pay patient segments.
Cardiac Rhythm Management Devices Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Consolidated purchasing power among integrated delivery networks favors manufacturers with ecosystem-wide service contracts and remote monitoring platform integration. Strategic archetypes include integrated cath lab ecosystem providers, leadless technology specialists, and subcutaneous defibrillator innovators. Dominant competitive moves encompass strategic partnerships for cloud infrastructure development and portfolio diversification into AI-integrated diagnostic algorithms.
Within the integrated ecosystem tier, Medtronic and Abbott exemplify channel-control strategies through service contract anchoring across major hospital networks. Boston Scientific Corporation occupies a position representing subcutaneous defibrillator specialization that eliminates transvenous lead risks. Among European-based manufacturers, BIOTRONIK SE & Co. KG sits within the product-specialist archetype focused on implantable cardiac stimulation systems.
| Leading Market Players |
|---|
| BIOTRONIK SE & Co. KG |
| Koninklijke Philips N.V. |
| Medtronic |
| LivaNova PLC |
| ZOLL Medical Corporation |
| Boston Scientific Corporation |
| Stryker Corporation |
| GE HealthCare |
| Abbott |
| Others |
Supply Flow & Price Mechanics
Electrophysiology lab undercapacity in United States tertiary centers drives capital equipment pricing leverage toward integrated delivery networks while compressing margin structures for manufacturers without ecosystem-wide service contracts. This utilization squeeze simultaneously elevates procurement consolidation and forces supplier financing concessions to secure long-term device supply agreements.
Pricing Analysis
Cost-plus contracts with lithium-iodine battery indexation dominate implantable device procurement between major hospital networks and manufacturers. Pricing stratifies across premium, standard, and economy tiers based on remote monitoring platform integration depth and FDA premarket approval tier. Cost compression in economy-tier pacemakers intensifies because of purchasing consortium consolidation. Ambulatory surgical centers exhibit highest price sensitivity, while academic medical centers with dedicated electrophysiology infrastructure prioritize service bundling over unit economics.
Supply Chain Analysis
Extended payment terms through supply-chain finance facilities have become standard for component suppliers serving leadless pacemaker manufacturers. Manufacturing concentrates in United States, Germany, and Japan for final device assembly, with battery cell production anchored in Japan and South Korea. Raw material dependencies center on lithium-iodine chemistry, platinum-iridium electrodes, and hermetic titanium housings. Single-source vulnerability in specialized battery chemistries creates structural risk. Distribution runs through GPO-negotiated contracts with integrated delivery networks and direct hospital system agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Leadless pacemaker technology disruption and FDA premarket approval pathway acceleration are compressing technology transition timelines and reallocating competitive advantage toward manufacturers with cloud-integrated remote monitoring infrastructure.
For Market Incumbents: Harden service contract anchoring across electrophysiology suite ecosystems to defend against leadless technology specialists capturing frail patient segments. Prioritize backward integration into lithium-iodine battery supply to offset EPA disposal compliance cost pressures. Channel R&D toward AI-integrated diagnostic algorithms that preempt acute decompensation events. For New Entrants and Emerging Players: Build out wireless telemetry platform capabilities to capture recurring revenue streams offsetting upfront device margin compression. Target ambulatory surgical centers in United States metropolitan markets with streamlined leadless pacemaker workflows. Pursue hospital system partnerships emphasizing complication reduction economics over capital equipment pricing. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across remote monitoring cloud infrastructure development. Long-term viability over the next decade hinges on ecosystem integration depth rather than discrete device manufacturing. Acquisition targets should demonstrate electrophysiologist training program partnerships and GPO contract penetration. Monitor FDA premarket approval timeline compression as inflection signal for technology transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Electrophysiology suite ecosystem integration secures captive demand for compatible device platforms. |
| FDA Submission | Premarket approval pathway acceleration compresses competitive windows for leadless pacemaker entrants. |
| Software Companion Development | AI-integrated diagnostic algorithms enable preemptive intervention and recurring subscription revenues. |
| CE Marking Pathway | EU MDR harmonization streamlines market access across German statutory health insurance reimbursement channels. |
| Reimbursement Strategy | Cardiac resynchronization therapy coding expansion in Germany unlocks patient access across risk categories. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA premarket approval filings, CMS Medicare reimbursement databases, hospital procurement contracts, and EU MDR technical documentation. Electrophysiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided qualitative input through structured interviews. Bottom-up procedure volume estimates triangulate against top-down market value reconstructions.
Forecast inputs incorporate electrophysiology lab capacity buildout trajectories, statutory health insurance reimbursement policy shifts, and leadless technology adoption curves across the projection horizon. Segmentation dimensions span product type, end user, technology maturity, and clinical indication severity. CAGRs derive from installed base turnover rates and replacement cycle compression. Battery chemistry transition timelines and AI diagnostic algorithm regulatory pathways inform scenario weighting.
Sensitivities concentrate around FDA approval timeline variability, EPA lithium-iodine disposal protocol enforcement intensity, and electrophysiologist fellowship program output constraints. Forecasts reflect documented assumptions regarding reimbursement velocity and technology transition economics. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Artificial Blood Vessels Market
Cardiovascular Devices
MRI-Guided Cardiac Ablation Market
Cardiovascular Devices
Global Intravascular Catheters Market
Cardiovascular Devices
Balloon Catheters Market
Cardiovascular Devices
Atherectomy Systems Market
Cardiovascular Devices
Global Vascular Plugs Market
Cardiovascular Devices
United Kingdom Cardiovascular Devices Market
Cardiovascular Devices
Cardiac Mapping Systems Market
Cardiovascular Devices
Serration Balloon Catheters Market
Cardiovascular Devices
Atherosclerotic Renovascular Treatment Market
Cardiovascular Devices
Transcatheter Heart Valve Market
Cardiovascular Devices
Epinephrine Auto-Injectors Market
Cardiovascular Devices
Europe Cardiac Assist Devices Market
Cardiovascular Devices
LAMEA Cardiac Surgical Devices Market
Cardiovascular Devices
Stent-Assisted Coiling Market
Cardiovascular Devices
Wearable Artificial Organs Market