
 Global Stents Market | 2026-2036
Global Stents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stents Market Outlook
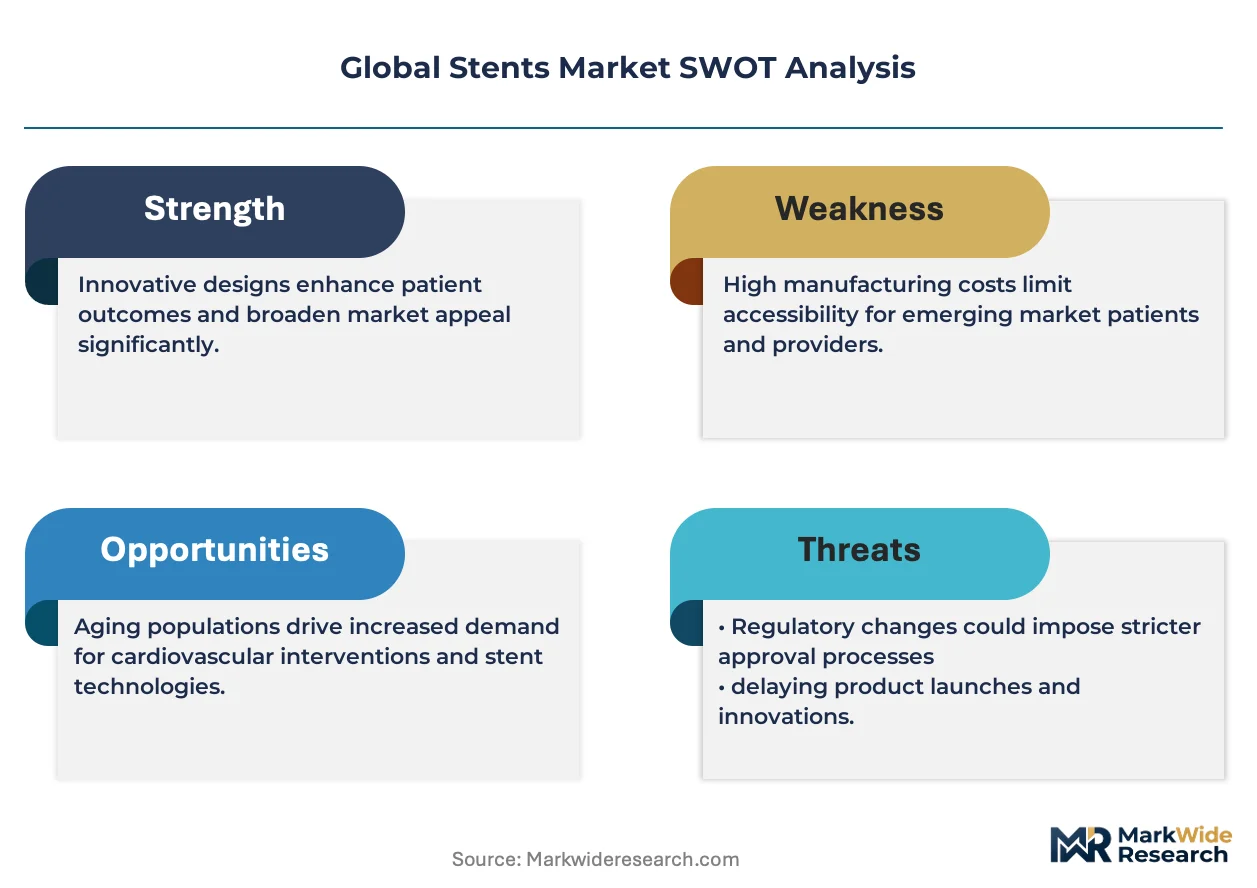
EU MDR is expanding the cost-of-entry calculus for stent manufacturers by mandating extended clinical follow-up and stricter post-market surveillance. Medtronic leverages its broad trial infrastructure to sustain European market access. Abbott Laboratories anchors its position through differentiated bioresorbable scaffold programs. Boston Scientific Corporation competes on manufacturing scale across balloon-expandable and self-expanding platforms.
Stents are tubular mesh devices typically fabricated from cobalt-chromium, nitinol, or biodegradable polymers, deployed via catheter to restore patency in narrowed vascular or non-vascular lumens. Coronary stents occupy the largest revenue pool, while peripheral stents represent the fastest-growing application as below-the-knee interventions expand. Drug-eluting materials command premium positioning due to superior restenosis outcomes, whereas metallic bare-metal platforms face commoditization pressure in price-sensitive hospital procurement.
FDA premarket approval pathways, EMA CE marking under MDR, and Japan PMDA shonin reviews collectively shape product development timelines and geographic launch sequencing. These frameworks demand rigorous biocompatibility testing and localized clinical data, effectively filtering market access for firms without regulatory operations across multiple jurisdictions. Stakeholders must monitor evolving health technology assessment methodologies in Germany and Japan, where added-benefit determinations increasingly influence reimbursement and adoption velocity.
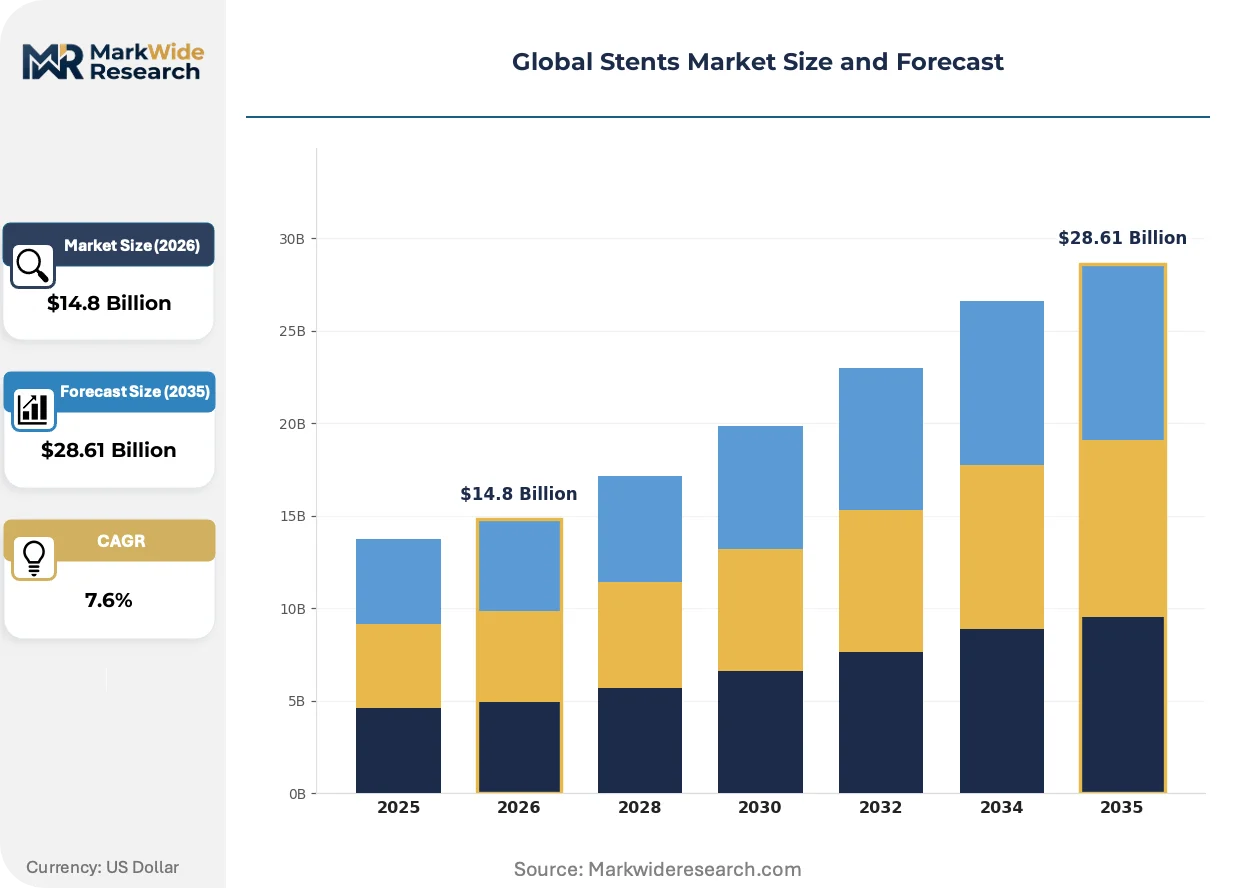
Market Dynamics
EU MDR's extended clinical follow-up mandates are restructuring competitive access for permanent implantables, favoring firms with established trial infrastructure over emerging entrants.
Growth Catalysts
- Catheterization lab expansion:Hospital infrastructure investments across aging demographics in Germany and Japan are elevating procedure volumes for drug-eluting platforms.
- REACH-compliant polymer innovation:Biodegradable scaffold materials meeting ECHA safety thresholds are opening premium positioning in European coronary applications.
- Below-the-knee intervention protocols:Peripheral vascular programs in United States academic medical centers are standardizing self-expanding nitinol deployment for limb salvage.
Market Restraints
- Cobalt-chromium supply concentration:Refining capacity for stent-grade alloys concentrates in a limited supplier base, exposing manufacturers to input volatility.
- MDR certification timelines:Extended EU notified body review periods for Class III implantables are compressing product launch windows and elevating compliance costs.
- Drug-eluting balloon substitution:Paclitaxel-coated balloons for femoropopliteal disease are capturing cases previously routed to permanent stenting in cost-sensitive procurement environments.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives under CDSCO oversight are attracting contract production investments for bare-metal platforms.
- Bioresorbable-polymer convergence with intravascular imaging:Integration of absorbable scaffolds with optical coherence tomography guidance is creating procedure-level differentiation in Japanese reimbursement pathways.
- Direct-to-hospital distribution:Bypassing traditional distributor layers for high-value drug-eluting stents is capturing margin in United States integrated delivery networks.
Industry Challenges
- Polymer science talent scarcity:Formulation expertise for controlled-release drug matrices remains concentrated among a narrow pool of specialists, constraining R&D velocity.
- PMDA shonin data localization:Japan's requirement for domestic clinical evidence is extending approval timelines and elevating trial infrastructure investments for foreign manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stents Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $28.61 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coronary Stents, Peripheral Stents, Carotid Stents, Biliary Stents Material: Metallic, Biodegradable, Drug-Eluting, Polymer End User: Hospitals, Ambulatory Surgical Centers, Cardiology Clinics, Research Institutes Delivery Mode: Balloon-Expandable, Self-Expanding, Hybrid, Others |
| Companies Covered | Medtronic, Abbott Laboratories, Boston Scientific Corporation, B. Braun Melsungen AG, Terumo Corporation, Biotronik SE & Co. KG, Cook Medical, MicroPort Scientific Corporation, W. L. Gore & Associates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stents Market Strategic Shifts
Convergence between imaging guidance and scaffold materials is compressing the gap between deployment precision and long-term vessel restoration outcomes.
Bioresorbable polymer technology is unifying the mechanical support function of traditional metallic stents with complete absorption timelines that eliminate late thrombosis risks. Interventional cardiologists in German university hospitals are adopting these platforms for complex bifurcation lesions at accelerating rates. This unification is compressing the market for permanent metallic alternatives in premium coronary segments.
EU MDR's post-market surveillance requirements are mandating systematic registry participation and extended patient follow-up for all Class III implantables. Manufacturers must now maintain active surveillance systems across multiple member states to retain CE marking validity. Drug-eluting stent portfolios face the steepest compliance burden, with German notified bodies applying the most rigorous interpretation.
Hospital procurement committees are consolidating vendor relationships around single-source agreements for catheterization lab consumables. Integrated delivery networks in the United States are replacing fragmented purchasing with system-wide contracts that bundle stents, balloons, and guidewires. This concentration is most visible in Florida and Texas markets where hospital consolidation has proceeded fastest.
Global Stents Market Segmentation
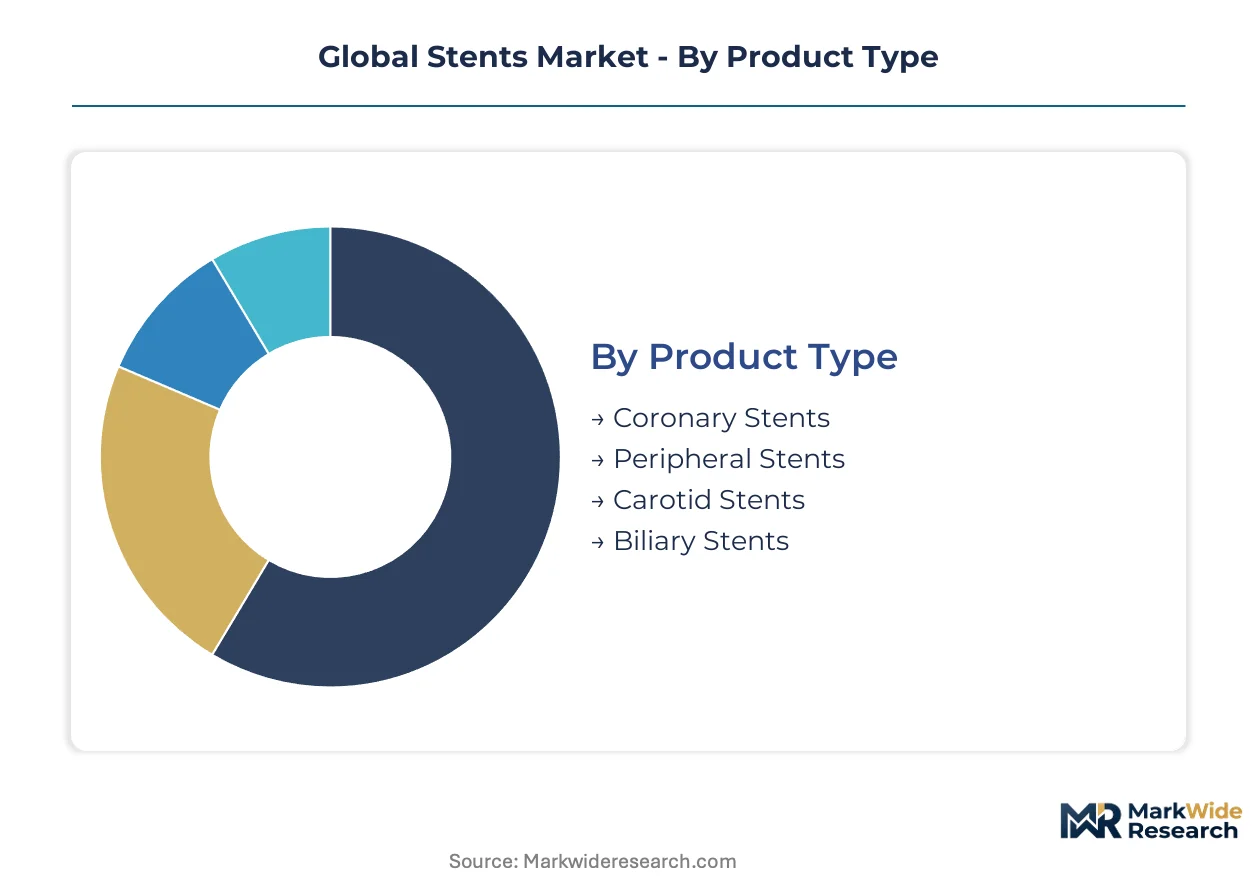
Stent segmentation reveals how material science, anatomical targeting, and procedural setting intersect to determine pricing power and regulatory pathway complexity. Manufacturers align R&D portfolios against specific category boundaries where clinical evidence requirements and reimbursement velocity diverge sharply.
Product Type:
Technology differentiation across vascular territories drives distinct competitive dynamics and evidence-generation burdens.
- Coronary Stents:Drug-eluting platforms dominate revenue concentration in United States catheterization labs, where Medicare reimbursement favors proven restenosis reduction over bare-metal alternatives. German university hospitals are accelerating bioresorbable scaffold adoption for complex bifurcation lesions.
- Peripheral Stents:Self-expanding nitinol designs capture below-the-knee intervention growth in United States academic medical centers standardizing limb-salvage protocols. This category is expanding most quickly as diabetes prevalence elevates chronic limb-threatening ischemia case volumes.
- Carotid Stents:Embolic protection systems integrated with delivery platforms address stroke prevention in high-surgical-risk patients at Japanese stroke centers.
- Biliary Stents:Plastic and metallic variants manage malignant obstruction in interventional radiology suites across Indian tertiary hospitals.
Mature deployment sits with Coronary Stents. Newer deployment is concentrated in Peripheral Stents.
Material:
Cost tiers separate premium clinical outcomes from commodity positioning in hospital procurement.
- Drug-Eluting:Polymer matrices releasing paclitaxel or sirolimus command premium pricing in United States integrated delivery networks where outcome-based contracts reward restenosis reduction. FDA premarket approval pathways demand rigorous biocompatibility validation.
- Metallic:Cobalt-chromium and nitinol alloys retain dominance in price-sensitive procurement environments, though bare-metal platforms face commoditization pressure from drug-eluting balloon substitution in femoropopliteal disease.
- Biodegradable:Poly-lactic acid scaffolds absorb completely within 24-36 months, eliminating late thrombosis risks in German coronary applications.
- Polymer:Non-resorbable polymers serve as drug carriers or structural backbones in specific niche indications.
Volume leadership belongs to Metallic platforms. Margin concentration favors Drug-Eluting formulations.
End User:
Customer type determines purchasing authority complexity and contract bundling scope.
- Hospitals:Catheterization lab volume growth in aging Japanese and German populations anchors procedure throughput. Integrated delivery networks in Florida and Texas consolidate vendor relationships around single-source agreements spanning stents, balloons, and guidewires.
- Ambulatory Surgical Centers:Lower-acuity peripheral interventions migrate to outpatient settings where CMS reimbursement shifts favor same-day discharge economics.
- Cardiology Clinics:Diagnostic and follow-up functions concentrate in community-based settings without interventional capability.
- Research Institutes:Academic medical centers in United States and Japan generate clinical evidence for regulatory submissions and health technology assessments.
Procurement scale peaks at Hospitals. Site-of-care migration is accelerating fastest at Ambulatory Surgical Centers.
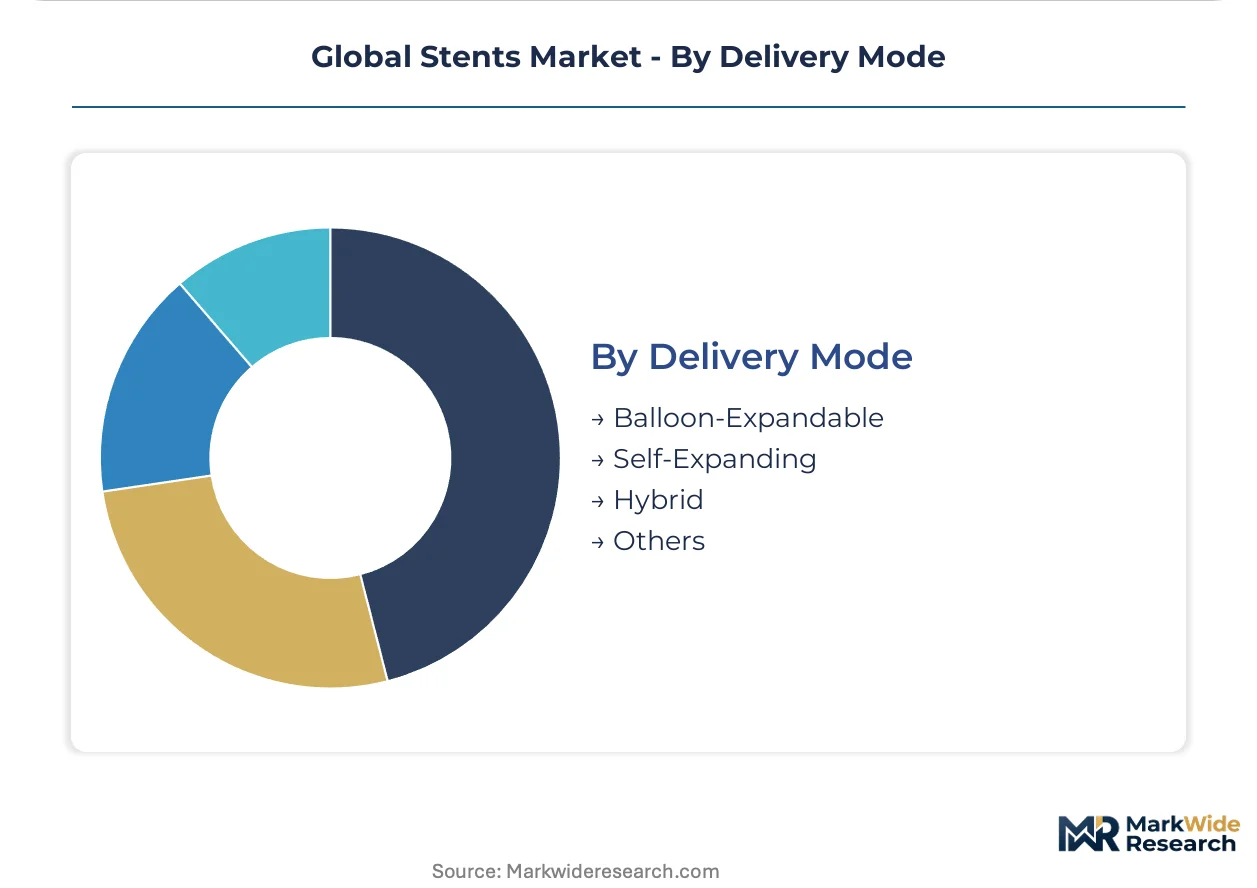
Delivery Mode:
Deployment mechanism selection hinges on lesion morphology and vessel compliance characteristics.
- Balloon-Expandable:Stainless steel and cobalt-chromium platforms deliver precise diameter control in calcified coronary lesions at German university hospitals.
- Self-Expanding:Nitinol's thermal shape memory enables conformal apposition in tortuous peripheral anatomy below the knee.
- Hybrid:Dual-mechanism designs attempt to merge radial strength with flexibility in specific bifurcation applications.
- Others:Novel deployment technologies remain in limited clinical evaluation.
Balloon-Expandable systems retain the broadest installed base. Self-Expanding deployment is gaining share fastest in peripheral indications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Catheterization lab volumes concentrate in the United States, Germany, and Japan where aging demographics and established reimbursement pathways anchor procedure throughput. Hospital infrastructure investments in these markets elevate demand for drug-eluting and bioresorbable platforms. Regulatory frameworks in each geography filter market access through distinct clinical evidence requirements.
United States
Medicare reimbursement favors proven restenosis reduction in coronary interventions, anchoring drug-eluting stent demand in integrated delivery networks. FDA premarket approval pathways demand rigorous biocompatibility validation and localized clinical data. Florida and Texas hospital consolidation proceeds fastest, consolidating vendor relationships around single-source agreements spanning stents, balloons, and guidewires.
Germany
University hospitals accelerate bioresorbable scaffold adoption for complex bifurcation lesions as catheterization lab volumes rise. EU MDR mandates extended clinical follow-up and stricter post-market surveillance for Class III implantables, with German notified bodies applying the most rigorous interpretation. The Rhine-Ruhr and Bavarian medical technology clusters concentrate notified body expertise and trial infrastructure.
Japan
PMDA shonin reviews require domestic clinical evidence, extending approval timelines for foreign manufacturers while elevating trial infrastructure investments. Aging demographics drive catheterization lab expansion across tertiary stroke centers. Tokyo and Osaka academic medical centers generate clinical evidence for health technology assessments and reimbursement determinations.
India
Domestic manufacturing incentives under CDSCO oversight attract contract production investments for bare-metal platforms. Price-sensitive hospital procurement environments favor metallic alternatives facing commoditization pressure. Maharashtra and Gujarat medical device corridors concentrate production capacity for export-oriented and domestic consumption.
China
NMPA regulatory pathways shape product development timelines for manufacturers seeking market access in the world's second-largest healthcare economy. Volume-based procurement reforms compress pricing for metallic platforms while premium drug-eluting segments retain margin. Yangtze River Delta medical technology clusters concentrate interventional cardiology training and procedure standardization.
Global Stents Market Competitive Environment
United States producers anchor one tier; European and Japanese specialists hold differentiated positions through regulatory compliance depth and materials science expertise. Market structure consolidates around established trial infrastructure holders capable of sustaining EU MDR certification burdens. Three archetypes dominate: integrated multinationals with broad cardiovascular portfolios, focused interventional specialists with scaffold innovation pipelines, and regional contract manufacturers serving price-sensitive procurement. Competitive moves concentrate on M&A for trial infrastructure and strategic partnerships for polymer science capabilities.
Among integrated multinationals, Medtronic leverages broad trial infrastructure to sustain European market access, while Abbott Laboratories anchors position through differentiated bioresorbable scaffold programs. Boston Scientific Corporation occupies a scale-driven position across balloon-expandable and self-expanding platforms. These three represent distinct strategic postures: infrastructure depth, materials innovation, and manufacturing scale.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Boston Scientific Corporation |
| B. Braun Melsungen AG |
| Terumo Corporation |
| Biotronik SE & Co. KG |
| Cook Medical |
| MicroPort Scientific Corporation |
| W. L. Gore & Associates |
| Others |
Value Chain & Pricing Dynamics
Integrated delivery networks in Florida and Texas anchor pricing power through single-source agreements that compress vendor margins while rewarding volume scale. Drug-eluting platforms command premium positioning against bare-metal alternatives facing commoditization pressure from drug-eluting balloon substitution.
Pricing Analysis
Short lead-time availability for cobalt-chromium and nitinol alloys commands premium pricing from stent-grade metal refiners serving notified body-certified manufacturers. Three-tier pricing structure across premium drug-eluting, standard metallic, and economy bare-metal levels reflects certification grade and clinical evidence depth. Price differentiation separates FDA PMA-approved platforms from CE-marked alternatives and unregistered imports in Indian procurement. Cost compression in metallic bare-metal segments is intensifying because of India's PLI scheme attracting contract production investments. Ambulatory surgical centers exhibit highest price sensitivity while German university hospitals prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Freight costs for temperature-controlled polymer resin shipments from European suppliers elevate landed costs for biodegradable scaffold manufacturers in United States and Japan. Stent-grade cobalt-chromium refining concentrates in Germany, Japan, and United States, while nitinol shape-memory alloy production clusters in United States and Chinese medical technology corridors. Raw material dependencies include cobalt-chromium alloys, nitinol wire, and poly-lactic acid resins. Single-source vulnerability pervades stent-grade alloy suppliers, exposing manufacturers to input volatility when refining capacity tightens. Distribution runs through authorized distributor networks for high-value drug-eluting platforms and direct-to-hospital channels for integrated delivery network contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into polymer formulation capabilities and trial infrastructure represents the dominant competitive lever as EU MDR compliance costs filter out undercapitalized entrants.
For Market Incumbents: To counter drug-eluting balloon substitution in femoropopliteal interventions, incumbents should deepen scaffold-integrated imaging partnerships in Japanese reimbursement pathways and acquire notified body relationships to compress MDR certification timelines. Captive supply of controlled-release polymer matrices insulates against formulation specialist scarcity constraining R&D velocity. For New Entrants and Emerging Players: Bioresorbable polymer convergence with optical coherence tomography guidance offers entry into German university hospital procurement committees seeking procedure-level differentiation. Below-the-knee peripheral indications in United States academic medical centers present the most penetrable segment given standardizing limb-salvage protocols. Partner with established trial infrastructure holders to satisfy PMDA domestic evidence requirements without captive investment. For Investors and Strategic Acquirers: The window for entry favors polymer science specialists with REACH-compliant formulation platforms and existing CE marking relationships. Long-term viability hinges on sustained EU MDR certification capacity across multiple notified bodies. Watch for German notified body capacity constraints as inflection indicator for regulatory bottleneck severity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR certification under German notified bodies secures European market access for Class III implantables. |
| Hospital System Partnership | Single-source agreements with Florida and Texas integrated delivery networks capture catheterization lab volume. |
| Reimbursement Strategy | Medicare coverage for drug-eluting platforms anchors United States coronary intervention economics. |
| Backward Integration | In-house polymer formulation reduces dependency on scarce controlled-release matrix specialists. |
| PMDA Shonin Pathway | Domestic clinical evidence generation unlocks Japanese aging demographic procedure demand. |
Study Parameters
FDA PMA filings, EMA MDR submissions, and CMS Medicare reimbursement databases formed the secondary backbone for this analysis. Primary interviews with interventional cardiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers validated demand assumptions. Top-down macroeconomic indicators and bottom-up procedure volume estimates were triangulated against stent shipment data from customs records.
Bottom-up modeling anchored catheterization lab capacity expansion and aging demographic projections against drug-eluting and bare-metal platform adoption curves. Segmentation dimensions included product type, material composition, end-user channel, and delivery mechanism. CAGRs were derived from procedure volume trajectories and pricing evolution across premium and commodity tiers. Forecast inputs incorporated EU MDR compliance cost burdens and PMDA shonin timeline assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended notified body review periods or accelerated drug-eluting balloon substitution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Surgical and Interventional Cardiology Devices Market
Cardiovascular Devices
Cardiovascular Stents Market
Cardiovascular Devices
Cardiac Rhythm Management Devices Market
Cardiovascular Devices
Cardiac Surgery Devices Market
Cardiovascular Devices
Europe Cardiac Assist Devices Market
Cardiovascular Devices
Mobile Stroke Unit (MSTU) Market
Cardiovascular Devices
Global Vascular Injury Treatment Market
Cardiovascular Devices
India Cardiovascular Devices Market
Cardiovascular Devices
Global Vascular Stents Market
Cardiovascular Devices
Global Peripheral Stent Market
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
North America Vascular Stents Market
Cardiovascular Devices
Argentina Cardiovascular Devices Market
Cardiovascular Devices
Arterial Blood Sampling Systems Market
Cardiovascular Devices
Cardiac Mapping Systems Market
Cardiovascular Devices
Patient-Controlled Injectors Market