
 Arrhythmogenic Right Ventricular Dysplasia Treatment Market | 2026-2036
Arrhythmogenic Right Ventricular Dysplasia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Arrhythmogenic Right Ventricular Dysplasia Treatment Market Analytics
Market Context with Strategic Players
Project finance for rare-disease therapeutic platforms is rewriting capital access for arrhythmogenic right ventricular dysplasia drug developers. Tenaya Therapeutics leverages gene therapy pipelines to sustain preclinical momentum in cardiomyopathy targets. GeneDx anchors hereditary cardiac panel services through laboratory partnerships with academic electrophysiology programs. Blueprint Genetics Oy differentiates via variant interpretation capabilities that compete on turnaround time for clinical geneticists.
Technical Definition and Structural Segments
Arrhythmogenic right ventricular dysplasia constitutes a progressive cardiomyopathy characterized by fibrofatty replacement of right ventricular myocardium, with diagnostic criteria incorporating electrocardiographic depolarization abnormalities, structural imaging defects, and pathogenic desmosomal gene variants. The condition demands interventions spanning antiarrhythmic pharmacology, catheter ablation of ventricular tachycardia substrates, and implantable cardioverter-defibrillator placement for sudden death prevention. Medications and implantable devices capture the dominant margin pools given chronic management requirements, while monitoring systems represent the fastest-expanding segment as remote cardiac telemetry integrates with genetic risk stratification protocols. Electrotherapy approaches mature alongside surgical intervention volumes that remain constrained by procedure complexity and specialist availability.
Regulatory Frame and Forward-Looking Close
FDA breakthrough therapy and orphan drug frameworks shape trial design incentives and exclusivity timelines for arrhythmogenic right ventricular dysplasia therapeutics, while HIPAA governs genetic data flows from clinical testing laboratories to cardiac care teams. The country's national pharmaceutical regulator maintains post-market surveillance of implantable device safety signals through mandatory manufacturer reporting. Stakeholders must monitor how payer coverage policies for prophylactic defibrillator implantation evolve alongside polygenic risk score integration into clinical decision support tools.
Market Dynamics
Genetic risk stratification protocols are compressing diagnostic timelines for inherited cardiomyopathies, forcing electrophysiology departments to reconfigure patient pathways around molecular testing integration rather than imaging-first workflows.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review timelines for arrhythmia diagnostics compress clinical trial phases, enabling faster commercialization of novel electrophysiology tools.
- Tertiary Cardiac Center Clustering:Metropolitan referral networks in the United States concentrate high-volume patient pools, creating economies of scale for specialized ARVD treatment protocols.
- Remote Cardiac Telemetry:Wearable monitoring systems enable continuous arrhythmia surveillance outside hospital settings, expanding addressable patient populations beyond traditional implantable device candidates.
Market Restraints
- Desmosomal Gene Variant Interpretation Complexity:Ambiguous pathogenicity classifications for rare genetic variants create diagnostic uncertainty, delaying treatment decisions and increasing liability exposure for clinical geneticists.
- Catheter Ablation Procedure Complexity:Technical difficulty of mapping arrhythmogenic substrates in fibrofatty myocardium limits specialist availability and procedural throughput.
- HIPAA-Compliant Data Infrastructure Costs:Secure transmission of genetic testing results to distributed cardiac care teams requires substantial health information technology investment.
Strategic Opportunities
- Polygenic Risk Score Integration:Multi-variant algorithms for sudden cardiac death prediction create decision support tool opportunities for electrophysiology laboratories.
- Prophylactic Defibrillator Policy Evolution:Shifting payer coverage criteria for primary prevention implantation expands reimbursable indications beyond current structural imaging thresholds.
- Gene Therapy Platform Convergence:Cardiomyopathy-targeted viral vector delivery systems intersect with CRISPR editing capabilities, opening curative rather than palliative intervention possibilities.
Industry Challenges
- Electrophysiology Fellowship Pipeline Constraints:Extended training requirements for complex ablation procedures create specialist scarcity relative to expanding genetic testing referral volumes.
- Implantable Device Longevity Certification:Extended battery life and lead durability testing protocols prolong regulatory submission timelines for next-generation hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arrhythmogenic Right Ventricular Dysplasia Treatment Market |
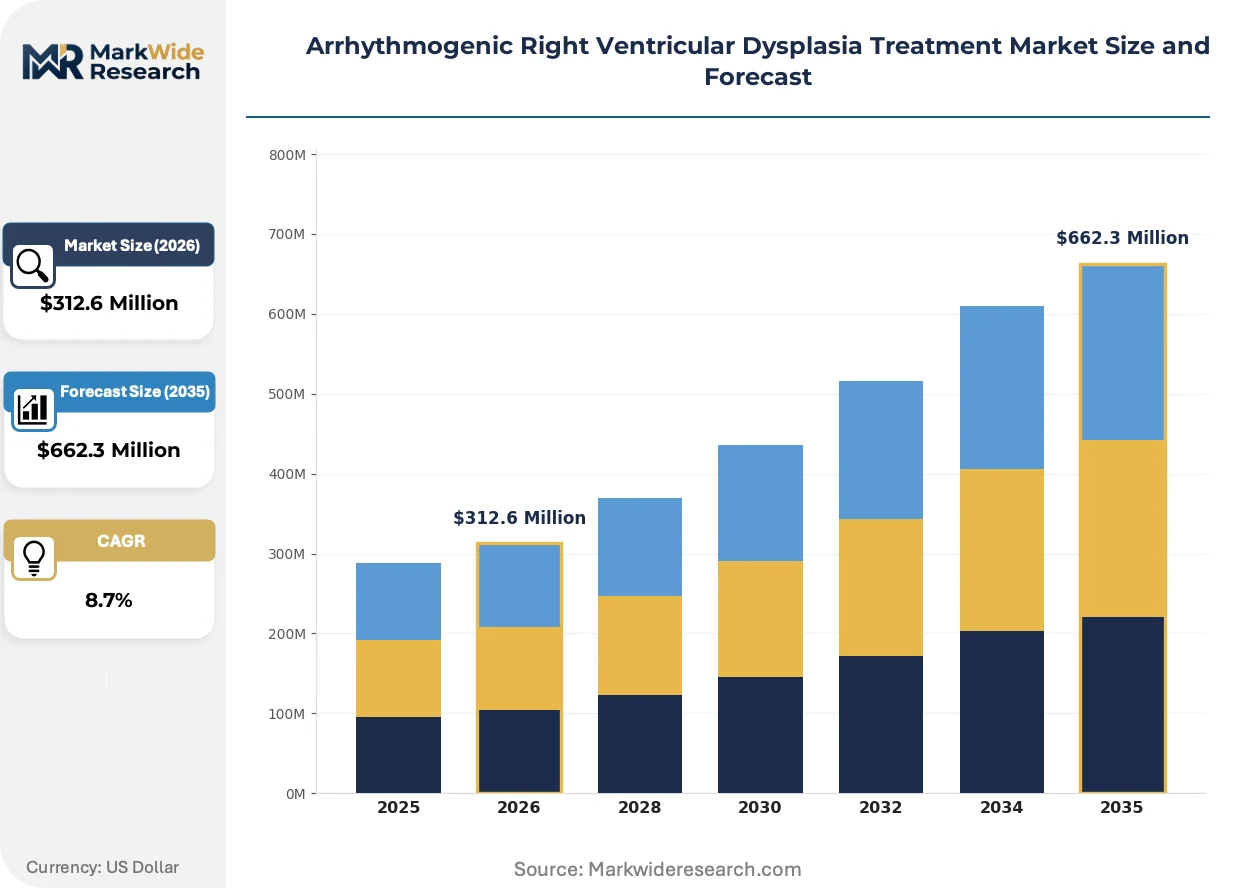
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Catheters, Implantable Devices, Monitoring Systems Treatment Approach: Drug Therapy, Surgical Intervention, Electrotherapy, Lifestyle Modification End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Distribution Channel: Direct Sales, Online Pharmacies, Wholesalers, Retail Pharmacies |
| Companies Covered | CENTOGENE AG, Ambry Genetics, GeneDx, Illumina, Asper Biogene, Cohesion Phenomics, Blueprint Genetics Oy, Invitae Corporation, Tenaya Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arrhythmogenic Right Ventricular Dysplasia Treatment Market Evolving Landscape
Computational phenotyping of cardiac magnetic resonance imaging is replacing subjective visual assessment of right ventricular wall motion abnormalities, standardizing diagnostic criteria application across heterogeneous clinician populations.
Artificial intelligence-based late gadolinium enhancement quantification is rendering obsolete manual tracing methods for fibrofatty infiltration assessment. Academic electrophysiology programs in the United States and Germany are deploying these tools for trainee education and prospective patient screening. The technology compresses inter-observer variability, reducing false-negative diagnostic rates that previously delayed defibrillator implantation decisions.
EMA's Medical Device Regulation (MDR) recertification requirements for implantable cardioverter-defibrillators impose enhanced clinical evidence standards on legacy device portfolios. Manufacturers must generate post-market surveillance data or withdraw products from European markets. High-complexity ablation catheters face disproportionate documentation burdens, favoring larger firms with dedicated regulatory affairs infrastructure over mid-tier competitors.
Academic medical centers are unbundling genetic counseling from electrophysiology consultation, creating standalone hereditary cardiomyopathy clinics with dedicated variant interpretation expertise. This restructuring displaces general cardiology practices that previously managed ARVD patient triage. The model concentrates most visibly in the United States, where tertiary institutions compete for referral network dominance through subspecialty service line differentiation.
Arrhythmogenic Right Ventricular Dysplasia Treatment Market Segmentation
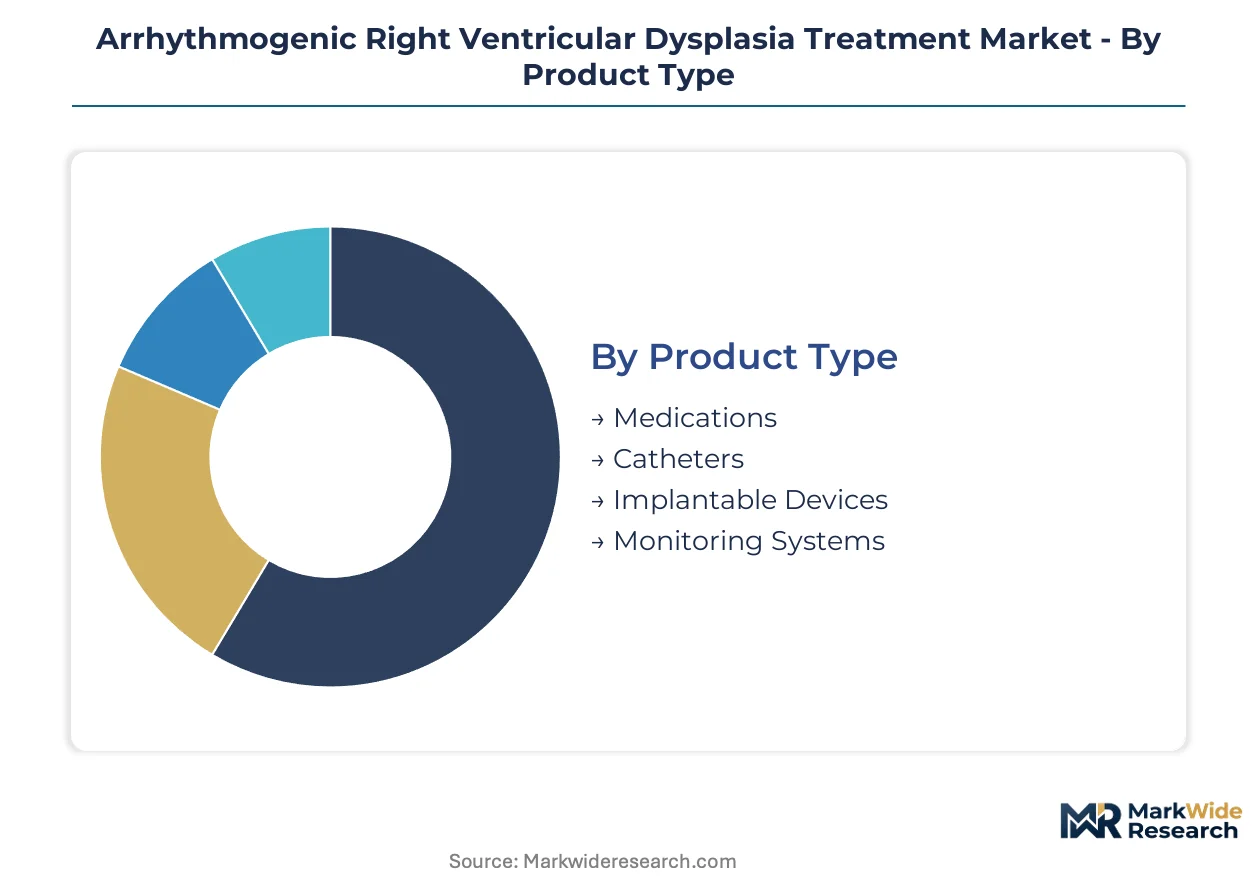
Segmentation in the arrhythmogenic right ventricular dysplasia treatment market reveals distinct margin structures and procurement patterns across therapeutic modalities. Each category reflects different stakeholder influence—electrophysiologists drive device selection while genetic counselors shape testing workflows.
Product Type:
Mature electrophysiology hardware segments coexist with emerging digital health platforms across this category.
- Medications:Antiarrhythmic pharmacology spans beta-blockers, flecainide, and sotalol protocols for ventricular tachycardia suppression. Demand concentrates in tertiary cardiac centers where electrophysiology departments manage complex polypharmacy regimens for inherited cardiomyopathy patients.
- Catheters:Three-dimensional electroanatomic mapping systems enable substrate ablation in fibrofatty myocardial tissue. Specialist availability constraints in metropolitan United States referral networks limit procedural throughput despite expanding genetic testing referral volumes.
- Implantable Devices:Implantable cardioverter-defibrillators with subcutaneous lead configurations reduce vascular complications.
- Monitoring Systems:Wearable cardiac telemetry patches transmit real-time rhythm data to cloud-based electrophysiology platforms.
Implantable devices handle the majority of throughput; monitoring systems are the fastest mover on share.
Treatment Approach:
Cost tier stratification separates acute intervention modalities from chronic management protocols in this category.
- Drug Therapy:Chronic oral antiarrhythmic regimens require therapeutic drug monitoring and dose titration protocols.
- Surgical Intervention:Right ventricular free wall disconnection and cardiac transplantation represent end-stage options for refractory arrhythmogenic cardiomyopathy. Academic medical centers in Germany and the United States concentrate surgical volume due to hybrid operating room infrastructure requirements.
- Electrotherapy:Catheter ablation and defibrillator therapy dominate interventional revenue pools. United States electrophysiology laboratories generate procedure volume through genetic cascade screening protocols that identify at-risk family members.
- Lifestyle Modification:Exercise restriction counseling and competitive athletics disqualification protocols reduce sudden cardiac death risk in genotype-positive patients.
Electrotherapy commands premium reimbursement; lifestyle modification is climbing the fastest on patient volume as genetic screening expands.
End User:
Customer type fragmentation reflects divergent capital equipment needs versus consumable purchasing patterns.
- Hospitals:Tertiary cardiac centers with dedicated electrophysiology laboratories perform complex ablation procedures and device implantations. United States metropolitan referral networks concentrate high-acuity ARVD cases requiring hybrid surgical-electrophysiology capabilities.
- Clinics:Outpatient cardiology practices manage stable patients on antiarrhythmic therapy with periodic remote monitoring.
- Rehabilitation Centers:Post-intervention cardiac rehabilitation programs supervise exercise tolerance testing after device implantation.
- Home Care:Remote patient monitoring vendors deploy wearable patch technologies for continuous arrhythmia surveillance outside institutional settings.
Hospitals absorb the dominant capital expenditure burden; home care is gaining share fastest on remote monitoring adoption.
Distribution Channel:
Supply concentration patterns differentiate capital equipment procurement from pharmaceutical distribution pathways.
- Direct Sales:Implantable device manufacturers maintain dedicated sales forces for electrophysiology laboratory relationships. United States tertiary cardiac centers negotiate capital equipment purchases through value-based procurement committees.
- Online Pharmacies:Antiarrhythmic medication refills and remote monitoring subscription services migrate to digital platforms. HIPAA-compliant infrastructure requirements create compliance barriers for smaller pharmacy operators.
- Wholesalers:Medical device distributors manage inventory logistics for catheter and monitoring system consumables.
- Retail Pharmacies:Community pharmacy networks dispense maintenance antiarrhythmic prescriptions with therapeutic drug monitoring coordination.
Direct sales channels capture the highest transaction values; online pharmacies show the steepest expansion trajectory on telehealth integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for genetic testing consumables and electrophysiology hardware shapes procurement strategies across major treatment markets, while export-oriented diagnostic laboratories in select jurisdictions supply variant interpretation services to international cardiac centers.
United States
Metropolitan referral networks in Boston, Cleveland, and Houston concentrate tertiary electrophysiology capacity for inherited cardiomyopathy management. FDA breakthrough device designations accelerate commercialization timelines for novel arrhythmia diagnostics. Academic medical centers in these clusters unbundle genetic counseling into standalone hereditary cardiac clinics, displacing general cardiology triage functions.
Germany
Hybrid operating room infrastructure at university hospitals in Berlin and Munich supports complex surgical-electrophysiology interventions for end-stage arrhythmogenic cardiomyopathy. EMA Medical Device Regulation recertification requirements impose enhanced clinical evidence standards on implantable cardioverter-defibrillator portfolios. The country's electrophysiology fellowship programs generate specialist supply for European referral networks.
United Kingdom
NHS England specialized commissioning frameworks determine access to prophylactic defibrillator implantation for genotype-positive patients. London and Manchester academic centers deploy computational cardiac magnetic resonance phenotyping to standardize right ventricular wall motion assessment. GDPR compliance infrastructure governs cross-border genetic data flows from clinical testing laboratories.
Japan
PMDA regulatory pathways for combination device-drug products influence development timelines for next-generation electrophysiology systems. Tokyo and Osaka metropolitan hospitals integrate wearable cardiac telemetry with electronic health record platforms for remote arrhythmia surveillance. METI industrial policy supports domestic manufacturing of high-complexity ablation catheter systems.
Canada
Health Canada post-market surveillance requirements for implantable devices mandate manufacturer reporting of safety signals. Toronto and Vancouver cardiac centers participate in North American genetic cascade screening protocols for at-risk family members. Provincial formularies determine reimbursement for antiarrhythmic pharmacotherapy regimens in inherited cardiomyopathy patients.
Arrhythmogenic Right Ventricular Dysplasia Treatment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in genetic testing and device manufacturing. The arrhythmogenic right ventricular dysplasia treatment market structures around three archetypes: gene therapy platform developers, hereditary cardiac panel service laboratories, and electrophysiology hardware manufacturers. Consolidation pressures concentrate among diagnostic service providers, while device segments favor larger firms with dedicated regulatory affairs infrastructure. Strategic moves center on laboratory partnership networks with academic electrophysiology programs and value-based procurement committee engagement at tertiary cardiac centers.
Within the gene therapy platform tier, Tenaya Therapeutics anchors preclinical momentum in cardiomyopathy-targeted viral vector delivery. Among hereditary cardiac panel specialists, GeneDx and Blueprint Genetics Oy exemplify variant interpretation capabilities that compete on turnaround time for clinical geneticists. These three entities occupy positions across the therapeutic development-to-diagnostic testing continuum, reflecting how capital access for rare-disease platforms intersects with molecular testing workflow integration in electrophysiology departments.
| Leading Market Players |
|---|
| CENTOGENE AG |
| Ambry Genetics |
| GeneDx |
| Illumina |
| Asper Biogene |
| Cohesion Phenomics |
| Blueprint Genetics Oy |
| Invitae Corporation |
| Tenaya Therapeutics |
| Others |
Value Network & Pricing Analysis
United States-based genetic testing consumable suppliers concentrate upstream capacity for hereditary cardiac panels, anchoring margin capture in electrophysiology laboratories that bundle molecular diagnostics with device implantation workflows. This concentration permits premium pricing for variant interpretation services while compressing margins on commodity catheter hardware.
Pricing Analysis
Hospital purchasing committees anchor pricing negotiations for implantable cardioverter-defibrillators through value-based procurement frameworks. Three-tier pricing structure across premium subcutaneous lead systems, standard transvenous configurations, and economy monitoring patches reflects FDA breakthrough designation status and battery longevity certification tiers. Pricing pressure stems from Medicare reimbursement compression for prophylactic device implantation. Academic medical centers demonstrate lowest price sensitivity due to research funding offsets, while community hospitals face acute budget constraints.
Supply Chain Analysis
Contract manufacturing for electrophysiology hardware concentrates with Flex, Jabil, and Sanmina serving implantable device OEMs. Component sourcing draws from Malaysia and Mexico for sterile packaging, Germany for precision catheter extrusion, and Ireland for biocompatible polymer feedstocks. Single-source vulnerability pervades desmosomal gene assay reagents tied to Illumina sequencing platforms. Distribution runs through dedicated sales forces for capital equipment and medical device distributors for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across genetic testing interpretation services creates niche opportunities as electrophysiology departments unbundle counseling from device-focused care. Cascade screening expansion multiplies addressable patient pools beyond index cases.
For Market Incumbents:Pre-empt consolidation among hereditary cardiac panel laboratories by acquiring variant interpretation specialists with turnaround time advantages. Secure exclusive partnerships with academic electrophysiology programs before competitors lock in genetic counseling workflow integration. Vertical integration into cloud-based telemetry platforms defends against remote monitoring entrants.
For New Entrants and Emerging Players:Standalone hereditary cardiomyopathy clinics in mid-sized United States metropolitan areas represent the most penetrable entry point, bypassing entrenched tertiary center relationships. Gene therapy platform developers targeting desmosomal mutations should prioritize preclinical proof-of-concept data to attract rare-disease venture capital. Direct-to-patient genetic risk stratification tools offer a go-to-market angle outside hospital procurement channels.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with PE-backed diagnostic service platforms seeking exit liquidity through strategic sales to electrophysiology device manufacturers. Five-to-ten year viability hinges on polygenic risk score integration into clinical decision support. Watch FDA breakthrough device designation velocity as an inflection indicator for platform valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated review timelines compress commercialization cycles for arrhythmia diagnostics developers. |
| Hospital System Partnership | Tertiary cardiac centers in Boston and Cleveland anchor referral networks for genetic cascade screening. |
| Software Companion Development | AI-based late gadolinium enhancement quantification standardizes fibrofatty infiltration assessment across clinicians. |
| Reimbursement Strategy | Medicare coverage expansion for prophylactic defibrillator implantation unlocks primary prevention volumes. |
| CE Marking Pathway | EMA MDR recertification requirements demand enhanced clinical evidence for European market retention. |
Research Methodology
Desk research of FDA 510(k) filings, ClinicalTrials.gov entries, and CMS reimbursement databases preceded structured interviews with electrophysiology laboratory directors, genetic counselors, hospital procurement managers, and biomedical engineers. Secondary validation drew from GPO contract repositories, patent landscapes for desmosomal gene therapies, and SEC filings of publicly traded diagnostic platforms. Bottom-up patient volume modeling triangulated against top-down market sizing from tertiary cardiac center capacity estimates.
Assumptions held genetic testing penetration rates and implantable device replacement cycles fixed while varying regulatory approval timelines and payer coverage expansion scenarios across the analysis window. Segmentation dimensions encompassed product type, treatment approach, end user, and distribution channel, with regional regulatory clusters as a cross-cutting variable. CAGRs derived from logistic adoption curves for remote monitoring technologies and linear extrapolation of surgical intervention volumes. Forecast inputs incorporated electrophysiology fellowship graduation rates and polygenic risk score clinical validation progress.
Practitioners should monitor FDA breakthrough designation grant rates and Medicare national coverage determination updates for early signals of demand inflection. Quarterly review of genetic testing reimbursement codes and implantable device safety signal reports is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Mobile Cardiac Telemetry Device Market
Cardiovascular Devices
Global Cardiac Resynchronization Therapy Market
Cardiovascular Devices
Normal Balloon Catheter Market
Cardiovascular Devices
Continuous Blood Pressure Monitoring Devices Market
Cardiovascular Devices
Chile Cardiovascular Devices Market
Cardiovascular Devices
Shock Wave Therapy Devices Market
Cardiovascular Devices
Germany Cardiovascular Devices Market
Cardiovascular Devices
Ventricular Drainage Sets Market
Cardiovascular Devices
Japan Cardiovascular Devices Market
Cardiovascular Devices
Cardiovascular and Soft Tissue Repair Patches Market
Cardiovascular Devices
North America Vascular Stents Market
Cardiovascular Devices
Transcatheter Heart Valve Replacement (THVR) Market
Cardiovascular Devices
Dual Therapy Stent Market
Cardiovascular Devices
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market
Cardiovascular Devices
Global Catheters Market
Cardiovascular Devices
Epinephrine Auto-Injectors Market