
 Vena Cava Clips and Filters Market | 2026-2036
Vena Cava Clips and Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Vena Cava Clips and Filters Market Analytics
A shift from single-source to multi-source procurement for nitinol wire and laser-cut tubing is realigning supply economics for filter manufacturers. Cook Medical leverages captive metallurgy partnerships to secure alloy consistency across its retrievable portfolio. Boston Scientific competes through vertically controlled fabrication of its proprietary filter geometries. Merit Medical Systems anchors its position with concentrated manufacturing in Salt Lake City, serving western U.S. hospital networks.
Vena cava clips and filters are implantable mechanical devices, typically constructed from nickel-titanium alloys or 316L stainless steel via laser micromachining, designed to trap emboli within the inferior vena cava and prevent pulmonary embolism in patients with contraindications to anticoagulation. Retrievable filters now command the largest revenue pool as retrieval protocols extend to longer dwell times, while permanent filters retain share in trauma settings where patient follow-up is uncertain. Biocompatible polymers represent the fastest-growing material category as manufacturers explore absorbable anchoring components to reduce long-term implant complications. Hospitals dominate end-user demand, though outpatient centers are capturing procedural volume as catheter-based retrieval techniques simplify.
The FDA's 510(k) clearance framework governs U.S. market entry, while the EU Medical Device Regulation requires notified body certification and post-market surveillance for filter longevity data. The FDA has intensified scrutiny of retrievable filter retrieval rates, prompting manufacturers to invest in retrieval registry participation. Stakeholders must monitor evolving retrieval success metrics and reimbursement alignment between implantation and removal procedures.
Market Dynamics
Hospital procurement of retrievable filters is accelerating as venous thromboembolism protocols tighten across major health systems, compressing supplier margins while elevating retrieval registry participation requirements.
Growth Catalysts
- FDA Retrieval Rate Scrutiny:Intensified post-market surveillance on retrievable filter dwell times is forcing manufacturers to redesign retrieval systems for longer implantation windows.
- Trauma Center Protocol Standardization:Emergency departments in the United States are embedding permanent filter placement into massive transfusion protocols for high-risk hemorrhagic patients.
- Laser Micromachining Precision:Advances in femtosecond laser cutting are enabling thinner nitinol strut geometries that improve filter conformability to irregular vena cava anatomies.
Market Restraints
- Nitinol Alloy Supply Concentration:Premium nickel-titanium wire production clusters in a limited set of metallurgical suppliers, exposing filter manufacturers to alloy consistency variability.
- EU MDR Certification Friction:The Medical Device Regulation's extended notified body timelines and clinical data requirements are delaying market entry for retrievable portfolio extensions.
- Anticoagulant Pharmacotherapy Advancement:Direct oral anticoagulants with improved bleeding risk profiles are reducing absolute contraindication rates for medical VTE prophylaxis.
Strategic Opportunities
- Absorbable Polymer Anchoring:Bioresorbable fixation components that dissolve after endothelialization could eliminate chronic implant complications and open long-dwell retrievable applications.
- Ambulatory Surgical Center Migration:Catheter-based retrieval techniques are enabling procedure volume capture outside hospital settings, creating channel expansion for outpatient-focused distributors.
- India CDSCO Pathway Alignment:Harmonized regulatory convergence with global standards is accelerating market access for manufacturers with established FDA or CE dossiers.
Industry Challenges
- Interventional Radiology Workforce Constraints:Retrieval procedure complexity requires specialized operator training that outpaces fellowship pipeline expansion in community hospital settings.
- Reimbursement Misalignment:Disconnected coding between implantation and removal procedures creates economic disincentives for retrieval completion, depressing registry-reported success rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vena Cava Clips and Filters Market |
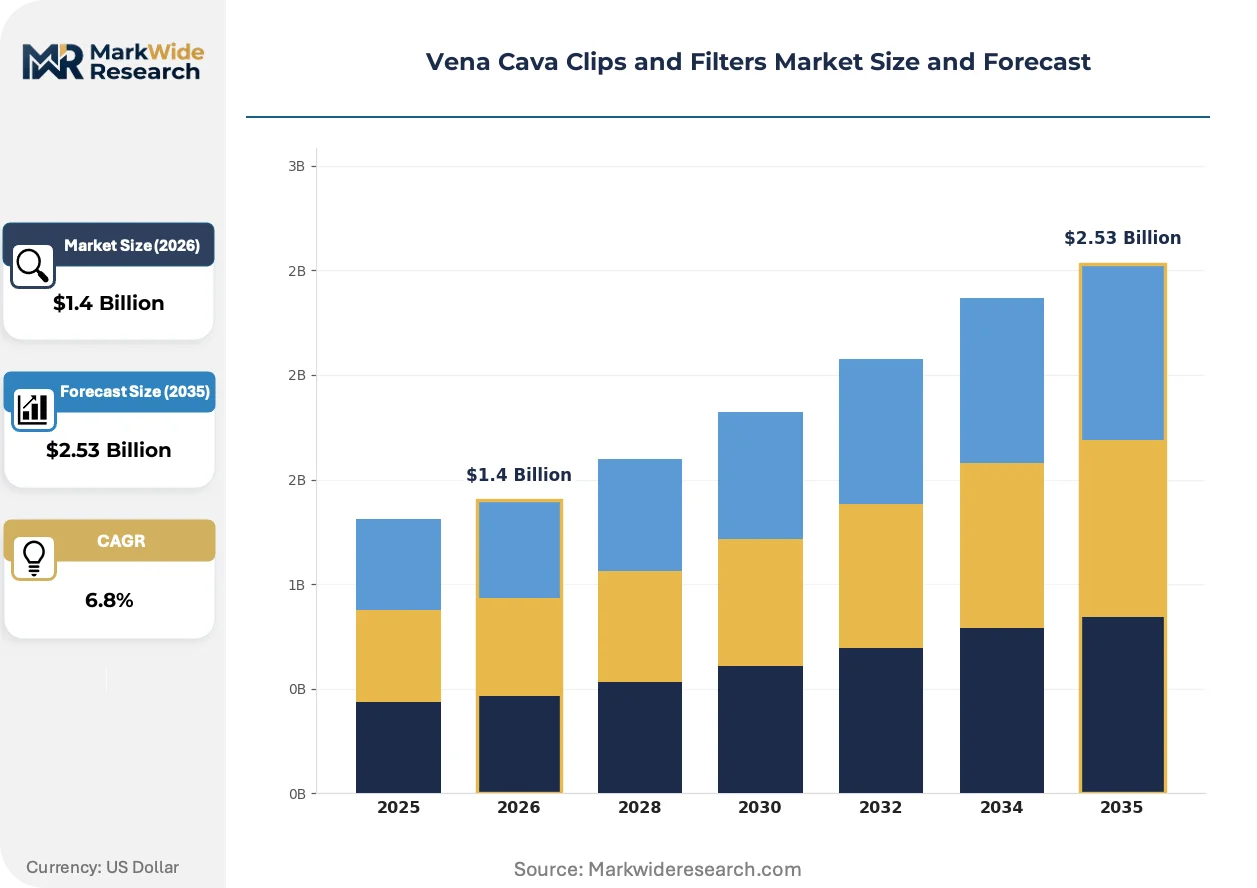
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retrievable Filters, Permanent Filters, Clips, Attachments Application: Trauma Surgery, Cardiovascular Procedures, Oncological Procedures, Preventive Treatments End User: Hospitals, Specialty Clinics, Outpatient Centers, Research Institutions Material: Metallic Alloys, Biocompatible Polymers, Stainless Steel, Composite Materials |
| Companies Covered | Cook Medical, B. Braun Melsungen AG, Cardinal Health, Becton Dickinson and Co, Argon Medical Devices, Boston Scientific, Medtronic, Merit Medical Systems, Teleflex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vena Cava Clips and Filters Market Evolving Landscape
Retrieval protocol extension is compressing the functional boundary between retrievable and permanent filter categories, while material science advances and procurement centralization reshape competitive positioning.
Femtosecond laser micromachining is overtaking conventional laser cutting for nitinol filter fabrication. The technology produces strut edges free of thermal recast layers, improving fatigue resistance during deployment and retrieval cycling. Academic medical centers with high retrieval volumes are specifying these precision-manufactured devices in their centralized procurement contracts, compressing market share for legacy fabrication methods.
The EU Medical Device Regulation now mandates post-market clinical follow-up for implantable vascular devices with extended dwell times. Manufacturers must submit annual safety reports and retrieval success data to notified bodies, extending certification maintenance costs. Retrievable filter portfolios face the steepest compliance burden, with Germany's BfArM and France's ANSM enforcing the strictest interpretation of longevity data requirements.
Integrated delivery networks in the United States are consolidating interventional device contracts under single-source agreements that bundle implantation and retrieval accessories. This purchasing behavior is displacing independent distributor relationships that historically supplied community hospitals. The concentration is most visible in Texas and Florida health systems, where IDN-affiliated facilities now represent the dominant procurement channel for filter procedures.
Vena Cava Clips and Filters Market Segmentation
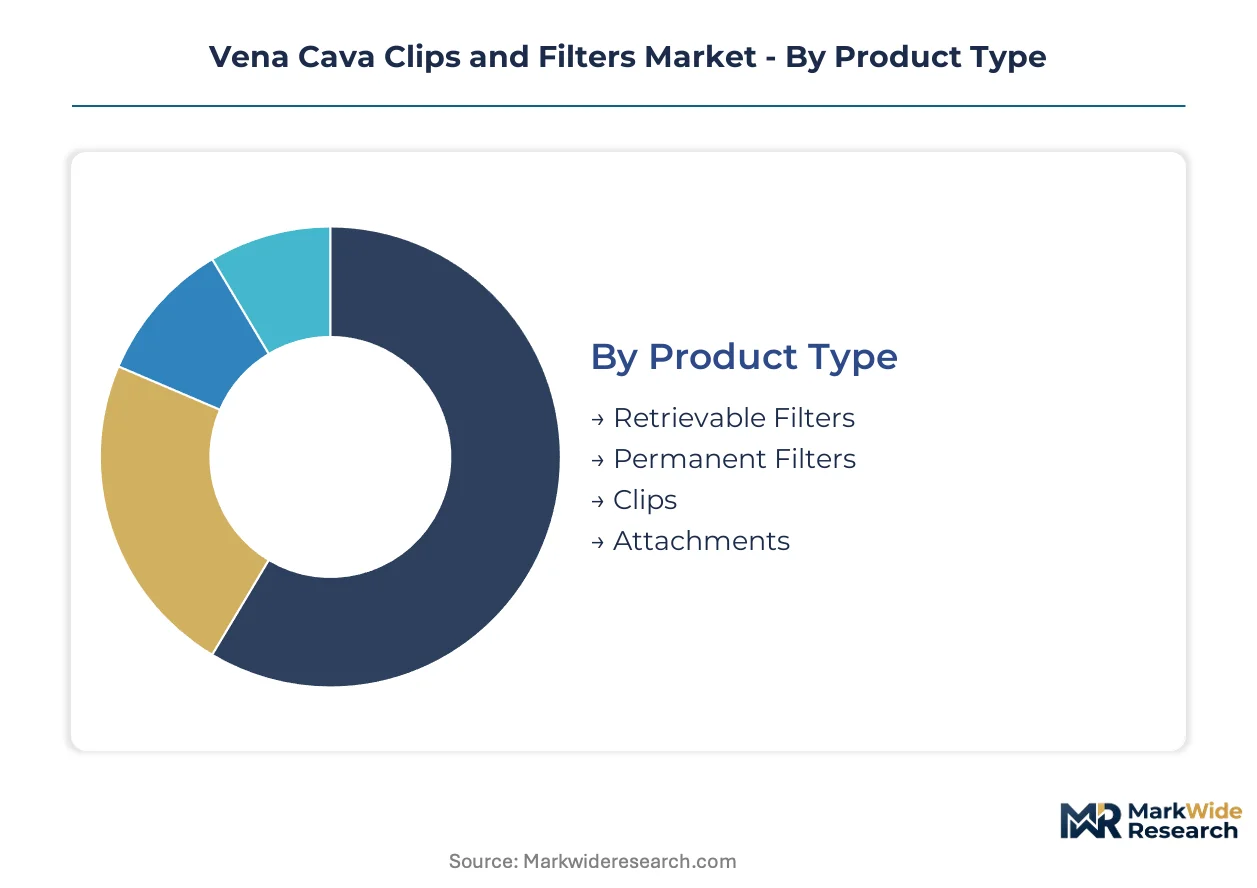
Device configuration and deployment setting dictate procurement patterns across the vena cava intervention landscape. Material selection and retrieval capability define reimbursement alignment and clinical protocol integration.
Product Type:
Filter architecture determines dwell time protocols and retrieval economics within hospital supply chains.
- Retrievable Filters:Nitinol wire frameworks with hook or cone designs enable endovascular extraction after extended implantation. Hospital systems in Texas and Florida specify these devices in bundled contracts that include retrieval accessories, compressing standalone filter margins.
- Permanent Filters:Stainless steel or titanium constructions with fixed anchoring struts serve trauma populations with uncertain follow-up capacity. Emergency departments embed permanent placement into massive transfusion protocols for hemorrhagic patients.
- Clips:Mechanical occlusion devices for caval interruption in patients with filter contraindications.
- Attachments:Retrieval snares, retrieval kits, and conversion accessories supporting filter management.
Retrievable filters lead on scale; clips lead on momentum as caval interruption alternatives gain protocol traction.
Application:
Procedure setting shapes device selection criteria and reimbursement pathway complexity.
- Trauma Surgery:Emergency caval filtration in hemorrhagic patients with anticoagulation contraindications. Level I trauma centers in the United States deploy permanent filters under massive transfusion protocols, generating concentrated procurement volume.
- Cardiovascular Procedures:Prophylactic filtration during cardiac surgery or catheter-based interventions. Academic medical centers specify retrievable devices with femtosecond-laser fabrication for complex anatomies.
- Oncological Procedures:VTE prophylaxis in cancer patients with chemotherapy-induced coagulopathy.
- Preventive Treatments:Elective filtration for high-risk medical populations with temporary mobility constraints.
Trauma surgery dominates absolute volume; cardiovascular procedures are climbing the fastest as interventional cardiology expands retrieval capabilities.
End User:
Site-of-care migration is redistributing procedural economics across facility types.
- Hospitals:Integrated delivery networks negotiate centralized contracts covering implantation through retrieval. IDN-affiliated facilities in the western United States anchor concentrated manufacturing relationships with Salt Lake City-based suppliers.
- Specialty Clinics:Interventional radiology practices with dedicated vascular access capabilities.
- Outpatient Centers:Ambulatory surgical centers capture retrieval volume as catheter-based techniques simplify. Florida and Texas health systems are driving this channel expansion through same-day discharge protocols.
- Research Institutions:Academic medical centers with retrieval registries and post-market surveillance obligations under FDA scrutiny.
Hospitals retain the deepest procurement relationships; outpatient centers show the steepest expansion trajectory as site-of-care economics shift.
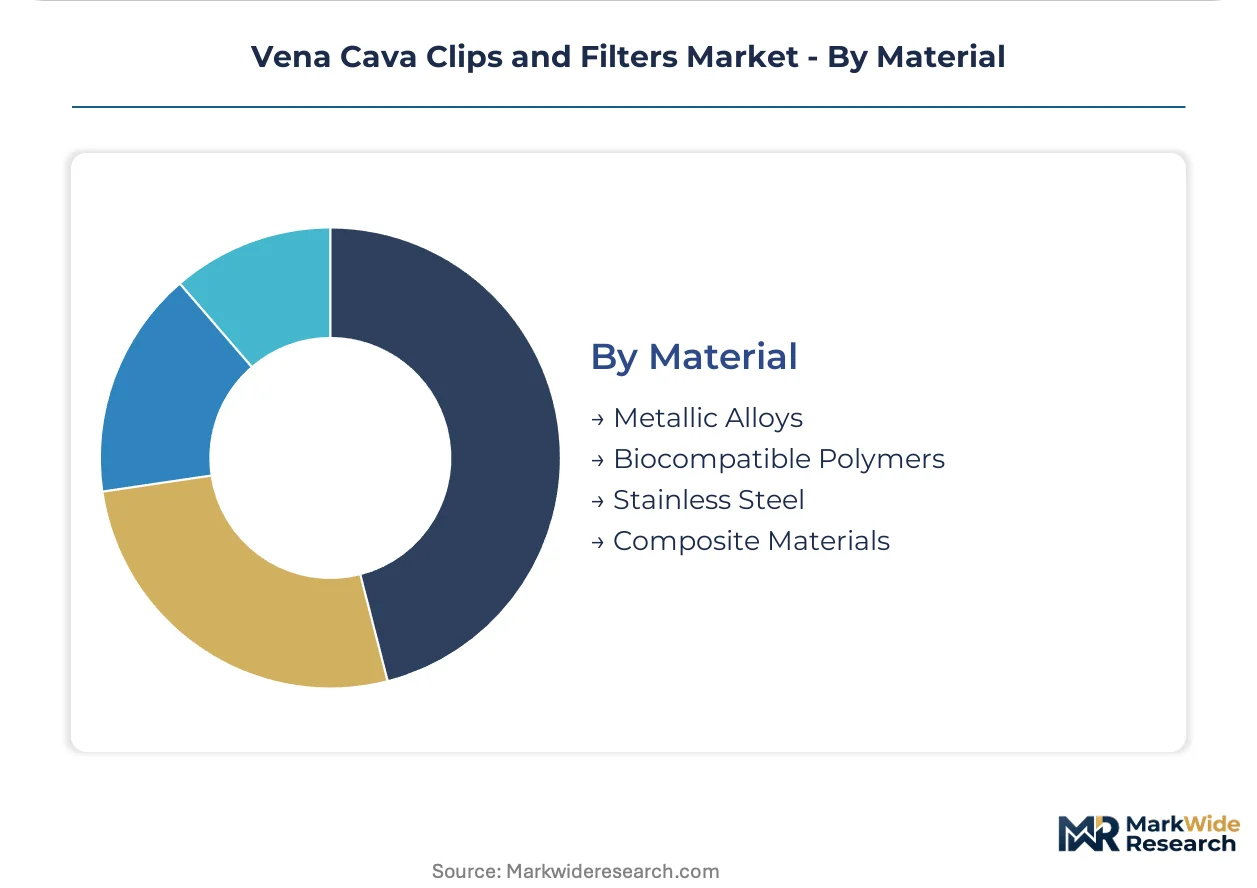
Material:
Substrate selection governs fatigue resistance, endothelialization rates, and long-term biocompatibility profiles.
- Metallic Alloys:Nickel-titanium formulations dominate retrievable filter fabrication. Cook Medical secures alloy consistency through captive metallurgy partnerships, while Boston Scientific controls proprietary geometry fabrication in-house.
- Biocompatible Polymers:Absorbable anchoring components are gaining share as manufacturers explore resorbable fixation to reduce chronic implant complications. This category is expanding most quickly as retrieval protocols extend dwell times.
- Stainless Steel:316L grade serves permanent filter applications with fixed structural requirements.
- Composite Materials:Hybrid constructions combining metallic frameworks with polymer coatings or absorbable elements.
Metallic alloys anchor current revenue; biocompatible polymers command the fastest growth as material science advances reshape retrieval economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Salt Lake City anchors concentrated manufacturing for western United States hospital networks, while regulatory divergence across major economies reshapes market access timelines for filter manufacturers.
United States
Integrated delivery networks in Texas and Florida negotiate bundled contracts covering implantation through retrieval accessories. FDA 510(k) clearance pathways govern market entry, with intensified post-market surveillance on retrievable filter dwell times. Salt Lake City-based Merit Medical Systems serves concentrated western hospital procurement relationships.
Germany
BfArM enforces strict interpretation of longevity data requirements under EU Medical Device Regulation, extending certification maintenance costs for retrievable portfolios. Academic medical centers with high retrieval volumes specify femtosecond-laser fabricated devices. The country's notified body infrastructure delays market entry for portfolio extensions.
France
ANSM mandates annual safety reports and retrieval success data submissions for implantable vascular devices with extended dwell times. Hospital procurement concentrates in Parisian academic centers with retrieval registry obligations. The regulatory friction compresses margins for manufacturers seeking retrievable filter certification.
India
CDSCO pathway alignment with global standards accelerates market access for manufacturers with established FDA or CE dossiers. Trauma centers in metropolitan hospitals embed permanent filter placement into hemorrhagic patient protocols. Mumbai and Delhi medical device distributors capture expanding procurement volume.
Japan
PMDA review timelines for nitinol-based implantable devices create extended validation periods for foreign manufacturers. Interventional cardiology departments in Tokyo and Osaka academic centers drive retrievable filter adoption. Domestic distributors consolidate relationships with western manufacturers seeking regulatory harmonization.
Vena Cava Clips and Filters Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue absorbable polymer anchoring technologies and ambulatory surgical center channel expansion. The vendor base stratifies across three tiers: integrated medical device conglomerates with captive metallurgy, mid-scale specialists with concentrated geographic manufacturing, and regional distributors with retrieval registry capabilities. Two dominant competitive moves define current positioning: backward integration into nitinol alloy supply chains to secure consistency, and strategic partnerships with integrated delivery networks for bundled contract capture.
Within the integrated conglomerate tier, Cook Medical, Boston Scientific, and Merit Medical Systems exemplify divergent supply chain strategies. Cook Medical represents the captive metallurgy archetype through alloy partnership control. Boston Scientific occupies the in-house fabrication position for proprietary geometries. Merit Medical Systems anchors the concentrated manufacturing model with Salt Lake City-based production serving western United States networks. These three structures illustrate how supply-side configuration determines competitive positioning in retrievable filter procurement.
| Leading Market Players |
|---|
| Cook Medical |
| B. Braun Melsungen AG |
| Cardinal Health |
| Becton Dickinson and Co |
| Argon Medical Devices |
| Boston Scientific |
| Medtronic |
| Merit Medical Systems |
| Teleflex |
| Others |
Value Network & Pricing Analysis
Nitinol wire feedstock costs cascade through three pricing tiers as manufacturers pass alloy volatility downstream to hospital procurement committees. Texas and Florida integrated delivery networks negotiate bundled contracts that compress standalone filter margins while elevating retrieval accessory premiums.
Pricing Analysis
Input-cost pass-through from nickel-titanium alloy suppliers governs contract-based long-term offtake structures across retrievable filter portfolios. Price differentiation separates femtosecond-laser fabricated devices with fatigue-resistant strut edges from conventional laser-cut alternatives, with FDA 510(k) clearance tier commanding additional premium. Pricing pressure stems from EU MDR certification friction extending validation timelines and elevating compliance overhead. Community hospitals exhibit highest price sensitivity, while academic medical centers with retrieval registry obligations absorb premium positioning for precision-manufactured devices.
Supply Chain Analysis
Direct-to-hospital channels handle integrated delivery network demand through concentrated manufacturing relationships, displacing independent distributor networks. Supply concentrates in United States, Germany, and India, with nitinol alloy production clustering in limited metallurgical facilities. Raw material dependencies center on nickel-titanium wire, laser-cut tubing, and biocompatible polymer feedstocks. Single-source vulnerability in premium alloy supply exposes manufacturers to consistency variability. Distribution runs through GPO-affiliated procurement platforms and IDN centralized contracting offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
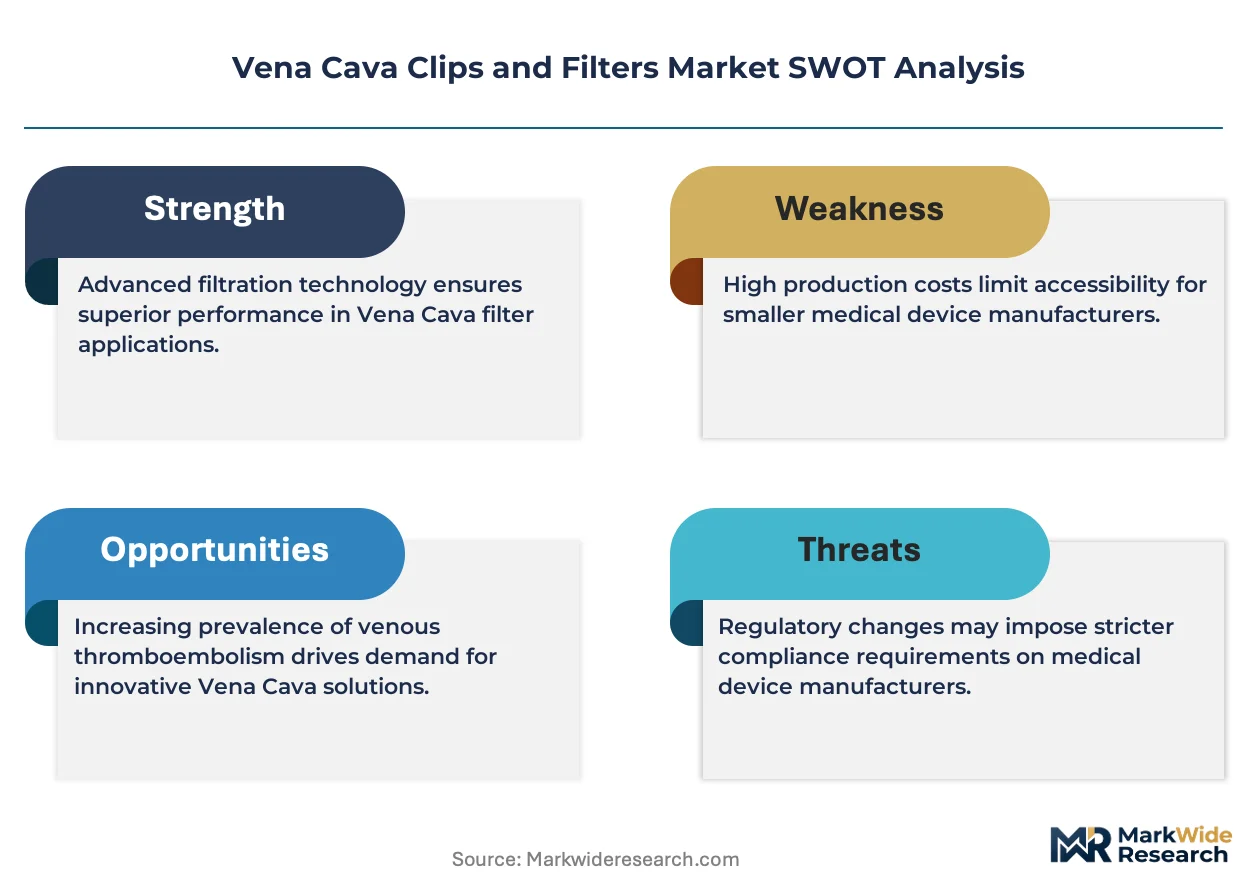
The vena cava clips and filters market functions as a regulatory compounder, with FDA intensified retrieval rate scrutiny forcing redesign investments that deepen incumbent moats.
For Market Incumbents: Hedge nitinol supply exposure through captive metallurgy partnerships or backward integration into alloy production, mirroring Cook Medical's consistency-securing model. Defend against ambulatory surgical center channel displacement by bundling retrieval accessories into same-day discharge protocols. Prioritize femtosecond laser fabrication certification to capture academic medical center procurement specifications. For New Entrants and Emerging Players: Begin with absorbable polymer anchoring components for extended-dwell retrievable applications, where bioresorbable fixation remains underdeveloped. Target India CDSCO pathway alignment as the most penetrable regulatory entry point for manufacturers with established FDA dossiers. Pursue outpatient center distributor partnerships to bypass IDN contracting concentration. For Investors and Strategic Acquirers: Roll-up economics work for regional retrieval registry operators because FDA post-market surveillance mandates create captive data assets with hospital system lock-in. Five-to-ten year viability hinges on reimbursement alignment between implantation and removal procedures. Watch retrieval success rate reporting as the inflection signal for portfolio valuation compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Retrieval Registry Participation | FDA scrutiny of dwell times elevates registry data to competitive necessity for 510(k) maintenance. |
| Femtosecond Laser Fabrication Investment | Academic medical centers specify thermal-recast-free strut edges in centralized procurement contracts. |
| Absorbable Polymer R&D Partnership | Bioresorbable anchoring components address chronic implant complications in extended-dwell protocols. |
| IDN Bundled Contract Capture | Texas and Florida health systems consolidate interventional device purchasing under single-source agreements. |
| EU MDR Notified Body Alignment | Germany's BfArM and France's ANSM enforce strictest longevity data requirements for retrievable portfolios. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down nitinol alloy supply tracking forms the analytical core of this study. Primary interviews with interventional radiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR notified body certifications, hospital procurement databases, and CMS Medicare reimbursement data. Triangulation across these sources ensures segmentation integrity across device configuration, material substrate, and end-user facility type.
Historical trendline analysis of retrievable filter retrieval rates and permanent filter trauma center deployment established baseline growth patterns across the projection horizon. The analytical framework models product type, application setting, end-user facility tier, and material composition dimensions. CAGRs derive from procedure volume trajectories, reimbursement pathway evolution, and regulatory certification timeline assumptions. Forecast inputs incorporate laser micromachining technology adoption curves and integrated delivery network contract consolidation patterns.
Several conditions sit outside the modeled scope, including anticoagulant pharmacotherapy breakthroughs that eliminate VTE contraindications, and interventional radiology workforce expansion rates that could accelerate retrieval completion. Forecasts reflect assumptions about FDA post-market surveillance intensity and EU MDR enforcement consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Heart Beat Irregularity Detection Device Market
Cardiovascular Devices
Global Aortic Repair Devices Market
Cardiovascular Devices
US Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
Global Coronary Stent Market
Cardiovascular Devices
Fluid Aspiration System Market
Cardiovascular Devices
Anticoagulation Market
Cardiovascular Devices
Drug-Coated Balloon Catheter Market
Cardiovascular Devices
Cardiovascular Diagnostic and Monitoring Devices Market
Cardiovascular Devices
India Cardiovascular Devices Market
Cardiovascular Devices
Cardiac Surgery Devices Market
Cardiovascular Devices
Europe Vascular Access Device Market
Cardiovascular Devices
Absorbable Heart Stent Market
Cardiovascular Devices
United Kingdom Cardiovascular Devices Market
Cardiovascular Devices
Drug Eluting Balloon Market
Cardiovascular Devices
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market
Cardiovascular Devices
Intravascular Stents Market