
 Cardiovascular Repair and Reconstruction Devices Market | 2026-2036
Cardiovascular Repair and Reconstruction Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiovascular Repair and Reconstruction Devices Market Intelligence
Bioresorbable polymers are consolidating their position against permanent metallic implants in coronary and peripheral interventions. Medtronic plc leverages its integrated manufacturing footprint to sustain cost leadership across graft and stent portfolios. Edwards Lifesciences Corporation anchors its competitive position through specialization in transcatheter valve repair technologies.
Cardiovascular repair and reconstruction devices encompass implantable and adjunct products engineered from nitinol alloys, expanded polytetrafluoroethylene, or decellularized biological matrices, designed to restore hemodynamic function following acquired or congenital structural damage. These devices must meet fatigue resistance thresholds exceeding 400 million cardiac cycles and biocompatibility standards under ISO 10993. Grafts fabricated from expanded polytetrafluoroethylene dominate open surgical aneurysm repair, while biologic valves capture premium positioning in younger patient cohorts seeking tissue-based solutions. Polymer-based drug-eluting stents occupy the largest volume position within coronary bypass applications, though metal-free platforms are gaining traction in complex lesion subsets.
The FDA's premarket approval framework and the EU Medical Device Regulation impose stringent clinical evidence requirements that extend development timelines but elevate barriers for non-compliant entrants. ISO 14155 governs investigational device trials across multiple jurisdictions, standardizing safety documentation for regulatory submissions. Stakeholders must monitor the convergence of digital health integration with traditional implantable hardware, as connected device capabilities reshape post-market surveillance obligations and reimbursement negotiations.
Market Dynamics
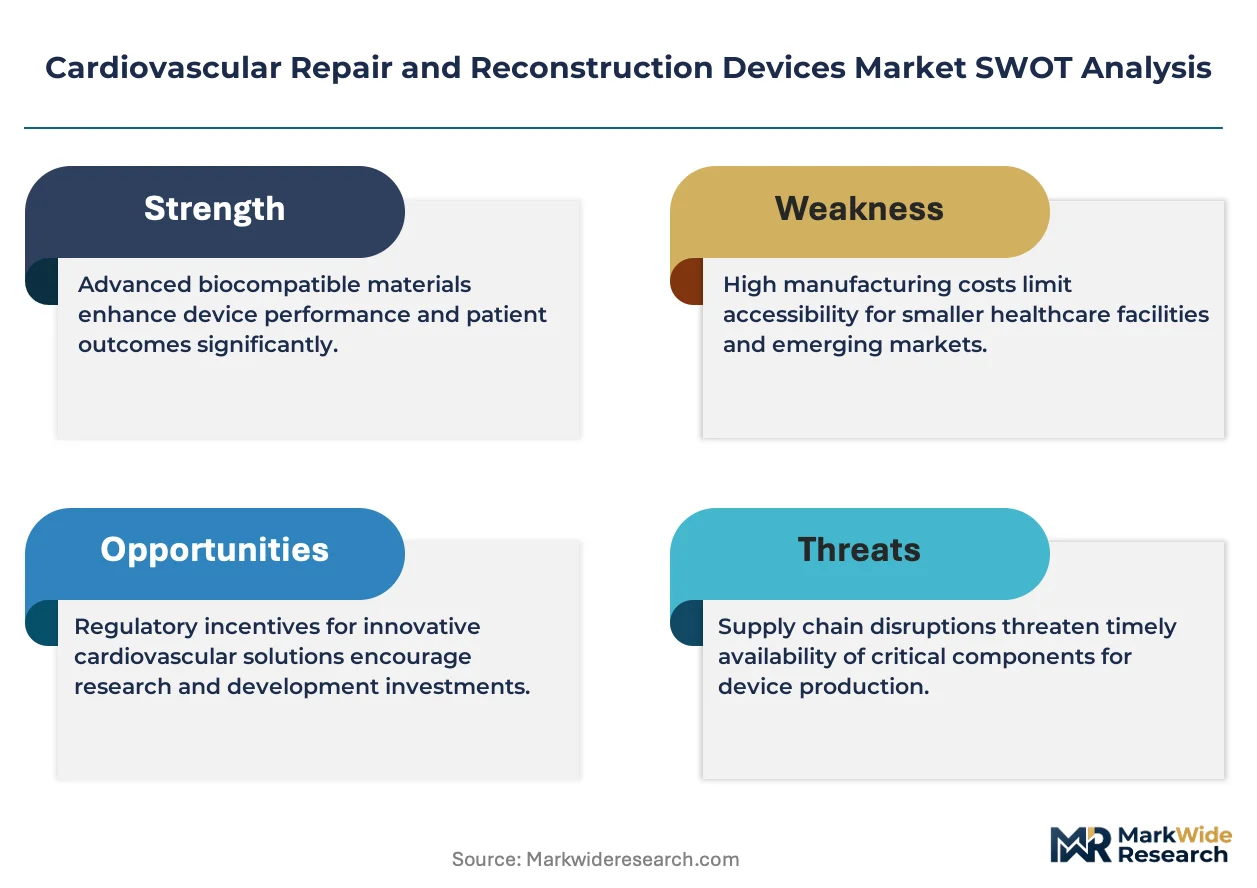
Bioresorbable scaffold technology is compressing the addressable market for permanent metallic implants while FDA premarket approval timelines extend development cycles beyond five years for novel device categories.
Growth Catalysts
- Aging demographics in the United States:The expanding Medicare-eligible population sustains procedural volume expansion for coronary artery bypass grafting and transcatheter valve replacement. Hospital systems in Florida and Arizona report capacity constraints in cardiac catheterization laboratories.
- ISO 10993 biocompatibility standardization:Harmonized testing protocols accelerate regulatory submissions across multiple jurisdictions. Device manufacturers leverage standardized cytotoxicity and hemocompatibility data packages to streamline market entry.
- Drug-eluting polymer platforms:Advanced sirolimus-analogue coatings reduce restenosis rates in complex coronary lesions. Academic medical centers prioritize these platforms for diabetic patient cohorts with multivessel disease.
Market Restraints
- Nitinol alloy supply concentration:Shape-memory alloy production concentrates among a limited set of European and Japanese metallurgical suppliers. Device manufacturers face input cost volatility when nickel prices fluctuate on commodity exchanges.
- EU Medical Device Regulation clinical evidence requirements:Post-market surveillance obligations and notified body capacity constraints extend CE marking timelines. Small and mid-cap developers encounter capital exhaustion before commercialization.
- Transcatheter valve durability limitations:Structural valve deterioration in bioprosthetic tissue remains unresolved for younger patient populations. Surgical valve replacement retains preference for patients under sixty-five years.
Strategic Opportunities
- Rural hospital catheterization laboratory expansion:Underserved regions in Texas, Georgia, and Ohio present volume growth potential. Mobile angiography units and teleradiology partnerships reduce capital barriers for community hospitals.
- Connected device post-market surveillance:Remote hemodynamic monitoring integration creates recurring revenue streams. The FDA's digital health pre-certification pathway offers accelerated review for software-enabled implants.
- Decellularized xenograft biological matrices:Bovine and porcine pericardial scaffolds enable off-the-shelf availability without immunosuppression. Pediatric congenital heart defect repair represents an emerging application with limited competition.
Industry Challenges
- Interventional cardiologist training pipeline constraints:Fellowship program slots fail to match procedural volume growth. Academic medical centers compete for qualified operators through signing bonuses and research allocation.
- Good Manufacturing Practice facility certification timelines:Cleanroom validation and process qualification extend manufacturing readiness by eighteen to twenty-four months. Contract manufacturers command premium pricing for expedited slots.
- Legacy electronic health record integration complexity:Implantable device data streams require custom API development for Epic and Cerner environments. Hospital IT departments deprioritize cardiovascular device connectivity against core clinical workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiovascular Repair and Reconstruction Devices Market |
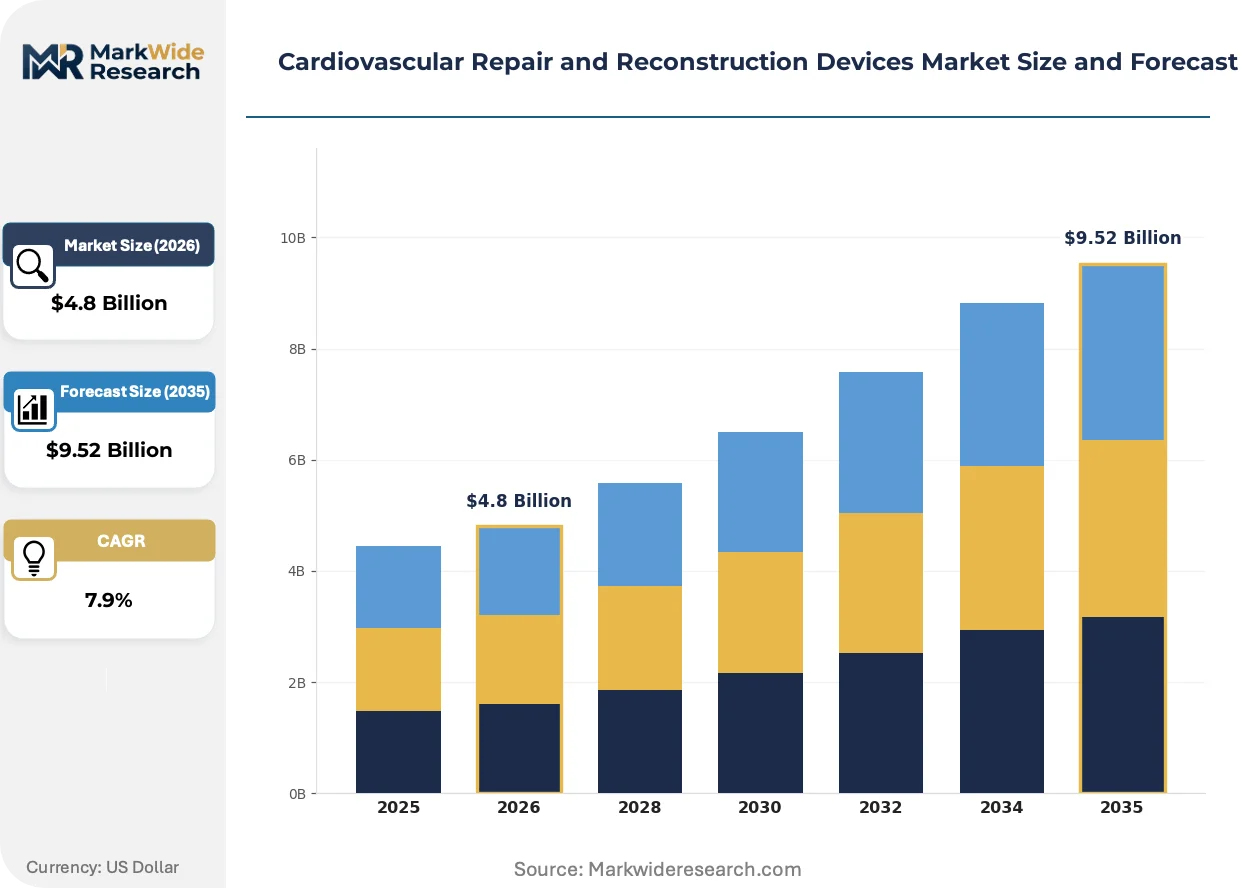
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.52 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Sutures, Grafts, Valves Material: Polymer, Metal, Biologic, Composite End User: Hospitals, Surgical Centers, Clinics, Research Institutions Application: Coronary Bypass, Valve Repair, Aneurysm Repair, Congenital Defects |
| Companies Covered | Medtronic plc, Edwards Lifesciences Corporation, Abbott Laboratories, Boston Scientific Corporation, Terumo Corporation, Johnson & Johnson, Getinge AB, CryoLife, Inc., W. L. Gore & Associates, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiovascular Repair and Reconstruction Devices Market Strategic Shifts & Innovations
Digital health integration is redefining post-implant patient management while materials science advances enable structural solutions previously unattainable with permanent implants.
Polymer-based bioresorbable vascular scaffolds provide temporary luminal support before complete metabolic absorption. Interventional cardiologists at Cleveland Clinic and Mayo Clinic have adopted these platforms for simple lesion subsets. This technology is electrifying the coronary stent competitive landscape by eliminating long-term metallic foreign body exposure and enabling future revascularization options.
The FDA's Breakthrough Devices Program offers expedited development and prioritized review for technologies addressing unmet cardiovascular needs. Manufacturers gain earlier engagement with agency reviewers and flexible clinical evidence requirements. Transcatheter mitral valve repair systems represent the primary beneficiary, with multiple PMA approvals leveraging adaptive trial designs.
Hospital value analysis committees now mandate head-to-head economic evidence against established standards of care. Device representatives must present budget impact models alongside clinical efficacy data. This behavioral shift is most pronounced in California and Massachusetts, where integrated delivery networks consolidate purchasing decisions across multiple facilities.
Cardiovascular Repair and Reconstruction Devices Market Segmentation
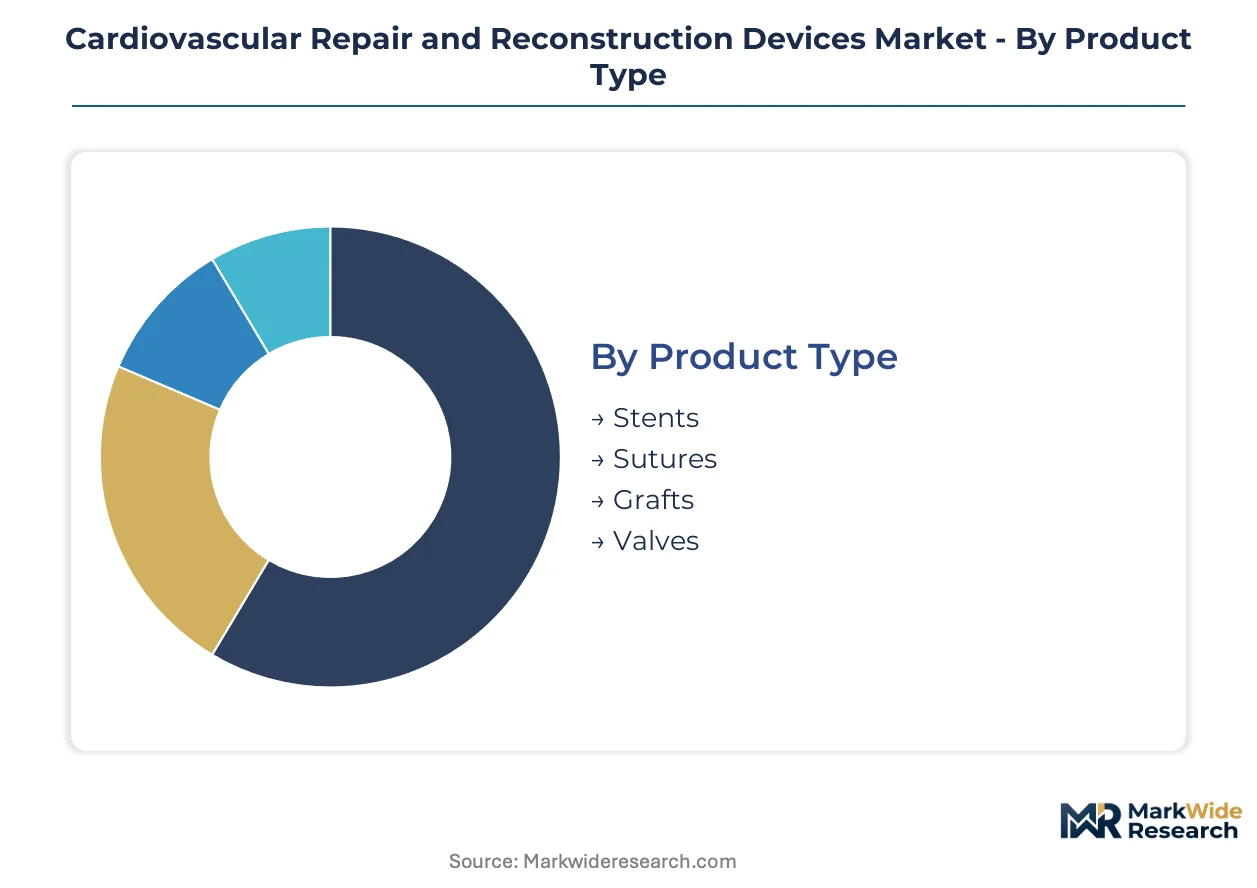
Cardiovascular repair and reconstruction devices segment across multiple dimensions that determine procurement patterns, reimbursement pathways, and clinical adoption curves. Material composition drives biocompatibility testing requirements and regulatory classification. End-user facility type dictates capital equipment needs and procedural volume economics.
Product Type:
Hospital purchasing committees prioritize clinical efficacy benchmarks and total procedure cost when selecting among implantable device categories.
- Stents:Metallic and polymer-based platforms provide luminal scaffolding in coronary and peripheral vessels. Demand concentrates in academic medical centers performing complex multivessel interventions, driven by drug-eluting coating technologies that reduce target lesion revascularization rates.
- Grafts:Tubular conduits fabricated from expanded polytetrafluoroethylene or decellularized biological matrices restore vascular continuity. Procurement volumes cluster in tertiary hospitals performing open surgical aneurysm repair, constrained by the limited availability of size-matched biologic inventories.
- Sutures:Braided polyester and monofilament polypropylene threads enable secure anastomotic closure. Cardiac surgery departments specify tensile strength ratings exceeding three kilograms for sternal closure applications.
- Valves:Mechanical and bioprosthetic replacements restore unidirectional blood flow. Volume sits with stents; growth tilts toward valves.
Material:
Raw material selection determines fatigue resistance thresholds, magnetic resonance imaging compatibility, and long-term implant durability expectations.
- Metal:Nitinol and cobalt-chromium alloys deliver shape-memory properties and radial force for self-expanding stent platforms. Nitinol supply concentrates among European and Japanese metallurgical processors, exposing device manufacturers to nickel price volatility.
- Polymer:Poly-L-lactic acid and polyglycolic acid formulations enable complete metabolic absorption in bioresorbable vascular scaffolds. Cleveland Clinic and Mayo Clinic interventionalists have adopted these platforms for simple lesion subsets.
- Biologic:Bovine pericardium and porcine aortic tissue provide native hemodynamic performance without chronic anticoagulation. Younger patient cohorts seeking tissue-based solutions drive procurement of these premium-priced alternatives.
- Composite:Hybrid constructions combine metallic frames with biological leaflets or polymer coatings. Manufacturing complexity extends good manufacturing practice certification timelines.
End User:
Facility reimbursement infrastructure and procedural volume capacity determine device specification requirements and inventory management protocols.
- Hospitals:Integrated delivery networks consolidate purchasing decisions across multiple catheterization laboratories and operating suites. Florida and Arizona hospital systems report capacity constraints in cardiac procedural units.
- Surgical Centers:Ambulatory facilities focus on same-day discharge protocols and streamlined supply chain logistics. Lower overhead structures enable competitive pricing for standardized valve and graft procedures.
- Clinics:Outpatient settings concentrate on diagnostic workup and post-implant surveillance. Remote hemodynamic monitoring integration creates recurring revenue opportunities.
- Research Institutions:Academic medical centers prioritize investigational device access and fellowship training programs. Fellowship slot constraints limit qualified operator availability.
Application:
Procedure complexity and patient comorbidity profiles shape device selection criteria and post-market surveillance obligations.
- Coronary Bypass:Arterial and venous graft configurations restore myocardial perfusion. Diabetic patient cohorts with multivessel disease receive priority allocation of drug-eluting polymer platforms.
- Valve Repair:Transcatheter and surgical approaches address structural deterioration in native and prosthetic valves. Structural valve deterioration in bioprosthetic tissue remains unresolved for younger populations.
- Aneurysm Repair:Endovascular and open surgical techniques exclude arterial dilation from systemic circulation. Expanded polytetrafluoroethylene grafts dominate open surgical repair volumes.
- Congenital Defects:Pediatric cardiac reconstruction addresses septal defects and vascular malformations. Decellularized xenograft matrices enable off-the-shelf availability without immunosuppression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Costa Rica and Puerto Rico concentrate cardiovascular manufacturing through tax-advantaged export platforms. These zones attract multinational assembly operations serving North American and Latin American markets with streamlined customs processing.
United States
The Medicare-eligible population expansion sustains procedural volume growth for coronary bypass and transcatheter valve replacement. FDA premarket approval pathways for Class III devices extend development timelines beyond five years. Hospital systems in Florida and Arizona report capacity constraints in cardiac catheterization laboratories.
Germany
Notified body capacity under EU Medical Device Regulation creates CE marking bottlenecks for cardiovascular device developers. The country's national pharmaceutical regulator enforces stringent post-market surveillance obligations. Industrial clusters in Baden-Württemberg host specialized nitinol alloy processing facilities serving European device manufacturers.
Japan
Aging demographics drive procedural volume expansion comparable to North American markets. PMDA consultation pathways offer earlier regulatory engagement for breakthrough cardiovascular technologies. Tokyo and Osaka metropolitan areas concentrate academic medical centers performing complex congenital defect repairs.
Switzerland
Premium positioning of biologic valve solutions attracts procurement from younger patient cohorts seeking tissue-based alternatives. Swissmedic maintains rigorous clinical evidence standards that elevate barriers for non-compliant entrants. The Lake Geneva region hosts headquarters operations for major cardiovascular device specialists.
India
Domestic manufacturing incentives under the PLI scheme encourage local production of cardiovascular stents and grafts. CDSCO regulatory harmonization with international standards accelerates market entry for multinational sponsors. Hyderabad and Bengaluru clusters specialize in medical device contract research and manufacturing services.
Cardiovascular Repair and Reconstruction Devices Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated device developers commanding premium positioning in transcatheter valve repair while component suppliers capture volume in standardized graft fabrication. Market structure tilts toward consolidation at the top tier, where diversified medtech conglomerates leverage cross-portfolio synergies. Three archetypes dominate: diversified conglomerates with cardiovascular divisions, pure-play cardiovascular specialists, and contract development and manufacturing organizations. Competitive moves center on strategic partnerships for digital health integration and backward integration into nitinol alloy supply.
Among diversified conglomerates with cardiovascular divisions, Medtronic plc and Johnson & Johnson occupy positions spanning stents, grafts, and surgical tools. Edwards Lifesciences Corporation exemplifies the pure-play specialist archetype through concentrated focus on transcatheter valve technologies. These three entities represent distinct strategic postures—scale-driven diversification, vertical integration into materials processing, and therapeutic-area specialization—without any single approach commanding definitive advantage across all procedural categories.
| Leading Market Players |
|---|
| Medtronic plc |
| Edwards Lifesciences Corporation |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Terumo Corporation |
| Johnson & Johnson |
| Getinge AB |
| CryoLife, Inc. |
| W. L. Gore & Associates, Inc. |
| Others |
Cost & Logistics Intelligence
Bioprosthetic-mechanical valve pricing divergence separates premium tissue-based solutions from commodity metallic alternatives, with that bifurcation manifesting in procurement concentration at academic medical centers versus distributed purchasing at community hospitals and corresponding supply chain configurations that prioritize cold-chain biologics logistics against standardized alloy inventory management.
Pricing Analysis
Volume sits with drug-eluting stents while margins concentrate in transcatheter valve repair systems. Three-tier pricing structure across premium, standard, and economy levels tracks FDA breakthrough designation status and CE marking tier. Pricing pressure stems from hospital value analysis committee mandates for head-to-head economic evidence. Community hospitals exhibit highest price sensitivity; integrated delivery networks in California and Massachusetts least.
Supply Chain Analysis
Single-source vulnerability sits with European and Japanese nitinol alloy processors. Device manufacturing draws from Germany, Switzerland, and Costa Rican special economic zones. Critical inputs encompass shape-memory alloys, decellularized biological matrices, and polymer coatings. Tariff exposure runs through medical device special economic zones. Distribution runs through GPO contracts and direct hospital system agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained nitinol alloy availability props pricing power for integrated manufacturers, with fellowship program slot limitations creating parallel capacity bottlenecks in qualified operator availability.
For Market Incumbents: Acquire nitinol alloy processing capabilities to neutralize input cost volatility from European and Japanese metallurgical suppliers. Secure catheterization laboratory capacity commitments in Florida and Arizona hospital systems facing procedural constraints. Bioresorbable scaffold displacement threatens permanent metallic implant portfolios; backward integration into polymer formulation secures cost position. For New Entrants and Emerging Players: Launch via mobile angiography unit partnerships targeting rural Texas, Georgia, and Ohio catheterization laboratory expansion. Pediatric congenital heart defect repair presents white-space opportunity with limited biologic matrix competition. Decellularized xenograft platforms offer differentiated entry with off-the-shelf availability positioning. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play transcatheter valve specialists given FDA Breakthrough Devices Program acceleration. Five-to-ten year viability hinges on digital health integration capabilities and remote hemodynamic monitoring recurring revenue streams. Watch FDA digital health pre-certification pathway enrollment as inflection signal for software-enabled implant valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Devices Pathway Enrollment | Prioritized review accelerates transcatheter mitral valve repair commercialization timelines. |
| CE Marking Under EU Medical Device Regulation | Notified body capacity constraints elevate barriers for non-compliant device developers. |
| Hospital System GPO Contract Consolidation | Integrated delivery networks in California and Massachusetts centralize purchasing decisions. |
| Software Companion Development | Remote hemodynamic monitoring integration creates recurring revenue and surveillance compliance. |
| Reimbursement Strategy for Transcatheter Procedures | Medicare coverage determination shapes addressable volume for valve repair technologies. |
Research Approach
Independent corroboration across hospital purchasing committee interviews, biomedical engineer consultations, and GPO contracts managers underwrites the qualitative findings. Primary fieldwork engaged interventional cardiologists, cardiac surgeons, regulatory affairs leads at device manufacturers, and CMS reimbursement specialists. Secondary validation drew from FDA PMA filings, CE marking databases, hospital procurement records, and ISO standard documentation. Bottom-up procedure volume modeling triangulated against top-down market size estimates.
Rate-of-change decomposition across the analysis window isolates demographic-driven volume expansion from technology substitution effects and pricing dynamics. Segmentation dimensions encompass product type, material composition, end-user facility tier, and application complexity. CAGRs derive from logistic diffusion curves for novel technologies and replacement demand modeling for established implants. Forecast inputs incorporate PMDA consultation pathway timelines and EU MDR notified body capacity constraints.
FDA approval timeline delays, EU notified body bottlenecks, and nickel price volatility are the dominant revision risks. Forecasts reflect documented assumptions regarding procedural volume growth and technology adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Fibromuscular Dysplasia Treatment Market
Cardiovascular Devices
Global Nitinol Medical Devices Market
Cardiovascular Devices
Non-Invasive Pulse Wave Tonometer Market
Cardiovascular Devices
Medical Devices Cuffs Market
Cardiovascular Devices
South Africa Cardiovascular Devices Market
Cardiovascular Devices
Atherectomy Devices Market
Cardiovascular Devices
Umbilical Vessel Catheters Market
Cardiovascular Devices
Arrhythmogenic Right Ventricular Dysplasia Treatment Market
Cardiovascular Devices
Integrated Cardiology Devices Market
Cardiovascular Devices
Intravascular Ultrasound Market
Cardiovascular Devices
Intra-Aortic Balloon Pump (IABP) Market
Cardiovascular Devices
Cardiovascular CT Systems Market
Cardiovascular Devices
Fractional Flow Reserve-Computed Tomography (FFR-CT) Market
Cardiovascular Devices
Italy Cardiovascular Devices Market
Cardiovascular Devices
Percutaneous Coronary Intervention Guidance Devices Market
Cardiovascular Devices
Global Critical Limb Ischemia Treatment Market