
 Cell Damage & Repair Market | 2026-2036
Cell Damage & Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Damage & Repair Market Analytics
REACH compliance in Europe is hardening purity requirements for reagent-grade compounds used in DNA repair assays. AstraZeneca leverages its synthetic lethality platform to dominate DDR inhibitor development. Bristol-Myers Squibb sustains broad immunotherapy portfolios that intersect with damage response modulation. Novartis anchors radioligand programs that depend on precise DNA repair pathway characterization.
Cell damage and repair encompasses molecular mechanisms that detect, signal, and resolve lesions in DNA, proteins, and lipids, operating through enzymatic cascades with nanomolar binding affinities for lesion recognition. The field serves pharmaceutical development by enabling target validation for oncology, neurodegeneration, and rare disease programs. CRISPR-based technologies lead investment flows due to programmable nuclease precision, while proteomics segments capture expanding margins as mass spectrometry sensitivity improves for post-translational damage mapping. Gene editing tools compete for share against established RNA interference methods in academic procurement.
FDA accelerated approval pathways compress development timelines for DNA damage response modulators, while EMA's ATMP framework shapes manufacturing standards for gene-edited cellular therapies. The EPA monitors solvent waste streams from high-throughput screening laboratories, raising operational compliance costs for contract research organizations. Stakeholders must weigh regulatory divergence between Washington and Brussels when siting clinical manufacturing capacity for repair-targeted biologics.
Market Dynamics
CRISPR-based repair assays are compressing traditional drug discovery timelines as pharmaceutical procurement shifts toward programmable nuclease platforms, forcing reagent suppliers to reconfigure purity grades and batch consistency protocols.
Growth Catalysts
- FDA Accelerated Approval:Compressed clinical trial timelines for DNA damage response inhibitors pull venture capital into early-stage oncology programs. Biotechnology firms anchor manufacturing capacity near Boston and San Diego clusters.
- Synthetic Lethality Platforms:Pharmaceutical pipelines exploit tumor-specific repair deficiencies, expanding demand for PARP inhibitor companion diagnostics. Academic medical centers in Germany and the United Kingdom validate biomarker assays.
- Mass Spectrometry Sensitivity Gains:Proteomics segments capture margin expansion as post-translational damage mapping resolution improves. Contract research organizations in Switzerland upgrade Orbitrap installations.
Market Restraints
- Reagent-Grade Purity Costs:REACH compliance in Europe hardens specifications for oligonucleotide synthesis solvents, raising per-batch qualification expenses for suppliers serving EMA-regulated trials.
- Specialized Talent Scarcity:Gene editing assay development requires rare combinations of molecular biology and computational expertise, concentrating hiring power within three US metropolitan clusters.
- CRISPR Licensing Complexity:Broad Institute and University of California patent thickets create friction for commercial tool developers, delaying product launches by 12-18 months in contested jurisdictions.
Strategic Opportunities
- Radioligand Therapy Convergence:DNA repair pathway characterization enables precise patient stratification for targeted alpha therapies. Novartis anchors manufacturing in Indianapolis and Basel.
- ATMP Manufacturing Standards:EMA's framework for gene-edited cellular therapies creates first-mover advantages for GMP-compliant contract manufacturers in the Netherlands and Belgium.
- Neurodegeneration Pivot:Protein damage repair mechanisms attract pharmaceutical investment as amyloid-targeting antibodies face efficacy ceilings. Japan's AMED funding accelerates tau-focused programs.
Industry Challenges
- Cross-Platform Data Integration:Mass spectrometry proteomics outputs and CRISPR screening datasets use incompatible file formats, forcing bioinformatics teams into manual curation workflows that extend analysis cycles.
- EPA Solvent Waste Compliance:High-throughput screening laboratories face escalating disposal costs for acetonitrile and dimethyl sulfoxide streams, compressing operating margins for US-based contract research organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Damage & Repair Market |
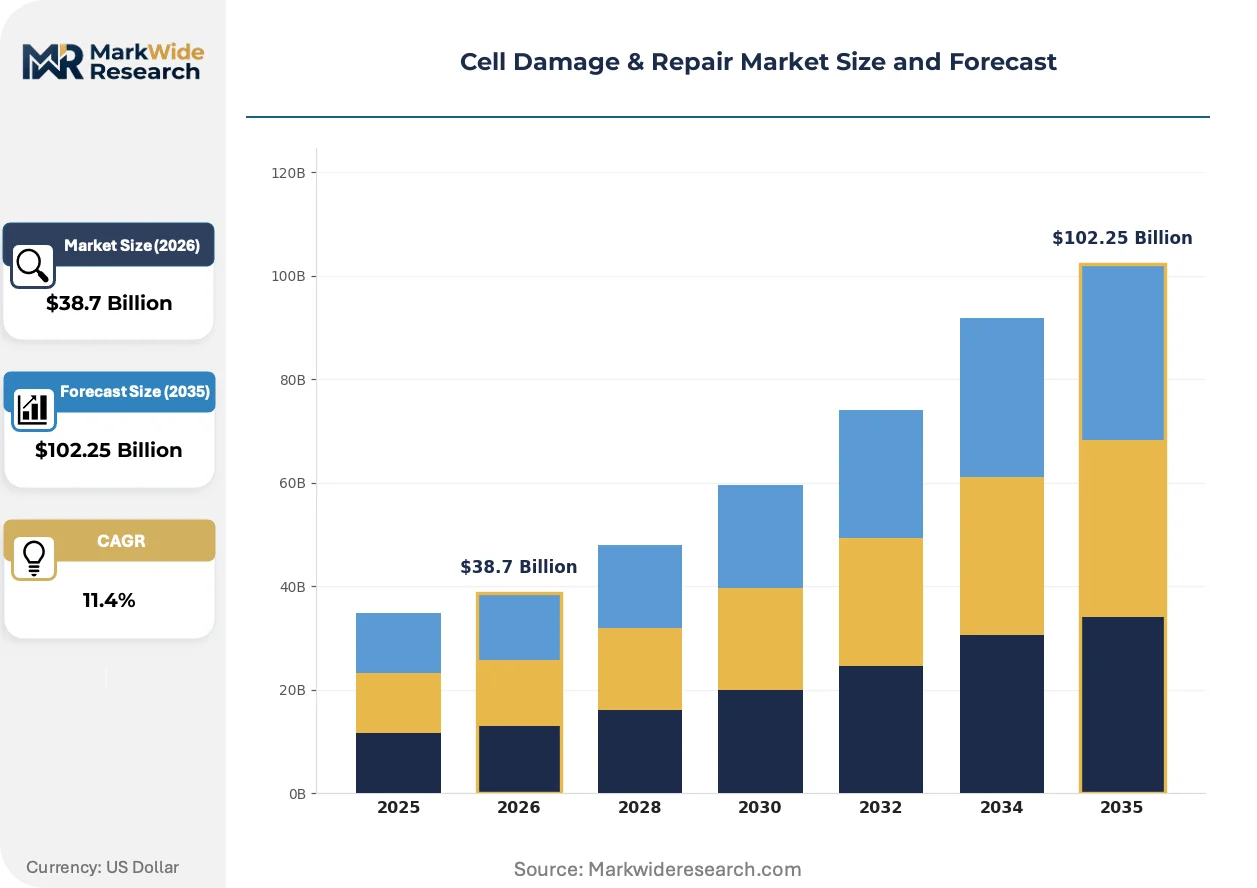
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Tools, Assays Application: Research, Drug Development, Diagnostics, Therapeutics End User: Academic Institutions, Research Laboratories, Hospitals, Pharmaceutical Companies Technology: CRISPR, Gene Editing, Proteomics, Genomics |
| Companies Covered | AstraZeneca, Novartis AG, Bristol-Myers Squibb Company, Repare Therapeutics, Aprea Therapeutics, Mission Therapeutics, Gilead Sciences, Inc., Johnson & Johnson Services, Inc., Chordia Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Damage & Repair Market Evolving Landscape
Programmable nuclease architectures are displacing established RNA interference methods in academic procurement, while regulatory frameworks on both sides of the Atlantic harden manufacturing standards for repair-targeted biologics.
Base editing platforms is integrating cytosine and adenine deaminase domains with catalytically impaired Cas variants to enable precise C-to-T and A-to-G conversions without double-strand breaks. Pharmaceutical discovery groups at Scripps Research and the Broad Institute are adopting these systems for high-throughput knockout screens, compressing target validation timelines from months to weeks as base editing is integrating into standard oncology pipeline workflows.
EMA's ATMP framework is tightening documentation requirements for starting materials in gene-edited cellular therapies, forcing contract manufacturers to implement electronic batch records and real-time environmental monitoring. European production facilities in Belgium and the Netherlands are investing in closed-system bioreactors to meet these standards, while US sponsors face divergent FDA expectations for comparability protocols when bridging clinical material across Atlantic sites.
Academic medical centers are consolidating reagent procurement through cooperative purchasing agreements, displacing individual laboratory ordering autonomy. The University of California system and the UK's Francis Crick Institute now negotiate framework contracts directly with CRISPR tool suppliers, extracting volume discounts that independent research groups cannot match. This concentration is most visible in California and Massachusetts, where institutional purchasing power reshapes supplier sales force deployment.
Cell Damage & Repair Market Segmentation
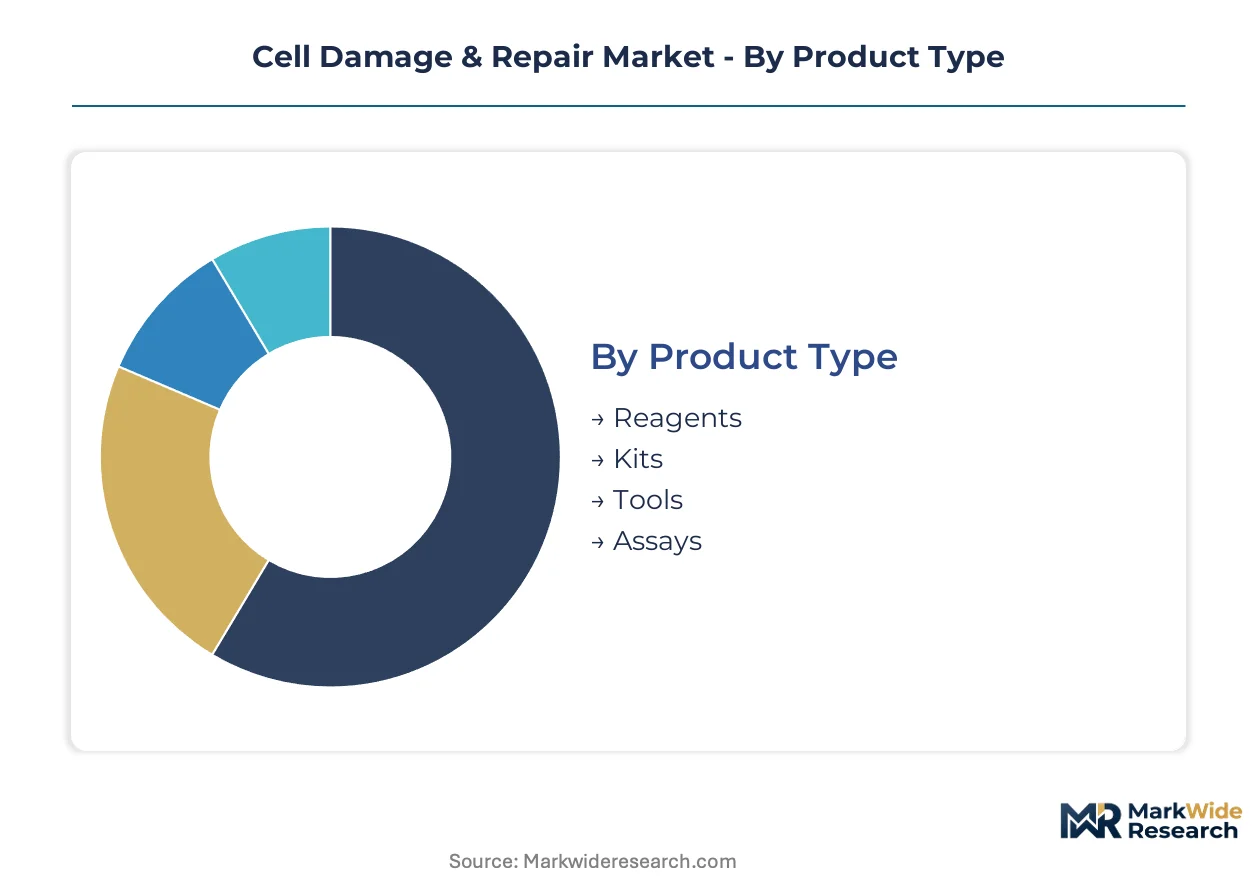
Cell damage and repair technologies serve divergent workflows across discovery, development, and clinical deployment. Procurement patterns split between standardized catalog products for high-throughput screening and customized assay configurations for targeted therapeutic programs. Understanding these segment boundaries clarifies where margin compression concentrates versus where premium pricing persists.
Product Type:
Standardized reagent formulations dominate catalog sales while tool customization escalates for integrated platform deployments.
- Reagents:High-purity oligonucleotides and enzyme preparations with certified endotoxin levels below 0.01 EU/µL. REACH-compliant solvent specifications harden qualification protocols for European supply chains, elevating per-batch documentation burdens.
- Kits:Pre-validated workflow bundles combining extraction buffers, detection antibodies, and calibration standards. Academic medical centers in Massachusetts and California consolidate procurement through cooperative purchasing agreements, extracting volume discounts unavailable to individual laboratories.
- Tools:Programmable nuclease platforms and automated liquid handling systems.
- Assays:Cell-based reporter systems and biochemical activity measurements.
Leading the category by volume: Reagents. Growing fastest: Kits.
Application:
Research applications anchor installed base expansion while therapeutic development commands premium pricing tiers.
- Research:Fundamental mechanism studies and pathway mapping in academic settings. CRISPR-based repair assays compress traditional discovery timelines, pulling venture capital toward early-stage oncology programs near Boston and San Diego clusters.
- Drug Development:Target validation and lead optimization for DNA damage response modulators. FDA accelerated approval pathways compress clinical trial timelines, forcing sponsors to anchor manufacturing capacity near regulatory submission sites.
- Diagnostics:Companion biomarker assays for patient stratification.
- Therapeutics:Gene-edited cellular products and repair-targeted biologics.
Dominating revenue contribution: Drug Development. Expanding most quickly: Therapeutics.
End User:
Pharmaceutical procurement concentrates spend while academic demand fragments across institutional purchasing cooperatives.
- Academic Institutions:University laboratories and medical school research divisions. The University of California system and the UK's Francis Crick Institute negotiate framework contracts directly with CRISPR tool suppliers, reshaping supplier sales force deployment toward institutional buyers.
- Research Laboratories:Independent contract research organizations and government facilities. EPA solvent waste compliance for acetonitrile and dimethyl sulfoxide streams compresses operating margins for US-based CROs.
- Hospitals:Clinical pathology and molecular diagnostic services.
- Pharmaceutical Companies:Integrated discovery and development organizations. AstraZeneca leverages synthetic lethality platforms while Bristol-Myers Squibb sustains broad immunotherapy portfolios intersecting with damage response modulation.
Commanding highest per-site spend: Pharmaceutical Companies. Fastest procurement volume growth: Academic Institutions.
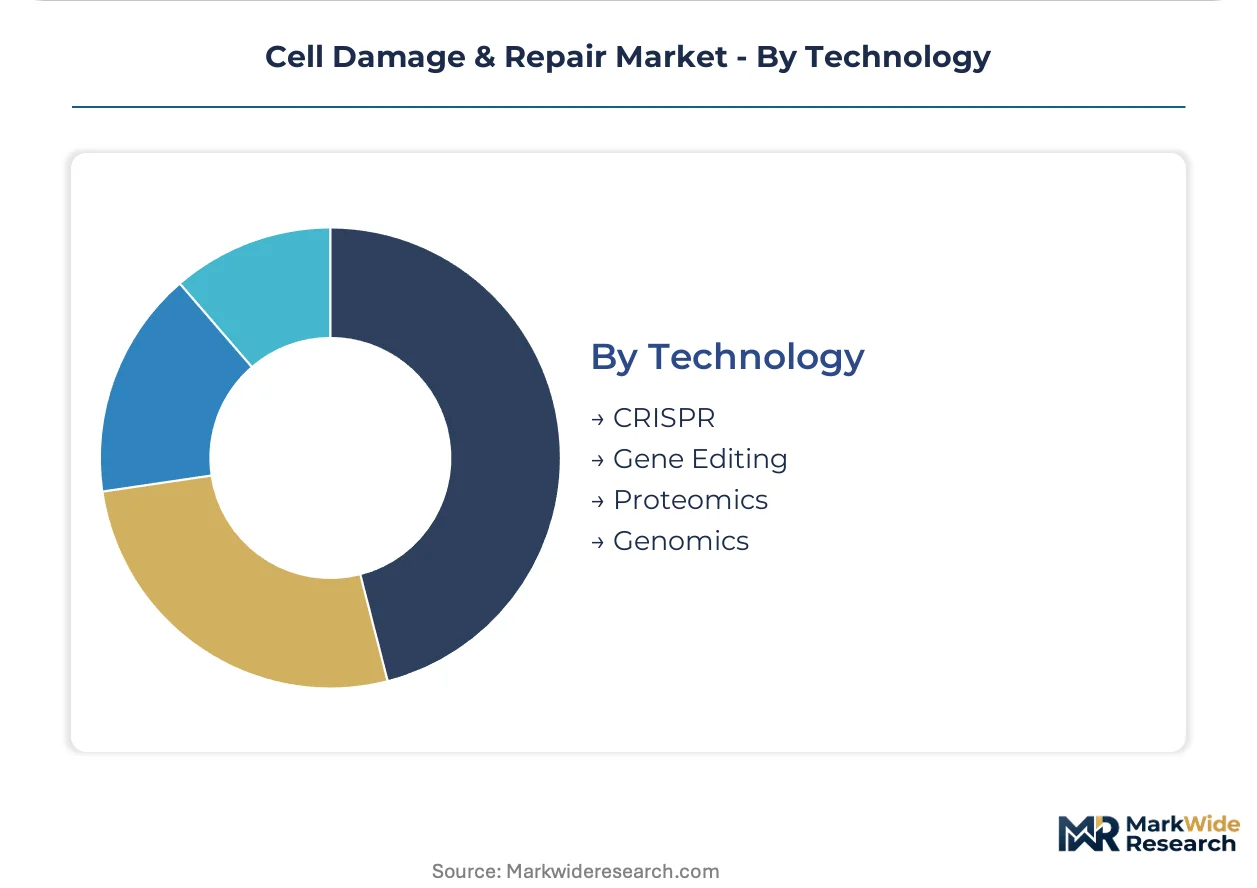
Technology:
Gene editing architectures displace legacy methods while proteomics sensitivity gains unlock new analytical applications.
- CRISPR:Programmable nuclease systems with guide RNA-directed targeting precision. Broad Institute and University of California patent thickets create licensing friction, delaying commercial tool launches by 12-18 months in contested jurisdictions.
- Gene Editing:Base editing platforms integrating cytosine and adenine deaminase domains with catalytically impaired Cas variants. Scripps Research and the Broad Institute adopt these for high-throughput knockout screens, compressing target validation timelines from months to weeks.
- Proteomics:Mass spectrometry-based post-translational damage mapping. Contract research organizations in Switzerland upgrade Orbitrap installations as resolution improvements capture margin expansion.
- Genomics:Sequencing-based lesion detection and repair pathway profiling.
Highest investment flow concentration: CRISPR. Steepest capability improvement trajectory: Proteomics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical procurement concentrates in the United States, where academic medical centers anchor early adoption of CRISPR-based repair assays. Venture capital flows cluster near Boston and San Diego, compressing target validation timelines for DNA damage response modulators. Regulatory divergence between Washington and Brussels shapes manufacturing siting decisions for repair-targeted biologics.
United States
FDA accelerated approval pathways pull venture capital into early-stage oncology programs, compressing clinical trial timelines for DNA damage response inhibitors. The EPA monitors solvent waste streams from high-throughput screening laboratories, raising operational compliance costs for contract research organizations. Biotechnology firms anchor manufacturing capacity near Boston and San Diego clusters, where synthetic lethality platforms dominate pipeline development.
Germany
REACH compliance hardens purity requirements for reagent-grade compounds used in DNA repair assays, elevating per-batch documentation burdens for suppliers. EMA's ATMP framework shapes manufacturing standards for gene-edited cellular therapies, forcing contract manufacturers to implement electronic batch records. Academic medical centers in Heidelberg and Munich validate biomarker assays for PARP inhibitor companion diagnostics.
Switzerland
Mass spectrometry sensitivity gains capture margin expansion as proteomics segments upgrade analytical infrastructure. Swissmedic oversees radioligand therapy manufacturing standards, creating compliance benchmarks for targeted alpha therapies. Contract research organizations in Basel upgrade Orbitrap installations, serving Novartis radioligand programs that depend on precise DNA repair pathway characterization.
United Kingdom
The Francis Crick Institute negotiates framework contracts directly with CRISPR tool suppliers, extracting volume discounts that reshape supplier sales force deployment. MHRA alignment with EMA standards streamlines cross-border trial material movement post-Brexit. London and Cambridge clusters concentrate gene editing assay development, though specialized talent scarcity concentrates hiring power within these metropolitan areas.
Japan
AMED funding accelerates tau-focused protein damage repair programs as amyloid-targeting antibodies face efficacy ceilings. PMDA review pathways for regenerative medicine products create structured entry points for gene-edited cellular therapies. Tokyo and Osaka medical school research divisions expand procurement of programmable nuclease platforms, displacing established RNA interference methods in academic settings.
Cell Damage & Repair Market Competitive Landscape
United States producers anchor one tier; Swiss and German specialists hold differentiated positions in analytical instrumentation and regulatory-compliant manufacturing. The market structures around three archetypes: integrated pharmaceutical conglomerates with synthetic lethality platforms, precision oncology biotechs, and analytical tool suppliers. Competitive moves concentrate on strategic partnerships for CRISPR licensing and capacity expansion for ATMP-compliant manufacturing.
Within the integrated pharmaceutical tier, AstraZeneca and Novartis AG exemplify archetypes leveraging platform breadth. AstraZeneca occupies a position representing synthetic lethality dominance, while Novartis AG anchors radioligand therapy convergence with DNA repair pathway characterization. Bristol-Myers Squibb Company sits within the immunotherapy intersection archetype, sustaining broad portfolios that modulate damage response mechanisms. These three represent the scale-driven end of competitive positioning, though specialized biotechs like Repare Therapeutics and Aprea Therapeutics exemplify focused precision oncology development.
| Leading Market Players |
|---|
| AstraZeneca |
| Novartis AG |
| Bristol-Myers Squibb Company |
| Repare Therapeutics |
| Aprea Therapeutics |
| Mission Therapeutics |
| Gilead Sciences, Inc. |
| Johnson & Johnson Services, Inc. |
| Chordia Therapeutics |
| Others |
Value Network & Pricing Analysis
High-purity oligonucleotide synthesis solvents cascade from specialty chemical manufacturers through reagent-grade distributors into tiered pricing structures shaped by REACH documentation burdens and FDA batch certification requirements. Contract research organizations absorb escalating per-unit costs as European purity specifications harden, while pharmaceutical sponsors negotiate volume discounts that compress margins for independent suppliers.
Pricing Analysis
Short lead-time premiums of 15-25% apply to CRISPR guide RNA libraries and GMP-grade nuclease preparations needed within four weeks for clinical manufacturing campaigns. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified reagents with full regulatory documentation from research-grade catalog products and bulk uncharacterized lots. Price differentiation rests on endotoxin certification tier and geographic delivery cost to Boston or Basel clusters. Cost compression in the standard tier is intensifying because academic purchasing cooperatives extract volume concessions that reshape supplier discount schedules. Academic medical centers exhibit highest price sensitivity due to fixed grant funding, while radioligand therapy developers show least sensitivity given patient-stratification value.
Supply Chain Analysis
Domestic-content mandates in the United States and India's PLI scheme for biotechnology inputs are reshaping sourcing patterns for programmable nuclease production. Supply concentrates in the United States, Germany, and Switzerland for CRISPR tool manufacturing, with China and India anchoring oligonucleotide synthesis feedstocks. Raw material dependencies include phosphoramidite chemistries, recombinant enzyme preparations, and fluorophore-labeled detection reagents. Single-source vulnerability concentrates in Cas9 variant patent licensing held by the Broad Institute and University of California. Distribution runs through authorized distributors for GMP tiers and direct e-commerce platforms for research-grade products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cell damage and repair sector sits in a technology-transition phase where base editing platforms displace first-generation CRISPR-Cas9 systems in pharmaceutical discovery workflows.
For Market Incumbents: Deepen synthetic lethality platform investments to defend against precision oncology biotechs exploiting tumor-specific repair deficiencies. Anchor manufacturing capacity in the Netherlands and Belgium to capture EMA ATMP framework first-mover advantages before FDA comparability protocols diverge further. Lock exclusive CRISPR licensing terms with academic institutions to delay competitive tool launches by 12-18 months. For New Entrants and Emerging Players: Begin with neurodegeneration protein damage repair mechanisms as amyloid-targeting antibodies face efficacy ceilings and Japan's AMED funding accelerates tau-focused programs. Target tau-focused academic consortia in Tokyo and Osaka where RNA interference displacement creates procurement white space. Deploy direct institutional sales teams to bypass distributor markups on programmable nuclease platforms. For Investors and Strategic Acquirers: FDA accelerated approval pathway utilization rates for DNA damage response inhibitors are the leading indicator that synthetic lethality platform valuations will compress or expand. Long-term viability favors vertically integrated players with captive GMP manufacturing and radioligand therapy convergence capabilities. Watch Novartis radioligand program expansion in Indianapolis and Basel as the signal for DNA repair pathway characterization demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| ATMP Manufacturing Scale-Up | EMA-compliant facilities in Belgium and Netherlands capture gene-edited cellular therapy production. |
| CRISPR Licensing Agreement | Patent thickets from Broad Institute and University of California delay commercial tool launches in contested jurisdictions. |
| Clinical Trial Advancement | FDA accelerated approval pathways compress timelines for DNA damage response modulators in oncology pipelines. |
| Radioligand Therapy Convergence | DNA repair pathway characterization enables precise patient stratification for Novartis targeted alpha therapies. |
| Base Editing Platform Integration | Cytosine and adenine deaminase domains at Scripps Research compress target validation from months to weeks. |
Research Methodology
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone for tracking DNA damage response inhibitor development timelines and regulatory approval pathways. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists validated pipeline assumptions and pricing dynamics. Bottom-up and top-down triangulation reconciled reagent supplier shipment data with pharmaceutical R&D expenditure disclosures across the analysis window.
Bottom-up modeling anchored volume estimates in programmable nuclease procurement patterns by academic medical centers and pharmaceutical discovery groups. Top-down cross-checks applied treatment-line segmentation, dosage form categories, and regional regulatory cluster frameworks to constrain projection boundaries. CAGRs were derived from fitted growth curves calibrated against historical gene editing tool adoption rates and mass spectrometry sensitivity improvement trajectories. Forecast inputs incorporated synthetic lethality platform expansion rates and radioligand therapy manufacturing capacity buildouts.
Underlying measurement precision varies by segment; CRISPR-based repair assays and proteomics segments carry tighter precision than emerging base editing platforms where commercial traction remains uneven. Forecasts reflect assumptions about FDA accelerated approval pathway continuity and EMA ATMP framework stability. Patent litigation outcomes and EPA solvent waste compliance cost escalation represent specific risk factors that could revise trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Europe Regenerative Medicines Market
Regenerative Medicine
Tenosynovial Giant Cell Tumor Treatment Market
Regenerative Medicine
Dural Graft Market
Regenerative Medicine
Longevity and Anti-Senescence Therapy for Cancer Market
Regenerative Medicine
Global Breast Reconstruction Market
Regenerative Medicine
Orthopedic Regenerative Medicine Market
Regenerative Medicine
Hyper Personalized Medicine Market
Regenerative Medicine
US Regenerative Medicine Market
Regenerative Medicine
China Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Tooth Regeneration Market
Regenerative Medicine
Asia Pacific Platelet Rich Plasma Market
Regenerative Medicine
US Scar Treatment Market
Regenerative Medicine
US Platelet Rich Plasma Market
Regenerative Medicine
North America Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Mesotherapy Guns Market
Regenerative Medicine
North America Regenerative Medicines Market