
 Cardiac Ablation Technologies Market | 2026-2036
Cardiac Ablation Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Ablation Technologies Market Analysis
Hospital electrophysiology departments is rotating toward outpatient surgical centers as the fastest-growing buyer archetype for cardiac ablation systems. Medtronic leverages its integrated mapping and ablation platform to sustain technology leadership across major markets. Johnson & Johnson anchors its competitive position through irrigated catheter specialization. Abbott Laboratories differentiates with contact force-sensing catheter systems that occupy premium procedural segments.
Cardiac ablation technologies encompass energy-delivery systems and navigation platforms that destroy arrhythmic cardiac tissue through controlled thermal or electrical energy application, typically operating at radiofrequency ranges of 300-750 kHz or cryogenic temperatures below minus 40 degrees Celsius to achieve transmural lesion formation. These systems serve the primary commercial purpose of reducing recurrent atrial fibrillation burden and preventing stroke-related hospitalizations in patients refractory to antiarrhythmic drug therapy. Radiofrequency ablation systems lead procedural volume due to established reimbursement and operator familiarity, while cryoablation platforms represent the fastest-growing energy modality driven by shorter learning curves and single-shot pulmonary vein isolation capabilities. Mapping systems command concentrated margin pools as hospitals prioritize three-dimensional electroanatomical navigation to reduce fluoroscopy exposure and improve procedural efficiency.
The FDA regulates cardiac ablation catheters as Class III medical devices requiring premarket approval, while the EU MDR imposes strengthened clinical evidence requirements for CE marking of active implantable and invasive cardiovascular devices. Japan's PMDA maintains distinct technical standards for radiofrequency generators that shape product registration timelines and design modifications for that market. Stakeholders must monitor evolving CMS national coverage determinations for catheter ablation indications and EU notified body capacity constraints that could delay market access timelines.
Market Dynamics
Catheter-based radiofrequency systems are consolidating procedural workflows as electrophysiology labs prioritize single-vendor platform integration over multi-supplier configurations.
Growth Catalysts
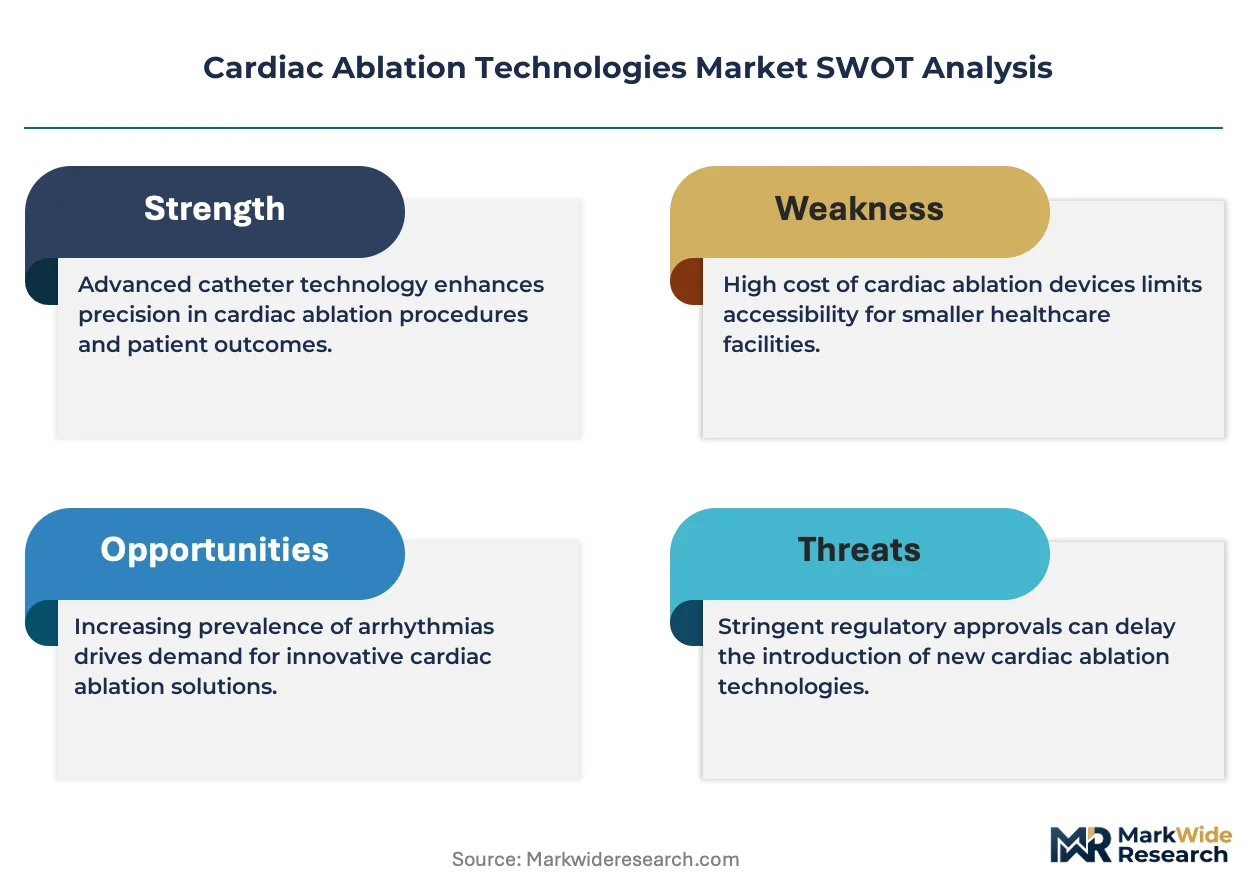
- EU MDR streamlined pathways:Accelerated CE marking timelines for breakthrough ablation devices reduce commercialization delays across European hospital networks.
- Outpatient surgical centers:Ambulatory facility construction in the United States creates dedicated procedural capacity outside traditional hospital infrastructure.
- Pulsed field ablation:Next-generation energy delivery mechanisms demonstrate superior safety profiles in cardiac tissue specificity testing.
Market Restraints
- Generator hardware concentration:Radiofrequency power supply manufacturing clusters in Germany and Japan create geographic supply vulnerability.
- Reimbursement lag:CMS national coverage determinations trail FDA approvals by eighteen to thirty-six months for novel ablation indications.
- Fluoroscopy dependence:Persistent reliance on X-ray guidance limits procedural expansion into resource-constrained clinical settings.
Strategic Opportunities
- India's cardiac centers:Private hospital chains in Mumbai and Delhi are installing dedicated electrophysiology suites without legacy equipment constraints.
- Japan's PMDA fast-track:Sakigake designation pathways compress review timelines for innovative ablation catheters targeting ventricular arrhythmias.
- AI-integrated mapping:Machine learning algorithms combined with electroanatomical navigation reduce procedure duration and operator training requirements.
Industry Challenges
- Electrophysiologist training pipelines:Fellowship program capacity constraints in the United States limit qualified operator supply expansion.
- Legacy mapping system integration:New ablation catheters require software compatibility layers with installed three-dimensional navigation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Ablation Technologies Market |
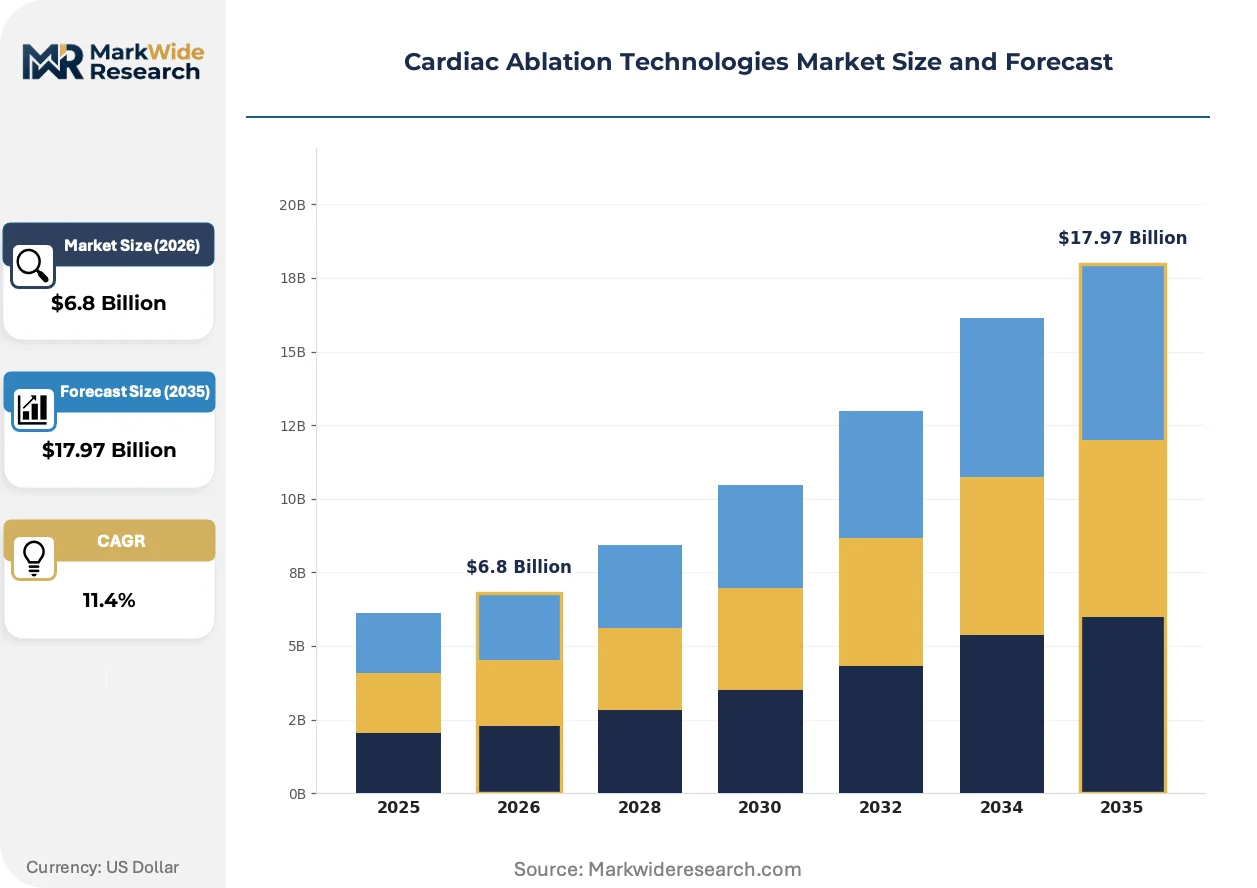
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiofrequency, Cryoablation, Laser, Microwave Technology: Mapping Systems, Irrigated Catheters, Non-irrigated Catheters, Ablation Systems End User: Hospital, Surgical Center, Cardiology Clinics, Research Institutes Application: Atrial Fibrillation, Atrial Flutter, Ventricular Tachycardia, Supraventricular Tachycardia |
| Companies Covered | Medtronic, Johnson & Johnson, Boston Scientific Corporation, Abbott Laboratories, AtriCure, AngioDynamics, Biotronik, MicroPort Scientific Corporation, Acutus Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Ablation Technologies Market Emerging Trajectories
Energy modality diversification and navigation autonomy are compressing the traditional trade-off between procedural safety and operator skill requirements.
Pulsed field ablation technology delivers irreversible electroporation through non-thermal cellular membrane disruption. Academic medical centers in Germany and the Netherlands are adopting these systems for first-line paroxysmal atrial fibrillation cases. This mechanism is supplanting thermal ablation in select patient populations where esophageal injury risk previously limited treatment candidacy.
EU MDR clinical evidence requirements now mandate post-market surveillance data collection for active implantable cardiovascular devices. Manufacturers must maintain technical documentation across product lifecycles with annual safety reporting to notified bodies. Cryoablation catheter suppliers face compressed timelines for real-world evidence generation to support CE marking renewals.
Hospital procurement committees now bundle mapping system acquisitions with multi-year catheter supply agreements. Integrated platform contracts displace standalone device purchasing in United States health systems exceeding five hundred beds. This consolidation concentrates vendor relationships within electrophysiology departments seeking standardized training protocols.
Cardiac Ablation Technologies Market Segmentation
Segmentation in cardiac ablation technologies reveals how energy modalities, navigation platforms, and care settings compete for capital allocation. Understanding these divisions exposes where substitution pressures and integration trends reshape procurement priorities across electrophysiology service lines.
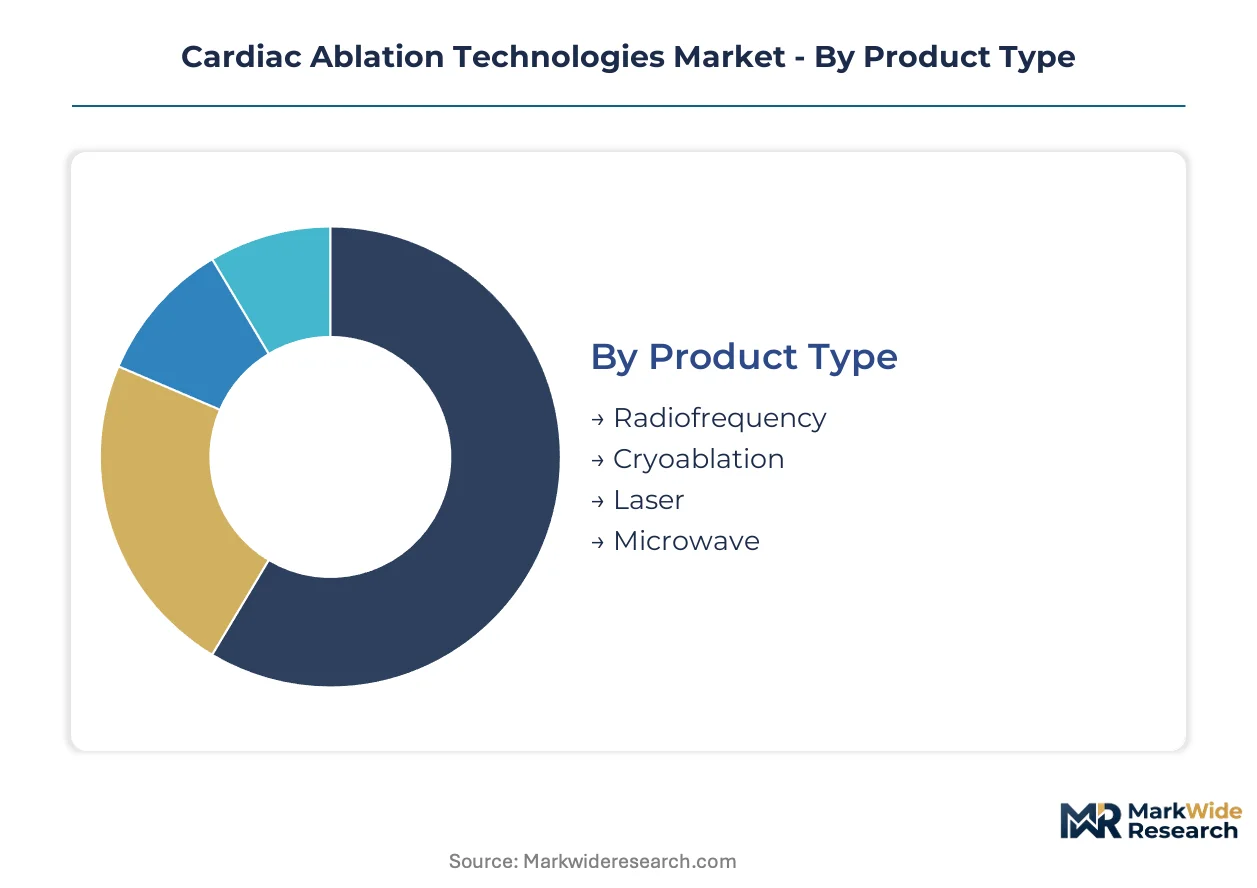
Product Type:
Radiofrequency platforms face the most intense substitution pressure as pulsed field ablation enters clinical validation, while cryoablation defends its position through procedural simplicity advantages.
- Radiofrequency:Thermal energy delivery at 300-750 kHz frequencies creates transmural lesions through resistive heating of cardiac tissue. Hospital electrophysiology labs in the United States and Germany deploy these systems for complex arrhythmia substrates where precise lesion control matters; operator familiarity and established CMS reimbursement codes sustain installed base dominance despite thermal injury risks.
- Cryoablation:Nitrous oxide or argon-based cooling achieves temperatures below minus 40 degrees Celsius for tissue destruction via ice crystal formation and osmotic stress. Single-shot balloon designs enable rapid pulmonary vein isolation, attracting surgical centers in Japan and ambulatory facilities seeking shorter procedure times with reduced training barriers.
- Laser:Optical energy delivery through fiberoptic catheter channels enables direct visual targeting of arrhythmic foci.
- Microwave:Electromagnetic field generation produces deeper heating profiles than radiofrequency in select myocardial thickness applications.
Radiofrequency handles the majority of throughput; cryoablation is the fastest mover on share.
Technology:
Cost tier stratification separates premium navigation platforms from commoditized catheter hardware, with mapping systems capturing disproportionate margin pools relative to procedural volume.
- Mapping Systems:Three-dimensional electroanatomical navigation platforms reconstruct cardiac chamber geometry from electrode catheter contact points, enabling fluoroscopy-free ablation guidance. Academic medical centers in the Netherlands and university hospitals in Germany prioritize these investments to reduce radiation exposure and improve first-pass isolation rates.
- Irrigated Catheters:Saline-cooled electrode tips prevent char formation and enable higher power delivery without thrombus risk, expanding lesion depth control for ventricular applications.
- Non-irrigated Catheters:Standard electrode designs serve cost-sensitive procedural environments and straightforward atrial flutter ablations.
- Ablation Systems:Integrated generator-cart combinations bundle energy delivery with pressure monitoring and impedance feedback.
Mapping systems command premium pricing tiers; irrigated catheters are climbing the fastest on procedural adoption curves.
End User:
Customer type fragmentation reflects divergent capital intensity tolerance, with outpatient migration disrupting traditional hospital-centric equipment deployment models.
- Hospital:Integrated electrophysiology labs with hybrid operating room capabilities manage complex ventricular tachycardia cases requiring hemodynamic support and surgical standby.
- Surgical Center:Dedicated ambulatory facilities in the United States target straightforward paroxysmal atrial fibrillation cases with same-day discharge protocols.
- Cardiology Clinics:Office-based diagnostic and follow-up services refer intervention candidates to procedural centers.
- Research Institutes:Academic centers in Germany and Japan conduct first-in-human trials for novel energy modalities and mapping algorithms.
Hospitals retain the bulk of complex case volume; surgical centers are expanding their addressable procedure base most aggressively.
Application:
Clinical indication maturity varies sharply, with atrial fibrillation commanding technology development investment while ventricular applications await durable safety validation.
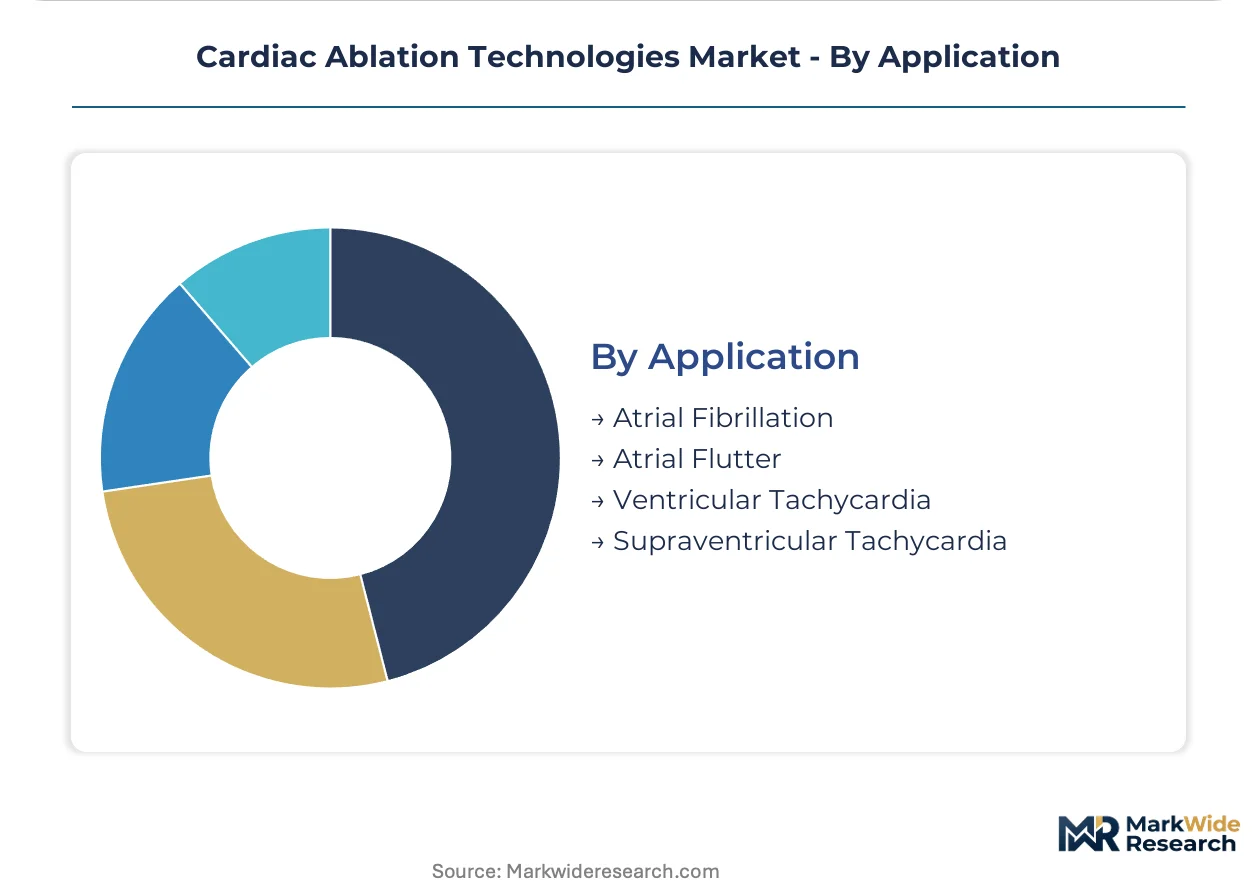
- Atrial Fibrillation:Irregular atrial electrical activation from pulmonary vein triggers drives the largest procedural volume, with catheter ablation now competing with antiarrhythmic drugs as first-line rhythm control therapy.
- Atrial Flutter:Macro-reentrant right atrial circuits offer straightforward ablation targets with high acute success rates and lower recurrence than atrial fibrillation.
- Ventricular Tachycardia:Life-threatening arrhythmias arising from scar-related reentry in ischemic cardiomyopathy require substrate mapping and often hemodynamic support.
- Supraventricular Tachycardia:Accessory pathway and atrioventricular nodal reentry tachycardias present curative ablation opportunities with minimal infrastructure requirements.
Atrial fibrillation absorbs the dominant share of catheter development investment; ventricular tachycardia ablation is advancing most rapidly on expanded indication eligibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports radiofrequency generator hardware to electrophysiology labs across the United States and Japan, establishing a critical trade corridor in cardiac ablation equipment supply chains.
United States
CMS reimbursement maturity for atrial fibrillation ablation and ambulatory surgical center expansion drive procedural volume growth. The FDA's Class III premarket approval pathway shapes product development timelines for catheter manufacturers. Hospital networks in Texas and Florida are consolidating electrophysiology service lines under single-vendor platform contracts.
Germany
Academic medical centers in Heidelberg and Munich pioneer pulsed field ablation adoption for paroxysmal cases. The EU MDR's strengthened clinical evidence requirements compress CE marking renewal timelines for cryoablation catheter suppliers. Bavaria's medical technology cluster hosts concentrated radiofrequency generator manufacturing capacity serving European hospital networks.
Japan
PMDA's Sakigake fast-track designation accelerates review timelines for innovative ventricular arrhythmia catheters. Aging demographics expand the eligible patient pool for stroke-prevention procedures. Tokyo and Osaka metropolitan hospitals prioritize contact force-sensing systems to reduce fluoroscopy exposure in complex substrate ablations.
India
Private hospital chains in Mumbai and Delhi install dedicated electrophysiology suites without legacy equipment constraints. The country's national pharmaceutical regulator maintains distinct import licensing requirements for active implantable cardiovascular devices. Bangalore's medical device corridor attracts catheter assembly operations targeting domestic and Southeast Asian markets.
Netherlands
Three-dimensional electroanatomical mapping adoption concentrates in Amsterdam and Rotterdam academic centers seeking fluoroscopy-free workflows. EU MDR notified body capacity constraints in the region delay market access for novel ablation indications. Dutch electrophysiology labs serve as clinical validation sites for next-generation navigation algorithms.
Cardiac Ablation Technologies Market Vendor Landscape
Player mix skews toward diversified medical technology conglomerates with integrated electrophysiology platforms, creating a consolidated structure where single-vendor contracts displace multi-supplier configurations. Tier-one participants combine mapping system hardware with catheter supply agreements. Tier-two specialists concentrate on irrigated or force-sensing catheter designs. Competitive moves center on platform integration bundling and outpatient surgical center partnerships.
Among diversified technology conglomerates, Medtronic and Johnson & Johnson occupy positions exemplifying integrated platform strategies, while Abbott Laboratories represents the force-sensing catheter specialization archetype. These three anchors demonstrate how vendor relationships concentrate within electrophysiology departments seeking standardized training protocols and multi-year supply security.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Boston Scientific Corporation |
| Abbott Laboratories |
| AtriCure |
| AngioDynamics |
| Biotronik |
| MicroPort Scientific Corporation |
| Acutus Medical |
| Others |
Supply Flow & Price Mechanics
Multi-year catheter supply agreements bundled with mapping system acquisitions lock in both supply access and price visibility for United States hospital networks exceeding five hundred beds, insulating electrophysiology departments from spot-market volatility while committing capital to single-vendor platforms.
Pricing Analysis
Next-generation pulsed field ablation systems command premium positioning against established radiofrequency platforms and legacy cryoablation equipment. Three-tier pricing structure across premium force-sensing catheters, standard irrigated designs, and economy non-irrigated configurations reflects FDA breakthrough designation status and CE marking tier under EU MDR. Cost compression in standard radiofrequency catheter tiers intensifies as outpatient surgical centers negotiate volume-based contracts. Ambulatory facilities exhibit highest price sensitivity; academic medical centers prioritize premium navigation capabilities over unit economics.
Supply Chain Analysis
Strategic stockpiling of radiofrequency generator hardware dominates procurement behavior among German and Japanese electrophysiology labs facing extended lead times from Bavaria's concentrated manufacturing cluster. Radiofrequency power supply production centers on Germany, Japan, and select United States facilities. Nitrous oxide cryogen supply and fiberoptic catheter components draw from specialized chemical and optical manufacturing bases. Single-source vulnerability in generator hardware creates geographic concentration risk. Distribution runs through hospital procurement committees and GPO contracts rather than direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pulsed field ablation technology threatens thermal modality incumbents with superior safety profiles, forcing established players to defend installed base relationships while accelerating next-generation platform development.
For Market Incumbents: Shield market position by deepening backward integration into force-sensing catheter manufacturing and securing exclusive mapping system software compatibility layers. Accelerate pulsed field ablation R&D investment to match emerging competitor safety claims. Prioritize long-term platform contracts with United States hospital networks to lock out substitute technology trials. For New Entrants and Emerging Players: Outpatient surgical center service gaps present immediate white-space opportunity where legacy vendors under-serve ambulatory workflow requirements. Target straightforward paroxysmal atrial fibrillation cases in United States freestanding facilities lacking legacy equipment constraints. Pursue direct sales models bypassing hospital GPO structures to capture price-sensitive volume. For Investors and Strategic Acquirers: Force-sensing catheter specialists with proprietary pressure-monitoring IP represent attractive acquisition targets as platform consolidation accelerates. Long-term viability hinges on navigation autonomy and AI-integrated mapping capabilities displacing fluoroscopy-dependent workflows. Watch for FDA breakthrough designation announcements as inflection indicators for technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Pulsed Field Ablation Platform Development | FDA breakthrough designation accelerates market entry against thermal modalities in paroxysmal atrial fibrillation. |
| AI-Integrated Mapping System Launch | Machine learning algorithms reduce procedure duration and operator training barriers in electrophysiology labs. |
| Outpatient Surgical Center Partnership | Ambulatory facility expansion in Texas and Florida creates dedicated procedural capacity outside hospital infrastructure. |
| Force-Sensing Catheter Manufacturing Scale-Up | Contact pressure monitoring improves lesion quality and reduces esophageal injury risk in complex substrates. |
| EU MDR CE Marking Pathway Acceleration | Streamlined notified body engagement compresses renewal timelines for cryoablation catheter suppliers. |
Methodological Framework
Initial hypotheses were tested against primary input from electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation across FDA 510(k) and PMA filings, CMS national coverage determinations, EU MDR notified body documentation, and hospital procurement database records. Bottom-up catheter volume estimates triangulated with top-down energy modality spend analysis across the analysis window.
Variance decomposition structured the analytical framework across product type, technology tier, end-user facility category, and clinical indication severity throughout the forecast period. CAGRs derived from procedure volume trajectories weighted by reimbursement code maturity and technology substitution elasticity. Pulsed field ablation adoption curves and outpatient migration rates served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA Class III PMA pathways and EU MDR CE marking regimes; material policy shifts would require re-modeling. Revision becomes warranted when pulsed field ablation safety data crosses superiority thresholds in head-to-head clinical trials.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Renovascular Hypertension Treatment Market
Cardiovascular Devices
Bioresorbable Coronary Stents Market
Cardiovascular Devices
United Kingdom Cardiovascular Devices Market
Cardiovascular Devices
Cardiac Cryoablation Device Market
Cardiovascular Devices
Global Atrial Fibrillation Surgery Market
Cardiovascular Devices
Global Blood Pressure Cuffs Market
Cardiovascular Devices
Stent Grafts Market
Cardiovascular Devices
Radiofrequency Balloon Catheter Market
Cardiovascular Devices
Dual Therapy Stent Market
Cardiovascular Devices
Global Pericardiocentesis Procedures Market
Cardiovascular Devices
Global Cardiovascular Ultrasound System Market
Cardiovascular Devices
Catheter-Directed Thrombolysis Market
Cardiovascular Devices
Vascular Prostheses Market
Cardiovascular Devices
Cardiac Implantable Electronic Device Market
Cardiovascular Devices
Interventional Cardiology Market
Cardiovascular Devices
Global Transcranial Doppler Ultrasound Market