
 Global Nitinol-Based Medical Devices Market | 2026-2036
Global Nitinol-Based Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nitinol-Based Medical Devices Market Outlook
The EU MDR is shifting cost-of-entry calculus for nitinol device manufacturers by mandating extended clinical follow-up and notified body re-certification. Medtronic plc leverages its vertically integrated superelastic alloy supply chain to sustain margin resilience under these compliance burdens. Boston Scientific Corporation anchors its European portfolio through dedicated MDR transition teams that navigate renewed technical documentation requirements.
Nitinol-based medical devices exploit a near-equiatomic nickel-titanium alloy exhibiting superelasticity and thermal shape memory, typically processed through vacuum arc remelting and cold working to achieve Af temperatures between 25°C and 35°C for physiological activation. Stents and guidewires dominate current revenue pools, with cardiovascular applications commanding premium pricing due to catheter-delivered deployment complexity. Minimally invasive delivery modes now outpace open surgical alternatives, as hospital systems prioritize reduced length-of-stay metrics and ambulatory shift compatibility.
The FDA maintains stringent biocompatibility and fatigue testing protocols under 21 CFR Part 820 quality system regulations, while ISO 25539-1 governs endovascular device structural validation across major markets. Japan's PMDA imposes additional nickel ion release assessments that extend premarket review cycles for nitinol implants. Stakeholders must monitor evolving sterilization validation requirements and alloy traceability standards as regulators tighten supply chain documentation expectations.
Market Dynamics
The EU Medical Device Regulation is compressing conformity assessment timelines while mandating extended clinical follow-up for shape-memory implants, forcing manufacturers to restructure quality management systems and notified body relationships ahead of certificate expiration deadlines.
Growth Catalysts
- CMS Reimbursement Expansion:The US Centers for Medicare and Medicaid Services continues broadening coverage determinations for transcatheter procedures, directly enlarging addressable patient populations for nitinol stenting interventions.
- Ambulatory Surgical Center Migration:Hospital systems across Germany and the United States are redirecting catheterization lab budgets toward same-day discharge protocols compatible with nitinol device deployment.
- Superelastic Alloy Processing:Advances in vacuum arc remelting and cold working techniques enable tighter Af temperature control between 25°C and 35°C, improving physiological activation reliability.
Market Restraints
- Nickel Supply Concentration:Primary nickel refining capacity clusters in Indonesia and Russia, exposing nitinol feedstock costs to geopolitical supply disruptions and export restriction cascades.
- PMDA Review Cycles:Japan's Pharmaceuticals and Medical Devices Agency imposes supplemental nickel ion release assessments that extend premarket approval timelines by twelve to eighteen months relative to FDA pathways.
- Polymer Stent Substitution:Bioresorbable vascular scaffold technologies in coronary applications threaten nitinol's dominance in peripheral indications as polymer fatigue resistance improves.
Strategic Opportunities
- India Catheterization Infrastructure:Greenfield hospital construction in Mumbai and Delhi creates first-mover positioning for nitinol guidewire and stent suppliers as cardiac intervention volumes accelerate.
- EU MDR Transition Services:Technical documentation remediation and clinical evidence gap analysis for legacy devices represents a service revenue stream parallel to hardware sales.
- Robotic-Assisted Deployment:Convergence of magnetic navigation systems with nitinol device flexibility enables remote catheter manipulation, opening interventional radiology to telesurgery architectures.
Industry Challenges
- Notified Body Bottleneck:EU MDR designation delays have reduced the pool of certifying organizations capable of reviewing Class III implantable devices, stretching queue times beyond thirty-six months.
- Alloy Traceability Documentation:Regulators in Switzerland and Australia now mandate lot-level vacuum arc remelting records, forcing supply chain software upgrades and vendor qualification re-audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nitinol-Based Medical Devices Market |
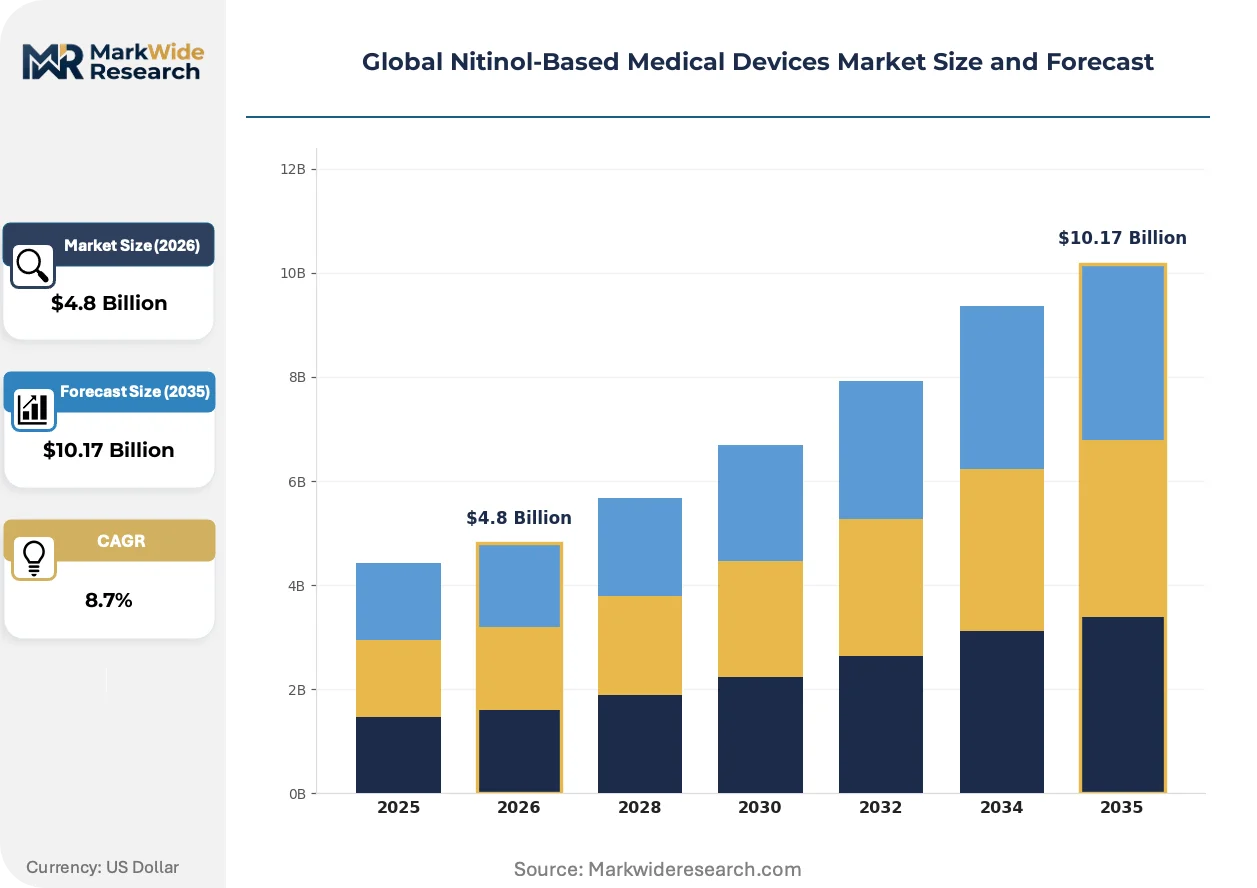
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Guidewires, Surgical Instruments, Catheters Application: Cardiovascular, Orthopedics, Urology, Gastroenterology End User: Hospitals, Surgical Centers, Clinics, Laboratories Delivery Mode: Minimally Invasive, Robotic-Assisted, Open Surgery, Intervention |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Abbott Laboratories, Terumo Corporation, Edwards Lifesciences, Becton Dickinson and Company, W.L. Gore & Associates, Cook Medical, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nitinol-Based Medical Devices Market Strategic Shifts
Computational modeling and additive manufacturing are converging to reshape nitinol device development cycles, compressing prototyping timelines while enabling patient-specific geometries previously unattainable through conventional subtractive methods.
Shape-set programming via laser micromachining is integrating finite element analysis predictions directly into manufacturing workflows, allowing stent designers to preload specific mechanical responses at defined temperature thresholds. Interventional cardiologists in tertiary US hospital systems are adopting these next-generation platforms for complex tortuous anatomy cases. The technology is integrating predictive biomechanical simulation with real-time deployment feedback, collapsing the iteration cycle between bench testing and first-in-human trials.
The EU Medical Device Regulation's Annex XIV clinical evaluation requirements are mandating systematic literature reviews and post-market clinical follow-up protocols that exceed prior Medical Device Directive standards. Manufacturers must now demonstrate equivalence through biological, technical, and clinical criteria simultaneously, not sequentially. Small and mid-cap device developers without legacy predicate data are responding by sponsoring prospective registries across German and French hospital networks to generate de novo evidence packages.
Hospital procurement committees are consolidating vendor relationships for catheterization lab consumables, bundling nitinol stents with guidewires and delivery systems under multi-year framework agreements. This concentration is displacing spot purchasing through distributor networks across US integrated delivery networks and UK National Health Service trusts. The shift is most visible in cardiovascular service lines where value-analysis teams now mandate total procedure cost targets rather than line-item device pricing.
Global Nitinol-Based Medical Devices Market Segmentation
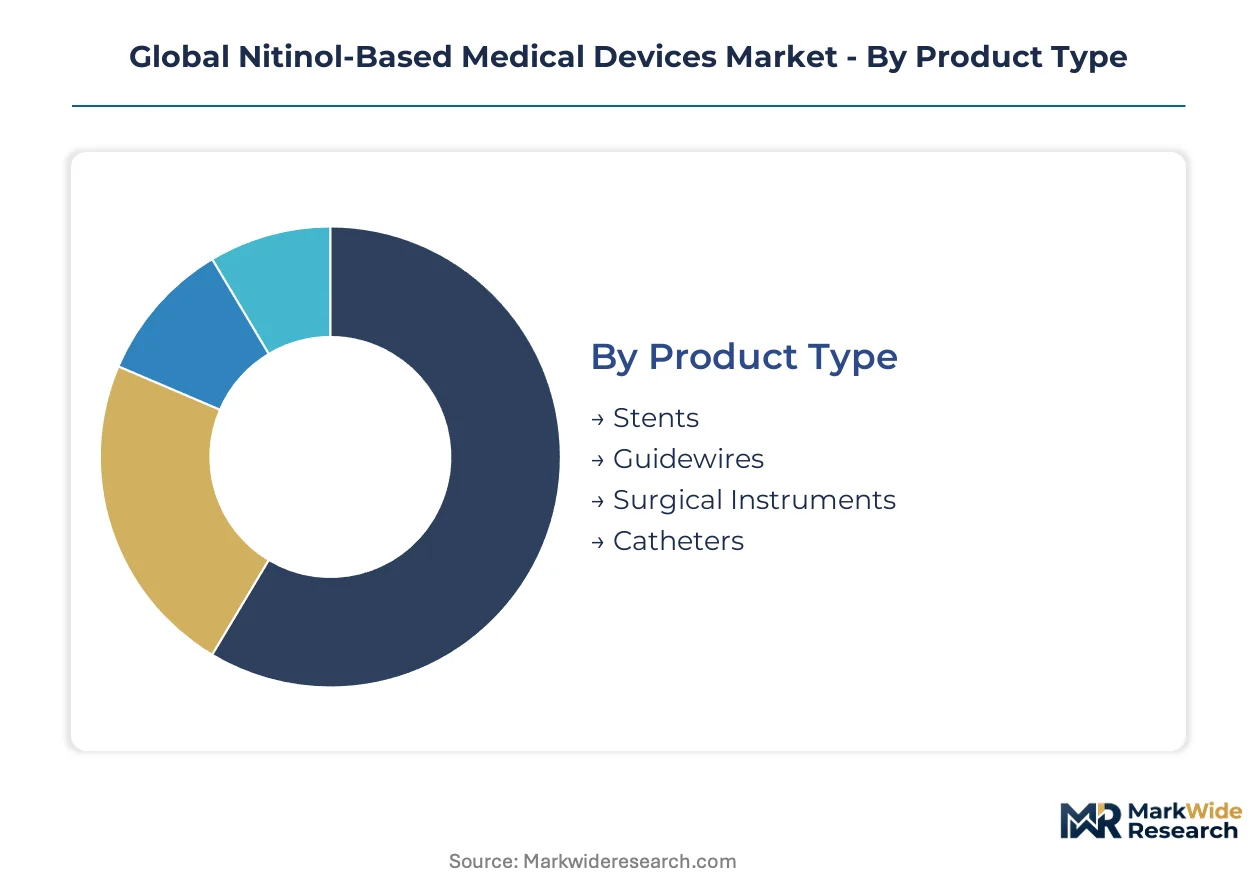
Nitinol device segmentation reveals distinct value capture patterns across integration depths. Standalone implants command premium pricing against embedded catheter components, while delivery modality determines reimbursement tier and hospital procurement priority.
Product Type:
Integration depth separates self-expanding implants from catheter-embedded components, with standalone devices absorbing disproportionate manufacturing margin and regulatory validation burden.
- Stents:Self-expanding vascular scaffolds exploit superelastic recovery after crimped delivery. Cardiovascular catheterization labs in the United States and Germany absorb the majority of peripheral and carotid placements, driven by CMS reimbursement expansion for transcatheter procedures.
- Guidewires:Kink-resistant core wires with superelastic tips navigate tortuous anatomy during endovascular access. Demand clusters in tertiary hospital systems performing complex chronic total occlusion interventions, where wire torque response determines procedural success rates.
- Surgical Instruments:Shape-memory graspers and retractors activate at body temperature for laparoscopic deployment.
- Catheters:Reinforced shafts and steerable tips incorporate nitinol braiding for torque transmission.
Volume placements concentrate in Stents; the faster expansion belongs to Guidewires.
Application:
Cost tier stratification follows procedure reimbursement intensity, with cardiovascular interventions sustaining premium device pricing against commoditized urological applications.
- Cardiovascular:Peripheral arterial disease and carotid revascularization dominate revenue pools. Japanese PMDA nickel ion release requirements extend approval timelines, compressing first-mover advantage windows for new entrants.
- Orthopedics:Bone staples and compression plates leverage thermal shape memory for minimally invasive fracture fixation. German and Austrian trauma centers lead adoption of smart implant systems with programmable activation temperatures.
- Urology:Stone retrieval baskets and stents face pricing pressure from single-use polymer alternatives.
- Gastroenterology:Biliary and esophageal stents serve niche indications with limited addressable populations.
Cardiovascular absorbs the dominant revenue share; Orthopedics is climbing the fastest as ambulatory surgery migration favors same-day fracture fixation.
End User:
Customer type determines procurement leverage, with consolidated hospital networks extracting volume discounts against fragmented clinic purchasing.
- Hospitals:Integrated delivery networks in the United States and NHS trusts in the United Kingdom bundle catheterization lab consumables under multi-year framework agreements. Value-analysis committees now mandate total procedure cost targets rather than line-item device pricing.
- Surgical Centers:Ambulatory facilities in Germany and the United States prioritize same-day discharge compatibility. Nitinol device flexibility enables reduced length-of-stay metrics that satisfy payer quality incentives.
- Clinics:Office-based labs face reimbursement compression for interventional procedures.
- Laboratories:Preclinical testing services consume prototype quantities for biocompatibility validation.
Hospitals dominate absolute volume; Surgical Centers are gaining share fastest as catheterization infrastructure decentralizes.
Delivery Mode:
Maturity gradients separate established minimally invasive platforms from emerging robotic architectures requiring capital equipment partnerships.
- Minimally Invasive:Transcatheter deployment through femoral or radial access represents the incumbent standard. FDA 21 CFR Part 820 quality system regulations govern biocompatibility and fatigue validation protocols for these devices.
- Robotic-Assisted:Magnetic navigation systems enable remote catheter manipulation with nitinol device flexibility. Tertiary US hospital systems pilot telesurgery architectures that extend interventional radiologist reach to underserved regions.
- Open Surgery:Direct implantation persists in orthopedic and emergency trauma settings.
- Intervention:Hybrid operating rooms combine surgical and endovascular capabilities.
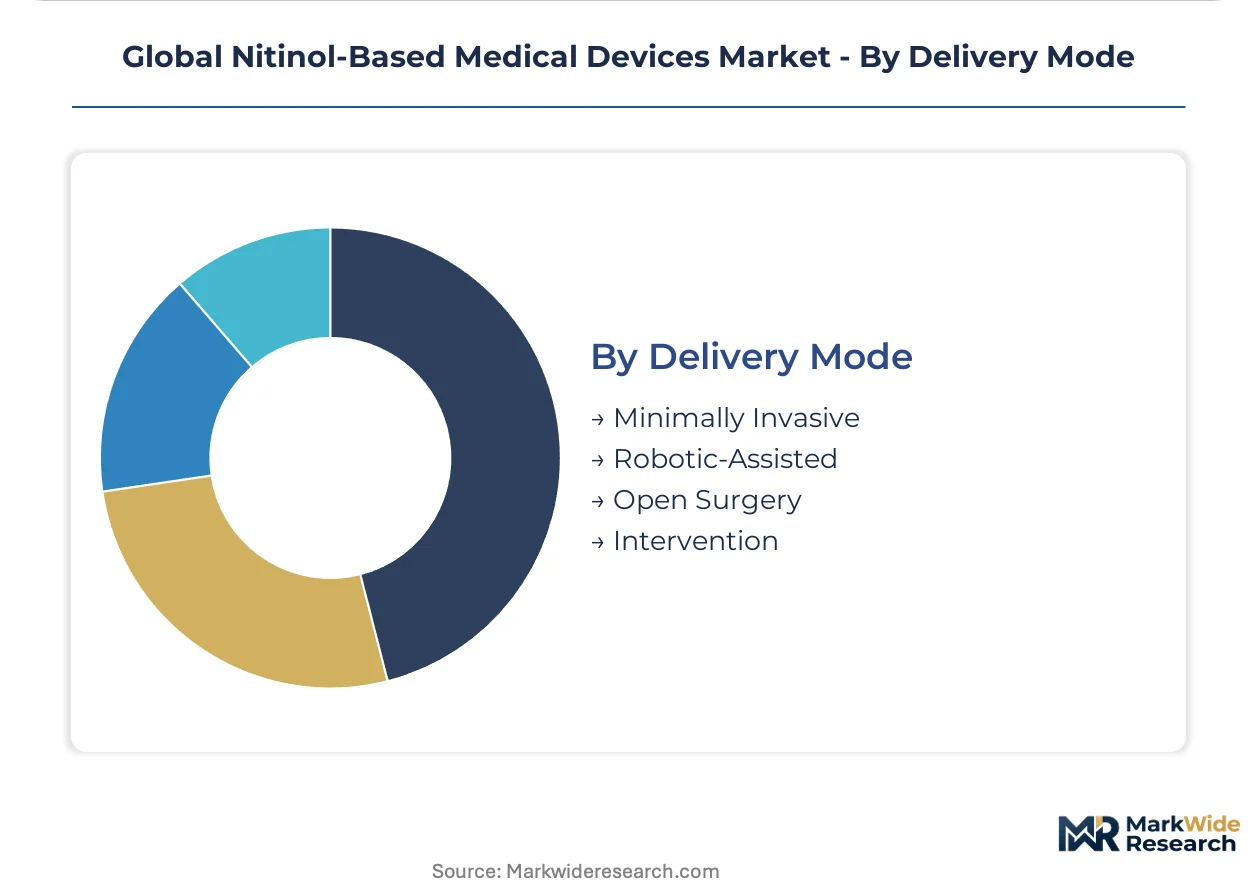
Minimally Invasive retains volume concentration; Robotic-Assisted shows the steepest expansion trajectory as capital equipment costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device free trade zones in Costa Rica and Puerto Rico concentrate nitinol stent finishing operations for US-bound shipments. Singapore's Biopolis hub anchors Asia-Pacific R&D for shape-memory alloys. Ireland's IDA tax incentives attract European distribution headquarters for transcatheter device portfolios.
United States
CMS reimbursement expansion for peripheral arterial disease interventions drives catheterization lab capital budgets toward nitinol stent platforms. FDA 21 CFR Part 820 quality system regulations mandate biocompatibility validation protocols that extend development timelines. Minneapolis-St. Paul hosts Medtronic's vertically integrated superelastic alloy supply chain, while Boston Scientific anchors its European transition teams from Marlborough, Massachusetts.
Germany
University hospital networks in Munich and Heidelberg generate clinical evidence packages for EU MDR conformity assessments. BfArM oversees notified body designation delays that stretch Class III implantable device queue times beyond thirty-six months. Baden-Württemberg's precision engineering clusters supply cold-working equipment for Af temperature control in physiological activation ranges.
Japan
PMDA nickel ion release assessments extend premarket approval timelines twelve to eighteen months beyond FDA pathways for nitinol implants. METI funding for robotic-assisted surgery platforms accelerates magnetic navigation system adoption in Tokyo and Osaka tertiary centers. Kobe's medical device manufacturing zone concentrates guidewire finishing operations for domestic and export markets.
India
Greenfield hospital construction in Mumbai and Delhi creates first-mover positioning for catheterization infrastructure suppliers. CDSCO medical device rules align with ISO 25539-1 structural validation standards for endovascular devices. Tamil Nadu's Sri City special economic zone attracts contract manufacturers for nitinol component machining serving European and US OEMs.
Switzerland
Swissmedic now mandates lot-level vacuum arc remelting records for alloy traceability documentation. Geneva and Zurich hospital procurement committees consolidate vendor relationships under multi-year framework agreements for catheterization lab consumables. The country's precision metallurgy heritage supports niche superelastic wire drawing operations for orthopedic staple applications.
Global Nitinol-Based Medical Devices Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the nitinol device value chain. The market structure concentrates revenue among vertically integrated manufacturers with captive alloy supply, while mid-cap developers rely on outsourced vacuum arc remelting feedstock. Three archetypes dominate: diversified medtech conglomerates with full catheterization lab portfolios, pure-play interventional vascular specialists, and contract manufacturers serving OEM specification. Competitive moves center on M&A for MDR technical documentation assets and strategic partnerships for robotic-assisted deployment platforms.
Among US-based diversified conglomerates, Medtronic plc and Boston Scientific Corporation exemplify the integrated archetype with European MDR transition capabilities. Abbott Laboratories occupies a position bridging cardiovascular and structural heart portfolios. Terumo Corporation represents the Asia-Pacific headquartered specialist tier with guidewire and catheter expertise. These three named entities anchor the competitive landscape without exhausting its structural diversity.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Terumo Corporation |
| Edwards Lifesciences |
| Becton Dickinson and Company |
| W.L. Gore & Associates |
| Cook Medical |
| Stryker Corporation |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap precision metallurgy specialists in Germany and Japan anchor superelastic alloy feedstock production, creating pricing discipline through captive vacuum arc remelting capacity and long-term offtake relationships with catheterization lab OEMs. Their ownership structure resists quarterly margin pressure, sustaining premium pricing for Af-temperature-controlled nitinol wire despite hospital procurement consolidation.
Pricing Analysis
Short lead-time premiums for MDR-compliant technical documentation packages command thirty to fifty percent markups over standard delivery cycles in European markets. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked Class III implants from predicate-device equivalents and unvalidated contract-manufactured components. Pricing pressure stems from NHS trust framework agreements bundling stents with guidewires under total-procedure cost targets. Ambulatory surgical centers exhibit highest price sensitivity; integrated delivery networks with captive GPO contracts demonstrate lowest.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme for medical devices are reshaping sourcing patterns for European and US OEMs seeking tariff-advantaged export platforms. Primary nickel refining concentrates in Indonesia and Russia; superelastic wire drawing clusters in Germany and Japan; catheter finishing operations concentrate in Costa Rica and Puerto Rico. Nitinol feedstock draws from vacuum arc remelted ingots, cold-working dies, and Af-temperature calibration baths. Single-source vulnerability runs through Indonesian nickel export permit cascades. Distribution runs through hospital procurement committees consolidating vendor relationships under multi-year agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
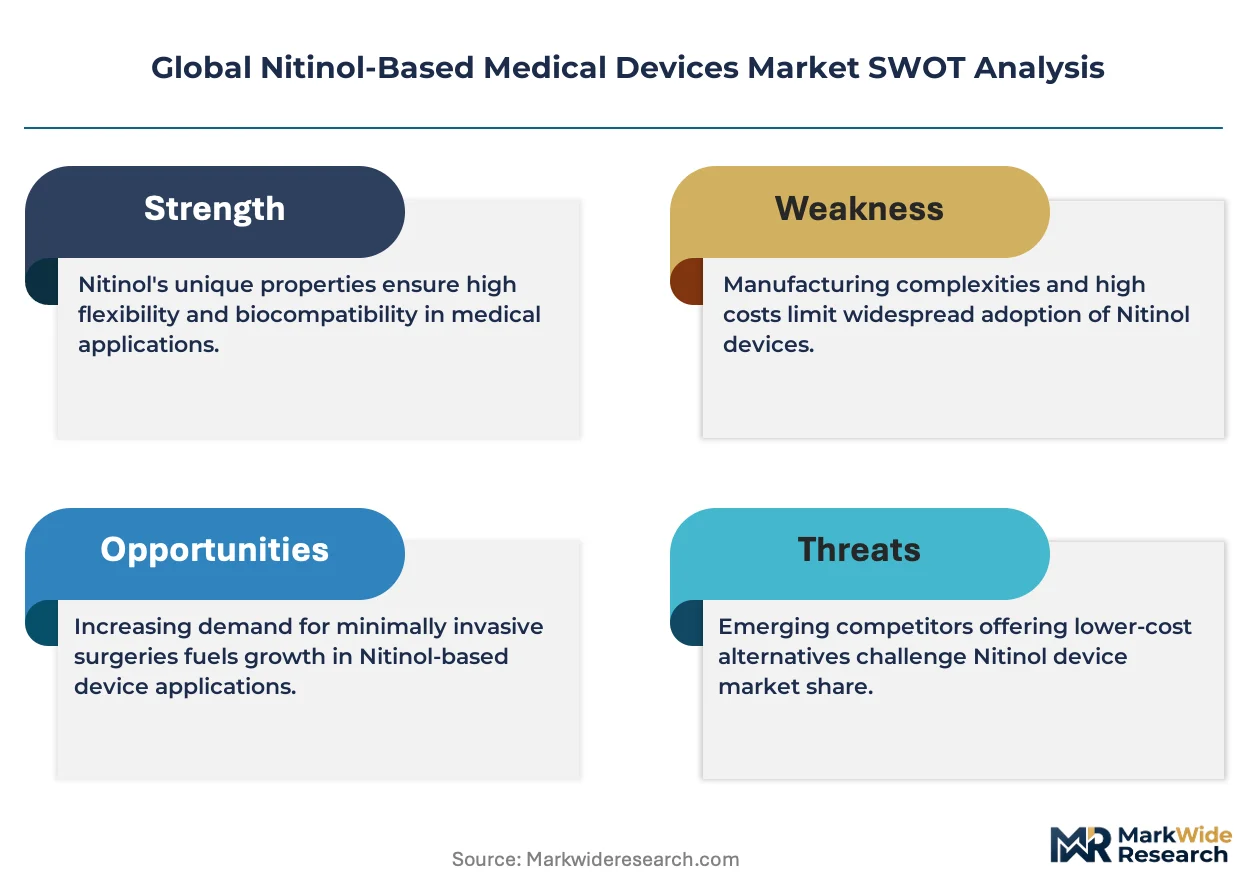
The EU MDR recalibrates cost-of-entry calculus for nitinol device manufacturers, erecting a regulatory moat that rewards players with legacy clinical data and notified body relationships. Certificate expiration deadlines compress competitive windows for non-compliant portfolios.
For Market Incumbents: Anticipate polymer stent substitution threats in coronary applications by accelerating peripheral vascular indications with superior fatigue resistance. Deepen backward integration into vacuum arc remelting capacity to insulate margin structures from Indonesian nickel export volatility. Prioritize MDR technical documentation asset acquisitions to compress notified body queue times for Class III implantable devices.
For New Entrants and Emerging Players: CDSCO alignment with ISO 25539-1 in India opens a window for greenfield catheterization infrastructure suppliers as Mumbai and Delhi hospital construction accelerates. Target ambulatory surgical center compatibility for same-day discharge protocols. Pursue robotic-assisted deployment platform partnerships with magnetic navigation system developers to bypass incumbent catheter lab bundling power.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap device developers with incomplete MDR transition funding in German and French hospital network corridors. Long-term viability hinges on clinical evidence generation capabilities and notified body relationship depth. Watch PMDA nickel ion release assessment timelines as inflection indicator for Japan market access competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Remediation | Notified body re-certification services capture parallel revenue streams alongside hardware sales in EU markets. |
| Hospital System Partnership | Framework agreements with NHS trusts and US integrated delivery networks lock in multi-year catheterization lab consumable volumes. |
| Backward Integration into Alloy Supply | Captive vacuum arc remelting capacity insulates margin structures from Indonesian nickel export restrictions. |
| Robotic-Assisted Deployment Platform | Magnetic navigation convergence enables telesurgery architectures extending interventional radiologist reach. |
| Reimbursement Strategy | CMS coverage determination alignment for transcatheter procedures directly enlarges addressable patient populations. |
Study Parameters
Document review covered FDA 510(k) filings, EU MDR technical documentation databases, and CMS national coverage determinations, complemented by interviews with catheterization lab directors, biomedical engineers, hospital GPO contracts managers, and nitinol alloy procurement leads. Secondary validation drew from notified body designation records, ISO 25539-1 structural validation standards, and PMDA premarket approval timelines. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing.
Cross-referencing historical reimbursement expansion patterns against clinician panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product integration depth, application reimbursement intensity, end-user procurement leverage, and delivery modality maturity. CAGRs derived from procedure volume elasticity to CMS coverage determinations and EU MDR certificate expiration cascades. Forecast inputs incorporated nickel price volatility indices and notified body queue time projections.
The model assumes a particular technology adoption path for robotic-assisted deployment; alternative pathways for magnetic navigation system integration would alter the outlook for telesurgery penetration. Forecasts reflect assumptions regarding MDR transition completion rates and CMS reimbursement expansion continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Pericardiocentesis Procedures Market
Cardiovascular Devices
Serration Balloon Catheters Market
Cardiovascular Devices
Cardiac Implantable Electronic Device Market
Cardiovascular Devices
Implantable Infusion Pumps Market
Cardiovascular Devices
Wearable Artificial Organs Market
Cardiovascular Devices
Extracorporeal Membrane Oxygenation (ECMO) Market
Cardiovascular Devices
Cardiovascular Devices Market
Cardiovascular Devices
Surgical Heart Valves Market
Cardiovascular Devices
Cardiac Ablation Market
Cardiovascular Devices
Cardiac Mapping Systems Market
Cardiovascular Devices
Global Artificial Heart Market
Cardiovascular Devices
Netherlands Cardiovascular Devices Market
Cardiovascular Devices
Renovascular Hypertension Treatment Market
Cardiovascular Devices
Europe Cardiac Assist Devices Market
Cardiovascular Devices
Stent Grafts Market
Cardiovascular Devices
Global Resuscitation Devices Market