
 Serration Balloon Catheters Market | 2026-2036
Serration Balloon Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Serration Balloon Catheters Market Analytics
Interventional cardiology fellowship training capacity is rotating toward structural heart and peripheral vascular procedures, expanding the clinician pool capable of deploying serration balloon systems. Boston Scientific leverages its endovascular portfolio breadth to sustain catheter lab presence across multiple continents. Abbott anchors its competitive stance through integrated imaging-to-intervention workflows that complement balloon delivery. Cagent Vascular specializes in serration-specific engineering, occupying a narrow but defensible technology niche.
Serration balloon catheters incorporate circumferential micro-cutting elements on compliant or semi-compliant balloon surfaces, typically manufactured from nylon or polyurethane, designed to score calcified plaque while dilating stenotic vessels during percutaneous intervention. Drug-coated balloon variants command premium positioning due to antiproliferative agent delivery that reduces restenosis in femoropopliteal and below-the-knee applications. Catheterization labs represent the highest-throughput end user channel where procedure bundling and capital equipment lock-in concentrate purchasing power. Peripheral interventions outpace vascular intervention growth as diabetes prevalence and limb salvage protocols expand treatable patient populations.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and sterilization validation burdens for manufacturers seeking dual-market access. Japan's PMDA imposes additional clinical bridging study expectations that filter market entrants and privilege established players with local regulatory infrastructure. Stakeholders must monitor evolving CMS outpatient procedure reimbursement designations and EU IVDR companion diagnostic intersections that could reshape commercial deployment economics.
Market Dynamics
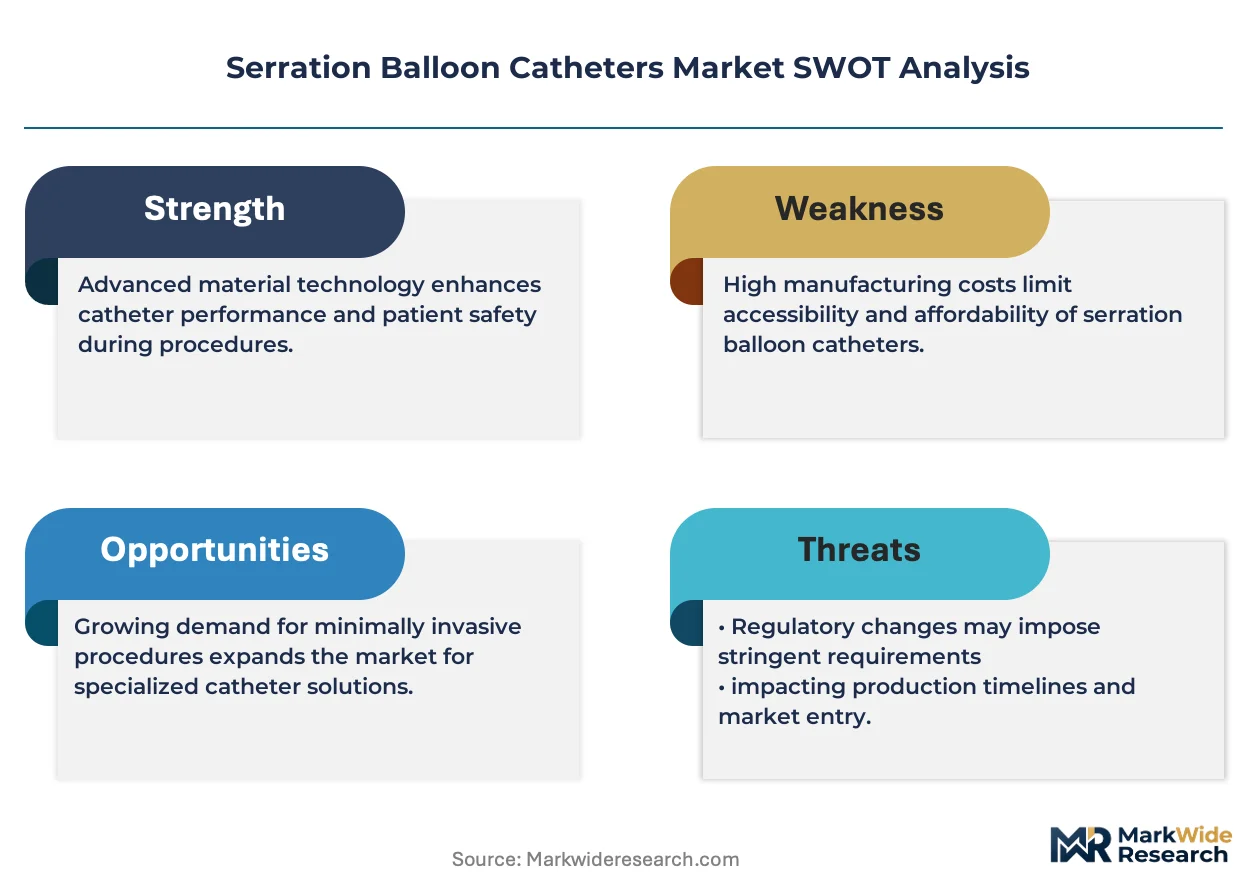
Calcified lesion complexity in peripheral arterial disease is forcing catheterization labs to upgrade from conventional balloon angioplasty to serration-based plaque modification, restructuring capital allocation and training priorities across interventional cardiology departments.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited premarket notification reviews for predicate device modifications accelerate product iteration cycles, enabling faster commercialization of next-generation scoring element geometries.
- Catheterization lab procedure bundling:Reimbursement consolidation around comprehensive care episodes concentrates purchasing authority toward integrated device vendors capable of supplying full lesion preparation workflows.
- Polyurethane-nylon composite balloon materials:Advanced polymer formulations deliver superior compliance profiles and scoring element adhesion, expanding treatable lesion morphologies in heavily calcified femoropopliteal segments.
Market Restraints
- Nitinol scoring element supply concentration:Precision laser-cutting capacity for micro-serrated crowns clusters among specialized contract manufacturers in Switzerland and Germany, creating single-source vulnerability.
- EU MDR technical documentation burden:Enhanced clinical evidence requirements for Class III device conformity assessments extend certification timelines and inflate regulatory affairs headcount costs.
- Atherectomy system substitution:Orbital and rotational plaque debulking technologies compete for the same calcified lesion indications, particularly in above-the-knee interventions where vessel diameter accommodates larger device profiles.
Strategic Opportunities
- Below-the-knee arterial expansion:Critical limb ischemia protocols in Japan and Germany are expanding reimbursement for infrapopliteal interventions, opening addressable patient populations previously managed conservatively.
- Drug-coated serration convergence:Integration of paclitaxel or sirolimus matrices onto scored balloon surfaces combines mechanical plaque modification with antiproliferative pharmacotherapy.
- Ambulatory surgical center migration:Outpatient procedural site expansion in the United States creates demand for simplified device systems compatible with lower-acuity settings and reduced support staff.
Industry Challenges
- Interventionalist training bandwidth:Fellowship programs face compressed curricula for structural heart and peripheral vascular skills, limiting proficient serration balloon operators.
- Sterilization validation complexity:Ethylene oxide residual limits and alternative sterilization method qualification for scoring element adhesives extend manufacturing release timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Serration Balloon Catheters Market |
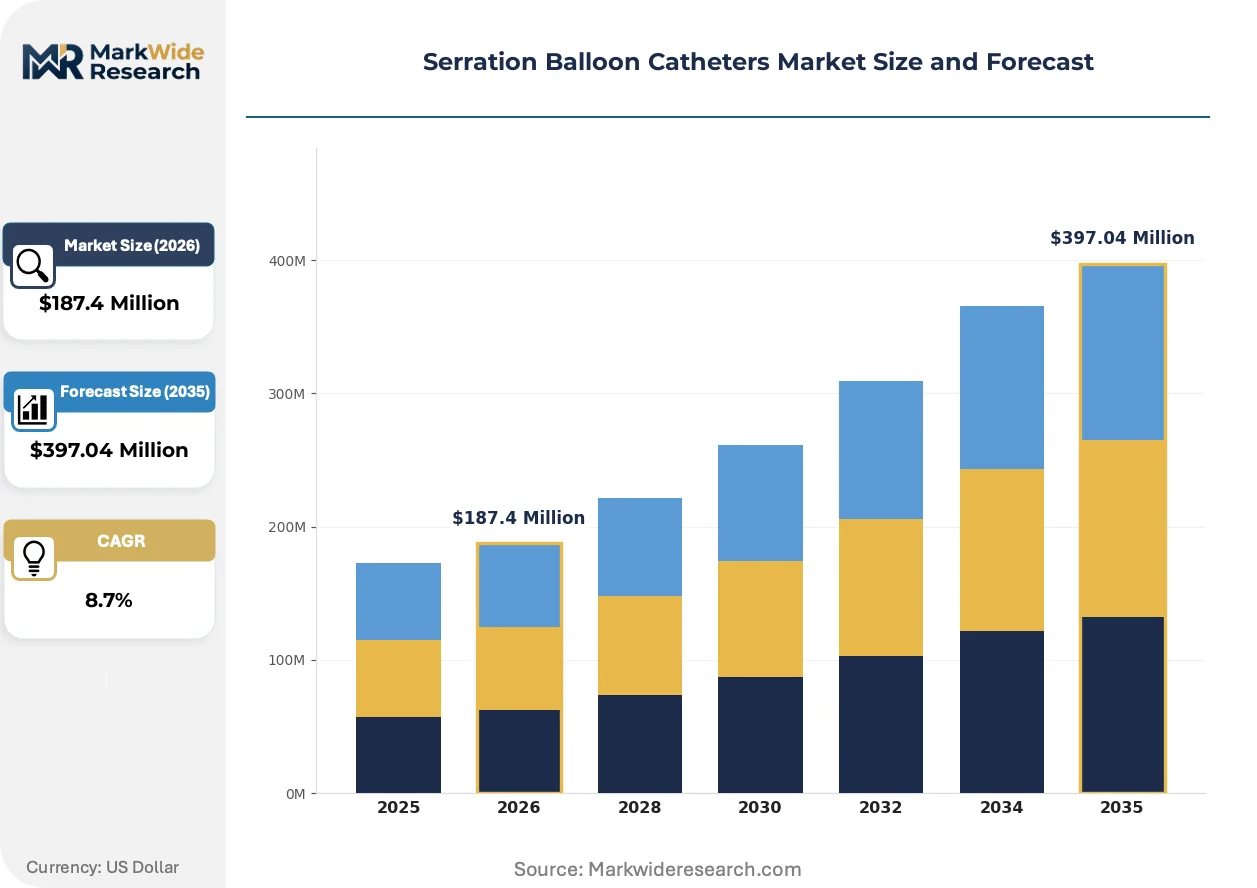
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
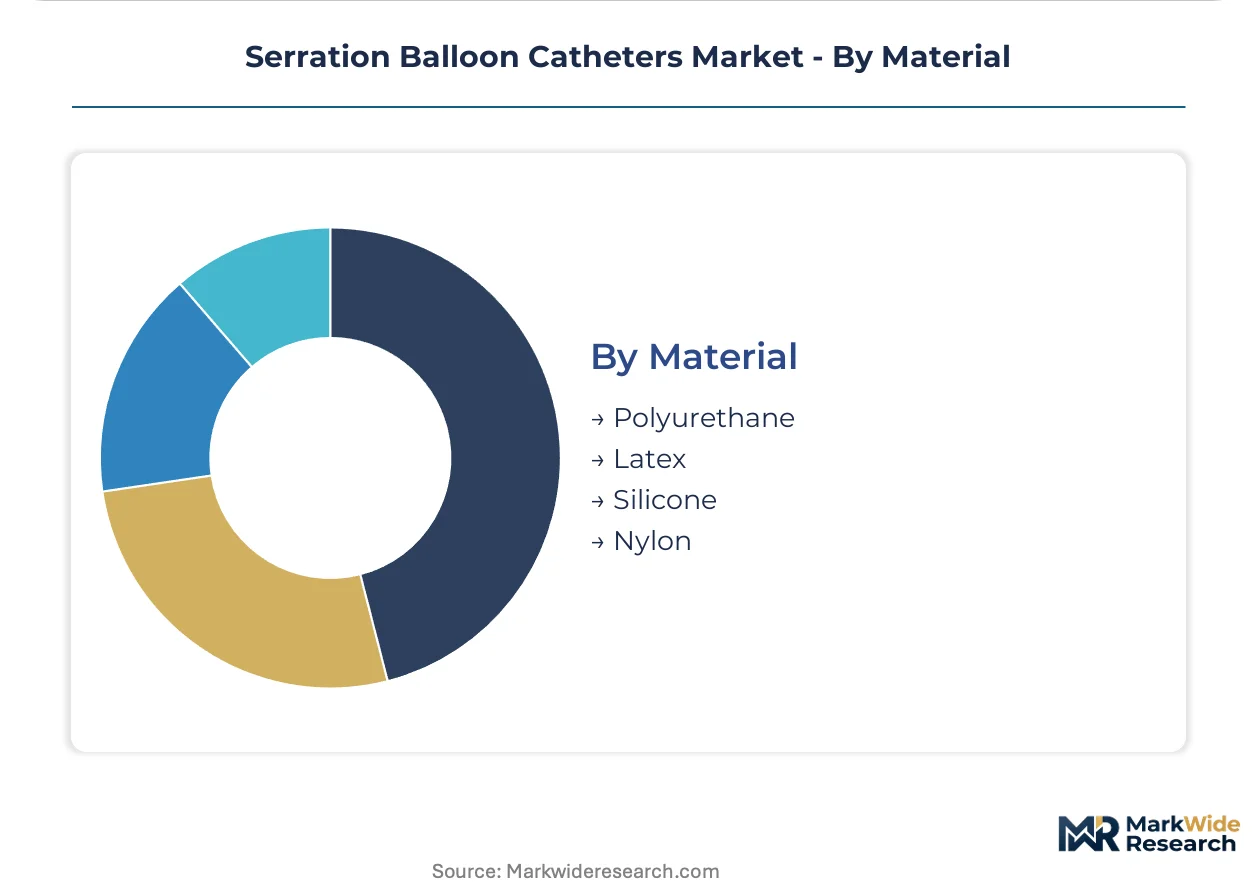
| Segmentation | Product Type: Drug-Coated, Non-Coated, Inflation Device, Guidewire End User: Hospitals, Outpatient Clinics, Specialty Clinics, Catheterization Labs Application: Vascular Interventions, Urological Procedures, Gastroenterology, Peripheral Interventions Material: Polyurethane, Latex, Silicone, Nylon |
| Companies Covered | Terumo, Cardinal Health, Boston Scientific, Cagent Vascular, C. R. Bard, Abbott, Intact Vascular, Covidien, Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Serration Balloon Catheters Market Evolving Landscape
Active catheter engineering is converging with imaging integration and local drug delivery, transforming serration balloons from mechanical tools into multi-modal therapeutic platforms that reshape procedural economics.
Semicompliant balloon designs with circumferential micro-serration patterns are displacing conventional high-pressure non-compliant systems in moderate-to-severe calcification cases. Interventional cardiologists in high-volume United States catheterization labs are adopting these platforms for superficial femoral artery interventions at accelerating rates. The shift is compressing market space for standalone angioplasty balloons while elevating scoring capability to a baseline expectation.
EU MDR recertification deadlines for legacy device approvals are compressing manufacturer compliance timelines and forcing portfolio rationalization decisions. Technical documentation gaps for predicate device equivalency arguments are triggering clinical study requirements that previously submitted under MDD avoided. Peripheral intervention portfolios with concentrated EU revenue exposure face the most severe resource reallocation pressures.
Hospital procurement committees are consolidating vendor relationships around full-line interventional suppliers capable of bundling serration balloons with guidewires, microcatheters, and closure devices. Catheterization lab directors in Germany and Japan are negotiating multi-year supply agreements that lock in device standardization across operator preferences. This concentration is marginalizing single-product entrants and elevating scale-based negotiation leverage.
Serration Balloon Catheters Market Segmentation

Serration balloon catheter purchasing decisions split across clinical setting, lesion morphology, and reimbursement pathway. Material selection and coating technology determine regulatory classification and sterilization validation burden for manufacturers.
Product Type:
FDA 510(k) predicate pathways and EU MDR clinical evidence requirements create divergent approval timelines across coating categories.
- Drug-Coated:Paclitaxel or sirolimus matrices integrated onto scored balloon surfaces deliver antiproliferative pharmacotherapy during mechanical plaque modification. Catheterization labs in Germany and Japan concentrate demand for these premium variants where limb salvage protocols justify higher procedural reimbursement.
- Non-Coated:Bare serration balloons rely solely on circumferential micro-cutting elements for calcified lesion preparation. Outpatient clinics in the United States favor these systems for cost-sensitive superficial femoral artery interventions where procedure bundling compresses device margins.
- Inflation Device:Precision pressure delivery systems engineered for controlled scoring element deployment against calcified vessel walls.
- Guidewire:Dedicated workhorse and support wires designed for serration balloon trackability through tortuous peripheral anatomy.
Established volume favors Non-Coated; emerging adoption favors Drug-Coated.
End User:
Capital equipment lock-in and procedure bundling reshape purchasing authority across acute and ambulatory settings.
- Catheterization Labs:High-throughput interventional cardiology suites generate concentrated procedural volume for femoropopliteal and below-the-knee interventions. Boston Scientific and Abbott leverage integrated portfolio breadth to secure multi-year supply agreements with lab directors in the United States.
- Hospitals:Academic medical centers with hybrid operating rooms accommodate complex calcified lesion cases requiring combined atherectomy and serration strategies. Japan's PMDA clinical bridging requirements privilege established vendors with local regulatory infrastructure.
- Outpatient Clinics:Lower-acuity settings demand simplified device systems compatible with reduced support staff and faster turnover.
- Specialty Clinics:Peripheral vascular-focused practices concentrate expertise in limb salvage protocols and critical limb ischemia management.
Procedure economics concentrate purchasing power at Catheterization Labs; site-of-service migration expands Outpatient Clinics.
Application:
Lesion complexity and diabetes prevalence redirect clinical training and device development priorities.
- Peripheral Interventions:Femoropopliteal and infrapopliteal arterial disease drives the steepest expansion trajectory as diabetes prevalence expands treatable patient populations. Germany's reimbursement clarity for below-the-knee procedures accelerates adoption of drug-coated serration platforms in critical limb ischemia protocols.
- Vascular Interventions:Above-the-knee and aortoiliac segments compete with orbital atherectomy systems for calcified plaque modification.
- Urological Procedures:Benign prostatic hyperplasia and ureteral stricture applications utilize scoring balloon technology for precise tissue incision.
- Gastroenterology:Biliary and pancreatic duct strictures represent niche indications with specialized device sizing requirements.
Peripheral Interventions command development resources; Vascular Interventions face substitution pressure from debulking alternatives.
Material:
Polymer compliance profiles and scoring element adhesion properties determine treatable lesion morphologies.
- Polyurethane:Advanced elastomer formulations deliver superior compliance control and micro-serration crown retention under high-pressure inflation cycles. Specialty contract manufacturers in Switzerland and Germany concentrate precision laser-cutting capacity for these composite structures.
- Nylon:Semi-compliant balloon substrates balance puncture resistance with scoring element integration for moderate calcification cases.
- Silicone:Biocompatible elastomer options selected for specific drug-matrix compatibility in coated variants.
- Latex:Legacy material presence in certain regional markets with established sterilization validation pathways.
Polyurethane anchors premium positioning; Nylon sustains volume through cost-optimized configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Catheterization labs in the United States deploy serration balloon systems at higher procedural density than peer markets, while Japan and Germany concentrate adoption in below-the-knee limb salvage protocols. Reimbursement pathway maturity and regulatory infrastructure quality create sharp performance divergences across national markets.
United States
Outpatient procedure site migration and CMS bundled payment expansion concentrate purchasing authority toward integrated device vendors. FDA 510(k) pathway streamlining accelerates predicate-based product iterations for scoring element geometries. Minneapolis and Boston anchor the highest-throughput catheterization lab networks where procedure economics favor premium platform adoption.
Germany
Critical limb ischemia protocols and statutory health fund reimbursement clarity drive drug-coated serration platform penetration in infrapopliteal segments. EU MDR technical documentation requirements extend certification timelines for Class III device conformity assessments. Baden-Württemberg and Bavaria host precision laser-cutting contract manufacturers supplying micro-serrated crown components.
Japan
Aging demographics and diabetes prevalence expand treatable patient populations for peripheral arterial disease interventions. PMDA clinical bridging study expectations filter market entrants and privilege established players with local regulatory infrastructure. Tokyo and Osaka medical centers concentrate fellowship training capacity for structural heart and peripheral vascular procedures.
Switzerland
Precision manufacturing heritage supports specialized contract production of nitinol scoring elements for global catheter OEMs. Swissmedic conformity assessment procedures align with EU MDR benchmarks while maintaining distinct technical documentation protocols. Zurich and Basel clusters concentrate laser micromachining capacity for micro-serrated crown fabrication.
United Kingdom
NHS procurement consolidation shifts purchasing authority toward full-line interventional suppliers capable of bundling serration balloons with complementary devices. MHRA post-Brexit regulatory divergence from EU MDR creates parallel certification pathways for market access. London and Manchester academic medical centers accommodate complex calcified lesion cases requiring combined therapeutic strategies.
Serration Balloon Catheters Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with portfolio breadth determining catheterization lab contract security. The upper tier secures multi-year supply agreements through guidewire-to-closure device bundling, while specialists defend position through serration-specific engineering depth. Three archetypes dominate: diversified medtech conglomerates with endovascular portfolio breadth, focused vascular intervention specialists, and precision component contract manufacturers. Competitive moves concentrate on regulatory infrastructure scaling for EU MDR compliance and sterilization validation capacity expansion.
Within the integrated tier, Boston Scientific and Abbott exemplify full-line positioning through catheter lab presence across multiple continents. Cagent Vascular occupies the specialist archetype, anchoring narrow but defensible technology positioning in serration-specific engineering. Terumo represents Japanese-origin diversified players with established PMDA regulatory infrastructure and Asia-Pacific distribution density.
| Leading Market Players |
|---|
| Terumo |
| Cardinal Health |
| Boston Scientific |
| Cagent Vascular |
| C. R. Bard |
| Abbott |
| Intact Vascular |
| Covidien |
| Cook Medical |
| Others |
Value Network & Pricing Analysis
FDA 510(k) clearance pathways and EU MDR Class III device classifications simultaneously gate supplier qualification and stratify price positioning across serration balloon catheter tiers. Manufacturers carrying dual-market regulatory infrastructure command premium contract terms, while single-territory entrants compete on narrower margins in cost-sensitive outpatient channels.
Pricing Analysis
Long-term supply agreements dominate catheterization lab procurement, with multi-year offtake contracts locking in device standardization across operator preferences. Price differentiation separates drug-coated premium platforms from bare serration systems, with reimbursement clarity in Germany and Japan amplifying tier separation. Cost compression in non-coated segments intensifies as outpatient clinic migration demands simplified, lower-support configurations. Outpatient clinics exhibit highest price sensitivity; academic medical centers with hybrid operating rooms demonstrate lowest.
Supply Chain Analysis
Switzerland and Germany anchor precision laser-cutting capacity for nitinol micro-serrated crowns, with Zurich and Basel clusters feeding global catheter OEMs. Balloon substrate production draws from polyurethane and nylon polymer specialists in the United States and Germany, while sterilization validation services concentrate among ethylene oxide contract facilities. Single-source vulnerability in nitinol scoring element fabrication creates supply chain risk. Distribution runs through hospital procurement committees and GPO contract frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Catheter lab platform economics are shifting toward integrated imaging-to-intervention workflows, with interoperability between serration delivery systems and intravascular ultrasound reshaping vendor lock-in dynamics.
For Market Incumbents: Compound catheter lab presence through guidewire-to-closure device bundling that secures multi-year supply agreements against atherectomy system substitution threats. Deepen backward integration into nitinol laser-cutting capacity to reduce Swiss and German contract manufacturer dependency. Prioritize sterilization validation infrastructure expansion to compress EU MDR compliance timelines. For New Entrants and Emerging Players: FDA 510(k) predicate pathway streamlining offers accelerated market access for scoring element geometry innovations. Target below-the-knee arterial expansion in Japan and Germany where critical limb ischemia protocols are expanding reimbursable indications. Pursue ambulatory surgical center compatibility as a differentiated go-to-market angle against capital-equipment-heavy incumbents. For Investors and Strategic Acquirers: EU MDR recertification deadlines reshape the acquisition landscape toward targets with completed technical documentation and sterilization validation infrastructure. Five-to-ten year viability favors serration-specific engineering specialists with defensible IP positions over diversified commodity balloon manufacturers. Monitor PMDA clinical bridging study completion rates as an inflection indicator for Asia-Pacific market access trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Completion | Class III device conformity assessments determine market access timelines across European catheterization labs. |
| Drug-Coated Serration Platform Development | Paclitaxel matrix integration combines mechanical plaque modification with antiproliferative pharmacotherapy delivery. |
| Catheterization Lab Supply Agreement Expansion | Multi-year contracts with Minneapolis and Boston hospital networks lock in procedure bundling economics. |
| Ambulatory Surgical Center Compatibility Engineering | Simplified device systems capture outpatient migration from hospital-based catheterization labs. |
| Nitinol Scoring Element Laser-Cutting Acquisition | Upstream control over Swiss and German precision manufacturing reduces single-source supply vulnerability. |
Research Methodology
A standing panel of interventional cardiologists, catheterization lab directors, hospital procurement committee members, and biomedical engineers provided ongoing calibration against secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, CMS outpatient procedure reimbursement designations, and hospital GPO contract records. Bottom-up procedural volume estimates triangulated with top-down device shipment analysis.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation modeling incorporated product type, end user channel, application morphology, and material compliance dimensions. CAGRs were derived from fitted growth curves applied to procedure expansion trajectories and device replacement cycles, with diabetes prevalence and limb salvage protocol adoption as specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside reimbursement clarity maintenance, regulatory pathway stability, or sterilization validation capacity expansion would require recalibration. Forecasts reflect documented assumptions regarding procedural site migration rates and EU MDR implementation timelines. Recalibration cycles align with material shifts in CMS bundled payment designations and PMDA clinical evidence requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiac Ablation Technologies Market
Cardiovascular Devices
Cardiac Mapping Systems Market
Cardiovascular Devices
Argentina Cardiovascular Devices Market
Cardiovascular Devices
Global Cardiac Resynchronization Therapy Market
Cardiovascular Devices
North America Interventional Cardiology and Peripheral Vascular Devices Market
Cardiovascular Devices
Global Peripheral Stent Market
Cardiovascular Devices
Umbilical Vessel Catheters Market
Cardiovascular Devices
Renovascular Hypertension Treatment Market
Cardiovascular Devices
Global Advanced Balloon Catheter Market
Cardiovascular Devices
Pulmonary Artery Catheter Market
Cardiovascular Devices
Intravascular Stents Market
Cardiovascular Devices
Hypertension Management Devices Market
Cardiovascular Devices
Wearable Artificial Organs Market
Cardiovascular Devices
Global Heart Valve Repair and Replacement Market
Cardiovascular Devices
Global Drug Eluting Balloon Catheters Market
Cardiovascular Devices
Heart Valves Market