
 Cardiovascular Stents Market | 2026-2036
Cardiovascular Stents Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiovascular Stents Market Intelligence
Post-procedural patient monitoring software is decoupling the one-time device sale from long-term patient management value. Medtronic leverages its extensive device portfolio to integrate these digital health solutions across its cardiology offerings. Boston Scientific Corporation competes on the basis of robust clinical data supporting its drug-eluting stent technologies. Abbott differentiates through its pioneering work in bioresorbable vascular scaffold innovations, aiming to improve long-term vessel health.
A cardiovascular stent is a small, expandable mesh tube used to treat narrowed or blocked coronary and peripheral arteries. Often fabricated from materials like cobalt-chromium alloy, these devices are implanted during a percutaneous coronary intervention to restore blood flow. Drug-eluting stents command the largest market share due to their efficacy in preventing restenosis. The bioresorbable stents segment, however, represents the fastest-growing category, driven by clinical interest in leaving no permanent implant behind.
Market access is governed by stringent regulatory approvals, including the FDA's Premarket Approval (PMA) process in the United States and the CE marking under the Medical Device Regulation (MDR) in Europe. China's NMPA similarly imposes rigorous clinical trial requirements, influencing global launch sequencing and R&D timelines. Navigating these diverse and evolving regulatory landscapes remains a central strategic challenge for all device manufacturers.
Market Dynamics
The market's evolution is defined by the tension between rapid material science advancements, such as bioresorbable polymers, and the protracted, complex regulatory pathways across major markets like the US, Europe, and China, which govern market access.
Growth Catalysts
- Bioresorbable Stents:The development of fully absorbable scaffolds addresses clinical demand for treating coronary artery disease without leaving a permanent implant, improving long-term vessel health and vasomotion.
- Healthcare Modernization in China:Rapid expansion of interventional cardiology capabilities and healthcare infrastructure in China, supported by government initiatives, creates a concentrated zone of high-volume demand for advanced coronary and peripheral stents.
- Specialty Hospital Adoption:The increasing procedural complexity of percutaneous coronary interventions drives uptake in specialty hospitals, which possess the advanced imaging and surgical suites required for complex stenting cases in high-risk patient populations.
Market Restraints
- Stringent Regulatory Pathways:The lengthy and costly Premarket Approval (PMA) process by the FDA and rigorous data requirements under Europe's Medical Device Regulation (MDR) create significant barriers to entry and delay product launches.
- Risk of Restenosis and Thrombosis:Despite the efficacy of drug-eluting stents, the persistent clinical risk of in-stent restenosis and late stent thrombosis necessitates long-term antiplatelet therapy, posing patient compliance challenges.
- High Input Material Costs:Reliance on specialized materials like cobalt-chromium and platinum-chromium alloys for stent fabrication results in a high-cost manufacturing base, limiting pricing flexibility in reimbursement-sensitive healthcare systems.
Strategic Opportunities
- Digital Health Integration:Integrating stents with post-procedural patient monitoring software offers a new value stream, shifting from a single device sale to long-term management and data-driven care models.
- Latin American Market Expansion:Expanding access to interventional cardiology in major Latin American economies represents a significant growth opportunity as healthcare systems improve and the prevalence of cardiovascular disease rises.
- Peripheral Artery Disease Applications:Developing stents engineered for the unique anatomical and biomechanical challenges of peripheral arteries, such as in the legs, opens a large and underserved patient population beyond coronary applications.
Industry Challenges
- MDR Transition Complexity:Navigating the transition to the European Union's Medical Device Regulation (MDR) requires extensive updates to technical documentation and clinical evidence for legacy products, consuming significant resources.
- Complex Intellectual Property Landscape:The dense web of patents covering drug coatings, polymer technologies, and stent platform designs creates significant freedom-to-operate challenges and risks of costly litigation for all market participants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiovascular Stents Market |
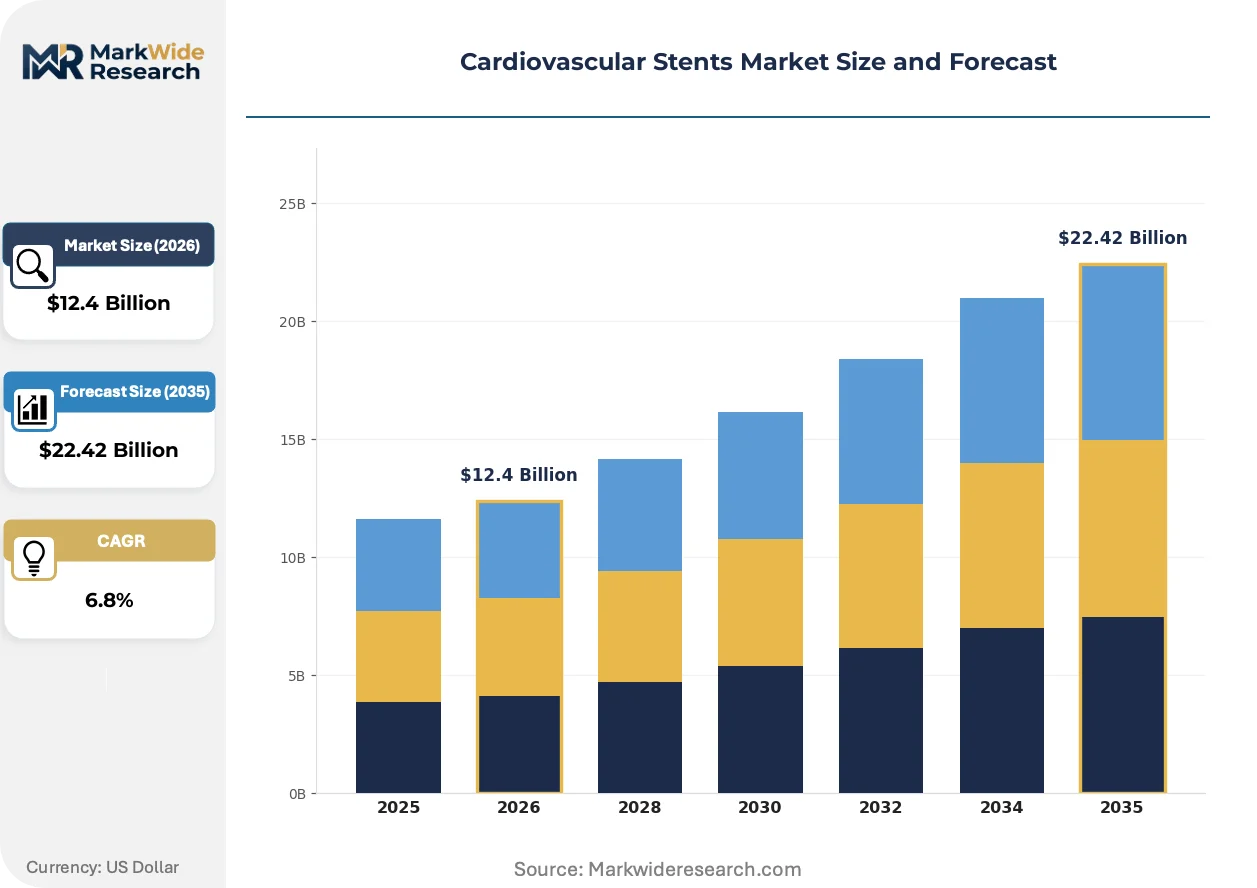
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drug-Eluting Stents, Bare-Metal Stents, Bioresorbable Stents, Covered Stents, Dual Therapy Stents Material: Cobalt-Chromium Alloy, Stainless Steel, Platinum-Chromium Alloy, Polymer-Based, Magnesium Alloy Application: Percutaneous Coronary Intervention, Peripheral Artery Disease, Carotid Artery Disease, Dialysis Access, Venous Stenosis End User: Cardiology Clinics, Vascular Surgery Centers, Specialty Hospitals, Ambulatory Care Centers, Interventional Radiology Units |
| Companies Covered | Abbott, Medtronic, Boston Scientific Corporation, Biotronik SE & Co. KG, Terumo Corporation, B. Braun Melsungen AG, MicroPort Scientific Corporation, C. R. Bard, Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiovascular Stents Market Strategic Shifts & Innovations
The cardiovascular stent is transforming from a passive mechanical scaffold into an active therapeutic delivery platform. This evolution is driven by material science breakthroughs and digital health integration, altering long-term patient care pathways and clinical outcomes.
Bioresorbable vascular scaffolds (BVS) are temporary implants designed to restore blood flow and then dissolve completely over time. Interventional cardiologists are adopting this technology for younger patients or simpler lesions where leaving a permanent metal implant is undesirable. The BVS concept is absorbing the long-term risk and complication profile associated with permanent metallic stents, aiming for a "leave nothing behind" therapeutic endpoint.
China's National Medical Products Administration (NMPA) is implementing localized clinical trial requirements for high-risk medical devices. This policy forces manufacturers to conduct specific studies on the Chinese population before gaining market approval, rather than relying solely on global data. The drug-eluting and bioresorbable stent segments are most affected, as companies must now factor these country-specific trials into their global R&D strategies.
A shift towards value-based healthcare is unbundling the one-time device purchase from the continuous value of patient management. This disrupts the traditional sales model, as hospitals now evaluate the total cost of care, including post-procedural monitoring and reduced re-intervention rates. This behavioral change is most visible in integrated health networks in the United States, which leverage purchasing power to demand new contracting models.
Cardiovascular Stents Market Segmentation
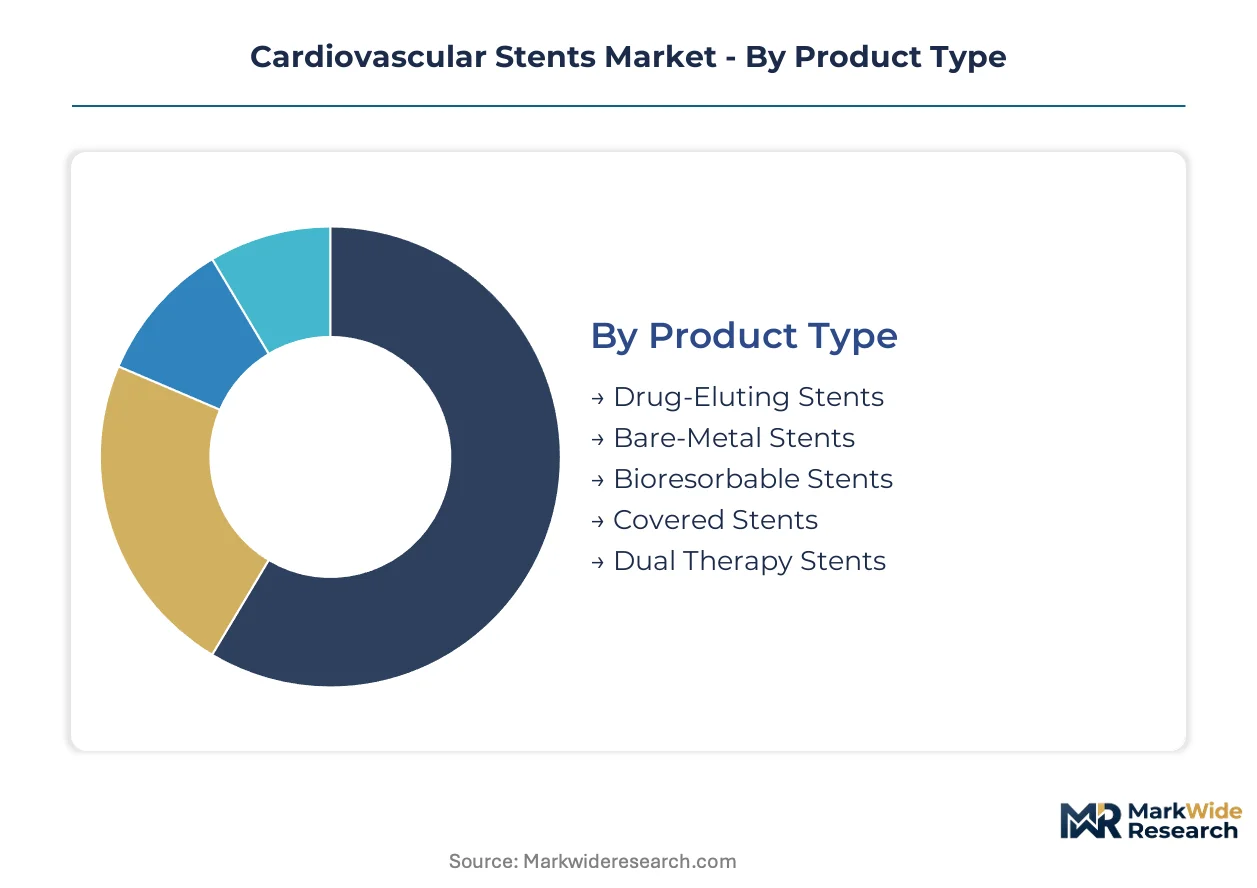
Understanding the segmentation within the cardiovascular stents market is essential for discerning the varied technological preferences and clinical demands across different healthcare settings. This detailed breakdown reveals how product innovations, material science, and specific applications shape market dynamics and end-user adoption patterns.
Product Type:
The product type segmentation highlights the strategic balance between high-volume, established technologies and innovative, premium solutions in the cardiovascular stents market.
- Drug-Eluting Stents:These devices feature a metallic scaffold coated with antiproliferative drugs designed to prevent in-stent restenosis. Demand dominates in China and Europe due to proven efficacy in reducing re-interventions and improving long-term patient outcomes.
- Bioresorbable Stents:Composed of biodegradable polymers or metals, these temporary implants restore blood flow and then dissolve completely over time, leaving no permanent foreign material. Demand is gaining traction in specialty hospitals for younger patients seeking an implant-free solution, particularly in the United States.
- Bare-Metal Stents:Uncoated metallic tubes provide mechanical support to open narrowed arteries, often used in simpler lesions or when drug-eluting stents are contraindicated.
- Covered Stents:These stents incorporate an impermeable membrane to seal perforations, treat aneurysms, or manage fistulas within the vascular system.
- Dual Therapy Stents:These devices combine drug elution with a pro-healing surface designed to promote rapid endothelialization and reduce thrombotic events.
Today's leader: Drug-Eluting Stents. Tomorrow's challenger: Bioresorbable Stents.
Material:
Material choices for cardiovascular stents reflect a spectrum from cost-effective options to advanced, high-performance alloys, influencing device functionality and clinical outcomes.
- Cobalt-Chromium Alloy:This alloy offers high radial strength, excellent radiopacity, and allows for thinner strut designs, enhancing deliverability and reducing vessel injury. Demand is widespread in US and German interventional cardiology due to superior mechanical properties and biocompatibility.
- Polymer-Based:Utilized primarily for bioresorbable scaffolds, these materials offer biocompatibility and controlled degradation profiles without leaving a permanent metallic implant. Demand is concentrated in R&D and early clinical adoption, particularly for next-generation devices in Japan and South Korea.
- Stainless Steel:A traditional material known for its biocompatibility, established manufacturing processes, and cost-effectiveness in stent fabrication.
- Platinum-Chromium Alloy:This material provides enhanced radiopacity and improved deliverability, particularly beneficial in complex anatomies and calcified lesions.
- Magnesium Alloy:Explored for its bioresorbable properties, this material offers a metallic alternative to polymer-based designs, with potential for faster degradation.
Established materials like Cobalt-Chromium alloy continue to evolve, while Polymer-Based and Magnesium Alloy represent the next wave of innovation.
Application:
The application landscape for cardiovascular stents is dominated by high-volume coronary interventions, with growing segments addressing other vascular territories like peripheral arteries.
- Percutaneous Coronary Intervention:This application involves placing stents in narrowed or blocked coronary arteries to restore adequate blood flow to the heart muscle. Demand represents the largest segment globally, driven by the high prevalence of coronary artery disease in countries like India and Brazil.
- Peripheral Artery Disease:This segment addresses blockages in arteries outside the heart, primarily in the legs, arms, and kidneys, using specialized stents. Demand is experiencing rapid expansion in Latin American markets as diagnostic capabilities and treatment access improve.
- Carotid Artery Disease:Focuses on stenting the carotid arteries in the neck to prevent strokes by treating significant narrowing or blockages.
- Dialysis Access:Utilizes stents to maintain the patency of vascular access sites, such as arteriovenous fistulas or grafts, for hemodialysis patients.
- Venous Stenosis:Employs stents to open narrowed veins, often in the iliac or subclavian regions, to alleviate symptoms and improve blood return to the heart.
While Percutaneous Coronary Intervention remains central, Peripheral Artery Disease applications are expanding most quickly.
End User:
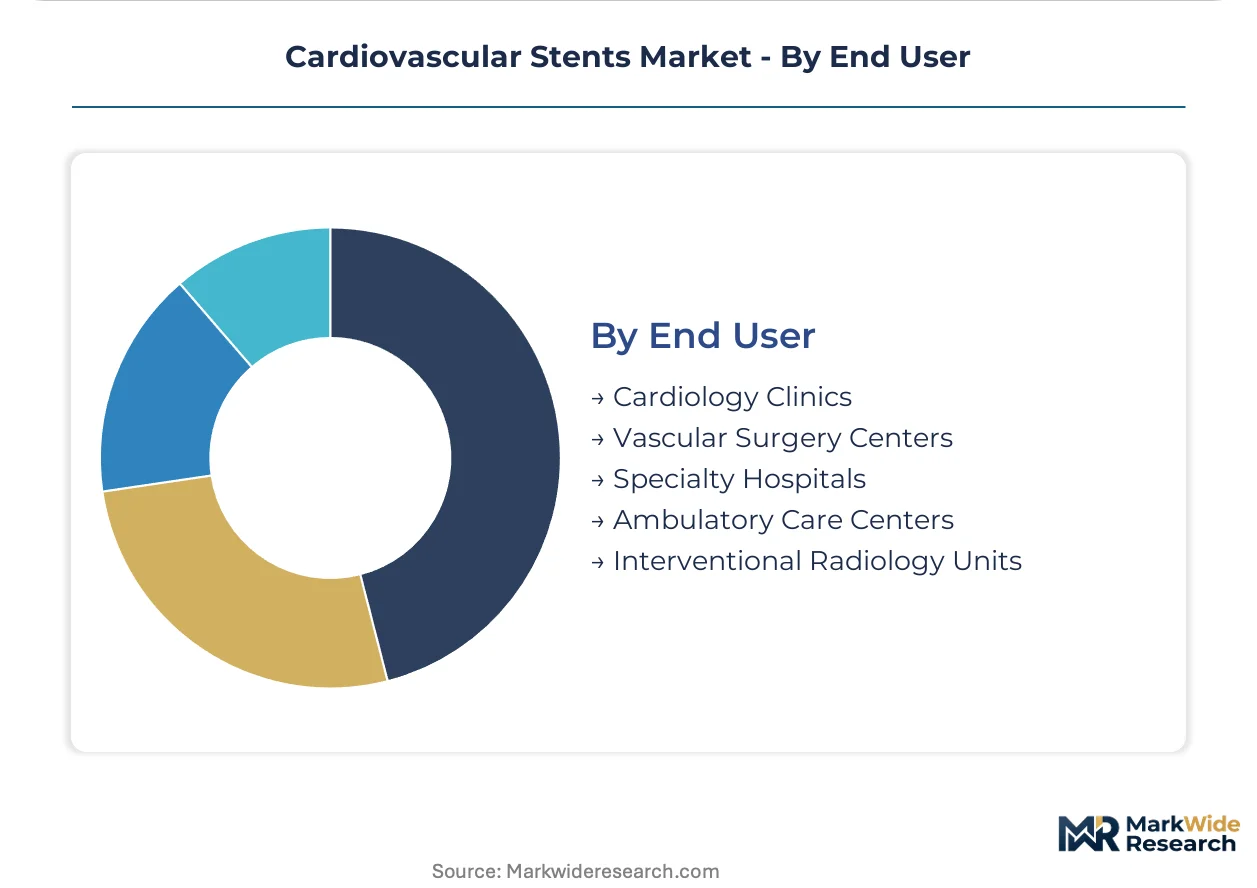
The end-user landscape for cardiovascular stents is characterized by specialized facilities equipped for complex interventional procedures and those increasingly handling less acute cases.
- Specialty Hospitals:These facilities possess advanced catheterization labs, specialized imaging equipment, and multidisciplinary teams for complex stenting cases and high-risk patient populations. Demand is concentrated in major urban centers across the US and Germany, handling a significant volume of advanced procedures.
- Vascular Surgery Centers:These centers focus on a broad range of arterial and venous interventions, including peripheral stenting, often providing dedicated surgical and interventional expertise. Demand is growing in emerging markets like Brazil and India, often offering more cost-effective procedural environments.
- Cardiology Clinics:Primarily handle patient diagnostics, risk assessment, and long-term follow-up, referring complex interventional cases to larger hospital settings.
- Ambulatory Care Centers:Increasingly perform less complex peripheral stenting procedures in an outpatient setting, driven by cost-efficiency and patient convenience.
- Interventional Radiology Units:Utilize imaging guidance for a wide array of vascular interventions, including stent placements in various body regions, often collaborating with cardiology and vascular surgery departments.
Specialty Hospitals maintain their leadership in complex cases, while Ambulatory Care Centers are gaining share for less acute procedures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory differences across major markets significantly influence the global launch sequencing and R&D timelines for cardiovascular stents, creating a landscape where manufacturers strategically prioritize market access based on compliance costs and approval speeds. This regulatory-arbitrage angle shapes investment decisions and product development pathways for innovative stent technologies.
China
Healthcare modernization and widening access to interventional cardiology procedures drive substantial demand for advanced coronary and peripheral stents in China. The NMPA's localized clinical trial requirements compel manufacturers to conduct specific studies on the Chinese population before market approval, influencing global R&D strategies. The Yangtze River Delta region is a hub for medical device manufacturing and clinical research, attracting both domestic and international players.
United States
Advanced procedural capabilities in specialty hospitals and the uptake of bioresorbable stents for complex cases fuel market expansion in the United States. The FDA's Premarket Approval (PMA) process sets a high bar for market entry, demanding extensive clinical evidence for new devices. The Boston-Cambridge innovation hub remains central for medical device R&D, fostering collaboration between academia and industry.
Germany
High-volume advanced interventional cardiology procedures and a strong emphasis on clinical data support demand for cardiovascular stents in Germany. CE marking under the Medical Device Regulation (MDR) requires rigorous technical documentation and clinical evidence for product conformity. Bavaria, with its robust MedTech sector and specialized cardiology centers, contributes significantly to stent innovation and adoption.
Japan
Early clinical adoption of next-generation devices, particularly polymer-based bioresorbable scaffolds, drives innovation within the Japanese market. The PMDA's stringent approval process for medical devices emphasizes patient safety and long-term efficacy. The Tokyo metropolitan area hosts major medical device companies and advanced research institutions, leading in the development of novel stent materials.
Brazil
The high prevalence of cardiovascular disease and improving diagnostic capabilities are expanding the market for interventional cardiology procedures in Brazil. ANVISA's requirements for medical device registration ensure product quality and safety within the national healthcare system. São Paulo serves as a major hub for medical services and device distribution, facilitating access to advanced stent technologies across Latin America.
Cardiovascular Stents Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, creating a tiered market structure for cardiovascular stents. Established global players dominate the premium segment, while specialized technology innovators focus on niche applications like bioresorbable stents. Regional manufacturers compete on cost-effectiveness and localized distribution networks, particularly in emerging markets. Portfolio diversification into digital health solutions and strategic partnerships for technology licensing are dominant competitive moves.
Within the established global leader archetype, Medtronic and Abbott represent companies with extensive device portfolios and integrated digital health solutions across cardiology offerings. Boston Scientific Corporation also occupies a strong position, anchoring its competitive strategy on robust clinical data supporting its drug-eluting stent technologies. These companies leverage their scale and R&D capabilities to navigate complex regulatory landscapes and drive technological advancements.
| Leading Market Players |
|---|
| Abbott |
| Medtronic |
| Boston Scientific Corporation |
| Biotronik SE & Co. KG |
| Terumo Corporation |
| B. Braun Melsungen AG |
| MicroPort Scientific Corporation |
| C. R. Bard |
| Cook Medical |
| Others |
Cost & Logistics Intelligence
The European Union's Medical Device Regulation (MDR) lifecycle assessment requirements gate qualified supply and premium-tier pricing access for cardiovascular stents. This regulatory environment influences both material sourcing strategies and the final market positioning of advanced stent technologies.
Pricing Analysis
Capacity additions in China are reshaping price floors for drug-eluting stents, particularly in high-volume segments. Value-based pricing is gaining traction, especially when integrated with digital health solutions, complementing traditional per-unit transactional sales. Price differentiation drivers include robust clinical data supporting efficacy and bioresorbable material innovation. Pricing pressure intensifies due to stringent regulatory hurdles like FDA Premarket Approval and high R&D costs. Public healthcare systems in Europe and China are highly price-sensitive, while private specialty hospitals in the United States prioritize advanced technology and patient outcomes.
Supply Chain Analysis
Input material sourcing for cardiovascular stents rests on specialized metal alloy producers, primarily for cobalt-chromium from Germany and platinum-chromium from various global suppliers. Polymer-based materials for bioresorbable stents often originate from Japan and South Korea. Single-source vulnerability for niche alloys and advanced polymer components presents a structural supply chain risk. Distribution runs through direct sales channels to specialty hospitals and vascular surgery centers, increasingly leveraging Group Purchasing Organizations (GPOs) within integrated health networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cardiovascular stents market operates as a stable compounder, driven by the persistent global prevalence of coronary artery disease and peripheral vascular conditions.
For Market Incumbents: Lock in long-term contracts with integrated health networks, leveraging extensive device portfolios and digital health integration. Consolidate market share by acquiring niche innovators in bioresorbable technologies, countering the threat of substitute technologies. Invest in clinical data generation to support next-generation drug-eluting stent efficacy, maintaining a competitive edge against emerging entrants.
For New Entrants and Emerging Players: Younger patients seeking implant-free solutions represent an underserved buyer archetype, creating a white space for novel bioresorbable stent designs. Target Latin American markets for peripheral artery disease applications, where diagnostic capabilities are improving. A go-to-market angle focusing on cost-effective bioresorbable solutions with streamlined regulatory pathways offers a distinct advantage.
For Investors and Strategic Acquirers: Roll-up economics work for technology-focused MedTech firms because fragmented innovation allows for strategic consolidation of intellectual property. The long-term viability of the market remains strong over a 5-10 year window, supported by an aging global population and rising chronic disease prevalence. Acquisition targets should include specialists in digital health integration or advanced material science for next-generation stents. Accelerating NMPA approvals for bioresorbable stents in China is a signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Next-Gen BVS | Secures market access and validates innovation for advanced bioresorbable vascular scaffolds in the United States. |
| Digital Health Integration | Shifts revenue models from device sales to long-term patient management value streams. |
| Clinical Trial Expansion in China | Addresses NMPA's localized data requirements for new drug-eluting stent technologies. |
| Peripheral Stent R&D | Unlocks significant demand from the underserved patient population with peripheral artery disease. |
| GPO Contract Optimization | Enhances market penetration and cost-effectiveness within integrated US health networks. |
Research Approach
Bottom-up end-user modeling for specialty hospitals reconciled against top-down manufacturer supply tracking forms the analytical core of this study. Primary interviews with interventional cardiologists, hospital purchasing managers, medical device engineers, and regulatory affairs specialists provided qualitative insights. Secondary data sources included FDA Premarket Approval filings, CE marking documentation, NMPA clinical trial databases, and industry association reports, ensuring robust triangulation.
Historical trendline analysis across the entire analysis window established foundational market trajectories for cardiovascular stents. The forecast framework modeled segmentation dimensions including product type, material, application, end user, and regional regulatory frameworks. Compound annual growth rates were derived from volume and value projections, accounting for technology adoption rates and healthcare expenditure. Key industry-specific forecast inputs included the prevalence of coronary artery disease and interventional cardiology procedure volumes.
Underlying measurement precision varies by segment; established drug-eluting stents carry tighter precision than emerging bioresorbable stents. Forecasts reflect assumptions regarding technological advancements and healthcare policy stability. Unforeseen regulatory changes, material science breakthroughs, or shifts in reimbursement policies represent specific risk factors. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Remote Endarterectomy Devices Market
Cardiovascular Devices
Cardiac Mapping Systems Market
Cardiovascular Devices
Medical Devices Cuffs Market
Cardiovascular Devices
Point-Of-Care Cholesterol Monitoring Device Market
Cardiovascular Devices
LAMEA Cardiac Surgical Devices Market
Cardiovascular Devices
Chile Cardiovascular Devices Market
Cardiovascular Devices
Blood Fluid Warming System Market
Cardiovascular Devices
Human Non-Invasive Blood Pressure (NIBP) Recording System Market
Cardiovascular Devices
Mitral Valve Disease Market
Cardiovascular Devices
Global Nitinol-Based Medical Devices Market
Cardiovascular Devices
Normal Balloon Catheter Market
Cardiovascular Devices
Cardiac Catheters Market
Cardiovascular Devices
India Cardiovascular Devices Market
Cardiovascular Devices
Cardiovascular Catheter Market
Cardiovascular Devices
Global Resuscitation Devices Market
Cardiovascular Devices
Intravenous Catheters Market