
 Branched Stent Grafts Market | 2026-2036
Branched Stent Grafts Market Size, Share, and Industry Trends Forecast 2026-2036
Branched Stent Grafts Market Intelligence
Hospital procurement of branched stent grafts is restructuring as cardiovascular service lines consolidate into high-volume aortic centers. Cook Medical sustains manufacturing depth in custom fenestrated platforms through its Indiana-based production campus. Medtronic dominates integrated delivery network contracts across the southeastern United States. W. L. Gore & Associates differentiates through expanded polytetrafluoroethylene material science that anchors its thoracoabdominal portfolio.
Branched stent grafts are implantable endovascular prostheses with multiple fenestrations or side branches that maintain perfusion to visceral arteries during aortic aneurysm repair, typically constructed from nitinol or cobalt-chromium frameworks covered with woven polyester or ePTFE. These devices enable minimally invasive treatment of juxtarenal and thoracoabdominal pathologies that previously required open surgical exposure. Fenestrated stent grafts occupy the highest-margin tier within product type segmentation due to patient-specific customization requirements and extended manufacturing lead times. Standard stent grafts compete on throughput economics in infrarenal indications where off-the-shelf availability drives inventory turns. Robotic-assisted delivery mode is gaining procedural traction as surgeons seek enhanced precision in branch cannulation.
FDA premarket approval pathways and the EU Medical Device Regulation shape commercialization timelines, with notified body capacity constraints in Europe extending certification cycles for custom device manufacturers. The FDA's continued refinement of fenestrated and branched device evaluation standards under its breakthrough devices program influences R&D allocation across the competitive set. Stakeholders must monitor evolving reimbursement determinations from CMS for complex endovascular aortic repair codes, as coverage decisions will determine addressable procedure volumes in the United States market.
Market Dynamics
FDA breakthrough device designation for fenestrated platforms compresses premarket timelines while EU MDR notified body bottlenecks force manufacturers to triage certification resources toward highest-margin custom configurations.
Growth Catalysts
- Complex aortic pathology volume:Tertiary referral networks in the United States consolidate juxtarenal and thoracoabdominal cases into high-volume centers, creating concentrated demand pools for patient-specific grafts.
- Material science advancement:Expanded polytetrafluoroethylene lamination techniques improve branch patency rates and reduce endoleak incidence, expanding eligible patient populations.
- CMS reimbursement expansion:Coverage determinations for complex endovascular aortic repair codes in the United States validate procedural economics and stabilize hospital capital planning.
Market Restraints
- Platinum-iridium marker wire scarcity:Radiopaque element supply concentrates among specialty metal refiners, exposing manufacturers to spot price volatility and allocation risk.
- Custom manufacturing lead times:Patient-specific fenestrated grafts require 6-8 week production cycles, constraining inventory velocity and working capital efficiency.
- Open surgical substitute persistence:Medicare Advantage plans in select United States markets maintain prior authorization hurdles that favor established open repair pathways for anatomically straightforward cases.
Strategic Opportunities
- Robotic-assisted delivery convergence:Integration of magnetic navigation with preoperative 3D planning software reduces branch cannulation time and radiation exposure.
- Off-the-shelf thoracoabdominal platforms:Standardized multi-branch configurations address urgent symptomatic aneurysms where custom manufacturing timelines are clinically unacceptable.
- Japan reimbursement pathway:PMDA conditional approval frameworks for breakthrough devices create accelerated market access for next-generation fenestrated systems.
Industry Challenges
- Computational fluid dynamics talent scarcity:Patient-specific graft design requires specialized simulation expertise that outpaces vascular engineering training pipeline output.
- Legacy enterprise resource planning integration:Custom device manufacturers struggle to align FDA 21 CFR Part 820 quality system requirements with modern manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Branched Stent Grafts Market |
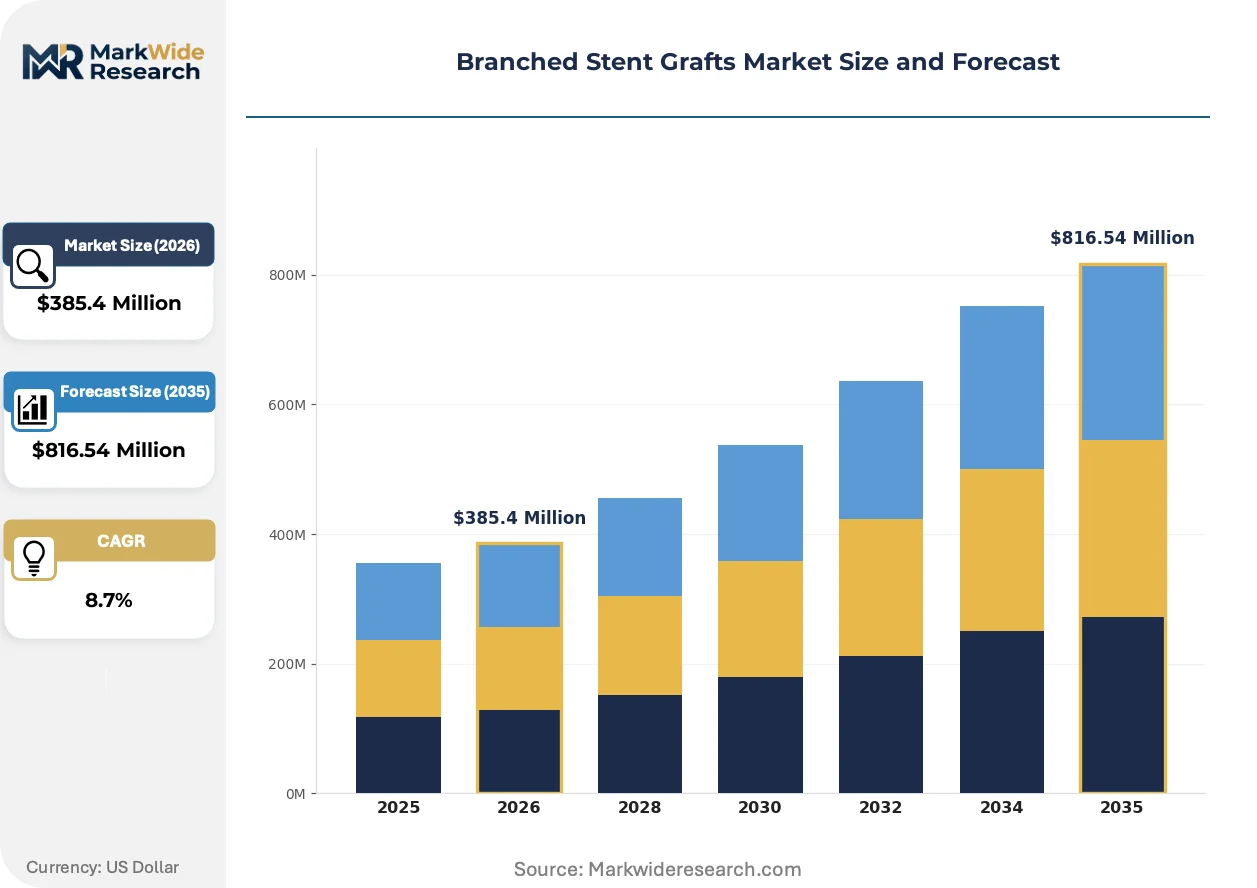
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fenestrated Stent Grafts, Custom Stent Grafts, Standard Stent Grafts, Hybrid Stent Grafts End User: Cardiovascular Clinics, Hospitals, Ambulatory Surgical Centers, Specialty Cardiovascular Centers Delivery Mode: Endovascular, Open Surgery, Minimally Invasive, Robotic-Assisted Application: Aortic Aneurysms, Aortic Dissection, Peripheral Artery Disease, Vascular Repair |
| Companies Covered | Medtronic, Cook Medical, Terumo Corporation, Boston Scientific Corporation, Abbott Laboratories, Biotronik, Merit Medical Systems, Cardinal Health, W. L. Gore & Associates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Branched Stent Grafts Market Strategic Shifts & Innovations
Digital preoperative planning ecosystems are compressing the boundary between imaging interpretation and device specification, enabling same-day graft design consultations that previously required multi-week specialist coordination.
Preloaded branch delivery systems with integrated guidewire capture mechanisms reduce cannulation complexity and fluoroscopy time. High-volume aortic centers in the United States and Germany adopt these platforms for elective thoracoabdominal repairs. The technology is modularizing surgeon training curves and expanding eligible operator pools beyond fellowship-trained specialists.
EU MDR Article 52 extended review timelines for custom-made devices force manufacturers to maintain parallel technical documentation systems. Small-batch producers face disproportionate compliance cost burdens relative to standardized graft portfolios. Fenestrated device manufacturers respond by consolidating notified body relationships and pre-submission engagement with BSI and TÜV SÜD.
Hospital cardiovascular service lines unbundle device procurement from bundled payment negotiations, creating direct manufacturer-contracting channels that bypass traditional distributor markups. Integrated delivery networks in the southeastern United States pilot consignment inventory models for high-cost custom grafts. This restructuring concentrates purchasing leverage among systems with sufficient case volume to justify dedicated implant coordinators.
Branched Stent Grafts Market Segmentation
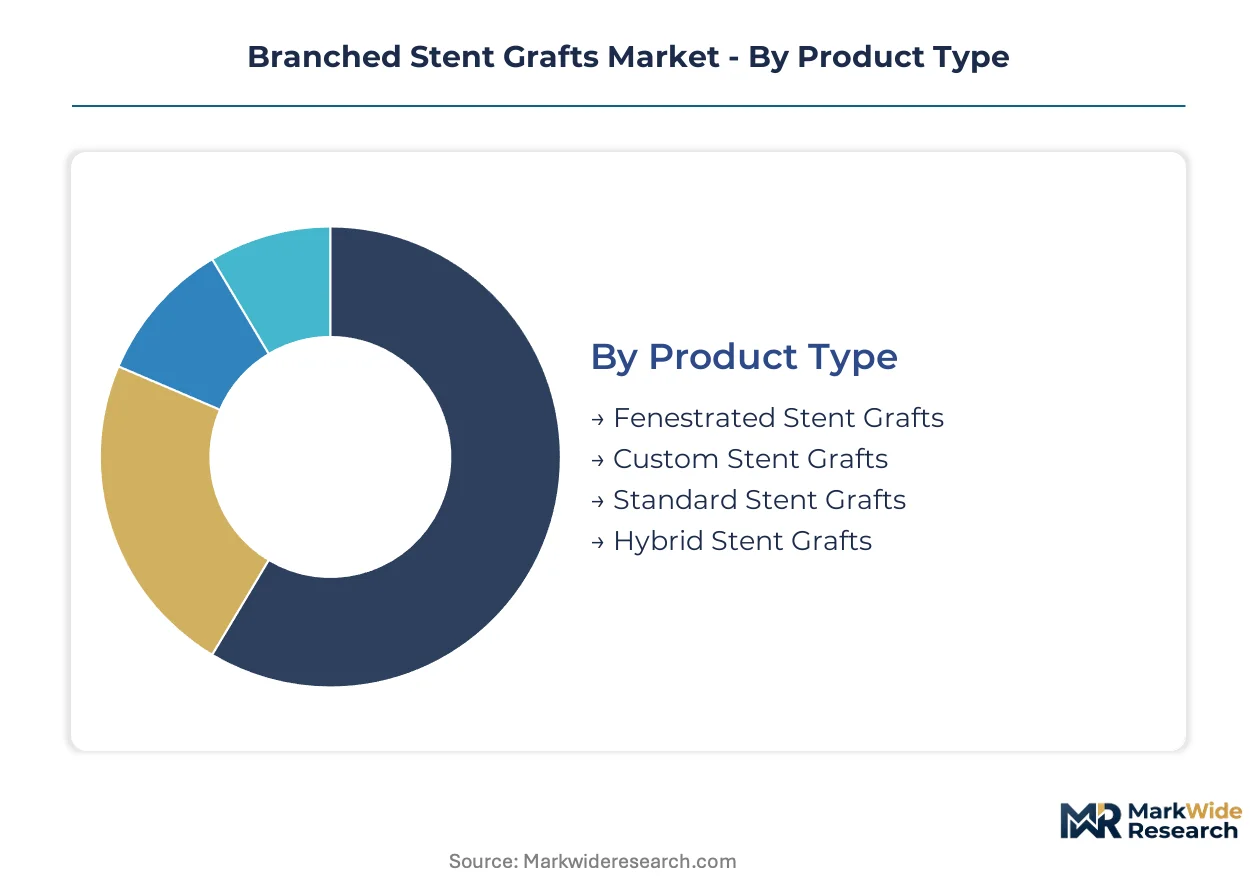
Patient-specific customization requirements create divergent margin profiles across product architectures, while delivery modality selection reshapes capital deployment patterns in cardiovascular service lines. Segmentation clarity enables manufacturers to align production capacity with procedural volume concentration in high-volume aortic centers.
Product Type:
The customization-to-standardization spectrum determines manufacturing complexity, regulatory pathway intensity, and inventory velocity across this category.
- Fenestrated Stent Grafts:Patient-specific devices incorporate precisely positioned fenestrations matching individual visceral artery anatomy, requiring 6-8 week production cycles and intensive computational fluid dynamics simulation. Demand concentrates in United States tertiary referral centers where complex juxtarenal and thoracoabdominal case volumes justify extended lead times. Cook Medical maintains manufacturing depth through its Indiana-based production campus.
- Custom Stent Grafts:These physician-specified configurations extend beyond standard sizing matrices to address anatomical outliers and redo procedures. United States integrated delivery networks with dedicated aortic programs drive procurement concentration, prioritizing graft-host compatibility over procurement velocity.
- Standard Stent Grafts:Off-the-shelf availability enables rapid inventory turns for infrarenal indications where anatomical parameters fall within conventional sizing ranges.
- Hybrid Stent Grafts:Combined endovascular-surgical platforms address arch and proximal descending pathology through staged deployment protocols.
Most installed capacity flows through Fenestrated Stent Grafts. Expansion is steepest in Standard Stent Grafts as urgent symptomatic presentations outpace custom manufacturing timelines.
End User:
Procedural volume thresholds and capital equipment requirements stratify purchasing authority across this category.
- Hospitals:Tertiary cardiovascular centers with dedicated aortic service lines consolidate complex case volumes and maintain hybrid operating suite infrastructure. United States referral networks have matured to concentrate juxtarenal and thoracoabdominal repairs into high-volume institutions with fellowship-trained specialists. Medtronic dominates integrated delivery network contracts across the southeastern United States.
- Specialty Cardiovascular Centers:Focused institutions with single-specialty concentration achieve superior outcomes metrics that drive regional referral patterns and justify premium device procurement.
- Cardiovascular Clinics:Diagnostic and follow-up facilities without interventional capabilities refer procedural candidates to affiliated hospital systems.
- Ambulatory Surgical Centers:Limited to straightforward infrarenal cases with favorable anatomy and minimal comorbidity burden.
Procurement authority concentrates in Hospitals. Specialty Cardiovascular Centers are gaining share fastest through outcome-based referral consolidation.
Delivery Mode:
Precision requirements and radiation exposure concerns differentiate technology adoption curves across this category.
- Robotic-Assisted:Magnetic navigation platforms integrated with preoperative 3D planning software reduce branch cannulation time and fluoroscopy exposure. High-volume aortic centers in the United States and Germany adopt these systems for elective thoracoabdominal repairs, expanding eligible operator pools beyond fellowship-trained specialists.
- Endovascular:Transfemoral deployment remains the dominant approach for fenestrated and branched configurations, requiring advanced imaging fusion and dedicated hybrid suite infrastructure.
- Minimally Invasive:Percutaneous access techniques reduce recovery timelines for anatomically favorable cases with straightforward branch anatomy.
- Open Surgery:Persistent role for anatomically complex cases and patients with unfavorable endovascular anatomy, particularly where Medicare Advantage prior authorization favors established surgical pathways.
Capital deployment favors Endovascular infrastructure. Robotic-Assisted delivery is climbing the fastest as precision requirements intensify.
Application:
Anatomical location and clinical urgency determine device specification complexity and reimbursement pathway across this category.
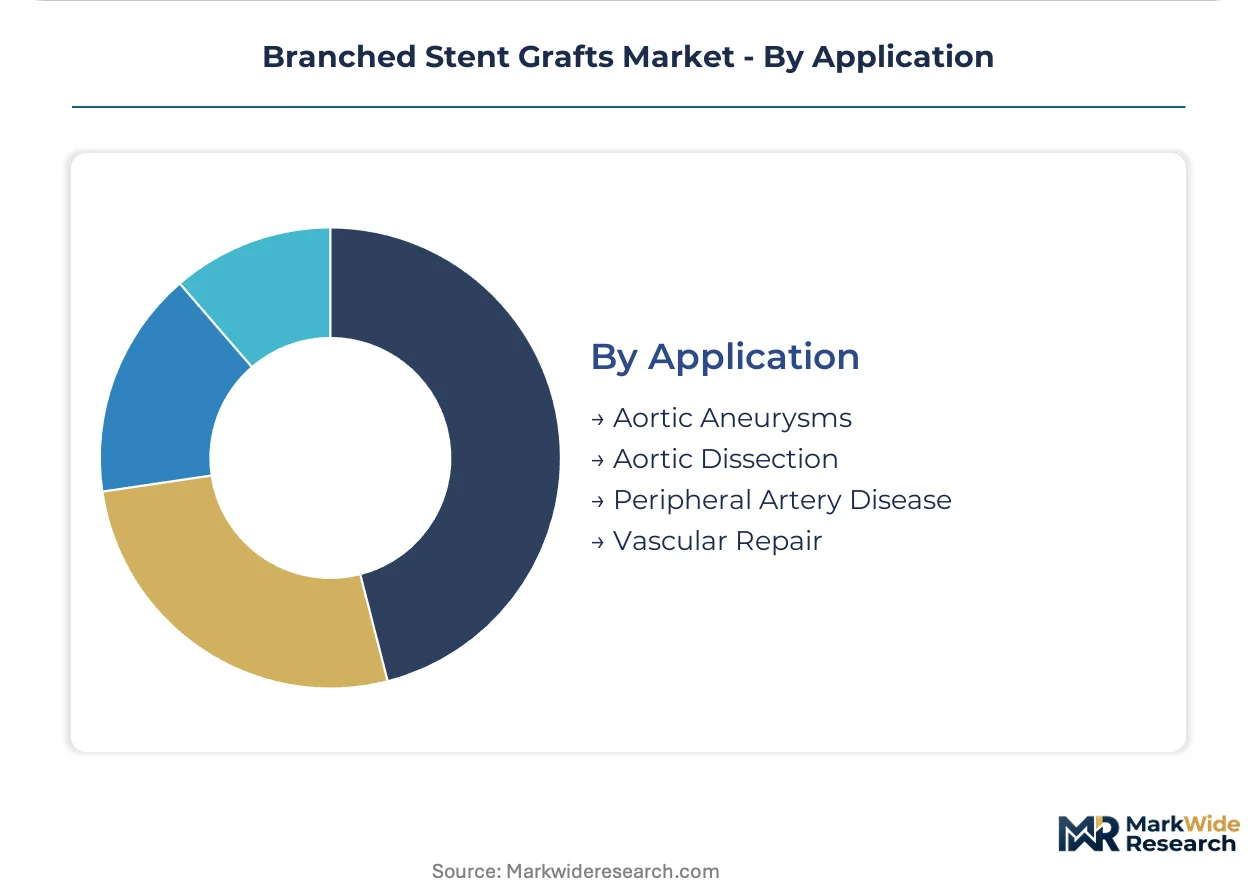
- Aortic Aneurysms:Juxtarenal and thoracoabdominal presentations require fenestrated or branched platforms to maintain visceral perfusion, representing the highest-complexity tier within endovascular aortic repair. United States CMS coverage determinations for complex endovascular codes validate procedural economics and stabilize hospital capital planning.
- Aortic Dissection:Acute and chronic presentations drive demand for off-the-shelf thoracoabdominal platforms where custom manufacturing timelines are clinically unacceptable.
- Peripheral Artery Disease:Lower complexity indications utilize standard stent graft configurations with established reimbursement pathways.
- Vascular Repair:Trauma and iatrogenic injury applications require rapid device availability and flexible sizing matrices.
Clinical volume concentrates in Aortic Aneurysms. Aortic Dissection is expanding most quickly as urgent presentation protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing migration patterns track regulatory arbitrage opportunities, with custom device producers shifting technical documentation capacity toward jurisdictions with streamlined premarket pathways. The United States maintains procedural volume concentration while European certification bottlenecks redirect investment toward Asian regulatory accelerators.
United States
Tertiary aortic centers in Houston, Cleveland, and Baltimore consolidate complex case volumes that drive fenestrated graft procurement. FDA breakthrough device designation compresses premarket timelines for patient-specific platforms, attracting R&D investment toward its 510(k) refinement pathways. The southeastern integrated delivery network corridor anchors contract concentration for high-volume hospital systems.
Germany
High-volume aortic programs in Munich and Heidelberg adopt robotic-assisted delivery systems for elective thoracoabdominal repairs. EU MDR notified body bottlenecks force manufacturers to maintain parallel technical documentation systems for custom device exports. The Baden-Württemberg medical technology cluster concentrates simulation engineering talent for computational fluid dynamics design.
Japan
PMDA conditional approval frameworks for breakthrough devices create accelerated market access for next-generation fenestrated systems. Tokyo and Osaka academic medical centers drive adoption of preloaded branch delivery platforms. METI medical device reimbursement reform stabilizes hospital capital planning for complex endovascular infrastructure.
China
NMPA innovation approval pathways for domestically manufactured branched grafts shorten time-to-market for local producers. Shanghai and Beijing cardiovascular centers expand hybrid operating suite capacity to address growing thoracoabdominal case volumes. MIIT medical device industry policy incentivizes domestic substitution in vascular implant manufacturing.
Switzerland
Swissmedic streamlined review for custom-made devices attracts European manufacturers seeking regulatory efficiency for high-margin patient-specific portfolios. Zurich and Geneva academic hospitals maintain referral relationships with German and French aortic centers. The Basel pharmaceutical-medical device corridor concentrates materials science expertise for ePTFE lamination technologies.
Branched Stent Grafts Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with patient-specific customization requirements favoring vertically integrated producers over outsourced fabrication networks. The vendor base concentrates around three strategic archetypes: integrated cardiovascular conglomerates with broad graft portfolios, dedicated endovascular specialists with manufacturing depth in fenestrated platforms, and materials science innovators leveraging proprietary polymer lamination techniques. Capacity expansion and strategic partnerships dominate competitive moves, as manufacturers seek to compress custom graft lead times while maintaining regulatory compliance across multiple jurisdictions.
Among integrated delivery network suppliers, Medtronic and Cook Medical exemplify divergent scale strategies, with the former anchoring multi-state hospital system contracts and the latter maintaining captive production for patient-specific configurations. W. L. Gore & Associates occupies a position within the materials science tier, representing manufacturers that differentiate through proprietary expanded polytetrafluoroethylene platforms rather than device assembly scale.
| Leading Market Players |
|---|
| Medtronic |
| Cook Medical |
| Terumo Corporation |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Biotronik |
| Merit Medical Systems |
| Cardinal Health |
| W. L. Gore & Associates |
| Others |
Cost & Logistics Intelligence
Hospital cardiovascular service line consolidation into high-volume aortic centers in the United States is compressing procurement timelines and forcing manufacturers to absorb working capital costs from extended custom graft production cycles, which in turn stratifies pricing across patient-specific and off-the-shelf tiers.
Pricing Analysis
Distributor margin compression in integrated delivery network contracting is accelerating direct manufacturer-to-hospital negotiations. Three-tier pricing structure across premium fenestrated, standard thoracoabdominal, and economy infrarenal levels reflects customization intensity and regulatory pathway investment. Price differentiation hinges on FDA breakthrough designation status and computational fluid dynamics simulation depth. Cost compression in standard stent graft tiers is intensifying because of inventory velocity competition, while fenestrated platforms maintain pricing power through patient-specific scarcity. Ambulatory surgical centers exhibit highest price sensitivity; tertiary aortic centers prioritize graft-host compatibility over unit cost.
Supply Chain Analysis
Nitinol wire supply rests on specialty metal refiners in the United States and Germany, with platinum-iridium marker element sourcing concentrating among Japanese and Swiss precious metal processors. Woven polyester textile production draws from established medical textile manufacturers in the United States and Ireland, while expanded polytetrafluoroethylene lamination anchors in the United States and Japan. Single-source vulnerability in radiopaque marker supply exposes manufacturers to spot price volatility and allocation risk. Distribution runs through GPO-contracted channels for hospital systems and direct consignment models for high-volume aortic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The branched stent graft market operates as a regulatory compounder where FDA breakthrough device designation for fenestrated platforms compresses premarket timelines and validates premium pricing, creating sustained demand concentration in United States tertiary referral networks.
For Market Incumbents: Extend manufacturing depth in patient-specific configurations through captive computational fluid dynamics talent acquisition, addressing the simulation engineering pipeline shortage that constrains custom graft design capacity. Expand parallel technical documentation systems for EU MDR compliance to mitigate notified body bottleneck exposure. Vertical integration into nitinol wire processing reduces radiopaque element supply risk from Japanese and Swiss specialty refiners. For New Entrants and Emerging Players: Robotic-assisted delivery platform integration with preoperative 3D planning software offers a technology-first wedge into high-volume aortic centers seeking to expand eligible operator pools beyond fellowship-trained specialists. Target ambulatory surgical center infrastructure for straightforward infrarenal cases where price sensitivity creates entry opportunity. Pursue hospital system partnership models that bypass traditional GPO markup layers through direct contracting channels. For Investors and Strategic Acquirers: Asymmetric upside sits with materials science innovators possessing proprietary ePTFE lamination techniques and established notified body relationships for EU MDR navigation. Long-term viability centers on manufacturers with compressed custom graft lead times and regulatory approval breadth across FDA, PMDA, and NMPA pathways. Watch FDA 510(k) refinement timelines for fenestrated device categories as inflection indicator for R&D allocation efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway Navigation | Accelerated premarket timelines compress competitive entry windows for patient-specific platforms. |
| Hospital System Direct Contracting | Bypasses GPO distributor markups and secures volume commitments from high-volume aortic centers. |
| Computational Fluid Dynamics Talent Acquisition | Addresses simulation engineering scarcity that constrains custom fenestrated graft design capacity. |
| EU MDR Notified Body Consolidation | Reduces compliance cost burden from parallel technical documentation requirements for custom devices. |
| Robotic-Assisted Delivery Platform Integration | Expands eligible operator pools beyond fellowship-trained specialists in tertiary referral networks. |
Research Approach
Direct dialogue with vascular surgeons, hospital purchasing committee members, biomedical engineers at custom device manufacturers, and GPO contracts managers grounded the qualitative foundation. Secondary validation drew from FDA 510(k) and PMA filings, CMS Medicare reimbursement determinations, EU MDR notified body public summaries, and hospital procurement database extracts. Bottom-up procedure volume modeling and top-down market sizing triangulated demand estimates across the analysis window.
Segmented outputs across product type, end user, delivery mode, and application dimensions fed into analytical framework construction. CAGRs were derived from procedure volume trajectories and device pricing stratification patterns. Industry-specific inputs incorporated tertiary aortic center referral network maturation, FDA breakthrough designation pipeline flow, and platinum-iridium marker wire supply allocation dynamics.
The model holds under stable CMS reimbursement determinations and FDA premarket pathway refinement; deviation in EU MDR notified body capacity or radiopaque element supply disruption would shift manufacturer certification resource allocation and working capital requirements. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Point-Of-Care Cholesterol Monitoring Device Market
Cardiovascular Devices
Fractional Flow Reserve-Computed Tomography (FFR-CT) Market
Cardiovascular Devices
Remote Endarterectomy Devices Market
Cardiovascular Devices
Microsclerotherapy Treatment Market
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
Vascular Access Systems Market
Cardiovascular Devices
Intravascular Stents Market
Cardiovascular Devices
Global Vascular Graft Market
Cardiovascular Devices
Wearable Artificial Organs Market
Cardiovascular Devices
Pressure Infusion Cuffs Market
Cardiovascular Devices
Peripheral Vascular Interventions Market
Cardiovascular Devices
Chronic Venous Occlusions Treatment Market
Cardiovascular Devices
Global Intracranial Stents Market
Cardiovascular Devices
Neurovascular Coiling Assist Devices Market
Cardiovascular Devices
US Ventricular Assist Devices Market
Cardiovascular Devices
Atrial Fibrillation (AF) Ablation Market