
 Emulsified Fuel Market | 2026-2036
Emulsified Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Emulsified Fuel Market Analysis
Specialized marine fuel chemists is reorganizing supply chains as vessel operators seek compliant low-sulfur alternatives. Quadrise Fuels International leverages its emulsion combustion technology to serve power-plant retrofits across European ports. TecnoVeritas anchors its position through onboard fuel-system engineering that integrates emulsified blends into existing engine architectures. Eneco Holdings differentiates via geographic dominance in Asian maritime corridors where bunker fuel specifications tighten progressively.
Emulsified fuel denotes a colloidal suspension of water droplets dispersed within a continuous hydrocarbon phase, typically stabilized by surfactant concentrations between 0.5% and 2% by volume, designed to reduce NOx and particulate emissions during combustion. Heavy oil emulsions dominate current marine application volumes due to established bunkering infrastructure and cost compatibility with two-stroke diesel engines. Power generation applications represent the fastest-expanding segment as utilities retrofit aging heavy-fuel-oil plants to meet sulfur-oxide thresholds without full fuel-switching investments. Diesel emulsions command premium positioning in transportation fleets where cold-start emission regulations drive surfactant formulation complexity.
The International Maritime Organization enforces sulfur-content ceilings that directly expand addressable demand for water-in-fuel emulsions as a compliance pathway. EPA standards for stationary diesel engines and EU F-Gas Regulation indirectly shape surfactant selection and water-content ratios through thermal-efficiency benchmarks. Stakeholders must monitor evolving carbon-intensity metrics at port authorities, since future berth-access rules may redefine whether emulsified blends qualify as transitional or terminal fuel solutions.
Market Dynamics
Marine fuel compliance deadlines are compressing procurement cycles as vessel operators abandon high-sulfur residual oils ahead of enforcement milestones. The International Maritime Organization's sulfur caps have triggered a wholesale reorganization of bunkering infrastructure toward water-in-fuel emulsion systems.
Growth Catalysts
- IMO 2020 Sulfur Regulations:The International Maritime Organization's 0.5% sulfur ceiling mandates immediate fuel reformulation across international shipping corridors. Compliance deadlines drive retrofit demand at major bunkering terminals.
- Heavy Fuel Oil Infrastructure:Existing storage and distribution networks for residual marine fuels enable rapid emulsion blending deployment without greenfield capital. Port operators leverage sunk-cost advantages to offer compliant fuel alternatives.
- Surfactant Chemistry Advances:German chemical laboratories have developed temperature-stable emulsifiers that maintain colloidal integrity across tropical bunker storage conditions. These formulations extend emulsion shelf life from days to weeks.
Market Restraints
- Crude Oil Price Volatility:Feedstock cost swings for heavy fuel oil and marine diesel create margin compression for emulsion blenders. Water-content ratios must recalibrate when base fuel economics shift abruptly.
- Singapore Supply Concentration:Southeast Asian bunkering volumes concentrate at a single hub port, creating geographic vulnerability to local enforcement delays or infrastructure bottlenecks. Regional diversification remains underdeveloped.
- LNG Substitution Threat:Liquefied natural gas bunkering infrastructure expands at Rotterdam, Singapore, and Shanghai terminals. Dual-fuel vessel orders accelerate as operators hedge against emulsion combustion uncertainty.
Strategic Opportunities
- Indian Power Generation Retrofits:State electricity boards operate aging heavy-fuel-oil plants facing sulfur-oxide thresholds under Central Electricity Authority guidelines. Emulsion combustion offers compliance without full fuel-switching investments.
- EU F-Gas Regulation Thermal Benchmarks:The European Union's efficiency standards for stationary combustion equipment indirectly reward water-in-fuel emulsions through NOx reduction credits. Utilities gain regulatory headroom for plant life extensions.
- Onboard Fuel System Integration:Real-time emulsion generation at vessel engine rooms eliminates storage stability concerns entirely. Marine engineering firms pioneer compact homogenizer units for deep-sea tanker fleets.
Industry Challenges
- Marine Fuel Chemist Shortage:Specialized formulation expertise for water-in-hydrocarbon colloids remains concentrated among legacy petroleum laboratories. Training pipelines for surfactant-blend optimization lag fleet expansion timelines.
- Emulsion Stability Certification:Port state control authorities lack harmonized testing protocols for emulsified fuel quality at bunkering. ISO standards for water-content verification remain under development, creating acceptance uncertainty.
- Engine Manufacturer Warranty Complexity:Original equipment manufacturers impose varying water-content limits on two-stroke diesel injection systems. Operators navigate conflicting technical guidance across Wärtsilä, MAN Energy Solutions, and Mitsubishi portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emulsified Fuel Market |
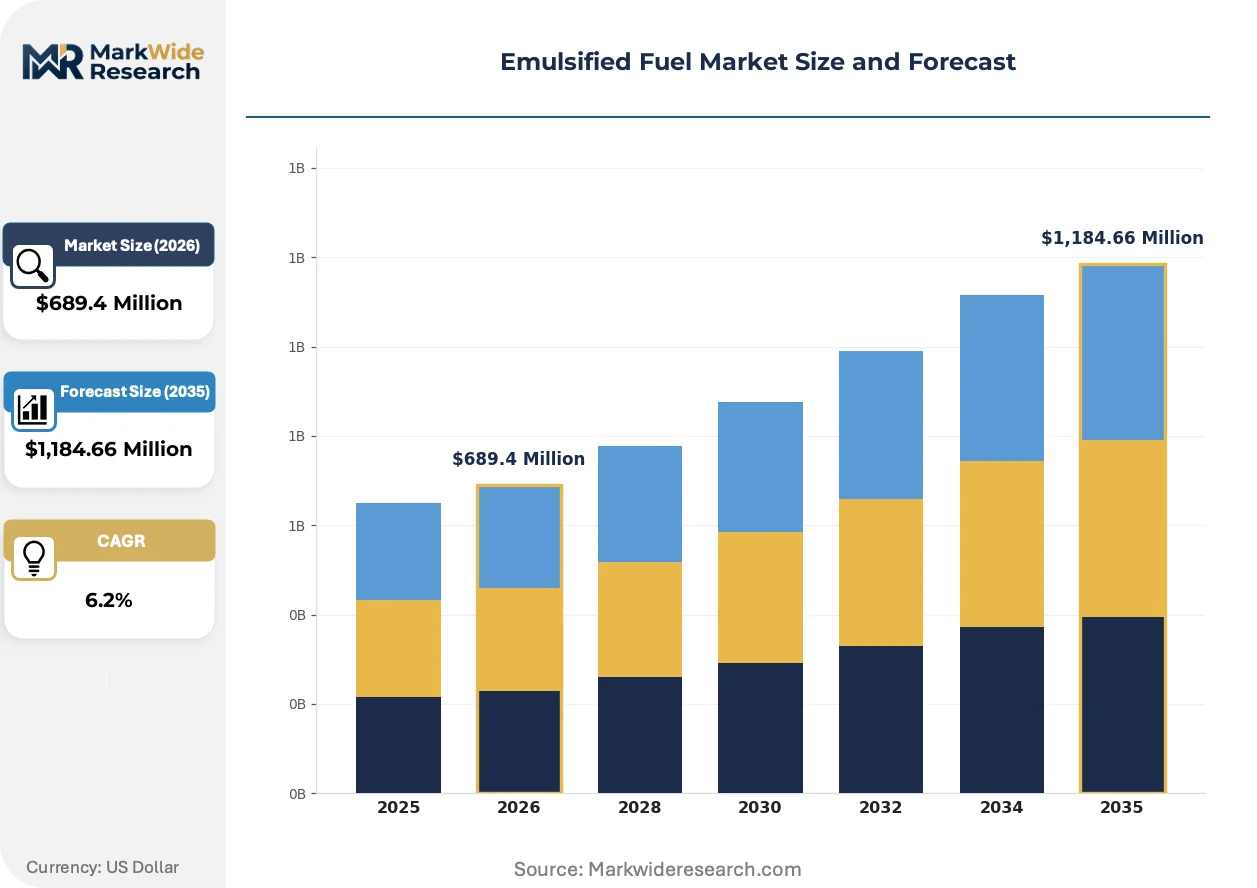
| Market Size in 2026 | $689.4 Million |
| Market Size in 2035 | $1,184.66 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Biofuels, Diesel, Gasoline, Heavy Oil Application: Marine, Power Generation, Transportation, Industrial Heating Component: Water, Surfactants, Oil, Emulsifiers Technology: Emulsification, Dispersion, Blending, Stabilization |
| Companies Covered | TecnoVeritas, Eneco Holdings, Quadrise Fuels International, Clean Diesel Technologies, Fukai Souken, TotalEnergies, Alternative Petroleum Technologies, Emulsol, SULNOX Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emulsified Fuel Market Emerging Trajectories
Combustion chemistry and regulatory enforcement are converging to redefine fuel formulation economics. Water-in-fuel emulsion technology advances through three distinct vectors reshaping marine and stationary power applications.
Surfactant formulation science is fragmenting the competitive landscape between synthetic and bio-based stabilizers. Synthetic alkylbenzene sulfonates dominate current marine volumes due to cost parity with residual fuel economics. Bio-derived lecithin and fatty-acid esters command premium positioning in European power generation where REACH compliance adds regulatory value. The technology shift is fragmenting supplier tiers between petrochemical majors and specialty biochemical firms.
EPA standards for stationary diesel engines now incorporate thermal-efficiency benchmarks that indirectly favor water-emulsion combustion pathways. The agency's Tier 4 compliance timeline compresses retrofit decision windows for US utilities operating aging heavy-fuel-oil assets. Power plant operators in Texas and Louisiana are piloting emulsion systems ahead of state implementation plan deadlines, creating regional demand clusters distinct from marine bunkering patterns.
Buyers are consolidating procurement authority through integrated fuel-service contracts that bundle emulsion supply with combustion optimization. Major container lines now negotiate directly with formulation specialists rather than intermediating through traditional bunker traders. This pattern concentrates most visibly in Singapore's port authority jurisdiction, where PSA Marine and Jurong Port operators demand performance guarantees linking surfactant quality to emission outcomes.
Emulsified Fuel Market Segmentation
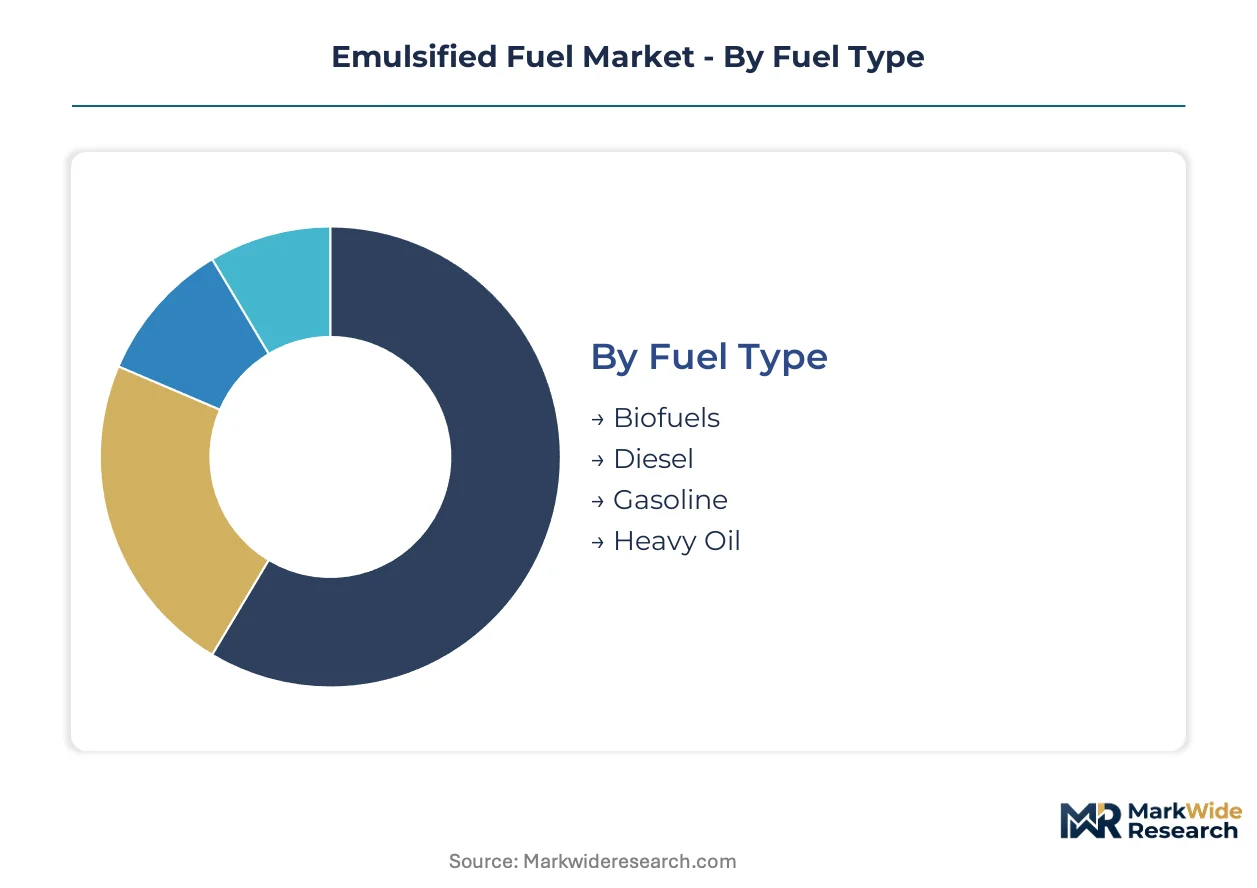
Emulsified fuel markets fragment across fuel chemistries, combustion applications, and formulation technologies that each impose distinct surfactant requirements and supply chain configurations. Understanding these boundaries reveals where procurement power concentrates and where technical barriers protect margin structures.
Fuel Type:
Geographic demand patterns split sharply between marine-export corridors and domestic power-generation basins.
- Heavy Oil:Residual fuel emulsions carry water fractions between 10% and 30% by volume, stabilized by alkylbenzene sulfonate surfactants. Demand clusters at Singapore's bunkering terminals where IMO sulfur enforcement drives vessel operators toward compliant heavy-fuel-oil alternatives without scrubber investments.
- Diesel:Water-in-diesel emulsions achieve NOx reductions through micro-explosion combustion physics. European transportation fleets in Germany and the Netherlands adopt these formulations where cold-start particulate regulations under EURO VI standards impose surfactant complexity premiums.
- Biofuels:Fatty-acid methyl ester emulsions blend with conventional distillates for carbon-intensity scoring.
- Gasoline:Spark-ignition emulsions remain experimental outside Japanese passenger-vehicle test programs.
Heavy oil commands the established base. The steepest expansion runs through diesel.
Application:
End-use economics diverge between capital-intensive marine retrofits and operational-expense-driven power plant conversions.
- Marine:Two-stroke diesel engines on deep-sea tankers and container vessels consume emulsified residual fuels through modified injection systems. Singapore, Rotterdam, and Shanghai bunkering hubs enforce quality protocols that concentrate procurement through certified blenders.
- Power Generation:Stationary combustion turbines and heavy-fuel-oil boilers retrofit emulsion systems to meet sulfur-oxide thresholds without fuel-switching capital. Indian state electricity boards and Texas independent power producers drive regional demand clusters.
- Transportation:Fleet operators in California and Germany pilot emulsified diesel for particulate compliance.
- Industrial Heating:Cement kilns and steel reheat furnaces apply emulsion combustion for thermal-efficiency gains.
Marine applications anchor current procurement volumes. Power generation is expanding most quickly.
Component:
Formulation cost structures concentrate value capture in surfactant chemistry versus commodity water and base oil inputs.
- Surfactants:Synthetic alkylbenzene sulfonates dominate marine formulations due to cost parity with residual fuel economics. German chemical laboratories develop temperature-stable variants extending emulsion shelf life from days to weeks under tropical storage conditions.
- Water:Deionized process water constitutes 10% to 30% of emulsion volume, sourced from port infrastructure or onboard desalination.
- Oil:Heavy fuel oil and marine diesel serve as continuous hydrocarbon phases.
- Emulsifiers:Bio-derived lecithin and fatty-acid esters command premiums in European power generation where REACH compliance adds regulatory value.
Synthetic surfactants hold the volume base. Bio-based emulsifiers are gaining share fastest.
Technology:
Process control sophistication separates laboratory-scale formulation from industrial emulsion stability at scale.
- Emulsification:High-shear homogenization creates water droplet dispersions below 10 microns for combustion efficiency. Onboard marine units from TecnoVeritas and Quadrise enable real-time generation eliminating storage degradation risks.
- Stabilization:Colloidal integrity maintenance across temperature cycling determines shelf life and bunkering acceptance.
- Dispersion:Droplet size distribution control affects NOx reduction coefficients.
- Blending:Inline mixing systems at port terminals achieve batch consistency for ISO certification.
Emulsification technology commands the installed base. Stabilization represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The IMO's sulfur caps anchor regulatory momentum in Singapore, where port authorities enforce the world's strictest bunkering standards. This maritime enforcement cascade reshapes fuel procurement across four additional national markets.
Singapore
PSA Marine and Jurong Port operators drive procurement consolidation through integrated fuel-service contracts bundling emulsion supply with combustion guarantees. The Maritime and Port Authority enforces quality protocols that concentrate demand through certified blenders. Bunkering volumes at Singapore's hub terminals exceed regional competitors by multiples, creating geographic concentration risk.
Germany
REACH compliance requirements elevate bio-derived lecithin and fatty-acid ester premiums in European power generation procurement. The country's chemical laboratories develop temperature-stable surfactants extending emulsion shelf life under tropical storage conditions. Hamburg and Bremerhaven port clusters anchor North Sea bunkering demand for compliant residual fuel alternatives.
United States
EPA Tier 4 standards compress retrofit decision windows for utilities operating aging heavy-fuel-oil assets across Texas and Louisiana. State implementation plan deadlines drive regional demand clusters distinct from marine bunkering patterns. Gulf Coast independent power producers pilot emulsion systems ahead of enforcement milestones.
India
Central Electricity Authority guidelines push state electricity boards toward sulfur-oxide compliance without full fuel-switching capital investments. The country's aging heavy-fuel-oil plant fleet creates retrofit opportunity at scale. Gujarat and Maharashtra industrial corridors concentrate procurement authority among integrated energy majors.
Netherlands
Rotterdam's LNG bunkering infrastructure expansion creates competitive pressure on emulsion combustion pathways. The EU F-Gas Regulation's thermal-efficiency benchmarks indirectly reward water-in-fuel emulsions through NOx reduction credits. Port of Rotterdam operators hedge between dual-fuel vessel orders and emulsion blending capacity.
Emulsified Fuel Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with petrochemical majors controlling surfactant supply and marine engineering firms capturing system integration value. The structure rewards backward integration into emulsifier chemistry and geographic anchoring at enforcement-heavy port authorities. Two archetypes dominate: formulation specialists with laboratory-scale optimization capabilities and port-terminal operators with bunkering infrastructure leverage. Competitive moves center on strategic partnerships with engine manufacturers and technology licensing for onboard homogenizer deployment.
Within the marine engineering tier, TecnoVeritas and Quadrise Fuels International exemplify system integration specialists, while Eneco Holdings occupies a position reflecting Asian maritime corridor concentration. These three entities represent distinct geographic and technical positioning without overlapping core competencies.
| Leading Market Players |
|---|
| TecnoVeritas |
| Eneco Holdings |
| Quadrise Fuels International |
| Clean Diesel Technologies |
| Fukai Souken |
| TotalEnergies |
| Alternative Petroleum Technologies |
| Emulsol |
| SULNOX Group |
| Others |
Supply Flow & Price Mechanics
Fourteen-day surfactant inventory cycles at Singapore bunkering terminals concentrate pricing power among German chemical laboratories and integrated terminal operators, compressing margin capture for independent blenders while rewarding backward-integrated suppliers with captive emulsifier production.
Pricing Analysis
Singapore-to-Rotterdam price spreads for heavy-fuel-oil emulsions exceed synthetic surfactant premiums by multiples, reflecting contract-based long-term offtake structures that dominate marine procurement. Price differentiation rests on ISO certification tiers and volume scale, with major container lines extracting concessions unavailable to spot buyers. Cost compression in standard-grade blends is intensifying because crude oil volatility forces rapid water-content recalibration. Independent vessel operators exhibit highest price sensitivity; integrated power utilities with captive generation assets show lowest.
Supply Chain Analysis
Strategic stockpiling of temperature-stable surfactants dominates over just-in-time approaches, as German chemical laboratories and Southeast Asian terminal operators buffer against tropical storage degradation and enforcement deadline clustering. Supply concentrates in Germany, Singapore, and India, with feedstock dependencies on alkylbenzene sulfonates, deionized process water, and residual heavy fuel oil. Single-source vulnerability around German specialty surfactant chemistry creates structural exposure. Distribution runs through certified bunkering terminals at major port authorities rather than open-market trading.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Emulsified fuel procurement is consolidating into platform-economics structures where integrated fuel-service contracts bundle formulation supply with combustion performance guarantees, eroding traditional bunker trader intermediation.
For Market Incumbents: Fortify positions through captive surfactant manufacturing partnerships with German chemical laboratories and exclusive terminal access agreements at Singapore's PSA Marine facilities. LNG bunkering infrastructure expansion at Rotterdam and Shanghai terminals threatens emulsion volume retention, making backward integration into temperature-stable emulsifier chemistry essential for margin defense. For New Entrants and Emerging Players: ISO 8217 fast-track certification for water-in-fuel emulsions unlocks procurement access at Indian state electricity boards and Texas independent power producers before marine bunkering saturation. White-space concentration sits with onboard real-time emulsion generation systems for deep-sea tanker fleets, where TecnoVeritas and Quadrise have not established exclusive engine-manufacturer partnerships. Go-to-market execution should anchor at Gulf Coast utilities facing EPA Tier 4 enforcement compression. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because sulfur-cap enforcement cascades through maritime corridors faster than LNG infrastructure deployment can match. Acquisition targets should display surfactant chemistry capabilities plus port-terminal relationships at enforcement-heavy jurisdictions. The signal to watch is berth-access rule evolution at port authorities, where carbon-intensity metrics may reclassify emulsified blends from transitional to terminal fuel solutions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Chemistry | German laboratory partnerships secure temperature-stable emulsifier supply against tropical storage degradation risks. |
| Onboard Emulsion Generation Deployment | Real-time homogenizer units eliminate storage stability concerns for deep-sea tanker fleets. |
| ISO Certification Fast-Track Investment | Quality protocol compliance concentrates procurement access through Singapore Maritime and Port Authority channels. |
| Integrated Fuel-Service Contract Bundling | Performance guarantees linking surfactant quality to emission outcomes displace traditional bunker traders. |
| Power Generation Retrofit Partnership | Indian state electricity board relationships capture sulfur-oxide compliance demand without fuel-switching capital. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with marine fuel chemists, port terminal procurement officers, and power plant engineering directors; and secondary validation through IMO regulatory filings, EPA Tier 4 compliance databases, and customs trade records for surfactant imports. Bottom-up volume modeling triangulated against top-down market sizing across fuel type, application, and technology segmentation dimensions.
Across the modeling period, analytical frameworks tracked emulsion stability certification adoption, onboard generation technology penetration, and regional enforcement milestone clustering. Segmentation dimensions included fuel chemistry, combustion application, formulation component, and process technology tier. CAGRs derived from installation base expansion rates and retrofit decision-window compression at utilities and marine operators.
Underlying assumptions cover sulfur-cap enforcement adherence, surfactant chemistry shelf-life extension, and LNG bunkering infrastructure buildout pace, with deviation risk concentrated in port state control harmonization delays and engine manufacturer warranty standardization. Practitioners should keep alternative scenarios live as carbon-intensity metrics at berth-access rules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Italy Chemical Logistics Market
Fuels
Gas to Liquid (GTL) Market
Fuels
Underground Coal Gasification Market
Fuels
Global Chemical Logistics Market
Fuels
Catalytic Hydrothermolysis Jet [CHJ] Fuel Market
Fuels
Multifuel Gas Turbine Market
Fuels
Oil Dispenser Market
Fuels
Europe Commercial Aircraft Aviation Fuel Market
Fuels
United States Coal Market
Fuels
Asia-Pacific Commercial Aircraft Aviation Fuel Market
Fuels
China LNG Bunkering Market
Fuels
Mobile Fuel Delivery Market
Fuels
Palm Methyl Ester Market
Fuels
Iso-Octane Market
Fuels
Storage Tank Market
Fuels
South Korea LNG Bunkering Market