
 Underground Coal Gasification Market | 2026-2036
Underground Coal Gasification Market Size, Share, and Industry Trends Forecast 2026-2036
Underground Coal Gasification Market Analytics
Australia is reshaping competitive dynamics in underground coal gasification through sustained investment in deep coal seam demonstration projects. Oil and Natural Gas Corp. Ltd. anchors its position through captive control over India's largest coal reserve blocks. Sasol Ltd. leverages decades of syngas processing expertise to extend its technology licensing footprint. Ergo Exergy Technologies Inc. specializes in proprietary eUCG reactor designs that differentiate its offering from conventional surface gasification.
Underground coal gasification involves the controlled partial combustion of coal seams in situ to produce synthesis gas, typically operating at depths between 100 and 1,000 meters with oxidant injection through drilled boreholes. The process yields a low-to-medium Btu gas stream comprising hydrogen, carbon monoxide, and methane for downstream power generation or chemical synthesis. Electricity generation occupies the largest share of current application revenue, though hydrogen production is accelerating fastest as refiners and ammonia producers seek low-carbon feedstock alternatives. Fixed bed gasifier configurations dominate installed pilot capacity, while entrained flow systems command premium engineering margins due to higher thermal efficiency and syngas quality.
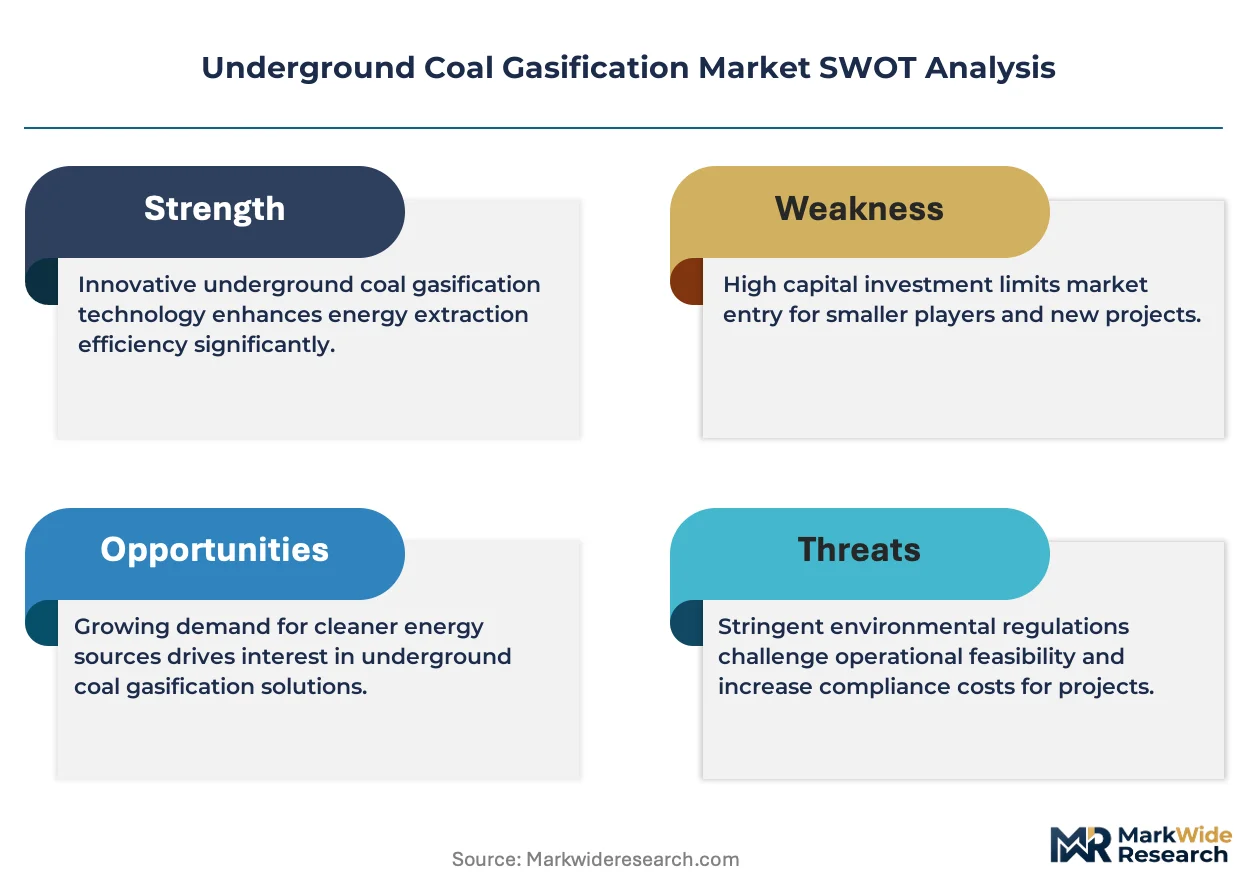
China's MEE imposes groundwater monitoring mandates on all UCG trial licenses, effectively raising compliance costs for shallow seam projects. Australia's state-level environmental regulators require continuous seismic monitoring and post-closure site rehabilitation bonds. India's CEA maintains a restrictive stance on commercial UCG deployment pending further groundwater impact studies. Stakeholders must weigh regulatory pathway certainty against resource quality when prioritizing project development sequences.
Market Dynamics
Industrial decarbonization mandates are forcing a recalibration of syngas sourcing strategies across energy-intensive manufacturing. The tension between stranded coal asset utilization and carbon intensity targets is redirecting capital toward in-situ conversion technologies that bypass surface mining and transportation emissions.
Growth Catalysts
- Dual carbon targets:China's MEE has accelerated pilot licensing for deep-seam UCG projects that align with national hydrogen production roadmaps.
- Refinery feedstock switching:Ammonia and methanol producers are evaluating syngas from in-situ gasification as a lower-carbon alternative to steam methane reforming.
- Sequestration pairing:Enhanced oil recovery operators are integrating UCG syngas with carbon capture infrastructure in depleted reservoir formations.
Market Restraints
- Groundwater contamination liability:Australia's state-level regulators require continuous aquifer monitoring and post-closure rehabilitation bonds that inflate project carrying costs.
- Oxidant supply concentration:Cryogenic oxygen production for deep injection wells depends on a concentrated industrial gas supplier base with limited geographic diversification.
- Surface gasification competition:Integrated gasification combined cycle plants with pre-combustion capture offer proven performance guarantees that UCG projects cannot yet match.
Strategic Opportunities
- India's stranded deep reserves:The CEA's pending groundwater impact framework could unlock commercial deployment in the Damodar and Godavari basins once finalized.
- Blue hydrogen certification:EU taxonomy alignment for low-carbon hydrogen production creates a compliance premium for UCG-sourced syngas with verified carbon capture.
- Modular reactor standardization:Convergence of directional drilling automation with real-time downhole monitoring is collapsing development timelines for repeatable project templates.
Industry Challenges
- Subsurface characterization expertise:Geomechanical modeling for cavity stability prediction requires specialized reservoir engineering talent that remains concentrated in conventional oilfield services.
- Permitting timeline compression:Multi-agency coordination between mining, environmental, and petroleum regulators extends pre-construction phases beyond typical investor return horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underground Coal Gasification Market |
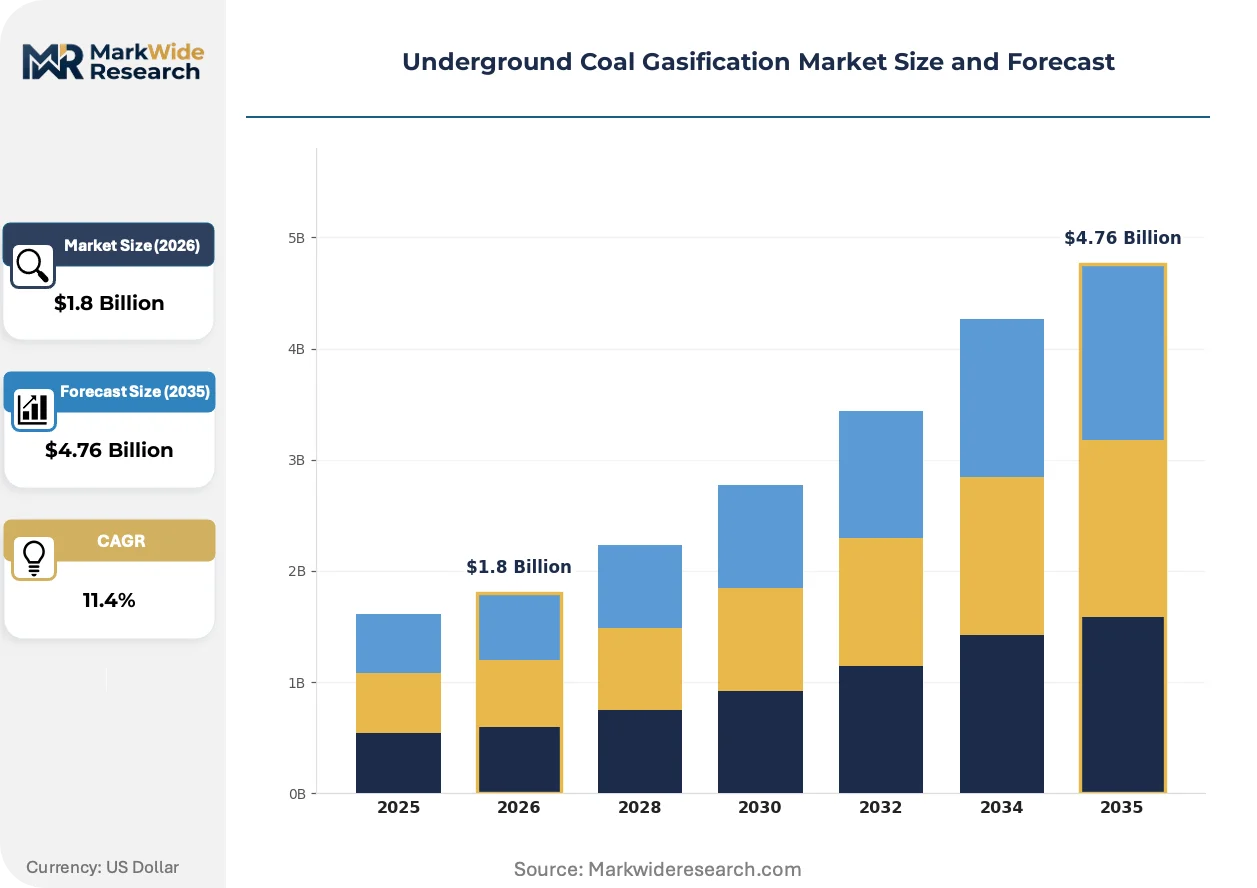
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: In-Situ Gasification, Modified Fracture, Continuous Flow, Non-Aqueous System Application: Electricity Generation, Hydrogen Production, Syngas Generation, Chemical Manufacturing End User: Power Plants, Industrial Manufacturers, Chemical Plants, Refining Sector Gasifier Type: Fixed Bed, Fluidized Bed, Entrained Flow, Others |
| Companies Covered | Oil and Natural Gas Corp. Ltd., Swan Hills Synfuels LLP, Synthesis Energy Systems Inc., Sasol Ltd., SEDIN Engineering Co. Ltd., Ergo Exergy Technologies Inc., Linc Energy, Carbon Energy, Coal India, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underground Coal Gasification Market Evolving Landscape
Directional drilling precision and real-time formation monitoring are converging to enable controlled combustion in previously inaccessible coal seams. These advances are reshaping project economics and opening new geological frontiers for syngas production.
Plasma-assisted ignition systems are collapsing the startup reliability gap that has historically plagued UCG field trials. Operators in Australia's Surat Basin are deploying these systems to achieve consistent syngas quality across variable seam moisture content. The technology is compressing the risk premium that lenders apply to first-of-a-kind project finance.
China's MEE groundwater monitoring mandates are forcing integration of distributed sensor networks into trial license applications. This regulatory pressure is accelerating adoption of fiber-optic temperature sensing and microseismic arrays that were previously considered optional. Shallow-seam projects in the Ordos Basin are most affected, with several operators redesigning well configurations to satisfy continuous monitoring requirements.
Refinery procurement teams are unbundling syngas supply contracts from long-term offtake commitments that characterized earlier UCG development waves. This purchasing flexibility is displacing integrated project structures in favor of tolling arrangements where the operator retains product risk. The shift is most visible in Western Australia's industrial corridors, where ammonia producers are negotiating short-term pilot supply agreements before committing to facility-scale investment.
Underground Coal Gasification Market Segmentation
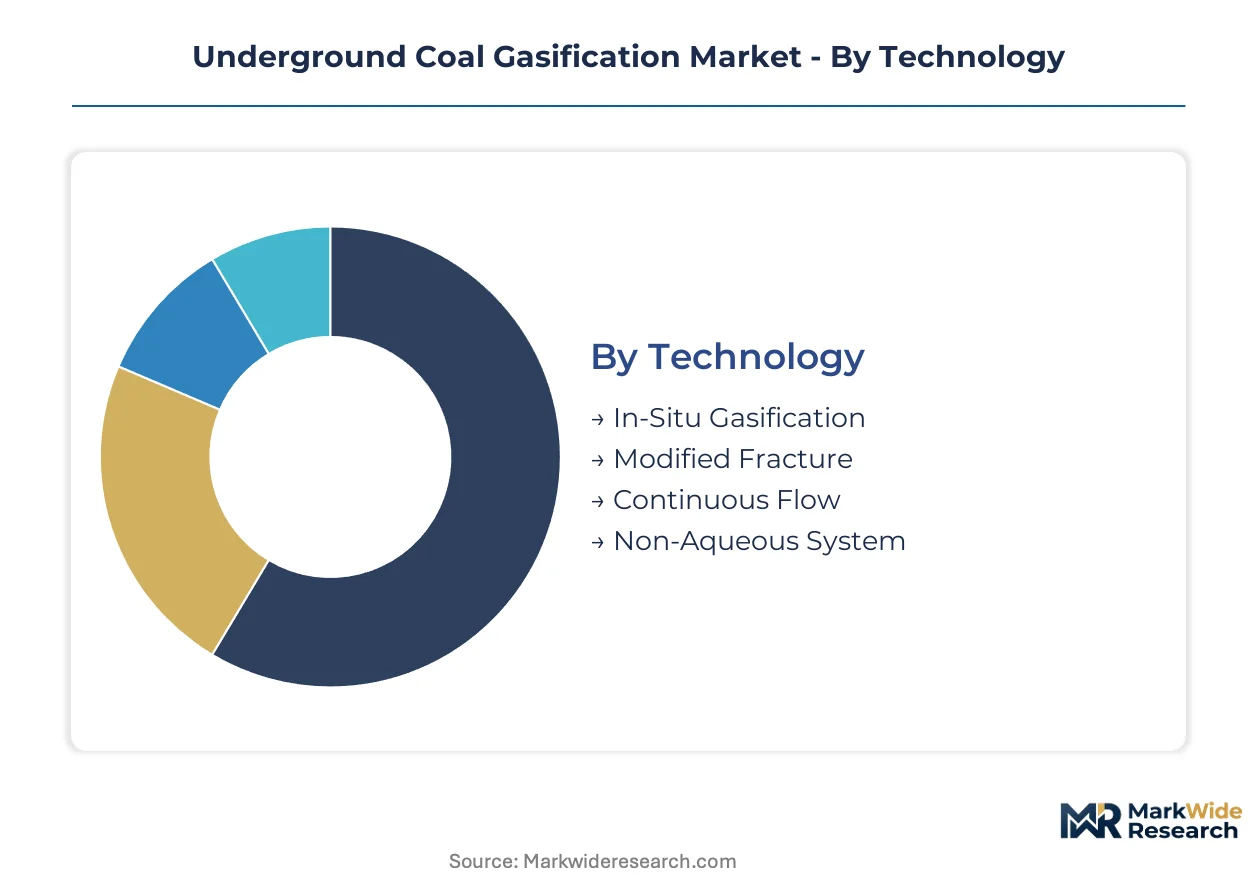
Technology choices in underground coal gasification determine cavity stability, syngas quality, and project financing terms. Application segmentation reveals where industrial decarbonization mandates are redirecting capital most aggressively.
Technology:
Cost tier differentiation separates proven methods from experimental configurations still seeking commercial validation.
- In-Situ Gasification:The foundational approach injects oxidants directly into unmined coal seams through vertical boreholes, creating controlled combustion cavities at depths between 100 and 1,000 meters. Australia's Surat Basin hosts the most advanced commercial demonstrations of this method, where Linc Energy and Carbon Energy have validated syngas consistency across variable seam thicknesses. China's MEE licensing framework favors deep-seam in-situ projects that align with national hydrogen production roadmaps.
- Continuous Flow:This configuration maintains steady oxidant injection and syngas extraction through dedicated well pairs, enabling higher thermal efficiency and more predictable output volumes. Refinery procurement teams in Western Australia's industrial corridors are evaluating continuous flow pilots for ammonia feedstock supply, attracted by the shorter commissioning timelines relative to batch-cycle alternatives.
- Modified Fracture:Employs directional drilling and controlled fracturing to enhance permeability in low-porosity coal seams.
- Non-Aqueous System:Eliminates water-based drilling fluids to reduce groundwater contamination risks in environmentally sensitive formations.
In-Situ Gasification holds installed capacity. Continuous Flow is rotating up the share rankings.
Application:
End-use demand concentrates where carbon intensity regulations are tightening fastest and syngas substitutes command premium pricing.
- Hydrogen Production:UCG-derived syngas offers refiners and ammonia producers a pathway to blue hydrogen certification under EU taxonomy rules, provided carbon capture verification accompanies production. The segment is climbing the fastest as industrial decarbonization targets in China, Australia, and India force feedstock switching away from steam methane reforming. MEE oversight in China has specifically prioritized hydrogen-linked UCG pilots in the Ordos Basin.
- Electricity Generation:Integrated gasification combined cycle plants consuming UCG syngas bypass surface mining emissions and transportation logistics entirely. India's CEA maintains restrictive licensing for power-sector UCG pending groundwater impact studies, though captive power applications in the Damodar Basin remain under evaluation.
- Syngas Generation:Intermediate product supply for methanol, Fischer-Tropsch liquids, and synthetic natural gas production.
- Chemical Manufacturing:Direct feedstock for ammonia, urea, and specialty chemical synthesis requiring specific H2/CO ratios.
Electricity Generation dominates current revenue. Hydrogen Production is gaining share fastest.
End User:
Customer type determines offtake contract structures, with power utilities favoring long-term supply agreements and industrial manufacturers preferring tolling arrangements.
- Power Plants:Baseload generators in coal-dependent grids evaluate UCG as a stranded asset recovery mechanism, particularly where surface mining reserves are depleted or environmentally constrained. Australia's state-level regulators require continuous seismic monitoring and rehabilitation bonds that inflate project carrying costs for power-sector developers.
- Refining Sector:Hydrogen demand for hydrocracking and desulfurization operations has refiners sourcing syngas from in-situ gasification as a lower-carbon alternative. Procurement teams are unbundling supply contracts from integrated project structures, negotiating short-term pilot agreements before facility-scale commitment.
- Industrial Manufacturers:Steel and cement producers with captive power needs.
- Chemical Plants:Methanol and ammonia synthesis facilities requiring consistent syngas composition.
Power Plants anchor historical deployment. Refining Sector is rotating up the share rankings.
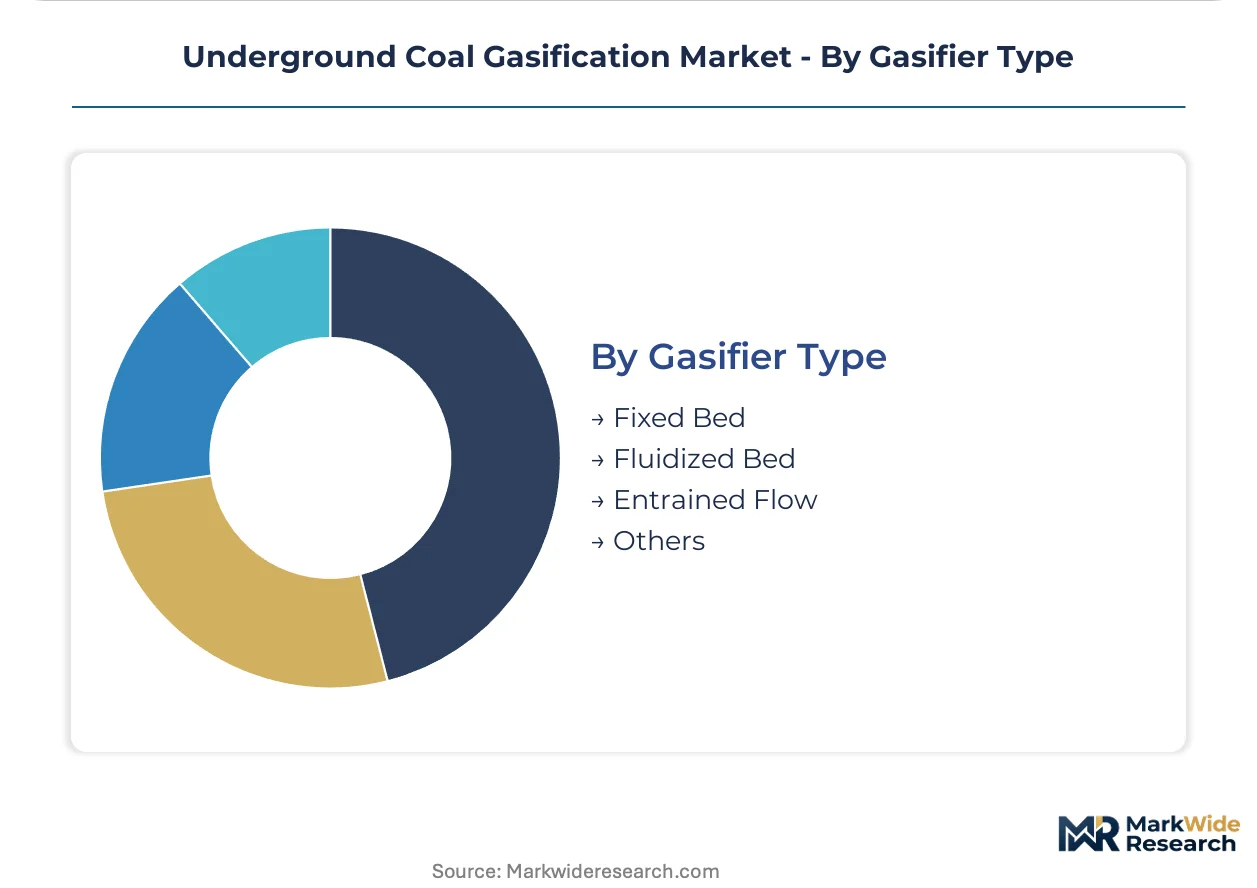
Gasifier Type:
Engineering margin concentration follows thermal efficiency and syngas quality specifications, with premium configurations commanding higher licensing fees.
- Fixed Bed:Dominates installed pilot capacity due to simpler mechanical design and lower capital requirements for demonstration-scale projects. The configuration handles high-ash coals common in India's Damodar and Godavari basins, though CEA restrictions on commercial deployment have limited scaling beyond trial licenses.
- Entrained Flow:Operates at higher temperatures and pressures to produce syngas with minimal tars and particulates, suitable for refined chemical synthesis and hydrogen production. Premium engineering margins reflect the specialized refractory materials and oxygen supply infrastructure required, with cryogenic oxygen production dependencies concentrating supplier risk.
- Fluidized Bed:Offers intermediate thermal efficiency with better fuel flexibility than fixed bed alternatives.
- Others:Emerging configurations including molten bath and plasma-assisted systems still seeking commercial validation.
Fixed Bed holds installed capacity. Entrained Flow is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE oversight in China anchors the dominant geography for underground coal gasification, with pilot licensing frameworks accelerating deep-seam projects that align with national hydrogen production roadmaps.
China
Deep-seam UCG projects in the Ordos Basin are climbing the priority list as MEE groundwater monitoring mandates force integration of distributed sensor networks into trial license applications. Dual carbon targets are redirecting capital toward in-situ conversion technologies that bypass surface mining emissions. Operators in the Ordos Basin are redesigning well configurations to satisfy continuous monitoring requirements.
Australia
State-level environmental regulators in Queensland and Western Australia require continuous seismic monitoring and post-closure site rehabilitation bonds that inflate project carrying costs. The Surat Basin hosts the most advanced commercial demonstrations where plasma-assisted ignition systems are collapsing startup reliability gaps. Linc Energy and Carbon Energy have validated syngas consistency across variable seam thicknesses in this basin.
India
CEA restrictions on commercial UCG deployment are pending further groundwater impact studies, though captive power applications in the Damodar Basin remain under evaluation. Fixed bed gasifier configurations dominate installed pilot capacity due to simpler mechanical design. The Damodar and Godavari basins hold stranded deep reserves that could unlock commercial deployment once the CEA framework finalizes.
South Africa
Sasol Ltd. leverages decades of syngas processing expertise to extend its technology licensing footprint across southern African coal belts. The country's national energy regulator maintains scrutiny of groundwater impacts for shallow seam projects. Industrial corridors near Secunda concentrate evaluation of continuous flow pilots for ammonia feedstock supply.
United States
EPA groundwater protection standards and state-level mining regulations create a complex permitting environment for UCG field trials. Enhanced oil recovery operators in the Permian Basin are integrating UCG syngas with carbon capture infrastructure in depleted reservoir formations. Wyoming's Powder River Basin hosts preliminary geological assessments for deep-seam viability.
Underground Coal Gasification Market Competitive Landscape
State-affiliated energy conglomerates and specialized technology licensors split the market into distinct competitive spheres. The vendor base concentrates around entities with captive coal reserve access or proprietary reactor engineering capabilities. National oil companies and independent syngas specialists represent the dominant archetypes, with technology licensing and strategic partnerships serving as the primary competitive moves.
Within the state-affiliated tier, Oil and Natural Gas Corp. Ltd. and Coal India exemplify entities with captive control over national coal reserve blocks. Among technology specialists, Ergo Exergy Technologies Inc. occupies a position defined by proprietary eUCG reactor designs. Sasol Ltd. anchors the syngas processing archetype through decades of operational experience. Synthesis Energy Systems Inc. and SEDIN Engineering Co. Ltd. sit within the engineering and systems integration tier, reflecting the geographic diversification of technical capability across North American and Chinese markets respectively.
| Leading Market Players |
|---|
| Oil and Natural Gas Corp. Ltd. |
| Swan Hills Synfuels LLP |
| Synthesis Energy Systems Inc. |
| Sasol Ltd. |
| SEDIN Engineering Co. Ltd. |
| Ergo Exergy Technologies Inc. |
| Linc Energy |
| Carbon Energy |
| Coal India |
| Others |
Value Network & Pricing Analysis
Cryogenic oxygen production for deep injection wells concentrates in a limited supplier base across China, Germany, and the United States, anchoring margin pools downstream with entrained flow gasifier operators who command premium engineering fees for higher thermal efficiency configurations.
Pricing Analysis
Price spreads between fixed bed and entrained flow configurations run widest in Australia and China, where MEE groundwater monitoring mandates inflate compliance costs for shallow-seam projects. Project-based pricing dominates, with differentiation driven by certification level for carbon capture verification and seam depth complexity. Pricing pressure stems from surface gasification competition offering proven performance guarantees that UCG pilots cannot yet match. Power utilities exhibit highest price sensitivity due to long-term offtake contract exposure, while refiners negotiating tolling arrangements absorb premium syngas costs for hydrogen feedstock security.
Supply Chain Analysis
Extended payment terms from state-affiliated energy conglomerates in China and India are reshaping supplier financing structures for directional drilling contractors and fiber-optic sensor networks. Component sourcing draws from Germany for precision drilling equipment, China for distributed sensor arrays, and Australia for plasma-assisted ignition systems. Single-source vulnerability concentrates around cryogenic oxygen supply infrastructure with limited geographic diversification. Distribution runs through EPC contractors integrating UCG modules into broader hydrogen production or enhanced oil recovery project portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Underground coal gasification represents a service-attach opportunity where real-time downhole monitoring subscriptions and post-closure rehabilitation bonds expand faster than reactor hardware sales as regulatory mandates tighten across trial jurisdictions.
For Market Incumbents: Harden groundwater liability frameworks through captive insurance structures before Australia's state-level regulators expand rehabilitation bond requirements. Consolidate directional drilling automation capabilities through backward integration into specialist contractors, as plasma-assisted ignition system reliability becomes the primary differentiation lever against emerging modular reactor licensors.
For New Entrants and Emerging Players: Establish a beachhead in India's Damodar Basin captive power applications where CEA restrictions have delayed incumbent scaling and stranded deep reserves await commercial framework finalization. Target tolling arrangement structures with Western Australian ammonia producers who are unbundling supply contracts from integrated project commitments.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed syngas technology licensors holding proprietary eUCG reactor designs but lacking captive coal reserve access. Long-term viability across the analysis window hinges on hydrogen certification alignment with EU taxonomy rules. Watch MEE pilot license acceleration in the Ordos Basin as the inflection indicator for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Agreement | Ergo Exergy Technologies extends proprietary eUCG reactor designs into China's Ordos Basin trial projects. |
| Backward Integration into Oxygen Supply | Entrained flow operators secure cryogenic production capacity to reduce single-source supplier vulnerability. |
| Joint Venture for Modular Standardization | Directional drilling automation converges with real-time monitoring to compress development timelines. |
| Long-term Tolling Arrangement | Western Australian ammonia producers negotiate flexible syngas supply without integrated project commitment. |
| Carbon Capture Certification Program | Blue hydrogen verification under EU taxonomy rules creates compliance premium for UCG-sourced syngas. |
Research Methodology
Initial hypotheses were tested against primary input from UCG project developers, state environmental regulator licensing officers, refinery hydrogen procurement managers, and EPC contractors with syngas integration experience, then refined against secondary validation from MEE trial license filings, Australian state environmental impact statements, CEA technical committee reports, and IEA hydrogen production roadmaps. Bottom-up project pipeline assessments triangulated with top-down energy transition spending forecasts.
Demand-supply balance modeling across the projection horizon segmented by gasifier type, application end-use, and regulatory framework cluster, with CAGRs derived from installer capacity buildout trajectories and offtake contract velocity. Modeled inputs included hydrogen certification timeline assumptions, groundwater monitoring technology adoption curves, and directional drilling cost compression rates.
Sensitivities concentrate around MEE licensing acceleration, CEA framework finalization, and EU taxonomy hydrogen certification rule changes. Forecasts reflect documented assumptions on pilot-to-commercial scaling timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
United Arab Emirates Fuel Station Market
Fuels
China LNG Market
Fuels
Catalytic Hydrothermolysis Jet [CHJ] Fuel Market
Fuels
Refuse Derived Fuel Market
Fuels
Gas Feed System Market
Fuels
South Korea LNG Bunkering Market
Fuels
Gas Hydrates Market
Fuels
Bunker Fuel Market
Fuels
Renewable Fuel Quality and Regulatory Compliance Test Instruments Market
Fuels
India Coal Market
Fuels
Gasoline As a Fuel Market
Fuels
High-Temperature Industrial Burner Market
Fuels
South America Bunker Fuel Market
Fuels
No.2 Diesel Fuel Market
Fuels
North America Commercial Aircraft Aviation Fuel Market
Fuels
Global Industrial Burner Market