
 Global Chemical Logistics Market | 2026-2036
Global Chemical Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chemical Logistics Market Foresight
Buyer concentration among pharmaceutical manufacturers is hardening as large-scale drug makers consolidate procurement under fewer global contracts. Deutsche Post DHL Group leverages its temperature-controlled network to anchor high-value pharma lanes. Kuehne + Nagel sustains competitive density through dedicated hazardous material handling certifications across European ports. A.P. Moller - Maersk competes on integrated maritime-land chemical flows, particularly in Asia-Europe corridors.
Chemical logistics encompasses the specialized transportation, storage, and handling of industrial chemicals, requiring temperature control, pressure vessels, and segregation protocols to prevent cross-contamination or reactive incidents. Tank container transportation dominates capital deployment due to asset intensity and regulatory compliance costs, while warehousing solutions command premium margins where hazardous material zoning restricts new facility permits. Third-party logistics providers lead channel share by aggregating fragmented shipper demand, though dedicated fleet services retain footholds among agrochemical producers with seasonal volume spikes.
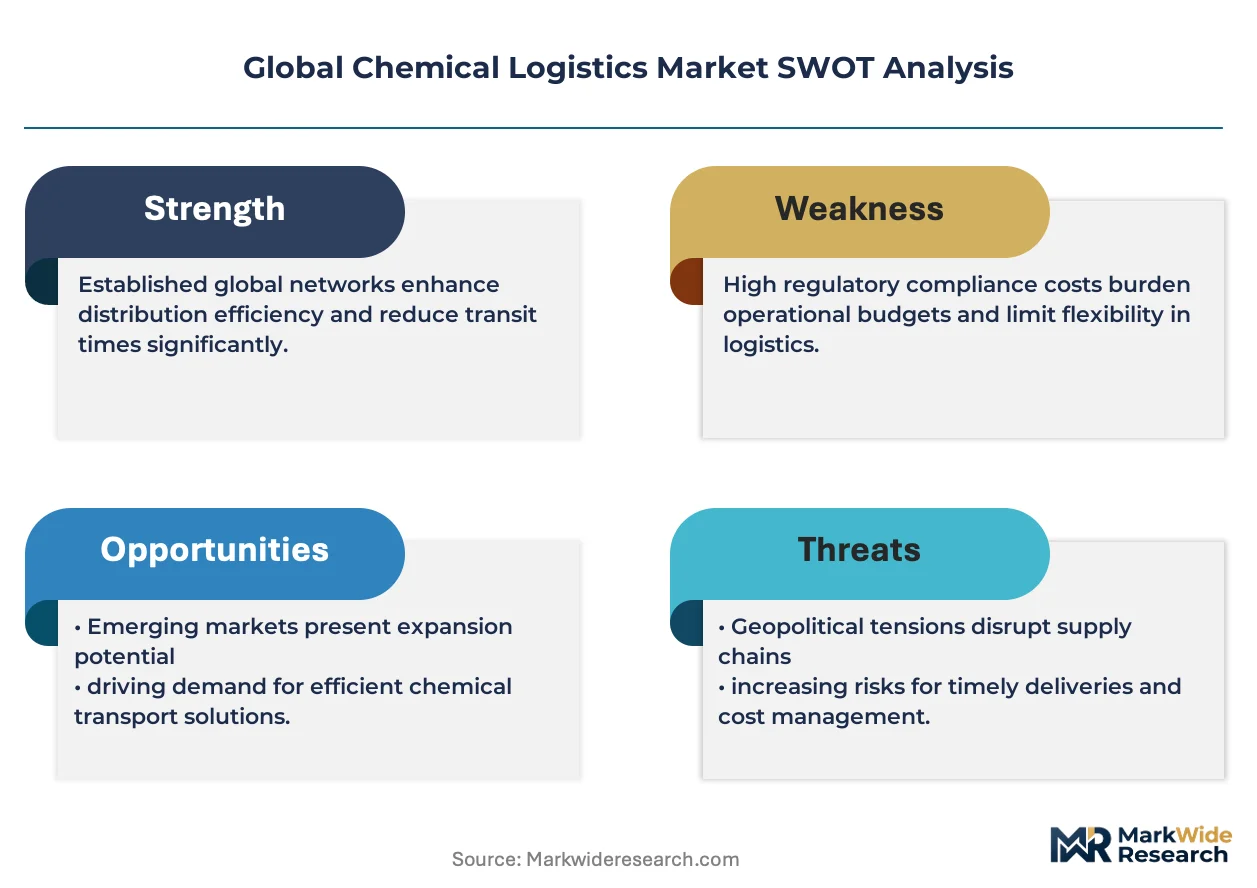
EPA hazardous waste manifest rules, REACH substance registration requirements, and IMO International Maritime Dangerous Goods codes collectively elevate compliance costs and barrier thresholds for new entrants. FDA current Good Manufacturing Practice standards for pharmaceutical logistics further segment carrier qualifications, restricting market access to certified operators. Stakeholders must monitor regulatory divergence between jurisdictions as digital tracking mandates and carbon disclosure rules reshape network design priorities.
Market Dynamics
Carrier certification requirements are tightening across multiple jurisdictions, forcing logistics providers to consolidate specialized capabilities or exit hazardous material lanes entirely. This structural pressure favors operators with pre-existing compliance infrastructure and integrated multimodal networks.
Growth Catalysts
- REACH substance registration:European chemical manufacturers are outsourcing logistics to certified third-party providers rather than building in-house hazardous material handling capabilities.
- Pharmaceutical cold chain expansion:Temperature-sensitive biologics now constitute the fastest-growing cargo category requiring validated packaging and real-time monitoring systems.
- Germany's chemical park density:The country's integrated production clusters generate concentrated intermodal freight flows that reward dedicated tank container operators.
Market Restraints
- Stainless steel tank container procurement costs:Asset intensity limits fleet expansion for mid-sized operators competing against capital-rich integrated carriers.
- Specialized driver certification scarcity:Hazardous material endorsements and dangerous goods training programs create bottlenecks in labor supply across North America and Europe.
- Facility zoning restrictions:Municipal hazardous material storage permits in the Netherlands and Belgium constrain warehouse capacity additions near major ports.
Strategic Opportunities
- India's agrochemical export corridors:Domestic formulation plants are expanding dedicated fleet partnerships to serve Southeast Asian and African markets.
- Digital freight matching platforms:Algorithmic load-board systems are reducing empty backhaul miles for tank container operators in fragmented regional lanes.
- EU Green Deal carbon disclosure mandates:Emissions tracking requirements are creating premium service tiers for logistics providers with verified Scope 3 data.
Industry Challenges
- IMO IMDG code revision cycles:Maritime dangerous goods classification updates force recurring re-certification of cargo documentation systems and crew training protocols.
- Legacy warehouse management system integration:Hazardous material inventory tracking modules require costly customization to interface with modern IoT sensor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chemical Logistics Market |
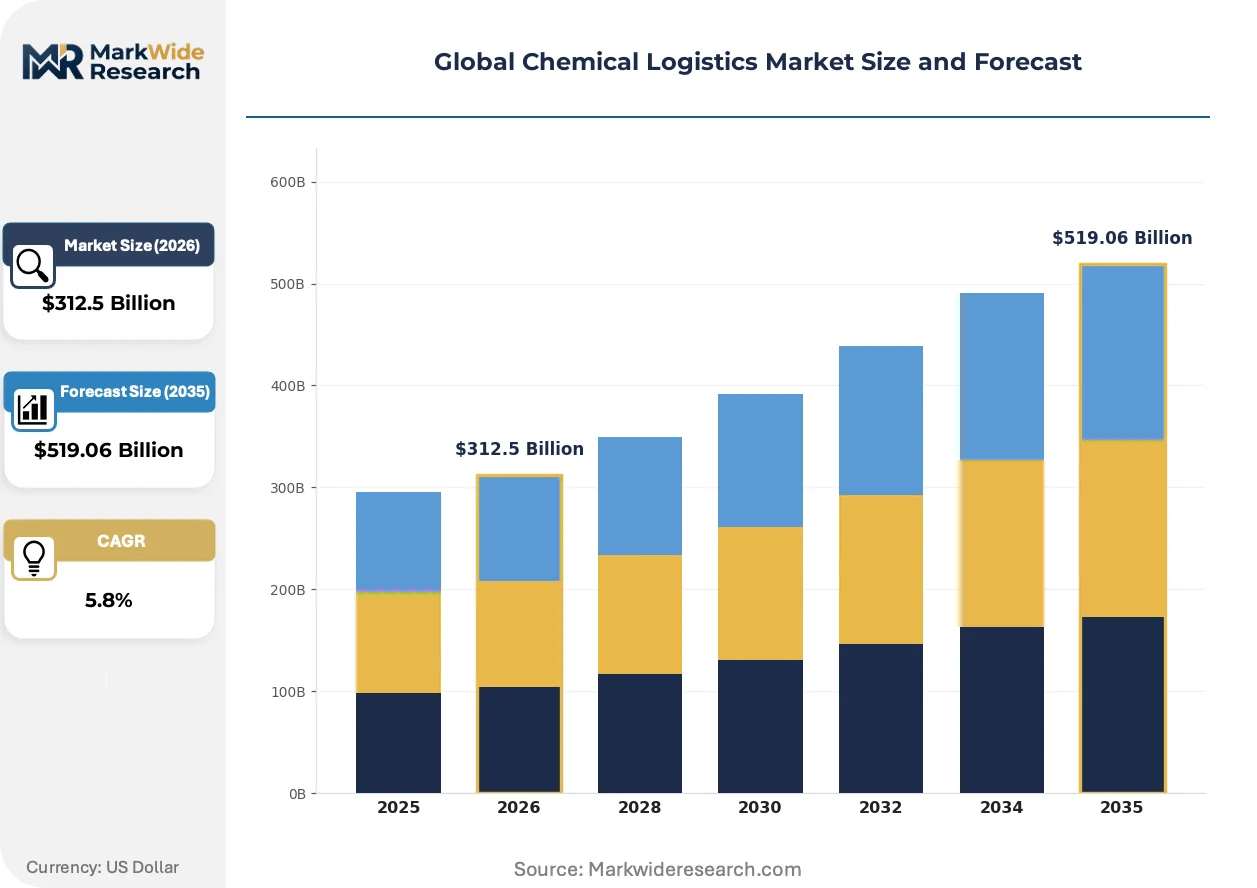
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $519.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Tank Container Transportation, Bulk Chemical Shipping, Hazardous Material Handling, Warehousing Solutions, Packaging & Labeling End User Industry: Pharmaceutical Manufacturers, Agrochemical Producers, Paint & Coatings Companies, Adhesives & Sealants Makers, Specialty Chemical Firms Packaging Type: IBC Containers, Drums, Flexible Bulk Containers, Carboys, Composite Packaging Distribution Channel: Third-Party Logistics Providers, Dedicated Fleet Services, Freight Forwarders, Rail Transport, Maritime Shipping |
| Companies Covered | Deutsche Post DHL Group, Kuehne + Nagel, A.P. Moller - Maersk, DSV, DB Schenker, HOYER Group, BDP International, C.H. Robinson Worldwide, Bertschi AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chemical Logistics Market Shifts & Advancements
Operational visibility platforms are displacing paper-based manifest systems across chemical supply chains. Real-time tracking is becoming a baseline requirement rather than a premium service tier.
Blockchain-enabled documentation is converging with customs pre-clearance protocols to compress port dwell times for hazardous cargo. Major pharmaceutical shippers in Switzerland and Singapore are mandating immutable chain-of-custody records for high-value active pharmaceutical ingredients. This technology convergence is compressing insurance premiums for certified operators while raising barriers for analog-dependent competitors.
EPA hazardous waste manifest rules are expanding electronic reporting requirements for cross-border movements between the United States and Canada. The industrial consequence is accelerated consolidation among smaller freight forwarders lacking compliance automation infrastructure. Bulk petrochemical distributors in the Gulf Coast corridor are responding by pre-qualifying carriers with integrated e-manifest capabilities.
Specialty chemical buyers are unbundling transportation from warehousing contracts to optimize working capital. Large agrochemical formulators in Brazil and Australia now tender lane-specific freight separately from storage services. This procurement fragmentation is most visible in seasonal crop protection markets where inventory financing costs exceed logistics spend.
Global Chemical Logistics Market Segmentation
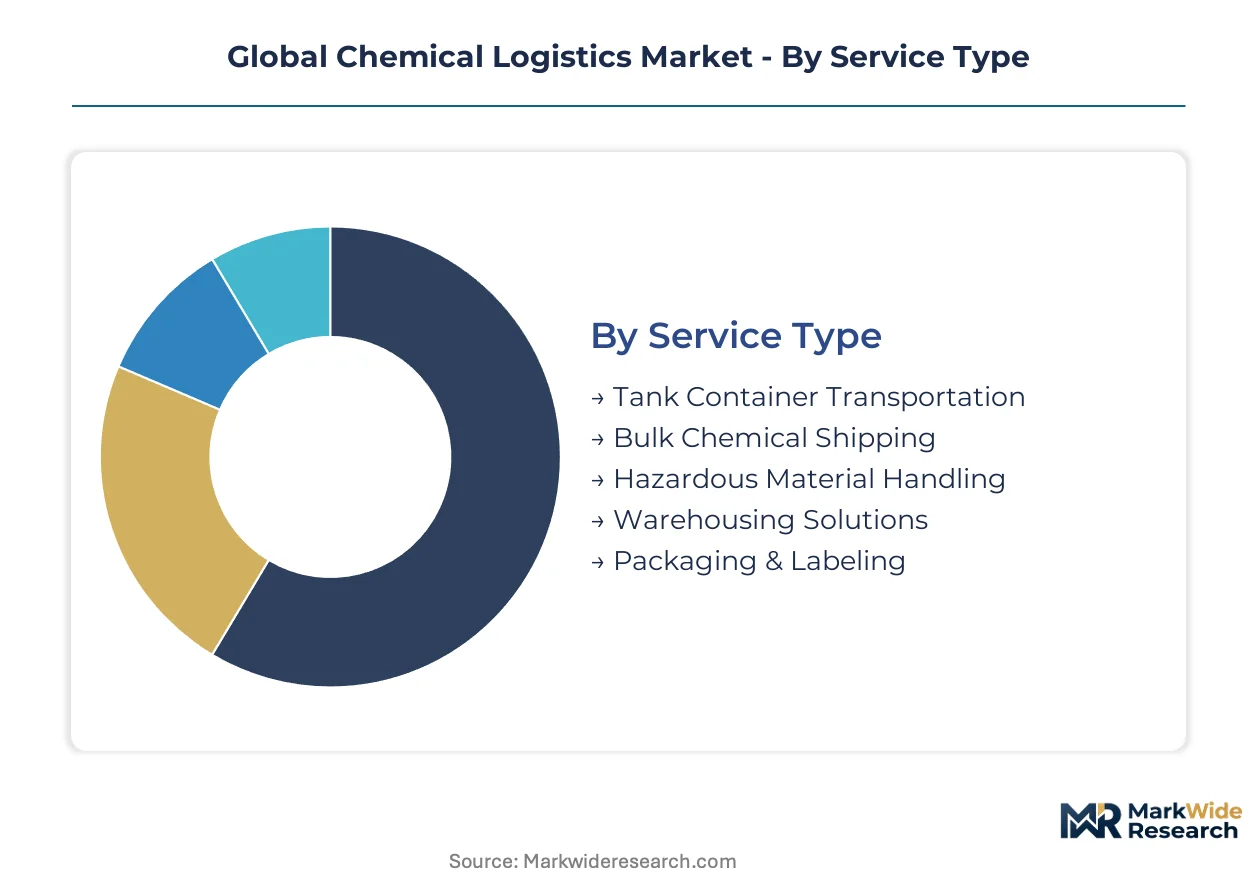
Chemical logistics segmentation reflects asset intensity and regulatory complexity. Buyers prioritize certification tiers over cost alone. Network density and hazardous material handling capabilities determine vendor selection across all service categories.
Service Type:
Buyers segment procurement by capital deployment requirements and compliance burden. Tank-intensive services command long-term contracts; variable-cost solutions suit seasonal demand.
- Tank Container Transportation:Stainless steel ISO tank units with pressure relief systems and thermal insulation handle liquid chemicals, gases, and food-grade products. Demand concentrates in Germany's chemical park clusters where BASF, Covestro, and Lanxess generate continuous intermodal flows. REACH certification requirements favor operators with pre-existing hazardous material infrastructure.
- Bulk Chemical Shipping:Parcel tankers and chemical carriers move large-volume liquid cargoes on fixed maritime routes. Asia-Europe corridors dominate tonnage as Chinese petrochemical exports expand. IMO IMDG code compliance and port state control inspections elevate carrier qualification thresholds.
- Hazardous Material Handling:Segregated storage protocols and reactive incident prevention systems for flammable, corrosive, and toxic substances. Specialized labor scarcity constrains capacity expansion.
- Warehousing Solutions:Temperature-controlled facilities with hazardous material zoning permits near Rotterdam, Antwerp, and Singapore. Municipal approval bottlenecks limit new construction.
- Packaging & Labeling:UN-certified containment and GHS-compliant hazard communication for downstream distribution. Pharmaceutical serialization mandates drive automation investment.
Volume sits with tank container transportation; growth tilts toward hazardous material handling as regulatory complexity deepens.
End User Industry:
Application-specific requirements fragment procurement patterns. Cold chain validation, seasonal volume spikes, and formulation complexity each favor different logistics architectures.
- Pharmaceutical Manufacturers:Temperature-sensitive biologics and active pharmaceutical ingredients requiring validated packaging, real-time monitoring, and chain-of-custody documentation. Swiss and Singaporean shippers mandate immutable records for high-value APIs. FDA cGMP standards and EMA GDP guidelines restrict carrier access to certified operators.
- Agrochemical Producers:Seasonal crop protection formulations with concentrated spring and autumn shipping windows. Brazil and Australian formulators unbundle transportation from warehousing to optimize working capital.
- Paint & Coatings Companies:Solvent-based and waterborne products with VOC emission controls. Regional formulation plants favor dedicated fleet partnerships.
- Adhesives & Sealants Makers:Reactive polymers and cyanoacrylates requiring moisture exclusion and temperature stability. Just-in-time delivery contracts predominate.
- Specialty Chemical Firms:High-value, low-volume products with complex handling protocols. Outsourcing accelerates as REACH registration costs escalate.
Pharmaceutical manufacturers anchor premium service tiers; specialty chemical firms are expanding most quickly as outsourcing penetration deepens.
Packaging Type:
Containment technology selection balances product compatibility, handling efficiency, and regulatory acceptance across multimodal networks.
- IBC Containers:Intermediate bulk containers with composite or steel construction for liquids and semi-solids. Chemical parks in Ludwigshafen and Antwerp generate concentrated reuse and cleaning demand.
- Drums:Steel and fiber drums for smaller batch shipments and sample distribution. Standardized dimensions enable efficient palletization.
- Flexible Bulk Containers:FIBC bags with conductive and non-conductive variants for powders and granules. Agrochemical export corridors from India favor this format.
- Carboys:Glass and plastic containers for laboratory-scale and reagent-grade chemicals. Fragility limits multimodal applicability.
- Composite Packaging:Multi-material systems combining structural strength with chemical resistance. UN performance testing requirements elevate manufacturing standards.
IBC containers dominate reusable asset pools; flexible bulk containers gain share fastest in emerging market export lanes.
Distribution Channel:
Channel selection reflects shipper scale, route complexity, and the trade-off between control and capital efficiency.
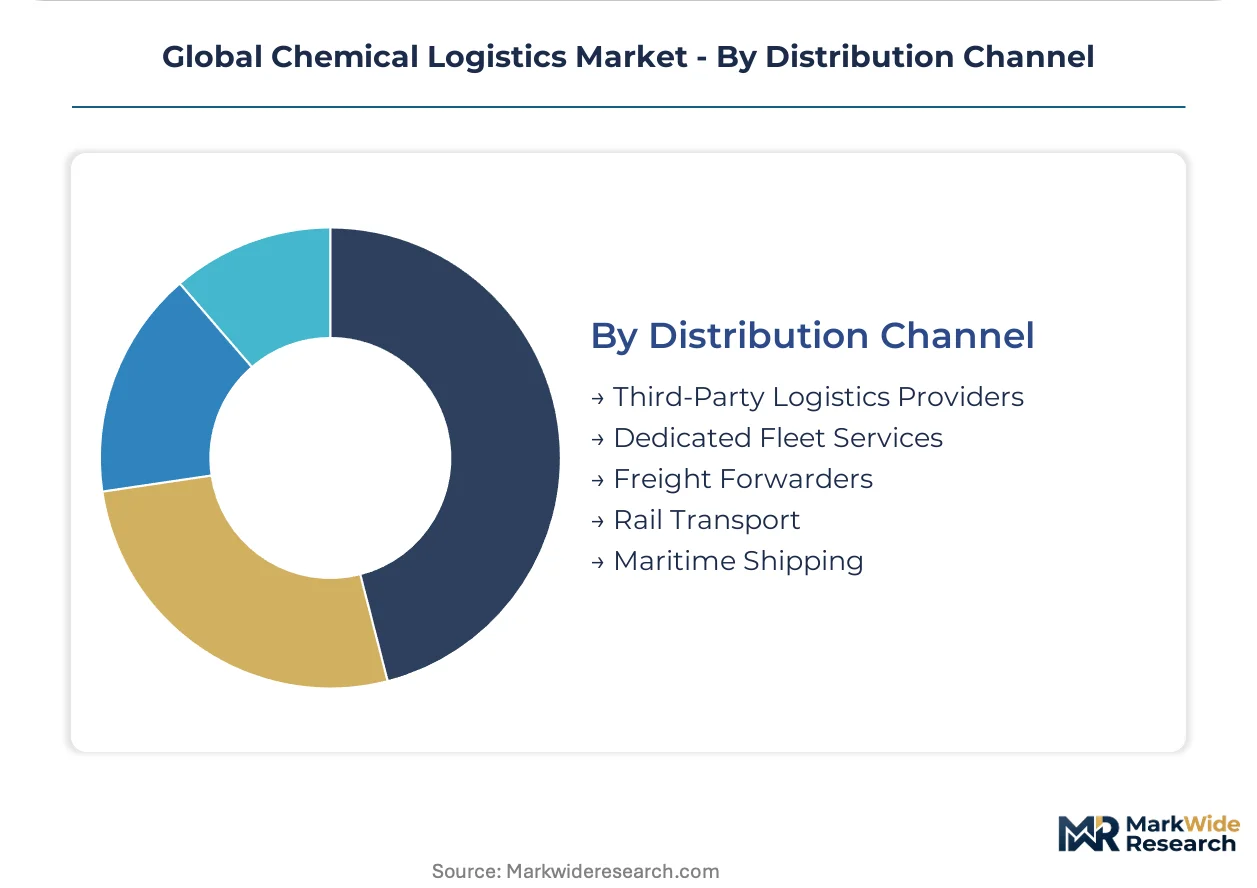
- Third-Party Logistics Providers:Aggregators of fragmented shipper demand with integrated multimodal networks and compliance infrastructure. Kuehne + Nagel's hazardous material certifications across European ports exemplify competitive positioning.
- Dedicated Fleet Services:Captive or contracted assets for high-volume, predictable flows. Agrochemical producers with seasonal spikes retain this option.
- Freight Forwarders:Non-asset intermediaries with customs brokerage and documentation expertise. Electronic manifest mandates accelerate consolidation.
- Rail Transport:Bulk liquid and dry chemical movements on dedicated tank car fleets. North American class I railroads and European combined transport operators serve this segment.
- Maritime Shipping:Deep-sea parcel tankers and chemical carriers for intercontinental flows. A.P. Moller-Maersk competes on integrated maritime-land corridors.
Third-party logistics providers hold volume leadership; dedicated fleet services defend position in seasonal agrochemical lanes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates chemical logistics demand through its dense chemical park infrastructure, while regulatory divergence between jurisdictions reshapes network investments across major producing regions.
United States
Gulf Coast petrochemical corridors and shale-derived feedstock expansion drive specialized tank container demand. EPA hazardous waste manifest rules mandate electronic reporting for cross-border movements with Canada. Houston and Beaumont anchor the nation's largest concentration of bulk liquid storage terminals.
Germany
BASF, Covestro, and Lanxess generate continuous intermodal flows through Ludwigshafen and Leverkusen chemical parks. REACH substance registration requirements favor certified third-party logistics providers over in-house capabilities. The country's integrated multimodal networks reward dedicated tank container operators with pre-existing hazardous material infrastructure.
China
Petrochemical export expansion along Asia-Europe corridors elevates maritime-land integration requirements. The Ministry of Ecology and Environment enforces dual carbon goals that reshape emissions tracking mandates. Ningbo and Shanghai port clusters concentrate parcel tanker throughput for chemical carriers.
India
Agrochemical formulation plants in Gujarat and Maharashtra expand dedicated fleet partnerships for Southeast Asian and African export markets. DGFT regulations govern hazardous chemical trade documentation. Mumbai and Mundra ports anchor the country's emerging tank container cleaning and reuse infrastructure.
Singapore
Pharmaceutical manufacturers mandate immutable chain-of-custody records for high-value active pharmaceutical ingredients. The Maritime and Port Authority enforces dangerous goods handling certifications for hub port operations. Jurong Island's integrated chemical complex generates premium cold chain validation demand for biologics shipments.
Global Chemical Logistics Market Competitive Landscape
European operators anchor the premium certification tier; North American and Asian specialists hold volume positions in regional corridors. Market structure concentrates among integrated multimodal providers with pre-existing hazardous material infrastructure, while mid-sized freight forwarders face consolidation pressure from electronic manifest mandates. Three archetypes dominate: asset-heavy tank container operators, compliance-focused third-party logistics aggregators, and pharmaceutical cold chain specialists. Competitive moves center on hazardous material certification acquisitions and carbon disclosure capability investments.
Among European-based integrated carriers, Deutsche Post DHL Group, Kuehne + Nagel, and A.P. Moller - Maersk represent distinct positioning archetypes. Deutsche Post DHL Group occupies the temperature-controlled pharmaceutical lane anchor position. Kuehne + Nagel exemplifies the compliance-density model through hazardous material handling certifications. A.P. Moller - Maersk sits within the maritime-land integration tier for intercontinental chemical flows.
| Leading Market Players |
|---|
| Deutsche Post DHL Group |
| Kuehne + Nagel |
| A.P. Moller - Maersk |
| DSV |
| DB Schenker |
| HOYER Group |
| BDP International |
| C.H. Robinson Worldwide |
| Bertschi AG |
| Others |
Supply & Pricing Matrix
Pharmaceutical manufacturer procurement consolidation under fewer global contracts is compressing margins for mid-tier logistics providers while rewarding operators with pre-existing hazardous material certifications. This buyer-side concentration forces supply response through specialized asset deployment and premium service tier investments that reshape pricing power across tank container and cold chain segments.
Pricing Analysis
Volume concentrates in contract-based long-term offtake agreements for bulk petrochemical flows, while margins concentrate in hazardous material handling and pharmaceutical cold chain validation tiers. Price differentiation hinges on REACH certification grade and real-time monitoring capability, with certified operators commanding substantial premiums over uncertified competitors. Cost compression in standard tank container lanes is intensifying because stainless steel procurement expenses and specialized driver scarcity elevate fixed costs. Agrochemical producers exhibit highest price sensitivity due to seasonal volume volatility, whereas pharmaceutical manufacturers prioritize chain-of-custody assurance over rate negotiation.
Supply Chain Analysis
Reverse-logistics flows for IBC container cleaning and reuse concentrate in Germany's Ludwigshafen and Belgium's Antwerp chemical park clusters, where dedicated tank depots handle residue processing and pressure testing. Geographic supply concentration centers on Germany, China, and the United States as dominant production hubs for chemical manufacturing and logistics infrastructure. Raw material dependencies include stainless steel for tank fabrication, specialized insulation materials for temperature-controlled units, and hazardous material zoning permits for warehouse construction. Single-source vulnerability in specialized driver certification programs across North America and Europe creates operational bottlenecks. Distribution runs through integrated third-party logistics networks with multimodal capabilities rather than fragmented freight forwarder channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as operators pursue backward control over tank container manufacturing and cleaning infrastructure to defend margin positions against certification-cost inflation.
For Market Incumbents: Anchor market position through hazardous material certification acquisitions and carbon disclosure capability investments that emerging digital-native competitors cannot replicate quickly. Consolidate specialized capabilities in Germany's chemical park corridors where zoning restrictions prevent new facility entrants. Defend against mid-sized freight forwarder disruption by automating electronic manifest compliance ahead of EPA cross-border mandate expansion. For New Entrants and Emerging Players: Enter via India's agrochemical export corridors where domestic formulation plants seek dedicated fleet partnerships for Southeast Asian and African markets. Target pharmaceutical cold chain validation services in Singapore and Switzerland where immutable chain-of-custody documentation mandates create certification barriers for established operators. Pursue digital freight matching platforms as the go-to-market angle to reduce empty backhaul miles in fragmented regional lanes. For Investors and Strategic Acquirers: The window for entry favors compliance-focused third-party logistics aggregators with pre-existing hazardous material infrastructure across multiple European ports. Long-term viability hinges on operators capable of integrating maritime-land chemical flows with verified Scope 3 emissions data for EU Green Deal alignment. Monitor IMO IMDG code revision cycles as the inflection signal—recurring re-certification demands will accelerate consolidation among analog-dependent competitors lacking compliance automation infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tank Manufacturing | Captive stainless steel container supply secures fleet expansion capacity against procurement cost inflation. |
| Hazardous Material Certification Acquisition | REACH and EPA compliance infrastructure creates barrier to entry for uncertified regional competitors. |
| Digital Freight Matching Platform Deployment | Algorithmic load-board systems compress empty backhaul miles in fragmented chemical transport lanes. |
| Carbon Disclosure Capability Investment | Verified Scope 3 data unlocks premium service tiers under EU Green Deal emissions tracking mandates. |
| Pharmaceutical Cold Chain Validation Expansion | FDA cGMP and EMA GDP certification accesses fastest-growing biologics temperature-controlled segment. |
Research Methodology
Trade databases, chemical industry association reports, and SEC regulatory filings formed the secondary backbone of this analysis, cross-referenced with primary interviews involving tank container fleet managers, pharmaceutical logistics procurement leads, hazardous material compliance officers, and European port authority dangerous goods specialists. Bottom-up and top-down triangulation validated volume estimates across service type and end-user industry segments.
Bottom-up modeling anchored forecast outputs, with top-down macroeconomic cross-checks ensuring consistency across the projection horizon. Segmentation dimensions included service type, end-user industry, packaging format, and regional production hub concentration. CAGRs were derived from trend extrapolation of certification requirement expansion rates and outsourcing penetration curves in specialty chemical and pharmaceutical verticals. Tank container fleet deployment data and electronic manifest adoption timelines served as industry-specific forecast inputs.
Revisions become necessary when IMO IMDG code implementation schedules accelerate, EPA hazardous waste manifest rules expand electronic reporting mandates beyond cross-border corridors, or EU Green Deal carbon disclosure thresholds tighten unexpectedly. Practitioners should monitor regulatory divergence between jurisdictions and specialized driver certification program expansion rates for early signals of forecast adjustment requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Europe Coal Market
Fuels
Turbine Drip Oil Market
Fuels
North America LNG Bunkering Market
Fuels
High-Temperature Industrial Burner Market
Fuels
Hydrogen Tube Trailer Market
Fuels
Multifuel Gas Turbine Market
Fuels
Compressed Natural Gas (CNG) Dispenser Market
Fuels
Gas Hydrates Market
Fuels
Asia-Pacific Bunker Fuel Market
Fuels
North America Oil and Gas Lubricants Market
Fuels
Gas and Solid Fuels (Wood) Fireplaces Market
Fuels
Europe Firewood Market
Fuels
Saudi Arabia Automotive Fuels Market
Fuels
Tire Derived Fuel Market
Fuels
South America Aviation Fuel Market
Fuels
Commercial Aircraft Aviation Fuel Market