
 United States Coal Market | 2026-2036
United States Coal Market Size, Share, and Industry Trends Forecast 2026-2036
United States Coal Market Analytics
Power generation demand from utilities is shifting toward baseload reliability roles rather than capacity expansion, altering procurement patterns for thermal coal suppliers. Peabody Energy Corp dominates Powder River Basin production through its massive surface mining complexes. Arch Resources specializes in metallurgical coal from Appalachia, supplying domestic and export steel markets. Alliance Resource Partners LP operates across the Illinois Basin, leveraging long-term utility contracts to sustain shipment volumes despite sector headwinds.
Coal in the United States comprises combustible sedimentary rock formed from compressed organic matter, with energy content ranging from sub-bituminous grades at 8,300 BTU/lb to high-volatile bituminous varieties exceeding 13,000 BTU/lb depending on rank and moisture content. Thermal coal serves electricity generation through pulverized combustion in utility boilers, while metallurgical coal undergoes coking in oxygen-starved ovens to produce carbon-dense coke for blast furnace steelmaking. Metallurgical coal commands premium pricing due to specialized coking properties and limited domestic reserves, whereas thermal coal volumes face structural compression from renewable displacement despite remaining essential for grid reliability. Rail transport retains dominance for long-haul delivery from Wyoming to Texas and Midwest markets, though barge corridors on the Ohio and Mississippi rivers serve cost-sensitive Illinois Basin producers.
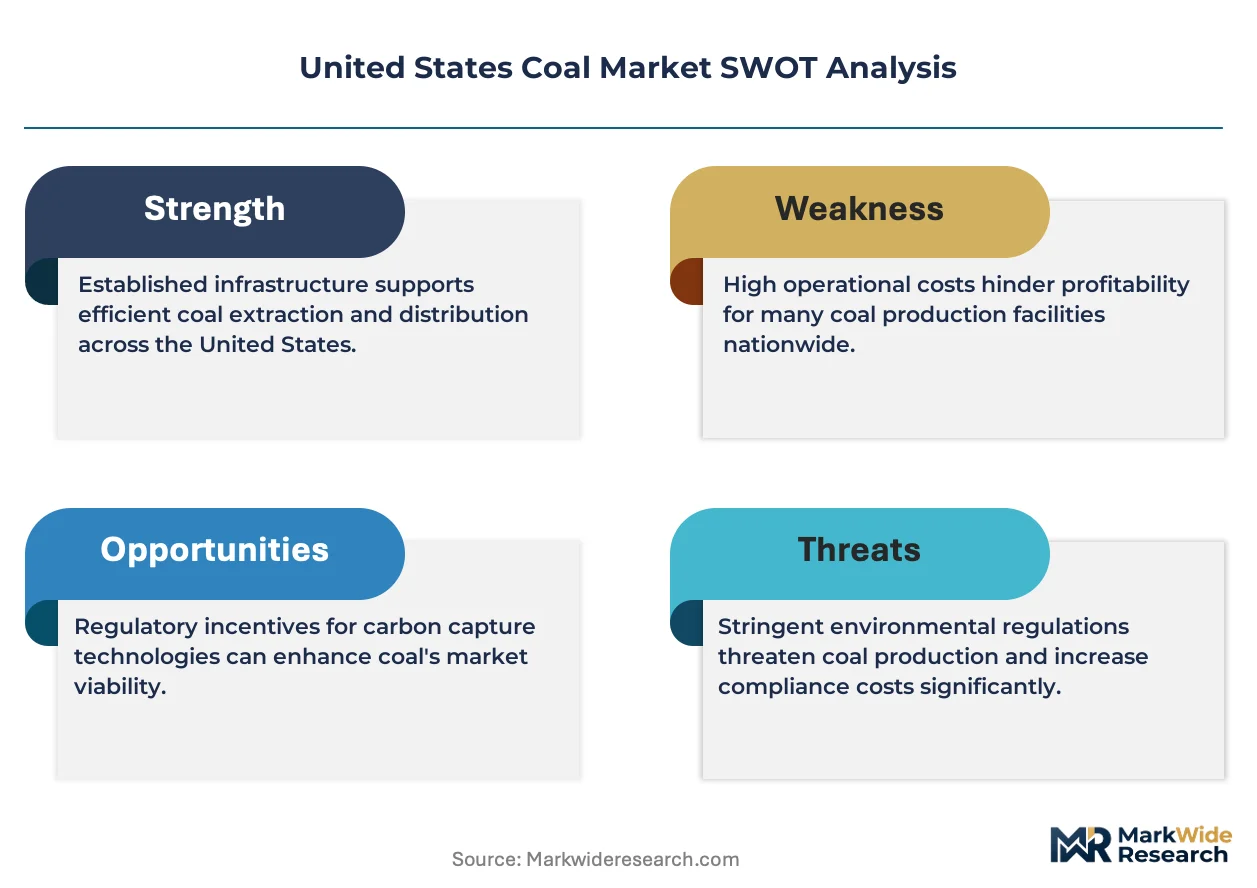
The EPA enforces emissions limits under the Clean Air Act, compelling utilities to retrofit scrubbers or retire aging coal-fired units, while FERC regulates interstate power markets that determine coal plant dispatch economics versus natural gas and renewables. OSHA mandates mine safety standards that elevate operating costs for underground Appalachian producers relative to Western surface operations. State-level renewable portfolio standards in Texas, California, and New York further constrain thermal coal demand by mandating zero-carbon electricity shares. Stakeholders must monitor the trajectory of carbon capture tax credits and EPA greenhouse gas rules for existing power plants, as these policy levers will determine whether coal retains a marginal role or faces accelerated displacement through the forecast horizon.
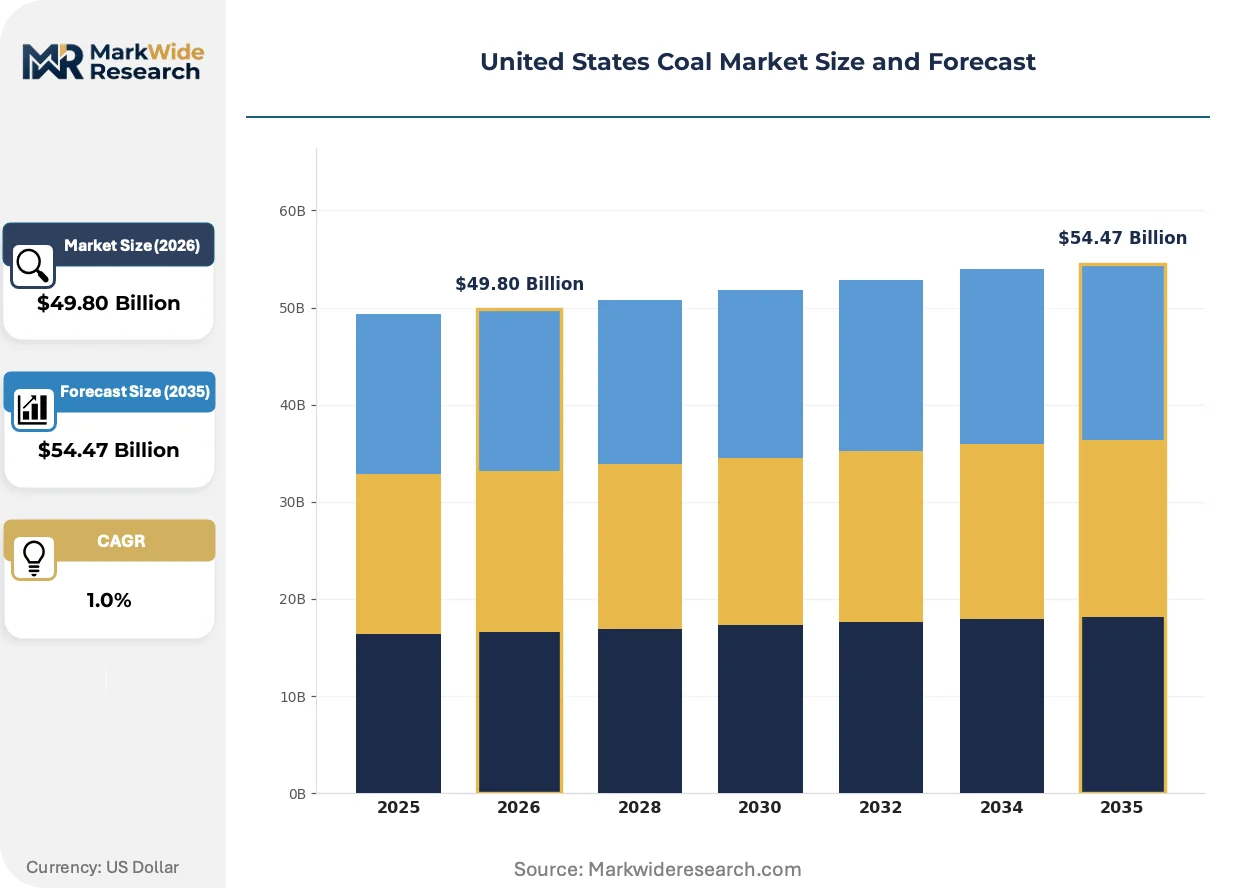
Market Dynamics
Baseload reliability contracts from grid operators are compressing thermal coal into a narrow operational niche, forcing producers to optimize for dispatch flexibility rather than volume throughput.
Growth Catalysts
- Domestic Steel Investment:Infrastructure spending sustains metallurgical coal demand from blast furnace operators. Appalachian coking coal retains irreplaceable metallurgical properties for high-strength steel.
- EPA Carbon Capture Incentives:Section 45Q tax credits reward retrofit installations at existing coal-fired plants. Wyoming producers partner with utilities to pilot post-combustion capture at Powder River Basin facilities.
- Grid Reliability Mandates:ERCOT and MISO capacity markets compensate thermal units for winter peak readiness. Texas utilities maintain coal dispatch capability against renewable intermittency.
Market Restraints
- Natural Gas Price Volatility:Henry Hub fluctuations compress coal plant dispatch economics. Combined-cycle gas turbines capture marginal generation hours in Midwest and Southeast markets.
- Renewable Portfolio Standards:California, New York, and Illinois mandates force utility procurement toward wind and solar. Thermal coal faces accelerated retirement timelines in coastal states.
- Appalachian Labor Scarcity:Underground mining skill gaps elevate operating costs versus Powder River Basin surface operations. Kentucky and West Virginia producers struggle to replace retiring workforce cohorts.
Strategic Opportunities
- Carbon Capture Retrofits:Section 45Q incentives cover capital costs for amine-based scrubber installations. Wyoming and Montana producers position low-sulfur coal as compatible with capture chemistry.
- Export Metallurgical Markets:Brazil and European steelmakers seek high-volatile coking coal from Alabama and Virginia mines. Appalachian producers expand terminal access through East Coast ports.
- Industrial Heat Applications:Cement and chemical manufacturers evaluate pulverized coal for process heat. Illinois Basin suppliers pilot direct combustion contracts outside power generation.
Industry Challenges
- Permitting Timeline Compression:NEPA environmental reviews delay mine expansion approvals. Producers face 5-7 year regulatory horizons for new surface leases.
- Rail Capacity Constraints:Union Pacific and BNSF prioritize grain and intermodal over coal unit trains. Powder River Basin producers negotiate dedicated track access against competing freight demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Coal Market |
| Market Size in 2026 | $49.80 Billion |
| Market Size in 2035 | $54.47 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Coal, Metallurgical Coal, Anthracite, Lignite End User: Power Generation, Steel Production, Cement Manufacturing, Industrial Applications Delivery Mode: Rail Transport, Barge Transport, Truck Transport, Conveyor Systems Application: Electricity Generation, Carbon Products, Fuel Production, Manufacturing |
| Companies Covered | Peabody Energy Corp, Core Natural Resources Inc, Navajo Transitional Energy Co, Alliance Resource Partners LP, Acnr Holdings Inc, NACCO Industries Inc, Alpha Metallurgical Resources Inc, Arch Resources, Vistra Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Coal Market Evolving Landscape
Carbon capture integration and dispatch optimization technologies are redefining operational viability for domestic coal assets. Producers must align technical roadmaps with evolving federal incentive structures.
Post-combustion amine scrubbing is electrifying retrofit economics at existing coal-fired units. Basin Electric Cooperative and Wyoming utilities pilot 90% capture rates at Dry Fork Station. The technology is electrifying stranded asset recovery prospects for Powder River Basin thermal producers.
EPA's greenhouse gas performance standards for existing power plants impose emission intensity benchmarks. Utilities must retrofit, co-fire with hydrogen, or retire subcritical boilers. Texas and Southeast operators face 2030 compliance horizons for aging supercritical units.
Utility procurement is consolidating around reliability-as-a-service contracts rather than fuel-specific supply agreements. Coal suppliers compete against gas and battery storage for capacity payments. MISO and PJM markets show this shift most acutely in Midwest dispatch auctions.
United States Coal Market Segmentation
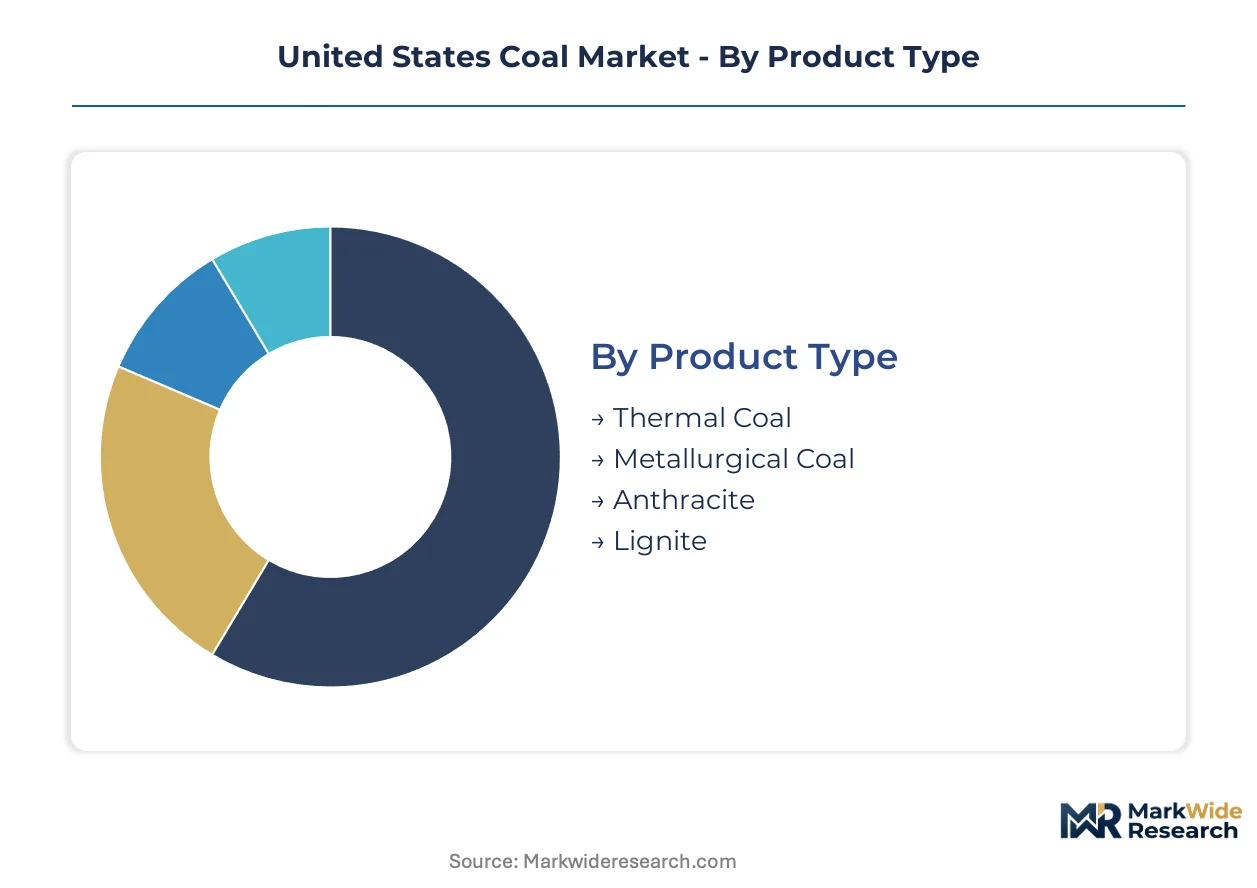
Coal market segmentation reveals how distinct physical properties and delivery economics create non-interchangeable supply chains. Producers must align mining operations with specific end-use specifications and transport infrastructure to capture value.
Product Type:
Thermal grades dominate volume while metallurgical varieties command premium pricing based on coking chemistry requirements.
- Thermal Coal:Sub-bituminous and bituminous grades with energy content from 8,300 to 13,000 BTU/lb serve pulverized combustion in utility boilers. Powder River Basin supply flows to Texas and Midwest grid operators under reliability contracts. EPA emission standards force sulfur content below 1.2% for unscrubbed units.
- Metallurgical Coal:High-volatile bituminous varieties undergo oxygen-starved coking to produce blast furnace coke. Appalachian reserves from Alabama and Virginia supply domestic steel mills and export terminals. Infrastructure spending sustains demand despite electric arc furnace displacement.
- Anthracite:Highest carbon density at 15,000 BTU/lb supports residential heating and metallurgical specialty applications in Pennsylvania.
- Lignite:High-moisture brown coal from Gulf Coast deposits serves mine-mouth power generation with limited transport radius.
Most installed capacity flows through thermal coal. Expansion is steepest in metallurgical coal.
End User:
Customer concentration varies from fragmented industrial buyers to consolidated utility procurement.
- Power Generation:Investor-owned utilities and municipal cooperatives purchase under long-term supply agreements or spot market arrangements. ERCOT and MISO grid operators compensate thermal units for capacity availability. Renewable intermittency preserves coal's dispatch role.
- Steel Production:Integrated blast furnace operators require specific coking coal blends from Appalachian reserves. Electric arc furnace growth constrains long-term demand trajectories.
- Cement Manufacturing:Kiln operators in Missouri and Pennsylvania substitute coal for petroleum coke based on relative pricing.
- Industrial Applications:Chemical and paper processors consume low-sulfur grades for process steam generation.
Utility procurement concentrates in Power Generation. Steel Production is gaining share fastest.
Delivery Mode:
Transport economics determine competitive reach for each production basin.
- Rail Transport:Unit trains from Wyoming traverse BNSF and Union Pacific corridors to Texas and Midwest markets. Dedicated track access commands premium pricing during grain harvest competition.
- Barge Transport:Ohio and Mississippi river corridors serve Illinois Basin producers with cost advantage to Gulf Coast export terminals.
- Truck Transport:Short-haul delivery from Appalachian surface mines to regional power plants and industrial boilers.
- Conveyor Systems:Mine-mouth power plants in North Dakota and Texas eliminate transport cost entirely.
Rail Transport handles the majority of tonnage. Barge Transport is expanding most quickly.
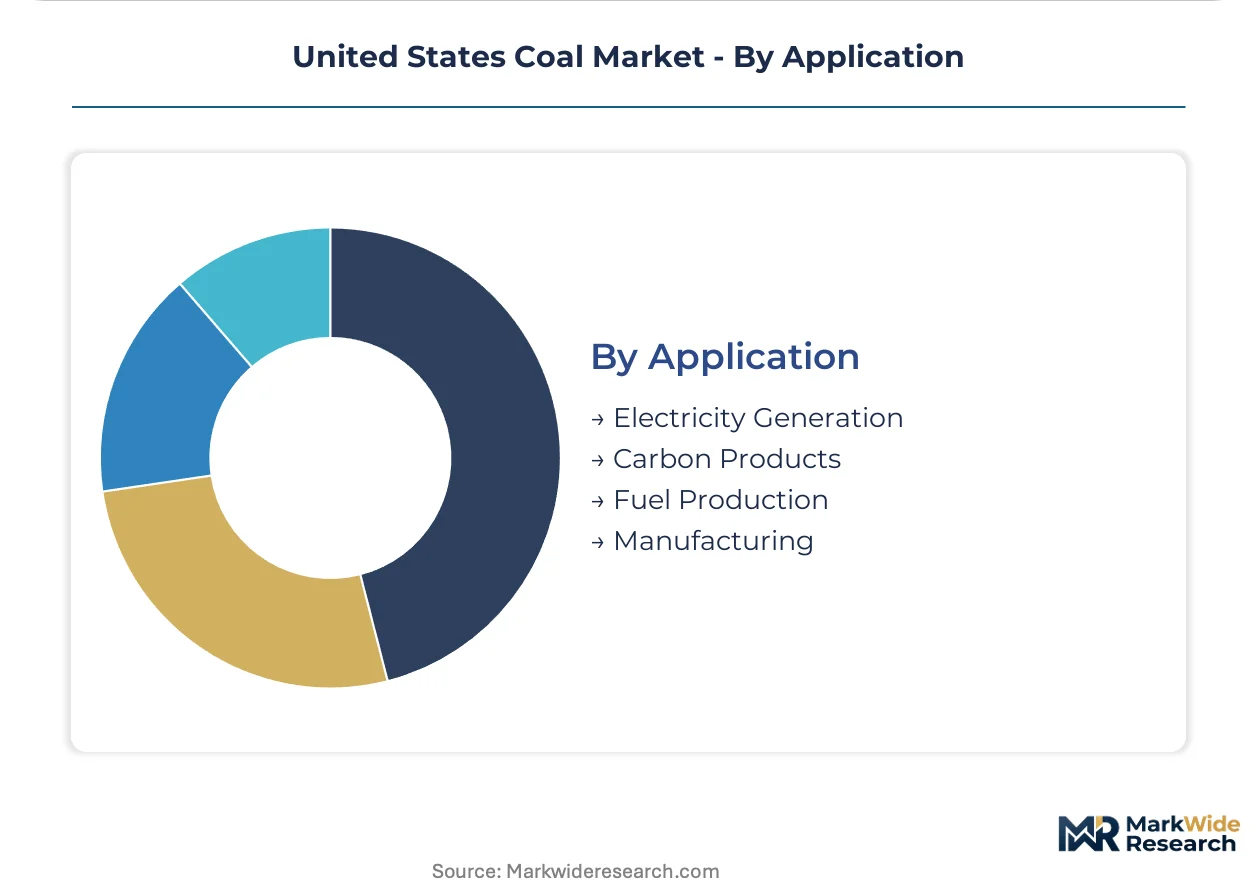
Application:
End-use specifications create divergent quality requirements and pricing structures.
- Electricity Generation:Pulverized coal combustion in subcritical and supercritical utility boilers. Wyoming sub-bituminous dominates due to low sulfur and delivered cost position.
- Carbon Products:Metallurgical coke, activated carbon, and graphite production from high-rank bituminous and anthracite reserves.
- Fuel Production:Coal-to-liquids and synthetic gas applications remain marginal without sustained oil price premiums.
- Manufacturing:Process heat for cement, lime, and chemical production using pulverized coal injection.
Electricity Generation retains the largest installed base. Carbon Products shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward basins with favorable regulatory economics. Wyoming and Montana surface operations avoid the compliance costs burdening Appalachian underground mines.
Powder River Basin
Sub-bituminous thermal coal from Wyoming and Montana supplies Texas and Midwest utilities under reliability contracts. EPA Mercury and Air Toxics Standards favor low-sulfur deposits that minimize scrubber retrofit requirements. Gillette, Wyoming anchors the nation's largest surface mining complex where Peabody Energy operates massive dragline fleets.
Appalachia
High-volatile bituminous coking coal from Alabama, Virginia, and West Virginia feeds domestic and export steel markets. OSHA underground safety mandates elevate labor costs versus Western surface operations. Birmingham, Alabama hosts integrated steel mills sourcing metallurgical blends from nearby Blue Ridge deposits.
Illinois Basin
High-sulfur bituminous coal serves regional utilities and industrial boilers through barge corridors. State renewable portfolio standards in Illinois compress long-term utility demand. The Ohio River valley around Evansville, Indiana concentrates longwall operations under long-term supply agreements.
Gulf Coast Lignite Belt
High-moisture brown coal from Texas and Louisiana supports mine-mouth power generation with minimal transport infrastructure. FERC interstate power market rules determine dispatch economics against natural gas. The Texas lignite district around Fairfield and Tatum maintains baseload capacity for ERCOT grid reliability.
United States Coal Market Competitive Landscape
Portfolio diversification dominates the current landscape as producers hedge thermal decline against metallurgical resilience. The vendor base concentrates around basin-specific specialists with irreplaceable reserve positions. Three archetypes define competitive positioning: Western surface thermal specialists, Appalachian coking coal miners, and diversified basin operators. M&A activity and carbon capture partnerships constitute the dominant competitive moves as players secure 45Q tax credit eligibility.
Among publicly traded operators, Peabody Energy Corp, Arch Resources, and Alliance Resource Partners LP occupy distinct strategic positions. Peabody anchors the Western thermal segment through Powder River Basin scale. Arch Resources exemplifies metallurgical specialization with Appalachian coking coal exposure. Alliance Resource Partners LP represents the diversified basin model spanning Illinois Basin thermal and growing metallurgical interests.
| Leading Market Players |
|---|
| Peabody Energy Corp |
| Core Natural Resources Inc |
| Navajo Transitional Energy Co |
| Alliance Resource Partners LP |
| Acnr Holdings Inc |
| NACCO Industries Inc |
| Alpha Metallurgical Resources Inc |
| Arch Resources |
| Vistra Energy |
| Others |
Value Network & Pricing Analysis
Metallurgical-thermal grade divergence separates premium Appalachian coking coal from commodity Powder River Basin thermal supply, with that bifurcation manifesting in both contract pricing structures and rail-barge logistics configurations. EPA sulfur standards and steel mill chemistry requirements lock in procurement premiums for high-volatile bituminous reserves while Wyoming sub-bituminous competes on delivered cost through unit train economics.
Pricing Analysis
Distributor margins on Illinois Basin high-sulfur coal compress under barge freight competition from Powder River Basin rail deliveries. Contract-based long-term offtake dominates utility procurement, with price differentiation driven by sulfur content grade and rail delivery cost to specific ISO nodes. Pricing pressure intensifies in thermal grades as ERCOT capacity markets favor gas turbine dispatch, while metallurgical coal retains inelastic demand from blast furnace operators. Cement and industrial buyers exhibit highest price sensitivity, switching to petroleum coke alternatives, whereas steel mills show least sensitivity due to irreplaceable coking chemistry requirements.
Supply Chain Analysis
Regional distribution centers in Chicago and St. Louis consolidate Illinois Basin barge receipts before final truck delivery to Midwest utilities. Supply concentrates in the United States exclusively, with Wyoming, West Virginia, and Alabama anchoring production. The chain draws from diesel fuel, mining equipment, and ammonium nitrate explosives as critical inputs. Single-source vulnerability emerges from Union Pacific and BNSF rail duopoly on Powder River Basin outbound capacity. Distribution runs through mine-mouth conveyor systems for Texas lignite, rail unit trains for Western thermal, and barge corridors for Illinois Basin supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States coal market represents a late-cycle quality story as baseload reliability contracts and metallurgical chemistry requirements concentrate value in premium reserve tiers. Infrastructure steel demand and carbon capture retrofit eligibility are shifting procurement toward specification-grade supply.
For Market Incumbents: Deepen vertical integration into rail logistics and terminal infrastructure to defend against gas turbine dispatch competition. Secure Section 45Q tax credit eligibility through utility partnerships at Wyoming facilities. Lock in long-term metallurgical offtake with domestic blast furnace operators before electric arc furnace displacement accelerates. For New Entrants and Emerging Players: Begin with carbon capture equipment installation and amine scrubber servicing as the most penetrable white-space adjacent to existing coal-fired units. Target Illinois Basin industrial heat applications outside power generation as underserved demand. Pursue direct combustion contracts with cement manufacturers as a go-to-market angle bypassing utility procurement consolidation. For Investors and Strategic Acquirers: Consolidation pressure builds where Appalachian labor scarcity elevates operating costs above Powder River Basin surface economics. Frame long-term viability around metallurgical specialization and carbon capture retrofit services rather than thermal volume exposure. Target surface mining specialists with low-sulfur reserve positions as acquisition archetypes. Watch EPA greenhouse gas performance standard implementation timelines as the critical inflection signal for accelerated plant retirement versus retrofit investment.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Partnership | Section 45Q tax credits unlock stranded asset recovery for Wyoming thermal producers. |
| Metallurgical Export Terminal Access | East Coast port capacity expansion captures Brazilian and European steelmaker demand. |
| Rail Logistics Integration | Union Pacific dedicated track agreements secure Powder River Basin delivery priority. |
| Industrial Heat Contract Diversification | Cement kiln direct combustion pilots reduce utility procurement dependence. |
| Mine-Mouth Power Plant Acquisition | ERCOT reliability payments anchor Texas lignite dispatch economics. |
Research Methodology
Multiple input streams — executive interviews with mine operators and utility fuel procurement officers, EIA production and consumption databases, FERC interstate power market filings, and EPA regulatory dockets — were reconciled through bottom-up reserve analysis and top-down demand triangulation. Primary fieldwork captured operational cost structures from Wyoming surface mines and Appalachian underground longwall operations. Secondary validation drew from railroad waybill samples, customs export records, and state mining agency production reports.
Data-stream reconciliation anchored volume projections to coal rank-specific demand segments across the projection horizon. The analytical framework modeled thermal versus metallurgical split, rail versus barge delivery mode, and sub-regional basin economics as core segmentation dimensions. CAGRs were derived from capacity factor assumptions for existing coal-fired units and infrastructure steel demand elasticity. Forecast inputs incorporated EPA compliance timeline scenarios and MISO capacity market clearing prices.
Several conditions sit outside the modeled scope, including unannounced federal carbon pricing legislation, breakthrough electric arc furnace technology adoption rates, and union labor action disruptions at Appalachian underground operations. Forecasts reflect documented assumptions around natural gas price bands and renewable buildout trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Oil Dispenser Market
Fuels
Marine Fuel Optimization Market
Fuels
Global Butane Gas Cartridges Market
Fuels
Italy Automotive Engine Oils Market
Fuels
Alcohol-To-Jet (ATJ) Fuel Market
Fuels
Solid Fuel Tablet Market
Fuels
India LNG Market
Fuels
Saudi Arabia Automotive Fuels Market
Fuels
India Petrol Station Market
Fuels
India Liquified Petroleum Gas (LPG) Market
Fuels
China Bunker Fuel Market
Fuels
Aviation Fuel Additives Market
Fuels
Heavy Fuel Oil Market
Fuels
Palm Methyl Ester Market
Fuels
India Bunker Fuel Market
Fuels
Global Methane Hydrate Market