
 Multifuel Gas Turbine Market | 2026-2036
Multifuel Gas Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Multifuel Gas Turbine Market Foresight
Advanced-class efficiency specifications above 60 percent combined-cycle ratings is reorganizing procurement criteria across utility buyers. General Electric leverages its HA-series turbine architecture to anchor premium positioning in large-scale power projects. Siemens Energy competes through integrated service contracts that extend lifecycle revenue beyond equipment sales. Mitsubishi Power specializes in air-cooled turbine designs that reduce water dependency in arid installations.
A multifuel gas turbine is a rotating combustion engine that converts thermal energy from multiple fuel sources—natural gas, diesel, biofuel, or hydrogen blends—into mechanical shaft power through sequential compressor, combustor, and turbine stages, typically achieving firing temperatures between 1,200°C and 1,600°C depending on blade metallurgy and cooling architecture. Its primary industrial purpose centers on grid-stabilizing power generation, mechanical drive for oil and gas compression, and marine propulsion where fuel flexibility hedges against supply disruption or price volatility. Heavy-duty turbines dominate installed capacity in baseload power generation while aero-derivative units capture fastest-growing demand for rapid-start grid balancing services. Hydrogen-capable fuel systems represent the emerging margin pool as utilities retrofit existing natural gas infrastructure for low-carbon fuel blending.
The EPA enforces stationary source emissions limits under the Clean Air Act that compel turbine operators to install selective catalytic reduction or lean-premix combustion hardware. The EU F-Gas Regulation and CE marking directives constrain refrigerant and insulation choices in turbine auxiliary systems sold across European member states. India's Central Electricity Authority mandates grid-code compliance for frequency response that favors multifuel turbines with sub-ten-minute start capabilities. Stakeholders must monitor hydrogen blending infrastructure buildout and corresponding burner retrofit standards to preserve asset valuations across evolving fuel regimes.
Market Dynamics
Grid instability across emerging economies is forcing utilities to prioritize fuel-flexible peaking capacity over baseload investments, compressing procurement cycles and elevating start-speed specifications above thermal efficiency in vendor selection criteria.
Growth Catalysts
- India's CEA Grid Code Mandates:Sub-ten-minute frequency response requirements compel state utilities to procure multifuel turbines capable of black-start operations and rapid ramping.
- Hydrogen Infrastructure Buildout:Pilot blending projects in Germany and Japan create retrofit demand for dry low-NOx combustors rated above 30 percent hydrogen by volume.
- Aero-Derivative Turbine Adoption:Independent power producers favor LM6000 and FT8-class units for distributed generation sites requiring sub-15-minute synchronization.
Market Restraints
- Superalloy Supply Concentration:Single-crystal blade casting capacity concentrates in the US and Japan, creating 18-month lead times for hot-section components.
- EPA NSPS Emission Compliance:Selective catalytic reduction retrofits add $8-12 per kW to installed costs for pre-2015 turbine fleets.
- Electrochemical Storage Substitution:Lithium-ion battery peaking plants now undercut gas turbines on 2-4 hour dispatch economics in markets with carbon pricing.
Strategic Opportunities
- Southeast Asia Island Grids:Indonesia and Philippines utilities lack interconnection redundancy, creating captive demand for diesel-natural gas bivalent units.
- EU Hydrogen Bank Financing:The €3 billion instrument subsidizes H2-ready turbine conversions at refineries and chemical clusters.
- Digital Twin Convergence:Physics-based modeling combined with operational data streams enables predictive maintenance contracts that capture 15-year service revenue.
Industry Challenges
- Combustion Engineering Talent Scarcity:Fewer than 200 specialists globally possess expertise in hydrogen flame stabilization and flashback suppression.
- Legacy Control System Integration:1990s-era DCS architectures in existing plants require complete replacement to accommodate advanced emissions monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multifuel Gas Turbine Market |
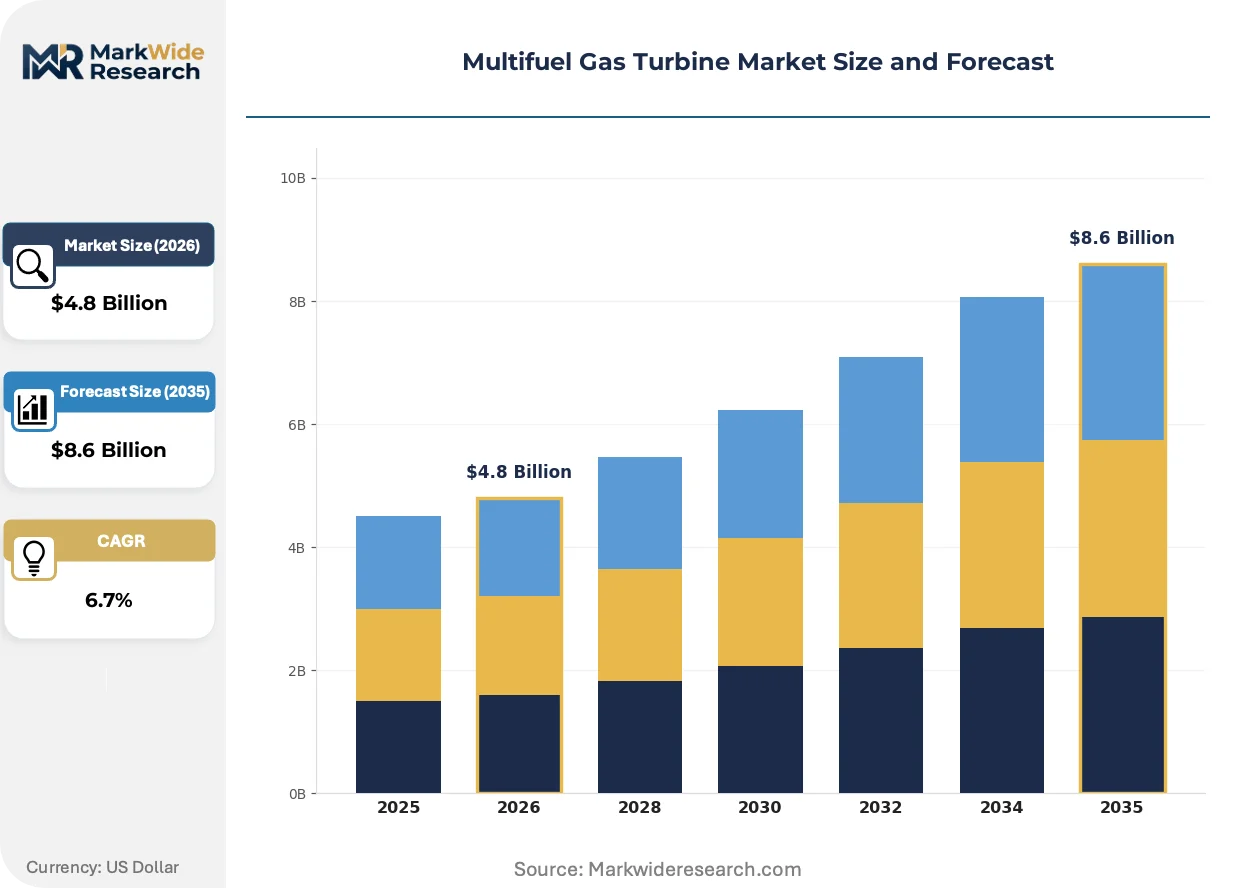
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty Turbines, Aero-Derivative Turbines, Micro Turbines, Industrial Turbines Fuel Type: Natural Gas, Diesel, Biofuel, Hydrogen Application: Power Generation, Oil & Gas, Marine, Industrial End User: Power Utilities, Manufacturing Companies, Shipping Industry, Independent Power Producers |
| Companies Covered | General Electric, Siemens Energy, Mitsubishi Power, Ansaldo Energia, Solar Turbines, Kawasaki Heavy Industries, MAN Energy Solutions, Doosan Enerbility, Capstone Green Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multifuel Gas Turbine Market Shifts & Advancements
Additive manufacturing of nickel superalloy turbine blades is collapsing production timelines and enabling geometries impossible through conventional investment casting. Three converging developments are restructuring competitive advantage.
Dry low-emissions combustor technology is miniaturizing from heavy-frame to aero-derivative platforms, allowing sub-50 MW units to achieve sub-9 ppm NOx without water injection. Packaged power plant developers in Texas and Alberta are specifying these systems for wellhead gas monetization. The compression of emissions hardware into smaller footprints is eliminating the historical trade-off between start speed and environmental compliance.
EPA's updated New Source Performance Standards for stationary gas turbines tighten NOx limits to 25 ppm for new units above 25 MW. The rule forces OEMs to certify lean-premix or catalytic combustion systems across their product ranges. Combined-cycle projects in California and Texas now front-load emissions guarantee negotiations before equipment selection.
Power purchase agreement structures are unbundling energy and capacity payments, exposing turbine operators to merchant price risk. Merchant plant developers in PJM and ERCOT are prioritizing fuel-switching capability over heat-rate optimization. This behavioral shift elevates dual-fuel systems in developer rankings even where natural gas supply appears secure.
Multifuel Gas Turbine Market Segmentation
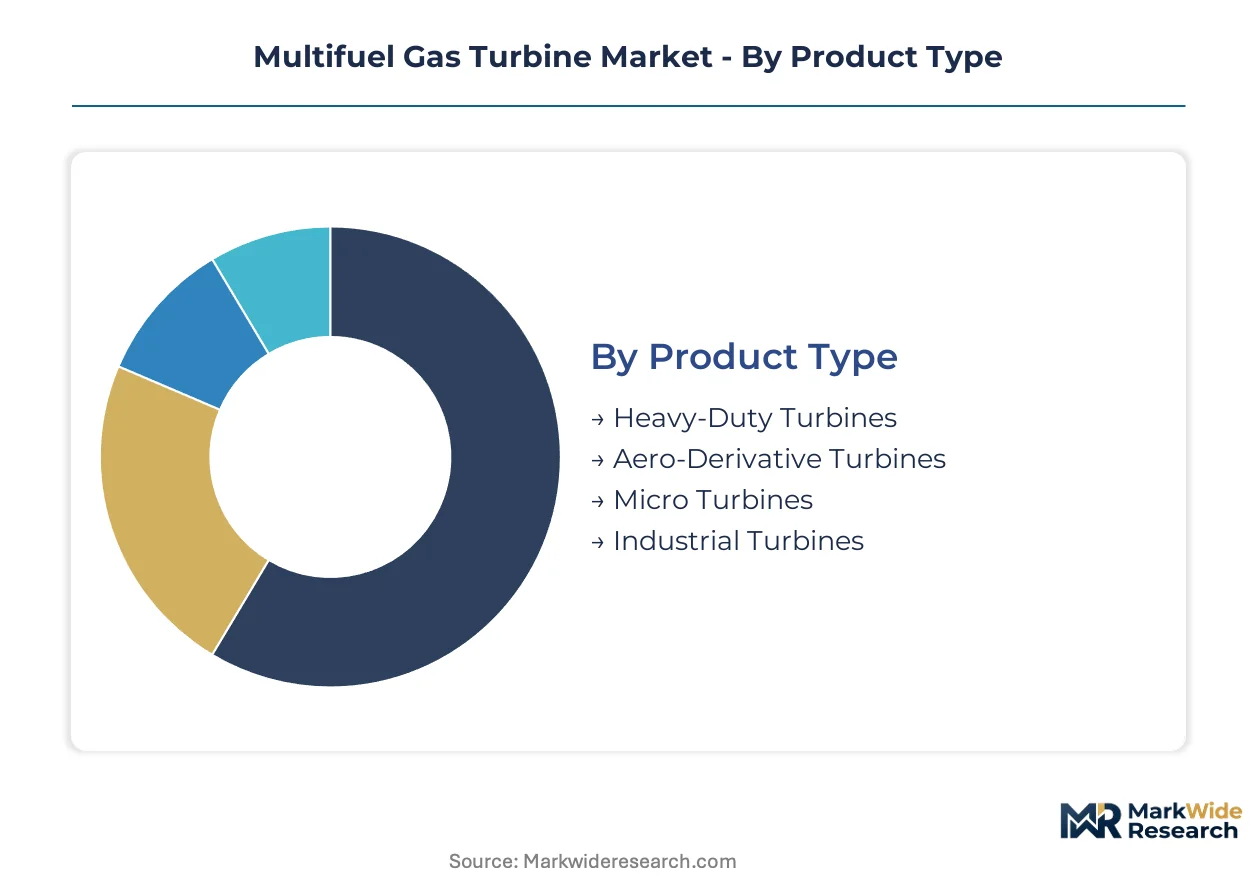
Multifuel gas turbine segmentation reveals divergent margin structures across product architectures and fuel systems. Procurement criteria vary sharply between baseload utilities prioritizing efficiency metrics and distributed generators demanding start-speed flexibility.
Product Type:
Margin pools concentrate in heavy-duty and aero-derivative platforms where aftermarket service contracts extend revenue visibility beyond equipment sales.
- Heavy-Duty Turbines:These frame-type units achieve firing temperatures above 1,500°C through advanced blade cooling and thermal barrier coatings. Demand concentrates in India's state-owned utilities procuring 100+ MW blocks for grid stabilization under CEA frequency response mandates. OEMs anchor profitability through 15-year long-term service agreements covering hot-section refurbishment cycles.
- Aero-Derivative Turbines:Aviation-heritage designs deliver sub-ten-minute start capabilities through lightweight rotors and modular construction. Independent power producers in Texas and Alberta favor LM6000-class units for wellhead gas monetization where dispatch economics favor rapid cycling over baseload efficiency.
- Micro Turbines:Sub-500 kW units serve distributed commercial and industrial loads with combined heat and power configurations.
- Industrial Turbines:Mechanical drive applications in pipeline compression and refinery processes emphasize torque characteristics over electrical output optimization.
Heavy-Duty Turbines hold installed capacity. Aero-Derivative Turbines are rotating up the share rankings.
Fuel Type:
Customer procurement patterns split between established natural gas infrastructure and emerging hydrogen blending requirements.
- Natural Gas:Pipeline-connected utilities specify dry low-NOx combustors achieving sub-25 ppm emissions without water injection. India's GAIL network expansion and US shale basins anchor demand concentration where supply security supports long-term power purchase agreements.
- Hydrogen:Pilot blending projects in Germany and Japan drive retrofit demand for burners rated above 30 percent H2 by volume. EU Hydrogen Bank financing subsidizes conversions at refineries and chemical clusters, creating margin expansion for OEMs with certified H2-ready systems.
- Diesel:Bivalent diesel-natural gas configurations serve island grids in Indonesia and Philippines lacking interconnection redundancy.
- Biofuel:Renewable liquid fuels from agricultural waste streams gain traction in European markets under RED III sustainability criteria.
Natural Gas dominates current procurement volumes. Hydrogen is gaining share fastest among forward-looking utility capex plans.
Application:
End-use differentiation centers on dispatch duration requirements and emissions exposure under carbon pricing regimes.
- Power Generation:Combined-cycle configurations above 400 MW target 60 percent-plus efficiency ratings for baseload operation. California and Texas developers front-load EPA NSPS compliance negotiations before equipment selection, elevating emissions guarantee terms in vendor contracts.
- Oil & Gas:Mechanical drive applications in upstream compression and LNG liquefaction prioritize fuel flexibility over heat-rate optimization. Merchant developers in carbon-priced markets favor dual-fuel capability to hedge against natural gas price volatility.
- Marine:IMO 2020 sulfur regulations and EEDI efficiency indices compel vessel operators toward LNG-diesel bivalent propulsion systems.
- Industrial:Cogeneration installations at chemical and paper facilities exploit waste heat recovery for process steam supply.
Power Generation commands the largest equipment revenue pool. Oil & Gas applications show the steepest expansion trajectory as upstream investment revives.
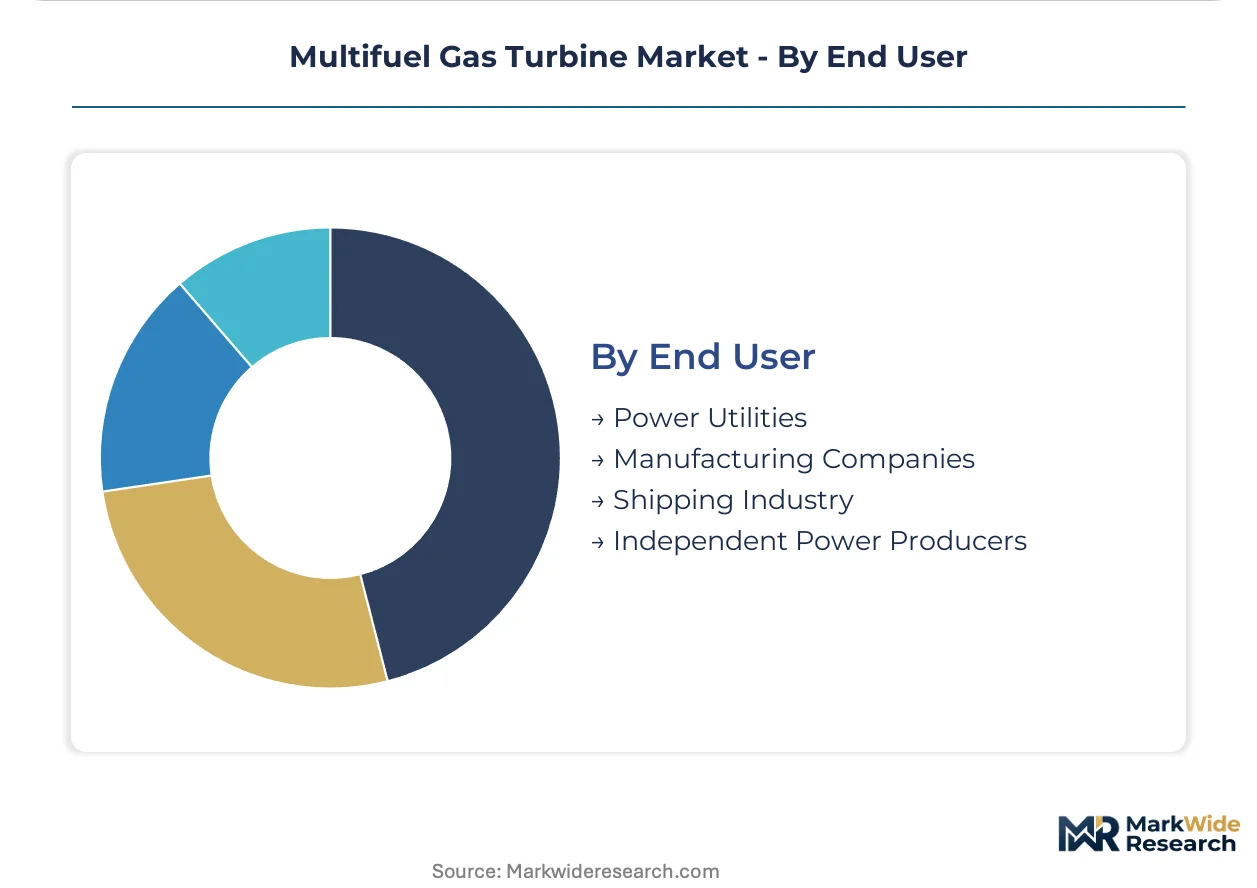
End User:
Buyer sophistication varies across centralized procurement offices and distributed project development entities.
- Power Utilities:State-owned generators in India and vertically integrated utilities in the US Gulf Coast specify black-start capability and grid-code compliance as non-negotiable technical requirements. Procurement cycles compress as frequency instability accelerates investment timelines.
- Independent Power Producers:Merchant developers in PJM and ERCOT unbundle energy and capacity payments, exposing operators to price risk that elevates fuel-switching specifications in equipment rankings.
- Manufacturing Companies:Captive power installations at steel and cement facilities emphasize reliability over efficiency given grid supply intermittency.
- Shipping Industry:Container line operators and LNG carriers specify propulsion systems meeting EEXI carbon intensity benchmarks.
Power Utilities retain the dominant share of heavy-frame turbine orders. Independent Power Producers are climbing fastest in aero-derivative procurement rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German turbine OEMs export hydrogen-ready combustion systems to Japanese utilities retrofitting combined-cycle plants for 30 percent H2 blending. This trade corridor reflects divergent regional decarbonization timelines and equipment upgrade cycles.
United States
Texas and California developers front-load EPA NSPS compliance negotiations before equipment selection, elevating emissions guarantee terms in vendor contracts. PJM and ERCOT merchant operators unbundle energy and capacity payments, exposing turbine owners to price volatility that prioritizes fuel-switching capability. The Permian Basin anchors aero-derivative demand for wellhead gas monetization.
India
State utilities under CEA frequency response mandates compress procurement cycles for sub-ten-minute start capability. GAIL pipeline expansion into eastern states enables natural gas-fired peaking capacity where grid instability drives investment. Maharashtra and Gujarat host the largest concentration of heavy-duty turbine installations serving industrial load centers.
Germany
EU Hydrogen Bank financing subsidizes H2-ready conversions at refineries and chemical clusters in the Rhine-Ruhr industrial corridor. The F-Gas Regulation constrains refrigerant choices in auxiliary systems sold across member states. Pilot blending projects in Lower Saxony drive retrofit demand for dry low-NOx combustors.
Japan
METI hydrogen roadmap targets 30 percent ammonia co-firing by 2030, compelling utilities to procure turbines with certified fuel-flexible combustion systems. Chubu Electric and JERA anchor demand concentration in the Nagoya and Tokyo metropolitan load centers. Single-crystal blade casting supply from domestic foundries creates 18-month lead times for hot-section components.
Indonesia
Island grid operators lacking interconnection redundancy specify diesel-natural gas bivalent units for captive peaking capacity. Java-Bali system instability accelerates procurement of rapid-start aero-derivative systems. Pertamina and PLN dominate utility-scale procurement for distributed generation sites.
Multifuel Gas Turbine Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and long-term service contracting. The market structure concentrates around three OEMs controlling heavy-frame turbine architecture while aero-derivative and micro-turbine segments fragment across aviation-heritage and industrial specialists. Strategic archetypes include integrated energy conglomerates with captive power generation, aviation-derivative specialists leveraging jet engine platforms, and industrial turbine fabricators serving mechanical drive applications. Dominant competitive moves center on 15-year service agreement extensions and hydrogen combustion certification partnerships.
Within the integrated conglomerate tier, General Electric and Siemens Energy exemplify scale-driven positioning through combined-cycle project bundling and lifecycle revenue capture. Mitsubishi Power occupies a distinct position in air-cooled turbine designs serving arid installations. These three anchors represent divergent approaches to the hydrogen transition—each pursuing differentiated combustion architecture and regional certification strategies without overlapping technology licensing.
| Leading Market Players |
|---|
| General Electric |
| Siemens Energy |
| Mitsubishi Power |
| Ansaldo Energia |
| Solar Turbines |
| Kawasaki Heavy Industries |
| MAN Energy Solutions |
| Doosan Enerbility |
| Capstone Green Energy |
| Others |
Supply & Pricing Matrix
Foundry utilization rates above 85 percent at precision casting facilities in the US and Japan compress blade delivery schedules and anchor price floors for heavy-frame turbine hot sections. This capacity discipline cascades through OEM pricing power, long-term service agreement structures, and independent power producer procurement timelines across emerging markets.
Pricing Analysis
Next-generation hydrogen-capable combustion systems command 15-25 percent premiums over legacy natural gas configurations, while prior-generation frame units face accelerated depreciation as utilities front-load emissions compliance negotiations. Project-based equipment procurement dominates, with price differentiation anchored in firing temperature ratings and guaranteed availability terms rather than base hardware costs. Cost compression in standard heavy-duty tiers intensifies as Chinese fabricators enter mid-capacity segments, though superalloy supply constraints limit downward pressure at the premium end. Merchant developers in Texas and Alberta exhibit highest price sensitivity, prioritizing fuel-switching flexibility over efficiency optimization in vendor rankings.
Supply Chain Analysis
Strait of Malacca transit underwrites nickel and cobalt feedstock flows to single-crystal blade foundries in Japan and the US, where casting capacity concentrates for hot-section components. Superalloy ingot production draws from Australian and Indonesian nickel mines, while rhenium supply rests on Chilean molybdenum byproduct extraction. Single-source vulnerability pervades precision casting equipment, where German and Swiss machine tool builders control electron beam and vacuum induction systems. Distribution runs through OEM-direct channels for heavy-frame units and specialized EPC contractors for aero-derivative packaged plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
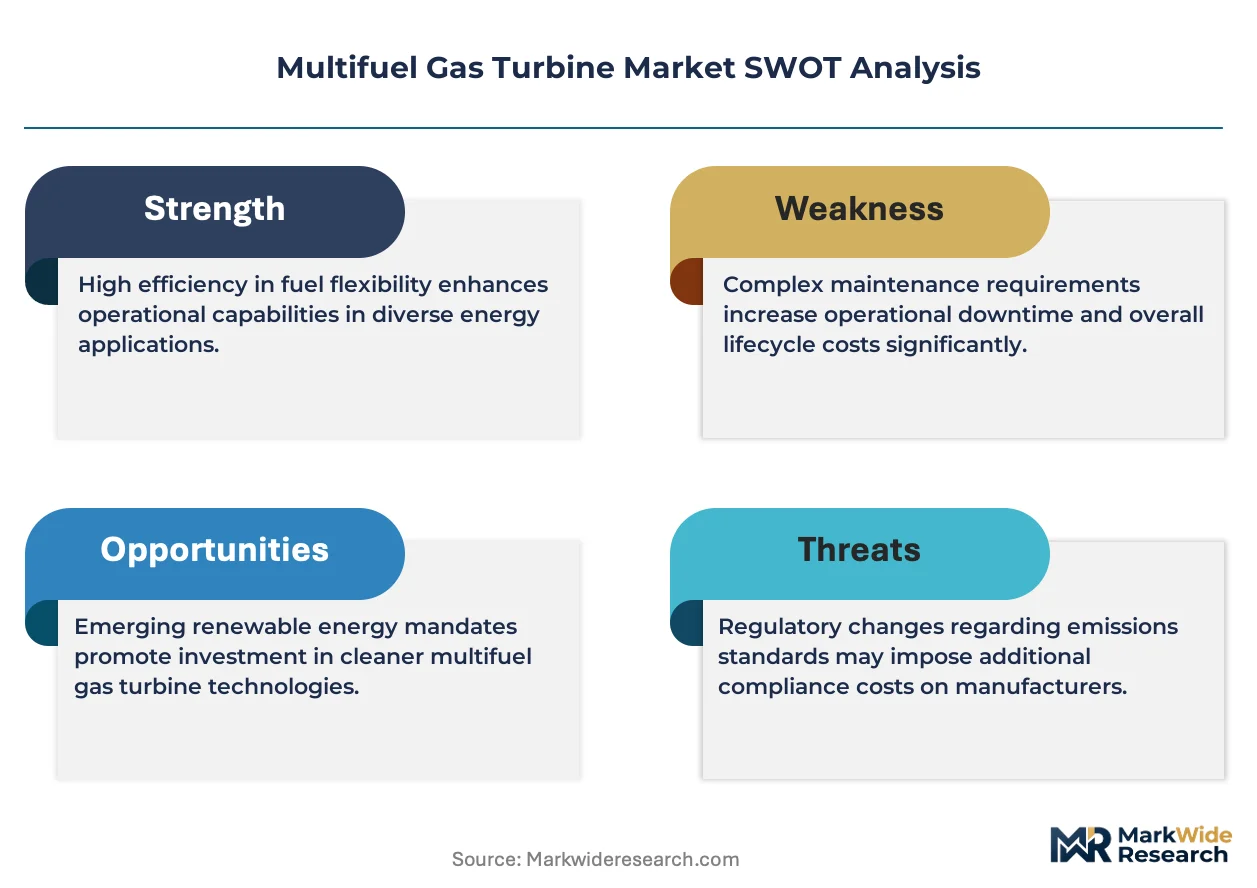
This market functions as a defensive-moat story where regulatory entrenchment around emissions certification and 15-year service agreement lock-in creates substantial switching costs for utility buyers.
For Market Incumbents: Fortify hydrogen combustion certification pipelines ahead of EU Hydrogen Bank disbursement timelines, while deepening captive casting capacity through joint ventures with Japanese superalloy foundries. Electrochemical storage substitution in 2-4 hour peaking applications threatens aero-derivative margins in carbon-priced markets, demanding accelerated dry low-NOx miniaturization to preserve technology differentiation. For New Entrants and Emerging Players: Predictive maintenance analytics for legacy turbine fleets represents a service-layer gap where incumbents under-serve independent power producers with 1990s-era control architectures. Southeast Asian island grids lacking interconnection redundancy offer the most penetrable geography, with diesel-natural gas bivalent retrofits creating equipment-plus-fuel-supply bundling opportunities against pure OEM competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors combustion engineering specialists with certified hydrogen blending capabilities above 30 percent by volume. Long-term viability hinges on retrofit demand persistence as utilities delay greenfield capex in favor of existing asset extensions. Watch hydrogen pipeline injection standards as the critical inflection signal for capital reallocation toward H2-ready system providers.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Combustion Certification | EU Hydrogen Bank financing eligibility hinges on OEM-verified H2-ready burner testing protocols. |
| Single-Crystal Casting Capacity Expansion | Japanese and US foundry investments compress 18-month blade delivery timelines for utility procurement cycles. |
| Digital Twin Platform Deployment | Physics-based modeling combined with operational data streams anchors 15-year predictive maintenance contracts. |
| Retrofit Control System Integration | Legacy DCS replacement for emissions monitoring compliance unlocks aftermarket revenue in 1990s-era installations. |
| Island Grid Fuel Supply Bundling | Indonesia and Philippines utilities prioritize diesel-natural gas bivalent vendors with captive fuel logistics capabilities. |
Research Methodology
A spread of perspectives from utility planning officers, independent power producer project developers, EPC contractors, and aftermarket service heads converged on the working assumptions around procurement cycle compression and hydrogen blending infrastructure timelines. Primary fieldwork combined structured interviews with secondary validation through EIA power plant databases, IEA technology roadmaps, FERC interconnection queue filings, and EPA New Source Performance Standards regulatory dockets. Bottom-up unit economics for turbine deployments across capacity tiers were triangulated against top-down market sizing from equipment manufacturer order backlogs and regional grid investment plans.
Segmentation dimensions modeled encompass fuel source flexibility, generation capacity tier, project scale archetype, regulatory framework cluster, and regional grid instability index across the projection horizon. CAGRs were derived from installed capacity buildout trajectories, replacement demand curves for pre-2015 fleets facing EPA compliance deadlines, and hydrogen retrofit penetration assumptions tied to EU Hydrogen Bank disbursement schedules. Forecast inputs incorporated superalloy supply lead times, CEA frequency response mandate enforcement intensity, and lithium-ion battery peaking cost curves in carbon-priced markets.
Material uncertainties — hydrogen pipeline injection standard finalization, single-crystal casting capacity expansion decisions, and electrochemical storage cost trajectories — sit outside the modeled envelope and could materially revise equipment demand projections. Practitioners should keep alternative scenarios live as EU Hydrogen Bank financing uptake rates and Indian state utility procurement acceleration timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
North America LNG Bunkering Market
Fuels
Europe Commercial Aircraft Aviation Fuel Market
Fuels
Refuse Derived Fuel Market
Fuels
Fuel Oxygenate Market
Fuels
Underground Coal Gasification Market
Fuels
Charcoal Briquette Market
Fuels
Hydrogen Tube Trailer Market
Fuels
Hybrid Propellants Market
Fuels
United Kingdom Chemical Logistics Market
Fuels
Gasoline Octane Improvers Market
Fuels
Fuel Grinder Market
Fuels
Oil Dispensing Stations Market
Fuels
Renewable Heating Fuels Market
Fuels
Synthetic Natural Gas (SNG) Market
Fuels
CNG Dispenser Market
Fuels
Gas Hydrates Market