
 Digital Energy Platform Market | 2026-2036
Digital Energy Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Energy Platform Market Insights
Industrial energy buyers are unwinding decades of reliance on passive utility relationships and instead procuring direct platform access for real-time load optimization. Schneider Electric leverages its distributed energy resource software stack to anchor enterprise microgrid deployments across manufacturing corridors. Siemens competes through deep domain integration in building automation and grid-edge analytics. Honeywell sustains relevance with cross-sector IoT platforms that unify facility energy data with carbon accounting workflows.
A digital energy platform integrates software layers for metering, forecasting, dispatch, and market settlement across distributed generation, storage, and demand assets, typically processing telemetry at sub-second intervals to maintain grid stability. These systems orchestrate multi-directional power flows and price signals to minimize curtailment and maximize asset utilization. Cloud-based deployment leads current adoption among utilities seeking elastic compute for seasonal demand spikes, while edge computing segments grow fastest where latency constraints govern protection and control decisions. Artificial intelligence and data analytics concentrate margin pools as buyers prioritize predictive load forecasting over basic monitoring dashboards.
The EU Green Deal and F-Gas Regulation reshape product standards by mandating granular emissions traceability and refrigerant lifecycle accountability in connected thermal systems. The EPA and FERC in the United States impose parallel requirements through greenhouse gas reporting rules and wholesale market participation protocols for aggregated distributed resources. Stakeholders must decide whether to build in-house platform governance or embed third-party compliance modules as regulatory fragmentation deepens across jurisdictions.
Market Dynamics
Utility procurement of AI-enabled grid management systems concentrates vendor relationships around platforms that embed real-time telemetry processing and automated dispatch, compressing traditional equipment supply chains into software-centric orchestration layers.
Growth Catalysts
- EU F-Gas Regulation:Mandates refrigerant lifecycle accountability in connected thermal systems, forcing facility operators to adopt digital platforms with granular emissions traceability.
- Industrial clusters in Germany:Manufacturing corridors anchor early deployment of hybrid cloud-energy orchestration platforms, creating reference architectures for adjacent European markets.
- Sub-second telemetry processing:Edge computing capabilities enable protection and control decisions at latencies cloud infrastructure cannot match, accelerating capital allocation to distributed intelligence.
Market Restraints
- Semiconductor supply concentration:Taiwan-based foundry capacity constraints limit production volumes of specialized metering ASICs essential for platform hardware layers.
- Cybersecurity certification timelines:IEC 62443 compliance requirements extend product validation cycles, delaying revenue recognition for new platform releases.
- Legacy SCADA substitution economics:Brownfield industrial sites face capital intensity barriers when replacing hardwired control systems with IP-native architectures.
Strategic Opportunities
- Aggregated distributed resource participation:FERC Order 2222 compliance creates wholesale market revenue streams for platforms orchestrating behind-the-meter assets in the United States.
- Carbon accounting workflow convergence:Integration of facility energy data with Scope 1-3 reporting tools opens enterprise software budgets previously siloed from operational technology.
- India's renewable purchase obligations:State-level mandates for industrial consumers drive demand for platforms that optimize dispatch across captive solar and grid supply.
Industry Challenges
- Power systems engineering talent scarcity:Platform vendors compete for specialists capable of bridging grid physics with software architecture, compressing development timelines.
- Multi-vendor protocol harmonization:Integration friction between proprietary DER communication standards delays deployment in heterogeneous asset environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Energy Platform Market |
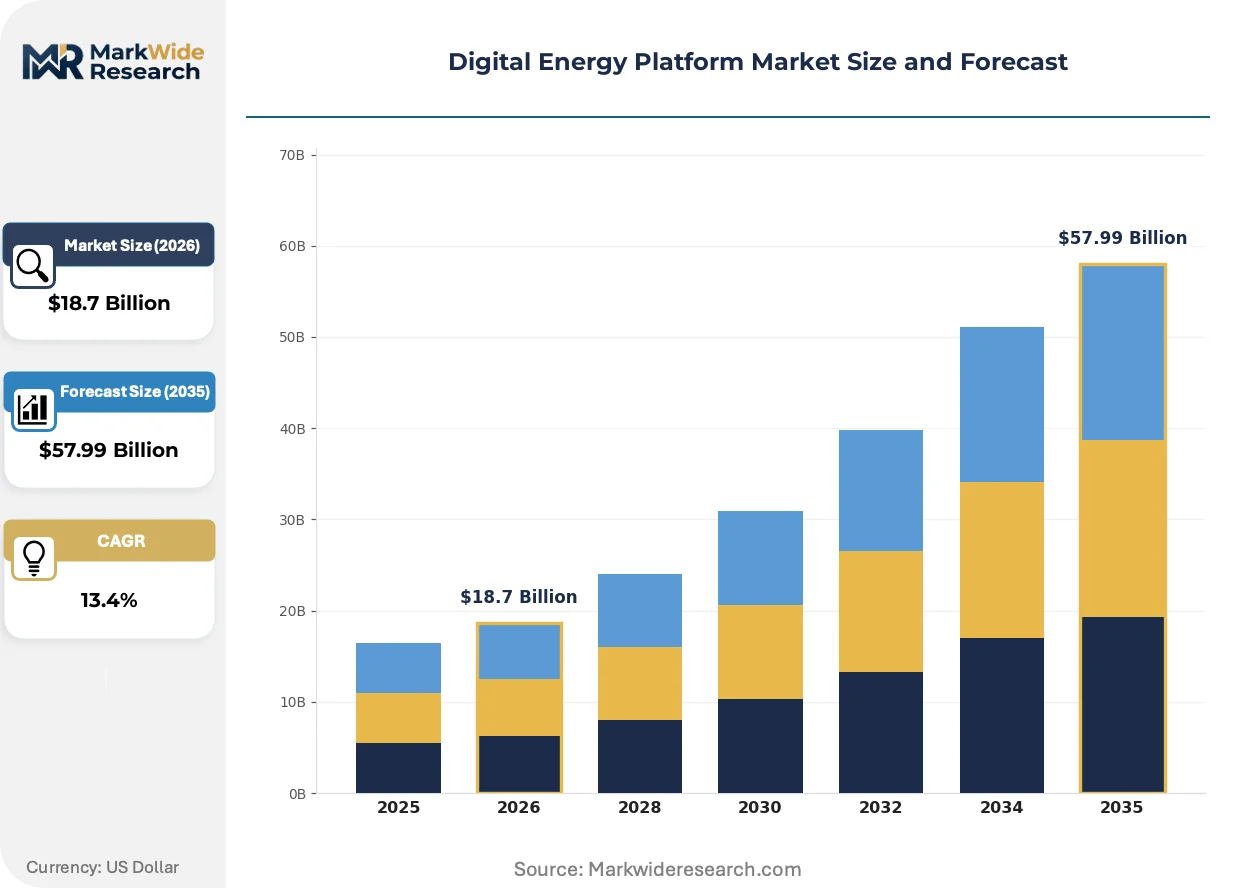
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $57.99 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Technology: Artificial Intelligence, Internet of Things, Blockchain, Data Analytics End User: Utilities, Industrial, Commercial, Residential Service Type: Consulting, Platform Management, Integration, Support |
| Companies Covered | Schneider Electric, Honeywell, Siemens, ABB, SAP, IBM, GE, Huawei, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Energy Platform Market Trends and Innovations
Software-defined grid architectures are compressing hardware procurement cycles while expanding the addressable market for algorithmic optimization services previously bundled with capital equipment.
Digital twin modeling of distribution networks is supplanting static planning studies for grid-edge capacity expansion. Municipal utilities in the Netherlands and Denmark deploy these simulations to defer transformer upgrades. The technology is supplanting traditional load forecasting vendors by embedding predictive analytics directly into platform control loops.
CSRD disclosure requirements in Europe mandate granular energy consumption reporting from listed entities. Industrial facility operators must install sub-metering infrastructure that feeds directly into audit-ready carbon accounting systems. Manufacturing sites in Belgium and northern Italy represent the most advanced compliance implementations, with platforms capturing process-level electricity data at fifteen-minute intervals.
Energy-as-a-service contracting structures now dominate procurement for commercial building retrofits, unbundling hardware ownership from optimization performance. Facility management firms in Singapore and Australia have pioneered these arrangements, transferring operational risk to platform operators. The model compresses buyer decision cycles by eliminating upfront capital allocation for metering and control infrastructure.
Digital Energy Platform Market Segmentation
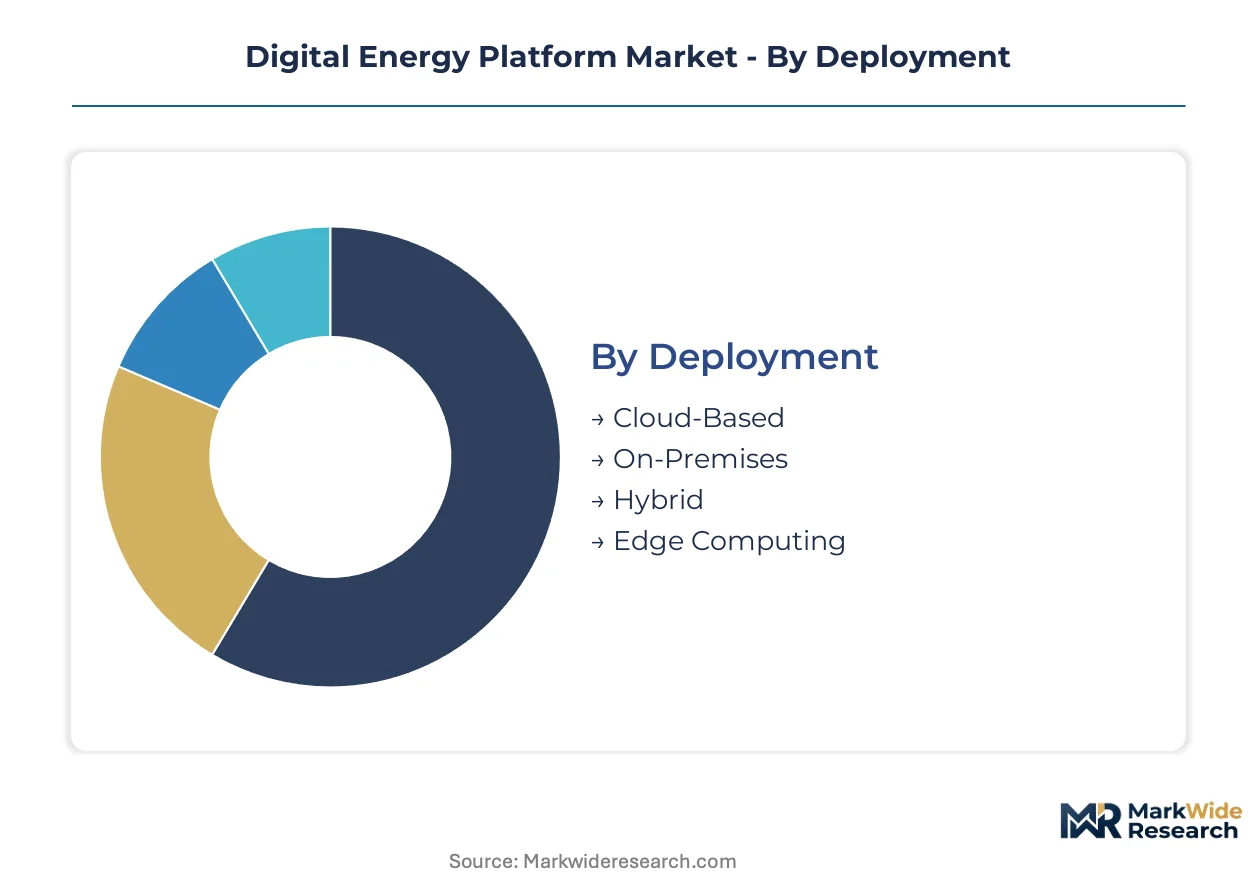
Digital energy platforms serve heterogeneous infrastructure environments where deployment constraints, latency requirements, and data sovereignty rules fragment procurement patterns across customer types. Segmentation reveals how vendors must architect modular stacks capable of spanning cloud-native utilities to edge-dependent industrial microgrids without sacrificing interoperability.
Deployment:
Cloud deployments dominate in markets with liberalized wholesale power markets and mature hyperscaler presence, while edge and hybrid configurations concentrate where grid code mandates sub-cycle protection response times.
- Cloud-Based:Elastic compute resources enable seasonal demand spike handling and centralized fleet management for multi-site enterprises. German municipal utilities and Nordic district heating operators anchor procurement volumes where data residency rules permit offshore processing.
- Hybrid:Split architectures process non-critical forecasting and settlement workloads in cloud environments while retaining protection-grade control at local nodes. Industrial clusters in Belgium and northern Italy deploy these configurations to satisfy CSRD audit trail requirements without sacrificing operational responsiveness.
- On-Premises:Air-gapped installations serve defense and critical infrastructure operators with classified load profiles.
- Edge Computing:Sub-10 millisecond telemetry processing enables distributed intelligence for inverter-based resource coordination.
Cloud-based systems command the established base. The steepest expansion runs through edge computing as inverter-dominated grids proliferate.
Technology:
Technology selection tracks customer maturity curves, with AI and analytics commanding premium pricing in deregulated markets while blockchain pilots concentrate in peer-to-peer energy trading jurisdictions.
- Artificial Intelligence:Neural network architectures for predictive load forecasting and automated dispatch now embed directly into platform control loops rather than operating as bolt-on modules. Dutch and Danish distribution system operators deploy these capabilities to defer transformer upgrades through dynamic hosting capacity analysis.
- Data Analytics:Descriptive and diagnostic dashboards dominate procurement in emerging markets where baseline visibility precedes optimization investments. India's state electricity boards purchase these platforms to meet renewable purchase obligation compliance with limited integration complexity.
- Internet of Things:Sensor fusion protocols unify metering, protection, and market telemetry streams.
- Blockchain:Distributed ledger implementations enable peer-to-peer settlement and renewable energy certificate traceability.
Data analytics commands the established base. The steepest expansion runs through artificial intelligence as algorithmic optimization displaces static planning studies.
End User:
End-user segmentation reflects diverging procurement authority structures, with utilities centralizing platform decisions while industrial and commercial buyers increasingly procure direct vendor relationships bypassing traditional utility intermediation.
- Utilities:Transmission and distribution operators purchase enterprise-grade orchestration platforms with native market interface capabilities. FERC Order 2222 compliance drives United States utility procurement of aggregated distributed resource management systems.
- Industrial:Manufacturing corridors in Germany unwind decades of passive utility relationships to procure direct platform access for real-time load optimization and Scope 1-3 carbon accounting integration.
- Commercial:Facility management firms in Singapore and Australia pioneer energy-as-a-service contracting structures.
- Residential:Behind-the-meter optimization concentrates in markets with time-of-use tariff structures and distributed solar penetration.
Utilities command the established base. The steepest expansion runs through industrial as manufacturing procurement autonomy accelerates.
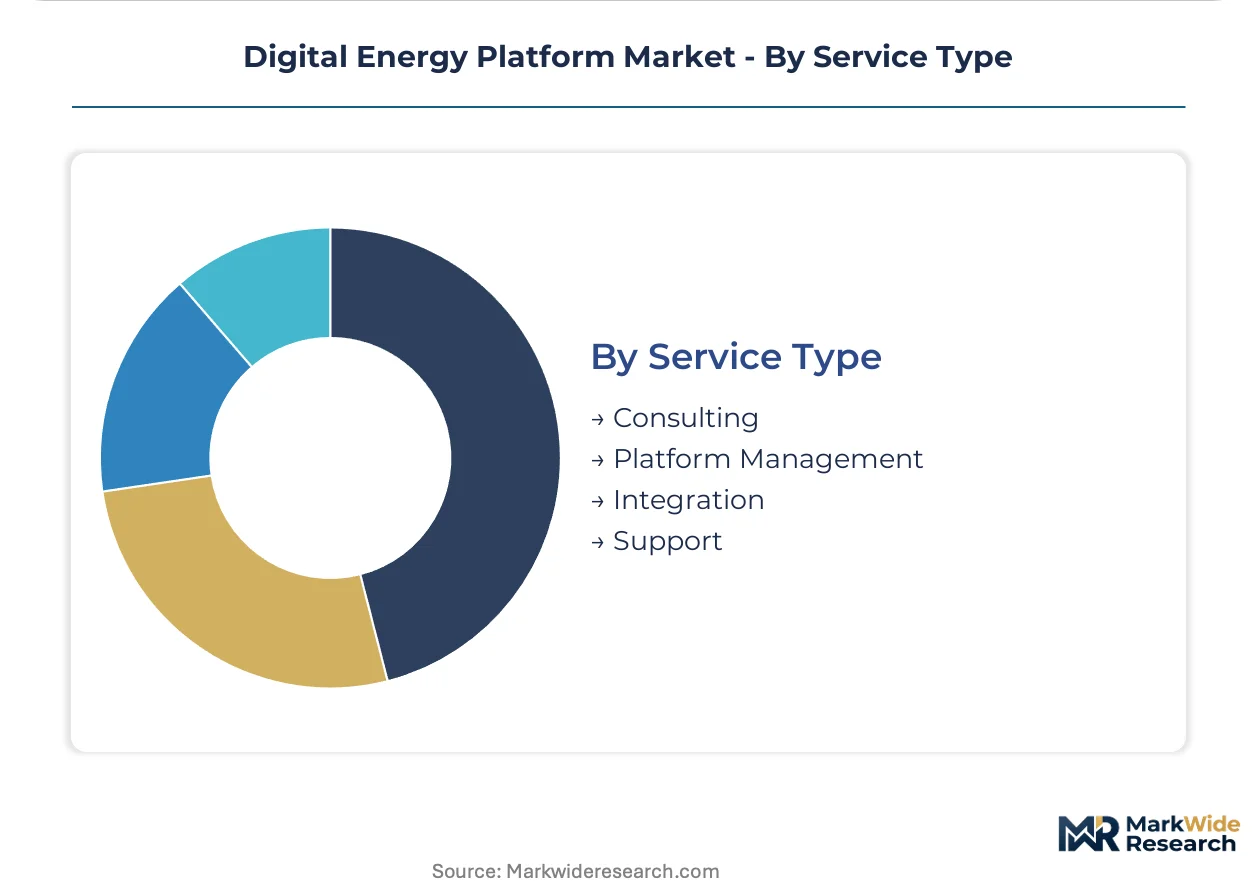
Service Type:
Service mix shifts toward recurring platform management revenue as vendors seek to capture lifetime value from hardware-light, software-heavy deployment models.
- Platform Management:Ongoing operational oversight including dispatch optimization, cybersecurity patching, and regulatory compliance module updates. Vendors price these services as percentage of underlying asset value or throughput-based fees.
- Integration:Multi-vendor protocol harmonization and legacy SCADA migration services address brownfield deployment friction.
- Consulting:Grid modernization roadmapping and regulatory strategy advisory.
- Support:Tiered response commitments for critical infrastructure uptime requirements.
Integration commands the established base. The steepest expansion runs through platform management as vendors capture recurring revenue from software-centric architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea offshore grid interconnects anchor European platform deployment, while the Pacific Northwest hydroelectric backbone and Texas ERCOT nodal market structure shape North American procurement patterns. India's Green Energy Corridors transmission program and China's ultra-high voltage direct current lines similarly concentrate regional platform demand.
United States
Industrial microgrid deployments cluster around the Texas Gulf Coast petrochemical corridor and California's Silicon Valley data center hubs. FERC Order 2222 mandates wholesale market participation protocols for aggregated distributed resources, compressing procurement timelines for grid-edge orchestration platforms. The PJM Interconnection territory anchors early adoption of sub-second telemetry systems for inverter-based resource coordination.
Germany
Manufacturing corridors in Bavaria and North Rhine-Westphalia unwind passive utility relationships to procure direct platform access for real-time load optimization. The EU F-Gas Regulation mandates refrigerant lifecycle accountability in connected thermal systems, forcing facility operators toward granular emissions traceability. Industrial clusters around Stuttgart and Düsseldorf represent the most advanced hybrid cloud-energy orchestration deployments in Europe.
China
Provincial renewable integration quotas concentrate platform demand in the Yangtze River Delta and Pearl River Delta manufacturing belts. The dual carbon goals framework imposes granular energy consumption reporting requirements on listed state-owned enterprises. Ultra-high voltage direct current transmission corridors from western solar and wind bases to eastern load centers require sophisticated dispatch coordination platforms.
India
State-level renewable purchase obligations drive industrial consumer procurement of dispatch optimization platforms across Maharashtra and Gujarat. The Central Electricity Authority mandates scheduling and forecasting protocols for captive solar installations above 10 MW capacity. Manufacturing clusters in Pune and Ahmedabad deploy hybrid architectures to optimize across grid supply and behind-the-meter solar assets.
Netherlands
Municipal utilities deploy digital twin modeling to defer transformer upgrades in Randstad urban corridors. The CSRD disclosure requirements mandate fifteen-minute interval energy consumption reporting from listed entities. Rotterdam's port industrial complex and Eindhoven's high-tech manufacturing belt anchor the most advanced sub-metering infrastructure implementations in northern Europe.
Digital Energy Platform Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and software velocity dimensions. The market structure concentrates around three tiers: diversified industrial conglomerates with embedded energy divisions, pure-play software vendors with native cloud architectures, and regional system integrators with deep utility relationships. Strategic moves center on protocol harmonization acquisitions and edge computing capacity partnerships rather than horizontal consolidation.
Among diversified industrial conglomerates, Schneider Electric, Siemens, and Honeywell occupy positions that exemplify the convergence of operational technology hardware with software-centric orchestration layers. Schneider Electric represents the European archetype of distributed energy resource software stacks anchoring enterprise microgrid deployments. Siemens exemplifies deep domain integration across building automation and grid-edge analytics. Honeywell sits within the cross-sector IoT platform tier that unifies facility energy data with carbon accounting workflows.
| Leading Market Players |
|---|
| Schneider Electric |
| Honeywell |
| Siemens |
| ABB |
| SAP |
| IBM |
| GE |
| Huawei |
| Microsoft |
| Others |
Pricing and Supply Chain Analysis
Energy-as-a-service contracting locks in decade-long platform access commitments while capping buyer exposure to semiconductor cost volatility and cloud compute pricing swings. German industrial clusters and Singapore facility management firms anchor this structure, trading upfront capital outlays for predictable operational expenditure curves tied to throughput-based fees.
Pricing Analysis
Volume-discount tiering separates enterprise utility deployments from mid-market commercial retrofits and pilot-scale industrial microgrids. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and cybersecurity module depth, with IEC 62443 compliance adding substantial premiums. Price erosion runs through the economy tier as open-source telemetry stacks commoditize basic monitoring functionality. Commercial building operators exhibit highest price sensitivity, while defense and critical infrastructure buyers prioritize air-gapped architectures regardless of cost.
Supply Chain Analysis
Strategic stockpiling of specialized metering ASICs and edge computing silicon dominates procurement strategy among platform vendors confronting Taiwan-based foundry capacity constraints. Hardware layer production draws from Taiwan, South Korea, and Germany, with software development anchored in India and Poland. Single-source vulnerability in advanced node semiconductor fabrication poses the most acute structural risk. Distribution runs through direct enterprise sales teams for utility-scale deployments and channel partners for commercial retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defensible positioning in digital energy platforms rests on regulatory entrenchment rather than technology alone. Compliance module depth creates switching costs that cement multi-year relationships as jurisdictions fragment their emissions traceability mandates.
For Market Incumbents: Secure protocol harmonization acquisitions to neutralize multi-vendor DER integration friction that delays competitor deployments. Deepen edge computing partnerships with Taiwan-based foundries to lock in ASIC supply allocation ahead of capacity constraints. Carbon accounting workflow convergence represents the most pressing margin pressure point from pure-play software entrants.
For New Entrants and Emerging Players: Lead with India's state-level renewable purchase obligations as the most penetrable regulatory wedge, where captive solar dispatch optimization demand outpaces incumbent service capacity. Target Maharashtra and Gujarat manufacturing clusters with lightweight hybrid cloud-edge architectures that undercut enterprise-grade utility pricing. Position through EPC contractor partnerships rather than direct utility sales cycles.
For Investors and Strategic Acquirers: Regional system integrators with deep utility relationships and native FERC Order 2222 compliance expertise command scarcity premiums in the United States market. Long-term viability hinges on software velocity outpacing hardware-centric conglomerates across the next decade. Watch F-Gas Regulation enforcement intensity in Germany as the inflection signal for European platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Partnership | Taiwan foundry alliances secure ASIC supply allocation against capacity constraints. |
| Protocol Harmonization Acquisition | Multi-vendor DER integration capabilities compress competitor deployment timelines. |
| Carbon Accounting Module Launch | CSRD compliance integration captures enterprise software budgets from operational technology silos. |
| FERC Order 2222 Certification | Wholesale market participation protocols unlock aggregated distributed resource revenue streams. |
| Energy-as-a-Service Expansion | Singapore and Australia contracting structures transfer operational risk to platform operators. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and grid operators and refined through secondary validation across EIA data, IEA reports, FERC filings, and project development databases. Bottom-up deployment modeling triangulated against top-down market sizing derived from hyperscaler capex disclosures and semiconductor trade flows.
Variance-decomposition framing separated volume drivers from price elasticity effects across deployment model, organization size, vertical integration depth, and regional grid type segmentation dimensions. CAGRs were derived from algorithmic trend fitting against historical adoption curves and forward pipeline visibility. Forecast inputs incorporated renewable purchase obligation enforcement schedules and ultra-high voltage transmission commissioning timelines.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal implementation intensity or Taiwan semiconductor supply stability would require recalibration. Forecasts reflect documented assumptions regarding regulatory harmonization pace and edge computing cost decline trajectories. Revision becomes warranted when F-Gas Regulation enforcement crosses thresholds that accelerate brownfield replacement cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
Industrial Energy Monitoring Market
Energy Analytics and Software
Carbon and Energy Software Market
Energy Analytics and Software
Predictive Maintenance in the Energy Market
Energy Analytics and Software
US Big Data Analytics in Energy Market
Energy Analytics and Software
Africa Big Data Analytics in Energy Market
Energy Analytics and Software
Big Data Analytics in Energy Market
Energy Analytics and Software
Big Data Analytics in Power Sector Market
Energy Analytics and Software
Global Wind Turbine Condition Monitoring System Market
Energy Analytics and Software
AI in Energy Market
Energy Analytics and Software
Utility Analytics and Energy Analytics Market
Energy Analytics and Software
GCC Well Testing Services Market
Energy Analytics and Software
Energy and Utilities Analytics Market
Energy Analytics and Software
Building Energy Simulation Software Market
Energy Analytics and Software
Japan Big Data Analytics in Energy Market
Energy Analytics and Software
Australia Big Data Analytics in Energy Market
Energy Analytics and Software
Spain Big Data Analytics in Energy Market