
 Bunker Fuel Market | 2026-2036
Bunker Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Bunker Fuel Market Intelligence
Middle Eastern refinery expansion, particularly in Saudi Arabia and the UAE, is reconfiguring established supply routes for low-sulfur fuels. Global traders like World Fuel Services leverage their extensive network for physical supply and brokerage services. Specialist firms such as Peninsula Petroleum and Minerva Bunkering compete on operational agility and flexible credit terms for shipowners. Integrated majors including Shell and TotalEnergies anchor their market position through direct refinery-to-port infrastructure.
Bunker fuel refers to any type of fuel oil used to power marine vessels. These fuels are typically residual products from crude oil distillation, with specifications for viscosity, density, and sulfur content dictating their grade. While residual fuel types like Heavy Fuel Oil still represent significant volume, demand for lower-sulfur Marine Gas Oil is accelerating. The container ship and tanker segments are the largest end-users, accounting for the majority of commercial shipping consumption.
The International Maritime Organization's (IMO) global sulfur cap is the primary regulatory driver shaping fuel quality. Regional bodies, including the US EPA and the European Commission through its FuelEU Maritime initiative, impose additional constraints on emissions in specific sea areas. Compliance with ISO 8217 standards remains a baseline requirement for all commercial transactions. Shipowners' long-term decisions on vessel technology, balancing scrubber installations against new alternative fuel-ready engines, will dictate future demand.
Market Dynamics
The bunker fuel market's structure is fundamentally defined by the global regulatory mandate for lower sulfur emissions. This pressure, codified by the International Maritime Organization, dictates fuel blend specifications, influences refinery investment decisions, and drives shipowner technology choices between scrubbers and alternative fuels.
Growth Catalysts
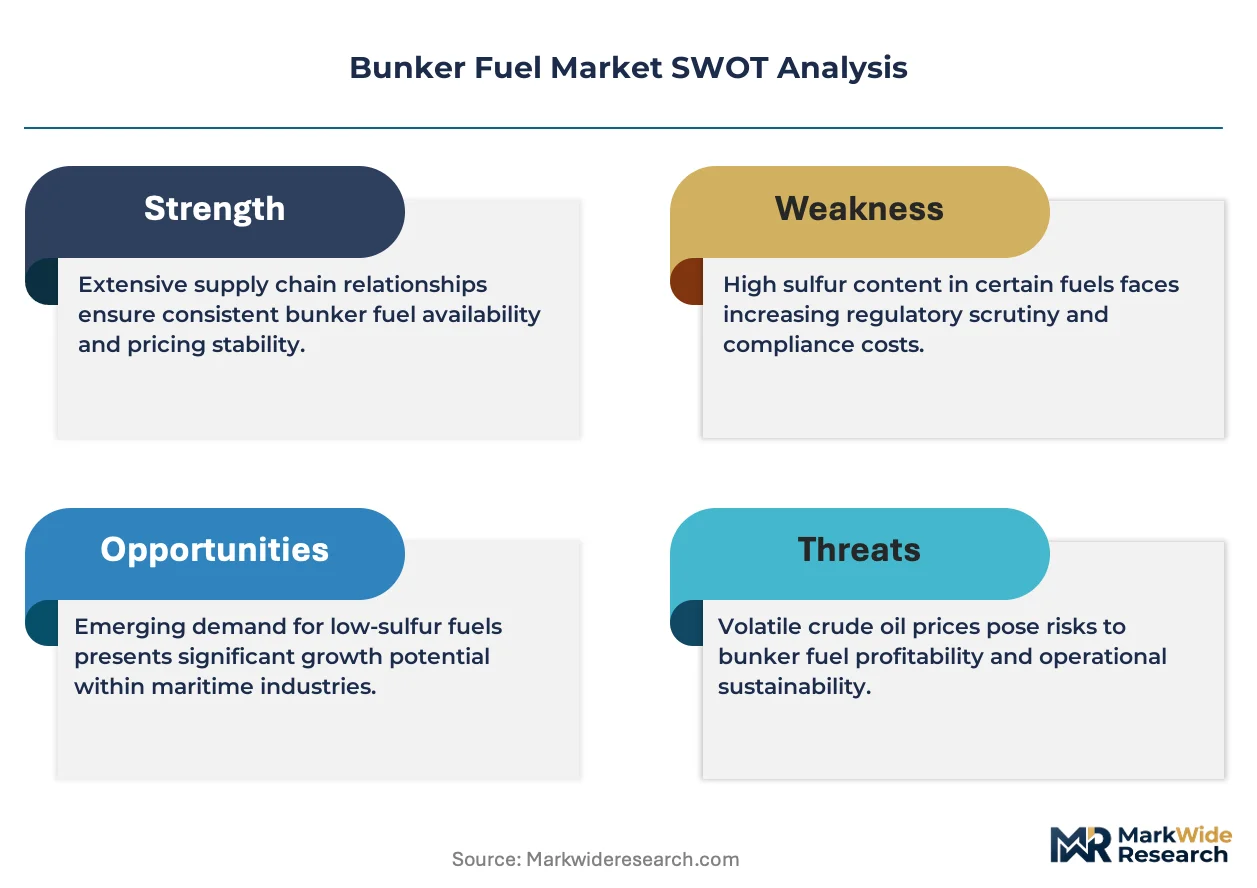
- IMO 2020 Compliance:The global sulfur cap regulation compels the shipping industry to consume higher-value, lower-sulfur fuels like VLSFO and MGO, directly expanding the market value over traditional high-sulfur fuel oil.
- Container Fleet Expansion:Sustained growth in the global container ship fleet, particularly vessels servicing trans-Pacific and Asia-Europe trade lanes, provides a consistent and expanding base for bunker fuel consumption.
- Refinery Modernization:Strategic investments in new coking and hydro-treating units at refineries, especially in the Middle East and Asia, increase the efficient supply of compliant low-sulfur bunker fuels to key ports.
Market Restraints
- Crude Oil Price Volatility:Bunker fuel prices are directly linked to volatile crude oil benchmarks, creating significant cost uncertainty and hedging challenges for shipowners and operators, which can depress purchasing volumes during price spikes.
- Alternative Fuel Infrastructure Gap:The limited availability of port infrastructure for bunkering emerging fuels like LNG, methanol, and ammonia acts as a major barrier to their widespread adoption, anchoring demand to conventional fuels.
- Technical Compatibility Issues:Inconsistent properties among Very Low Sulfur Fuel Oil (VLSFO) blends from various suppliers can lead to operational problems like sludge formation and engine damage, causing hesitancy among some ship operators.
Strategic Opportunities
- Biofuel Blending:The supply of marine biofuels, such as FAME or HVO, as drop-in blends with conventional bunker fuels presents an immediate pathway for shipowners to reduce their carbon intensity and meet emissions targets.
- Digital Bunkering Platforms:The development of digital marketplaces for fuel procurement, nomination, and quality assurance offers an opportunity to improve transparency, reduce disputes, and enhance efficiency in the bunkering process.
- Ammonia and Methanol Supply Chains:Investing in production and portside infrastructure for green methanol and ammonia in hubs like Singapore and Rotterdam positions suppliers for long-term demand from next-generation vessels.
Industry Challenges
- Fuel Quality Verification:The proliferation of new fuel blends post-IMO 2020 makes it difficult for vessel crews to quickly verify fuel quality and compatibility onboard, increasing the risk of engine issues and disputes over off-spec deliveries.
- Crew Competency for New Fuels:A significant training gap exists for seafarers who must learn to safely handle and manage alternative fuels like LNG and methanol, which have different storage requirements and safety protocols than traditional oils.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bunker Fuel Market |
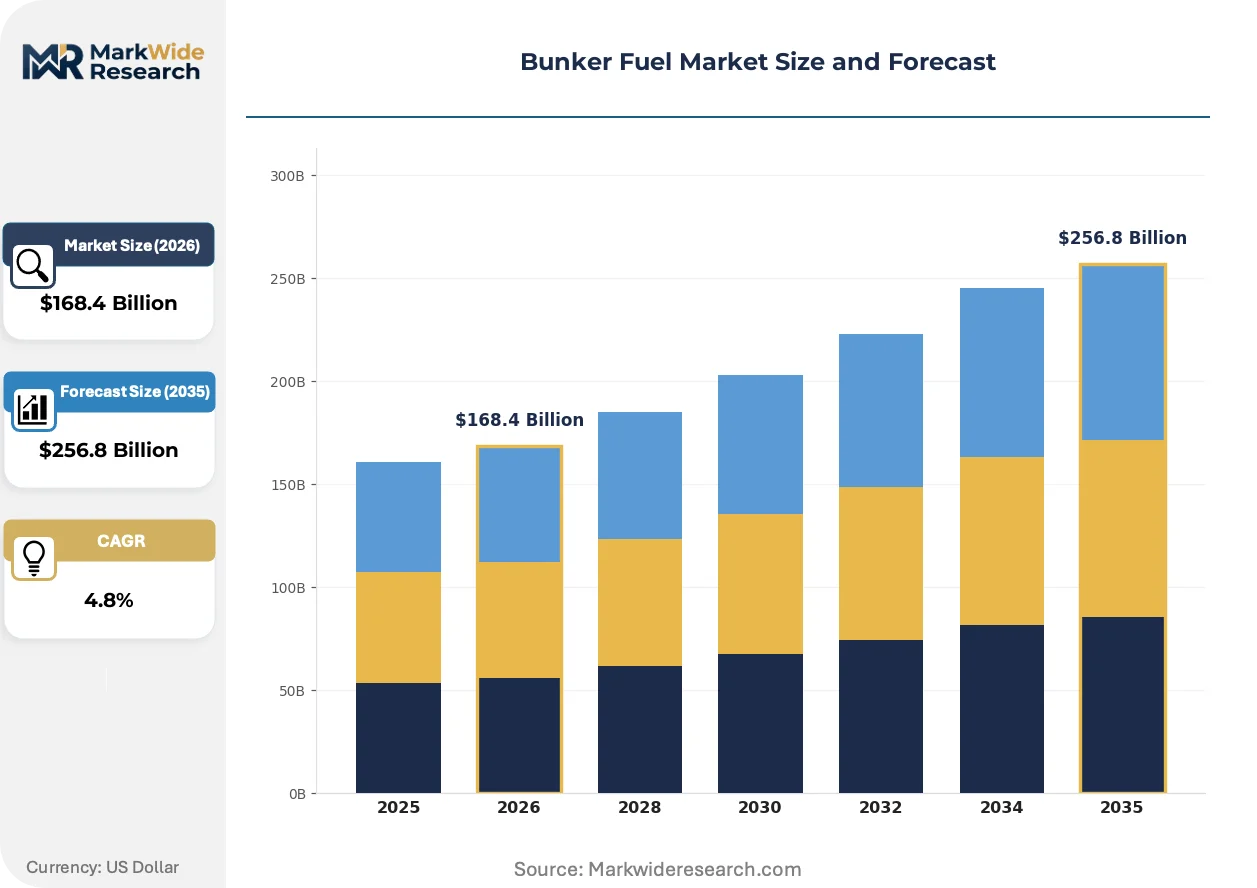
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $256.8 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Heavy Fuel Oil, Marine Diesel Oil, Marine Gas Oil, Residual Fuel End User: Container Ships, Bulk Carriers, Tankers, Passenger Vessels Application: Commercial Shipping, Fishing Vessels, Offshore Support Vessels, Port Services Distribution Channel: Direct Sales, Marine Bunkering Stations, Harbor Supply, Third-party Suppliers |
| Companies Covered | Bunker Holding, Peninsula Petroleum, Minerva Bunkering, World Fuel Services, Vitol Bunkers, Shell, BP, ExxonMobil, TotalEnergies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bunker Fuel Market Strategic Shifts & Innovations
The market's evolution is driven by the twin forces of decarbonization and digitalization. These pressures compel a fundamental shift in both the chemical composition of marine fuels and the transactional processes used to procure and verify them across the global fleet.
Digital mass flow meters (MFMs) provide a verifiable, real-time measurement of the quantity of fuel delivered to a vessel. Large ship operators and charterers are increasingly mandating their use to prevent disputes over volume. This technology is virtualizing the traditional process of delivery verification, replacing manual tank soundings with a secure, auditable digital record that reduces quantity disputes.
The European Union's FuelEU Maritime regulation introduces a new layer of complexity for vessel operators. This policy mandates a gradual reduction in the greenhouse gas intensity of energy used by ships calling at EU ports. The container and ro-ro segments, with frequent port calls, are most affected and are responding by exploring biofuel blends and planning for alternative fuel-ready newbuilds.
A clear shift is occurring from purely transactional, spot-based fuel purchasing toward more strategic, long-term supply agreements. Large container lines are forming partnerships with major suppliers to secure access to compliant fuels and manage price volatility. This trend is most pronounced in the major bunkering hubs of Singapore, Rotterdam, and Fujairah, where volume certainty is paramount.
Bunker Fuel Market Segmentation
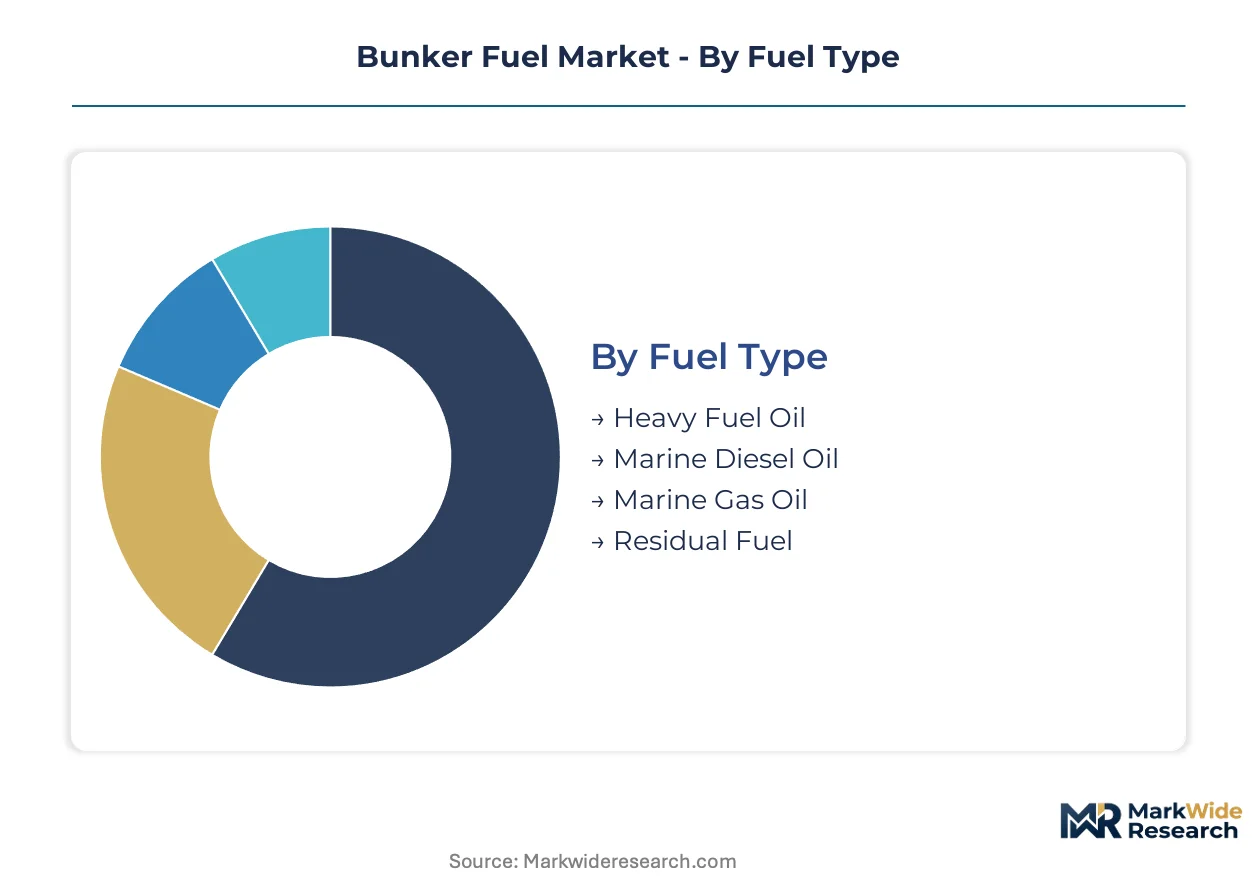
The bunker fuel market's segmentation provides a detailed view of demand drivers and supply chain dynamics across various fuel types, end-users, applications, and distribution channels. Understanding these distinct segments is crucial for suppliers to tailor product offerings and optimize logistical networks for diverse shipping requirements.
Fuel Type:
The bunker fuel market's fuel type segmentation highlights the varying operational requirements and after-sales-service intensity demanded by different marine engine technologies.
- Heavy Fuel Oil:This residual product from crude oil distillation features high viscosity and density, requiring heating before combustion in marine engines. It remains a significant volume segment for older vessels or those equipped with exhaust gas scrubbers, particularly in long-haul routes across the Pacific.
- Marine Gas Oil:A distillate fuel with low sulfur content, MGO requires minimal pre-treatment and offers operational simplicity for smaller vessels and those operating in Emission Control Areas. Demand for MGO is accelerating significantly due to IMO 2020 regulations and regional mandates like FuelEU Maritime.
- Marine Diesel Oil:MDO is a blend of distillate and residual fuels, offering a balance between cost and quality, often used in auxiliary engines or for short voyages. Its specifications vary, providing flexibility for operators seeking intermediate fuel solutions.
- Residual Fuel:This broad category encompasses various high-viscosity fuels derived from crude oil refining, primarily distinguished by their sulfur content and specific gravity.
Heavy Fuel Oil holds the largest share; momentum sits with Marine Gas Oil.
End User:
End-user categories delineate demand patterns based on vessel size, trade routes, and cargo volume, which significantly influence procurement scale.
- Container Ships:These vessels transport manufactured goods globally, operating on fixed schedules and high-volume routes like trans-Pacific lanes, driving consistent and substantial bunker fuel consumption. The expanding global container fleet provides a stable base for fuel demand.
- Tankers:Tankers specialize in bulk liquid cargo transport, including crude oil, refined products, and chemicals, operating worldwide with diverse fuel needs based on voyage length and port calls. This segment accounts for a large portion of commercial shipping consumption.
- Bulk Carriers:These ships transport unpackaged dry cargo such as iron ore, coal, and grain, often on tramp routes, leading to variable fuel purchasing patterns.
- Passenger Vessels:This category includes cruise ships and ferries, which often operate on fixed routes with frequent port calls, requiring high-quality, low-sulfur fuels to meet stringent emissions regulations in coastal areas.
Container Ships are expanding most quickly, while Bulk Carriers maintain significant consumption volume.
Application:
The application segment differentiates fuel consumption based on the operational profile and customer type of marine activities, driving diverse fuel specifications.
- Commercial Shipping:This broad application encompasses all cargo and passenger transport vessels engaged in international and domestic trade, representing the largest volume consumer of bunker fuels. Compliance with global and regional emissions regulations is a primary concern for this segment.
- Offshore Support Vessels:These specialized vessels serve the offshore oil and gas industry, providing logistics, construction, and maintenance support for platforms and rigs. Their operations often require specific fuel grades and reliable supply in remote locations.
- Fishing Vessels:Fisheries utilize various vessel types, from small trawlers to large factory ships, with fuel consumption patterns heavily influenced by fishing grounds and operational duration.
- Port Services:This application includes tugboats, pilot boats, dredgers, and other vessels supporting port operations, typically requiring smaller volumes of higher-grade fuels for frequent maneuvering.
The segment with the steepest expansion trajectory is Offshore Support Vessels, while Commercial Shipping commands the largest portion.
Distribution Channel:
Distribution channels reflect the supply concentration and logistical infrastructure required to deliver bunker fuels efficiently to global vessels.
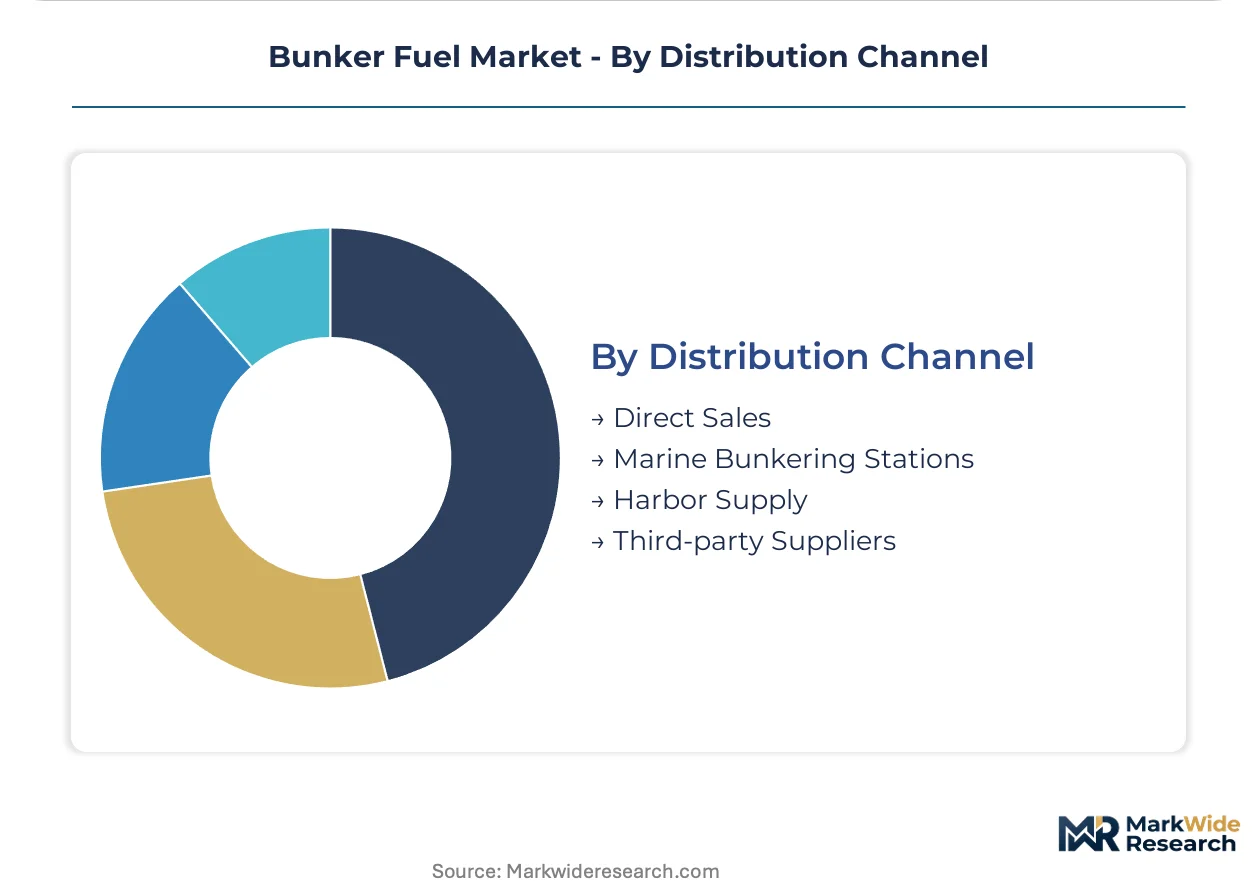
- Direct Sales:Major integrated oil companies and large trading houses often engage in direct sales, supplying fuel from their own refineries or terminals directly to shipowners. Integrated majors like Shell anchor their market position through this channel.
- Marine Bunkering Stations:These are dedicated facilities in major ports like Singapore and Rotterdam where bunker fuels are stored and delivered to vessels via barges or pipelines. Demand concentration is most pronounced in these hubs.
- Harbor Supply:This channel involves smaller-scale fuel deliveries within a harbor or port area, often for smaller vessels or those with limited bunkering requirements.
- Third-party Suppliers:Independent traders and brokers, such as World Fuel Services and Peninsula Petroleum, leverage extensive networks to provide physical supply and brokerage services, competing on operational agility and credit terms.
Growth is most pronounced in Third-party Suppliers, with Marine Bunkering Stations representing the dominant channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Chinese Ministry of Ecology and Environment (MEE) mandates stringent emissions controls, profoundly influencing marine fuel demand across the Asia-Pacific region. This regulatory pressure, coupled with expanding trade routes, drives investment in low-sulfur fuel production and infrastructure. Major bunkering hubs globally are adapting to evolving fuel specifications and increasing vessel traffic demands.
China
Expanding container ship traffic and a large domestic fishing fleet drive consistent bunker fuel consumption in China. Chinese authorities, including the MEE, enforce strict emissions standards in coastal waters and emission control areas. The port of Shanghai, a primary bunkering hub, sees significant demand for compliant low-sulfur fuels to service trans-Pacific trade lanes.
Singapore
Singapore's strategic location and robust port infrastructure position it as the world's largest bunkering hub, attracting diverse shipping lines. The Maritime and Port Authority of Singapore (MPA) actively promotes the adoption of digital bunkering solutions and alternative fuels. Massive volumes of VLSFO and MGO are supplied daily in Singapore, supporting global maritime trade flows.
United States
Demand for marine fuels in the United States stems from extensive commercial shipping, including container and tanker segments, and a growing cruise industry. The US Environmental Protection Agency (EPA) sets strict emissions limits for vessels operating in US waters, particularly in Emission Control Areas. Major ports like Houston and Los Angeles are investing in infrastructure for compliant and alternative fuels.
Netherlands
The Netherlands serves as a critical European maritime gateway, with the Port of Rotterdam being a leading bunkering location. The European Commission's FuelEU Maritime initiative significantly impacts fuel choices for vessels calling at Dutch ports. Rotterdam is a key hub for biofuel blending and is actively developing infrastructure for future alternative marine fuels like methanol.
United Arab Emirates
The United Arab Emirates benefits from its strategic location at the crossroads of major shipping lanes and significant refinery capacity. The UAE's Federal Transport Authority (FTA) oversees maritime regulations, ensuring compliance with international standards. Fujairah, a major bunkering hub, is expanding its storage and supply capabilities for low-sulfur and future fuels.
Bunker Fuel Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a dynamic competitive environment in the bunker fuel market. The market features integrated energy majors, global trading houses, and specialized physical suppliers. Key competitive moves include expanding physical supply networks and securing long-term supply agreements with shipowners.
Among integrated majors, Shell and TotalEnergies anchor their market position through direct refinery-to-port infrastructure, ensuring consistent supply of compliant fuels. Global traders like World Fuel Services leverage their extensive network for physical supply and brokerage services, offering broad market access. Peninsula Petroleum and Minerva Bunkering, as specialist firms, compete on operational agility and flexible credit terms for shipowners, serving diverse regional needs.
| Leading Market Players |
|---|
| Bunker Holding |
| Peninsula Petroleum |
| Minerva Bunkering |
| World Fuel Services |
| Vitol Bunkers |
| Shell |
| BP |
| ExxonMobil |
| TotalEnergies |
| Others |
Cost & Logistics Intelligence
Trans-Pacific trade lanes, with their substantial bunker fuel requirements, link cost dynamics to supply concentration in major Asian hubs and subsequent price differentiation for shipping lines. Global crude oil price volatility directly impacts these operational costs.
Pricing Analysis
Geographic price spreads for bunker fuels reflect regional supply-demand imbalances and logistical costs. The market primarily operates on a hybrid model, combining commodity spot transactions with long-term contract-based offtake agreements. Price differentiation stems from fuel quality grades and geographic delivery costs, with pricing pressure intensifying due to volatile crude oil benchmarks. Container ships on fixed routes are less price-sensitive than bulk carriers operating on tramp routes.
Supply Chain Analysis
Extended payment terms and flexible credit facilities are critical supplier-financing tools, particularly for specialist firms like Peninsula Petroleum. Supply concentration centers on major bunkering hubs in Singapore, the UAE, and the Netherlands, drawing from crude oil distillation products. Commodity price volatility represents a significant structural risk for the entire chain. Distribution runs through marine bunkering stations and third-party suppliers, alongside direct sales by integrated majors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bunker fuel market is experiencing a buyer-power shift, as large container lines increasingly form strategic partnerships with major suppliers to secure compliant fuels. This consolidates procurement influence among key shipping segments.
For Market Incumbents:Harden existing direct refinery-to-port infrastructure to ensure consistent supply of compliant fuels, countering crude oil price volatility. Pursue strategic investments in refinery modernization, specifically coking and hydro-treating units, to increase efficient low-sulfur fuel production. This mitigates the threat of supply chain disruptions and strengthens control over fuel specifications.
For New Entrants and Emerging Players:Establish a beachhead in niche segments by offering specialized biofuel blending services as drop-in solutions, targeting early adopters for carbon intensity reduction. Develop digital bunkering platforms to enhance transparency and efficiency in fuel procurement, appealing to smaller operators seeking operational agility. Focus on specific Emission Control Areas requiring MGO for smaller vessels.
For Investors and Strategic Acquirers:Specialist firms with expertise in alternative fuel logistics and digital bunkering platforms represent attractive acquisition targets for long-term growth. The market's expansion to $256.8 Billion by 2035 signals sustained demand for compliant and future-ready solutions. Watch for increased regulatory mandates like FuelEU Maritime driving investment in green methanol and ammonia infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Refinery Modernization | Strategic investments in coking and hydro-treating units increase low-sulfur fuel supply for global shipping. |
| Biofuel Blending Development | Offers shipowners an immediate pathway to reduce carbon intensity and meet emissions targets. |
| Digital Bunkering Platforms | Enhances transparency and efficiency in fuel procurement, reducing disputes over volume and quality. |
| Alternative Fuel Infrastructure | Investing in portside facilities for green methanol and ammonia prepares for next-generation vessel demand. |
| Long-term Supply Agreements | Secures access to compliant fuels and manages price volatility for large container lines. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary validation. Primary insights were gathered from shipowners, refinery operators, port authorities, and fuel traders. Secondary data sources included IMO regulations, US EPA reports, European Commission directives, and industry association publications. Bottom-up and top-down triangulation ensured comprehensive market sizing.
Forecast inputs considered global container fleet expansion, refinery investment cycles, and evolving regulatory landscapes. The analytical framework modeled market dynamics across the analysis window, segmenting by fuel type, end-user, application, and distribution channel. Compound Annual Growth Rates were derived from historical trends and projected growth drivers. Regional regulatory frameworks also served as a key input.
Sensitivities concentrate around crude oil price volatility, regulatory changes, and the pace of alternative fuel adoption. Forecasts reflect assumptions regarding economic growth and shipping trade volumes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Solid Fuel Tablet Market
Fuels
United Arab Emirates Fuel Station Market
Fuels
Coal Intelligent Dry Separators Market
Fuels
Canada Coal Market
Fuels
Middle-East and Africa Bunker Fuel Market
Fuels
Defense Aircraft Aviation Fuel Market
Fuels
Fuel Quality Testing Market
Fuels
Europe Renewable Aviation Fuel Market
Fuels
Germany Bunker Fuel Market
Fuels
LNG Filling Station Market
Fuels
Asia-Pacific Coal Market
Fuels
CNG Dispenser Market
Fuels
Canada Bunker Fuel Market
Fuels
North America LNG Bunkering Market
Fuels
Italy Automotive Engine Oils Market
Fuels
LPG Vaporizer Market