
 Palm Methyl Ester Market | 2026-2036
Palm Methyl Ester Market Size, Share, and Industry Trends Forecast 2026-2036
Palm Methyl Ester Market Outlook
Personal care formulation demand is hardening as brands reformulate away from petrochemical surfactants. Wilmar International leverages integrated plantation-to-oleochemical assets across Southeast Asia. IOI Group anchors European supply chains through certified sustainable production streams. KLK OLEO competes on specialty ester derivatives for industrial lubricant applications.
Palm methyl ester denotes fatty acid methyl esters derived from palm oil transesterification, typically exhibiting cloud points between 10°C and 15°C and iodine values of 50-55 g I₂/100g, serving primarily as renewable feedstock for biodiesel, surfactants, and lubricant base stocks. The product type dimension shows biodiesel commanding volume leadership while surfactant-grade esters capture disproportionate margin pools from personal care and household cleaning brands. Application segmentation reveals automotive fuel blending maturing in Indonesia and Malaysia while industrial lubricant formulations accelerate in European manufacturing.
Indonesia's B35 biodiesel mandate and Malaysia's B20 program, administered by each country's energy ministry, structurally anchor palm methyl ester offtake for transport end users. EU REACH and the EU Green Deal's renewable fuel criteria constrain market access for uncertified supply, redirecting trade flows toward ISCC-certified Malaysian and Indonesian producers. Stakeholders must monitor evolving calorific value specifications in next-generation biodiesel standards and assess backward integration into plantation assets before feedstock cost volatility reshapes competitive economics.
Market Dynamics
EU REACH compliance and Indonesia's B35 biodiesel mandate are redirecting procurement toward certified sustainable supply streams while concentrating production in Malaysian oleochemical processing zones. This dual regulatory pull is compressing margins for uncertified producers and rewarding backward integration into plantation assets.
Growth Catalysts
- EU Green Deal renewable fuel criteria:European buyers must source ISCC-certified palm methyl ester, redirecting trade flows toward Malaysian and Indonesian producers with verified sustainability credentials.
- Biodiesel blending mandates:Indonesia's B35 and Malaysia's B20 programs structurally anchor transport sector offtake, creating guaranteed demand basins for domestic producers.
- Personal care reformulation:Brands are substituting petrochemical surfactants with palm-derived methyl esters to meet clean-label consumer preferences and regulatory pressure on synthetic inputs.
Market Restraints
- Crude palm oil price volatility:Feedstock costs constitute 70-80% of production economics, exposing processors to commodity swings that compress conversion margins without pricing power.
- Supply concentration risk:Malaysian and Indonesian plantation assets dominate upstream supply, creating geographic single-point vulnerability to weather events and export policy shifts.
- Technical cold-flow limitations:Cloud points of 10-15°C restrict biodiesel blending ratios in temperate climates, capping addressable market share in European winter applications.
Strategic Opportunities
- Industrial lubricant formulations:European manufacturing is accelerating adoption of biodegradable base stocks, opening premium margin pools for specialty ester derivatives with superior oxidative stability.
- Household cleaning channel expansion:Concentrated liquid detergent formats in Southeast Asian urban markets are driving surfactant-grade ester demand outside traditional personal care verticals.
- EU CSRD supply chain disclosure:Mandatory Scope 3 emissions reporting is forcing European formulators to document feedstock provenance, advantaging certified producers with traceable plantation-to-ester documentation.
Industry Challenges
- ISCC certification timeline compression:Three-to-six-month audit cycles delay market access for new entrants while incumbents consolidate preferred supplier status with European offtakers.
- Transesterification catalyst optimization:Heterogeneous catalyst R&D requires sustained capex without guaranteed yield improvements, straining mid-scale processors with limited R&D budgets.
- Legacy system integration:Plantation management software must interface with oleochemical plant ERP systems for chain-of-custody documentation, creating IT fragmentation risks during certification audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Palm Methyl Ester Market |
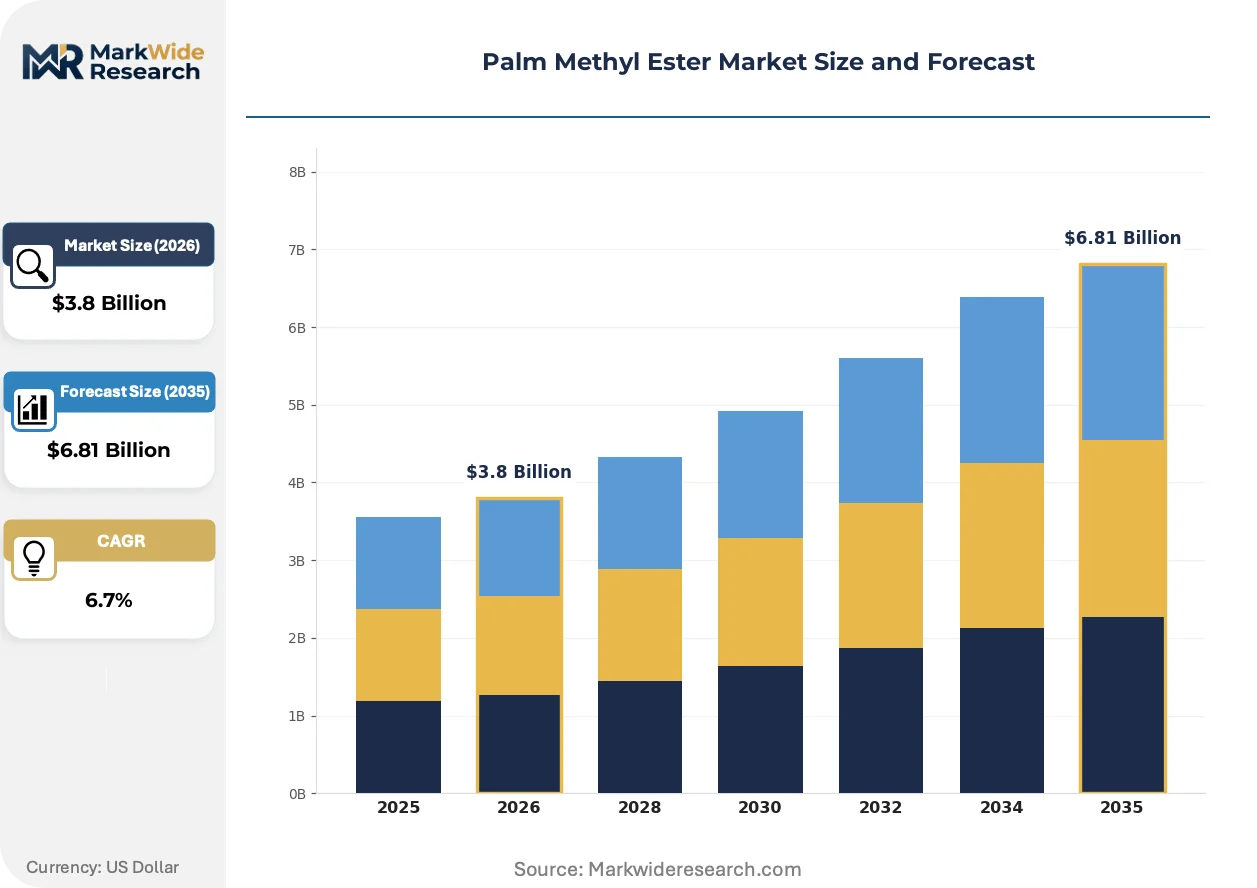
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodiesel, Surfactants, Lubricants, Emulsifiers Application: Automotive, Industrial, Household, Personal Care End User: Transport, Manufacturing, Agriculture, Retail Distribution Channel: Online Retail, Direct Sales, Distributors, B2B |
| Companies Covered | Wilmar International, IOI Group, KLK OLEO, Musim Mas Group, Sime Darby Plantation Berhad, Cargill, Emery Oleochemicals, Ecogreen Oleochemicals, Kao Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Palm Methyl Ester Market Strategic Shifts
Digital traceability platforms and enzymatic processing routes are displacing conventional alkali-catalyzed transesterification while regulatory disclosure mandates force supply chain transparency upgrades. These shifts favor capital-rich players with integrated asset footprints.
Continuous-flow enzymatic transesterification is automating quality control and yield optimization in Malaysian processing plants. Wilmar International and KLK OLEO have deployed immobilized lipase systems at commercial scale, reducing catalyst consumption and wastewater treatment costs. This technology is automating batch-to-batch consistency that previously required manual laboratory intervention, compressing quality assurance headcount and accelerating certification audit readiness.
EU F-Gas Regulation amendments are tightening restrictions on fluorinated surfactants in industrial applications, redirecting formulation demand toward palm methyl ester derivatives as biodegradable alternatives. German and Dutch chemical distributors are expanding dedicated renewable surfactant procurement desks to manage compliance transitions. The industrial lubricant segment is most affected, with BASF and Clariant accelerating methyl ester sulfonate capacity expansions to capture displaced fluorochemical volumes.
Buyers are consolidating supplier relationships around vertically integrated plantation-to-ester producers with documented ISCC-EU certification. European personal care brands are reducing qualified vendor lists from twelve to three sources, prioritizing partners with captive Malaysian or Indonesian plantation supply. This concentration is most visible in German and French cosmetic manufacturing clusters, where procurement teams now require blockchain-verified chain-of-custody documentation as a standard contract term.
Palm Methyl Ester Market Segmentation

Palm methyl ester demand fragments across four distinct category dimensions, each reflecting divergent technical specifications and procurement economics. Buyers optimize formulation choices against cold-flow properties, oxidative stability, and certification requirements that vary sharply by end-use.
Product Type:
Upgrade cycles in fuel standards and surfactant chemistry are redrawing product mix priorities across Indonesian and Malaysian processing assets.
- Biodiesel:Fatty acid methyl esters meeting EN 14214 or ASTM D6751 specifications with cloud points of 10-15°C, anchoring Indonesian transport sector offtake under the B35 mandate while facing winter blending limits in temperate European climates.
- Surfactants:Fractionated ester derivatives with tailored carbon chain distributions (C12-C18) command premium positioning in German and French personal care manufacturing, where EU REACH compliance forces substitution away from petrochemical feedstocks.
- Lubricants:High-oleic variants provide biodegradable base stocks for hydraulic fluids and metalworking applications.
- Emulsifiers:Food-grade and industrial emulsification agents serve processed food and agrochemical formulation channels.
Biodiesel sits at the top of the volume ranking, with surfactants climbing the fastest.
Application:
Cost tier stratification separates commodity fuel blending from specialty chemical formulations with divergent margin structures.
- Automotive:Diesel blending applications in Indonesia and Malaysia absorb standardized ester grades with minimal specification variation, compressing processor margins through volume-driven procurement by state energy distributors.
- Personal Care:Cosmetic-grade methyl esters with ultra-low moisture content and color specifications serve reformulation demand from L'Oréal and Unilever supply chains, where clean-label positioning justifies 40-60% price premiums over industrial grades.
- Industrial:Manufacturing lubricant and solvent applications favor mid-tier ester specifications.
- Household:Concentrated liquid detergent formats in Southeast Asian urban markets drive surfactant-grade consumption.
Automotive commands absolute volume leadership, with personal care expanding most quickly.
End User:
Customer type concentration reflects the transport sector's structural anchoring through biodiesel mandates versus dispersed specialty demand.
- Transport:State-owned fuel distributors in Jakarta and Kuala Lumpur execute offtake agreements under B35 and B20 programs, creating demand basins that absorb 60-70% of regional biodiesel-grade production regardless of export price fluctuations.
- Manufacturing:European industrial lubricant compounders source ISCC-certified specialty esters through Rotterdam and Hamburg trading desks, requiring blockchain-verified chain-of-custody documentation under EU CSRD disclosure mandates.
- Agriculture:Biopesticide and crop oil concentrate formulations consume emulsifier-grade esters.
- Retail:Small-volume personal care and household product channels access surfactant grades through distributor networks.
Transport dominates volume absorption, with manufacturing gaining share fastest on sustainability certification requirements.
Distribution Channel:
Supply concentration in Malaysian oleochemical processing zones shapes channel economics and customer access patterns.
- Direct Sales:Integrated plantation-to-ester producers including Wilmar International and IOI Group negotiate multi-year supply agreements with European personal care brands, embedding ISCC-EU certification and fixed-price hedging clauses that bypass commodity trading volatility.
- Distributors:German and Dutch chemical distributors maintain dedicated renewable surfactant procurement desks to manage EU F-Gas Regulation compliance transitions, consolidating fragmented buyer demand into volume commitments with Malaysian processors.
- B2B:Industrial lubricant and biodiesel blending customers access standardized grades through trader-mediated spot markets.
- Online Retail:Specialty ester samples and small-batch surfactant grades reach independent cosmetic formulators through digital platforms.
Direct sales capture the largest volume flows, with distributor channels climbing fastest on regulatory complexity management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian oleochemical processing zones in Port Klang and Pasir Gudang concentrate the bulk of global palm methyl ester conversion capacity. Indonesian plantation belts feed upstream supply chains while European formulators drive certification requirements. Demand patterns diverge sharply between mandated biodiesel absorption in Southeast Asia and premium surfactant procurement in Western Europe.
Indonesia
State-owned fuel distributors under the B35 mandate absorb 60-70% of domestic biodiesel-grade production regardless of export price fluctuations. The Ministry of Energy and Mineral Resources enforces blending quotas through Pertamina offtake agreements. Riau and North Sumatra plantation belts supply feedstock to Dumai and Belawan processing clusters where transesterification capacity has expanded to meet mandate volumes.
Malaysia
ISCC-EU certification has become a mandatory entry ticket for European personal care brand supply chains. The Malaysian Palm Oil Board coordinates sustainability verification protocols that align with EU REACH documentation requirements. Johor's Pasir Gudang oleochemical zone and Selangor's Port Klang refineries now host the majority of certified ester derivative output serving German and French cosmetic manufacturers.
Germany
Industrial lubricant compounders in the Rhine-Ruhr manufacturing belt source specialty esters through Rotterdam trading desks with blockchain-verified chain-of-custody documentation. The Federal Environment Agency implements EU F-Gas Regulation amendments that redirect formulation demand away from fluorinated surfactants. Hamburg chemical distributors have established dedicated renewable surfactant procurement desks to manage compliance transitions for metalworking fluid applications.
France
Cosmetic-grade methyl ester procurement concentrates among Paris-region formulators serving L'Oréal and Unilever supply chains with clean-label positioning requirements. ANSM oversees cosmetic ingredient safety assessments that favor biodegradable palm derivatives over petrochemical alternatives. The Hauts-de-France chemical cluster near Lille has emerged as a secondary hub for surfactant blending operations targeting household cleaning channels.
Netherlands
Rotterdam's port infrastructure handles the majority of ISCC-certified palm methyl ester imports from Southeast Asia before redistribution to European manufacturing clusters. The Human Environment and Transport Inspectorate enforces EU Green Deal renewable fuel criteria that constrain market access for uncertified supply. Chemical trading houses in the Rotterdam-Antwerp corridor have consolidated vendor relationships around vertically integrated Malaysian producers with documented plantation-to-ester traceability.
Palm Methyl Ester Market Competitive Environment
Backward integration into plantation assets dominates the current landscape as processors seek feedstock cost control against crude palm oil volatility. The vendor base organizes around three strategic archetypes: integrated plantation-to-oleochemical conglomerates with captive Malaysian and Indonesian supply; European specialty chemical distributors managing certification complexity for formulator clients; and mid-scale processors competing on surfactant-grade fractionation capabilities. Competitive intensity concentrates on ISCC certification timelines and multi-year supply agreement negotiations with European personal care brands.
Within the integrated conglomerate tier, Wilmar International and IOI Group exemplify the plantation-captive model that European procurement teams now prioritize for Scope 3 disclosure compliance. KLK OLEO occupies a position among specialty ester derivative specialists competing on industrial lubricant applications with superior oxidative stability profiles. These three anchors represent the consolidation trajectory as qualified vendor lists contract from twelve sources to three preferred partners with verified sustainability credentials.
| Leading Market Players |
|---|
| Wilmar International |
| IOI Group |
| KLK OLEO |
| Musim Mas Group |
| Sime Darby Plantation Berhad |
| Cargill |
| Emery Oleochemicals |
| Ecogreen Oleochemicals |
| Kao Corporation |
| Others |
Value Chain & Pricing Dynamics
Skilled transesterification technicians concentrated in Malaysia's Pasir Gudang and Port Klang oleochemical zones command wage premiums that widen spreads between surfactant-grade and biodiesel-grade ester pricing. Labor-cost differentials between certified and uncertified processing facilities amplify tier separation as European buyers absorb sustainability premiums for ISCC-EU documentation.
Pricing Analysis
Input-cost pass-through from crude palm oil feedstock dominates pricing structures, with biodiesel-grade esters tracking commodity spot movements while surfactant-grade derivatives command contract-based long-term offtake premiums. Price differentiation separates ISCC-certified premium tiers from uncertified standard grades, with certification level and volume scale as primary drivers. Cost compression in biodiesel tiers is intensifying because state mandate pricing caps limit pass-through flexibility. State-owned fuel distributors in Indonesia exhibit highest price sensitivity, while European personal care brands demonstrate lowest sensitivity due to clean-label positioning requirements.
Supply Chain Analysis
Workforce availability constraints in Malaysian and Indonesian processing zones are tightening as enzymatic transesterification adoption outpaces technician training pipelines. Geographic supply concentration centers on Malaysia, Indonesia, and Netherlands redistribution hubs. Raw material dependencies draw from Riau and North Sumatra plantation belts, Rotterdam port infrastructure, and German chemical distributor networks. Single-source vulnerability from Malaysian oleochemical zone concentration creates weather and policy-related disruption exposure. Distribution runs through direct sales for integrated producers and trader-mediated spot markets for industrial biodiesel blenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by Indonesia's B35 and Malaysia's B20 biodiesel mandates, which structurally guarantee baseline offtake regardless of export price volatility.
For Market Incumbents: Acquire plantation assets in Riau and North Sumatra to secure feedstock cost control against crude palm oil volatility. Deepen backward integration into certified sustainable production streams to defend margin position against emerging Indonesian processors seeking ISCC-EU accreditation. Prioritize enzymatic transesterification R&D investment to automate quality assurance and compress certification audit timelines. For New Entrants and Emerging Players: Capture industrial lubricant formulation demand in European manufacturing clusters where biodegradable base stock requirements outpace incumbent specialty ester capacity. Target surfactant-grade fractionation for Southeast Asian household cleaning channels, where concentrated liquid detergent formats drive consumption outside personal care verticals. Pursue distributor partnerships with Rotterdam-Antwerp chemical trading houses managing EU F-Gas Regulation compliance transitions. For Investors and Strategic Acquirers: Specialty chemical distributors are the most active acquirer in this space, consolidating fragmented buyer demand into volume commitments with Malaysian processors. Long-term viability across the projection horizon rests on plantation-to-ester traceability capabilities that satisfy EU CSRD Scope 3 disclosure mandates. Monitor ISCC certification timeline compression as the critical inflection signal—audit cycle delays indicate incumbent consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Captures feedstock cost control against crude palm oil volatility in Riau and North Sumatra belts. |
| ISCC-EU Certification Investment | Unlocks European personal care supply chains requiring blockchain-verified chain-of-custody documentation. |
| Enzymatic Transesterification Deployment | Reduces catalyst consumption and wastewater treatment costs at Malaysian processing plants. |
| Long-term Supply Agreement Negotiation | Embeds fixed-price hedging clauses with German and French cosmetic manufacturers. |
| Specialty Ester Derivative Capacity Expansion | Captures premium margin pools from industrial lubricant applications with superior oxidative stability. |
Study Parameters
Direct dialogue with oleochemical plant managers, European personal care procurement leads, ISCC certification auditors, and Rotterdam chemical trading desk operators grounded qualitative insights. Secondary validation drew from Malaysian Palm Oil Board sustainability reports, EU REACH compliance documentation, Indonesia Ministry of Energy mandate filings, and customs trade data. Bottom-up capacity assessments across Port Klang and Pasir Gudang processing zones triangulated against top-down demand modeling from biodiesel blending mandates and surfactant reformulation trends.
Bottom-up modeling aggregated individual plant capacity, utilization rates, and product mix assumptions across Malaysian and Indonesian processing assets. Segmentation dimensions included product type tier, application vertical, end-user category, and distribution channel structure. CAGRs were derived from mandate-driven volume baselines and premium segment elasticity assessments. Industry-specific forecast inputs incorporated EU F-Gas Regulation amendment timelines and enzymatic processing yield improvement trajectories.
Underlying measurement precision varies by segment; biodiesel-grade production volumes carry tighter precision than specialty surfactant-grade derivative pricing. Forecasts reflect documented assumptions regarding mandate enforcement continuity, certification audit cycle durations, and crude palm oil price band stability. Material deviation in Indonesian export policy or EU renewable fuel criteria stringency warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Global Methane Hydrate Market
Fuels
Gas and Solid Fuels (Wood) Fireplaces Market
Fuels
Emulsified Fuel Market
Fuels
Germany Bunker Fuel Market
Fuels
Alcohol-To-Jet (ATJ) Fuel Market
Fuels
Turbine Drip Oil Market
Fuels
South America Commercial Aircraft Aviation Fuel Market
Fuels
Methane Market
Fuels
North America Oil and Gas Lubricants Market
Fuels
Oil Dispenser Market
Fuels
United States Bunker Fuel Market
Fuels
Fuel Oxygenate Market
Fuels
Fuel Quality Testing Market
Fuels
Wood Charcoal Market
Fuels
Global Steam Coal Market
Fuels
Global Gas Cylinder Market