
 Asia-Pacific Commercial Aircraft Aviation Fuel Market | 2026-2036
Asia-Pacific Commercial Aircraft Aviation Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Commercial Aircraft Aviation Fuel Market Outlook
A capital-intensity divergence between integrated refiners and logistics-dependent distributors is reorganizing competitive tiers across the Asia-Pacific aviation fuel landscape. ExxonMobil Corporation leverages its Singapore refinery complex to anchor jet fuel supply security for Changi Airport's hub operations. Shell plc competes through pipeline-connected storage networks that sustain just-in-time delivery contracts with premium carriers.
Asia-Pacific commercial aircraft aviation fuel encompasses refined kerosene-based products meeting strict flash point, freeze point, and sulfur content specifications for turbine-powered passenger and cargo transport. Jet A-1 dominates regional procurement due to its minus forty-seven degrees Celsius freeze point suitability for high-altitude long-haul routes across Himalayan corridors. Biofuels represent the fastest-growing fuel type segment as airlines face mounting pressure to demonstrate compliance with carbon reduction commitments. Commercial airlines occupy the deepest margin pools among end users, while cargo airlines extend volume throughput during peak e-commerce seasons.
China's Civil Aviation Administration, India's Petroleum and Natural Gas Regulatory Board, and the International Air Transport Association's carbon offset frameworks collectively shape product standards and market access across the region. ASTM D1655 and DEF STAN 91-91 certification requirements filter supplier eligibility at major international gateways. Stakeholders must monitor blending mandate timelines and refinery upgrade cycles to align infrastructure investments with evolving fuel specification thresholds.
Market Dynamics
China's Civil Aviation Administration blending mandates are compressing refinery upgrade timelines while Singapore's storage hub dominance concentrates supply security planning across Southeast Asian carrier networks.
Growth Catalysts
- Sustainable Aviation Fuel Mandates:China's Civil Aviation Administration pilots at Beijing Capital, Shanghai Pudong, and Guangzhou Baiyun force SAF procurement commitments from flag carriers. Blending thresholds ratchet upward through 2030.
- Narrow-Body Fleet Expansion:Low-cost carriers across Indonesia, Vietnam, and the Philippines are locking in Airbus A320neo and Boeing 737 MAX deliveries. Jet A-1 volume commitments follow fleet induction schedules.
- Metro Airport Cluster Concentration:India's Petroleum and Natural Gas Regulatory Board pipeline expansions around Delhi Indira Gandhi, Mumbai Chhatrapati Shivaji, and Bangalore Kempegowda anchor demand density for contracted suppliers.
Market Restraints
- Crude Price Volatility Transmission:Jet fuel pricing tracks Dubai-Oman crude benchmarks with limited hedging depth for Asia-Pacific airlines. Margin compression hits unhedged regional carriers disproportionately.
- Singapore Refinery Concentration:Over half of regional export-oriented jet fuel capacity sits within the Jurong Island complex. Disruption risks from maintenance cycles or shipping channel congestion cascade through Southeast Asian supply chains.
- ASTM D1655 Certification Bottlenecks:Alternative fuel pathways face multi-year approval timelines at the ASTM International level. SAF producers stall commercial scale-up pending definitive specification amendments.
Strategic Opportunities
- Vietnam and Philippines Greenfield Airports:Long Thanh International outside Ho Chi Minh City and Bulacan International near Manila lack legacy fuel infrastructure. Integrated refinery-storage-pipeline investments capture first-mover positioning.
- Hydrotreated Esters and Fatty Acids Convergence:HEFA-SPK processing technology merges with regional palm oil and used cooking oil feedstock availability. Malaysia and Indonesia waste oil collection networks align with ASTM-certified pathway requirements.
- Direct Airline Refinery Offtake Contracts:Singapore Airlines, Cathay Pacific, and ANA are bypassing traditional trader intermediaries. Long-term purchase agreements with Reliance Jamnagar and ExxonMobil Singapore secure volume certainty.
Industry Challenges
- Specialized Refinery Technician Scarcity:Hydroprocessing unit operations for SAF production require expertise concentrated in North American and European facilities. Asia-Pacific technical training pipelines lag commissioning schedules.
- Multi-Specification Storage Segregation:Simultaneous handling of Jet A-1, SAF blends, and future synthetic fuels demands tank farm reconfiguration. Capex intensity constrains independent terminal operators.
- DEF STAN 91-91 Dual Certification Complexity:Military and dual-use airports in Australia, Japan, and South Korea require parallel defense standard compliance. Civil-military coordination delays infrastructure sharing agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Commercial Aircraft Aviation Fuel Market |
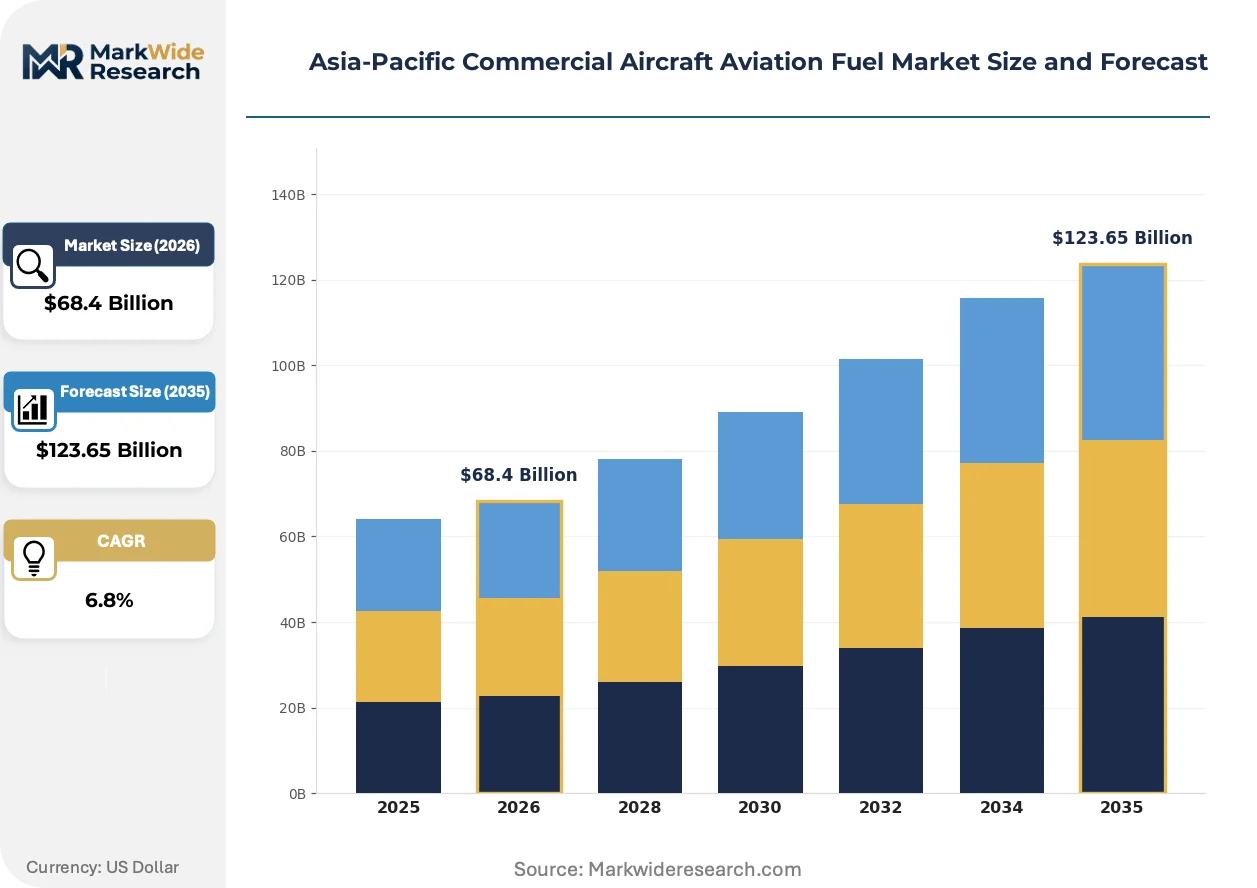
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Jet A, Jet A-1, Biofuels, Avgas Delivery Mode: Pipelines, Tankers, Truck Delivery, Airports End User: Commercial Airlines, Cargo Airlines, Charter Services, Private Operators Fuel Specification: ASTM D1655, DEF STAN 91-91, Jet A Grade, EN 228 |
| Companies Covered | ExxonMobil Corporation, Chevron Corporation, Shell plc, BP plc, TotalEnergies SE, China Aviation Oil Corporation Ltd, Bharat Petroleum Corp Ltd, Vitol Holding BV, World Fuel Services, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Commercial Aircraft Aviation Fuel Market Strategic Shifts
Digital fuel management systems and alternative processing pathways are compressing supply chain latency while regulatory certification timelines stretch product development cycles across the Asia-Pacific aviation fuel landscape.
Advanced metering infrastructure is miniaturizing. Distributed sensor networks now monitor fuel quality parameters at storage terminals, pipelines, and aircraft refueling trucks in real time. Singapore Changi and Hong Kong International deploy these systems to compress contamination detection windows from hours to minutes. The technology is miniaturizing quality assurance labor requirements while tightening specification compliance thresholds.
China's MIIT dual carbon goals and NMPA biofuel standards are accelerating domestic SAF production quotas. Refinery operators must align hydroprocessing capacity with aviation-specific certification rather than road diesel pathways. Domestic Chinese carriers face the steepest compliance ramps as provincial governments layer additional low-carbon intensity requirements onto national mandates.
Cargo airlines now unbundle fuel procurement from passenger carrier consortium arrangements. Dedicated freighter operators at Hong Kong, Incheon, and Taipei Taoyuan negotiate direct supply contracts reflecting distinct route profiles and volume seasonality. E-commerce peak cycles in November and December disrupt traditional annual contracting rhythms for integrated express carriers.
Asia-Pacific Commercial Aircraft Aviation Fuel Market Segmentation
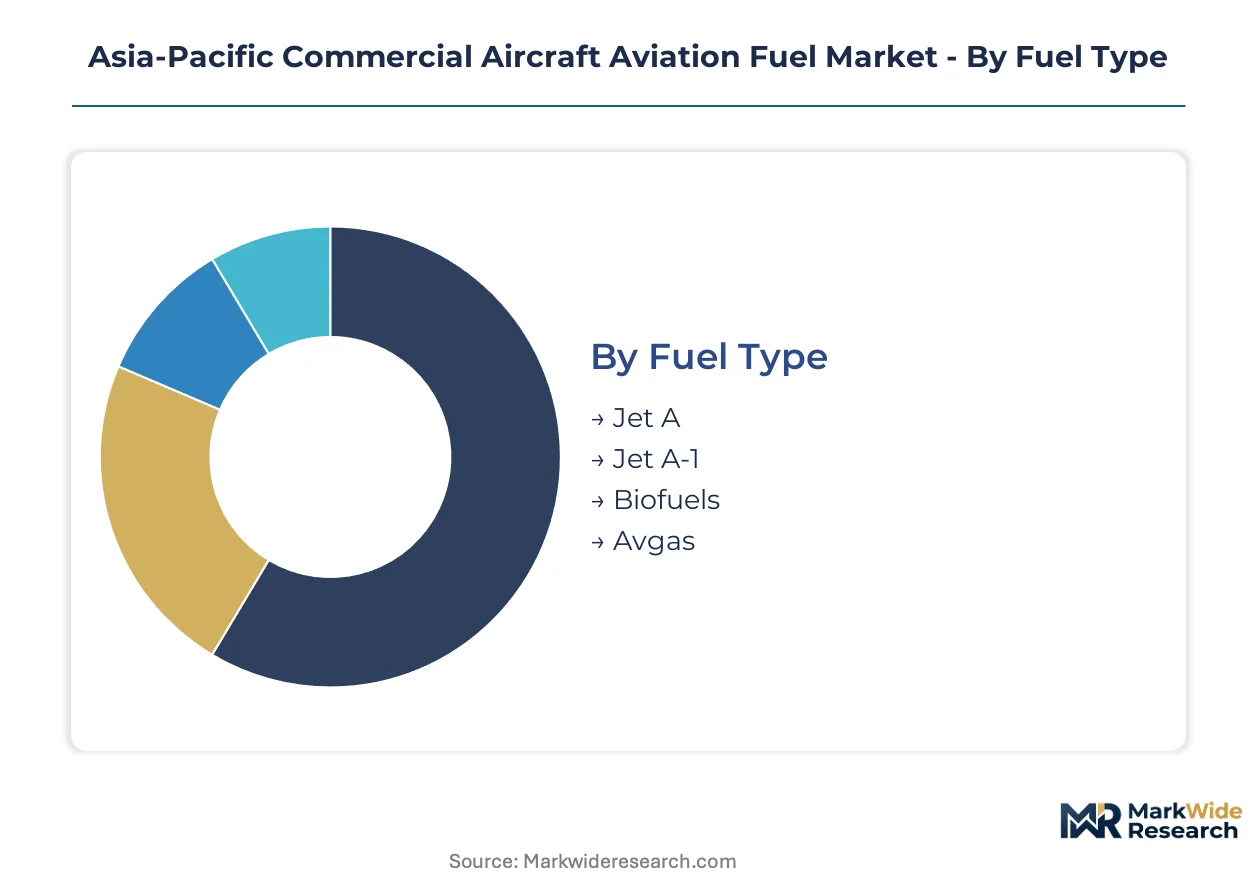
Segmentation in aviation fuel procurement determines infrastructure investment priorities across Asia-Pacific's dispersed airport network. Fuel type and specification requirements vary sharply between domestic trunk routes and long-haul international corridors, while delivery mode choices reflect refinery proximity and storage economics.
Fuel Type:
Domestic consumption centers on Jet A for shorter sectors within China and India, while export-led demand pulls Jet A-1 toward international hub airports serving transcontinental routes.
- Jet A:Refined kerosene with minus forty degrees Celsius freeze point serves domestic and regional flights across China, India, and Southeast Asia. China's MIIT domestic aviation standards prioritize Jet A for internal routes where cold-weather performance requirements moderate.
- Jet A-1:Minus forty-seven degrees Celsius freeze point specification dominates long-haul procurement at Singapore Changi, Hong Kong International, and Tokyo Narita. Himalayan corridor routes and polar tracks mandate this grade for high-altitude thermal stability.
- Biofuels:HEFA-SPK and emerging alcohol-to-jet pathways face ASTM D1655 certification timelines. Malaysia and Indonesia feedstock networks align with regional waste oil collection infrastructure.
- Avgas:High-octane aviation gasoline serves piston-engine aircraft in flight training, agricultural aviation, and general aviation sectors across Australia and New Zealand.
Jet A-1 holds the largest share; momentum sits with biofuels as China's Civil Aviation Administration blending mandates tighten.
Delivery Mode:
Cost tier separation distinguishes capital-intensive pipeline networks from flexible but higher-unit-cost truck and tanker alternatives.
- Pipelines:Dedicated aviation fuel pipelines connect Singapore's Jurong Island refineries to Changi Airport storage farms. India's Petroleum and Natural Gas Regulatory Board pipeline expansions around Delhi, Mumbai, and Bangalore anchor contracted supply security for flag carriers.
- Tankers:Coastal and inter-island tanker movements serve archipelagic Southeast Asia where pipeline economics fail. Indonesian and Philippine carrier networks depend on marine delivery for secondary hub fueling.
- Truck Delivery:Road tanker fleets reach airports lacking pipeline or coastal access across India's tier-two cities and Australia's regional airports. Unit costs run higher but enable market penetration beyond trunk infrastructure.
- Airports:On-airport storage and hydrant systems represent the terminal node of all delivery chains. Greenfield airports at Vietnam's Long Thanh and Philippines' Bulacan lack legacy hydrant infrastructure, opening first-mover positioning for integrated suppliers.
Pipelines capture the deepest volume pools; airports as infrastructure nodes are climbing the fastest as greenfield developments multiply.
End User:
Customer type segmentation separates scheduled service operators with predictable demand profiles from volatile charter and private segments.
- Commercial Airlines:Full-service and low-cost carriers generate baseline demand density at primary hubs. Narrow-body fleet commitments from Indonesia's Lion Air, Vietnam's VietJet, and Philippines' Cebu Pacific lock in Jet A-1 volume contracts.
- Cargo Airlines:Dedicated freighter operators at Hong Kong, Incheon, and Taipei Taoyuan negotiate direct supply contracts outside passenger carrier consortiums. E-commerce peak seasons in November and December disrupt traditional annual contracting rhythms.
- Charter Services:Ad hoc demand from tourism and corporate aviation segments concentrates in seasonal patterns across Thailand, Maldives, and Australian leisure destinations.
- Private Operators:Business aviation and fractional ownership fleets serve ultra-high-net-worth demand in Singapore, Shanghai, and Sydney. Volume remains marginal but pricing tolerance supports premium service tiers.
Commercial airlines hold the largest share; cargo airlines are expanding most quickly as e-commerce air freight volumes accelerate.
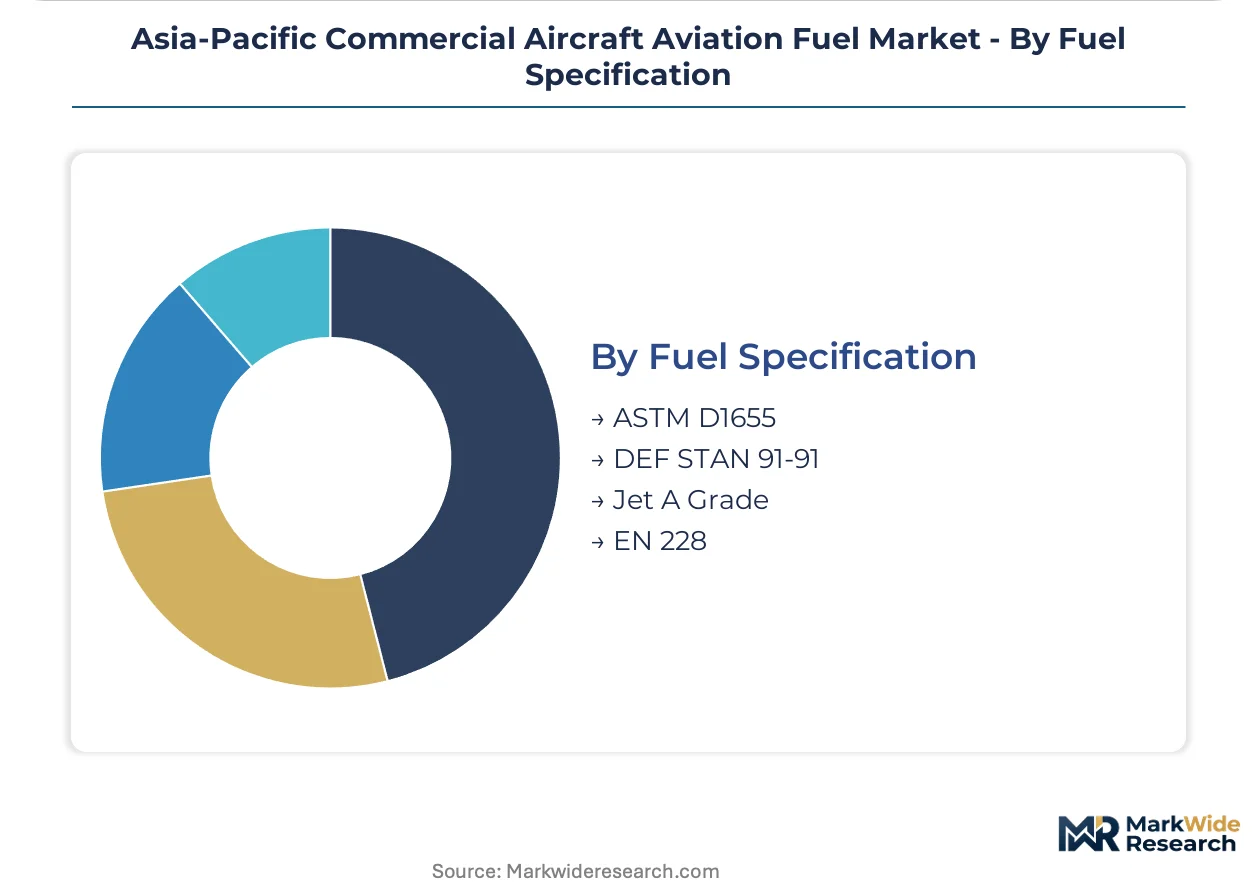
Fuel Specification:
Application-driven certification requirements filter supplier eligibility at major international gateways and dual-use military-civil airports.
- ASTM D1655:Dominant civil aviation standard across Asia-Pacific international airports. Certification gates entry for alternative fuel pathways including HEFA-SPK and Fischer-Tropsch synthetic paraffinic kerosene.
- DEF STAN 91-91:UK defense standard required at Australian, Japanese, and South Korean dual-use airports. Civil-military coordination delays infrastructure sharing agreements where both specifications must coexist.
- Jet A Grade:Simplified specification subset for domestic Chinese and Indian operations where international interchangeability is not required. China's GB standards and India's BIS alignment permit this grade for internal routes.
- EN 228:European automotive gasoline standard referenced for Avgas quality parameters in regional training aircraft and general aviation piston fleets.
ASTM D1655 holds the largest share; DEF STAN 91-91 faces the steepest expansion trajectory as defense-civil airport integration deepens across the region.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Low-cost carriers in Southeast Asia exhibit acute price sensitivity to jet fuel movements, while premium full-service operators at Singapore and Hong Kong absorb cost volatility through hedging programs. China's state-backed airlines negotiate supply security over spot-price optimization.
China
Beijing Capital, Shanghai Pudong, and Guangzhou Baiyun anchor domestic volume demand as China's Civil Aviation Administration mandates SAF blending pilots through 2030. The MIIT dual carbon framework compresses refinery upgrade timelines for hydroprocessing capacity. Yangtze River Delta airport clusters concentrate procurement negotiations with integrated suppliers.
India
Delhi Indira Gandhi, Mumbai Chhatrapati Shivaji, and Bangalore Kempegowda metro clusters generate density for pipeline-connected supply contracts. India's Petroleum and Natural Gas Regulatory Board infrastructure expansions reduce truck-dependency for flag carriers. Reliance Jamnagar refinery output secures direct offtake agreements with Air India and IndiGo.
Singapore
Changi Airport's hub operations depend on Jurong Island refinery complexes for supply security. The Maritime and Port Authority coordinates bunker and aviation fuel storage optimization across the island-state. ExxonMobil Singapore anchors regional export capacity for Southeast Asian carrier networks.
Japan
Tokyo Narita and Osaka Kansai serve as primary international gateways requiring Jet A-1 for polar and Himalayan corridor routes. METI energy security frameworks prioritize strategic petroleum reserve coordination for aviation fuel. Chubu Centrair and Fukuoka secondary hubs diversify supply chain concentration risks.
Australia
Sydney Kingsford Smith and Melbourne Tullamarine concentrate domestic trunk route demand with limited pipeline connectivity to coastal refineries. Dual-use military-civil airports require DEF STAN 91-91 certification alongside ASTM D1655 standards. Brisbane and Perth hubs manage supply through coastal tanker movements from Singapore.
Asia-Pacific Commercial Aircraft Aviation Fuel Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in Asia-Pacific aviation fuel supply. ExxonMobil Corporation and Shell plc anchor the top tier through refinery ownership and storage network control. Chevron Corporation and BP plc occupy mid-tier positions balancing upstream integration with regional trading capabilities. Specialist distributors including Vitol Holding BV and World Fuel Services compete on logistics flexibility and credit terms for unhedged carriers. Dominant competitive moves center on direct airline offtake contracts and SAF blending infrastructure investments.
Among integrated energy majors, ExxonMobil Corporation exemplifies refinery-anchored supply security through its Singapore complex position. Shell plc occupies a pipeline-connected logistics tier serving just-in-time delivery requirements at premium hubs. China Aviation Oil Corporation Ltd represents state-backed procurement consolidation for Chinese flag carrier networks.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Chevron Corporation |
| Shell plc |
| BP plc |
| TotalEnergies SE |
| China Aviation Oil Corporation Ltd |
| Bharat Petroleum Corp Ltd |
| Vitol Holding BV |
| World Fuel Services |
| Others |
Value Chain & Pricing Dynamics
ASTM D1655 certification requirements gate both supplier eligibility and price tiering across Asia-Pacific aviation fuel procurement, compressing margins for uncertified independents while rewarding integrated refiners with specification-compliant capacity. China's Civil Aviation Administration SAF blending mandates are layering additional certification costs onto Jet A-1 base pricing, forcing carriers to absorb tiered premiums for compliant fuel.
Pricing Analysis
Long-term offtake contracts with embedded service tiers now drive lifetime value for integrated suppliers. Pricing stratifies across ASTM-certified premium, dual-specification standard, and domestic-grade economy levels based on freeze point performance and sulfur content thresholds. Cost compression in the standard tier is intensifying because Singapore refinery maintenance cycles tighten spot availability for Southeast Asian low-cost carriers. Cargo airlines at Hong Kong and Incheon demonstrate lowest price sensitivity due to e-commerce volume premiums, while Indonesian and Philippine budget carriers operate with minimal hedging depth.
Supply Chain Analysis
Singapore, India, and China anchor regional jet fuel production through Jurong Island refining, Jamnagar export capacity, and Sinopec hydroprocessing installations. Feedstock draws from Dubai-Oman crude benchmarks, regional palm oil waste streams, and imported hydroprocessing catalysts. Single-source vulnerability concentrates in Singapore's Jurong complex, where maintenance disruptions cascade through Southeast Asian carrier networks. Distribution runs through pipeline-connected storage at Delhi-Mumbai-Bangalore clusters, coastal tanker movements for archipelagic Southeast Asia, and road delivery for India's tier-two airports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific aviation fuel demand is recovering through narrow-body fleet induction cycles across Southeast Asian low-cost carriers. This cyclical upswing rests on Airbus A320neo and Boeing 737 MAX delivery schedules locked in through the mid-2020s.
For Market Incumbents: Compound refinery-storage integration advantages by securing direct airline offtake contracts before greenfield airport commissioning at Vietnam's Long Thanh and Philippines' Bulacan. Expand hydroprocessing capacity for HEFA-SPK pathways to preempt China's Civil Aviation Administration blending threshold escalations. Lock in pipeline-connected terminal positions around India's metro airport clusters to defend against trader intermediaries eroding margin pools. For New Entrants and Emerging Players: Differentiate on waste oil feedstock aggregation capabilities across Malaysia and Indonesia, where used cooking oil collection networks align with ASTM-certified HEFA-SPK requirements. Target secondary hub fueling at tier-two Indian cities and Australian regional airports lacking pipeline infrastructure. Pursue direct airline partnerships bypassing incumbent trader networks through flexible credit terms and smaller minimum volume commitments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across SAF blending infrastructure as hydroprocessing unit capex requirements separate integrated refiners from logistics-dependent distributors. Five-to-ten year viability favors suppliers with captive refinery capacity and certification-compliant storage segregation. Monitor ASTM D1655 amendment timelines for alternative fuel pathways as the critical inflection signal for SAF production scale-up viability.| Strategic Initiative | Industry Significance |
|---|---|
| SAF Blending Infrastructure Investment | China's Civil Aviation Administration mandates compress upgrade timelines for hydroprocessing capacity. |
| Direct Airline Offtake Contracts | Singapore Airlines and Cathay Pacific bypass traders to secure volume certainty with Reliance Jamnagar. |
| Greenfield Airport First-Mover Positioning | Long Thanh and Bulacan lack legacy hydrant infrastructure, opening integrated supply capture. |
| HEFA-SPK Feedstock Network Development | Malaysia and Indonesia waste oil collection aligns with ASTM-certified pathway requirements. |
| Pipeline-Connected Storage Expansion | India's Petroleum and Natural Gas Regulatory Board infrastructure reduces truck-dependency for flag carriers. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with refinery operations managers, aviation fuel procurement leads at full-service and low-cost carriers, terminal storage operators, and China's Civil Aviation Administration policy officials. Secondary validation drew from IATA carbon offset framework disclosures, Petroleum and Natural Gas Regulatory Board pipeline expansion filings, ASTM International certification amendment dockets, and customs trade data for regional jet fuel movements. Bottom-up volume modeling triangulated against top-down refinery capacity assessments across the analysis window.
Across the projection horizon, forecasts segment by fuel type, delivery mode, end-user category, and fuel specification tier. CAGRs derive from fleet induction schedules, blending mandate compliance ramps, and infrastructure commissioning timelines. Modeled inputs include narrow-body delivery backlogs, hydroprocessing capacity expansion announcements, and greenfield airport development progressions.
Forecasts assume regulatory continuity in China's Civil Aviation Administration blending pilots and India's Petroleum and Natural Gas Regulatory Board infrastructure frameworks; material policy shifts would require re-modeling. Crude benchmark volatility, Singapore refinery disruption events, and ASTM certification delays for alternative fuel pathways represent specific revision triggers. Recalibration cycles align with material shifts in fleet delivery schedules and mandate threshold announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Pyrolysis Gas Market
Fuels
Global Wood Gas Generator Market
Fuels
India Retail Fuel Market
Fuels
North America Bunker Fuel Market
Fuels
Anthracite Coal Mining Market
Fuels
Diesel As Fuel Market
Fuels
Fuel Conditioning System Market
Fuels
Bunker Fuel Market
Fuels
Coal Briquettes Market
Fuels
Refuse Derived Fuel Market
Fuels
Palm Methyl Ester Market
Fuels
Smart Gas Solutions Market
Fuels
Chafing Fuel Market
Fuels
Fuel Grinder Market
Fuels
Coal Briquette Box Market
Fuels
North America Commercial Aircraft Aviation Fuel Market