
 South Korea LNG Bunkering Market | 2026-2036
South Korea LNG Bunkering Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea LNG Bunkering Market Analytics
Aftermarket service revenue is tilting toward integrated bunkering logistics as vessel operators seek single-source fuel and maintenance contracts. Korea Gas Corporation leverages its nationwide pipeline network to anchor storage and regasification capacity near major ports. POSCO International competes through upstream LNG procurement contracts that secure supply certainty for maritime clients. Wartsila Oyj Abp specializes in dual-fuel engine retrofits, extending its service footprint across Korean shipyards.
South Korea LNG bunkering denotes the transfer of liquefied natural gas to marine vessels for propulsion or auxiliary power, requiring cryogenic storage at minus 162 degrees Celsius and specialized manifold connections compliant with ISO 20519. Ship-to-Ship delivery dominates transaction volumes where deepwater anchorage permits direct carrier-to-vessel transfers without port congestion. Port-to-Ship infrastructure leads capital deployment along the Busan and Gwangyang coastlines. Conventional LNG retains near-term volume leadership while Bio-LNG procurement expands under Korea's green shipping certification pathways.
MFDS maritime safety standards, Ministry of Oceans and Fisheries port emission rules, and KSA shipbuilding codes collectively mandate cryogenic handling protocols and crew certification for LNG fuel operations. These frameworks shape demand by restricting market access to certified terminal operators and licensed vessel crews. Stakeholders must monitor regulatory alignment between domestic green corridor initiatives and International Maritime Organization fuel standards to anticipate infrastructure investment timing.
Market Dynamics
The Ministry of Oceans and Fisheries enforces emission control area compliance that compels domestic vessel operators to switch from marine diesel to LNG propulsion, creating immediate demand pull for cryogenic bunkering infrastructure at Busan, Ulsan, and Gwangyang ports.
Growth Catalysts
- Green Shipping Certification Pathways:Korea's maritime decarbonization framework rewards LNG adoption with port fee reductions and priority berthing rights for certified low-emission vessels.
- Container Fleet Electrification:Major shipping lines are expanding LNG-powered vessel orders, generating recurring bunkering demand along Korean trade routes.
- Busan-Ulsan Industrial Corridor:Concentrated heavy industry and shipbuilding activity creates dense clusters of dual-fuel vessel demand within short steaming distances.
Market Restraints
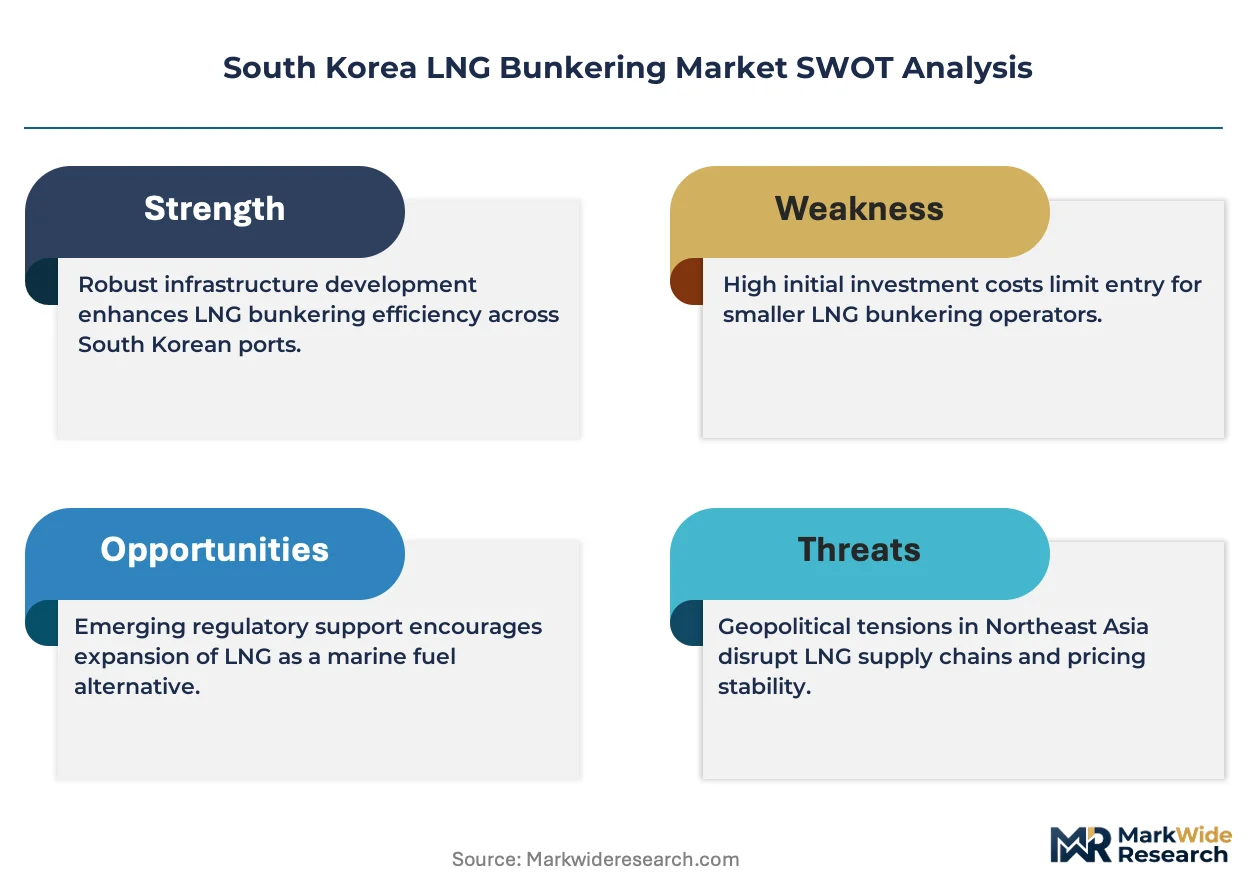
- Cryogenic Infrastructure Capital Intensity:Shoreside LNG storage and regasification terminals require specialized cryogenic materials and vacuum-insulated piping that inflate upfront investment.
- Supply Concentration in Qatari and Australian Contracts:Long-term LNG procurement for maritime bunkering relies on a narrow supplier base, exposing operators to cargo diversion risk during supply shocks.
- Dual-Fuel Engine Retrofit Technical Limitation:Existing diesel vessels face structural constraints on cryogenic fuel tank placement and engine room ventilation that limit conversion feasibility.
Strategic Opportunities
- Jeju Maritime Green Corridor:The island's designation as a domestic emission control area creates a contained testing ground for bio-LNG blending and small-scale bunkering operations.
- Ship-to-Ship Service Expansion:Deepwater anchorage off Yeosu offers untapped potential for direct carrier-to-vessel transfers without port congestion penalties.
- MFDS Crew Certification Programs:Maritime safety standards mandating specialized cryogenic handling training create ancillary revenue streams for certified training providers.
Industry Challenges
- Cryogenic Systems Engineering Talent Gap:The specialized knowledge required for minus 162 degrees Celsius fuel system design and maintenance outpaces domestic vocational training output.
- ISO 20519 Compliance Timeline:Bunkering manifold connection standardization demands extended certification periods that delay operational commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea LNG Bunkering Market |
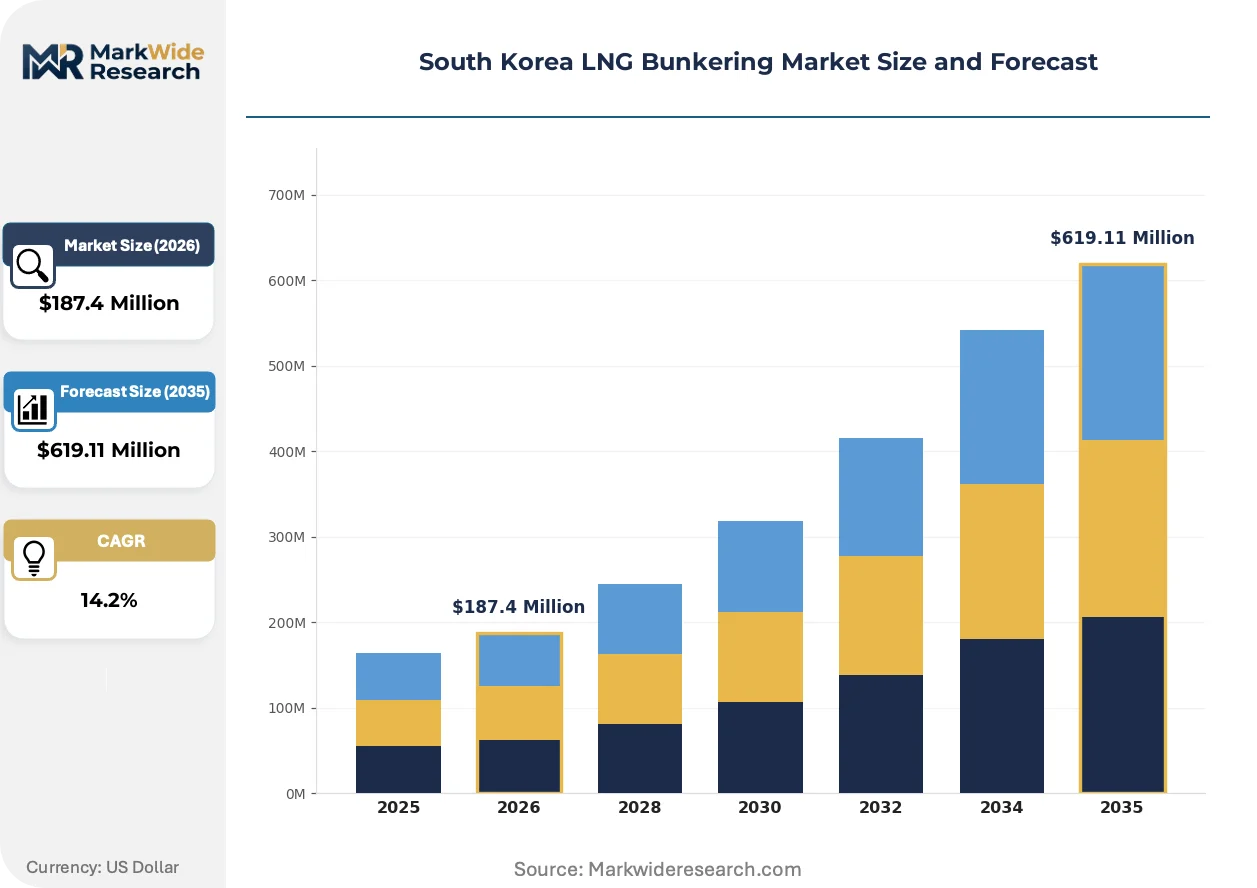
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ship-to-Ship, Port-to-Ship, Truck-to-Ship, Barge Supply End User: Shipping Companies, Freight Forwarders, Vessel Operators, Tanker Owners Supply Chain Model: Direct Supply, Reseller, Terminal Operator, Third-Party Logistics Fuel Grade: Bio-LNG, Synthetic LNG, Conventional LNG, Others |
| Companies Covered | HD Hyundai Chemical, TotalEnergies, Korea Gas Corporation, POSCO International, Korea National Oil Corporation, Korea Line Corporation, Wartsila Oyj Abp, SK Energy, HD Korea Shipbuilding & Offshore Engineering, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea LNG Bunkering Market Evolving Landscape
Maritime fuel technology is converging with digital logistics platforms and synthetic fuel pathways, reshaping how vessel operators procure, store, and consume LNG across Korean waters.
Dual-fuel engine architecture is hybridizing with battery-electric auxiliary systems to create hybrid propulsion configurations. Container shipping lines operating Korea-Japan routes are piloting these integrated powertrains to optimize fuel consumption during port approach and idle periods. This convergence is compressing the operational boundary between pure LNG and full-electric vessel categories.
MFDS maritime safety standards now mandate real-time cryogenic fuel monitoring and automated emergency shutdown protocols for all LNG-fueled vessels above gross tonnage thresholds. The regulatory framework forces terminal operators to upgrade legacy bunkering arms with sensor-integrated manifold connections. Domestic ferry operators serving Busan-Fukuoka routes face the most compressed compliance timelines.
Vessel operators are consolidating fuel procurement under integrated logistics contracts that bundle bunkering, maintenance, and emissions compliance reporting. Single-source contracting displaces fragmented spot-market purchasing among mid-size domestic shipping companies. This pattern concentrates most visibly among operators based in the Ulsan industrial zone seeking operational simplification.
South Korea LNG Bunkering Market Segmentation
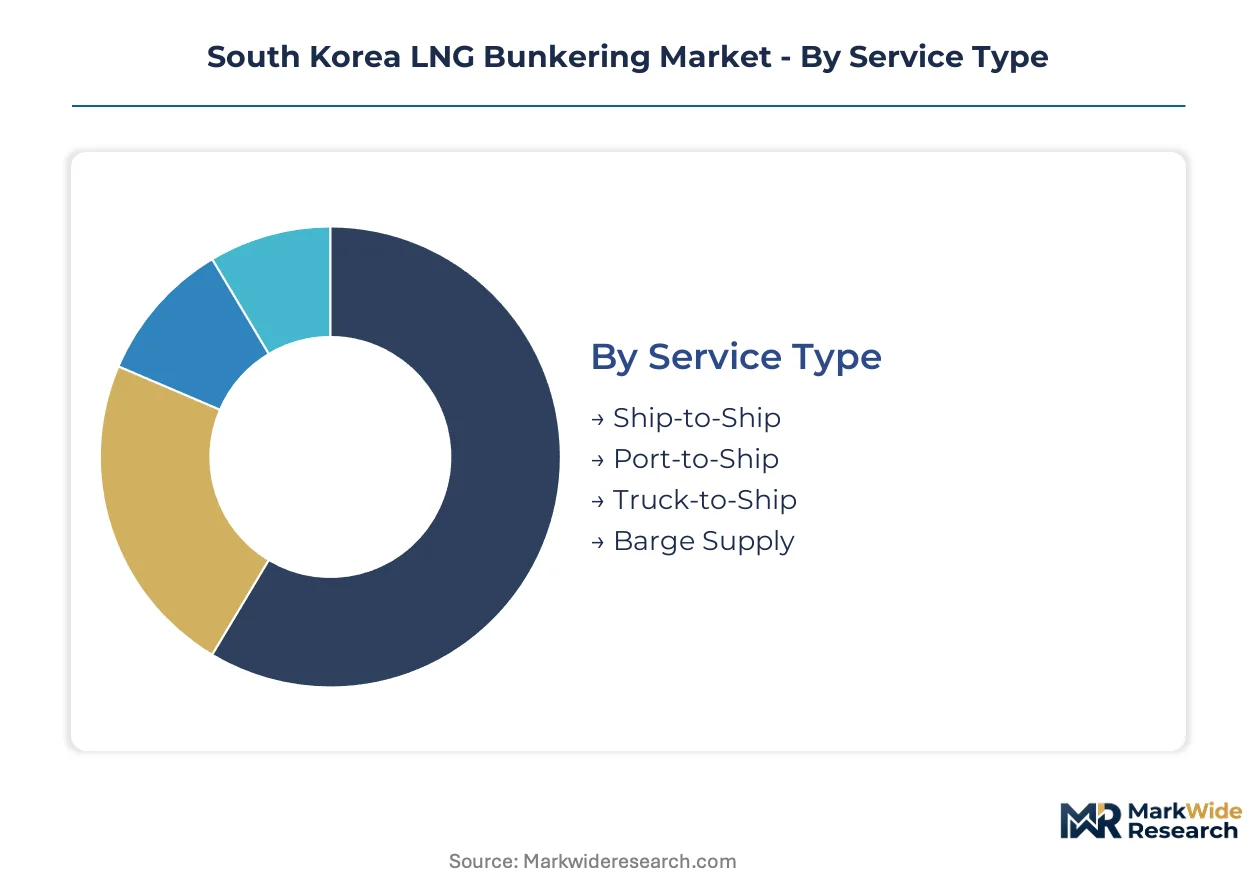
LNG bunkering infrastructure in South Korea serves distinct operational profiles across vessel types, fuel specifications, and delivery modalities. Segment-level differentiation determines capital deployment priorities for terminal operators and procurement strategies for maritime clients operating under MFDS safety mandates.
Service Type:
Delivery modality selection hinges on water depth, port congestion penalties, and vessel size compatibility across Korean anchorage zones.
- Ship-to-Ship:Direct carrier-to-vessel transfers at minus 162 degrees Celsius occur in deepwater anchorages off Busan and Yeosu, bypassing port queue constraints for large container vessels. Korean shipping lines with LNG-powered newbuilds concentrate demand here to minimize turnaround time.
- Port-to-Ship:Shoreside manifold connections at dedicated LNG terminals dominate capital deployment along the Gwangyang industrial coastline. MFDS-mandated cryogenic monitoring systems and automated emergency shutdown protocols inflate infrastructure costs for this modality.
- Truck-to-Ship:Mobile cryogenic tanker delivery serves small-scale ferry operations and harbor craft with limited storage capacity. Jeju maritime green corridor pilots utilize this flexibility for bio-LNG blending trials.
- Barge Supply:Intermediate volume transfers from floating storage units accommodate mid-size bulk carriers without dedicated LNG infrastructure. Ulsan industrial corridor vessel operators favor this option during terminal maintenance windows.
Established volume favors Port-to-Ship; emerging adoption favors Ship-to-Ship.
End User:
Procurement authority varies by fleet ownership structure and chartering arrangements within Korean maritime commerce.
- Shipping Companies:Integrated container lines with LNG-powered fleet orders negotiate long-term bunkering contracts tied to vessel delivery schedules. HMM and Sinokor Maritime anchor demand through binding offtake agreements with Korea Gas Corporation.
- Freight Forwarders:Non-vessel-operating common carriers lack direct fuel procurement authority but influence carrier selection based on emissions certification requirements for cargo owners.
- Vessel Operators:Third-party ship managers operating chartered tonnage face split incentive problems where owners bear retrofit costs while operators manage fuel expenditure.
- Tanker Owners:Specialized LNG carrier operators with spare cargo capacity occasionally engage in opportunistic bunkering sales during positioning voyages.
Contracting leverage concentrates with Shipping Companies; operational flexibility favors Vessel Operators.
Supply Chain Model:
Integration depth determines margin capture and supply certainty for maritime fuel delivery.
- Direct Supply:Upstream LNG producers or national gas utilities contract directly with vessel operators, eliminating intermediary markups. Korea Gas Corporation leverages pipeline network proximity to major ports for this structure.
- Reseller:Independent traders aggregate spot market cargoes for fragmented domestic shipping companies lacking procurement scale. Price volatility exposure limits contract duration.
- Terminal Operator:Port authority-affiliated entities bundle storage, regasification, and bunkering services under single-tariff arrangements. Busan Port Authority pursues this model to maximize facility utilization.
- Third-Party Logistics:Integrated providers bundle fuel delivery with maintenance, crew certification, and emissions compliance reporting. Mid-size operators in the Ulsan industrial zone increasingly consolidate procurement here.
Margin stability favors Terminal Operator; customization breadth favors Third-Party Logistics.
Fuel Grade:
Carbon intensity differentiation drives procurement decisions under Korea's green shipping certification pathways.
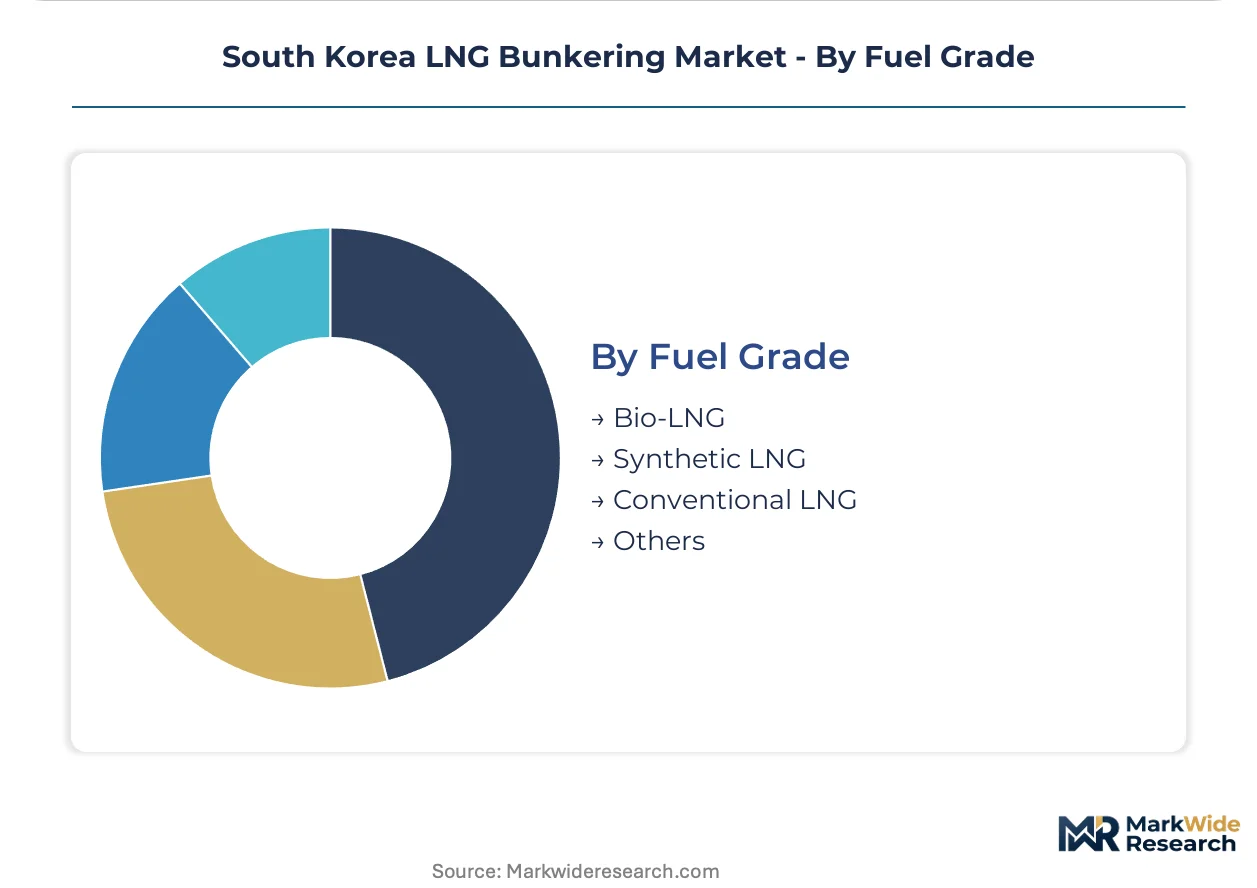
- Bio-LNG:Liquefied biomethane derived from organic waste streams qualifies for enhanced port fee reductions and priority berthing rights. Domestic production capacity remains constrained by feedstock availability.
- Synthetic LNG:Power-to-X e-fuels produced from renewable hydrogen and captured carbon dioxide remain pre-commercial at scale. Korean shipyards monitor pilot projects for future retrofit compatibility.
- Conventional LNG:Fossil-derived liquefied natural gas from Qatari and Australian long-term contracts supplies near-term volume requirements. Supply concentration exposes operators to cargo diversion risk during supply shocks.
- Others:Emerging blends including ammonia-LNG mixtures and methane slip-reduced formulations occupy experimental niches pending engine technology maturation.
Cost competitiveness favors Conventional LNG; regulatory preference favors Bio-LNG.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across South Korea's maritime corridors. Domestic ferry operators in the Jeju green corridor prioritize bio-LNG premiums for certification benefits, while bulk carriers along the Ulsan industrial belt minimize unit costs through long-term offtake contracts.
Seoul Capital Area
Administrative and financial headquarters of major shipping lines drive procurement decision-making rather than physical bunkering operations. MFDS regulatory filings and crew certification programs concentrate here, shaping nationwide compliance standards. Incheon Port handles limited LNG volumes but anchors policy coordination between the Ministry of Oceans and Fisheries and vessel operators.
Busan-Ulsan
Deepwater anchorage and dense shipbuilding activity generate the highest transaction volumes for ship-to-ship transfers. The Ministry of Oceans and Fisheries designates this corridor as a priority emission control area, accelerating dual-fuel retrofits at Hyundai Heavy Industries facilities. Ulsan's industrial zone clusters demand from petrochemical tankers and bulk carriers within short steaming distances of storage terminals.
Daegu-Gyeongbuk
Inland manufacturing supply chains feed component production for cryogenic systems and bunkering equipment. The region lacks direct port access but anchors vocational training programs for cryogenic handling certification under MFDS mandates. Pohang's steel export terminals generate ancillary demand for LNG-fueled coastal feeders.
Daejeon-Sejong
Government research institutes and standardization bodies drive technical specifications for ISO 20519-compliant manifold connections. Korea Gas Corporation coordinates pipeline network extensions from this administrative hub. The region influences infrastructure investment timing without direct bunkering operations.
Gwangju-Honam
Gwangyang Port's dedicated LNG terminals lead capital deployment for shoreside regasification and bunkering integration. POSCO International leverages proximity to steel export facilities for captive fuel demand. The Yeosu deepwater anchorage offers untapped ship-to-ship expansion potential for mid-size bulk carriers.
South Korea LNG Bunkering Market Competitive Landscape
National gas utilities and international energy majors split the market between infrastructure control and supply certainty. The competitive structure concentrates around two distinct strategic archetypes: pipeline-anchored domestic incumbents with storage and regasification assets, and trading-oriented multinationals with upstream procurement contracts. Capacity expansion along the Busan-Ulsan coastline and strategic partnerships for bio-LNG sourcing represent the dominant competitive moves.
Within the domestic utility tier, Korea Gas Corporation exemplifies pipeline-network leverage for terminal proximity, while POSCO International occupies a position linking industrial demand clusters with maritime fuel supply. Wartsila Oyj Abp represents the specialized engineering archetype, anchoring dual-fuel retrofit capabilities across Korean shipyards without direct fuel trading exposure.
| Leading Market Players |
|---|
| HD Hyundai Chemical |
| TotalEnergies |
| Korea Gas Corporation |
| POSCO International |
| Korea National Oil Corporation |
| Korea Line Corporation |
| Wartsila Oyj Abp |
| SK Energy |
| HD Korea Shipbuilding & Offshore Engineering |
| Others |
Value Network & Pricing Analysis
Terminal utilization rates below 60% at Gwangyang Port are forcing Korea Gas Corporation and POSCO International into aggressive contract pricing to cover fixed regasification costs, compressing margins for spot-market participants while locking in long-term offtake volumes for integrated shipping lines.
Pricing Analysis
Aftermarket service revenue from integrated bunkering logistics contracts drives lifetime value for terminal operators bundling fuel delivery with cryogenic maintenance and MFDS compliance reporting. Three-tier pricing structure across premium bio-LNG, standard conventional LNG, and economy barge-supply tiers differentiates port fee reductions and priority berthing rights. Cost compression in economy-tier barge supply is intensifying because mid-size bulk carriers negotiate volume aggregations during terminal maintenance windows. Domestic ferry operators in the Jeju green corridor show least price sensitivity, prioritizing certification benefits over unit cost.
Supply Chain Analysis
Extended payment terms from Korean shipyards to cryogenic equipment suppliers are straining working capital for domestic valve and manifold manufacturers, accelerating consolidation toward POSCO International's captive financing facilities. LNG procurement draws from Qatari and Australian long-term contracts, with cryogenic storage tanks and vacuum-insulated piping sourced from Japanese and German specialty fabricators. Single-source vulnerability in minus 162 degrees Celsius cargo containment systems exposes operators to extended lead times during regional supply shocks. Distribution runs through Korea Gas Corporation's pipeline-anchored terminals at Busan and Gwangyang, with ship-to-ship transfers bypassing congested port queues for large container vessels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated container lines HMM and Sinokor Maritime, whose binding offtake agreements with Korea Gas Corporation are displacing fragmented spot-market purchasing and forcing terminal operators into volume-commitment structures.
For Market Incumbents: Build regulatory certification moats by accelerating MFDS cryogenic handling accreditation programs before compliance deadlines compress. Anchor storage capacity additions at Yeosu deepwater anchorage to capture ship-to-ship demand migrating from congested Busan terminals. Dual-fuel engine retrofit competition from Wartsila Oyj Abp threatens service revenue capture unless incumbents bundle maintenance contracts with fuel supply. For New Entrants and Emerging Players: Small-scale bio-LNG blending operations in the Jeju maritime green corridor represent the most penetrable entry point, given constrained domestic production capacity and premium pricing tolerance among ferry operators. Truck-to-ship delivery infrastructure for harbor craft and coastal feeders offers white-space expansion with lower capital intensity than shoreside terminal development. Partner with Korea Gas Corporation for pipeline network access rather than competing on regasification capacity. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-capture play because emission control area expansion and green shipping certification pathways will compound demand for cryogenic bunkering assets with locational scarcity value. Target acquisition archetypes include specialized cryogenic engineering firms with MFDS training accreditation and existing Korean shipyard relationships. Monitor Qatari and Australian cargo diversion incidents as supply shock indicators that would accelerate domestic storage capacity investment.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Yeosu deepwater anchorage expansion captures ship-to-ship demand without port congestion penalties. |
| Long-term Supply Agreement | Binding offtake contracts with HMM and Sinokor Maritime lock in volume certainty for Korea Gas Corporation. |
| Green Certification Program | Bio-LNG blending accreditation under MFDS maritime safety standards secures priority berthing rights. |
| Backward Integration | Upstream LNG procurement contracts through POSCO International reduce cargo diversion exposure. |
| Technology Licensing | Wartsila Oyj Abp dual-fuel engine retrofits extend service footprint across Hyundai Heavy Industries facilities. |
Research Methodology
A standing panel of terminal operations managers, shipyard procurement directors, MFDS certification officers, and Korea Gas Corporation supply planners provided ongoing calibration across the primary research phase. Secondary validation drew from Ministry of Oceans and Fisheries emission control area filings, Korea Shipbuilding & Offshore Engineering cryogenic system specifications, customs import records for cryogenic equipment, and MFDS maritime safety standard updates. Bottom-up vessel fleet projections and top-down industrial demand estimates were triangulated against observed bunkering transaction patterns.
Scenario-bracketing around supply shock probability and bio-LNG feedstock availability shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include delivery modality, fuel grade certification tier, vessel size class, and supply chain integration depth. CAGRs were derived from fitted growth curves anchored to observed infrastructure commissioning timelines and vessel orderbook deliveries. Forecast inputs incorporated MFDS regulatory compliance deadlines and Korea's green shipping certification pathway adoption curves.
Practitioners should monitor Qatari and Australian contract renegotiation cycles, domestic bio-LNG production facility commissioning, and MFDS cryogenic handling training program expansion for early signals of demand inflection. Forecasts reflect assumptions about emission control area enforcement continuity and dual-fuel newbuild delivery schedules. Macroeconomic deviation in industrial export volumes, regulatory acceleration of ammonia-LNG blending standards, or technological breakthrough in synthetic LNG production would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Global Liquid Gas Cylinder (LGC) Market
Fuels
Europe Compressed Natural Gas Dispenser Market
Fuels
Fuel Analyzer Market
Fuels
Global Chemical Logistics Market
Fuels
No.4 Fuel Oil Market
Fuels
Chafing Fuel Market
Fuels
Gasoline Market
Fuels
LPG Gas Cylinder Market
Fuels
Coal Trading Market
Fuels
Middle-East and Africa Commercial Aircraft Aviation Fuel Market
Fuels
China LNG Market
Fuels
UAE Chemical Logistics Market
Fuels
South America Bunker Fuel Market
Fuels
Petroleum Fuel Dyes Sales Market
Fuels
Italy Automotive Engine Oils Market
Fuels
Waste-Derived Pyrolysis Oil Market