
 Global Package Boilers Market | 2026-2036
Global Package Boilers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Package Boilers Market Outlook
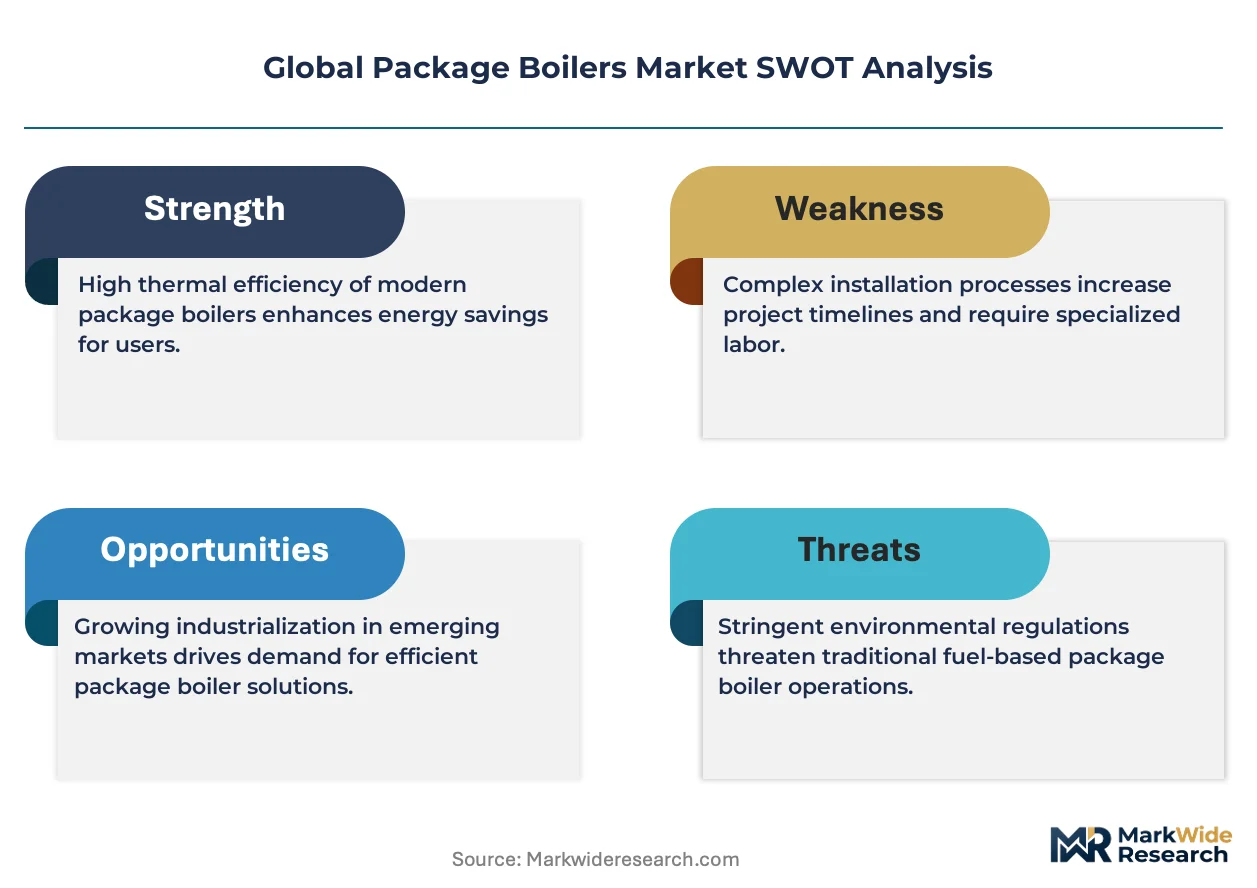
ASME Section I certification is unwinding legacy cost structures as buyers prioritize pressure-rated reliability over lowest-first-cost procurement. Cleaver-Brooks, Inc. leverages its vertical integration into burner and control systems to sustain margin capture across the specification chain. IHI Corporation anchors its position through R&D intensity in ultra-low NOx combustion architectures for East Asian utility contractors. Miura specializes in once-through water-tube designs that dominate footprint-constrained installations in pharmaceutical and beverage plants.
Package boilers are self-contained steam or hot-water generation systems factory-assembled with burner, controls, and pressure vessel on a single skid, typically rated between 10,000 and 250,000 pounds per hour of steam output for immediate site connection. Fire-tube units occupy the mature replacement cycle across North American refineries and chemical plants, while water-tube configurations lead in high-pressure process applications where rapid steam ramp rates protect batch continuity. Electric package boilers are gaining fastest in European food processing corridors where grid decarbonization targets and carbon border adjustments reshape fuel economics against natural gas baselines.
EPA New Source Performance Standards and the EU F-Gas Regulation are forcing combustion technology refreshes, with BIS pressure equipment rules in India adding a third compliance layer for exporters. OSHA process safety management requirements tighten operator training and inspection cadences, extending replacement intervals but raising specification floors. Stakeholders must monitor how carbon pricing mechanisms and hydrogen blending mandates recalibrate burner engineering roadmaps before committing to long-dated fleet investments.
Market Dynamics
EPA New Source Performance Standards and the EU F-Gas Regulation are forcing simultaneous burner retrofits across legacy installed bases, compressing replacement cycles while elevating specification floors for new procurement.
Growth Catalysts
- Food processing expansion:Pasteurization and sterilization loads in dairy and meat processing facilities are pulling in modular steam units for batch continuity.
- EPA emissions enforcement:Low-NOx retrofit mandates across US industrial corridors are accelerating combustion technology refreshes in aging refinery fleets.
- India industrial park buildout:BIS certification requirements and state-level manufacturing zones are concentrating demand for pre-packaged boiler skids.
Market Restraints
- Alloy steel input volatility:Pressure vessel-grade chromium-molybdenum plate pricing swings compress fabricator margins on fixed-price contracts.
- Fabrication concentration:Skid assembly capacity clusters in Gujarat and Shandong, exposing delivery timelines to regional logistics bottlenecks.
- Heat pump substitution:Sub-500 kW thermal applications in European commercial buildings are migrating to electric vapor compression systems.
Strategic Opportunities
- Hydrogen blending infrastructure:Pilot programs in Netherlands and Germany are creating early-mover specification advantages for dual-fuel burner architectures.
- Pharmaceutical micro-facilities:Compact once-through designs are penetrating single-use bioprocessing plants where clean steam purity requirements exclude central plant distribution.
- EU Green Deal incentives:Carbon border adjustment mechanisms are reshaping fuel economics for exporters serving European food processing corridors.
Industry Challenges
- Combustion engineering talent scarcity:Ultra-low NOx tuning expertise resides with retiring specialists, extending commissioning timelines for complex retrofits.
- ASME Section I certification backlog:Third-party inspector capacity constraints stretch pressure vessel approval cycles, delaying project cash conversion.
- Legacy DCS integration friction:Modern burner management systems require protocol translation layers to interface with 1990s-era distributed control platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Package Boilers Market |
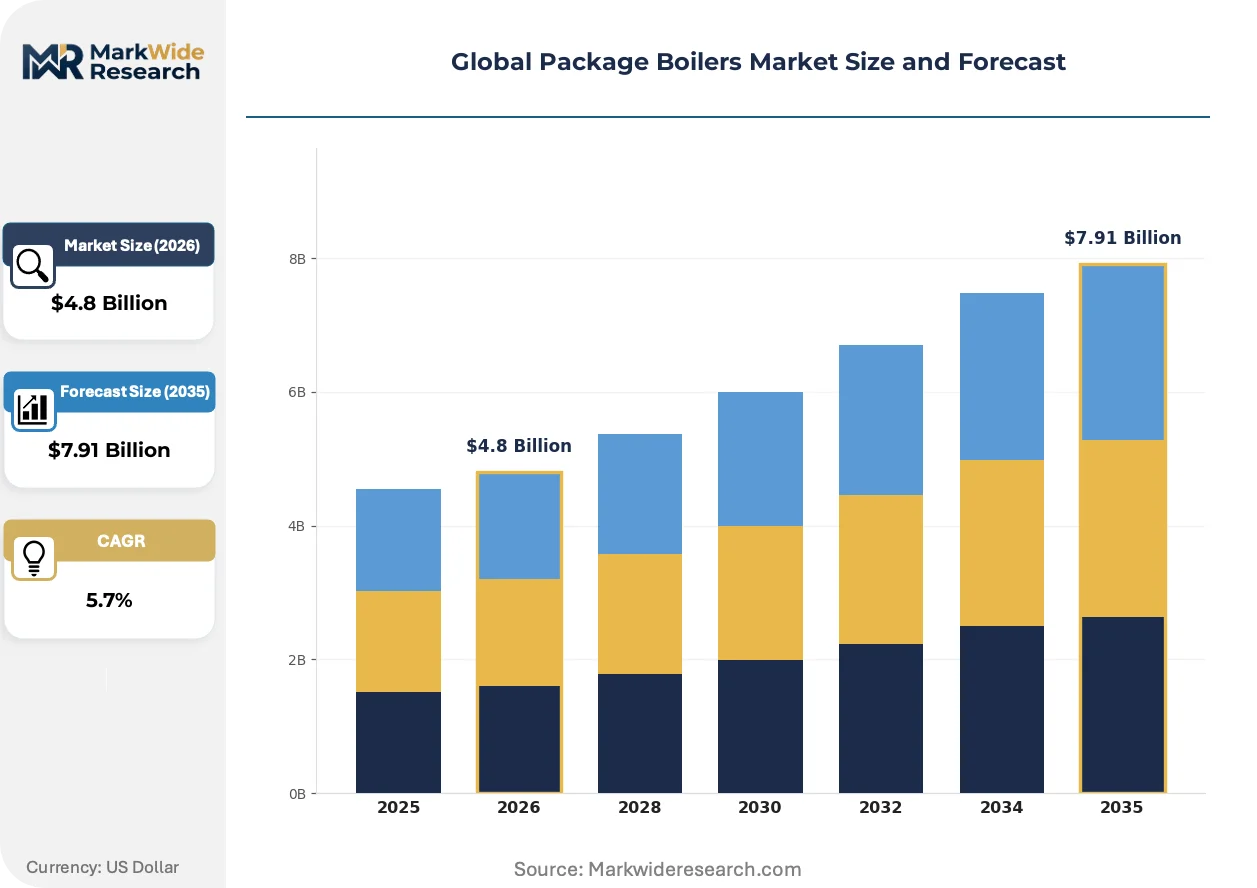
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire-tube, Water-tube, Electric, Combined Heat and Power End User: Manufacturing, Oil & Gas, Power Generation, Food Processing Fuel Type: Natural Gas, Diesel, Biomass, Coal Installation Type: On-site, Pre-packaged, Modular, Custom |
| Companies Covered | Babcock & Wilcox Enterprises, Inc., Cleaver-Brooks, Inc., IHI Corporation, Parker Boiler Company, Miura, Forbes Marshall Private Limited, Hurst Boiler & Welding Co., Inc., Johnston Boiler Company, Indeck Power Equipment Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Package Boilers Market Strategic Shifts
Digital combustion optimization and modular skidding architectures are redrawing competitive boundaries between field-erected and factory-built alternatives.
Condensing economizer technology is fragmenting the traditional efficiency hierarchy between fire-tube and water-tube designs. Pharmaceutical facilities in Switzerland and Germany are specifying these heat recovery modules to recover latent energy from low-temperature flue streams. The technology is fragmenting procurement patterns by allowing smaller footprint units to achieve thermal efficiencies previously requiring larger pressure vessels.
The EU F-Gas Regulation is accelerating refrigerant-based heat pump displacement of small steam loads in food processing corridors. Industrial bakeries and dairy plants in Denmark and Belgium are reassessing gas-fired baselines against electric alternatives. Water-tube configurations above 150 psi face the steepest competitive pressure in these applications.
Specification authority is migrating from plant engineers to corporate sustainability officers with carbon accounting mandates. Energy-as-a-service contracts are displacing traditional capex procurement in German chemical parks and Dutch greenhouse clusters. The shift is most visible in horticulture districts where heat and CO2 supply are bundled under performance guarantees.
Global Package Boilers Market Segmentation
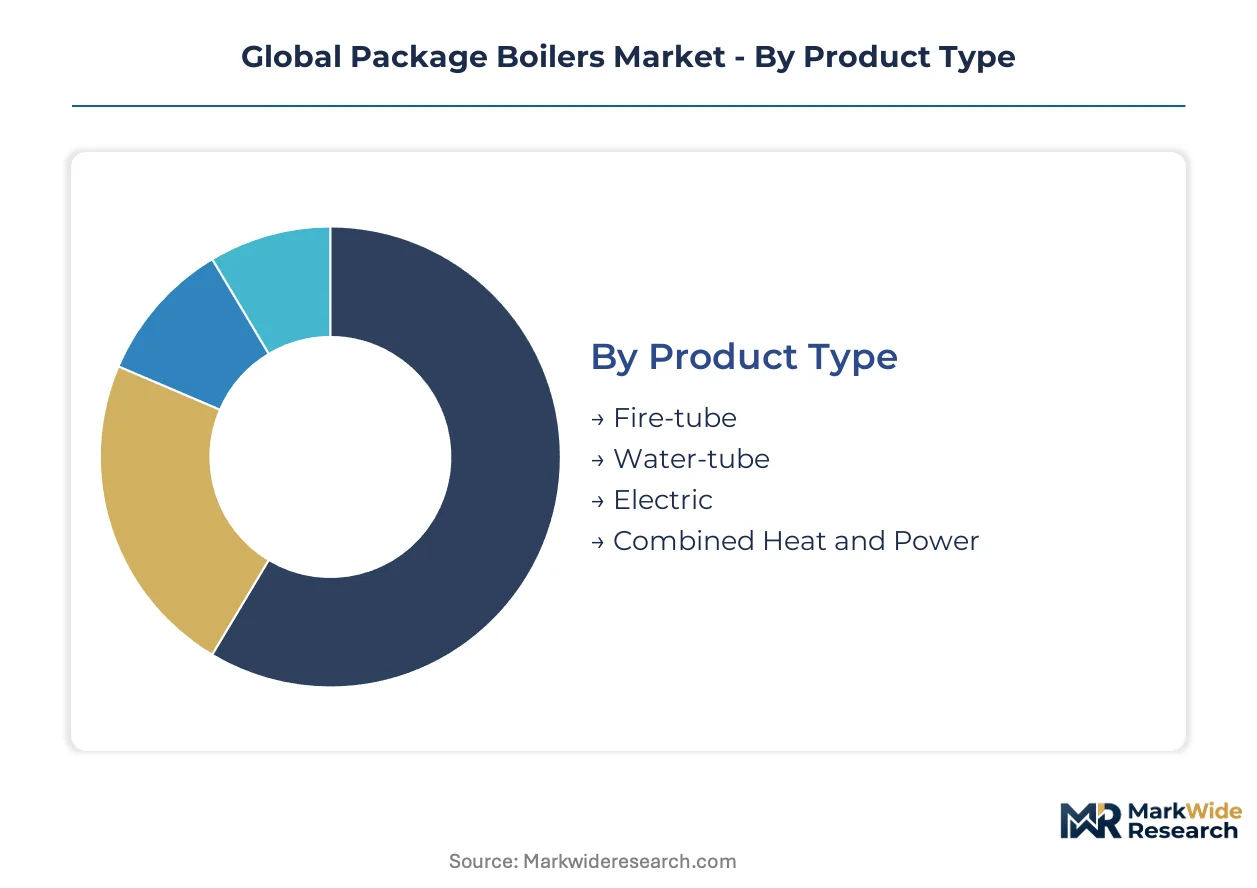
Package boiler procurement patterns diverge sharply across product architectures and fuel pathways, with specification authority migrating toward sustainability metrics and modular deployment economics. Understanding segment boundaries reveals where technology substitution pressures concentrate and where incumbent designs retain defensible positions.
Product Type:
Fire-tube and water-tube configurations anchor domestic replacement cycles across North American refineries and chemical corridors, while electric and CHP variants ride export demand from European decarbonization mandates and Asian industrial park buildouts.
- Fire-tube:Cylindrical pressure vessels route combustion gases through submerged tubes, delivering saturated steam at pressures below 250 psi. Demand clusters in US Gulf Coast refineries where EPA New Source Performance Standards force low-NOx retrofits on aging installed bases. Replacement cycles compress as emissions enforcement tightens.
- Water-tube:Once-through designs circulate feedwater through multiple small-diameter tubes exposed to radiant heat, enabling rapid steam ramp rates critical for batch pharmaceutical manufacturing. Miura and IHI configurations dominate footprint-constrained installations in Japan and South Korea where land scarcity elevates compactness premiums.
- Electric:Resistance-element or electrode steam generators eliminate combustion emissions entirely, gaining traction in Swiss and German food processing corridors under EU carbon border adjustment mechanisms.
- Combined Heat and Power:Integrated turbine-exhaust recovery systems capture thermal energy from power generation, penetrating Dutch greenhouse clusters where heat and CO2 supply bundling creates operational synergies.
Fire-tube commands the established base. The steepest expansion runs through electric configurations.
End User:
Cost-tier stratification separates capital-intensive process industries from margin-sensitive food processors, with power generation occupying a distinct procurement logic around dispatch flexibility and grid interconnection standards.
- Manufacturing:Chemical plants and automotive stamping facilities specify high-pressure water-tube units for process steam reliability. German chemical parks in Ludwigshafen and Leverkusen are piloting hydrogen-ready burner retrofits under EU Green Deal incentives.
- Oil & Gas:Upstream production platforms and downstream refineries require explosion-rated enclosures and marine-certified skids. US Gulf Coast operators face compressed replacement timelines from EPA emissions enforcement.
- Power Generation:Cogeneration and auxiliary boiler applications favor large-capacity water-tube designs with rapid load-following capability.
- Food Processing:Dairy pasteurization and meat sterilization loads pull in modular fire-tube and electric units. Indian dairy cooperatives in Gujarat and Punjab are expanding boiler fleets under FSSAI hygiene mandate expansions.
Manufacturing absorbs the highest absolute unit volumes. Food processing is climbing the fastest as cold-chain infrastructure expands across South Asia.
Fuel Type:
Supply concentration in pipeline infrastructure and biomass logistics networks shapes regional fuel preferences, with diesel retaining niche resilience in off-grid installations.
- Natural Gas:Cleanest combustion profile among fossil fuels dominates OECD markets with established pipeline distribution. Netherlands and Germany are mandating hydrogen blending compatibility for new burner specifications.
- Diesel:Distillate fuel oil powers remote mining camps and construction sites lacking grid gas access. Arctic installations in Canada and Russia specify dual-fuel capability for supply security.
- Biomass:Agricultural residue and wood pellet combustion penetrates Nordic district heating networks and Brazilian sugarcane processing complexes.
- Coal:Bituminous and sub-bituminous firing persists in Indian textile clusters and Indonesian palm oil refineries where domestic coal subsidies distort fuel economics.
Natural gas commands the established base. The steepest expansion runs through biomass as carbon accounting frameworks mature.
Installation Type:
Customer-type stratification separates owner-operated industrial facilities from third-party energy service providers, with pre-packaged and modular formats capturing outsourced thermal energy contracts.
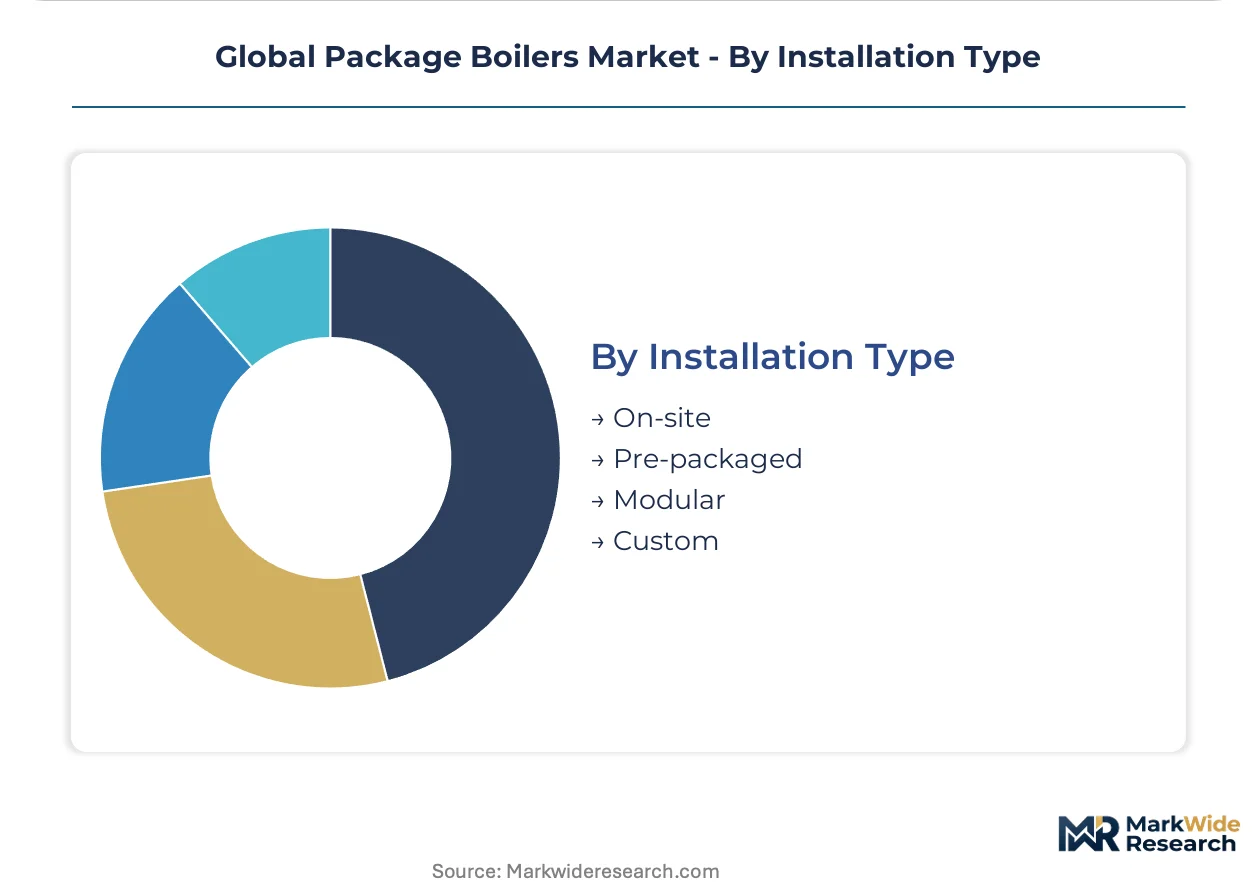
- On-site:Field-erected pressure vessels and combustion trains require extended commissioning timelines and specialized welding labor. Legacy US refineries retain this pathway for non-standard capacity requirements.
- Pre-packaged:Factory-assembled skids with integrated controls and burners enable rapid deployment. Indian industrial parks in Maharashtra and Tamil Nadu specify these units to meet BIS certification deadlines.
- Modular:Containerized or trailer-mounted configurations support temporary steam supply and mobile disaster response. German chemical parks are deploying these for seasonal peak shaving.
- Custom:Engineered-to-order systems accommodate extreme pressure ratings or exotic metallurgy for supercritical process applications.
On-site commands the established base. The steepest expansion runs through pre-packaged formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fabrication capacity clusters in Gujarat and Shandong expose delivery timelines to regional logistics bottlenecks, while procurement patterns diverge sharply across regulatory jurisdictions.
United States
EPA New Source Performance Standards force low-NOx retrofits across Gulf Coast refineries and chemical corridors. OSHA process safety management requirements tighten inspection cadences and extend replacement intervals. Houston and Beaumont industrial clusters absorb the highest concentration of fire-tube replacement demand.
Germany
EU F-Gas Regulation and EU Green Deal incentives accelerate hydrogen-ready burner specifications in Ludwigshafen and Leverkusen chemical parks. Carbon border adjustment mechanisms reshape fuel economics for exporters serving European food processing corridors. Energy-as-a-service contracts displace traditional capex procurement in Dutch-German border greenhouse clusters.
India
BIS certification requirements and state-level manufacturing zones concentrate demand for pre-packaged boiler skids in Maharashtra and Tamil Nadu. FSSAI hygiene mandate expansions drive dairy cooperative fleet buildouts in Gujarat and Punjab. Industrial park authorities specify factory-assembled units to meet compressed commissioning deadlines.
Japan
Land scarcity elevates compactness premiums for once-through water-tube designs in pharmaceutical and beverage plants around Osaka and Nagoya. METI efficiency standards push ultra-low NOx combustion architectures for utility contractors. East Asian urban density constraints favor footprint-minimized installations.
Netherlands
Hydrogen blending pilot programs in Rotterdam and Eindhoven create early-mover specification advantages for dual-fuel burner architectures. Carbon pricing mechanisms recalibrate burner engineering roadmaps for horticulture districts bundling heat and CO2 supply under performance guarantees. EU decarbonization targets accelerate electric package boiler penetration in food processing corridors.
Global Package Boilers Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the specification chain. The vendor base stratifies into three tiers: integrated systems houses controlling burner and control production, specialized water-tube fabricators serving footprint-constrained process industries, and regional fabricators competing on delivery speed for standard fire-tube replacements. Dominant competitive moves include backward integration into pressure vessel metallurgy and strategic partnerships with hydrogen infrastructure developers.
Among North American integrated systems houses, Cleaver-Brooks, Inc. exemplifies the captive-supply archetype through in-house production of burner and control systems. IHI Corporation anchors the East Asian technology tier, representing R&D-intensive positioning in ultra-low NOx combustion architectures. Miura occupies the compact-system specialist position, with its once-through designs serving pharmaceutical and beverage installations where footprint constraints dominate procurement criteria.
| Leading Market Players |
|---|
| Babcock & Wilcox Enterprises, Inc. |
| Cleaver-Brooks, Inc. |
| IHI Corporation |
| Parker Boiler Company |
| Miura |
| Forbes Marshall Private Limited |
| Hurst Boiler & Welding Co., Inc. |
| Johnston Boiler Company |
| Indeck Power Equipment Company |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Indian industrial park authorities and Gujarat-based fabricators lock in both alloy steel supply access and price visibility across the 18-24 month project cycle. These arrangements insulate buyers from chromium-molybdenum plate volatility while committing fabricators to fixed delivery windows under BIS certification timelines.
Pricing Analysis
EPA New Source Performance Standards dictate the pricing tier structure across US Gulf Coast refinery retrofits, separating ASME Section I certified units from uncertified alternatives. Three-tier pricing structure across premium certified, standard compliant, and economy replacement levels tracks directly to NOx emission thresholds and inspection documentation depth. Cost compression in the economy tier is intensifying because alloy steel input swings compress fabricator margins on fixed-price contracts. Food processing cooperatives in Gujarat exhibit the highest price sensitivity, while German chemical parks under EU Green Deal mandates show the least.
Supply Chain Analysis
Inventory buffers for pressure vessel-grade plate stretch 8-12 weeks at major skid assembly locations, exposing delivery timelines to regional logistics friction. Manufacturing gravity centers on India, China, and South Korea, with chromium-molybdenum steel plate, burner management systems, and control electronics as critical inputs. Single-source vulnerability concentrates in specialized ultra-low NOx combustion component sourcing from Japanese precision foundries. Distribution runs through OEM-direct channels for large process industry accounts and regional distributor networks for standard fire-tube replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification authority fragmentation across sustainability officers, plant engineers, and procurement teams creates multiple entry points for differentiated positioning. Corporate carbon accounting mandates are splitting demand into parallel tracks with distinct vendor selection criteria.
For Market Incumbents: Secure captive supply positions in hydrogen-ready burner architectures before Netherlands and Germany mandate blending compatibility. Deepen backward integration into pressure vessel metallurgy to defend margin position against alloy steel volatility. Lock in long-term service contracts with US Gulf Coast refineries facing compressed EPA-driven replacement cycles. For New Entrants and Emerging Players: Differentiate on modular containerized formats for German chemical park peak-shaving applications where energy-as-a-service contracts displace traditional capex procurement. Target pharmaceutical micro-facilities in Switzerland with compact once-through designs for single-use bioprocessing plants. Lead with clean steam purity guarantees rather than thermal efficiency metrics. For Investors and Strategic Acquirers: Burner technology specialists with dual-fuel hydrogen compatibility represent the most defensible acquisition archetype as EU decarbonization mandates recalibrate engineering roadmaps. Long-term viability hinges on exposure to regulatory jurisdictions with enforceable carbon pricing mechanisms. Watch for ASME Section I certification backlog resolution as the inflection signal for project cash conversion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Burner Development | Netherlands and Germany pilot programs create first-mover specification advantages for dual-fuel architectures. |
| Backward Integration into Pressure Vessel Metallurgy | Cleaver-Brooks and integrated systems houses defend margin capture against chromium-molybdenum plate volatility. |
| Modular Skid Capacity Expansion | Indian industrial parks in Maharashtra specify factory-assembled units to meet compressed BIS certification deadlines. |
| Energy-as-a-Service Contract Structuring | Dutch-German border greenhouse clusters bundle heat and CO2 supply under performance guarantees. |
| Ultra-Low NOx Combustion R&D Intensity | IHI Corporation anchors East Asian positioning through METI efficiency standards compliance. |
Study Parameters
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this study. Primary fieldwork across US Gulf Coast refineries, German chemical parks, and Indian dairy cooperatives combined with secondary validation from EPA enforcement databases, BIS certification registries, and EU F-Gas Regulation implementation reports. Customs data on alloy steel plate imports and SEC filings from publicly traded fabricators provided demand-side triangulation against bottom-up unit installation tracking.
Sensitivity analysis around hydrogen blending adoption rates and carbon pricing mechanism expansion shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, fuel pathway, end-use industry, and installation format. CAGRs derived from unit shipment trajectories weighted by average selling price evolution across certified and uncertified tiers. Forecast inputs incorporated EPA enforcement intensity indices and EU Green Deal incentive allocation patterns.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement or accelerated hydrogen infrastructure buildout would require recalibration. Forecasts reflect documented assumptions regarding alloy steel price stability and ASME inspector capacity expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
GCC Electric Water Heater Market
Boilers
US Boiler Market
Boilers
Fuel Operated Heaters Market
Boilers
Gas Fired Boilers Market
Boilers
Boiler Combustion Chamber Market
Boilers
Industrial Boiler MRO Market
Boilers
Circulating Fluidized Bed Boilers Market
Boilers
Hydrogen Boilers Market
Boilers
North America Commercial Boiler Market
Boilers
Advanced Utility Boilers Market
Boilers
Electric Boiler Market
Boilers
Asia-Pacific Power Plant Boiler Market
Boilers
Industrial and Residential Heating Market
Boilers
Space Heating Boilers Market
Boilers
Oil-Fired Boiler Market
Boilers
Global Boiler Market