
 Gas to Liquid (GTL) Market | 2026-2036
Gas to Liquid (GTL) Market Size, Share, and Industry Trends Forecast 2026-2036
Gas to Liquid (GTL) Market Intelligence
The divergence between premium synthetic products and commodity fuel substitutes is realigning competitive strategy across the GTL sector. QatarEnergy leverages its integrated Pearl facility to dominate ultra-large-scale production. Sasol Limited anchors its position through Fischer-Tropsch specialization and South African operational depth. Royal Dutch Shell competes via technology licensing and selective equity positions in downstream synthesis assets.
Gas to Liquid conversion transforms natural gas into liquid hydrocarbons through Fischer-Tropsch synthesis or methanol-to-gasoline pathways, typically yielding ultra-low sulfur diesel, synthetic lubricant base oils, and paraffinic waxes with cetane numbers exceeding 70. Diesel output serves marine and power generation applications where sulfur restrictions tighten product specifications. Wax segments occupy high-margin specialty chemicals for cosmetics and coatings, while base oil production is concentrating among energy producers seeking captive synthetic lubricant supply chains. Hydrocracking technology leads commercial deployment, though catalytic conversion advances promise milder operating conditions.
FAA certification requirements govern synthetic aviation fuel pathways in the United States, while IMO marine sulfur regulations reshape demand toward GTL-derived distillates for shipping operators. EMA fuel quality directives and REACH chemical registration in Europe constrain product composition and market access for non-compliant suppliers. Stakeholders must monitor carbon intensity accounting methodologies, as these will determine which synthesis routes qualify for low-carbon fuel standards and offtake contracts.
Market Dynamics
The GTL sector is being restructured by marine sulfur regulations that redirect bunker fuel procurement toward ultra-low sulfur distillates, compressing demand for conventional residual fuels while elevating synthetic diesel premiums.
Growth Catalysts
- IMO 2020 Sulfur Cap:Shipping operators across Rotterdam, Singapore, and Houston ports now source GTL marine gasoil to comply with 0.5% sulfur limits, creating sustained offtake for Pearl-scale facilities.
- Fischer-Tropsch Catalyst Advances:Cobalt-based slurry-phase systems achieve 90% carbon conversion efficiency, reducing per-barrel opex for operators running at 140,000 bpd nameplate capacity.
- Aviation Decarbonization:Synthetic paraffinic kerosene pathways secured ASTM D7566 certification, opening jet fuel offtake from carriers seeking to diversify beyond petroleum-derived Jet A-1.
Market Restraints
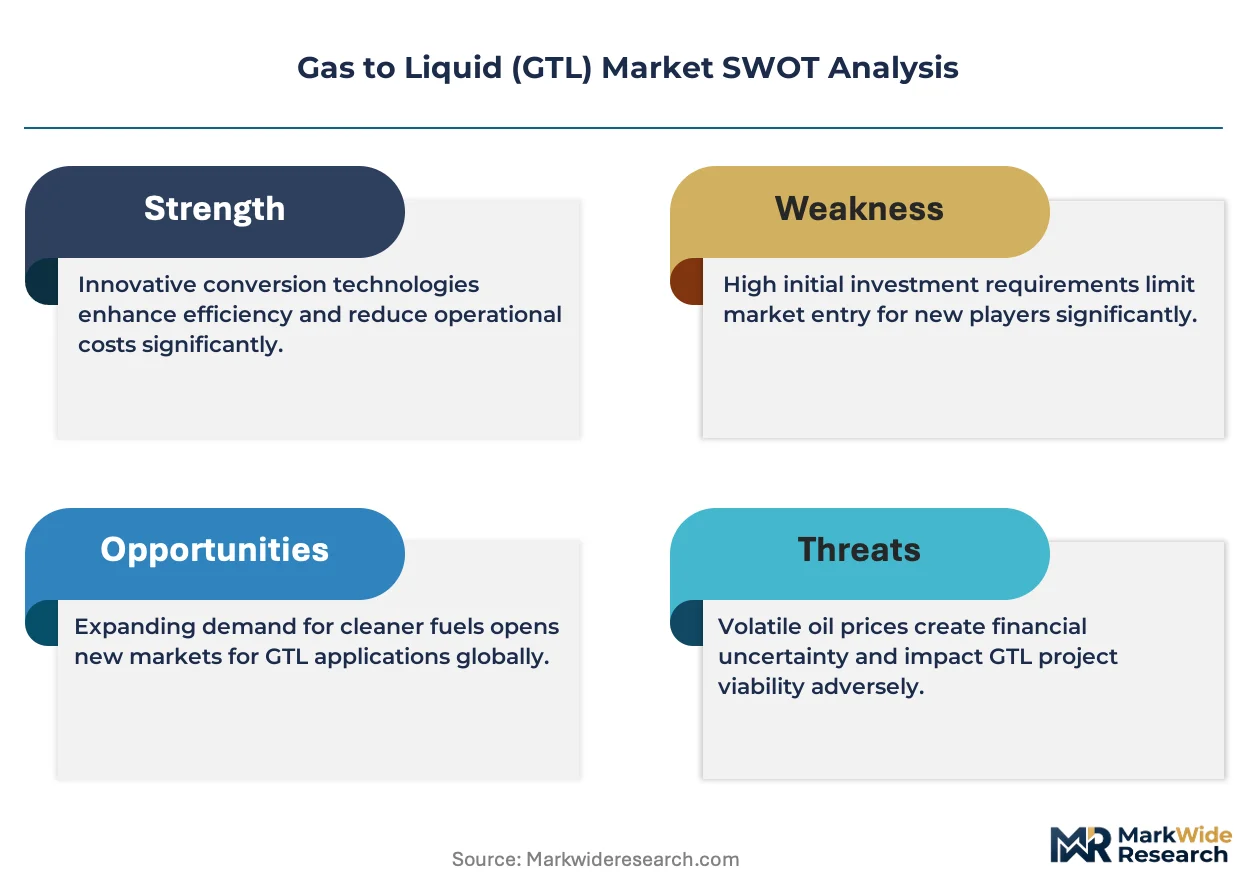
- Natural Gas Feedstock Volatility:Henry Hub price swings above $3.50/MMBtu erode GTL project economics, particularly for ventures lacking long-term upstream integration.
- Facility Concentration Risk:Operational GTL capacity clusters in Qatar and South Africa, exposing supply continuity to single-point geopolitical or technical disruptions.
- Electrification Substitution:Battery-electric propulsion advances in short-haul marine and heavy trucking segments threaten diesel demand growth trajectories.
Strategic Opportunities
- India Industrial Corridor Expansion:Gujarat and Maharashtra state governments actively solicit GTL investments under petroleum product import substitution mandates.
- Carbon Capture Integration:Fischer-Tropsch process off-gas streams enable cost-effective CO2 sequestration, qualifying output for EU low-carbon fuel standards.
- Modular Small-Scale Systems:Containerized GTL units targeting stranded gas fields in Nigeria and Indonesia unlock production below 10,000 bpd thresholds previously uneconomic.
Industry Challenges
- Fischer-Tropsch Specialist Scarcity:Refinery operators face acute shortages of process engineers trained in cobalt catalyst management and wax hydrocracking optimization.
- ASTM Certification Timelines:Synthetic aviation fuel pathways require 24-36 month qualification cycles, delaying revenue recognition for new production entrants.
- Complex Licensing Architecture:Patent thickets around slurry-bed reactor designs and cobalt catalyst formulations create negotiation friction between technology holders and project developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas to Liquid (GTL) Market |
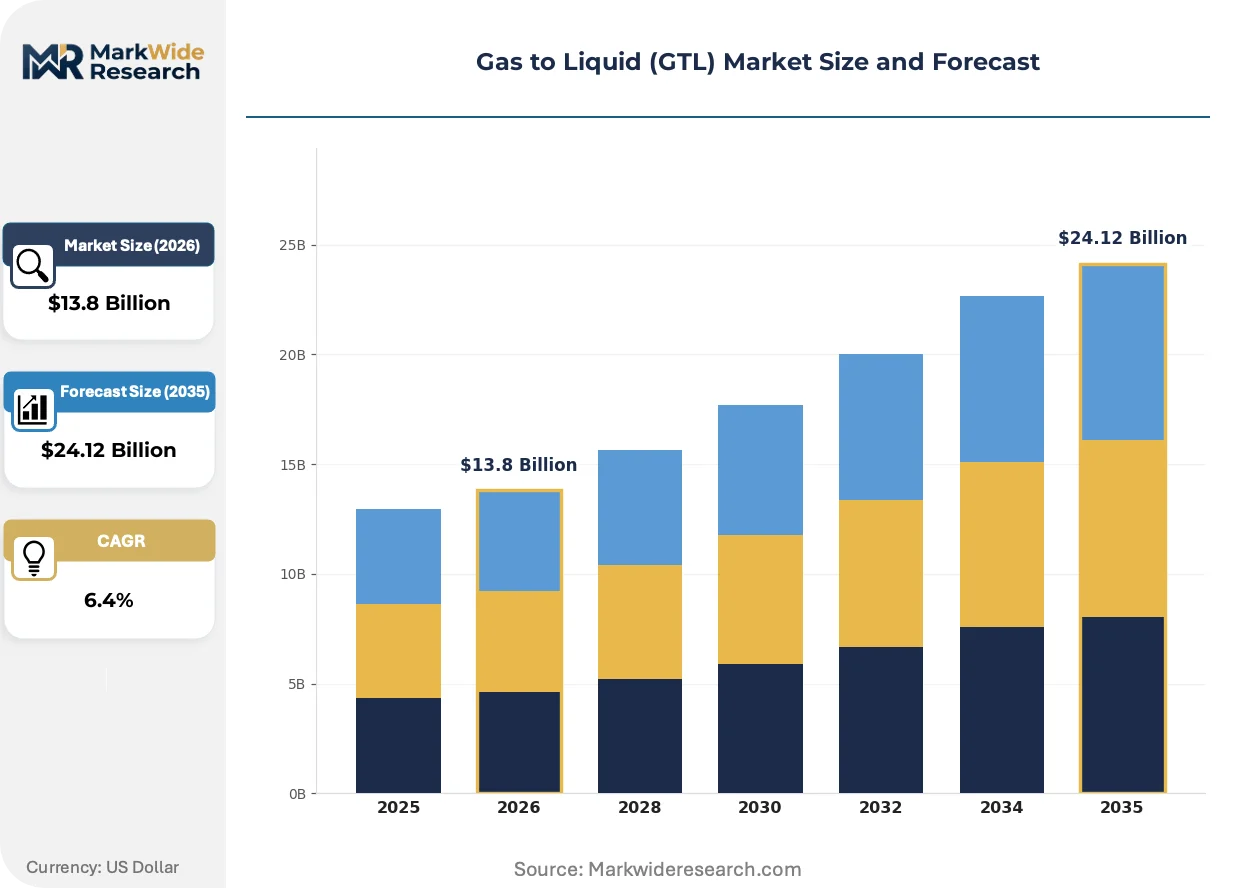
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel, Naphtha, Kerosene, LPG, Base Oil, Wax Technology: Fisher-Tropsch Synthesis, Methanol-to-Gasoline, Catalytic Conversion, Hydrocracking Application: Power Generation, Marine Fuel, Synthetic Lubricants, Aviation Fuel, Industrial Heating, Chemical Feedstock End User: Energy Producers, Chemical Manufacturers, Shipping Operators, Aviation Companies, Power Utilities |
| Companies Covered | QatarEnergy, Velocys PLC, Royal Dutch Shell, ConocoPhillips Company, Petro SA, Chevron Corporation, ExxonMobil Corporation, TotalEnergies SE, Sasol Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas to Liquid (GTL) Market Strategic Shifts & Innovations
Process intensification and regulatory chemistry are rewriting GTL competitive economics. Three developments are compressing legacy technology deployment windows while opening new application domains.
Cobalt-based Fischer-Tropsch synthesis is overtaking iron-catalyzed systems in commercial deployments. Sasol and Shell now specify cobalt for Pearl-scale facilities targeting high wax and lube base oil yields. The shift enables longer catalyst cycles above 8,000 hours, reducing turnaround frequency and maintenance labor intensity.
REACH chemical registration requirements in Europe are tightening paraffin and wax import specifications. ECHA substance evaluation protocols now demand full carbon chain characterization for synthetic lubricant base stocks. German and Dutch blenders are consolidating supplier lists to pre-registered GTL producers, excluding smaller Fischer-Tropsch operators lacking compliance documentation.
Marine fuel buyers are consolidating procurement around integrated suppliers offering bundled bunkering and emissions verification. Singapore port authorities now require blockchain-tracked sulfur content certificates. Greek and Danish tanker operators prefer term contracts with GTL producers providing certified mass-balance documentation for EU emissions trading compliance.
Gas to Liquid (GTL) Market Segmentation
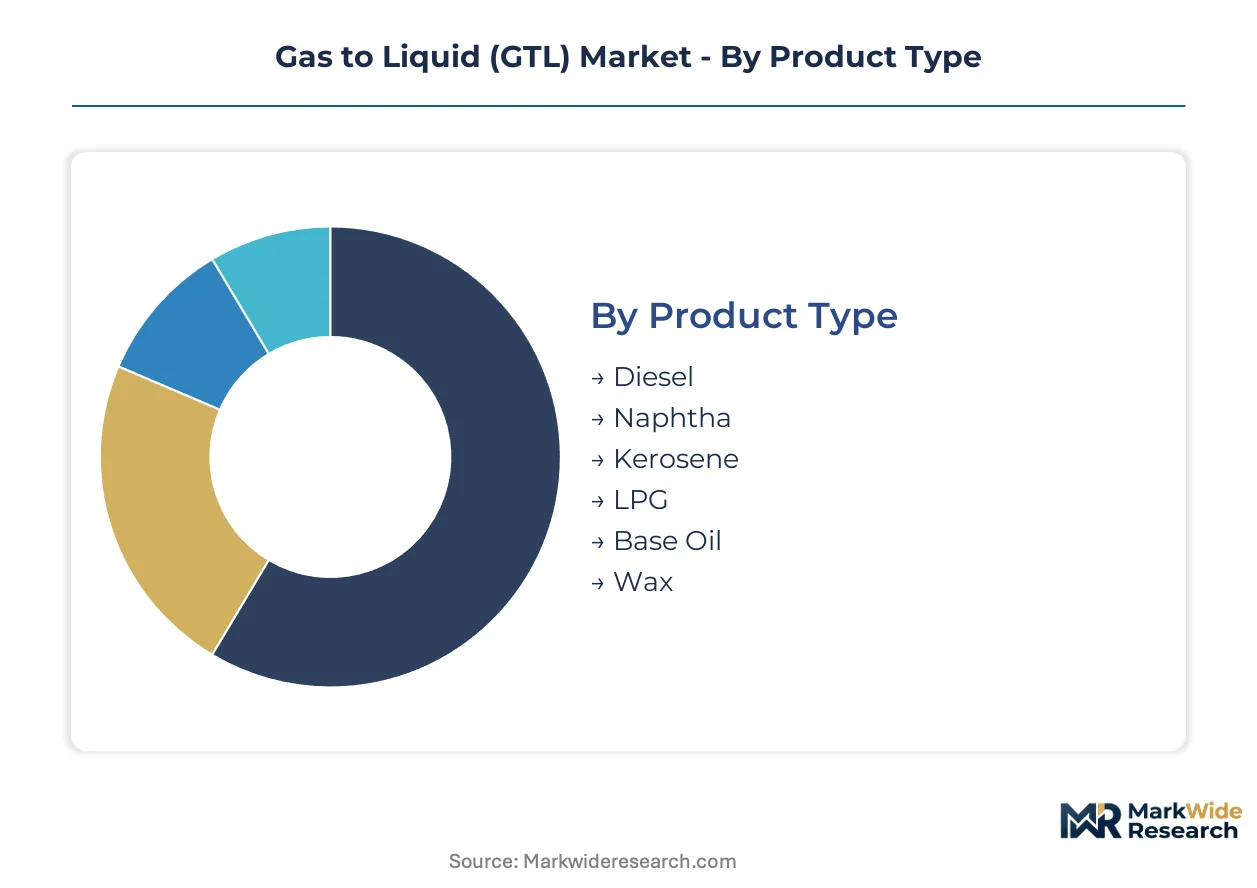
GTL product differentiation determines capital allocation, facility configuration, and offtake contract structures across the value chain. Technology choices lock in feedstock flexibility and product slate for decades. Application segmentation reveals which regulatory regimes and customer procurement patterns govern revenue stability.
Product Type:
Capital intensity peaks with wax and base oil production, where dedicated hydrocracking trains and fractionation towers multiply upfront investment versus fuel-only configurations.
- Diesel:Ultra-low sulfur distillate with cetane numbers exceeding 70 serves marine bunkering and power generation. Demand concentrates at Rotterdam and Singapore port authorities enforcing IMO sulfur caps, though margins compress when natural gas feedstock costs spike above economic thresholds.
- Base Oil:Synthetic lubricant feedstock requires advanced hydroisomerization to achieve Group III+ specifications. Aviation companies in the United States and Europe now mandate certified synthetic base stocks for turbine engine lubricants, creating premium offtake channels distinct from commodity fuel markets.
- Naphtha:Light paraffinic stream feeds steam crackers and reforming units.
- Kerosene:Synthetic paraffinic kerosene pathway requires ASTM certification for aviation blending.
- LPG:C3-C4 fraction captured as byproduct from Fischer-Tropsch condensate recovery.
- Wax:High-melting-point paraffins serve cosmetics and coatings applications with specialized fractionation requirements.
Most installed capacity flows through diesel. Expansion is steepest in base oil.
Technology:
Process selection dictates feedstock tolerance, product flexibility, and operating cost structure across facility lifecycles.
- Fischer-Tropsch Synthesis:Cobalt-based slurry-phase systems achieve 90% carbon conversion efficiency at Pearl-scale operations. Qatar and South Africa host the majority of commercial capacity, with catalyst cycles now extending beyond 8,000 hours between replacements.
- Hydrocracking:Heavy wax and residue upgrading to distillate range products requires high-pressure hydrogen addition. This technology anchors product slate flexibility at integrated GTL complexes, enabling swing production between diesel and base oil yields based on offtake contract premiums.
- Methanol-to-Gasoline:Fixed-bed catalytic dehydration route targets motor gasoline rather than diesel-focused output.
- Catalytic Conversion:Milder operating conditions under development promise reduced opex for stranded gas applications.
Capacity concentrates in Fischer-Tropsch synthesis. Methanol-to-gasoline is gaining share fastest.
Application:
End-use diversification spreads revenue risk across regulatory jurisdictions with divergent compliance timelines and carbon accounting methodologies.
- Marine Fuel:IMO 2020 sulfur regulations redirect bunker procurement toward GTL marine gasoil at major transshipment hubs. Greek and Danish tanker operators now require blockchain-tracked sulfur certificates and mass-balance documentation for EU emissions trading compliance.
- Aviation Fuel:Synthetic paraffinic kerosene secured ASTM D7566 certification, enabling blending with conventional Jet A-1. FAA certification pathways in the United States and EASA alignment in Europe govern market access, with qualification cycles extending 24-36 months for new production entrants.
- Power Generation:Diesel-fired peaking plants and remote generation assets source ultra-low sulfur distillate.
- Synthetic Lubricants:Automotive and industrial blending operations demand Group III+ base stocks.
- Industrial Heating:Clean-burning characteristics suit food processing and precision manufacturing heat requirements.
- Chemical Feedstock:Paraffinic streams supply surfactant and solvent manufacturing chains.
Volume concentrates in marine fuel. Aviation fuel is climbing the fastest.
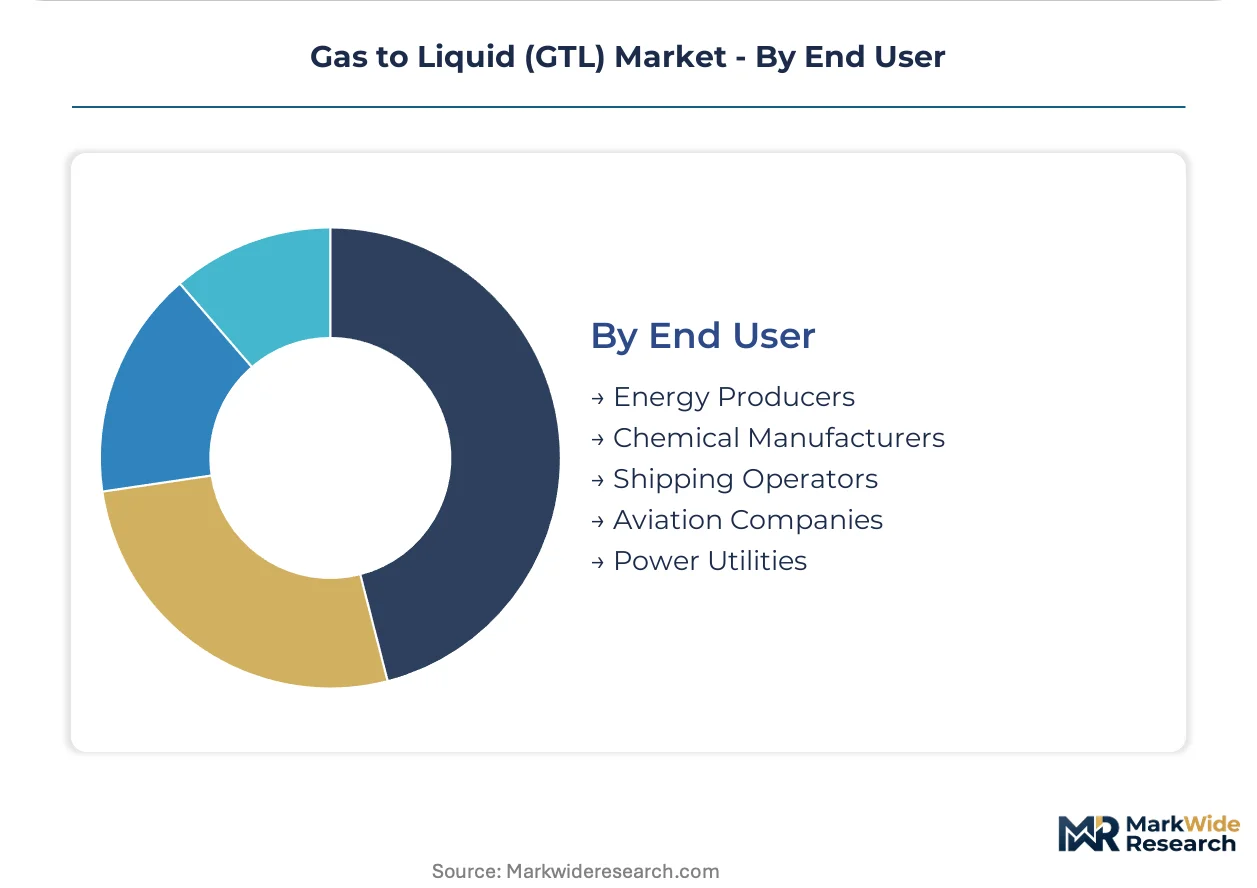
End User:
Procurement scale and contract duration vary sharply across customer categories, influencing project financing structures and feedstock supply agreements.
- Shipping Operators:Consolidated bunker procurement at Rotterdam, Singapore, and Houston ports now favors term contracts with integrated suppliers offering bundled fuel and emissions verification. Singapore port authorities mandate blockchain-tracked sulfur content documentation.
- Aviation Companies:Carriers seeking to diversify beyond petroleum-derived Jet A-1 source certified synthetic paraffinic kerosene through offtake agreements tied to corporate sustainability targets.
- Energy Producers:Integrated oil and gas companies operate captive GTL capacity for product slate optimization.
- Chemical Manufacturers:Specialty wax and base oil consumers require REACH-registered supply chains for European market access.
- Power Utilities:Remote and island grid operators procure diesel for generation reliability.
Contract value concentrates with shipping operators. Procurement growth is steepest among aviation companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar and South Africa concentrate operational GTL capacity through Pearl-scale facilities and Fischer-Tropsch specialization, while the United States and India pursue divergent pathways toward synthetic fuel adoption.
Qatar
QatarEnergy's integrated Pearl facility anchors ultra-large-scale production serving marine gasoil demand at Rotterdam and Singapore ports. The Qatar Free Zones Authority incentivizes downstream petrochemical investments through tax holidays and customs exemptions. Ras Laffan Industrial City hosts concentrated gas conversion infrastructure supplying IMO-compliant distillates to Greek and Danish tanker operators.
South Africa
Sasol Limited's Fischer-Tropsch specialization supports synthetic lubricant base oil production for aviation companies seeking ASTM-certified alternatives. South Africa's Department of Mineral Resources and Energy maintains strategic fuel stockpiles mandating synthetic blending quotas. The Secunda complex represents the densest operational concentration of coal-to-liquids and gas-to-liquids synthesis capacity outside the Middle East.
United States
FAA certification pathways govern synthetic paraffinic kerosene market access for aviation fuel producers targeting corporate sustainability contracts. The Inflation Reduction Act's clean fuel production credits incentivize carbon capture integration at Fischer-Tropsch facilities. The Gulf Coast petrochemical corridor attracts technology licensing investments from integrated oil majors seeking downstream synthesis equity positions.
India
Gujarat and Maharashtra state governments solicit GTL investments under petroleum product import substitution mandates targeting marine and power generation diesel. The Petroleum and Natural Gas Regulatory Board streamlines city gas distribution licenses for stranded gas monetization. The Dahej Special Economic Zone concentrates proposed gas conversion capacity serving domestic bunker fuel demand at Mumbai and Kandla ports.
Nigeria
Modular small-scale GTL systems target stranded gas fields in the Niger Delta previously uneconomic for pipeline export. The Nigerian National Petroleum Corporation's gas flare commercialization program mandates utilization of associated gas for synthetic fuel production. Lagos and Port Harcourt anchor procurement demand from industrial diesel consumers seeking ultra-low sulfur alternatives to imported distillates.
Gas to Liquid (GTL) Market Key Industry Players
Top-tier vendors anchor integrated production at Pearl-scale facilities, while technology licensing specialists and modular system developers occupy differentiated competitive positions. The vendor base stratifies across three archetypes: state-affiliated energy majors with captive gas reserves, international oil companies with synthesis technology portfolios, and venture-stage innovators targeting stranded gas applications. Capacity expansion and carbon capture integration represent the dominant competitive moves reshaping facility economics.
Within the state-affiliated tier, QatarEnergy exemplifies vertical control from upstream gas through downstream synthetic products. Royal Dutch Shell and Sasol Limited occupy positions bridging technology licensing and selective equity participation in commercial synthesis assets. These three entities represent contrasting pathways—captive resource monetization, intellectual property commercialization, and Fischer-Tropsch operational depth—around which competitive positioning organizes.
| Leading Market Players |
|---|
| QatarEnergy |
| Velocys PLC |
| Royal Dutch Shell |
| ConocoPhillips Company |
| Petro SA |
| Chevron Corporation |
| ExxonMobil Corporation |
| TotalEnergies SE |
| Sasol Limited |
| Others |
Cost & Logistics Intelligence
Natural gas feedstock costs cascade through GTL economics from upstream Henry Hub volatility to downstream diesel and base oil pricing tiers, compressing margins at Pearl-scale facilities when input prices spike above operational thresholds and redirecting procurement toward long-term offtake contracts that lock in buyer-supplier spreads.
Pricing Analysis
Capacity additions in Qatar are reshaping price floors for ultra-low sulfur diesel and synthetic base oils, establishing benchmark premiums against conventional petroleum distillates. Three-tier pricing structure across premium certified, standard marine-grade, and economy fuel-only tiers separates IMO-compliant marine gasoil from REACH-registered wax and base oil streams. Cost compression in the standard tier intensifies because Henry Hub volatility above $3.50/MMBtu erodes project economics for non-integrated operators. Shipping operators at Rotterdam and Singapore ports demonstrate highest price sensitivity through consolidated term-contract procurement, while aviation companies seeking ASTM-certified synthetic paraffinic kerosene accept premium pricing for sustainability-linked offtake agreements.
Supply Chain Analysis
Spent cobalt catalyst recovery and regeneration flows create reverse-logistics requirements at Fischer-Tropsch facilities, with catalyst cycle extensions beyond 8,000 hours reducing replacement frequency and associated transport costs. Supply concentrates in Qatar, South Africa, and Nigeria, with modular small-scale systems emerging in Indonesia for stranded gas monetization. Feedstock sourcing draws from associated gas fields, pipeline natural gas, and flare capture programs, while product distribution runs through Rotterdam, Singapore, and Houston bunkering hubs. Single-source vulnerability concentrates at Ras Laffan Industrial City and the Secunda complex, where operational disruptions would constrain global synthetic diesel and base oil availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GTL market functions as a geographic-arbitrage play between Qatar's integrated gas conversion infrastructure and India's import-substitution corridors, where domestic diesel demand and stranded gas reserves create cost and regulatory divergences worth exploiting.
For Market Incumbents: Lock in feedstock supply through long-term upstream integration or captive gas field development, particularly in Qatar and Nigeria where flare commercialization mandates secure low-cost methane access. Defend margin position by extending cobalt catalyst cycles above 8,000 hours and consolidating hydrocracking capacity for swing production between diesel and base oil yields. Electrification substitution in short-haul marine and heavy trucking segments threatens diesel demand growth trajectories, making aviation and specialty wax diversification essential for revenue stability.
For New Entrants and Emerging Players: Begin with modular small-scale GTL systems targeting stranded gas fields in Nigeria and Indonesia, where sub-10,000 bpd thresholds previously uneconomic now unlock production through containerized units. The most penetrable white-space sits in India's Gujarat and Maharashtra industrial corridors, where state governments actively solicit GTL investments under petroleum product import substitution mandates. Go-to-market positioning should emphasize carbon capture integration to qualify output for EU low-carbon fuel standards and attract sustainability-linked offtake contracts from European shipping operators.
For Investors and Strategic Acquirers: Consolidation pressure builds where Fischer-Tropsch specialist scarcity constrains operational expansion and technology licensing friction limits new project development. Long-term viability across the projection horizon favors integrated operators with captive gas reserves and downstream synthesis assets over pure technology licensors. Acquisition targets should display carbon capture readiness and REACH registration completion for European market access. The signal to watch is ASTM certification timeline compression for synthetic aviation fuel pathways, as accelerated qualification cycles would unlock premium offtake from carriers diversifying beyond petroleum-derived Jet A-1.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | Fischer-Tropsch off-gas sequestration qualifies output for EU low-carbon fuel standards and emissions trading compliance. |
| Modular Small-Scale Deployment | Containerized units unlock stranded gas monetization in Nigeria and Indonesia below previous economic thresholds. |
| ASTM Certification Acceleration | Compressed qualification timelines for synthetic paraffinic kerosene open aviation offtake from sustainability-targeted carriers. |
| REACH Registration Completion | Full carbon chain characterization secures European market access for synthetic lubricant base stocks and waxes. |
| Long-Term Marine Ofctake Contracts | Blockchain-tracked sulfur certificates bundled with bunkering services lock in Rotterdam and Singapore port demand. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Fischer-Tropsch process engineers, marine fuel procurement managers at Greek and Danish tanker operators, aviation fuel sustainability leads, and cobalt catalyst specialists with secondary validation through EIA natural gas data, IEA energy transition reports, IMO sulfur regulation filings, and ASTM certification documentation. Bottom-up facility capacity modeling and top-down demand segmentation across marine, aviation, and specialty chemical applications ensured cross-verification.
Historical reference periods anchored the forecast window to pre-IMO 2020 implementation baselines and post-pandemic demand recovery trajectories, with CAGRs derived from segment-level growth differentials across diesel, base oil, wax, and kerosene product slates. The analytical framework modeled technology deployment rates, feedstock cost scenarios, and regulatory compliance timelines as primary drivers, with carbon intensity accounting methodologies and EU low-carbon fuel standard eligibility criteria as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including abrupt geopolitical disruptions to Qatar or South African supply, breakthrough battery-electric propulsion advances in marine applications, and fundamental shifts in natural gas pricing regimes. Forecasts reflect documented assumptions about catalyst efficiency gains and certification timeline stability. Practitioners should monitor IMO sulfur enforcement consistency, ASTM qualification backlog durations, and EU carbon border adjustment implementation for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Renewable Heating Fuels Market
Fuels
Singapore Bunker Fuel Market
Fuels
Middle-East and Africa Commercial Aircraft Aviation Fuel Market
Fuels
Europe Defense Aircraft Aviation Fuel Market
Fuels
Italy Chemical Logistics Market
Fuels
Global Steam Coal Market
Fuels
Global Liquid Gas Cylinder (LGC) Market
Fuels
Liquid Propellants Market
Fuels
India LNG Market
Fuels
Germany Bunker Fuel Market
Fuels
Asia-Pacific Bunker Fuel Market
Fuels
Global Butane Gas Cartridges Market
Fuels
Brazil Bunker Fuel Market
Fuels
Canada Coal Market
Fuels
Underground Coal Gasification Market
Fuels
Global Turbine Oil Market