
 Catalytic Hydrothermolysis Jet [CHJ] Fuel Market | 2026-2036
Catalytic Hydrothermolysis Jet [CHJ] Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Catalytic Hydrothermolysis Jet [CHJ] Fuel Market Outlook
Specialized chemical engineering talent for hydrothermal liquefaction scale-up is collapsing across North American and European labor markets. Applied Research Associates, Inc. leverages its defense contracting heritage to anchor military aviation certification pathways for CHJ fuels. Neste Oyj dominates renewable feedstock logistics through its Singapore and Rotterdam refining complexes. SkyNRG competes by aggregating airline offtake demand across European flag carriers.
Catalytic Hydrothermolysis Jet Fuel denotes a synthetic paraffinic kerosene produced through aqueous-phase catalytic conversion of wet biomass or waste lipids at subcritical temperatures, yielding a C8-C16 hydrocarbon stream meeting ASTM D7566 Annex A5 specifications for aviation turbine fuel. The process operates at 250-350°C and 10-20 MPa with heterogeneous catalysts, targeting drop-in compatibility with existing jet engine infrastructure. Renewable CHJ Fuels lead product type revenue pools due to airline net-zero commitments and policy-backed blending floors, while Synthetic CHJ Fuels occupy the fastest-growing tier as power-to-liquid pathways mature. Aviation applications sustain the dominant demand share, though Chemical Manufacturing feedstock substitution is emerging as a secondary volume sink for off-spec hydrothermal output.
The U.S. EPA administers Renewable Fuel Standard obligations that classify CHJ-derived SAF for compliance credits, while the EU's ReFuelEU Aviation mandates progressive blending thresholds at EU airports. ASTM International's D7566 and DEF STAN 91-091 certification frameworks govern product qualification, creating multi-year approval barriers for new process entrants. Stakeholders must monitor military specification expansions and bilateral SAF trade agreements to anticipate demand geography shifts.
Market Dynamics
Military procurement programs and commercial airline offtake agreements are compressing certification timelines for drop-in sustainable aviation fuels, forcing process developers to parallel-track ASTM D7566 Annex A5 qualification with production scale-up.
Growth Catalysts
- ReFuelEU Aviation Mandates:The EU's progressive blending thresholds at member state airports obligate fuel suppliers to source certified SAF volumes, creating guaranteed offtake channels for CHJ producers.
- Wet Biomass Feedstock Abundance:Agricultural residues and waste lipids in the United States Corn Belt and Southeast Asia provide geographically distributed input streams that reduce supply risk.
- Heterogeneous Catalyst Advances:Nickel-molybdenum and noble-metal formulations developed at subcritical temperatures are improving C8-C16 hydrocarbon selectivity and reducing reactor fouling.
Market Restraints
- Hydrogen Input Cost Volatility:Green hydrogen procurement for hydrodeoxygenation stages exposes CHJ economics to electrolyzer capacity constraints and renewable electricity price swings.
- Specialized Reactor Fabrication Bottlenecks:High-pressure vessel manufacturing concentrates among a limited set of certified fabricators, extending equipment delivery timelines.
- ASTM D7566 Certification Friction:Multi-year qualification protocols for novel Annex A5 pathways delay revenue generation for new market entrants.
Strategic Opportunities
- Chemical Manufacturing Feedstock Substitution:Off-spec hydrothermal output streams can displace naphtha-derived intermediates in specialty chemical synthesis.
- Power-to-Liquid Pathway Convergence:Integration of electrolytic hydrogen with captured carbon dioxide enables fully synthetic CHJ production independent of biomass availability.
- Bilateral SAF Trade Agreements:Emerging frameworks between the United States and European Union jurisdictions could unlock cross-border certificate trading for compliance purposes.
Industry Challenges
- Hydrothermal Liquefaction Engineering Talent Scarcity:The specialized skill set for aqueous-phase catalytic conversion scale-up is collapsing across North American and European labor markets.
- Multi-Phase Reactor Commissioning Complexity:Subcritical temperature and pressure control systems require extended startup periods that compress project returns.
- Intellectual Property Licensing Fragmentation:Patent thickets covering catalyst compositions and reactor designs create negotiation overhead for technology adopters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Catalytic Hydrothermolysis Jet [CHJ] Fuel Market |
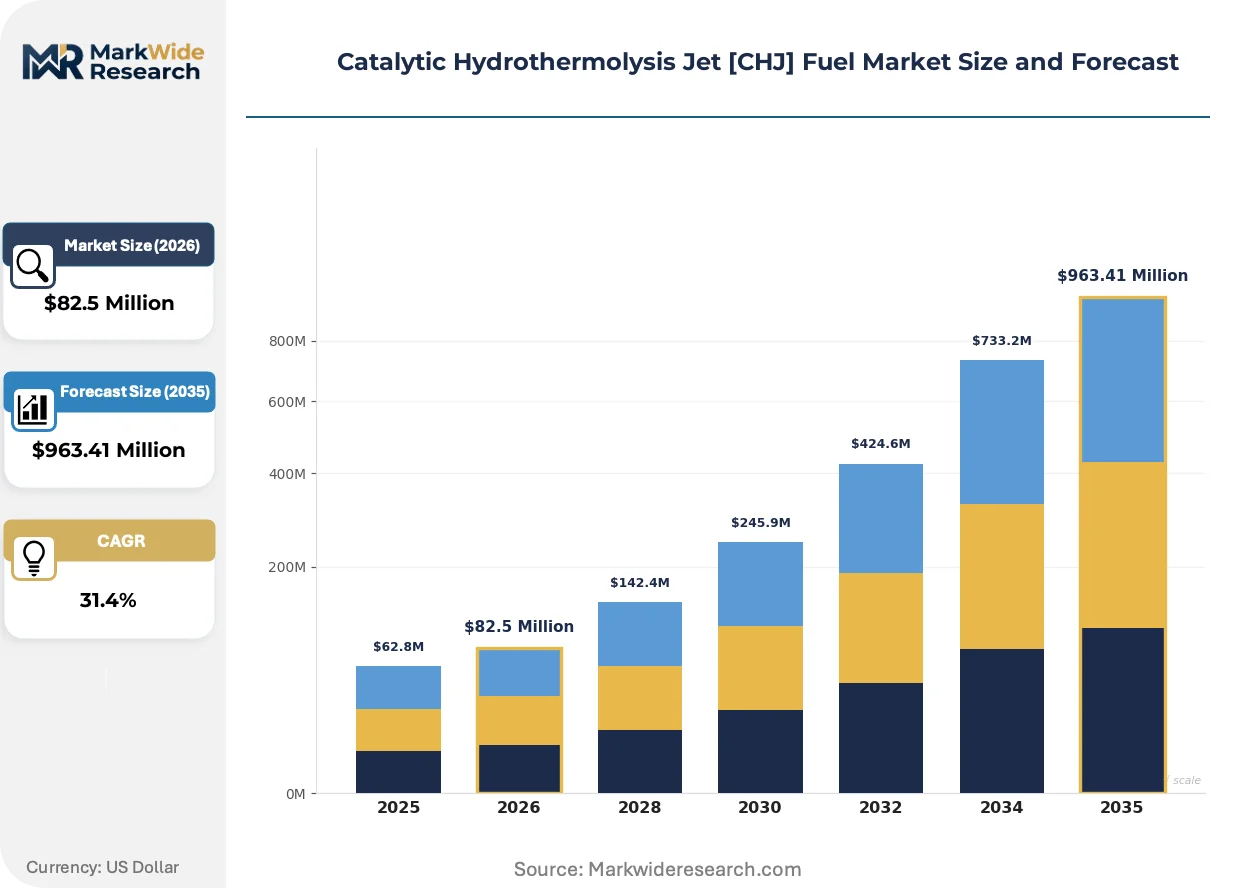
| Market Size in 2026 | $82.5 Million |
| Market Size in 2035 | $963.41 Million |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional CHJ Fuels, Renewable CHJ Fuels, Synthetic CHJ Fuels, Blended CHJ Fuels Application: Aviation, Transportation, Chemical Manufacturing, Power Generation End User: Aerospace Industry, Oil & Gas Sector, Energy Companies, Research Institutions Technology: Hydrothermal Liquefaction, Catalytic Processing, Thermal Treatment, Upgrading Techniques |
| Companies Covered | Applied Research Associates, Inc., Chevron Lummus Global, World Energy, McDermott, SkyNRG, Aemetis, Inc., Neste Oyj, Honeywell UOP, Gevo, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Catalytic Hydrothermolysis Jet [CHJ] Fuel Market Strategic Shifts
Continuous-flow reactor architectures and integrated hydrotreating configurations are compressing capital intensity and improving product slate flexibility for CHJ producers targeting aviation offtake.
Continuous hydrothermal liquefaction reactor designs with solid-separation internals are supplanting batch-mode systems that dominated pilot-scale demonstrations. Aviation fuel offtakers including European flag carriers and U.S. defense procurement offices are specifying continuous-process guarantees in supply agreements. This technology transition is collapsing per-unit capital requirements and enabling modular deployment strategies.
The U.S. EPA's Renewable Fuel Standard obligation structure now explicitly classifies CHJ-derived SAF for compliance credit generation, altering refiner procurement calculus. Fuel suppliers must demonstrate renewable volume obligations through certified pathways, redirecting capital toward ASTM-qualified processes. Military aviation specification expansions are responding fastest, with U.S. Navy and Air Force programs accelerating Annex A5 integration timelines.
Airline procurement departments are consolidating SAF purchasing through aggregator intermediaries rather than direct biorefinery contracting. European flag carriers and North American network carriers are channeling demand through specialized fuel suppliers that blend and certify multi-pathway volumes. This intermediation concentrates price-setting power in Rotterdam and Singapore trading hubs.
Catalytic Hydrothermolysis Jet [CHJ] Fuel Market Segmentation
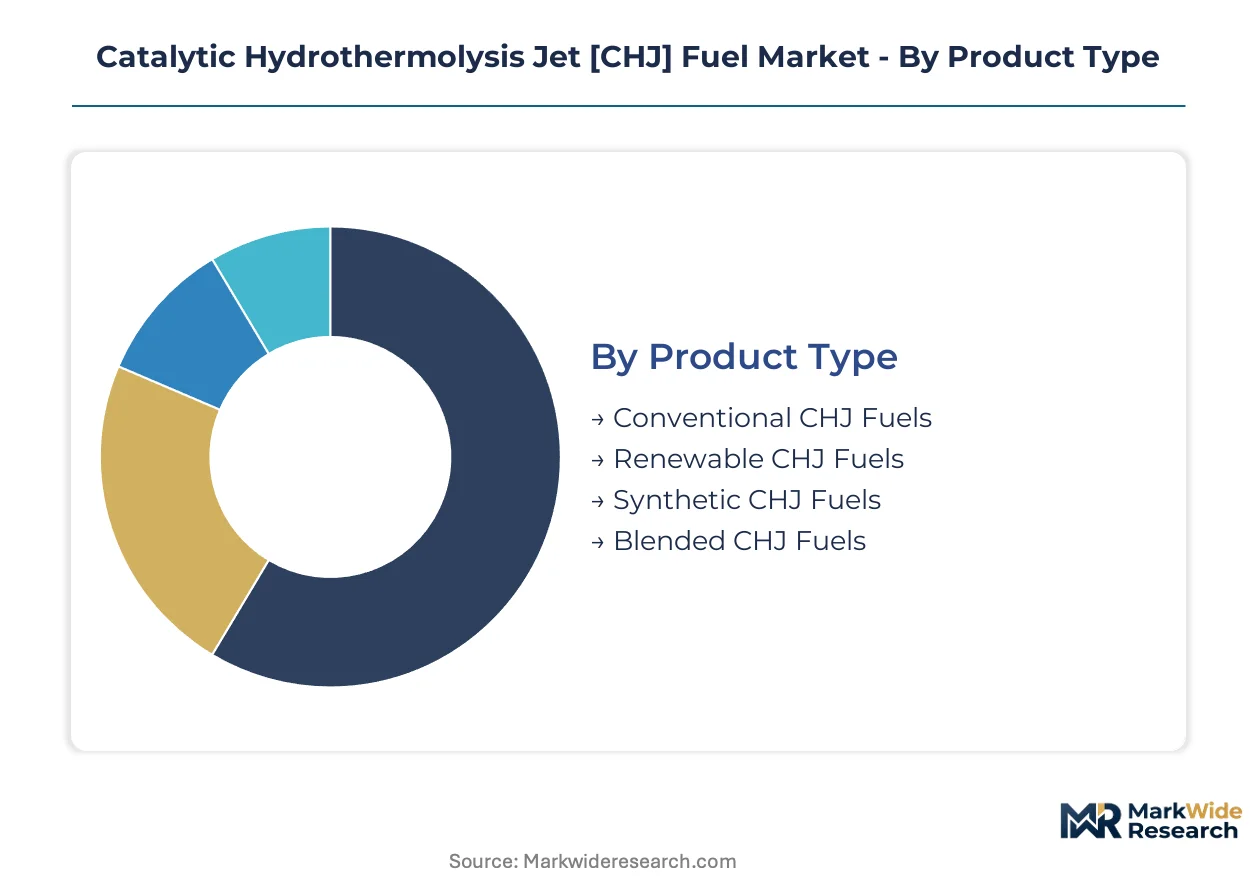
Segmentation reveals how regulatory pathways and certification frameworks partition demand across the CHJ fuel value chain. ASTM D7566 Annex A5 qualification status determines which product categories access military and commercial aviation procurement channels.
Product Type:
ASTM International's D7566 framework creates tiered market access based on feedstock origin and process pathway, with Annex A5 specifically governing catalytic hydrothermolysis qualification.
- Renewable CHJ Fuels:Produced from wet biomass or waste lipids through aqueous-phase catalytic conversion at subcritical temperatures. U.S. EPA Renewable Fuel Standard obligations and EU ReFuelEU Aviation mandates concentrate demand in North American and European airport fueling systems.
- Synthetic CHJ Fuels:Manufactured via power-to-liquid pathways integrating electrolytic hydrogen with captured carbon dioxide. Emerging bilateral SAF trade agreements between the United States and European Union jurisdictions are accelerating procurement for this category.
- Conventional CHJ Fuels:Early-generation hydrothermal products predating current ASTM specifications, now limited to research and non-certification applications.
- Blended CHJ Fuels:Mixtures with conventional jet fuel meeting specific aromatic content thresholds for drop-in compatibility.
Established volume favors Renewable CHJ Fuels; emerging adoption favors Synthetic CHJ Fuels.
Application:
Cost tier differentiation separates premium-certified aviation volumes from lower-margin chemical feedstock off-take for off-spec hydrothermal output.
- Aviation:Drop-in sustainable aviation fuel meeting ASTM D7566 Annex A5 and DEF STAN 91-091 specifications for turbine engine compatibility. U.S. Navy and Air Force procurement programs compress certification timelines for qualified producers.
- Chemical Manufacturing:Off-spec hydrothermal streams displace naphtha-derived intermediates in specialty chemical synthesis. Singapore and Rotterdam trading hubs aggregate this secondary demand.
- Transportation:Ground vehicle and marine diesel applications utilizing CHJ-derived paraffinic streams outside aviation certification pathways.
- Power Generation:Turbine combustion applications in distributed energy systems requiring liquid fuel flexibility.
Aviation commands premium pricing tiers; Chemical Manufacturing absorbs volume at compressed margins.
End User:
Customer type concentration reflects procurement centralization through specialized fuel aggregators rather than direct biorefinery contracting.
- Aerospace Industry:Commercial airlines and defense procurement offices specifying continuous-process guarantees in supply agreements. European flag carriers channel demand through Rotterdam-based intermediaries.
- Oil & Gas Sector:Integrated refiners seeking renewable volume obligations under EPA compliance structures.
- Energy Companies:Diversified fuel suppliers blending multi-pathway SAF volumes for airport delivery.
- Research Institutions:National laboratories and university consortia conducting catalyst and process development.
Procurement consolidation favors Aerospace Industry intermediation; direct contracting persists with Research Institutions.
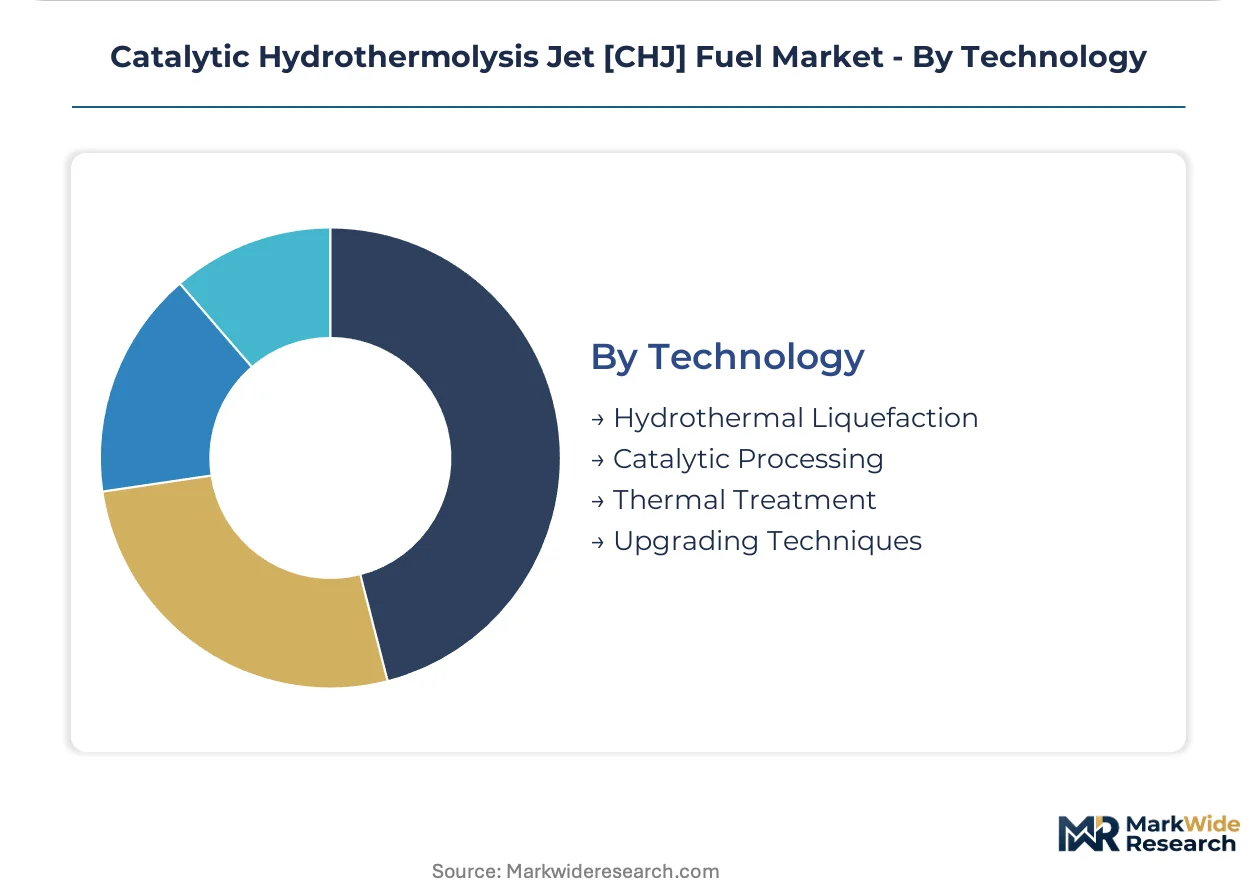
Technology:
Supply concentration in high-pressure vessel fabrication creates bottlenecks that favor specific reactor configurations.
- Hydrothermal Liquefaction:Aqueous-phase biomass conversion at 250-350°C and 10-20 MPa yielding C8-C16 hydrocarbon streams. Continuous-flow reactor designs with solid-separation internals are supplanting batch-mode pilot systems.
- Catalytic Processing:Heterogeneous nickel-molybdenum and noble-metal formulations improving hydrocarbon selectivity. Extended startup periods for subcritical temperature control compress project returns.
- Thermal Treatment:Pre-processing stages for feedstock conditioning and moisture management.
- Upgrading Techniques:Hydrotreating and hydrodeoxygenation stages requiring green hydrogen inputs.
Hydrothermal Liquefaction anchors current deployment; Catalytic Processing gains share fastest through catalyst advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-setting power concentrates in Rotterdam and Singapore trading hubs, while production scale-up accelerates across the United States Corn Belt. Regulatory asymmetry between EU blending mandates and US military procurement programs is fragmenting regional competitive dynamics.
United States
Domestic feedstock abundance and defense procurement programs compress certification timelines for CHJ producers. The EPA's Renewable Fuel Standard obligations classify CHJ-derived SAF for compliance credits, redirecting refiner capital toward ASTM-qualified processes. Agricultural residue clusters in Iowa and Illinois anchor wet biomass supply chains for hydrothermal liquefaction scale-up.
Germany
Industrial chemical demand and aviation decarbonization targets create dual offtake channels for CHJ output. The EU's ReFuelEU Aviation mandates progressive blending thresholds at German airports, forcing fuel suppliers to source certified SAF volumes. The Ruhr industrial corridor concentrates hydrotreating capacity and catalyst manufacturing expertise for process developers.
Singapore
Trading hub status and renewable refining infrastructure aggregate multi-pathway SAF volumes for Asian aviation markets. The country's national environmental regulator enforces maritime and aviation fuel quality standards that align with ASTM D7566 frameworks. Jurong Island's integrated petrochemical complex hosts hydroprocessing units adaptable to CHJ co-processing.
Netherlands
Rotterdam's port infrastructure and existing biofuel terminals position the region as Europe's SAF blending and certification center. EU Green Deal implementation tightens carbon intensity thresholds for aviation fuel imports through Dutch customs zones. The Port of Rotterdam's industrial cluster hosts pre-commercial CHJ demonstration units targeting Annex A5 qualification.
United Kingdom
Defense aviation specifications and commercial airline net-zero commitments drive parallel certification efforts. DEF STAN 91-091 standards govern military turbine fuel compatibility, creating a separate qualification pathway from commercial ASTM protocols. The Humber industrial cluster hosts carbon capture and hydrogen production assets relevant to power-to-liquid CHJ synthesis.
Catalytic Hydrothermolysis Jet [CHJ] Fuel Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Patent holders with hydrothermal liquefaction expertise occupy premium positions in process licensing, while integrated refiners and fuel aggregators capture margin through blending and certification scale. The market consolidates around three strategic archetypes: defense contractors with military certification heritage, renewable feedstock logistics specialists, and diversified energy traders with SAF aggregation platforms. Dominant competitive moves include strategic partnerships between technology developers and offtake aggregators, plus capacity expansion at existing renewable diesel complexes.
Among defense-contractor-derived technology developers, Applied Research Associates, Inc. exemplifies the military-certification-first archetype, leveraging federal procurement relationships to accelerate Annex A5 pathways. Neste Oyj anchors the renewable feedstock logistics tier through Singapore and Rotterdam refining positions. SkyNRG occupies the fuel aggregation specialist position, channeling European flag carrier demand through certified blending infrastructure. These three represent distinct competitive vectors rather than direct substitutes.
| Leading Market Players |
|---|
| Applied Research Associates, Inc. |
| Chevron Lummus Global |
| World Energy |
| McDermott |
| SkyNRG |
| Aemetis, Inc. |
| Neste Oyj |
| Honeywell UOP |
| Gevo, Inc. |
| Others |
Value Chain & Pricing Dynamics
ASTM D7566 Annex A5 certification gates both supply qualification and price differentiation simultaneously, creating a bifurcated market where certified producers command aviation offtake premiums while uncertified volumes divert to chemical feedstock channels at compressed margins. The EPA's Renewable Fuel Standard obligation structure and EU ReFuelEU Aviation mandates institutionalize this tiering by linking compliance credit values to pathway qualification status.
Pricing Analysis
The customization-premium spread separates continuous-process guarantees demanded by military procurement offices from standard batch-mode output sold into chemical manufacturing. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with aviation-certified volumes capturing the widest spreads. Cost compression in synthetic CHJ pathways is intensifying because green hydrogen procurement exposes economics to electrolyzer capacity constraints. Chemical Manufacturing buyers exhibit highest price sensitivity; defense procurement offices demonstrate lowest.
Supply Chain Analysis
High-pressure vessel fabrication bottlenecks concentrate among certified fabricators in Germany, Japan, and South Korea, extending equipment delivery timelines for reactor deployment. Feedstock supply draws from wet biomass clusters in the United States Corn Belt and Southeast Asian palm oil residues, while catalyst formulations rest on nickel-molybdenum and noble-metal supply chains. Single-source vulnerability in heterogeneous catalyst intellectual property creates licensing negotiation overhead. Distribution runs through Rotterdam and Singapore trading hubs that aggregate multi-pathway SAF volumes for airport delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a high-growth disruption anchored by the convergence of power-to-liquid pathway maturation and tightening EU blending mandates that compress incumbent refiner adaptation windows.
For Market Incumbents: Secure military certification heritage advantages by accelerating Annex A5 parallel-track qualification with production scale-up before synthetic CHJ pathways achieve cost parity. Defend position through backward integration into wet biomass feedstock clusters in Iowa and Illinois, locking supply certainty against emerging power-to-liquid competitors. Channel R&D toward continuous-flow reactor architectures that collapse per-unit capital intensity. For New Entrants and Emerging Players: Lead with chemical manufacturing feedstock substitution as the most penetrable white-space target, displacing naphtha-derived intermediates with off-spec hydrothermal output at compressed but volume-accretive margins. Target Singapore and Rotterdam trading hub intermediation as the go-to-market angle, bypassing direct airline contracting complexity through fuel aggregator relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from defense contractors with stranded hydrothermal liquefaction intellectual property and limited commercial aviation channel access. Long-term viability favors technology licensing positions over asset-heavy production ownership given reactor fabrication bottlenecks and certification friction timelines. Watch bilateral SAF trade agreement negotiations between the United States and European Union as the critical inflection signal for cross-border certificate trading value.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Reactor Deployment | Collapses capital intensity for CHJ producers targeting ASTM D7566 Annex A5 qualification. |
| Backward Integration into Feedstock | Locks wet biomass supply certainty in United States Corn Belt agricultural residue clusters. |
| Military Certification Fast-Track | Leverages U.S. Navy and Air Force procurement programs to compress Annex A5 timelines. |
| Power-to-Liquid Pathway Investment | Integrates electrolytic hydrogen with captured carbon dioxide for synthetic CHJ independence. |
| Fuel Aggregator Partnership | Channels European flag carrier demand through Rotterdam-based blending infrastructure. |
Study Parameters
Cross-validation between primary interviews with industry stakeholders and secondary validation anchors the qualitative findings. The research combined discussions with hydrothermal liquefaction plant managers, aviation fuel procurement leads at European flag carriers, catalyst R&D directors, and defense contracting officers with trade data from U.S. EPA Renewable Fuel Standard compliance reports, EU ReFuelEU Aviation implementation documents, ASTM International certification filings, and customs records tracking renewable diesel complex expansions. Bottom-up and top-down triangulation reconciled production capacity announcements with offtake agreement volumes.
Sensitivity analysis across feedstock cost scenarios, hydrogen price volatility bands, and certification timeline compressions informed the analytical framework over the projection horizon. The model segmented by product type, application, end user, and technology pathway, with CAGRs derived from regression analysis against policy-mandated blending floors and military procurement acceleration curves. Industry-specific forecast inputs incorporated electrolyzer capacity buildout trajectories and heterogeneous catalyst selectivity improvements from subcritical temperature research.
The analysis sits within stated boundaries; outcomes outside sustained EPA obligation enforcement and EU mandate implementation timelines would require recalibration. Forecasts reflect assumptions regarding ASTM D7566 Annex A5 qualification throughput and green hydrogen cost curves. Practitioners should keep alternative scenarios live as bilateral SAF trade agreement negotiations and military specification expansion decisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
India Retail Fuel Market
Fuels
China LNG Bunkering Market
Fuels
LPG Cylinder Manufacturing Market
Fuels
Commercial Aircraft Aviation Fuel Market
Fuels
South America Bunker Fuel Market
Fuels
Iso-Octane Market
Fuels
Refuse Derived Fuel Market
Fuels
Renewable Heating Fuels Market
Fuels
Biobutanol Market
Fuels
Brazil Bunker Fuel Market
Fuels
Diesel As Fuel Market
Fuels
Asia-Pacific Coal Market
Fuels
China Bunker Fuel Market
Fuels
Aerospace Aviation Fuels Market
Fuels
Alcohol-To-Jet (ATJ) Fuel Market
Fuels
Global Industrial Burner Market