
 Europe Commercial Aircraft Aviation Fuel Market | 2026-2036
Europe Commercial Aircraft Aviation Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Commercial Aircraft Aviation Fuel Market Foresight
The capability gap between integrated refiners and standalone fuel blenders is collapsing as ReFuelEU Aviation mandates force every supplier to build biogenic feedstock access and ISCC certification. BP plc leverages its Rotterdam refinery complex and pipeline network to anchor supply security across Northwest Europe. Shell plc sustains competitive positioning through backward integration into renewable feedstock trading and hydrogen-derived synthetic fuel pilots. TotalEnergies SE differentiates via dedicated SAF production at its La Mède biorefinery and offtake agreements with Air France-KLM.
Europe commercial aircraft aviation fuel comprises refined kerosene meeting strict flash point, freeze point, and aromatics specifications under DEF STAN 91-091 and ASTM D1655, engineered to deliver reliable combustion performance at altitude and sub-zero temperatures. Jet A-1 dominates volume across the continent due to its lower freeze point suitability for transcontinental routes, while sustainable aviation fuel represents the fastest-growing category as blending mandates escalate and certificate trading mechanisms mature. Airlines command the largest end-user share through centralized procurement at major hub airports, though cargo operators are gaining structural importance as integrators like DHL and FedEx expand European freighter bases.
EMA, ECHA, and the EU Green Deal collectively shape product standards, carbon intensity thresholds, and market access conditions for aviation fuel suppliers across Europe. ReFuelEU Aviation imposes progressively binding SAF blending obligations that redirect refinery investment toward hydroprocessed esters and fatty acids and Fischer-Tropsch synthesis pathways. Stakeholders must monitor feedstock competition with road transport biodiesel, certification cost trajectories, and the pace of power-to-liquid commercialization to align capital deployment with regulatory compliance deadlines.
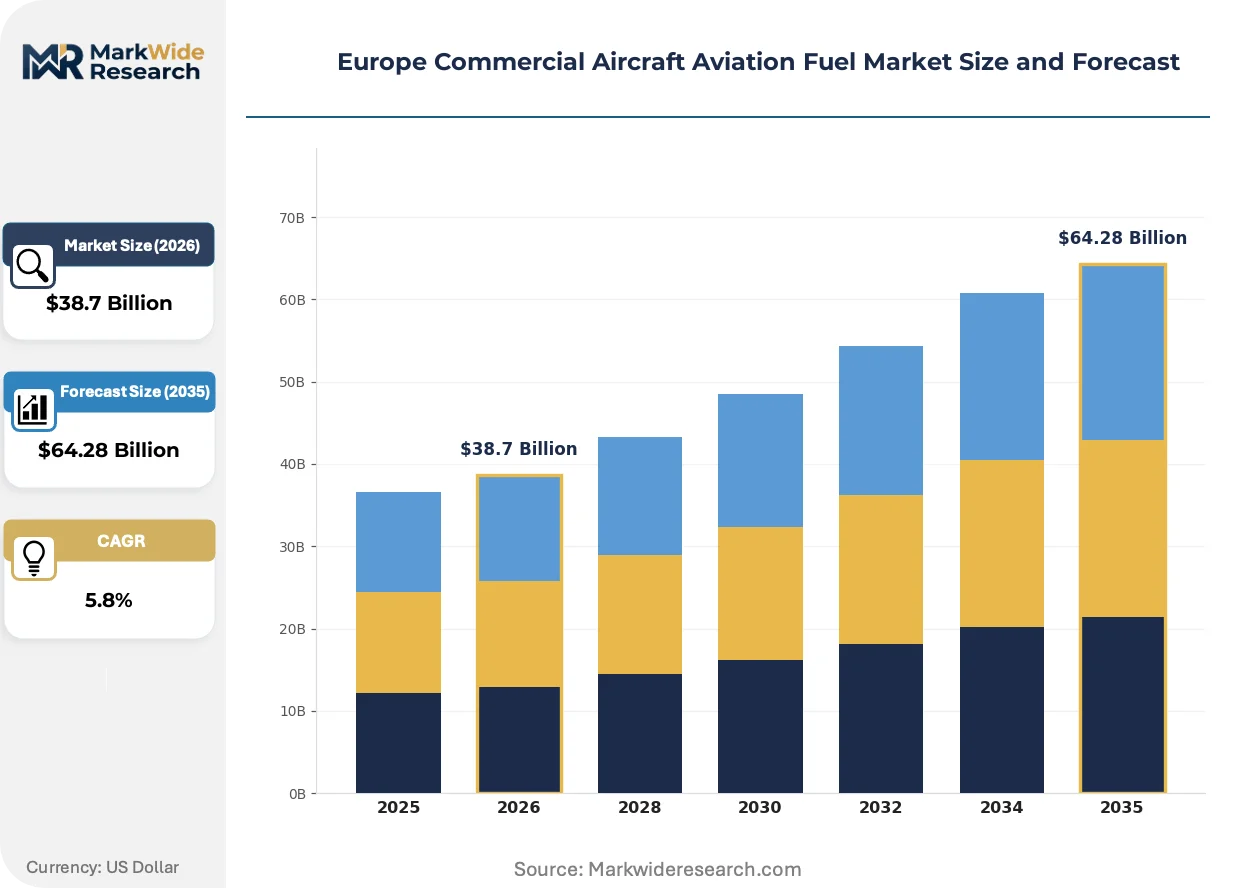
Market Dynamics
ReFuelEU Aviation mandates are compressing the capability gap between integrated refiners and standalone blenders, forcing every supplier to secure biogenic feedstock access and ISCC certification regardless of scale.
Growth Catalysts
- EU Green Deal enforcement:Binding carbon intensity thresholds redirect capital toward hydroprocessed esters and fatty acids production facilities across the continent.
- Full-service carrier fleet expansion:Long-haul aircraft deliveries at Frankfurt, Amsterdam Schiphol, and Paris Charles de Gaulle drive concentrated offtake volumes.
- Hub airport density concentration:Germany, France, and the United Kingdom sustain disproportionate fuel demand through synchronized slot allocation and route network optimization.
Market Restraints
- Feedstock competition with road transport:Waste oils and animal fats face bidding pressure from FAME biodiesel producers under RED III transport targets.
- Power-to-liquid capex intensity:Fischer-Tropsch synthesis facilities require electrolyzer scale and renewable power purchase agreements that few suppliers can secure.
- Certification cost trajectories:ISCC CORSIA and RSB verification expenses disproportionately burden smaller blenders without refinery integration.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden, Norway, and Finland offer first-mover advantages for synthetic fuel offtake agreements with SAS and Norwegian.
- Cargo operator procurement centralization:DHL and FedEx European freighter base expansions create dedicated fuel contracting channels outside passenger airline intermediation.
- Certificate trading mechanism maturation:ReFuelEU Aviation's book-and-claim system enables geographic decoupling of production and consumption for optimized logistics.
Industry Challenges
- Specialized process engineering talent scarcity:Hydroprocessing and gas-to-liquid expertise concentrates at Rotterdam, Antwerp, and Singapore, constraining European expansion timelines.
- Legacy Jet A-1 infrastructure lock-in:Existing pipeline networks and storage terminals require costly retrofitting for blended sustainable aviation fuel compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Commercial Aircraft Aviation Fuel Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Jet A, Jet A-1, Jet B, Sustainable Aviation Fuel End User: Airlines, Cargo Operators, Charter Services, Government Agencies Distribution Channel: Direct Sales, Distributors, Fueling Stations, Online Platforms Application: Commercial Flights, Military Operations, Private Aviation, Cargo Transport |
| Companies Covered | BP plc, Shell plc, TotalEnergies SE, Neste Oyj, Exxon Mobil Corporation, Repsol SA, Gazprom Neft PJSC, Chevron Corporation, Phillips 66, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Commercial Aircraft Aviation Fuel Market Shifts & Advancements
Aviation fuel supply chains are reconfiguring around biogenic feedstock provenance and synthetic pathway commercialization, with certification mechanisms replacing volume as the primary competitive differentiator.
Hydroprocessed esters and fatty acids technology is bifurcating the supplier base between those with captive waste oil collection networks and those dependent on spot market purchases. Full-service carriers at London Heathrow and Amsterdam Schiphol now mandate chain-of-custody documentation from their fuel suppliers. The technology is compressing margins for traders without backward integration into rendering and used cooking oil aggregation.
ReFuelEU Aviation's progressively binding SAF blending obligations are redirecting refinery investment away from conventional hydrocracking capacity. ECHA oversight of sustainability criteria ensures that only certified pathways qualify for mandate compliance. Suppliers without dedicated biorefinery assets face structural disadvantage as 2030 interim targets approach.
Airline procurement departments are consolidating fuel contracting around hub-specific offtake agreements rather than regional portfolio purchasing. Cargo operators at Leipzig and Liège are establishing direct supplier relationships that bypass traditional into-plane service providers. This pattern is most visible in Germany and the Netherlands where integrator freighter bases concentrate.
Europe Commercial Aircraft Aviation Fuel Market Segmentation
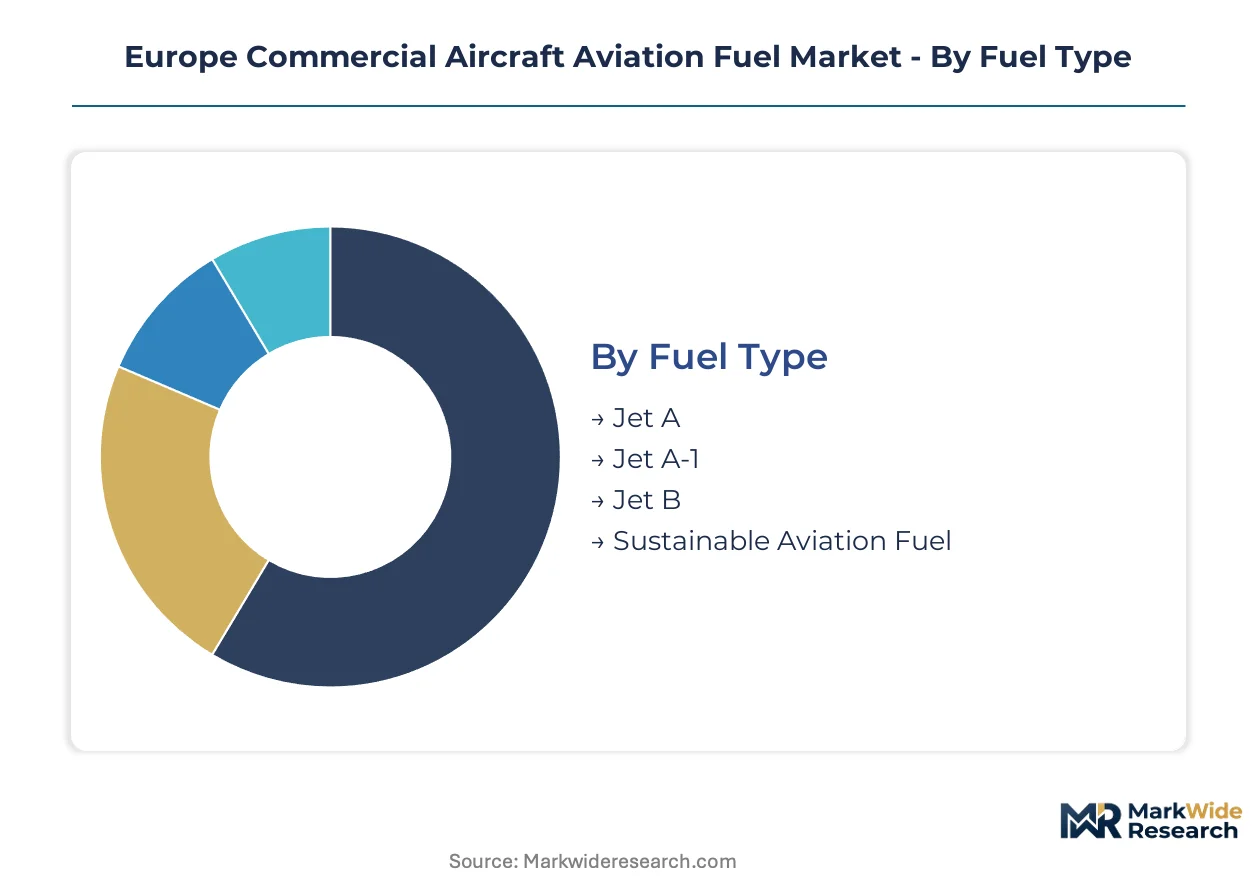
Segmentation in European aviation fuel markets determines supplier capital allocation, certification requirements, and pricing power. ReFuelEU Aviation mandates reshape competitive dynamics differently across fuel types, end users, and distribution channels.
Fuel Type:
Substitution pressure from sustainable alternatives varies sharply by fuel type, with conventional kerosene grades facing the steepest regulatory displacement.
- Jet A:Refined kerosene with flash point minimum of 38°C and freeze point of -40°C, formulated primarily for domestic US operations with limited European penetration. Demand concentrates at Mediterranean airports serving short-haul narrowbody fleets where cold-weather performance requirements relax.
- Jet A-1:Lower freeze point specification of -47°C enables transcontinental and polar route operations without fuel gelling. Frankfurt, Amsterdam Schiphol, and Paris Charles de Gaulle anchor European offtake volumes through full-service carrier hub operations and long-haul fleet density.
- Jet B:Wide-cut gasoline-kerosene blend with freeze point of -60°C, deployed for extreme cold climate operations. Arctic and high-altitude airports in Norway and northern Sweden sustain niche demand from regional turboprop services.
- Sustainable Aviation Fuel:Certified drop-in fuel meeting ASTM D7566 and DEF STAN 91-091 specifications through hydroprocessed esters and fatty acids or Fischer-Tropsch synthesis pathways. Blending mandates under ReFuelEU Aviation redirect refinery investment toward biogenic feedstock processing at Rotterdam, La Mède, and Neste's Singapore-exporting European supply points.
Jet A-1 anchors the volume base while Sustainable Aviation Fuel gains share at the steepest rate.
End User:
Procurement concentration determines supplier margin structure, with centralized airline fuel desks commanding steeper volume discounts than fragmented charter operators.
- Airlines:Full-service carriers at London Heathrow, Frankfurt, and Paris Charles de Gaulle operate centralized fuel procurement desks negotiating multi-year offtake agreements. Network density at hub airports creates concentrated demand pools that integrated refiners target with pipeline-connected supply security.
- Cargo Operators:Integrators DHL and FedEx expand dedicated freighter bases at Leipzig and Liège, establishing direct supplier relationships outside passenger airline intermediation. E-commerce volume growth drives structural importance in European fuel contracting.
- Charter Services:Fragmented operator base with seasonal demand fluctuations and airport-specific fueling requirements. Smaller scale limits negotiating leverage against into-plane service providers.
- Government Agencies:Military and state aviation operations governed by national defense procurement frameworks with specification waivers for operational security. NATO standardization enables cross-border supply coordination.
Airlines dominate procurement volume while Cargo Operators expand contract share most aggressively.
Distribution Channel:
Channel selection reflects supply chain control priorities, with direct sales capturing margin from integrated refiners and distributors serving fragmented demand.
- Direct Sales:Integrated refiners BP, Shell, and TotalEnergies supply major airlines through pipeline-connected terminal networks. Rotterdam-Antwerp- Amsterdam corridor concentration enables economies of scale in jet fuel logistics.
- Distributors:Independent fuel traders and regional suppliers serve secondary airports without pipeline access. ISCC certification requirements under ReFuelEU Aviation compress margins for non-integrated blenders.
- Fueling Stations:Into-plane service providers operate at airport ramps under airline fueling agreements. Ground handling consolidation at major hubs reduces supplier interface complexity.
- Online Platforms:Digital procurement interfaces emerging for spot market transactions and certificate trading under ReFuelEU Aviation book-and-claim mechanisms. Adoption remains limited by physical delivery requirements.
Direct Sales channels capture the largest volume flows while Online Platforms show the most rapid adoption trajectory.
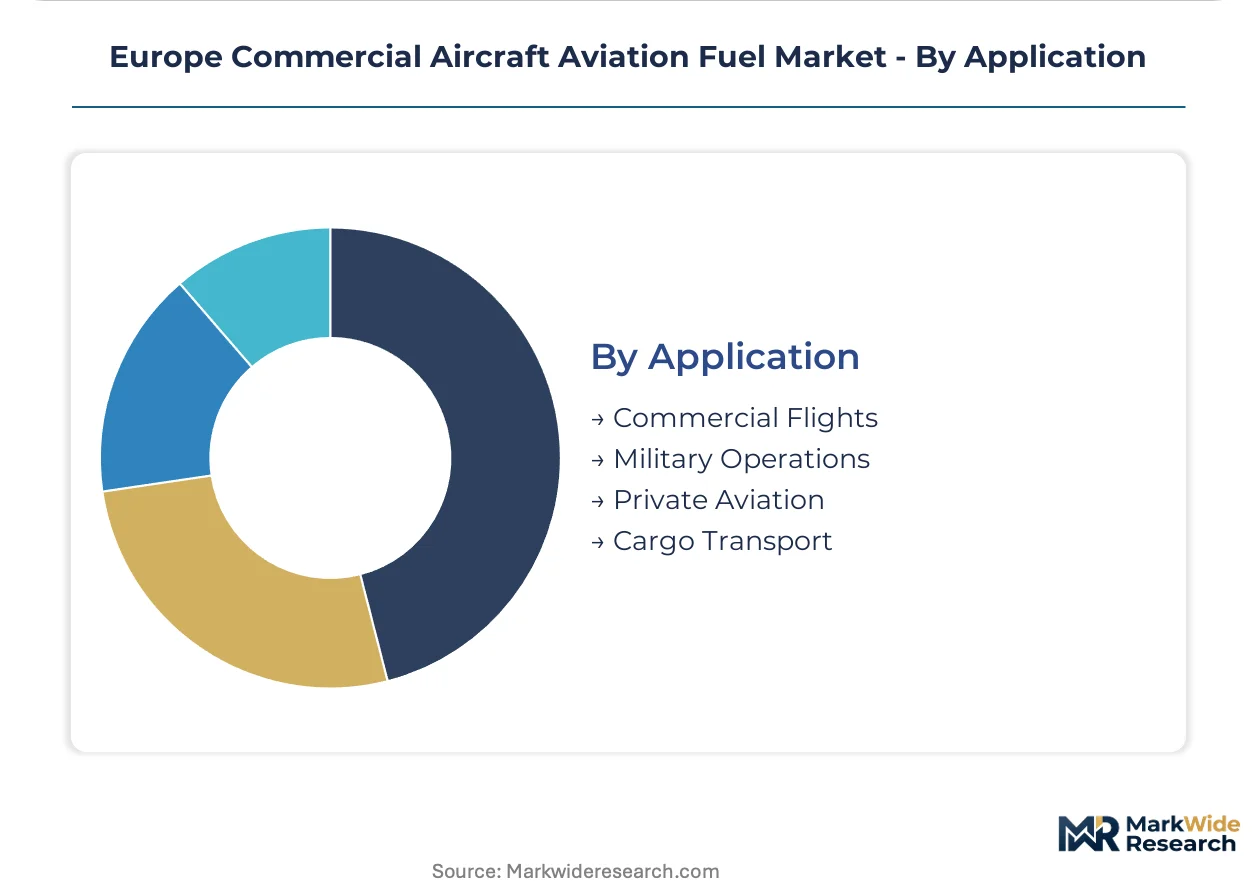
Application:
Application segmentation determines specification stringency and regulatory oversight intensity, with military operations operating outside civilian certification frameworks.
- Commercial Flights:Scheduled passenger services governed by EASA oversight and EU Green Deal carbon intensity thresholds. Full-service carriers at hub airports drive concentrated demand for certified sustainable aviation fuel.
- Military Operations:Defense aviation exempt from ReFuelEU Aviation mandates under national security provisions. NATO standardization enables supply interoperability across European airbases.
- Private Aviation:Business jet operations at London City, Geneva, and Nice Côte d'Azur with premium pricing tolerance for expedited fueling services. Smaller volume per transaction limits supplier prioritization.
- Cargo Transport:Dedicated freighter operations with overnight scheduling intensity and hub-specific fueling windows. Leipzig and Liège integrator bases reshape European distribution patterns.
Commercial Flights anchor demand volume while Cargo Transport applications expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cargo operators at Leipzig and Liège exhibit the lowest price elasticity, absorbing premium SAF costs under long-term integrator contracts. Charter services at Mediterranean secondary airports face acute price sensitivity, with seasonal demand forcing spot-market purchasing. Full-service carriers at Frankfurt, Amsterdam Schiphol, and Paris Charles de Gaulle occupy the middle ground, negotiating volume discounts while accepting mandated SAF premiums.
Germany
Frankfurt Airport anchors continental fuel demand through Lufthansa's hub-and-spoke network, while Leipzig-Halle freighter bases reshape cargo procurement patterns. The German Federal Ministry for Economic Affairs and Climate Action enforces national blending quotas accelerating SAF infrastructure deployment. The Rhine-Main industrial corridor concentrates hydroprocessing expertise and pipeline-connected storage terminals serving Central European distribution.
United Kingdom
London Heathrow and Gatwick sustain the highest passenger-volume fuel offtake in Europe, with British Airways and Virgin Atlantic driving concentrated procurement desk negotiations. The UK Department for Transport mandates SAF blending under the Jet Zero strategy, with 2040 net-zero aviation commitments exceeding EU timelines. The Thames estuary refining cluster and Liverpool storage terminals anchor Northwest European supply security.
France
Air France-KLM's dual-hub structure at Paris Charles de Gaulle and Orly generates synchronized demand spikes across long-haul and short-haul fleet rotations. The French Ministry of Ecological Transition implements ReFuelEU Aviation mandates through DGAC oversight, with La Mède biorefinery anchoring domestic HEFA production capacity. The Marseille-Fos industrial zone and Le Havre import terminals concentrate Atlantic coast fuel logistics.
Netherlands
Royal Dutch Shell and BP pipeline networks from Rotterdam to Amsterdam Schiphol create the densest jet fuel logistics corridor in Europe, with KLM's fleet renewal driving SAF offtake growth. The Dutch Ministry of Infrastructure and Water Management enforces national sustainable aviation targets exceeding baseline EU requirements. The Rotterdam-Antwerp refining complex hosts the continent's largest hydroprocessing capacity for biogenic feedstock conversion.
Nordic Region
SAS and Norwegian Air Shuttle operations at Stockholm Arlanda, Oslo Gardermoen, and Helsinki-Vantaa sustain premium pricing tolerance for synthetic fuel pilots and early SAF adoption. Sweden's Environmental Protection Agency and Norway's Ministry of Climate and Environment implement carbon taxation and blending mandates exceeding EU stringency. The Gothenburg biorefinery cluster and Statoil's Mongstad facility anchor Scandinavian synthetic fuel pathway development.
Europe Commercial Aircraft Aviation Fuel Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with refinery-backed suppliers commanding pipeline-connected supply security while independent blenders compete on certification agility. The market structure concentrates around three archetypes: integrated oil majors with backward biogenic feedstock control, standalone renewable fuel specialists with ISCC-certified production assets, and regional distributors serving secondary airports without pipeline access. Dominant competitive moves include strategic partnerships between refiners and airlines for multi-year SAF offtake agreements, and capacity expansion into hydroprocessed esters and fatty acids production at Rotterdam, La Mède, and Antwerp.
Among the integrated oil majors, BP plc, Shell plc, and TotalEnergies SE exemplify the refinery-backed archetype, each occupying positions shaped by pipeline network density and biorefinery asset control. Neste Oyj represents the standalone renewable specialist tier, with its Singapore-exporting supply points anchoring European HEFA availability. These four companies collectively illustrate how ReFuelEU Aviation mandates are collapsing historical capability gaps between integrated and non-integrated suppliers, forcing uniform biogenic feedstock access and certification compliance regardless of scale or legacy infrastructure.
| Leading Market Players |
|---|
| BP plc |
| Shell plc |
| TotalEnergies SE |
| Neste Oyj |
| Exxon Mobil Corporation |
| Repsol SA |
| Gazprom Neft PJSC |
| Chevron Corporation |
| Phillips 66 |
| Others |
Supply & Pricing Matrix
Ninety-day biogenic feedstock inventory cycles at Rotterdam storage terminals concentrate pricing power among pipeline-connected refiners while forcing standalone blenders into volatile spot-market exposure. This lead-time structure amplifies margin compression when waste oil and animal fat costs spike under RED III transport competition, embedding ReFuelEU Aviation compliance premiums into long-term offtake negotiations.
Pricing Analysis
After-sales service revenue from into-plane fueling and technical support contracts drives lifetime value beyond commodity margins for integrated suppliers. The market operates on contract-based long-term offtake structures, with price differentiation anchored in ISCC CORSIA certification tier and volume scale commitments. Cost compression in the charter operator segment is intensifying because seasonal demand fluctuations force spot-market purchasing against concentrated hub-airline procurement desks. Cargo operators at Leipzig and Liège exhibit the lowest price sensitivity, absorbing mandated SAF premiums under integrator contracts, while Mediterranean charter services face acute pricing pressure.
Supply Chain Analysis
Port congestion at Rotterdam and Antwerp container terminals elevates inbound logistics costs for biogenic feedstock shipments from Southeast Asian collection networks. Supply concentrates in the Netherlands, Belgium, and France, with hydroprocessing capacity drawing from waste oils, animal fats, and used cooking oil feedstocks. Single-source vulnerability to Neste's Singapore-exporting supply points creates structural risk for European HEFA availability. Distribution runs through pipeline-connected terminal networks serving hub airports, with secondary airports dependent on barge and truck logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ReFuelEU Aviation mandates constitute a regulatory inflection forcing uniform biogenic feedstock access across all supplier tiers, transforming a historically bifurcated market into a certification-driven growth disruption.
For Market Incumbents: Compound pipeline-connected supply security through dedicated biorefinery capacity expansion at Rotterdam, La Mède, and Antwerp. Deepen backward integration into waste oil collection networks to neutralize RED III transport competition. Anchor competitive positioning through multi-year SAF offtake agreements with Air France-KLM and Lufthansa procurement desks. For New Entrants and Emerging Players: Anchor in Nordic synthetic fuel pilots at Gothenburg and Mongstad where SAS and Norwegian Air Shuttle tolerate premium pricing for early pathway commercialization. Target cargo operator procurement centralization at Leipzig and Liège as the most penetrable segment outside passenger airline intermediation. Pursue direct supplier relationships with DHL and FedEx European freighter bases. For Investors and Strategic Acquirers: Carve-out targets emerge from national oil companies with stranded conventional hydrocracking assets requiring biorefinery retrofit capital. Long-term viability centers on ISCC-certified production capacity with pipeline-connected terminal access. Watch power-to-liquid electrolyzer scale and renewable power purchase agreement closures as the critical inflection signal for synthetic pathway commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| Biorefinery Capacity Expansion | HEFA production at Rotterdam and La Mède secures ReFuelEU Aviation compliance feedstock. |
| Backward Integration into Feedstock | Captive waste oil collection networks neutralize RED III transport sector bidding pressure. |
| Long-term SAF Offtake Agreements | Multi-year contracts with Air France-KLM anchor revenue visibility through mandate escalation. |
| Power-to-Liquid Pilot Investment | Fischer-Tropsch synthesis at Mongstad positions for synthetic fuel pathway maturation. |
| Certificate Trading Mechanism Participation | Book-and-claim system enables geographic decoupling for optimized logistics under ECHA oversight. |
Research Methodology
The analysis maps conventional jet fuel grades, sustainable aviation fuel pathways, and synthetic fuel pilots, each validated through fuel procurement executives, refinery operations directors, airline sustainability officers, and into-plane service providers. Primary interview intelligence triangulates against EIA jet fuel stock data, EU ETS transaction records, ISCC certification registries, and ReFuelEU Aviation implementation guidance. Bottom-up segment sizing and top-down macroeconomic anchoring ensure cross-methodology consistency.
Forecast outputs were validated against external benchmarks including IEA aviation fuel demand projections and Eurocontrol traffic recovery patterns. The analytical framework models fuel type substitution dynamics, end-user procurement concentration, distribution channel evolution, and regional mandate stringency across the projection horizon. CAGRs derive from segment-level volume build-ups incorporating fleet renewal schedules, hub airport slot allocations, and blending obligation trajectories. Industry-specific inputs include hydroprocessing capacity utilization rates and biogenic feedstock cost curves.
Material uncertainties — feedstock competition intensification, power-to-liquid commercialization delays, and certificate trading mechanism liquidity — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and airline fleet renewal timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Methane Market
Fuels
City Gas Distribution Market
Fuels
Industrial Fuel Filter Market
Fuels
Global Industrial Burner Market
Fuels
Caribbean Islands Bunker Fuel Market
Fuels
North America Wood Pellet Market
Fuels
Global Fuel Ethanol Market
Fuels
Carbonizers Market
Fuels
Saudi Arabia Automotive Fuels Market
Fuels
Coal Intelligent Dry Separators Market
Fuels
Fuel Quality Testing Market
Fuels
South America Defense Aircraft Aviation Fuel Market
Fuels
LNG Fueling Station Market
Fuels
Composite Overwrapped Pressure Vessels (Copvs) Market
Fuels
Middle-East and Africa Defense Aircraft Aviation Fuel Market
Fuels
Mobile Gas Pumping System Market