
 Iso-Octane Market | 2026-2036
Iso-Octane Market Size, Share, and Industry Trends Forecast 2026-2036
Iso-Octane Market Foresight
Middle Eastern alkylate supply is decoupling from traditional Atlantic Basin pricing benchmarks, creating arbitrage windows for Asian buyers. ExxonMobil Corporation leverages integrated refinery-chemical complexes in the US Gulf Coast to sustain cost-advantaged iso-octane output. Royal Dutch Shell plc anchors its position through proprietary alkylation technology licensed across European and Asian refineries. Chevron Phillips Chemical Company competes on specialty-grade purity, controlling narrow-cut distillation capacity that serves laboratory reagent and precision fuel-testing segments.
Iso-octane, or 2,2,4-trimethylpentane, is a branched-chain alkane with a research octane number of 100 that serves as the primary reference standard for antiknock performance in spark-ignition engines. Industrial production relies on catalytic alkylation of isobutane with isobutylene or n-butenes over strong acid catalysts, yielding a product stream that refiners blend into premium gasoline or sell as pure reference fuel for engine calibration and emissions certification. Pure Iso-Octate dominates value capture due to stringent purity requirements in ASTM and EN standard test protocols, while Blended Iso-Octane occupies higher volume tiers tied to regional gasoline specifications. The Automotive Industry end-user segment leads structural demand as OEMs redesign powertrains around higher compression ratios that require 95+ RON fuels, whereas Research Laboratories represent a stable margin pool insulated from commodity cyclicality.
EPA fuel volatility standards and the EU F-Gas Regulation indirectly shape iso-octane demand by mandating cleaner-burning gasoline formulations that favor high-octane, low-vapor-pressure blending components. China's SAMR enforces GB 17930 gasoline standards that elevate national octane floors, compelling domestic refiners to expand alkylation capacity or import premium blending stocks. Stakeholders must monitor regulatory divergence between California's CARB specifications and emerging Asian national standards, as fragmented certification requirements will determine which purity grades and distribution channels capture premium returns.
Market Dynamics
Refiners face mounting pressure to upgrade alkylation units as China's GB standards and California's CARB specifications simultaneously tighten octane floors and vapor-pressure limits, forcing capital allocation toward higher-purity iso-octane streams.
Growth Catalysts
- GB 17930 Mandate:China's SAMR-enforced gasoline standard elevates national RON requirements, compelling domestic refiners to expand alkylation capacity or import premium blending components.
- Powertrain Redesign:Automotive OEMs engineering higher compression ratio engines generate structural demand for 95+ RON fuels that iso-octane satisfies.
- East Asian Refining Hub Concentration:Export-oriented petrochemical complexes in South Korea and Japan anchor regional supply chains serving premium gasoline markets.
Market Restraints
- Hydrofluoric Acid Catalyst Risk:Strong acid alkylation processes face operational hazards and environmental liability that constrain greenfield unit deployment.
- Middle Eastern Supply Decoupling:Alkylate flows from Gulf producers increasingly bypass Atlantic Basin pricing benchmarks, creating arbitrage uncertainty for traditional buyers.
- Alternative Octane Boosters:Ethanol blending mandates and ether-based oxygenates compete for gasoline pool volume in regulated markets.
Strategic Opportunities
- Research Laboratory Segment:ASTM and EN standard test protocols require ultra-pure reference fuels, insulating margins from commodity cyclicality.
- EU F-Gas Regulation:Cleaner-burning gasoline formulations favor high-octane, low-vapor-pressure blending components in European refining.
- Digital Fuel Certification:Blockchain-traceable batch documentation opens premium pricing for precision engine calibration applications.
Industry Challenges
- Alkylation Unit Capex Intensity:Sulfuric acid and solid acid catalyst systems require substantial capital outlay for capacity expansion.
- Fragmented Certification Requirements:Divergence between California CARB specifications and emerging Asian national standards complicates multi-market product qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iso-Octane Market |
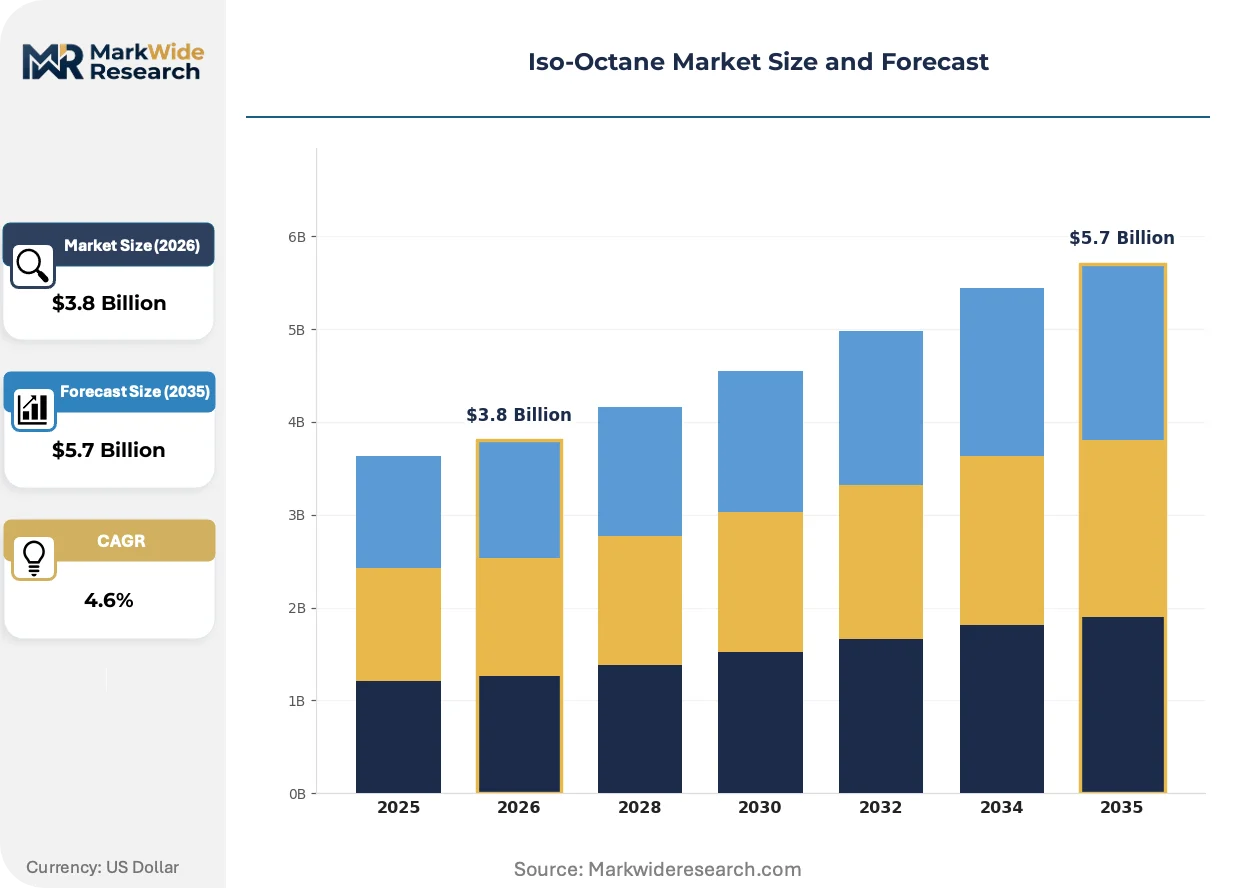
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Iso-Octane, Blended Iso-Octane, Additive Iso-Octane, Commercial Iso-Octane Application: Fuel, Chemical Solvent, Hydraulic Fluid, Laboratory Reagent End User: Automotive Industry, Chemical Manufacturing, Research Laboratories, Oil Refineries Distribution Channel: Direct Sales, Online Retail, Distributors, Specialty Stores |
| Companies Covered | ExxonMobil Corporation, Royal Dutch Shell plc, BP plc, Chevron Phillips Chemical Company, LyondellBasell Industries N.V., TotalEnergies SE, Valero Energy Corporation, Gazprom, Borealis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iso-Octane Market Shifts & Advancements
Solid acid catalyst systems and ionic liquid alkylation technologies are reshaping production economics while regulatory pressure on hydrofluoric acid units accelerates process substitution across major refining corridors.
Ionic liquid alkylation technology is unifying catalytic efficiency with reduced corrosion and environmental risk. European refiners adopting BP and UOP-licensed systems are compressing payback periods to under five years. The technology is unifying process safety improvements with higher iso-octane yield rates, displacing conventional sulfuric acid units in capacity expansion projects.
The EU F-Gas Regulation and its national implementing acts restrict high-global-warming-potential substances in industrial processes, indirectly mandating cleaner gasoline formulations. Refiners must reformulate toward lower-vapor-pressure, high-octane components to maintain compliance. German KBA vehicle-type approval procedures now reference these fuel specifications, forcing blendstock suppliers to certify purity grades previously reserved for laboratory markets.
Buyers in the automotive testing sector are consolidating procurement around certified reference fuel suppliers capable of dual ASTM-EN documentation. Tier-1 powertrain engineering firms in Stuttgart and Nagoya now require single-source accountability for engine calibration campaigns. This concentration is most visible in emissions certification workflows, where test-cell downtime costs exceed any premium paid for guaranteed batch consistency.
Iso-Octane Market Segmentation
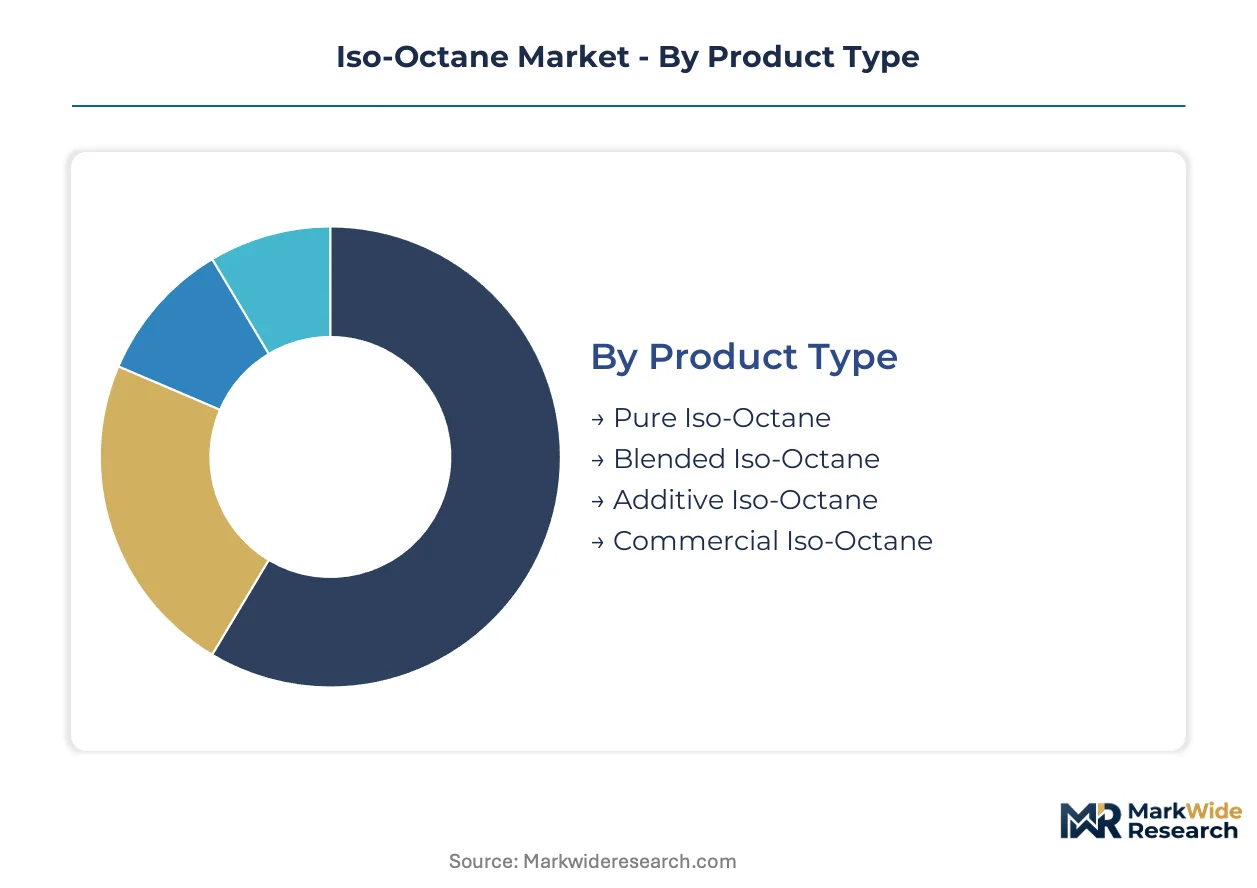
Iso-octane segmentation separates high-purity reference fuels commanding laboratory premiums from volume-grade blending stocks tied to refinery economics. Distinct purity tiers, application-specific formulations, and channel structures determine margin capture across automotive testing, chemical processing, and fuel blending end-uses.
Product Type:
Pure grades dominate value capture while blended volumes anchor refinery throughput economics.
- Pure Iso-Octane:2,2,4-trimethylpentane meeting ASTM D2700 and EN 228 reference fuel specifications serves engine calibration and emissions certification workflows. Demand concentrates in Stuttgart and Nagoya testing centers where OEMs require guaranteed batch consistency for powertrain development.
- Blended Iso-Octane:Alkylate streams blended to 95-98 RON specifications supply premium gasoline pools across East Asian refining hubs. South Korean and Japanese export-oriented petrochemical complexes anchor regional supply chains serving tightening GB 17930 and CARB octane floors.
- Additive Iso-Octane:Formulations incorporating detergents or stabilizers target specialized fuel system applications.
- Commercial Iso-Octane:General-purpose grades serve industrial solvent and cleaning applications with less stringent purity requirements.
Today's leader: Pure Iso-Octane. Tomorrow's challenger: Blended Iso-Octane.
Application:
End-use differentiation separates combustion performance requirements from chemical processing specifications.
- Fuel:High-octane blending component for spark-ignition engines where compression ratio increases drive structural demand for 95+ RON formulations. China's SAMR-enforced GB standards and California's CARB specifications simultaneously tighten requirements.
- Chemical Solvent:Non-polar solvent applications in polymer processing and extraction workflows leverage iso-octane's narrow volatility range and low reactivity profile.
- Hydraulic Fluid:Specialized formulations serve precision equipment requiring stable viscosity across temperature extremes.
- Laboratory Reagent:Ultra-pure grades for analytical chemistry and instrument calibration command pricing insulated from commodity cyclicality through ASTM and EN protocol mandates.
Fuel applications generate volume dominance. Laboratory reagents sustain margin premiums.
End User:
Customer concentration varies from consolidated automotive OEMs to fragmented research institutions.
- Automotive Industry:OEM powertrain engineering and Tier-1 supplier testing operations drive structural demand for certified reference fuels. Tier-1 firms now require single-source accountability for engine calibration campaigns.
- Chemical Manufacturing:Process industries utilize iso-octane as reaction medium and extraction solvent in polymer and pharmaceutical intermediate production.
- Research Laboratories:Academic and government testing facilities require dual ASTM-EN documentation, consolidating procurement around certified suppliers capable of guaranteed batch consistency.
- Oil Refineries:Integrated operators consume alkylate streams internally for gasoline pool blending or market premium blending components to third parties.
Automotive Industry commands volume leadership. Research Laboratories defend pricing power.
Distribution Channel:
Channel selection tracks order scale, certification requirements, and geographic concentration of demand.
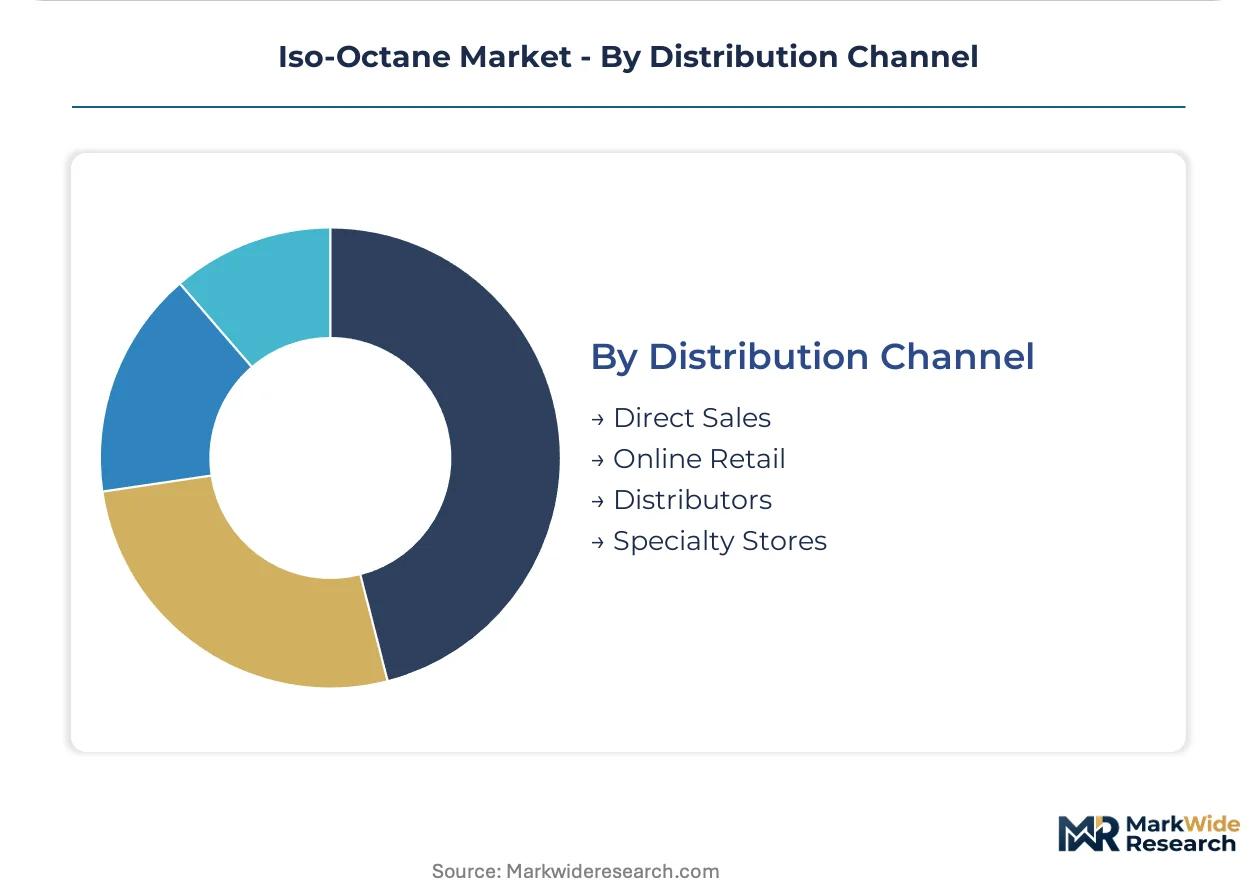
- Direct Sales:Long-term supply agreements between refiners and automotive OEMs or large chemical processors secure volume commitments and lock in certification documentation.
- Distributors:Regional intermediaries serve mid-scale chemical manufacturers and independent testing laboratories requiring smaller batch sizes with localized logistics support.
- Online Retail:E-commerce platforms facilitate procurement of laboratory-grade reagents by academic and small commercial research facilities.
- Specialty Stores:Niche outlets serve hobbyist and small-scale industrial users with packaged retail formats.
Direct Sales anchors refinery-scale volumes. Distributors capture fragmented laboratory demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between tightening fuel standards and legacy refinery infrastructure is redirecting alkylate trade flows toward jurisdictions where compliance costs align with upgrading incentives. Producers migrate capacity toward markets where octane-premium capture justifies acid-catalyst replacement cycles.
United States
Gulf Coast integrated refiners leverage existing alkylation infrastructure to supply CARB-specification blending components for California gasoline pools. EPA volatility standards under the Clean Air Act constrain Reid Vapor Pressure limits, forcing reformulation toward low-vapor-pressure iso-octane streams. Houston and Beaumont petrochemical corridors anchor domestic supply chains serving both automotive testing laboratories and premium gasoline blenders.
China
Domestic refiners face SAMR-enforced GB 17930 mandates elevating national RON floors to 95+ in metropolitan markets. MIIT gasoline quality standards compel alkylation unit expansion at state-owned refining complexes. Yangtze River Delta refining hubs around Shanghai and Ningbo concentrate import demand for high-purity blending stocks as domestic capacity ramps.
Germany
KBA vehicle-type approval procedures now reference EU F-Gas Regulation fuel specifications, forcing blendstock suppliers toward laboratory-grade purity tiers. REACH compliance adds cost layers to imported alkylate streams. Rhineland refining clusters and Bavarian automotive engineering centers around Stuttgart generate concentrated demand for certified reference fuels.
South Korea
Export-oriented petrochemical complexes at Ulsan and Yeosu anchor regional supply chains serving Japanese and Chinese premium gasoline markets. MFDS-aligned fuel quality enforcement creates certification requirements that favor integrated refinery-chemical operators. Yeosu industrial complex operators expand narrow-cut distillation capacity to capture laboratory reagent premiums.
Japan
METI energy security policies prioritize domestic alkylation capacity despite feedstock import dependence. Nagoya and Yokohama automotive testing corridors concentrate procurement power among Tier-1 powertrain engineering firms. JIS standard alignment with ASTM protocols enables dual-certification fuel suppliers to consolidate reference fuel contracts.
Iso-Octane Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue solid-acid technology licensing and ionic liquid process partnerships. The vendor base stratifies across integrated majors with captive refinery networks, independent alkylate merchants, and specialty pure-grade suppliers. Three archetypes dominate: Gulf Coast-anchored integrated refiners, European technology licensors, and Asian export-oriented petrochemical complexes. Capacity expansion and strategic technology licensing constitute the dominant competitive vectors as acid-catalyst replacement cycles accelerate.
Among integrated majors, ExxonMobil Corporation and Royal Dutch Shell plc exemplify the refinery-chemical complex archetype with proprietary alkylation technology positions. Chevron Phillips Chemical Company occupies a specialist tier focused on narrow-cut distillation purity grades. These three entities represent distinct strategic postures: integrated upstream-downstream control, technology licensing leverage, and specialty-grade margin capture respectively.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Royal Dutch Shell plc |
| BP plc |
| Chevron Phillips Chemical Company |
| LyondellBasell Industries N.V. |
| TotalEnergies SE |
| Valero Energy Corporation |
| Gazprom |
| Borealis |
| Others |
Supply & Pricing Matrix
Pure-grade certification ladders separating ASTM D2700 reference fuels from volume alkylate streams create divergent margin architectures across the Iso-Octane Market. Laboratory-grade batches command premiums through dual-documentation requirements while refinery-scale blending components compete on throughput economics, with each tier demanding distinct feedstock sourcing and distribution infrastructure.
Pricing Analysis
Distributor margins compress most severely at the commodity alkylate tier where South Korean and Japanese export complexes compete on volume. Three-tier pricing structure across premium reference fuels, standard automotive blends, and economy solvent grades reflects certification burden and batch-traceability investments. Cost compression in the blended segment intensifies because Middle Eastern supply decoupling fragments benchmark transparency. Research laboratories exhibit lowest price sensitivity due to test-cell downtime costs, while independent refiners face acute margin pressure from acid-catalyst replacement cycles.
Supply Chain Analysis
Specialized alkylation technician availability constrains capacity expansion in the US Gulf Coast, South Korea, and Germany where complex acid-handling protocols dominate. Feedstock supply draws from isobutane-rich natural gas liquids in Texas and the Middle East, with isobutylene feedstock anchored in fluid catalytic cracking complexes. Single-source vulnerability concentrates around hydrofluoric acid catalyst supply chains facing regulatory phase-out pressures. Distribution runs through long-term direct contracts between integrated refiners and automotive OEMs, with spot market activity limited to distressed alkylate volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Iso-Octane Market functions as a regulatory compounder where China's GB 17930 mandate and California's CARB specifications simultaneously tighten octane floors, forcing capital deployment toward higher-purity production infrastructure.
For Market Incumbents: To counter solid-acid technology disruption from BP and UOP licensors, incumbents must accelerate sulfuric acid unit replacement cycles at US Gulf Coast and Rhineland complexes while securing captive isobutane supply through backward integration into NGL fractionation infrastructure. Certification investment in dual ASTM-EN documentation capabilities locks in automotive testing laboratory contracts against specialty-grade competitors. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany opens a window for ionic liquid technology adopters to capture KBA vehicle-type approval fuel contracts previously held by incumbent refiners. White-space concentrates in blockchain-traceable batch documentation for precision engine calibration applications, with Nagoya and Stuttgart Tier-1 engineering firms consolidating procurement around single-source suppliers. Go-to-market positioning targets digital fuel certification partnerships with emissions testing laboratories. For Investors and Strategic Acquirers: Consolidation pressure builds where narrow-cut distillation capability scarcity intersects with automotive OEM demand for guaranteed batch consistency. Long-term viability favors integrated refinery-chemical operators with proprietary alkylation technology positions and Yangtze River Delta or Yeosu industrial complex access. Signal to watch: MFDS-aligned enforcement accelerating laboratory-grade purity requirements across East Asian markets.| Strategic Initiative | Industry Significance |
|---|---|
| Solid Acid Catalyst Conversion | BP and UOP-licensed systems compress payback periods while displacing hazardous HF units. |
| Backward Integration into NGL Supply | Captive isobutane sourcing insulates Gulf Coast refiners from feedstock price volatility. |
| Dual Certification Investment | ASTM-EN documentation capabilities capture consolidated procurement at Stuttgart testing centers. |
| Ionic Liquid Technology Licensing | Process safety improvements unify with higher iso-octane yields in European capacity expansions. |
| Blockchain Traceability Implementation | Batch documentation transparency opens premium pricing for precision calibration applications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with refinery operations managers, automotive OEM fuel specialists, alkylation technology licensors, and laboratory procurement directors with secondary validation through customs trade data, American Chemistry Council reports, SEC refiner filings, and GB standards documentation. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates across purity tiers and regional production hubs.
Segment-weighting applied product type, application, end user, and distribution channel dimensions across the projection horizon, with purity-grade stratification and regional regulatory cluster alignment as industry-specific layers. CAGRs derived from capacity expansion announcements, alkylation unit utilization rates, and octane-premium capture trajectories. Forecast inputs incorporated acid-catalyst replacement cycle timing and automotive powertrain compression ratio roadmaps.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory acceleration in China or delayed CARB enforcement in California. Forecasts reflect documented assumptions regarding alkylation unit commissioning schedules and feedstock cost trajectories. Material deviation in GB 17930 implementation timelines or solid-acid technology adoption rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Saudi Arabia Chemical Logistics Market
Fuels
Charcoal Briquette Market
Fuels
Palm Methyl Ester Market
Fuels
China LNG Market
Fuels
White Coal Market
Fuels
Asia-Pacific Bunker Fuel Market
Fuels
High-Temperature Industrial Burner Market
Fuels
Europe Commercial Aircraft Aviation Fuel Market
Fuels
Middle-East and Africa Commercial Aircraft Aviation Fuel Market
Fuels
Tire Derived Fuel Market
Fuels
Middle East and Africa Compressed Natural Gas Dispenser Market
Fuels
India Coal Market
Fuels
Solid Recovered Fuel Market
Fuels
China LNG Bunkering Market
Fuels
Liquid Propellants Market
Fuels
Diesel As Fuel Market