
 LPG Tanker Market | 2026-2036
LPG Tanker Market Size, Share, and Industry Trends Forecast 2026-2036
LPG Tanker Market Intelligence
IMO 2020 is restructuring capital deployment across the LPG tanker orderbook as shipowners weigh scrubber retrofits against LNG dual-fuel newbuilds. BW LPG leverages its very large gas carrier fleet to sustain arbitrage-driven spot exposure between Middle Eastern export terminals and Asian discharge ports. Samsung Heavy Industries anchors South Korean shipyard competitiveness through automated panel-line welding systems purpose-built for cryogenic containment. Hyundai Heavy Industries differentiates via integrated engine-plant offerings that bundle low-pressure ME-GI dual-fuel engines with tanker hull designs.
An LPG tanker is a specialized marine vessel engineered to transport liquefied petroleum gas under refrigerated or pressurized conditions, typically employing nickel-steel alloy cargo containment systems rated for temperatures as low as minus 50 degrees Celsius and pressures up to 18 bar. The vessel's primary commercial function is to bridge geographically separated production and consumption nodes where pipeline infrastructure proves uneconomical or politically unviable. Spherical tank configurations dominate the very large gas carrier segment due to proven fatigue resistance and lower boil-off rates during extended voyages, while membrane designs gain share in mid-scale vessels where cargo cubic optimization drives charter economics. Automated loading systems represent the fastest-evolving dimension as terminal operators seek to reduce berthing windows and cut vapor recovery losses.
The International Maritime Organization enforces the IGC Code for gas carrier construction standards, while classification societies including DNV and Lloyd's Register administer material certification protocols that govern nickel-alloy steel procurement. The EU MRV and FuelEU Maritime frameworks will progressively tighten carbon intensity thresholds on vessels calling at European ports, redirecting investment toward hull air-lubrication and wind-assist technologies. Stakeholders must monitor the spread between newbuild contracting prices and secondhand asset values to time fleet renewal decisions before regulatory compliance costs widen the competitive gap between vintage and modern tonnage.
Market Dynamics
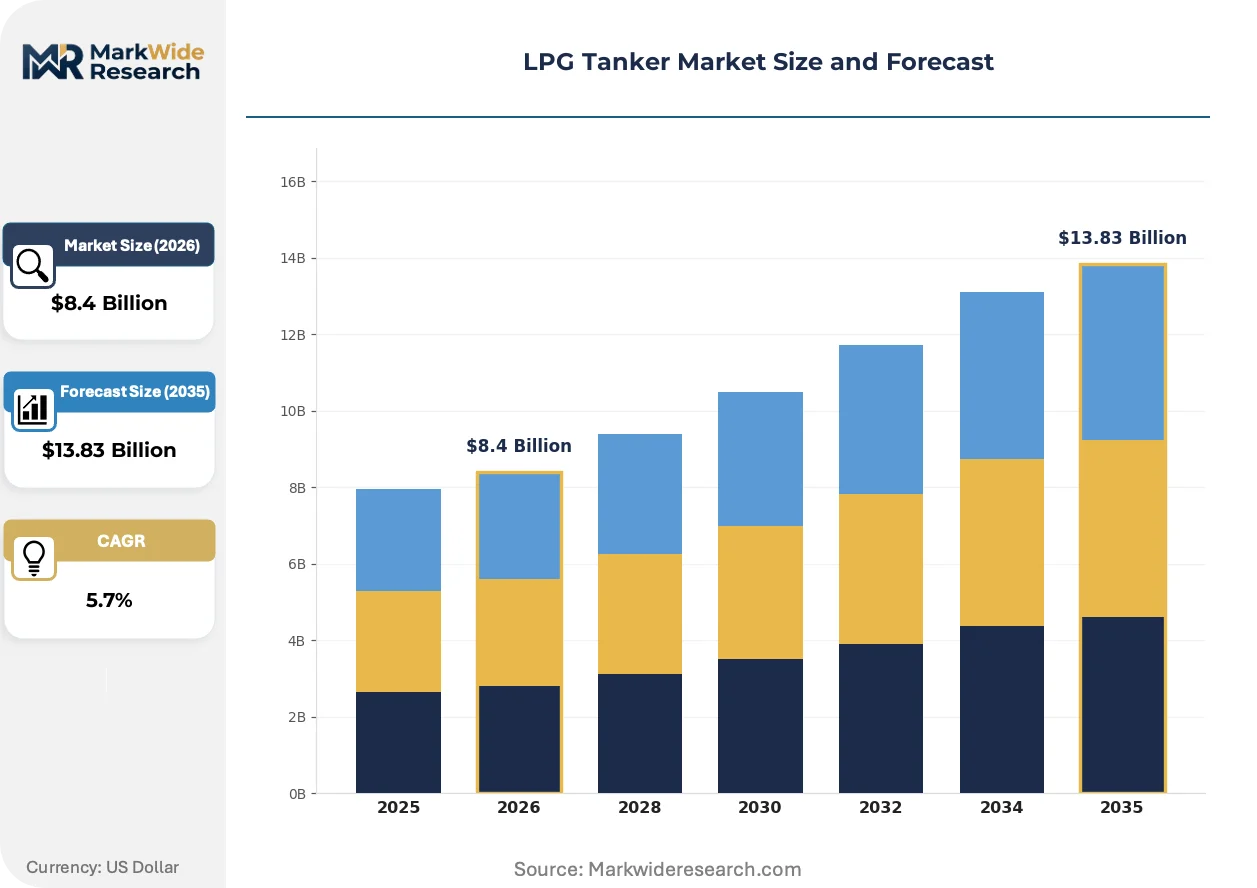
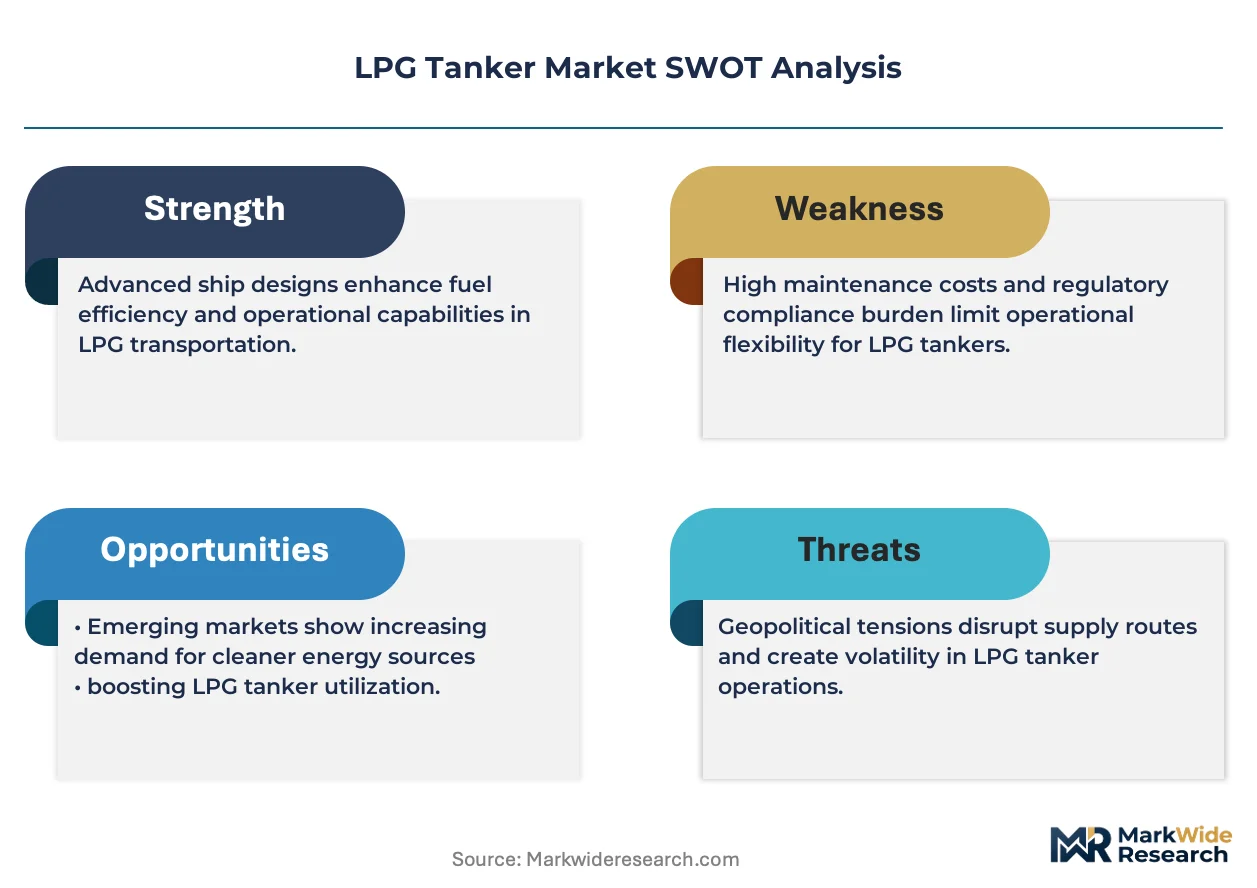
The LPG tanker sector is undergoing fleet renewal driven by the International Maritime Organization's sulfur cap and emerging carbon intensity regulations, forcing shipowners to choose between scrubber retrofits and dual-fuel propulsion investments before asset obsolescence widens.
Growth Catalysts
- Propane dehydrogenation expansion:Petrochemical producers across China and India are commissioning PDH plants that require dedicated marine feedstock delivery, tightening vessel utilization on Asia-Pacific trade routes.
- FuelEU Maritime compliance pathways:The European Union's carbon intensity thresholds are accelerating orders for LNG dual-fuel newbuilds with ME-GI engines that achieve Tier III NOx standards without exhaust after-treatment.
- City gas distribution mandates:India's Petroleum and Natural Gas Regulatory Board is enforcing residential LPG connection targets that require import terminal capacity expansion and corresponding tonnage deployment.
Market Restraints
- Nickel-alloy steel supply concentration:Cryogenic containment systems depend on Invar and 9% nickel steel production concentrated among Japanese and European specialty mills, creating procurement bottlenecks during fleet renewal cycles.
- Shipyard capacity constraints:South Korean builders Samsung Heavy Industries and Hyundai Heavy Industries dominate VLGC construction, limiting price competition and extending delivery schedules to 2027-2028 slots.
- Boil-off gas management limitations:Spherical tank designs achieve lower vaporization rates than membrane alternatives but sacrifice cargo cubic efficiency, constraining arbitrage economics on shorter-haul routes.
Strategic Opportunities
- Ammonia-ready vessel development:Classification societies DNV and Lloyd's Register are certifying tank designs capable of future ammonia fuel conversion, allowing shipowners to hedge against post-2030 fuel pathway uncertainty.
- Automated terminal interface systems:Mooring automation and vapor recovery integration at Middle Eastern export terminals are reducing berth occupancy from 36 hours to under 18 hours, improving vessel turnaround economics.
- Wind-assist propulsion retrofit:Rotor sail and kite systems are gaining regulatory approval under EU MRV emission accounting frameworks, offering compliance credits for existing tonnage without engine replacement.
Industry Challenges
- Cryogenic welding certification scarcity:Shipyards face shortages of qualified technicians certified to IGC Code standards for nickel-alloy joining procedures, extending construction timelines and quality control costs.
- Dual-fuel engine commissioning complexity:Low-pressure gas injection systems require specialized vendor oversight during sea trials, creating coordination friction between hull builders and engine-plant suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LPG Tanker Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Membrane, Spherical, Pressurized, Semi-membrane Loading Method: Top Loading, Bottom Loading, Manual Loading, Automated Loading End User: Shipping Companies, Oil & Gas Companies, Freight Forwarders, Logistics Providers Capacity: Small Scale, Medium Scale, Large Scale, Extra Large |
| Companies Covered | Mitsubishi Heavy Industries, Kawasaki Heavy Industries, BW LPG, EXMAR, Samsung Heavy Industries, Dorian LPG Ltd., Mitsui OSK Lines, Great Eastern Shipping, Hyundai Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LPG Tanker Market Strategic Shifts & Innovations
Fleet modernization is converging around three vectors: propulsion technology substitution, regulatory compliance architecture, and terminal automation integration that collectively redefine capital deployment and operational economics.
Membrane containment systems are integrating composite insulation layers that reduce heat ingress by 15% compared to conventional perlite powder designs. Korean shipyards are specifying these for mid-scale vessels where cargo volume optimization outweighs the fatigue resistance advantages of spherical tanks. This technology is integrating with hull air-lubrication systems to compound fuel efficiency gains on long-haul Middle East-to-Asia routes.
EU MRV and FuelEU Maritime frameworks are tightening carbon intensity thresholds on vessels calling at Rotterdam, Antwerp, and Hamburg. Shipowners must document well-to-wake emissions or face port access restrictions and fuel cost penalties starting 2025. The VLGC segment is responding with engine-plant upgrades and operational speed optimization to maintain charter competitiveness in European discharge markets.
Charterers are consolidating procurement around term contracts with embedded carbon accounting clauses that transfer compliance liability to vessel operators. Spot market exposure is compressing as Indian city gas distributors and Chinese petrochemical majors seek supply security through multi-year fixtures. This behavioral shift is most pronounced in the China-to-India lane where discharge port congestion and inventory management complexity favor committed tonnage over voyage charter flexibility.
LPG Tanker Market Segmentation
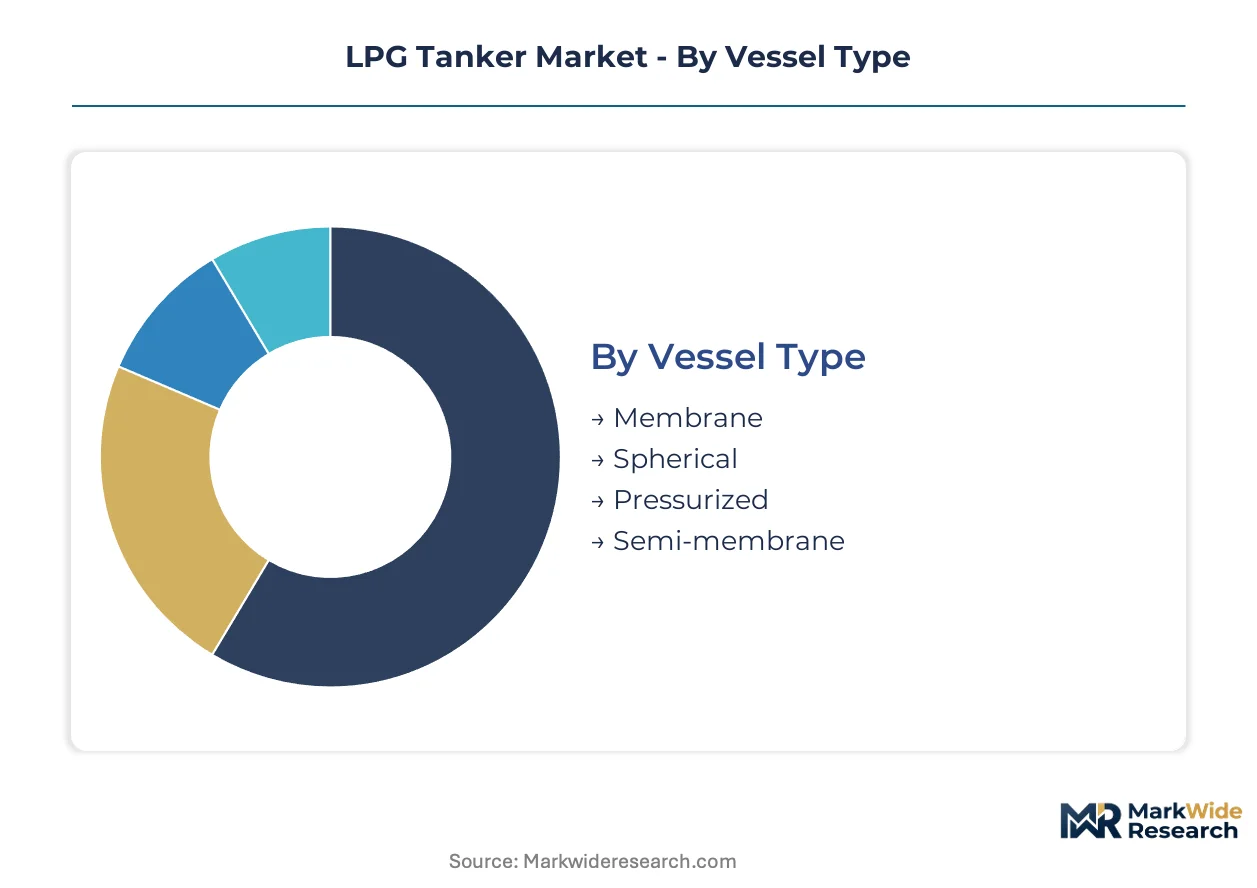
LPG tanker segmentation governs capital deployment decisions across shipyards, charterers, and terminal operators. Vessel configuration determines containment technology costs, while loading automation and capacity scaling reshape operational economics on high-volume Asia-Pacific trade lanes.
Vessel Type:
Capital intensity peaks with cryogenic containment systems requiring nickel-alloy steel and specialized welding certification.
- Spherical:Spherical tanks employ Invar or 9% nickel steel alloy shells with proven fatigue resistance across 25-year service lives. Demand concentrates in very large gas carrier newbuilds serving Middle East-to-India routes where boil-off gas minimization protects cargo volume on 21-day voyages. Samsung Heavy Industries and Hyundai Heavy Industries dominate construction of these units due to cryogenic welding capacity constraints at competing yards.
- Membrane:Membrane systems utilize composite insulation layers and corrugated stainless steel barriers that optimize cargo cubic efficiency. Chinese petrochemical terminals are driving orders for mid-scale membrane vessels where discharge port draft limitations favor dimensional flexibility over spherical tank structural margins.
- Pressurized:Pressurized designs operate at ambient temperature with cylindrical or bilobe tanks rated to 18 bar, serving short-haul coastal distribution.
- Semi-membrane:Semi-membrane configurations blend membrane cargo barriers with partial structural independence for intermediate scale applications.
Most installed capacity flows through Spherical designs. Expansion is steepest in Membrane systems gaining share in mid-scale vessel contracting.
Loading Method:
Terminal interface technology determines berth occupancy economics and vapor recovery compliance across discharge ports.
- Automated Loading:Automated systems integrate mooring automation, vapor recovery, and flow control to compress berthing windows. Middle Eastern export terminals at Ras Laffan and Jubail are mandating these interfaces to cut vessel turnaround from 36 hours below 18 hours, improving terminal throughput without jetty expansion.
- Top Loading:Top loading employs marine loading arms with vapor return lines for cryogenic cargo transfer. Indian import terminals at Hazira and Mundra are retrofitting top loading infrastructure to handle rising city gas distribution volumes, though berthing constraints persist during monsoon season.
- Bottom Loading:Bottom loading configurations utilize submerged cargo pumps for reduced vapor generation during transfer operations.
- Manual Loading:Manual systems persist at smaller coastal facilities with limited capital budgets and lower throughput requirements.
Automated Loading commands premium charter rates for vessels so equipped. Top Loading retains the largest installed base across existing terminal infrastructure.
End User:
Procurement authority concentrates with integrated energy majors and specialized shipping companies controlling fleet deployment decisions.
- Shipping Companies:Independent owners and operator pools manage vessel employment across spot and term charter markets. BW LPG and Avance Gas are consolidating procurement around multi-year fixtures with embedded carbon accounting clauses, transferring FuelEU Maritime compliance liability to vessel operators serving European discharge markets.
- Oil & Gas Companies:Integrated majors and national oil companies charter captive tonnage for feedstock supply security. Reliance Industries and Indian Oil Corporation are contracting dedicated VLGC fleets to supply propane dehydrogenation plants and city gas distribution networks, compressing spot market exposure on the China-to-India lane.
- Freight Forwarders:Forwarders aggregate smaller parcel shipments and coordinate multimodal LPG logistics for regional distributors.
- Logistics Providers:Third-party logistics firms manage inventory positioning and terminal coordination for import-dependent end-users.
Shipping Companies control the dominant share of vessel operating days. Oil & Gas Companies are expanding fastest as vertical integration into marine logistics deepens.
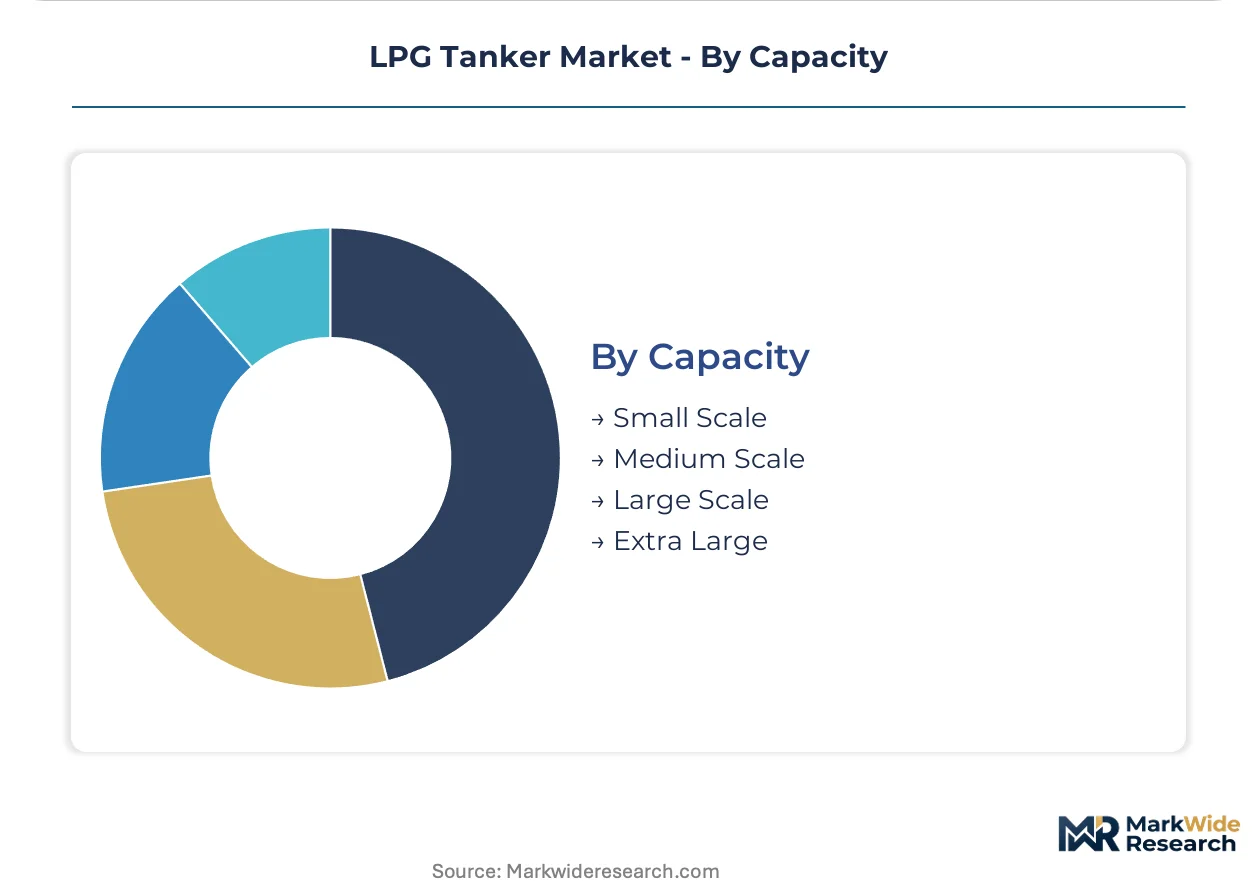
Capacity:
Scale economics and trade lane characteristics segment procurement across vessel size classes.
- Extra Large:Very large gas carriers exceed 80,000 cubic meters and dominate long-haul Middle East-to-Asia routes. South Korean shipyards are fully booked on Extra Large newbuilds through 2027-2028 delivery slots as Indian city gas distribution mandates and Chinese PDH expansion tighten vessel availability.
- Large Scale:Large vessels in the 60,000-80,000 cubic meter range serve secondary export terminals with draft or jetty length constraints. Southeast Asian import terminals at Map Ta Phut and Singapore are driving demand for this class where full VLGC dimensions exceed port infrastructure.
- Medium Scale:Medium vessels serve intra-regional trades and coastal distribution networks with flexible port access.
- Small Scale:Small vessels below 25,000 cubic meters handle short-haul coastal and island supply logistics.
Extra Large vessels carry the majority of seaborne LPG tonnage. Large Scale contracting is climbing fastest as secondary port infrastructure expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The LPG tanker industry traces its modern scaling to Japanese shipyards in the 1960s, where Mitsubishi Heavy Industries and Kawasaki Heavy Industries pioneered cryogenic containment for Middle East export cargoes. South Korean builders later captured VLGC construction dominance through automated welding investments. Today's fleet deployment centers on Asian import demand corridors.
China
Zhejiang Satellite Petrochemical and Hengli Petrochemical are commissioning propane dehydrogenation plants requiring dedicated marine feedstock delivery. MIIT's dual carbon goals are tightening vessel emission standards for domestic trade. Ningbo-Zhoushan port anchors VLGC discharge operations where terminal operators are retrofitting automated mooring systems.
India
Reliance Industries and Indian Oil Corporation are expanding city gas distribution networks driving import terminal capacity additions. The Petroleum and Natural Gas Regulatory Board enforces residential LPG connection targets under the Pradhan Mantri Ujjwala Yojana program. Hazira and Mundra terminals on the Gujarat coast are handling rising VLGC call volumes during monsoon-constrained berthing windows.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries hold fully booked VLGC orderbooks through 2027-2028 delivery slots. The Ministry of Trade, Industry and Energy supports shipyard competitiveness through automated panel-line welding investments. Geoje and Ulsan industrial clusters concentrate cryogenic welding certification capacity for nickel-alloy construction.
Japan
Mitsubishi Heavy Industries and Kawasaki Heavy Industries retain specialized competence in spherical tank containment systems. METI's maritime decarbonization roadmap is accelerating dual-fuel engine adoption in domestic fleet renewal. Nagasaki and Kobe shipyards maintain legacy cryogenic construction expertise for niche vessel specifications.
United States
Enterprise Product Partners and Targa Resources are expanding LPG export terminal capacity on the Gulf Coast. The EPA's marine diesel fuel sulfur regulations align with IMO 2020 compliance pathways. Houston Ship Channel infrastructure is handling rising VLGC loadings for Asia-Pacific discharge markets.
LPG Tanker Market Key Industry Players
The competitive structure tilts toward shipyard-led consolidation with Korean and Japanese builders controlling VLGC construction capacity. Tiered segmentation separates integrated energy majors with captive tonnage from independent vessel operators managing spot market exposure. Two dominant competitive moves are emerging: backward integration into terminal infrastructure by charterers, and technology licensing partnerships between engine suppliers and hull designers.
Among Korean shipyard specialists, Samsung Heavy Industries and Hyundai Heavy Industries occupy positions at the scale-driven end of VLGC construction. BW LPG exemplifies the independent operator archetype managing fleet employment across term and spot charter markets. These three entities anchor the competitive spectrum from asset production through vessel operation.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries |
| Kawasaki Heavy Industries |
| BW LPG |
| EXMAR |
| Samsung Heavy Industries |
| Dorian LPG Ltd. |
| Mitsui OSK Lines |
| Great Eastern Shipping |
| Hyundai Heavy Industries |
| Others |
Cost & Logistics Intelligence
Indian city gas distribution operators concentrate procurement authority through multi-year term fixtures, anchoring a contract-based pricing structure that transfers FuelEU Maritime compliance liability to vessel operators serving European discharge markets. This buyer concentration enables shipping companies to command rate premiums for dual-fuel tonnage while compressing spot market exposure.
Pricing Analysis
Three-tier pricing structure across ammonia-ready newbuilds, LNG dual-fuel vessels, and conventional scrubber-fitted tonnage governs charter rate differentiation. Price differentiation rests on IMO Tier III NOx certification and embedded carbon accounting capability. Cost compression in the conventional tier is intensifying because shipowners face stranded asset risk from EU MRV thresholds. Indian petrochemical majors demonstrate highest price sensitivity due to PDH plant feedstock cost exposure, while European charterers accept premium rates for compliance-credit-eligible vessels.
Supply Chain Analysis
Direct-to-shipyard contracting channels handle VLGC newbuild demand from integrated energy majors and independent fleet operators. Geographic supply concentrates in South Korea, Japan, and China where cryogenic welding certification capacity anchors construction. Nickel-alloy steel procurement draws from Japanese and European specialty mills, creating single-source vulnerability during fleet renewal cycles. Distribution runs through captive terminal infrastructure at Middle Eastern export hubs and Asian discharge ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as charter procurement consolidates around ammonia-ready vessel specifications that hedge against post-2030 fuel pathway uncertainty.
For Market Incumbents: To counter shipyard capacity constraints extending delivery schedules, secure 2027-2028 construction slots through advance contracting with Hyundai Heavy Industries and Samsung Heavy Industries. Prioritize IGC Code welding certification investments to differentiate construction quality during yard selection. Backward integration into terminal infrastructure at Hazira and Mundra captures port congestion premiums. For New Entrants and Emerging Players: Regional Indian city gas distributors represent an underserved buyer archetype seeking committed tonnage for Ujjwala program residential connection targets. Southeast Asian secondary terminals at Map Ta Phut offer penetrable infrastructure where VLGC dimensions exceed draft constraints. Partner with classification societies DNV or Lloyd's Register for ammonia-ready design certification to accelerate market entry. For Investors and Strategic Acquirers: Integrated energy majors with captive petrochemical feedstock demand are the most active acquirers in this space, seeking fleet control for PDH plant supply security. Target independent operators with term charter backlogs and dual-fuel engine installations. Monitor the spread between newbuild contracting prices and secondhand asset values as the inflection indicator for fleet renewal timing.| Strategic Initiative | Industry Significance |
|---|---|
| Ammonia-Ready Vessel Development | DNV and Lloyd's Register certification hedges against post-2030 fuel pathway uncertainty for shipowners. |
| Automated Terminal Interface Deployment | Ras Laffan and Jubail terminal operators compress berthing windows below 18 hours without jetty expansion. |
| Dual-Fuel Engine Plant Integration | Hyundai Heavy Industries bundles ME-GI engines with hull designs to streamline construction coordination. |
| Wind-Assist Propulsion Retrofit | Rotor sail systems gain EU MRV emission accounting credits for existing tonnage compliance. |
| Cryogenic Welding Certification Investment | South Korean shipyards automate panel-line systems to address IGC Code technician scarcity. |
Research Approach
Direct dialogue with VLGC fleet managers, shipyard procurement executives, terminal operators at Middle Eastern export hubs, and classification society surveyors grounded qualitative assessment in operational reality. Secondary validation drew from Lloyd's Register vessel data, IGC Code construction standards, EU MRV emission disclosures, and customs trade records. Bottom-up vessel deployment modeling triangulated against top-down trade flow analysis across the analysis window.
Segment-level value outputs derived from capacity deployment by vessel type, containment technology, propulsion architecture, and regional trade lane intensity. CAGRs were computed from contracted newbuild deliveries and terminal capacity expansion schedules. Forecast inputs incorporated PDH plant commissioning timelines, city gas distribution connection mandates, and FuelEU Maritime compliance pathway adoption rates.
Underlying measurement precision varies by segment; spherical VLGC newbuild contracting carries tighter precision than pressurized coastal vessel estimates. Forecasts reflect assumptions regarding nickel-alloy steel procurement continuity and shipyard delivery schedule adherence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Oil Dispensing Stations Market
Fuels
Global Steam Coal Market
Fuels
Ethyl Tertiary Butyl Ether Market
Fuels
Pyrolysis Gas Market
Fuels
Mobile Fuel Delivery Market
Fuels
India LNG Market
Fuels
Global Turbine Oil Market
Fuels
Global Methane Hydrate Market
Fuels
China LNG Bunkering Market
Fuels
Europe Wood Pellet Market
Fuels
China LNG Market
Fuels
LPG Vaporizer Market
Fuels
India City Gas Distribution (CGD) Market
Fuels
Tire Derived Fuel Market
Fuels
Fuel Conditioning System Market
Fuels
South America Commercial Aircraft Aviation Fuel Market