
 Explosion Vents Market | 2026-2036
Explosion Vents Market Size, Share, and Industry Trends Forecast 2026-2036
Explosion Vents Market Analytics
Capital-intensity divergence between integrated manufacturers and assembly-focused suppliers is bifurcating competitive tiers in the explosion vents landscape. REMBE GmbH leverages captive metallurgical testing and in-house rupture disc fabrication to sustain premium positioning across European chemical clusters. Fike Corporation anchors North American demand through NFPA-aligned distribution networks and localized burst-test calibration facilities. ZOOK Enterprises differentiates via specialized alloy formulations for high-temperature hydrogen venting applications.
Explosion vents are pressure-activated safety devices engineered from stainless steel, nickel alloys, or composite laminates that rupture at precisely calibrated burst pressures to vent deflagration or detonation energy away from personnel and equipment. These devices typically operate within milliseconds at pressures ranging from inches of water column to hundreds of psig, protecting vessels, ducts, and enclosures across process industries. Rupture panels dominate volume demand in mature chemical processing installations where replacement cycles drive recurring revenue, while detonation vents capture expanding margin pools in hydrogen energy and battery manufacturing facilities requiring multi-phase flame isolation. Wall-mounted configurations lead installation-method segmentation due to retrofit compatibility with existing vessel geometries, though roof-mounted demand accelerates in greenfield pharmaceutical cleanroom construction.
OSHA Process Safety Management standards and EPA Risk Management Program rules mandate documented overpressure protection for facilities handling regulated substances above threshold quantities in the United States. ATEX Directive 2014/34/EU and IEC 60079 explosion protection standards govern product certification and market access across European industrial zones, compelling manufacturers to maintain dual compliance architectures. Stakeholders must monitor evolving hydrogen-specific venting protocols as energy transition infrastructure scales, since existing NFPA 68 and EN 14491 frameworks face pressure-test gaps at cryogenic and ultra-high-pressure operating regimes.
Market Dynamics
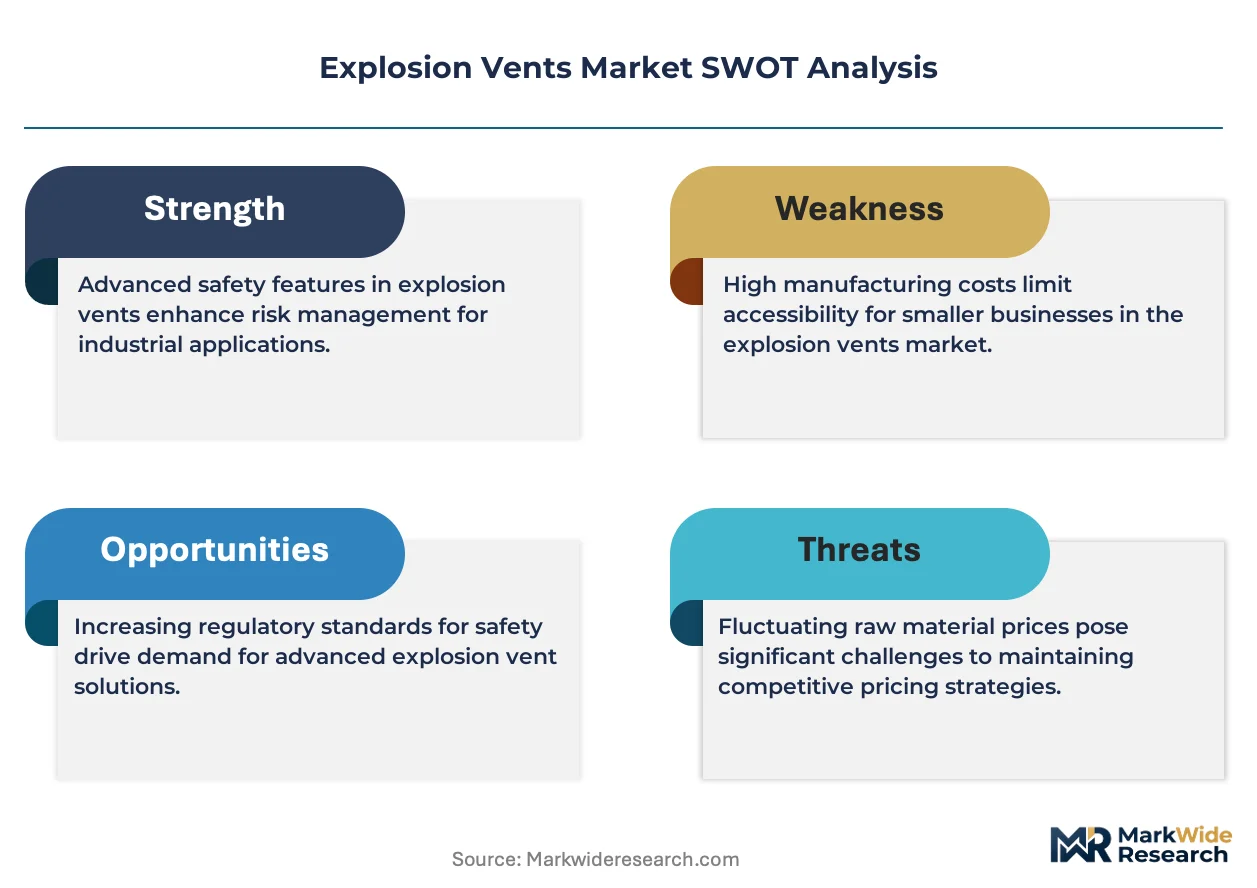
Stricter OSHA Process Safety Management enforcement and EU Pressure Equipment Directive compliance deadlines are accelerating replacement cycles for aging rupture disc installations across petrochemical corridors.
Growth Catalysts
- OSHA PSM mandate expansion:US facilities handling threshold quantities of regulated substances must document overpressure protection upgrades, driving systematic vent replacement programs.
- Hydrogen infrastructure buildout:Cryogenic and high-pressure hydrogen storage projects require ATEX-certified detonation vents with specialized alloy formulations for flame isolation.
- Battery manufacturing scale-up:Lithium-ion cell production facilities need multi-phase explosion protection for electrode coating and electrolyte handling operations.
Market Restraints
- Nickel alloy supply concentration:Inconel and Hastelloy sourcing depends on a limited set of specialty metallurgical suppliers, creating input cost volatility.
- Dual compliance architecture burden:Manufacturers serving both US and EU markets must maintain parallel NFPA 68 and EN 14491 certification tracks.
- Extended burst-test calibration cycles:Precision validation requirements stretch lead times for custom rupture pressure specifications.
Strategic Opportunities
- Greenfield pharmaceutical cleanrooms:Roof-mounted explosion vent demand accelerates in sterile manufacturing construction requiring contamination-resistant pressure relief.
- Retrofit compatibility services:Wall-mounted configuration expertise opens recurring revenue streams in mature chemical processing installations.
- IEC 60079 standard harmonization:Emerging market regulators are adopting EU-aligned certification frameworks, reducing market entry friction.
Industry Challenges
- Qualified rupture disc engineer scarcity:Specialized metallurgical testing and burst-pressure calculation expertise concentrates among aging technician cohorts.
- Legacy vessel integration complexity:Existing duct geometries and nozzle configurations constrain standardized vent sizing options.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Explosion Vents Market |
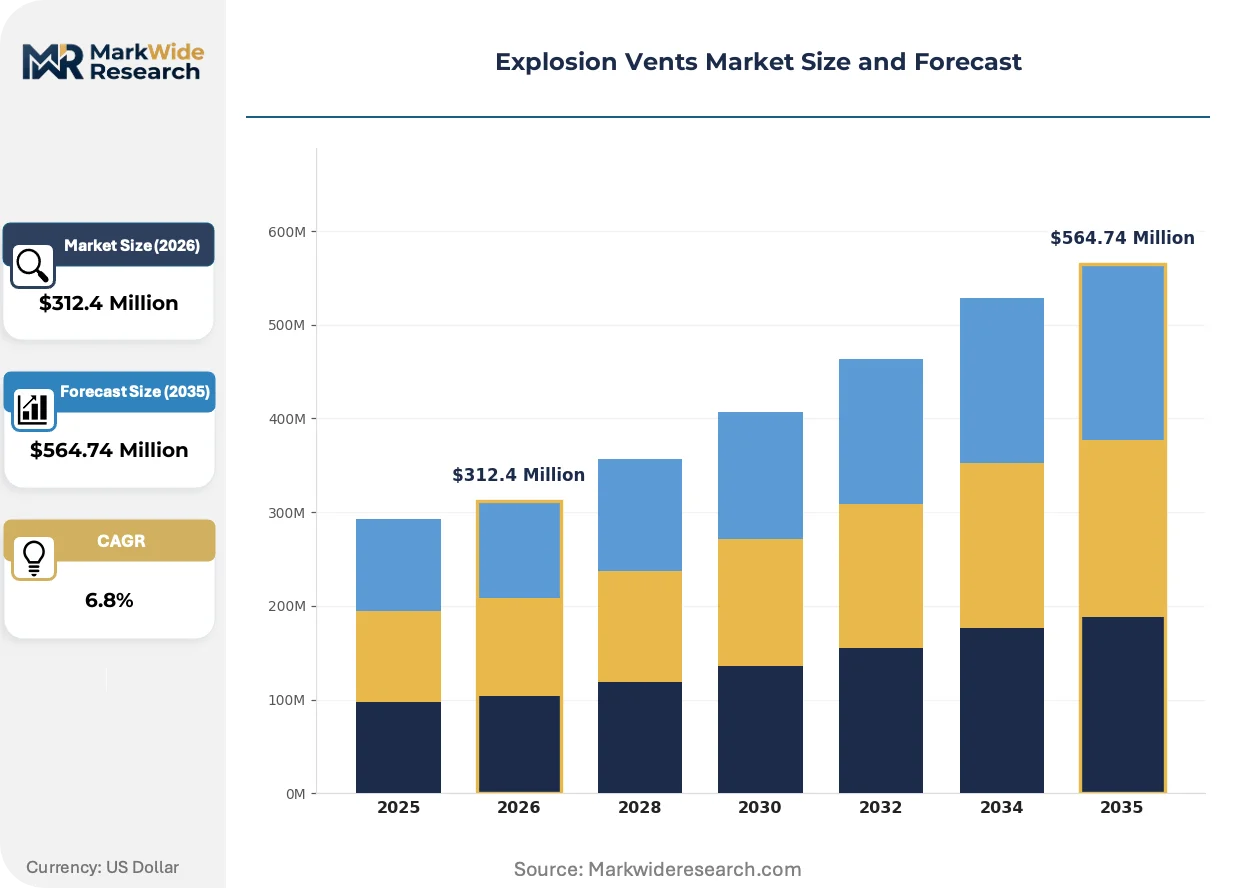
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flame Arrestors, Rupture Panels, Pressure Relief Vents, Detonation Vents Industry Vertical: Oil & Gas, Chemical Processing, Pharmaceuticals, Manufacturing Installation Method: Wall-Mounted, Roof-Mounted, Ceiling-Mounted, Floor-Mounted Standards Compliance: ATEX, NFPA, IS, IEC |
| Companies Covered | Fike Corporation, ZOOK Enterprises, Elfab Ltd, BS&B Safety Systems, REMBE GmbH, IEP Technologies, VIGILEX, CV Technology, Construction Specialties, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Explosion Vents Market Evolving Landscape
Material science advances and digital monitoring integration are redefining performance benchmarks for pressure-activated safety devices across process industries.
Composite laminate rupture panels incorporating graphite and fluoropolymer interlayers is bifurcating product tiers in chemical processing applications. Hydrogen sulfide service operators in Gulf Coast refineries are specifying these formulations for corrosion resistance. The technology is bifurcating procurement patterns between premium-specified new builds and commodity replacement cycles.
EPA Risk Management Program amendments are tightening consequence analysis requirements for stationary source facilities. Covered processes must now model alternative release scenarios with greater granularity. Pharmaceutical manufacturers in Puerto Rico and New Jersey are responding with third-party vent sizing validation services.
Specification authority is migrating from maintenance departments to centralized engineering procurement functions. Integrated EPC firms now bundle explosion protection into lump-sum construction contracts. This concentration is most visible in German chemical cluster expansions along the Rhine corridor.
Explosion Vents Market Segmentation
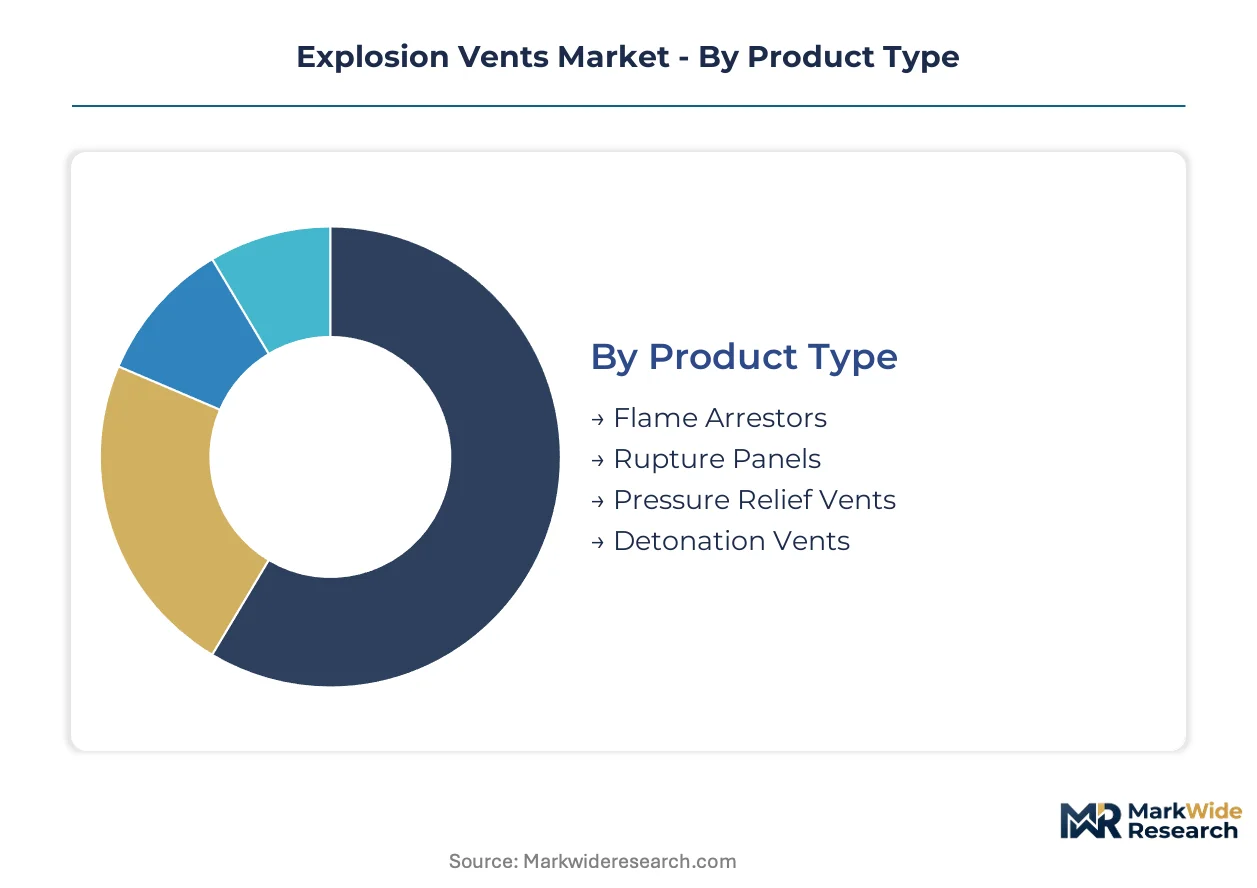
Explosion vent procurement patterns diverge sharply across product architectures and installation constraints. Specification authority concentrates in engineering procurement functions that bundle safety systems into lump-sum construction contracts, compressing vendor selection windows and elevating certification requirements.
Product Type:
Domestic fabrication dominates rupture panel supply chains in Germany and the US, while detonation vent production serves export markets from specialized alloy foundries in Japan and South Korea.
- Rupture Panels:Precision-calibrated metal discs of stainless steel or nickel alloy rupture at predetermined pressures to isolate deflagration events. Demand concentrates in US Gulf Coast petrochemical corridors and German Rhine chemical clusters where OSHA PSM and EU Pressure Equipment Directive mandates drive systematic replacement programs.
- Detonation Vents:Multi-phase flame isolation devices engineered with specialized Inconel or Hastelloy formulations for high-velocity combustion events. Hydrogen storage projects in Texas and Louisiana specify these for cryogenic and ultra-high-pressure operating regimes beyond standard NFPA 68 coverage.
- Flame Arrestors:Passive devices with crimped metal or ceramic matrices that quench flame fronts in vapor handling systems.
- Pressure Relief Vents:Reusable spring-loaded or pilot-operated valves for non-explosive overpressure protection in process vessels.
Rupture panels command the established base. The steepest expansion runs through detonation vents.
Industry Vertical:
Cost-tier stratification separates premium-specified new builds from commodity replacement cycles, with pharmaceutical and hydrogen applications commanding alloy premiums.
- Chemical Processing:ATEX-certified rupture disc installations dominate procurement volumes in mature European and North American facilities. German chemical plants along the Rhine corridor and US Gulf Coast refineries drive recurring revenue through mandated replacement cycles under tightening OSHA and EU enforcement.
- Oil & Gas:Hydrogen sulfide service operators in Louisiana and Texas refineries specify composite laminate rupture panels with graphite interlayers for corrosion resistance.
- Pharmaceuticals:Sterile manufacturing construction in Puerto Rico and New Jersey requires contamination-resistant roof-mounted configurations.
- Manufacturing:Battery cell production facilities for lithium-ion electrode coating need multi-phase explosion protection.
Chemical processing anchors volume demand. Battery manufacturing climbs the fastest.
Installation Method:
Retrofit compatibility constraints favor wall-mounted geometries in mature installations, while greenfield construction opens specification latitude.
- Wall-Mounted:Dominant configuration for existing vessel retrofits where duct geometries and nozzle positions constrain design options. Mature chemical processing plants in Germany and the US specify these for replacement cycles without structural modification.
- Roof-Mounted:Preferred in pharmaceutical cleanroom construction where contamination control protocols require upward venting away from personnel zones.
- Ceiling-Mounted:Specialized applications in confined equipment enclosures with vertical space constraints.
- Floor-Mounted:Underground storage and bunker applications with downward pressure relief paths.
Wall-mounted configurations hold the installed base. Roof-mounted demand gains share fastest.
Standards Compliance:
Dual certification architectures burden manufacturers serving transatlantic markets, with harmonization pressures emerging in Asian regulatory adoption.
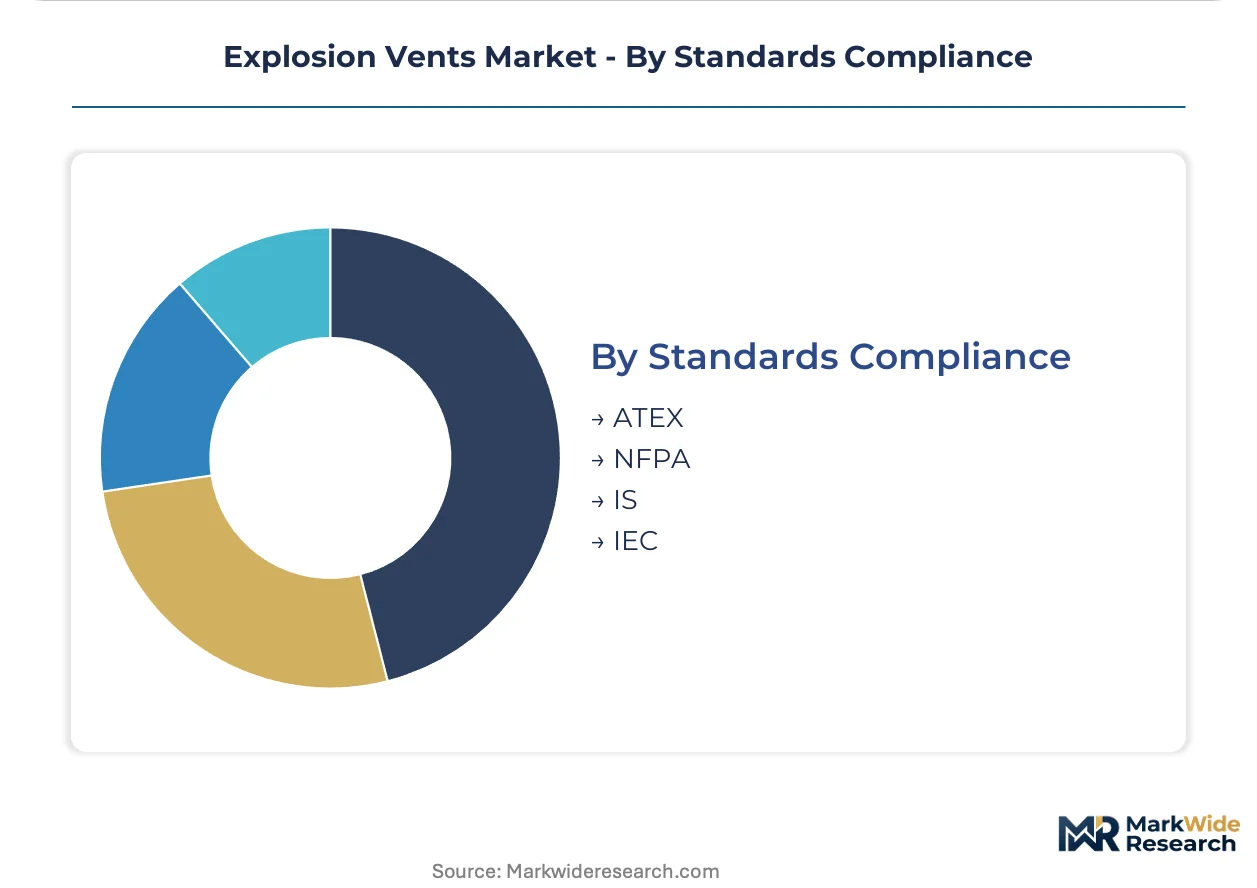
- ATEX:EU Directive 2014/34/EU certification mandatory for explosion protection equipment in European industrial zones. German chemical cluster expansions require documented compliance for market access.
- NFPA:US National Fire Protection Association standards govern deflagration venting design in petrochemical and pharmaceutical facilities. OSHA cross-references NFPA 68 in Process Safety Management enforcement.
- IEC:IEC 60079 explosion protection standards provide technical foundation for ATEX compliance and are being adopted by regulators in South Korea and Singapore to reduce market entry friction.
- IS:Indian Standards certification for domestic market access in process industries under Bureau of Indian Safety oversight.
ATEX and NFPA dominate specification authority. IEC-aligned frameworks expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States demonstrate low price elasticity as regulatory compliance mandates override cost considerations, while procurement teams in India and Southeast Asia exhibit higher sensitivity to unit pricing and local fabrication alternatives.
United States
Gulf Coast petrochemical corridor expansions and hydrogen storage projects drive specification of ATEX-certified detonation vents. OSHA Process Safety Management enforcement mandates documented overpressure protection upgrades for facilities handling threshold quantities of regulated substances. Louisiana and Texas refineries specify composite laminate rupture panels with graphite interlayers for hydrogen sulfide service corrosion resistance.
Germany
Rhine chemical cluster expansions concentrate procurement of precision-calibrated rupture discs for mature processing installations. EU Pressure Equipment Directive compliance deadlines accelerate systematic replacement cycles across BASF and Bayer facility networks. Bavarian and North Rhine-Westphalian industrial zones anchor premium-tier demand for in-house metallurgical testing and burst-test calibration capabilities.
China
Battery manufacturing scale-up for lithium-ion electrode coating operations requires multi-phase explosion protection systems. GB standards and emerging IEC 60079 adoption create regulatory alignment pressure for export-oriented fabricators. Yangtze River Delta chemical processing zones drive volume procurement of wall-mounted configurations for retrofit compatibility with existing vessel geometries.
India
Pharmaceutical manufacturing investments in Maharashtra and Gujarat generate demand for contamination-resistant roof-mounted venting in sterile construction. Bureau of Indian Safety oversight and evolving national standards create certification pathway uncertainty for imported equipment. Mumbai-Pune industrial corridor procurement teams prioritize cost-optimized wall-mounted configurations for brownfield chemical processing retrofits.
Japan
Specialized alloy foundries in Osaka and Nagoya supply high-temperature hydrogen venting components for export markets. METI industrial safety guidelines and JIS standards alignment with IEC frameworks reduce technical barriers for domestic manufacturers. Kyushu chemical processing facilities specify precision rupture panels for replacement cycles in mature ethylene and propylene production installations.
Explosion Vents Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the explosion vents landscape. Integrated manufacturers with captive metallurgical testing capabilities command premium positioning in European chemical clusters, while assembly-focused suppliers compete on lead time compression and standardized catalog offerings. Three archetypes dominate: vertically integrated specialists controlling alloy formulation and burst-test calibration; regional fabricators serving domestic procurement with NFPA or ATEX-aligned distribution; and diversified industrial safety conglomerates bundling explosion protection into broader process safety portfolios. Competitive moves concentrate on geographic expansion through localized certification facilities and portfolio diversification into hydrogen-specific venting protocols.
Within the integrated specialist tier, REMBE GmbH and Fike Corporation exemplify divergent regional anchoring strategies. REMBE occupies a position representing German chemical cluster proximity with in-house rupture disc fabrication capabilities. Fike exemplifies North American market presence through NFPA-aligned distribution network density. ZOOK Enterprises sits within the specialized alloy formulation segment, representing positioning around high-temperature hydrogen applications. These three anchors demonstrate how technology depth and geographic certification density separate competitive tiers rather than scale alone.
| Leading Market Players |
|---|
| Fike Corporation |
| ZOOK Enterprises |
| Elfab Ltd |
| BS&B Safety Systems |
| REMBE GmbH |
| IEP Technologies |
| VIGILEX |
| CV Technology |
| Construction Specialties |
| Others |
Value Network & Pricing Analysis
Composite laminate formulations displacing solid nickel alloy rupture panels are redrawing procurement geography toward Japanese and South Korean specialty foundries while compressing margin structures for legacy stainless steel fabricators in Germany and the United States.
Pricing Analysis
After-market rupture disc replacement programs generate recurring lifetime value that exceeds initial equipment sales by substantial multiples. Three-tier pricing structure across premium, standard, and economy levels separates ATEX-certified detonation vents with Inconel formulations from commodity stainless steel panels and unbranded regional alternatives. Pricing pressure stems from qualified rupture disc engineer scarcity stretching calibration lead times and forcing expedite premiums. Chemical processing procurement teams in the US Gulf Coast demonstrate lowest price sensitivity due to OSHA PSM compliance mandates, while Indian pharmaceutical brownfield retrofits exhibit highest elasticity.
Supply Chain Analysis
Nickel alloy concentrate refining in Indonesia and the Philippines underwrites specialty metallurgical supply for explosion vent fabricators worldwide. Inconel and Hastelloy sourcing draws from limited specialty alloy foundries concentrated in Japan, Germany, and the United States, with graphite interlayer composites increasingly sourced from South Korean laminate specialists. Single-source vulnerability concentrates in cryogenic hydrogen service formulations where only three certified suppliers maintain ATEX-qualified burst-test facilities. Distribution runs through NFPA-aligned technical distributors in North America and engineering-procurement-construction bundlers in European chemical cluster expansions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Explosion vent procurement fragmentation creates niche openings as specification authority migrates from plant maintenance departments to centralized EPC engineering functions, splintering vendor selection criteria across certification depth, lead time compression, and retrofit compatibility expertise.
For Market Incumbents: Shield premium positioning in hydrogen infrastructure by deepening captive metallurgical testing capabilities and securing early-mover ATEX certification for cryogenic pressure regimes. Defend against assembly-focused challengers through burst-test calibration facility expansion in Louisiana and Texas to compress lead times for Gulf Coast petrochemical replacement cycles. Prioritize backward integration into graphite-fluoropolymer composite laminate supply as hydrogen sulfide service specifications accelerate. For New Entrants and Emerging Players: Retrofit engineering services for legacy vessel geometries represent the most penetrable white-space where integrated manufacturers under-serve due to project-scale fragmentation. Target wall-mounted configuration expertise in mature German and US chemical processing installations where duct geometry constraints demand custom sizing validation. Pursue third-party vent sizing validation partnerships with pharmaceutical manufacturers in Puerto Rico responding to EPA Risk Management Program amendment requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional fabricators holding NFPA-aligned distribution networks in North American petrochemical corridors. Five-to-ten year viability hinges on hydrogen-specific venting protocol development capabilities as energy transition infrastructure scales. Monitor IEC 60079 adoption trajectories in South Korea and Singapore as the signal for reduced market entry friction enabling geographic expansion returns.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Specific Venting Protocol Development | Early ATEX certification for cryogenic regimes captures Texas and Louisiana storage project specifications. |
| Backward Integration into Composite Laminate Supply | Captive graphite-fluoropolymer interlayer production defends margin against nickel alloy volatility. |
| Burst-Test Calibration Facility Expansion | Localized validation capacity in Gulf Coast corridor compresses lead times for OSHA-mandated replacements. |
| Third-Party Sizing Validation Services | EPA RMP amendment response opens recurring revenue from pharmaceutical manufacturers in New Jersey. |
| IEC 60079 Certification Pre-Positioning | Regulatory alignment in South Korea and Singapore reduces friction for Asian market entry. |
Research Methodology
Operator-level perspectives from plant engineers, maintenance directors at petrochemical facilities, EPC procurement leads, and aftermarket service managers anchored the qualitative base for this analysis. Primary field engagement combined with secondary validation drawing from OSHA enforcement databases, EU Pressure Equipment Directive implementation reports, SEC filings of listed industrial safety conglomerates, and customs trade data for nickel alloy and specialty steel imports. Bottom-up rupture panel and detonation vent shipment estimates triangulated against top-down process industry capital expenditure tracking across chemical processing, oil and gas, and pharmaceutical verticals.
Sensitivity analysis across multiple demand scenarios tested forecast robustness over the projection horizon. Segmentation dimensions modeled include product architecture, installation method constraints, industry vertical specifications, and standards compliance tier. CAGRs derived from regression-based trending of replacement cycle frequencies, greenfield construction pipelines, and regulatory enforcement intensity indices. Hydrogen infrastructure buildout assumptions and battery manufacturing capacity expansion trajectories served as key industry-specific demand inputs.
Underlying assumptions cover OSHA PSM mandate expansion timelines, EU Pressure Equipment Directive compliance deadline adherence, and nickel alloy supply concentration persistence, with deviation risk concentrated in hydrogen-specific venting protocol standardization delays and qualified rupture disc engineer cohort retirement rates. Practitioners should keep alternative scenarios live as IEC 60079 harmonization progress and cryogenic pressure regime test standard development evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Mobile Hydraulic Valves Market
Valves
Choke Valves Market
Valves
Global Fluid Management Systems Market
Valves
Leak Detection Market
Valves
Global Globe Valve Market
Valves
Axial and Radial Seals Market
Valves
Valve Sack Market
Valves
Fluid Transfer Solutions Market
Valves
Middle East and Africa Industrial Valves Market
Valves
North America Industrial Valves Market
Valves
HVAC Valves Market
Valves
Global Control Valves Market
Valves
Pipeline Strainers Market
Valves
North America Valves Market
Valves
Orifice Reducers Market
Valves
Pinch Valve Market