
 Storage Tank Market | 2026-2036
Storage Tank Market Size, Share, and Industry Trends Forecast 2026-2036
Storage Tank Market Analysis
Water treatment utilities are gaining share as the buyer base is bifurcating away from pure oil and gas procurement. Highland Tank & Manufacturing Company Inc. leverages its vertical integration into coated steel fabrication to anchor municipal contracts across the Eastern United States. CST Industries Inc. competes through bolted tank technology leadership, while McDermott International Inc. dominates large-field erection for energy clients in the Gulf of Mexico basin.
Storage tanks are enclosed vessels engineered to hold liquids, gases, or granular solids at atmospheric or pressurized conditions, typically fabricated from carbon steel, stainless steel, or reinforced concrete with corrosion-resistant linings and welded or bolted seam construction. Above-ground steel tanks lead installed base value due to lower civil works and faster deployment cycles, though fiberglass composites represent the fastest-growing material category for chemical resistance in aggressive service. Water treatment end users concentrate demand in medium-capacity bolted designs, while oil and gas operators drive extra-large welded tank procurement for crude and refined product terminals.
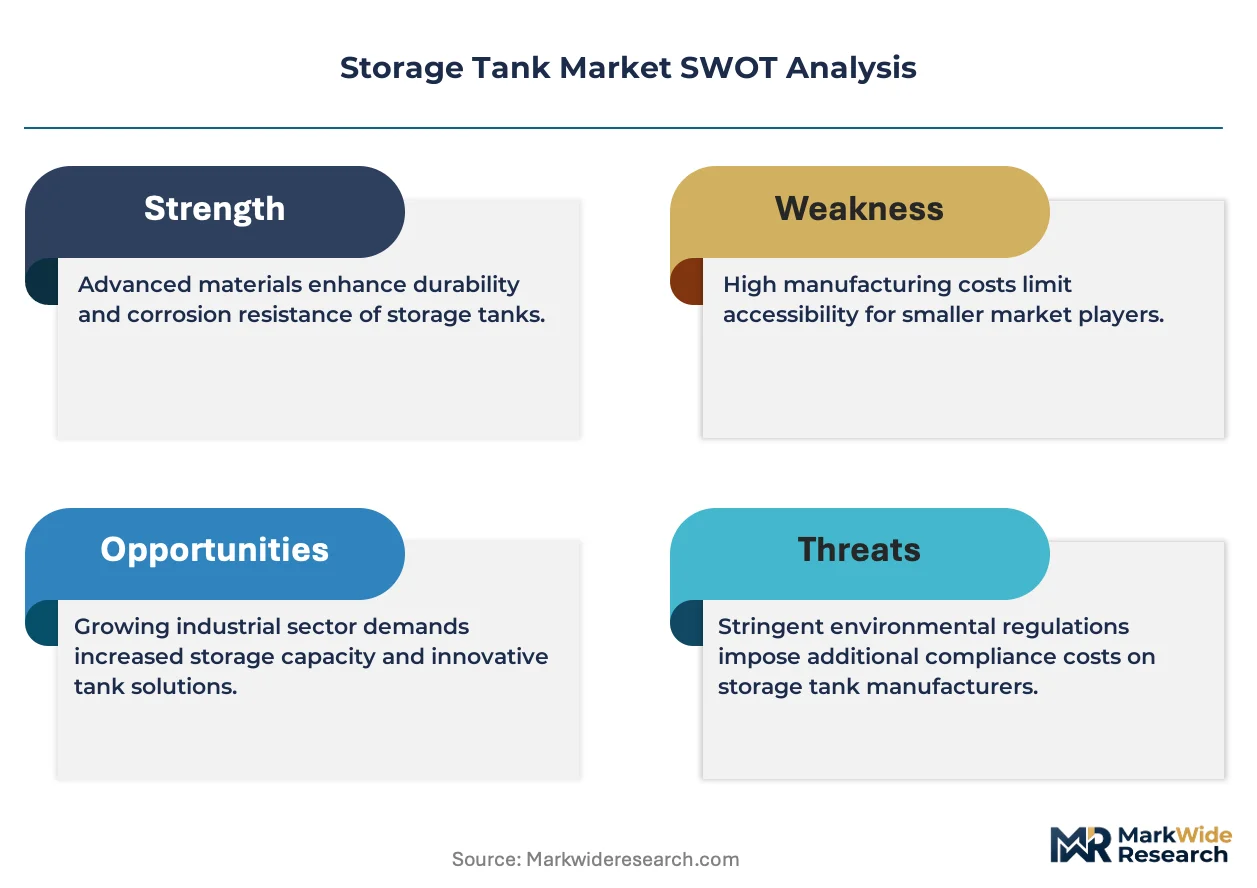
EPA Spill Prevention, Control, and Countermeasure rules and API 650/653 standards govern above-ground tank integrity testing, repair intervals, and secondary containment sizing across US installations. OSHA confined-space entry protocols and state-level fire codes further shape tank design specifications and maintenance economics. Stakeholders must monitor corrosion-monitoring IoT integration and evolving state-level PFAS storage requirements as these forces redefine capital allocation priorities.
Market Dynamics
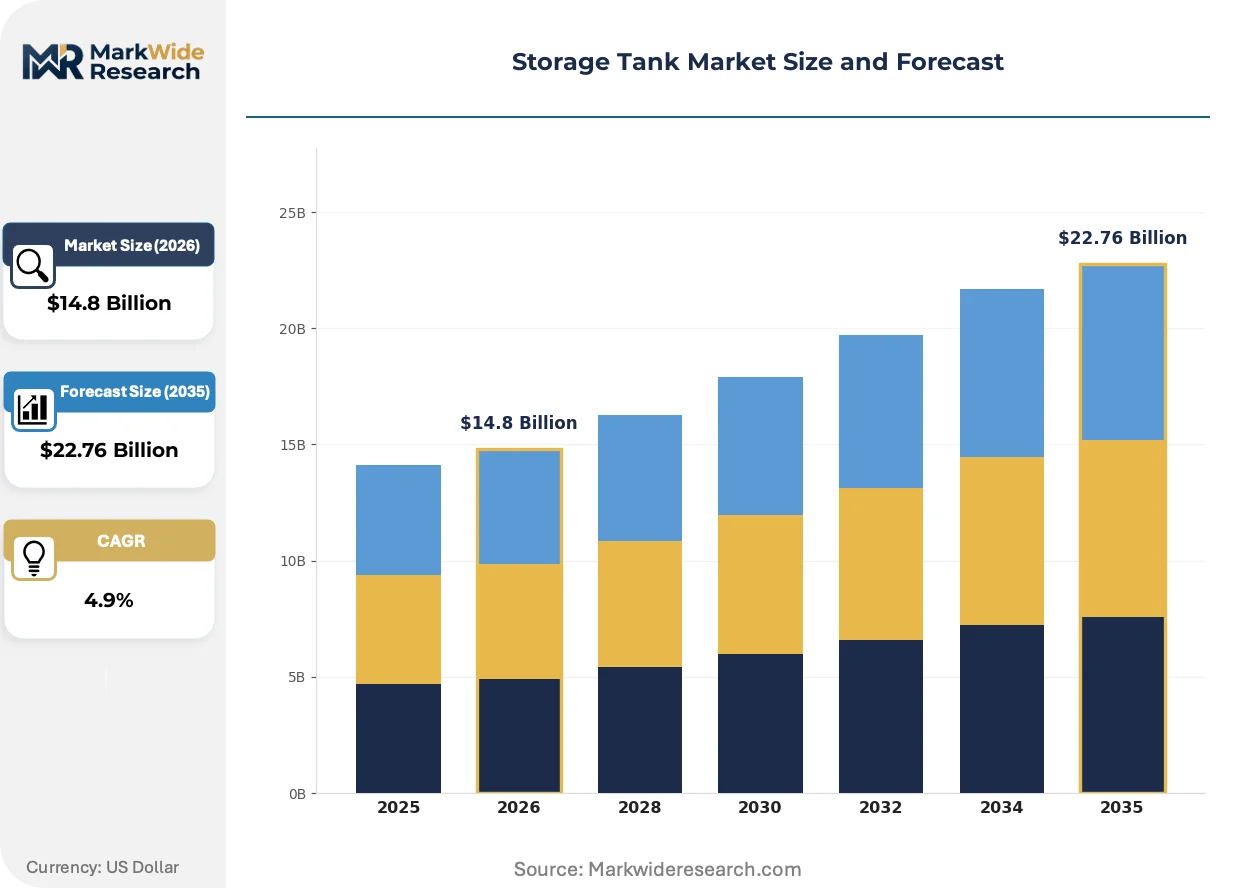
EPA discharge mandates are forcing water treatment utilities to expand above-ground steel capacity, while Korean and German fabrication innovations compress weld-cycle times and reshape competitive economics across the installed base.
Growth Catalysts
- EPA Spill Prevention mandates:Water treatment utilities must install secondary containment systems, driving bolted tank procurement across municipal infrastructure networks.
- Carbon steel fabrication automation:Korean producers deploy robotic welding cells that cut field erection time by half, accelerating project throughput for Gulf Coast petrochemical terminals.
- PFAS storage requirements:State-level regulators in the US are mandating specialized linings for per- and polyfluoroalkyl substance containment, creating replacement demand in legacy installations.
Market Restraints
- Specialized welder scarcity:API 650-certified field crews concentrate in the US Gulf Coast and Germany, creating bottlenecks for large-diameter tank erection elsewhere.
- Epoxy coating input volatility:Petrochemical feedstock fluctuations for corrosion-resistant linings compress margin predictability for fabricators serving chemical processing end users.
- Concrete tank substitution:Reinforced concrete designs retain cost advantage in Middle Eastern desalination projects, limiting steel tank penetration in that geography.
Strategic Opportunities
- IoT corrosion monitoring integration:Wireless sensor networks enable predictive maintenance contracts, shifting revenue from capital sales to recurring service streams.
- India water infrastructure buildout:The country's national water mission targets rural storage capacity expansion, opening demand for medium-capacity bolted designs.
- Fiberglass composite convergence:Chemical resistance properties in aggressive service applications are displacing coated steel in sulfuric acid and chlorine dioxide storage.
Industry Challenges
- API 653 inspector certification timelines:The 18-month qualification pathway for tank integrity assessors creates talent gaps as inspection intervals compress under stricter state enforcement.
- Legacy SCADA integration complexity:New IoT-enabled tanks face protocol mismatches with decades-old municipal control systems, extending commissioning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Storage Tank Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.76 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Above Ground, Underground, Pressure, Floating Material: Steel, Concrete, Fiberglass, Composite End User: Oil & Gas, Chemicals, Water Treatment, Agriculture Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Highland Tank & Manufacturing Company Inc., Motherwell Bridge, CST Industries Inc., Ishii Iron Works Co Ltd, Toyo Kanetsu K.K., McDermott International Inc., Fox Tank Company, Pfaudler Group, PermianLide LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Storage Tank Market Emerging Trajectories
Material science advances and regulatory digitization are restructuring how storage assets are specified, monitored, and maintained across industrial and municipal buyer segments.
Corrosion-resistant fiberglass composite tank construction is displacing carbon steel in chemical processing and wastewater applications. Pharmaceutical manufacturers and semiconductor fabs adopt these vessels for aggressive acid service, eliminating recoating downtime. The shift compresses total cost-of-ownership calculations and redirects fabricator R&D spending toward resin formulation rather than metallic weld procedures.
REACH chemical registration requirements in Europe are tightening coating material specifications for tanks handling hazardous substances. ECHA substance-of-very-high-concern listings now restrict certain epoxy hardeners, forcing reformulation of internal linings. German and Dutch tank fabricators accelerate fluoropolymer lining adoption to maintain CE marking compliance, passing material cost premiums to chemical terminal operators.
Asset-as-a-service contracting is restructuring procurement relationships for municipal water authorities. Long-term availability agreements bundle tank provision with predictive maintenance and regulatory compliance reporting, replacing traditional capital purchase models. This pattern concentrates most visibly in California and Texas, where state revolving fund administrators favor operational expenditure structures that align vendor incentives with leak-prevention outcomes.
Storage Tank Market Segmentation
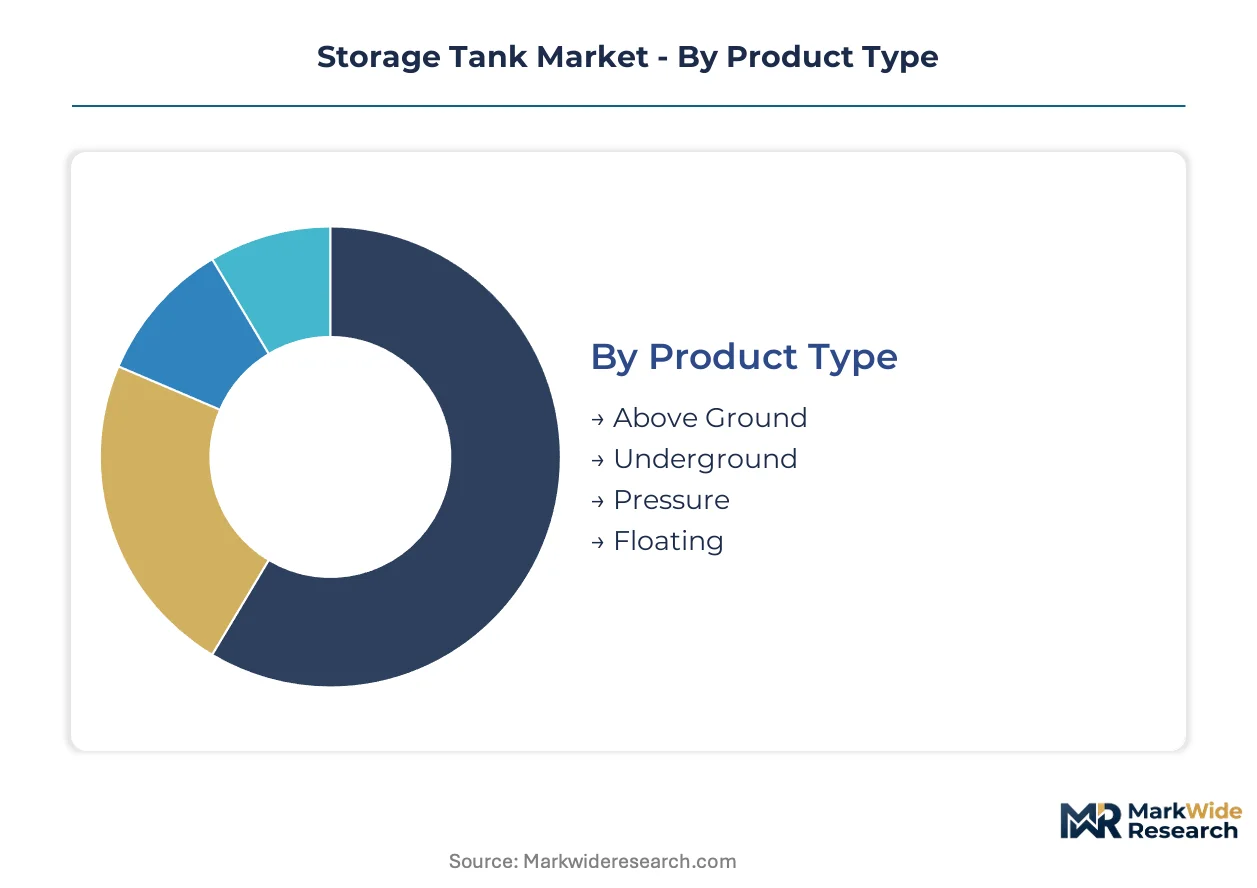
Storage tank procurement patterns diverge sharply across material, capacity, and installation type. Municipal utilities prioritize bolted steel designs for speed of deployment, while petrochemical operators demand welded field-erected vessels for hazardous service.
Product Type:
Above-ground installations dominate domestic procurement cycles, while floating roof designs concentrate in export-led crude terminal contracts.
- Above Ground:Welded and bolted steel configurations comprise the majority of municipal water and industrial chemical installations. Demand clusters in the US Gulf Coast petrochemical corridor where EPA secondary containment mandates accelerate replacement schedules.
- Underground:Double-wall fiberglass and steel-composite designs serve retail fuel stations and airport hydrant systems. State-level UST (underground storage tank) upgrade programs in California and Texas drive retrofit procurement as legacy single-wall installations face forced retirement.
- Pressure:ASME-coded vessels handle liquefied gases and high-vapor-pressure chemicals in refinery and specialty gas applications.
- Floating:Pontoon and double-deck roof designs minimize evaporative losses in crude oil and gasoline storage terminals.
Above-ground configurations hold the largest share; momentum sits with floating roof designs as emission regulations tighten.
Material:
Cost tier stratification separates commodity carbon steel from corrosion-resistant alternatives in aggressive chemical service.
- Steel:Carbon steel remains the baseline for atmospheric storage across water treatment and petroleum applications. Korean and German fabricators compete on automated welding throughput for large-diameter field-erected tanks.
- Concrete:Prestressed and reinforced designs dominate Middle Eastern desalination and cooling water reservoirs where steel faces chloride-induced corrosion.
- Fiberglass:Filament-wound and contact-molded vessels displace coated steel in sulfuric acid, chlorine dioxide, and pharmaceutical processing. Semiconductor fabs in Taiwan and South Korea specify FRP for ultra-pure chemical handling.
- Composite:Hybrid steel-FRP and concrete-steel configurations address seismic loading and chemical resistance in Japanese industrial zones.
Steel retains volume leadership; fiberglass gains share fastest in chemical processing replacement cycles.
End User:
Customer type bifurcation separates capital-intensive energy infrastructure from municipal operational expenditure models.
- Oil & Gas:Midstream terminals and refinery tank farms drive demand for extra-large welded storage. API 650 compliance and API 653 inspection protocols govern procurement specifications across North American and Middle Eastern production basins.
- Chemicals:Specialty chemical and agrochemical producers specify lined carbon steel or fiberglass for acid, caustic, and solvent containment. REACH compliance in Europe restricts certain epoxy hardeners, forcing fluoropolymer lining adoption.
- Water Treatment:Municipal utilities procure medium-capacity bolted steel tanks for potable water and wastewater applications. EPA discharge mandates and state revolving fund structures favor operational expenditure contracting models.
- Agriculture:Irrigation reservoirs and liquid fertilizer storage concentrate demand in rural water districts and cooperative distribution networks.
Oil and gas anchors installed base value; water treatment utilities are climbing the fastest as EPA mandates expand procurement.
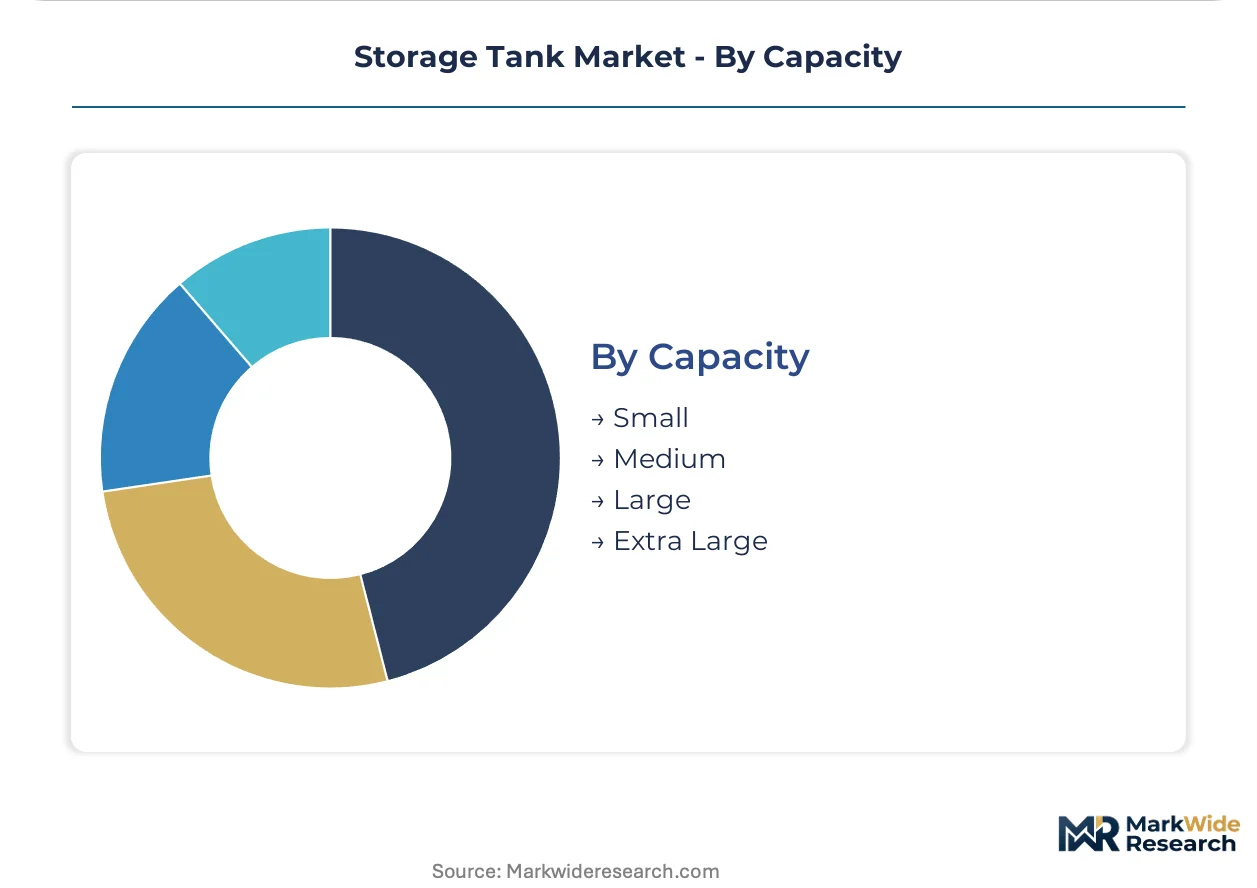
Capacity:
Volume scale determines fabrication location — shop-built vessels below threshold diameters versus field-erected megastructures.
- Small:Shop-fabricated tanks under 50,000 gallons serve commercial fuel oil, chemical day-tanks, and residential water systems. Standardized dimensions enable inventory stocking by regional distributors.
- Medium:Bolted steel designs in the 50,000–500,000 gallon range dominate municipal water and industrial process applications. Prefabricated panel shipment reduces field labor exposure to weather and confined-space protocols.
- Large:Field-erected welded tanks up to 5 million gallons serve refinery product terminals and bulk chemical storage. API 650 certification requirements constrain qualified fabricator pools.
- Extra Large:Crude oil terminals and strategic petroleum reserves require diameters exceeding 300 feet. Specialized heavy-lift erection equipment and API 653 inspection regimes define project economics.
Medium capacity commands the broadest buyer base; extra-large projects carry the steepest expansion trajectory in Gulf Coast petrochemical buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel underwrites United States dominance in large-field tank erection, while Rotterdam's liquid bulk terminals anchor European demand for floating roof designs.
United States
Gulf Coast petrochemical buildouts and EPA secondary containment mandates drive welded tank procurement. OSHA confined-space protocols and API 650 standards govern field erection across Texas and Louisiana terminals. Houston anchors the largest concentration of API-certified fabrication yards serving crude export infrastructure.
Germany
REACH chemical registration and ECHA substance-of-very-high-concern listings force fluoropolymer lining adoption in chemical storage. Automated welding cells from Baden-Württemberg fabricators compress production cycles for export markets. The Ruhr industrial corridor concentrates tank engineering competence serving Central European refineries.
China
National water mission targets and rural storage capacity expansion propel medium-capacity bolted tank demand. MEE environmental discharge standards tighten lining specifications for industrial wastewater containment. The Yangtze River Delta hosts the densest cluster of steel fabrication capacity serving domestic chemical processing.
India
Jal Jeevan Mission rural water infrastructure buildouts open demand for standardized bolted designs. BIS certification requirements and state-level procurement norms favor domestic fabrication. Gujarat's industrial corridor concentrates tank manufacturing serving petrochemical complexes in Jamnagar and Vadodara.
Saudi Arabia
Strategic petroleum reserve expansion and desalination cooling water reservoirs drive extra-large storage procurement. SAMR technical regulations and Saudi Aramco engineering standards specify materials for harsh climate service. The Eastern Province anchors tank farm construction serving Red Sea and Gulf export terminals.
Storage Tank Market Vendor Landscape
Listed leaders compete with private specialists across fabrication scale and geographic coverage. The vendor base separates into three tiers: integrated energy contractors, regional bolted-tank specialists, and municipal-focused fabricators. Strategic moves concentrate on automated welding technology licensing and backward integration into coated steel supply.
Among US-based fabricators, Highland Tank & Manufacturing Company Inc. and CST Industries Inc. occupy positions in the municipal and industrial tiers respectively, while McDermott International Inc. anchors the large-project contractor segment serving Gulf of Mexico energy clients. These three exemplify how geographic clustering around regulatory hubs shapes competitive positioning.
| Leading Market Players |
|---|
| Highland Tank & Manufacturing Company Inc. |
| Motherwell Bridge |
| CST Industries Inc. |
| Ishii Iron Works Co Ltd |
| Toyo Kanetsu K.K. |
| McDermott International Inc. |
| Fox Tank Company |
| Pfaudler Group |
| PermianLide LLC |
| Others |
Supply Flow & Price Mechanics
Long-term availability agreements now lock in both steel coil supply access and fabrication pricing visibility for municipal water authorities across California and Texas state revolving fund structures. These contracts bundle tank provision with predictive maintenance obligations, converting capital expenditure into operational outflows that align vendor incentives with leak-prevention outcomes.
Pricing Analysis
Volume-discount tiering structures separate extra-large field-erected projects above 5 million gallons from standardized medium-capacity bolted designs. Project-based pricing dominates welded tank procurement for Gulf Coast petrochemical terminals, while municipal buyers favor operational expenditure models with embedded service premiums. Price differentiation hinges on API 650 certification grade and geographic delivery distance from Korean or German fabrication hubs. Cost compression in carbon steel coil inputs is intensifying margin pressure on coated tank fabricators serving chemical processing end users. Municipal utilities exhibit highest price sensitivity due to constrained state revolving fund allocations, whereas oil and gas operators prioritize delivery speed over unit cost.
Supply Chain Analysis
Strategic stockpiling of corrosion-resistant coil inventory distinguishes large fabricators from project-to-project competitors in this market. Steel supply concentrates in South Korea, Germany, and the Yangtze River Delta of China, where automated welding cell production anchors export capacity. Raw material dependencies center on hot-rolled carbon steel coil, epoxy resin formulations for internal linings, and fluoropolymer sheeting for chemical-resistant applications. Single-source vulnerability in API 650-certified field erection crews creates bottlenecks for large-diameter tank projects outside the US Gulf Coast. Distribution runs through direct contracting between fabricators and municipal procurement authorities, with regional distributors handling standardized small-capacity inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IoT corrosion monitoring platforms are restructuring procurement relationships into recurring-revenue ecosystems, with wireless sensor networks forcing interoperability between decades-old municipal SCADA systems and new predictive maintenance protocols.
For Market Incumbents: Fortify API 653 inspection certification pipelines to address the 18-month qualification gap threatening field erection capacity. Backward integration into coated steel supply secures margin control against epoxy resin feedstock volatility. Incumbents must also defend bolted tank market share against fiberglass composite substitution in sulfuric acid and chlorine dioxide applications. For New Entrants and Emerging Players: API 653 fast-track certification programs open access to municipal predictive maintenance contracts where legacy fabricators lack service infrastructure. White-space targets concentrate in India's Jal Jeevan Mission rural water buildouts and US state-level PFAS storage retrofit mandates. A go-to-market angle emphasizing asset-as-a-service contracting disrupts traditional capital purchase relationships with municipal utilities. For Investors and Strategic Acquirers: Automated welding technology licensors with Korean or German equipment partnerships represent the priority acquisition archetype. Long-term viability over the next decade rests on exposure to EPA discharge mandate enforcement cycles and IoT-enabled service revenue conversion. The signal to watch is state-level PFAS lining requirement adoption rates, which trigger replacement demand in legacy installations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coated Steel Supply | Captive epoxy coil production insulates margins from petrochemical feedstock volatility affecting competitors. |
| IoT Corrosion Monitoring Platform Launch | Wireless sensor networks shift revenue from capital sales to recurring predictive maintenance contracts with municipalities. |
| API 653 Inspection Certification Pipeline | Qualified assessor capacity constraints create bottlenecks as state enforcement compresses inspection intervals. |
| Fiberglass Composite Manufacturing Scale-Up | Filament-wound vessels displace coated steel in semiconductor fab and pharmaceutical acid service applications. |
| Long-term Availability Agreement Structuring | Operational expenditure models align vendor incentives with EPA leak-prevention outcomes in California and Texas. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of trade association filings, customs import records, and regulatory enforcement databases. Primary interviews engaged tank fabrication executives, municipal water authority procurement directors, API-certified inspection contractors, and epoxy coating formulators. Secondary validation drew from EPA enforcement actions, API standards documentation, and state revolving fund disbursement records. Bottom-up project pipeline tracking triangulates against top-down capacity utilization estimates across Korean, German, and Chinese fabrication hubs.
Segmentation dimensions modeled include material type, capacity tier, installation configuration, and end-user vertical across the projection horizon. Analytical frameworks incorporate bolted versus welded fabrication economics, field erection labor availability, and coating specification evolution under REACH and state-level PFAS mandates. CAGRs derive from installed base replacement cycles, greenfield petrochemical capacity announcements, and rural water infrastructure budget allocations. Industry-specific forecast inputs encompass API 653 inspector certification throughput and fiberglass composite resin formulation cost curves.
Decision-makers should treat outputs as directional under assumptions of sustained EPA discharge mandate enforcement and Korean-German fabrication automation diffusion; material deviation would warrant model refresh. Specific risks include tariff exposure on steel coil imports, abrupt state-level PFAS regulatory acceleration, and API 650-certified welder supply shocks. Revision becomes warranted when IoT corrosion monitoring penetration in municipal contracts crosses thresholds that fundamentally alter replacement cycle timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
White Coal Market
Fuels
Caribbean Islands Bunker Fuel Market
Fuels
North America Aviation Fuel Market
Fuels
Fuel Grinder Market
Fuels
United Kingdom Bunker Fuel Market
Fuels
Brazil Bunker Fuel Market
Fuels
Solid Fuel Tablet Market
Fuels
Petroleum Fuel Dyes Sales Market
Fuels
Asia-Pacific Commercial Aircraft Aviation Fuel Market
Fuels
Collapsible Fuel Tank Market
Fuels
LNG Fueling Station Market
Fuels
Refuse Derived Fuel Market
Fuels
Aviation Fuel Additives Market
Fuels
Carbonizers Market
Fuels
High-Temperature Industrial Burner Market
Fuels
LNG As a Fuel Market