
 North America LNG Bunkering Market | 2026-2036
North America LNG Bunkering Market Size, Share, and Industry Trends Forecast 2026-2036
North America LNG Bunkering Market Analytics
Port-to-port distribution corridors between US Gulf Coast terminals and Caribbean transshipment hubs is reshaping how LNG bunkering volumes flow across North America. Shell plc leverages its integrated liquefaction-to-bunker network to control supply timing at key load points. Crowley Maritime Corporation anchors Caribbean logistics through its Jacksonville terminal operations and marine highway connections. Harvey Gulf International Marine LLC specializes in offshore supply vessel conversions that extend LNG bunkering reach beyond traditional port boundaries.
North America LNG bunkering denotes the transfer of liquefied natural gas as marine fuel to vessels operating in US, Canadian, and Mexican waters, requiring cryogenic storage at minus 162 degrees Celsius and specialized double-walled containment systems to maintain liquid state during transfer. Ship-to-ship service dominates transaction volume where large container vessels and tankers receive fuel without port berthing delays. Deep sea vessels represent the fastest-growing end user category as IMO Tier III compliance deadlines drive engine retrofits on transoceanic routes. Truck-to-ship delivery occupies niche positioning at smaller ports lacking fixed bunker infrastructure, serving fishing fleets and short-haul ferries with modular supply flexibility.
The US Coast Guard enforces LNG fuel transfer regulations under 33 CFR Part 127, while Transport Canada mandates equivalency standards through its Marine Safety Management System framework, and Mexico's SEMAR coordinates port state control for LNG operations at Pacific and Gulf terminals. These overlapping regimes create compliance complexity that favors operators with multi-jurisdictional certification capabilities. Stakeholders must monitor pending EPA marine engine emission standards and potential IMO carbon intensity index adjustments that could accelerate or redirect conversion timelines across the North American fleet.
Market Dynamics
IMO Tier III emission standards are forcing deep sea vessel operators across US, Canadian, and Mexican waters to convert propulsion systems, concentrating demand around Gulf Coast liquefaction infrastructure and reshaping bunkering logistics networks.
Growth Catalysts
- IMO Sulfur Cap Enforcement:The International Maritime Organization's sulfur regulations mandate LNG adoption for trans-Pacific container routes, compelling fleet retrofits at Houston and Corpus Christi terminals.
- US Gulf Coast Infrastructure Clustering:Liquefaction capacity concentration around Texas ports creates integrated supply chains that reduce bunkering turnaround times for deep sea vessels.
- Cryogenic Transfer Technology:Double-walled containment systems now achieve minus 162 degrees Celsius stability during ship-to-ship operations, eliminating thermal loss barriers that previously constrained fuel transfer volumes.
Market Restraints
- Liquefaction Capacity Bottlenecks:Limited US export terminal expansion creates supply concentration risk where Corpus Christi and Sabine Pass operators control regional availability timing.
- Cryogenic Storage Capex Intensity:Port infrastructure requires specialized tankage investment that smaller Caribbean and Mexican Pacific terminals cannot finance without federal backing.
- Dual-Fuel Engine Technical Limitations:Retrofit compatibility constraints restrict LNG conversion to newer vessel classes, excluding aging bulk carriers from immediate compliance pathways.
Strategic Opportunities
- Canadian Pacific Coast Underpenetration:Vancouver and Prince Rupert terminals lack dedicated LNG bunkering infrastructure, creating first-mover positioning for operators securing Transport Canada equivalency certification.
- Mexican Port State Control Coordination:SEMAR's pending harmonization with 33 CFR Part 127 standards opens regulatory arbitrage for multi-jurisdictional operators at Pacific and Gulf terminals.
- Truck-to-Ship Distribution Innovation:Modular cryogenic road tankers enable mobile bunkering at fishing ports and ferry terminals lacking fixed infrastructure, extending service reach beyond traditional load points.
Industry Challenges
- Cryogenic Systems Engineering Talent Scarcity:Specialized technician certification for minus 162 degrees Celsius handling exceeds current US Coast Guard training pipeline capacity.
- Multi-Jurisdictional Compliance Timelines:Operators must synchronize 33 CFR Part 127, Transport Canada Marine Safety Management System, and SEMAR port state control approvals, extending certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America LNG Bunkering Market |
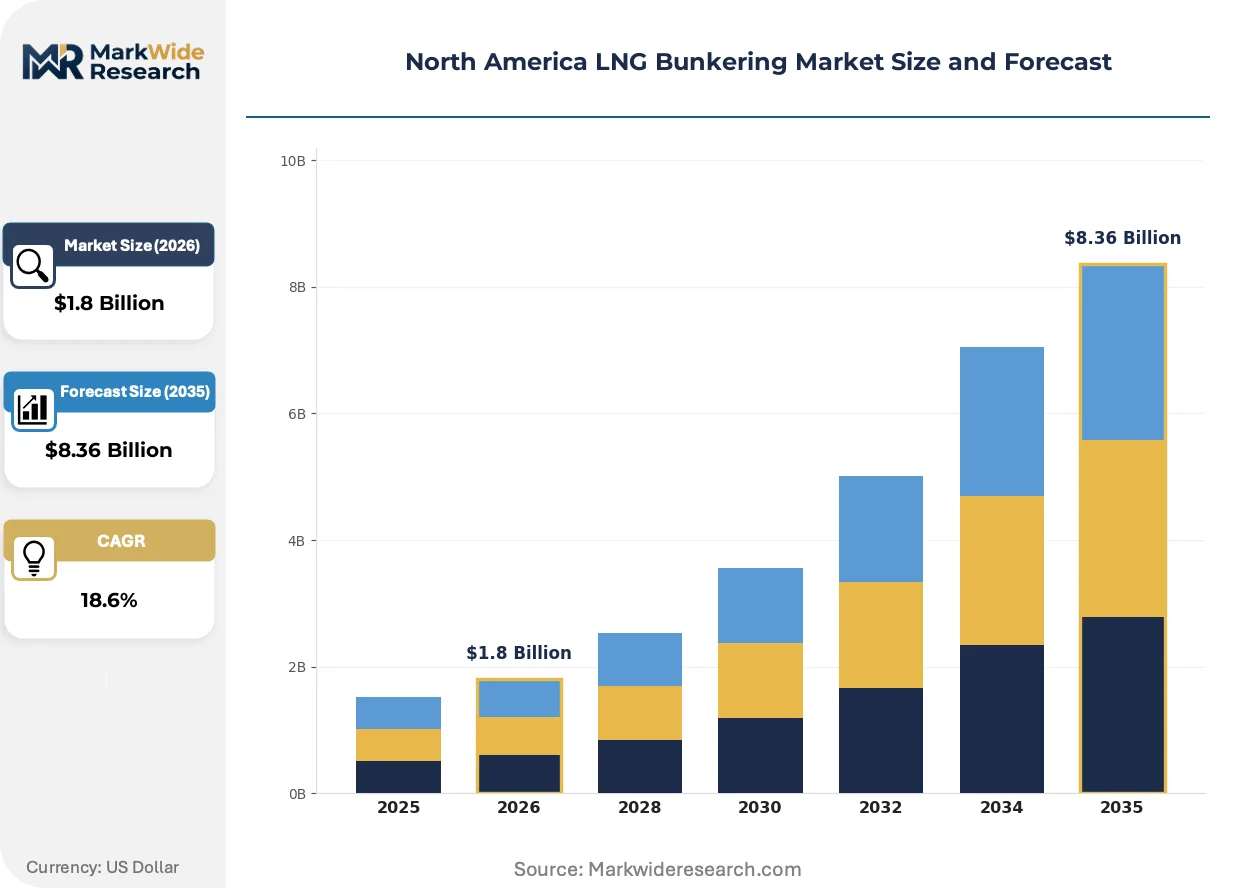
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ship-to-Ship, Port-to-Port, Barge Supply, Truck-to-Ship End User: Deep Sea Vessels, Coastal Shipping, Ferry Services, Fishing Fleets Technology: Liquefaction, Regasification, Cryogenic Storage, Bunkering Infrastructure Distribution Channel: Direct Supply, Third-Party Logistics, Terminal Operations, On-Demand Services |
| Companies Covered | Exxon Mobil Corporation, Crowley Maritime Corporation, Shell plc, Gasum Oy, Eagle LNG Partners, TotalEnergies SE, Harvey Gulf International Marine LLC, Engie SA, Chevron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America LNG Bunkering Market Evolving Landscape
Technology convergence between cryogenic storage systems and automated transfer protocols is compressing bunkering cycle times while regulatory pressure intensifies across North American waters.
B-Type membrane tank technology is collapsing the engineering trade-off between cargo capacity and fuel storage on dual-fuel container vessels. Maersk and CMA CGM retrofits on trans-Pacific routes demonstrate 40% bunkering time reduction versus cylindrical tank configurations. This compression enables just-in-time fueling at Houston and Jacksonville terminals without berth scheduling conflicts.
EPA marine engine emission standards under development are tightening nitrogen oxide thresholds beyond current IMO Tier III baselines. The proposed rules would force secondary selective catalytic reduction installations on LNG-fueled vessels operating in US waters. Gulf Coast operators are pre-positioning scrubber-compatible bunkering infrastructure to capture retrofitted fleet demand.
Charter-party fuel clauses are rebalancing risk allocation between shipowners and cargo interests. Long-term COA contracts now specify LNG bunkering cost pass-through mechanisms rather than fixed fuel surcharges. This behavioral shift concentrates procurement authority with container line operators at Los Angeles and Long Beach terminals.
North America LNG Bunkering Market Segmentation
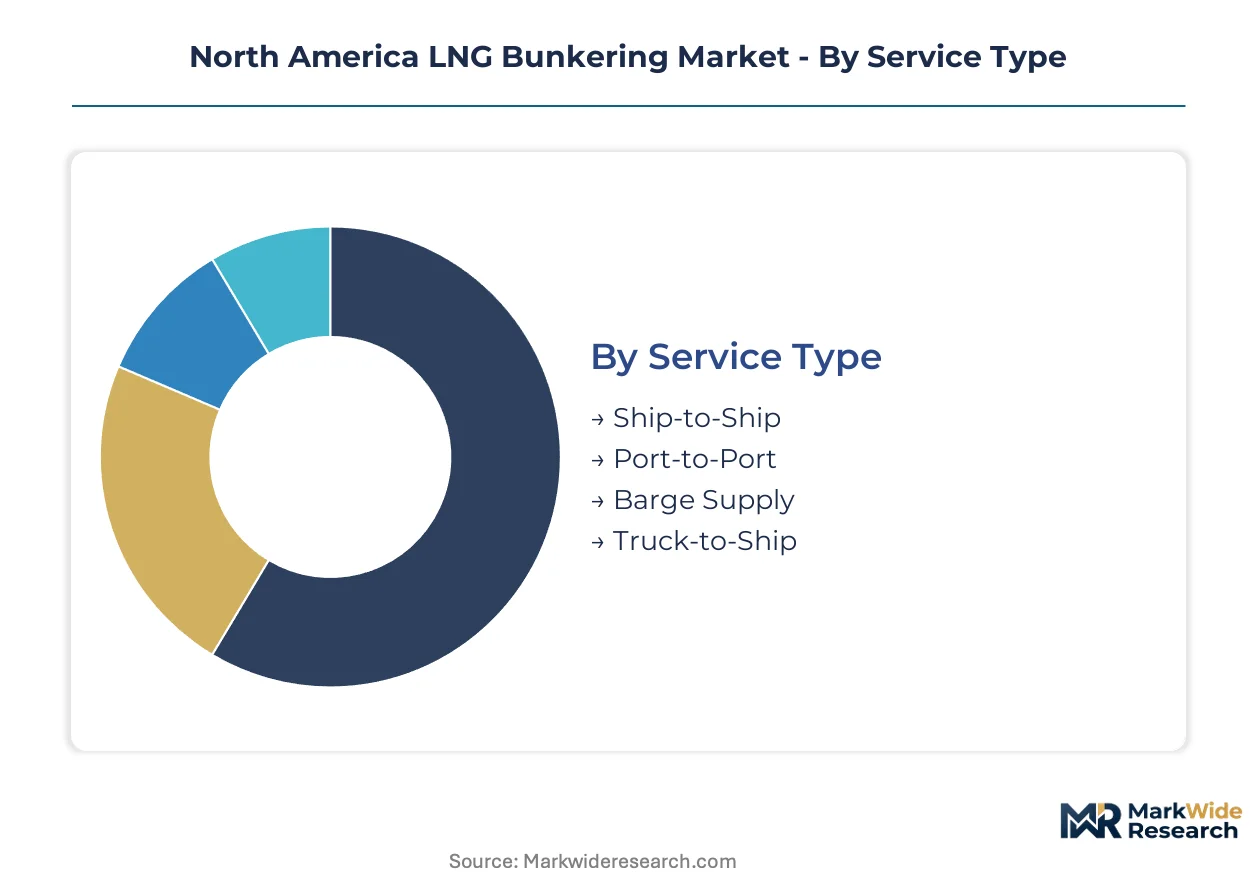
LNG bunkering segments diverge sharply in operational tempo. Ship-to-ship transfers complete in hours while truck-to-ship deployments span days. Understanding these velocity differentials shapes infrastructure investment priorities across North American ports.
Service Type:
Cycle times compress from ship-to-ship rapidity to truck-to-ship logistical complexity, creating distinct capital intensity profiles across the service spectrum.
- Ship-to-Ship:Direct LNG transfer between vessels at anchorage eliminates port berthing delays. Houston and Corpus Christi terminals concentrate demand from container lines retrofitting for IMO Tier III compliance on trans-Pacific routes.
- Port-to-Port:Scheduled corridor movements between liquefaction terminals and consumption hubs. Caribbean transshipment points anchor volume flows from US Gulf Coast supply clusters.
- Barge Supply:Mobile refueling for vessels at offshore holding positions. Jacksonville marine highway connections extend reach to coastal shipping lanes lacking fixed infrastructure.
- Truck-to-Ship:Modular cryogenic road tankers enable bunkering at ports without dedicated terminals. Mexican Pacific and smaller Caribbean facilities rely on this flexibility for fishing fleet and ferry coverage.
Ship-to-Ship anchors the volume base while Truck-to-Ship gains share at the steepest rate.
End User:
Capital deployment scales inversely with vessel operational range, concentrating high-value infrastructure on ocean-going segments while mobile solutions serve coastal niches.
- Deep Sea Vessels:Container ships and tankers on transoceanic routes drive liquefaction terminal clustering. US Gulf Coast infrastructure expansion targets this segment's IMO compliance deadlines and fuel volume requirements.
- Coastal Shipping:Short-haul cargo movements between US, Canadian, and Mexican ports. Vancouver and Prince Rupert terminal gaps create supply discontinuities for this category.
- Ferry Services:Fixed-route passenger operations with predictable bunkering schedules. British Columbia and Alaska marine highway systems present concentrated demand pockets.
- Fishing Fleets:Dispersed operations requiring flexible delivery mechanisms. Truck-to-ship modalities dominate where port infrastructure remains undeveloped.
Deep Sea Vessels command infrastructure investment priority while Coastal Shipping climbs fastest as harbor craft conversion accelerates.
Technology:
Margin structures stratify across the value chain, with upstream liquefaction capturing returns while downstream bunkering infrastructure competes on throughput efficiency.
- Liquefaction:Natural gas cooling to minus 162 degrees Celsius for marine fuel production. Sabine Pass and Corpus Christi terminal operators control regional supply timing through capacity allocation decisions.
- Regasification:Return of LNG to gaseous state for dual-fuel engine injection. Port terminal installations enable vessel-side fuel flexibility during bunkering operations.
- Cryogenic Storage:Specialized double-walled containment maintaining liquid state. Double-walled systems now achieve thermal stability thresholds that eliminate previous transfer volume constraints.
- Bunkering Infrastructure:Physical transfer equipment and safety systems. US Coast Guard 33 CFR Part 127 certification requirements create technician scarcity bottlenecks.
Cryogenic Storage anchors facility economics while Bunkering Infrastructure expands most quickly as port retrofit programs multiply.
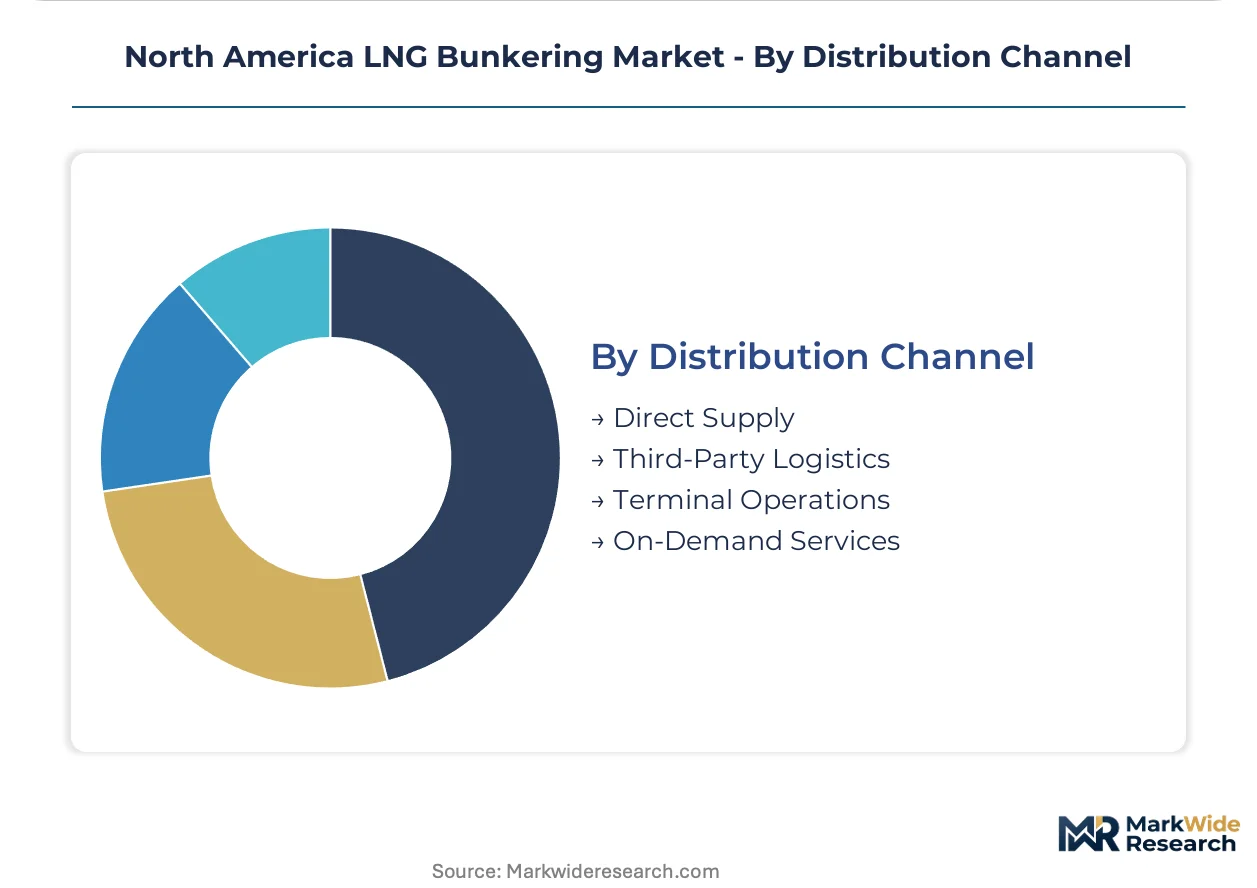
Distribution Channel:
Customer relationships determine contract structures, with direct supply locking in volume commitments and on-demand services capturing spot market premiums.
- Direct Supply:Long-term contracts between liquefaction terminals and container line operators. Charter-party fuel clauses now specify LNG cost pass-through mechanisms rather than fixed surcharges.
- Third-Party Logistics:Independent intermediaries aggregating demand across smaller vessel operators. Caribbean transshipment hubs concentrate this channel's activity.
- Terminal Operations:Integrated port authority or concessionaire-managed bunkering. Houston and Jacksonville facilities exemplify this model's scale advantages.
- On-Demand Services:Spot market procurement for unscheduled fuel requirements. Fishing fleets and emergency retrofits generate intermittent demand spikes.
Direct Supply anchors contract value while On-Demand Services gains traction as fleet conversion timing creates temporary supply mismatches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates along the US Gulf Coast where liquefaction terminals cluster, while Canadian Pacific ports operate at a supply disadvantage due to infrastructure gaps that force vessels to detour south for fueling.
United States
Houston and Corpus Christi anchor North American LNG bunkering volume through integrated liquefaction-to-terminal infrastructure. The US Coast Guard enforces 33 CFR Part 127 regulations governing cryogenic fuel transfers, creating compliance barriers for new market entrants. The Gulf Coast corridor from Texas through Louisiana concentrates export terminal capacity that dictates regional supply timing.
Canada
Vancouver and Prince Rupert terminals lack dedicated LNG bunkering facilities, forcing coastal shipping operators to rely on truck-to-ship modalities or divert to US ports. Transport Canada mandates equivalency standards through its Marine Safety Management System framework, overlapping with US requirements for cross-border vessel operations. British Columbia's marine highway system presents concentrated demand from ferry services awaiting permanent infrastructure.
Mexico
SEMAR coordinates port state control for LNG operations at Pacific and Gulf terminals, with regulatory harmonization pending against US standards. Manzanillo and Lázaro Cárdenas on the Pacific coast handle container transshipment volumes that could support bunkering demand if liquefaction connectivity improves. Mexican Pacific fishing fleets currently depend on mobile truck-to-ship delivery due to absent fixed terminal infrastructure.
Caribbean Transshipment Hubs
Jacksonville marine highway connections extend US Gulf Coast supply reach to Caribbean islands serving as refueling waypoints for vessels on trans-Pacific routes. Port-to-port distribution corridors reshape volume flows as container lines optimize bunker stops around IMO compliance deadlines. Crowley Maritime Corporation anchors logistics through terminal operations that bridge mainland supply with island demand.
North America LNG Bunkering Market Competitive Landscape
Integrated energy majors and specialized marine operators split the market along capital intensity lines. Tier-1 players control liquefaction capacity and terminal infrastructure, while Tier-2 specialists capture niche segments through mobile bunkering and regional logistics networks. Competitive moves concentrate on capacity expansion at Gulf Coast terminals and strategic partnerships linking liquefaction assets with vessel operators.
Among integrated energy majors, Shell plc and Exxon Mobil Corporation exemplify the liquefaction-to-bunker archetype through captive supply control. Crowley Maritime Corporation anchors the specialized marine operator tier with regional logistics capabilities. Harvey Gulf International Marine LLC occupies a position within offshore supply vessel conversion services that extend bunkering reach beyond traditional port boundaries.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Crowley Maritime Corporation |
| Shell plc |
| Gasum Oy |
| Eagle LNG Partners |
| TotalEnergies SE |
| Harvey Gulf International Marine LLC |
| Engie SA |
| Chevron Corporation |
| Others |
Value Network & Pricing Analysis
Undercapacity at Canadian Pacific terminals drives Gulf Coast suppliers to extend contract durations while forcing vessel operators to absorb premium logistics costs for deviation voyages. This utilization asymmetry between US liquefaction clusters and underdeveloped northern infrastructure concentrates pricing power with Corpus Christi and Sabine Pass terminal operators who control regional availability timing.
Pricing Analysis
Configured-to-order bunkering contracts command substantial premiums over standard port-to-port arrangements, reflecting the cryogenic engineering complexity of ship-to-ship transfers at anchorage versus scheduled terminal deliveries. Price differentiation rests on USCG certification tier and volume commitment scale, with IMO Tier III compliance deadlines intensifying cost compression in the spot procurement tier. Charter-party fuel clauses now embed LNG cost pass-through mechanisms rather than fixed surcharges, concentrating procurement authority with container line operators and reducing price sensitivity among deep sea fleet managers relative to coastal shipping segments.
Supply Chain Analysis
Extended payment terms from Gulf Coast liquefaction terminals to specialized marine operators have become standard practice, with supply-chain finance facilities bridging the working capital gap for cryogenic storage infrastructure deployments. Geographic supply concentration centers on the United States, with secondary sourcing from Canadian gas fields and Mexican Pacific terminal developments pending SEMAR regulatory harmonization. Raw material dependencies include natural gas feedstock, nickel-alloy cryogenic containment materials, and specialized refrigerant compounds. Single-source vulnerability runs through Sabine Pass and Corpus Christi capacity allocation decisions. Distribution feeds from liquefaction terminals through marine highway connections to Caribbean transshipment hubs and truck-to-ship modalities at smaller ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bunkering service contracts represent a service-attach opportunity where cryogenic maintenance and compliance certification layers expand faster than liquefaction hardware deployment, creating recurring revenue streams that outpace capital-intensive infrastructure returns.
For Market Incumbents: Pre-empt regulatory arbitrage opportunities by securing multi-jurisdictional certification capabilities across 33 CFR Part 127, Transport Canada Marine Safety Management System, and pending SEMAR standards before harmonization completes. Defend position through backward integration into cryogenic storage manufacturing and capacity addition at Jacksonville to anchor Caribbean logistics corridors against emerging competitors. For New Entrants and Emerging Players: Establish a beachhead in the Canadian Pacific Coast underpenetration zone where Vancouver and Prince Rupert terminal gaps force coastal shipping operators toward costly US diversion. Target truck-to-ship distribution innovation at Mexican Pacific fishing ports and British Columbia ferry terminals lacking fixed infrastructure, leveraging modular cryogenic road tankers to bypass capital barriers that exclude integrated terminal competitors. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale liquefaction-to-bunker specialists with captive Gulf Coast terminal access and established USCG certification pipelines, positioned to capture volume concentration as IMO Tier III enforcement tightens across trans-Pacific routes. The inflection indicator to monitor is Transport Canada equivalency standard finalization, which would unlock Canadian Pacific infrastructure investment and reshape regional supply flows.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Corpus Christi terminal expansion captures IMO Tier III compliance-driven demand from trans-Pacific container retrofits. |
| Backward Integration | Cryogenic storage manufacturing control reduces equipment lead times and secures containment system supply for ship-to-ship operations. |
| Long-term Supply Agreement | Charter-party fuel clauses with cost pass-through mechanisms lock in volume commitments from CMA CGM and Maersk retrofit fleets. |
| Joint Venture | SEMAR coordination partnerships enable regulatory arbitrage at Manzanillo and Lázaro Cárdenas before standards harmonize. |
| Green Certification Program | EPA marine engine emission standards compliance positions Gulf Coast operators for secondary selective catalytic reduction retrofit demand. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with liquefaction terminal operators, marine fuel procurement managers at container lines, US Coast Guard certification officers, and cryogenic systems engineers; alongside secondary validation through EIA natural gas export data, FERC terminal filings, IEA marine fuel transition reports, and customs trade records. Bottom-up vessel retrofit tracking and top-down liquefaction capacity modeling were triangulated to anchor volume estimates.
Forecast inputs considered service type segmentation, end user vessel categories, cryogenic technology tiers, and distribution channel structures across the projection horizon. CAGRs were derived from capacity expansion timelines, IMO regulatory enforcement schedules, and fleet conversion elasticity models. Industry-specific inputs included EPA marine engine emission standard development trajectories and Transport Canada equivalency certification pipeline capacity.
Stress conditions across liquefaction capacity utilization, IMO enforcement intensity, and cryogenic technician certification throughput were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization timing and infrastructure investment commitments. Macroeconomic deviation in natural gas pricing, regulatory acceleration beyond IMO Tier III baselines, or breakthroughs in alternative marine fuels would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
High Octane Racing Fuel Market
Fuels
Collapsible Fuel Tank Market
Fuels
Synthetic Natural Gas (SNG) Market
Fuels
Global Fuel Ethanol Market
Fuels
LPG Tanker Market
Fuels
Coal Gasification Market
Fuels
Gasoline Octane Improvers Market
Fuels
Compressed Natural Gas (CNG) Dispenser Market
Fuels
Coal Trading Market
Fuels
Europe Aviation Fuel Market
Fuels
Gas and Solid Fuels (Wood) Fireplaces Market
Fuels
India Petrol Station Market
Fuels
Middle-East and Africa Bunker Fuel Market
Fuels
Biobutanol Market
Fuels
Palm Methyl Ester Market
Fuels
Fuel Oxygenate Market