
 Italy Chemical Logistics Market | 2026-2036
Italy Chemical Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Chemical Logistics Market Insights
Buyer concentration among Italian specialty chemical manufacturers is decoupling from traditional bulk petrochemical clients as pharmaceutical and agrochemical purchasers fragment into smaller, compliance-intensive accounts. GDT Logistics leverages its temperature-controlled warehousing network across northern Italy to capture this shift. FA Chemical Logistics S.R.L specializes in hazardous materials handling certifications that smaller buyers now require. Raben Group anchors its competitive position through extensive cross-border road distribution into Slovenia and Austria.
Chemical logistics encompasses the specialized transportation, storage, and handling of hazardous and non-hazardous chemical products under controlled conditions including temperature monitoring, ADR-compliant vehicle specifications, and segregation protocols for incompatible substances. The primary purpose is ensuring safety, regulatory compliance, and supply chain continuity for chemical manufacturers moving products from production facilities to industrial end users. Road transportation dominates service revenue due to Italy's dense manufacturing corridor geography, while warehousing margins concentrate in temperature-controlled and hazardous-certified facilities near Milan and Ravenna port complexes. Pharmaceutical end-use logistics represents the fastest-expanding segment as biologics and temperature-sensitive APIs multiply cold-chain infrastructure requirements.
Italy's chemical logistics sector operates under EU REACH registration requirements, ADR road transport directives, and national Seveso III implementation for high-tier hazardous site controls, with ECHA classification standards directly determining packaging, labeling, and segregation protocols that logistics providers must embed operationally. The Italian National Institute for Insurance against Accidents at Work enforces workplace chemical exposure limits that shape warehouse automation investment and labor deployment patterns. Stakeholders must monitor how EU Green Deal carbon border adjustments and emerging digital product passport requirements will restructure chemical freight routing and documentation burdens.
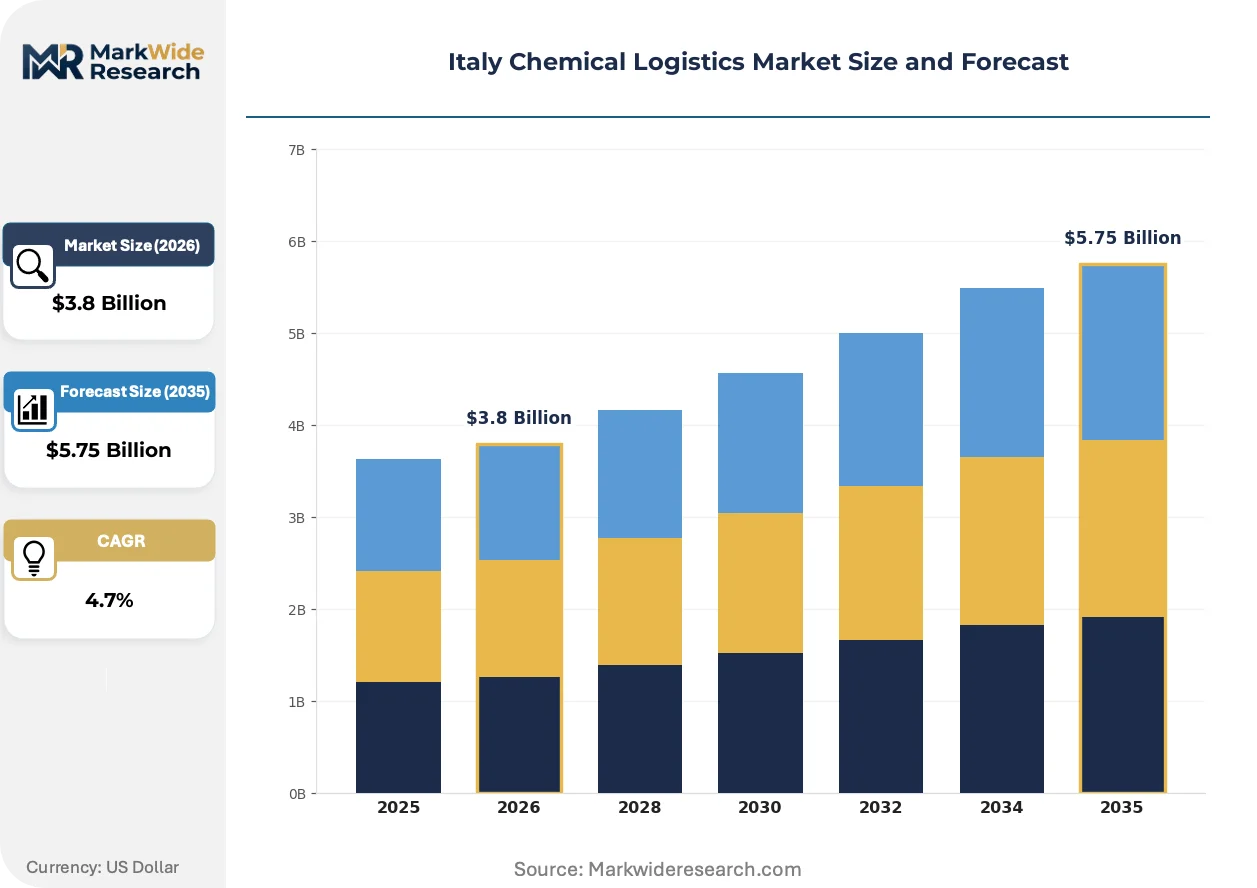
Market Dynamics
Italy's chemical logistics sector is restructuring around pharmaceutical cold-chain expansion in the Lombardy-Veneto corridor, where temperature-sensitive biologics and active pharmaceutical ingredients are displacing traditional bulk chemical freight flows.
Growth Catalysts
- EU CLP Regulation compliance mandates:Chemical classification standardization is forcing warehouse operators to upgrade segregation protocols and labeling systems, creating service differentiation for certified providers.
- Specialty pharmaceutical manufacturing clusters:Milan and Turin biologics producers are multiplying cold-storage requirements, pulling investment into temperature-controlled infrastructure.
- Intermodal freight integration:Petrochemical and agrochemical concentration along the Po Valley is anchoring rail-road barge combinations that reduce per-unit transport costs for hazardous materials.
Market Restraints
- Seveso III high-tier site controls:National implementation of EU major-accident hazard directives imposes capital-intensive safety infrastructure on warehouse operators near population centers.
- Natural gas price volatility:Refrigeration and heating costs for temperature-controlled facilities fluctuate with continental energy markets, compressing warehousing margins.
- Skilled hazardous materials handler scarcity:ADR-certified drivers and dangerous goods safety advisors face limited supply in northern Italian labor markets.
Strategic Opportunities
- Sicily and southern port underpenetration:Catania and Gioia Tauro chemical handling capacity lags northern equivalents, offering first-mover expansion potential for temperature-certified operators.
- EU Green Deal carbon border adjustments:Emerging documentation requirements for chemical imports will reward logistics providers with embedded emissions tracking capabilities.
- Digital product passport integration:Blockchain-enabled batch traceability is converging with warehouse management systems to create premium service tiers for pharmaceutical clients.
Industry Challenges
- REACH registration data management:Logistics providers must maintain auditable substance flow documentation across multi-modal handoffs, straining legacy IT systems.
- Cross-border driver certification reciprocity:ADR qualifications face recognition friction with Slovenian and Austrian regulatory authorities, complicating Raben Group's corridor operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Chemical Logistics Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Packaging, Distribution Delivery Mode: Road, Rail, Sea, Air End Use Industry: Pharmaceuticals, Agrochemicals, Paints, Petrochemicals Packaging Type: Cylinders, Drums, IBCs, Bulk Containers |
| Companies Covered | GDT Logistics, FA Chemical Logistics S.R.L, Raben Group, Gruber Logistics, Noatum Logistics, DHL, Dachser Logistics, GEODIS, Rhenus Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Chemical Logistics Market Trends and Innovations
Real-time environmental monitoring and predictive routing algorithms are compressing transit times for temperature-sensitive chemical shipments while tightening compliance documentation. These technologies are reshaping competitive positioning around data transparency rather than pure asset scale.
IoT-enabled cold-chain sensors are converging with warehouse management platforms to create continuous temperature and humidity documentation for pharmaceutical shipments. Specialty chemical manufacturers in Lombardy are adopting these systems at accelerating rates. The technology is converging with automated alert protocols that trigger contingency logistics before product degradation occurs.
EU Green Deal implementation is tightening carbon reporting requirements for chemical freight movements across Italian borders. Logistics operators must now document emissions per shipment lane to maintain pharmaceutical client contracts. The F-Gas Regulation is additionally phasing down hydrofluorocarbon refrigeration, forcing warehouse retrofits in the Milan-Ravenna corridor.
Pharmaceutical buyers are unbundling after-sales logistics from manufacturing contracts, creating standalone procurement for cold-chain services. Third-party logistics providers are capturing these relationships through dedicated quality agreements. This pattern concentrates in Turin's injectables manufacturing cluster where product stability requirements exceed in-house capabilities.
Italy Chemical Logistics Market Segmentation
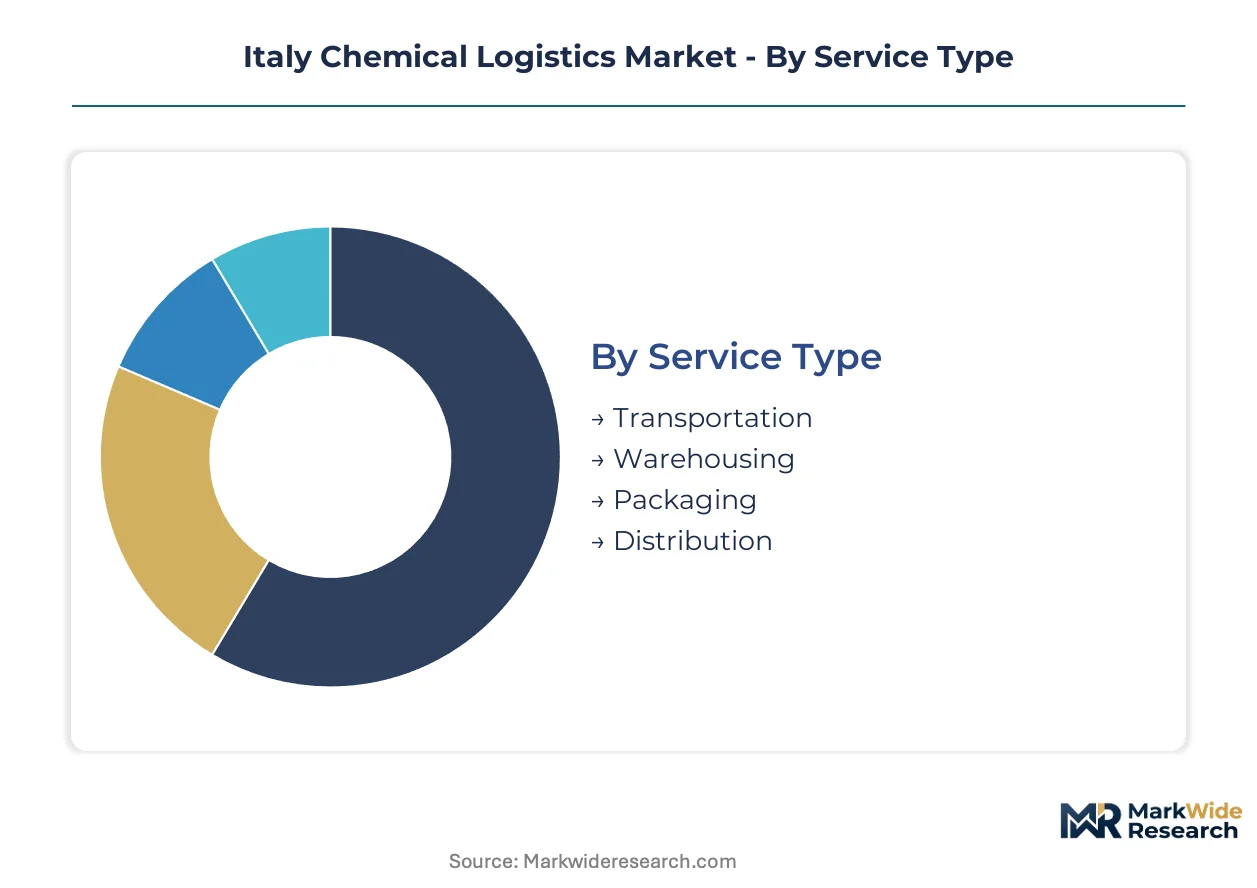
Italy's chemical logistics market fragments across service modalities, transport infrastructure, and end-use specifications that determine compliance burdens and margin profiles. Segmentation reveals where cold-chain investment concentrates versus commodity handling, exposing divergent growth trajectories across the Lombardy-Veneto corridor and southern port zones.
Service Type:
Temperature control specifications and hazardous materials certification requirements differentiate service tiers across northern Italy's chemical corridor.
- Transportation:ADR-compliant road haulage dominates revenue through dense manufacturing geography between Milan, Turin, and Ravenna. Pharmaceutical manufacturers in Lombardy are multiplying temperature-monitored truck requirements, pulling fleet investment toward refrigerated vehicle specifications.
- Warehousing:Cold-storage facilities with Seveso III high-tier controls command premium margins near Milan and Verona. Natural gas price volatility compresses heating and refrigeration economics, forcing automation investments to reduce labor exposure costs.
- Packaging:UN-certified container specifications for hazardous substances are tightening under EU CLP Regulation alignment. Demand concentrates at Ravenna port complexes where petrochemical import flows require compliant intermediate bulk container preparation.
- Distribution:Cross-border consolidation into Slovenia and Austria anchors Raben Group's network density. Last-mile pharmaceutical delivery is fragmenting into smaller, compliance-intensive accounts as specialty manufacturers unbundle logistics from production contracts.
Mature deployment sits with Transportation. Newer deployment is concentrated in Warehousing.
Delivery Mode:
Intermodal combinations across the Po Valley are reshaping cost structures for hazardous materials movement.
- Road:Dense northern Italian manufacturing geography sustains truck dominance despite ADR driver scarcity. Real-time environmental monitoring and predictive routing algorithms are compressing transit times for temperature-sensitive shipments.
- Rail:Petrochemical flows from Ravenna port to inland Lombardy clusters are anchoring rail-road barge combinations. Bulk hazardous materials achieve per-unit cost reductions through dedicated chemical wagon specifications.
- Sea:Deep-water capacity at Gioia Tauro and Catania lags northern equivalents, offering first-mover expansion potential. Maritime chemical handling requires IMO-compliant documentation converging with EU REACH registration data.
- Air:Temperature-sensitive biologics and active pharmaceutical ingredients from Milan Malpensa are climbing the fastest, though volumes remain constrained by cargo capacity and security screening protocols.
Established infrastructure concentrates in Road. Emerging infrastructure investment targets Rail.
End Use Industry:
Pharmaceutical cold-chain requirements are displacing traditional bulk chemical freight flows across service provider portfolios.
- Pharmaceuticals:Biologics and injectables manufacturing in Turin and Milan are multiplying temperature-controlled storage and transport specifications. EMA compliance documentation and batch traceability requirements are converging with warehouse management platforms.
- Agrochemicals:Seasonal demand patterns in the Po Valley anchor intermodal freight flows with concentrated spring distribution windows. EU Green Deal carbon border adjustments are restructuring import documentation burdens for fertilizer and pesticide formulations.
- Paints:Specialty coatings manufacturers in Veneto require flammable liquid handling certifications and segregation protocols. VOC regulations under EU industrial emissions directives are tightening warehouse ventilation and fire suppression specifications.
- Petrochemicals:Bulk polymer and intermediate flows through Ravenna and Venice ports sustain commodity logistics volumes. Margins compress against pharmaceutical segments, though volume scale maintains network density for multi-modal operators.
Volume concentration persists in Petrochemicals. Margin expansion concentrates in Pharmaceuticals.
Packaging Type:
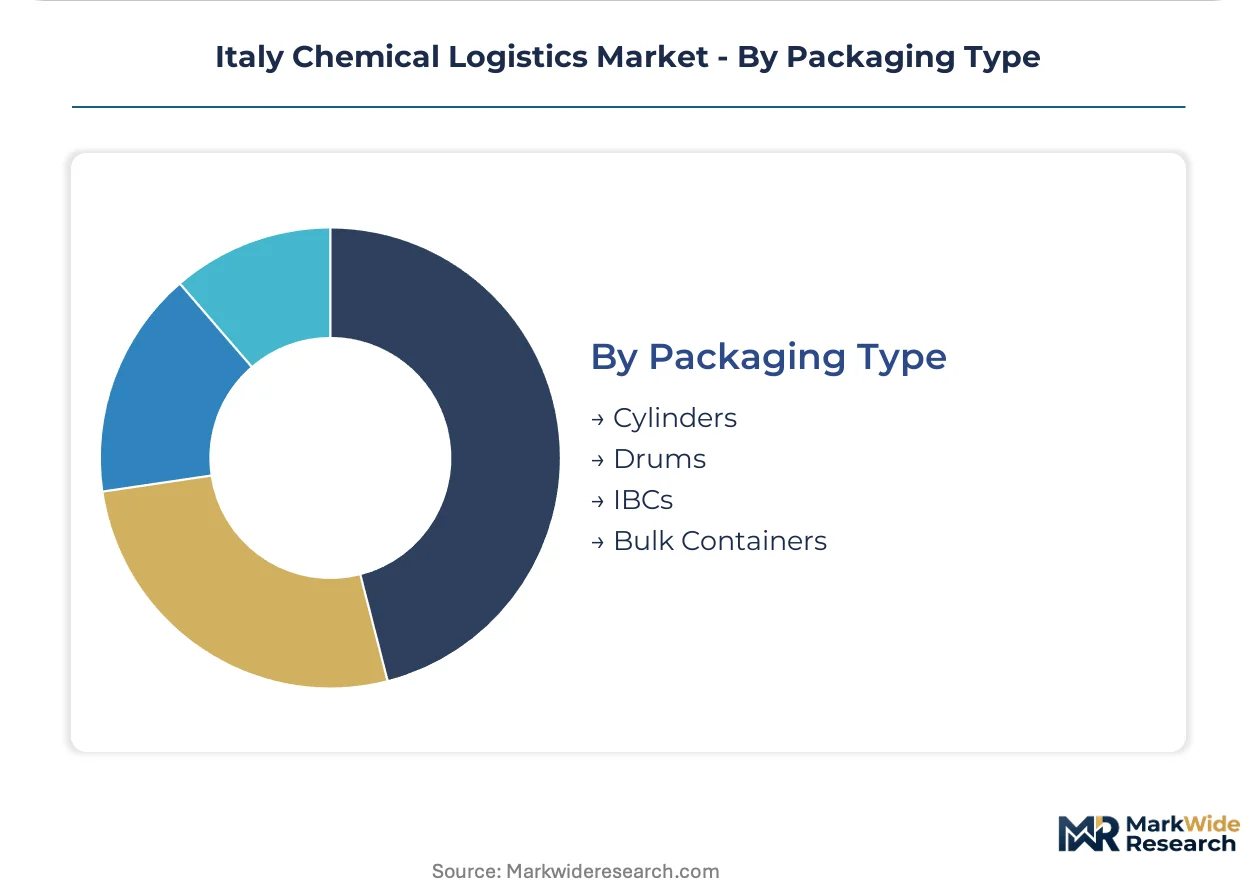
Container specifications directly determine segregation protocols and handling automation requirements under ECHA classification standards.
- Cylinders:Pressurized gas containment for industrial and medical applications requires specialized handling equipment and pressure testing documentation. Demand clusters near Milan's specialty chemical manufacturing zones.
- Drums:Standardized steel and fiber containers for mid-volume liquid chemicals dominate warehousing throughput. UN certification and reconditioning services concentrate at Ravenna port logistics parks.
- IBCs:Intermediate bulk containers enable efficient pharmaceutical and agrochemical distribution with reduced handling points. Reusable IBC pooling systems are gaining share fastest among sustainability-focused manufacturers.
- Bulk Containers:Tank containers and flexitanks for high-volume petrochemical flows achieve lowest per-unit logistics costs. Specialized cleaning and compatibility verification infrastructure anchors at port terminals.
Operational standardization centers on Drums. Technology investment is concentrating in IBCs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's chemical logistics demand concentrates in northern industrial corridors where pharmaceutical manufacturing clusters and petrochemical import flows anchor specialized cold-chain and hazardous materials infrastructure investments.
Lombardy
Milan's biologics and injectables manufacturers are multiplying temperature-controlled storage requirements under EMA compliance mandates. The region operates under Italy's national Seveso III implementation for high-tier hazardous site controls. Specialty pharmaceutical producers in the Milan metropolitan area are unbundling logistics from manufacturing contracts, pulling third-party cold-chain investment into temperature-monitored warehouse facilities.
Piedmont
Turin's active pharmaceutical ingredient manufacturers require continuous temperature documentation for EMA batch traceability. EU REACH registration requirements shape substance flow documentation across multi-modal handoffs. The Turin injectables manufacturing cluster is driving dedicated quality agreements with logistics providers as product stability requirements exceed in-house capabilities.
Veneto
Agrochemical seasonal demand patterns in the Po Valley anchor intermodal freight flows with concentrated spring distribution windows. EU Green Deal carbon border adjustments are restructuring import documentation burdens for fertilizer and pesticide formulations. Verona's cold-storage facilities with Seveso III high-tier controls command premium margins as natural gas price volatility compresses heating and refrigeration economics.
Emilia-Romagna
Ravenna port complexes sustain bulk polymer and intermediate flows through UN-certified container preparation and reconditioning services. The F-Gas Regulation is phasing down hydrofluorocarbon refrigeration, forcing warehouse retrofits in the Milan-Ravenna corridor. Petrochemical import volumes at Ravenna maintain network density for multi-modal operators serving commodity chemical segments.
Sicily
Catania's chemical handling capacity lags northern equivalents, offering first-mover expansion potential for temperature-certified operators. Maritime chemical handling at southern ports requires IMO-compliant documentation converging with EU REACH registration data. The underpenetrated southern port zone presents strategic opportunities for logistics providers with embedded emissions tracking capabilities under emerging EU Green Deal requirements.
Italy Chemical Logistics Market Competitive Landscape
Northern Italian operators anchor one tier; cross-border European specialists hold another through extensive road distribution networks. The vendor base organizes around three strategic archetypes: temperature-controlled warehousing specialists, hazardous materials certification providers, and multi-modal corridor operators. Competitive moves concentrate on fleet investment toward refrigerated vehicle specifications and warehouse automation to reduce labor exposure costs under national workplace chemical exposure limits.
Within the hazardous materials handling tier, FA Chemical Logistics S.R.L exemplifies certification-intensive service positioning for smaller compliance-demanding accounts. GDT Logistics occupies a position among temperature-controlled warehousing networks capturing pharmaceutical cold-chain expansion. Raben Group anchors cross-border distribution capabilities through road freight consolidation into adjacent European markets. These three operators represent divergent strategic responses to buyer fragmentation among specialty chemical manufacturers decoupling from traditional bulk petrochemical clients.
| Leading Market Players |
|---|
| GDT Logistics |
| FA Chemical Logistics S.R.L |
| Raben Group |
| Gruber Logistics |
| Noatum Logistics |
| DHL |
| Dachser Logistics |
| GEODIS |
| Rhenus Logistics |
| Others |
Pricing and Supply Chain Analysis
IoT-enabled cold-chain sensors are compressing cost economics for temperature-controlled warehousing while simultaneously concentrating supply among operators with capital reserves for real-time monitoring infrastructure. Pharmaceutical manufacturers in Lombardy now demand continuous environmental documentation, forcing smaller warehouse operators toward margin-negative compliance investments or exit.
Pricing Analysis
Volume concentration in petrochemical bulk logistics compresses margins against pharmaceutical cold-chain premiums. Three-tier pricing structure across EMA-certified premium, CLP-compliant standard, and commodity economy levels separates temperature-monitored pharmaceutical services from hazardous-certified industrial handling. Cost compression in the petrochemical tier intensifies because Ravenna port throughput sustains oversupply. Pharmaceutical buyers show least price sensitivity due to batch integrity requirements, while agrochemical distributors face seasonal margin pressure.
Supply Chain Analysis
Reusable IBC pooling systems are creating reverse-logistics revenue streams as sustainability-focused manufacturers demand container traceability back to reconditioning facilities. Supply concentrates in Italy's Lombardy-Veneto corridor, Germany's Rhine-Ruhr chemical cluster, and Belgium's Antwerp port complex. Raw material flows draw from North Sea petrochemical feedstocks, API imports from India and China, and specialty chemical intermediates from Switzerland. Single-source vulnerability sits with ADR-certified driver pools in northern Italian labor markets. Distribution runs through road-dominant networks with rail-barge intermodal anchoring bulk hazardous materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy chemical logistics market sits in a technology-transition phase as blockchain-enabled batch traceability replaces paper-based REACH documentation. Legacy warehouse management platforms face obsolescence against pharmaceutical client demands for real-time data integration.
For Market Incumbents: Deepen temperature-controlled infrastructure investment in Milan and Turin corridors before smaller competitors achieve Seveso III high-tier certification. Consolidate ADR-certified driver pools through acquisition or exclusive contracting to offset labor scarcity threatening cross-border operations. Anchor defensive positioning against digital-native entrants by embedding IoT sensor networks into existing warehouse management platforms. For New Entrants and Emerging Players: EU Green Deal carbon border adjustments in Italy open a window for emissions-tracking logistics services that incumbent platforms lack. Target underpenetrated Catania and Gioia Tauro port zones with temperature-certified warehousing before northern operators extend south. Pursue pharmaceutical quality agreements in Turin's injectables cluster as manufacturers unbundle logistics from production contracts. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to European multi-modal operators seeking Italian corridor density. Long-term viability favors vertically integrated cold-chain specialists with embedded pharmaceutical compliance capabilities over commodity petrochemical handlers. Monitor ADR driver wage inflation and F-Gas Regulation retrofit deadlines as inflection indicators for warehouse operator margin stress.| Strategic Initiative | Industry Significance |
|---|---|
| Seveso III High-Tier Certification Investment | Unlocks premium pharmaceutical warehousing margins in Milan metropolitan zone under ECHA safety protocols. |
| IoT Cold-Chain Platform Integration | Enables real-time temperature alerts for biologics shipments meeting EMA batch traceability mandates. |
| ADR Driver Pool Consolidation | Secures scarce certified labor against Raben Group's cross-border corridor expansion into Slovenia. |
| Southern Port First-Mover Expansion | Captures underpenetrated Catania chemical handling capacity before northern operators extend distribution networks. |
| Blockchain Emissions Documentation | Positions for EU Green Deal carbon border adjustment compliance as pharmaceutical clients mandate shipment-level tracking. |
Research Methodology
Italian customs data, ECHA substance flow registrations, and Cefic chemical logistics reports formed the secondary backbone of this analysis. Primary interviews with warehouse operations directors, pharmaceutical procurement leads, ADR-certified fleet managers, and dangerous goods safety advisors validated demand assumptions. Bottom-up facility capacity counts across Lombardy-Veneto corridors combined with top-down trade flow analysis to triangulate market sizing.
Historical trendline analysis of cold-chain infrastructure investment patterns informed projection frameworks across the analysis window. Segmentation modeling incorporated service modality, transport infrastructure, end-use industry, and regional regulatory cluster dimensions. CAGRs derived from weighted capacity expansion pipelines, pharmaceutical manufacturing growth trajectories, and energy cost elasticity assumptions for temperature-controlled facilities.
The model assumes a particular technology adoption path for IoT-enabled environmental monitoring; alternative pathways for blockchain traceability integration would alter the outlook if pharmaceutical buyers accelerate digital product passport requirements. Forecasts reflect assumptions about Seveso III implementation timelines, natural gas price stabilization, and ADR driver supply recovery. Practitioners should monitor EU Green Deal secondary legislation, F-Gas Regulation phase-down schedules, and EMA guidance on batch documentation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Hydrogen Tube Trailer Market
Fuels
Pyrolysis Gas Market
Fuels
Gas Feed System Market
Fuels
Coal Liquefaction Market
Fuels
Brazil Bunker Fuel Market
Fuels
Gasoline Octane Improvers Market
Fuels
North America Commercial Aircraft Aviation Fuel Market
Fuels
Gas and Solid Fuels (Wood) Fireplaces Market
Fuels
High Octane Racing Fuel Market
Fuels
Refuse Derived Fuel Market
Fuels
Mobile Gas Pumping System Market
Fuels
Hydrogen Fuel Tanks Market
Fuels
Gasoline As a Fuel Market
Fuels
India Coal Market
Fuels
Europe Aviation Fuel Market
Fuels
Hydrogen Cylinder Market