
 Oil Dispenser Market | 2026-2036
Oil Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Dispenser Market Analytics
A capital-intensity divergence between automated and manual production lines is reorganizing competitive hierarchies in the oil dispenser sector. OXO International Ltd. leverages consumer-centric design capabilities to dominate premium kitchen segments across North America. Bormioli Rocco anchors European glass-dispenser supply through integrated borosilicate manufacturing in Italy. IKEA competes on cost-engineered plastic formats with captive retail distribution spanning multiple continents.
An oil dispenser is a controlled-release vessel engineered to deliver lubricants, cooking oils, or industrial fluids through calibrated nozzles, pumps, or gravity-fed mechanisms, typically constructed with corrosion-resistant alloys or food-grade polymers to prevent contamination and ensure measured flow rates. Manual dispensers retain the largest installed base due to low maintenance requirements and minimal capital outlay, though automatic variants are capturing margin pools in high-throughput automotive and industrial settings. Metal construction leads in durability-critical applications such as marine engine rooms and heavy-equipment service bays, while plastic formats occupy cost-sensitive commercial kitchen procurement channels.
FDA food-contact regulations and EFSA migration limits govern material selection for culinary oil dispensers, compelling manufacturers to certify silicone gaskets and stainless steel grades for direct food exposure. EPA spill-prevention standards and OSHA workplace safety protocols shape industrial dispenser design in the United States, mandating secondary containment features and drip-free nozzle mechanisms. Stakeholders must monitor evolving PFAS restrictions and dual-carbon compliance deadlines in the European Union, as these frameworks will soon disqualify certain polymer formulations and energy-intensive glass-melting processes from qualified supply chains.
Market Dynamics
Commercial kitchens in Germany, the United Kingdom, and France are replacing legacy dispensing infrastructure to comply with EFSA migration limits on food-contact materials, forcing stainless steel and borosilicate glass formats into procurement pipelines previously dominated by polymer alternatives.
Growth Catalysts
- EFSA Migration Limits:European food-contact material standards are disqualifying polycarbonate and certain epoxy-lined dispensers from commercial kitchen supply chains, redirecting procurement toward certified stainless steel grades.
- Automotive Workshop Density:Germany's precision manufacturing cluster generates sustained demand for calibrated metal dispensers in maintenance bays serving industrial machinery and passenger vehicle fleets.
- Dual-Carbon Compliance Deadlines:EU Green Deal targets are accelerating capital deployment into energy-efficient glass-melting and metal-forming processes that reduce Scope 1 emissions in dispenser manufacturing.
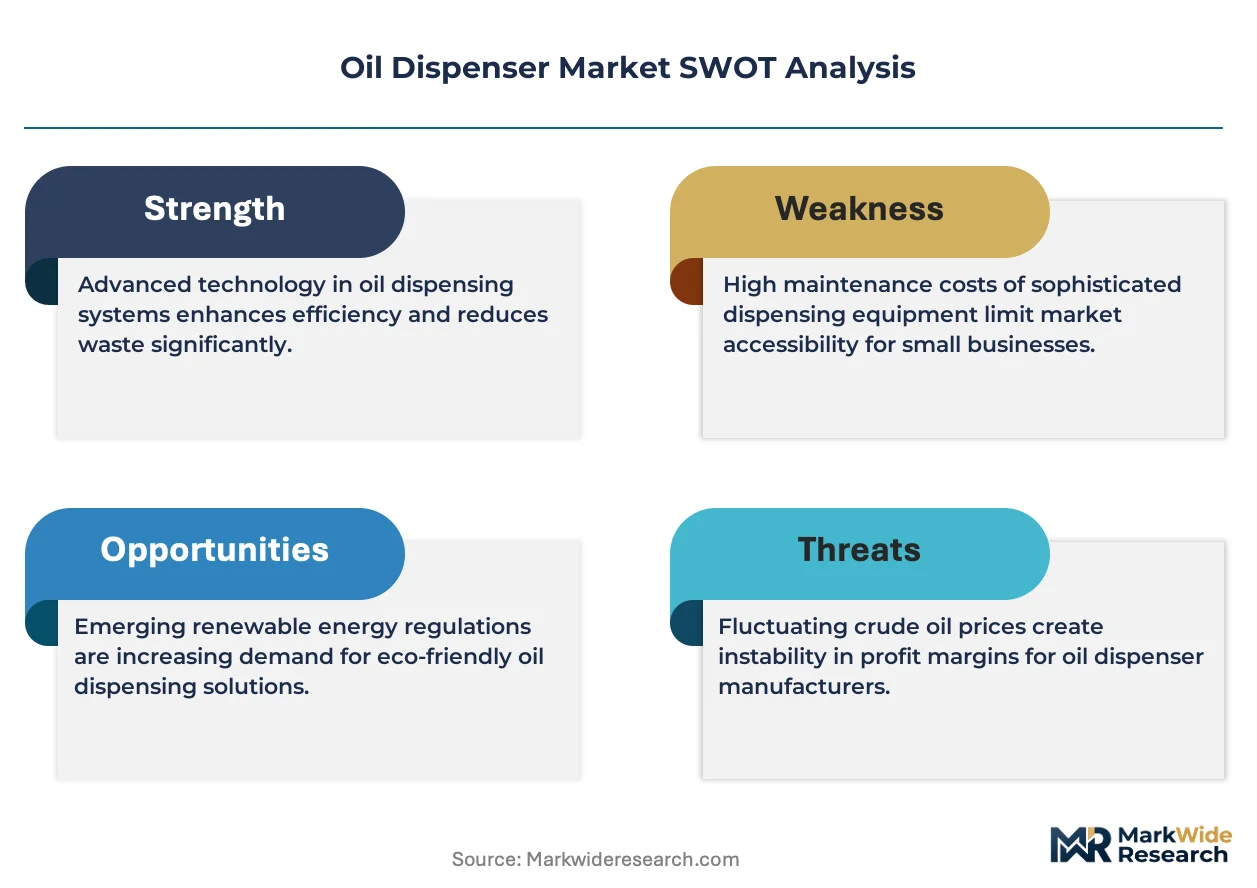
Market Restraints
- Nickel and Chromium Price Volatility:Stainless steel 304 and 316 input costs fluctuate with London Metal Exchange pricing, compressing margins for precision-engineered dispenser producers serving price-sensitive institutional buyers.
- Italian Borosilicate Concentration:European glass-dispenser supply chains depend heavily on integrated manufacturing in Italy's Veneto region, creating vulnerability to localized energy cost spikes or logistics disruptions.
- PFAS Substitution Complexity:REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of non-stick interior coatings and gasket materials without fully validated alternatives for high-temperature oil exposure.
Strategic Opportunities
- Central and Eastern Europe:Poland, Czechia, and Romania exhibit underpenetrated commercial kitchen infrastructure relative to Western European saturation, with accelerating foodservice investment creating first-mover positioning for compliant dispenser suppliers.
- IoT-Enabled Flow Monitoring:Convergence of precision dosing mechanisms with connected sensor networks enables predictive maintenance and usage-analytics offerings for industrial lubricant dispensing contracts.
- CSRD Reporting Requirements:Corporate Sustainability Reporting Directive mandates are driving large foodservice operators toward dispensers with verified lifecycle carbon footprints and recyclable end-of-life pathways.
Industry Challenges
- Multi-Material Certification Timelines:FDA and EFSA parallel approval processes for novel silicone gasket compounds and composite vessel constructions extend product development cycles by 18-24 months.
- Legacy Equipment Integration:Automated dispensing systems face retrofit complexity in established commercial kitchens with non-standardized fill ports and proprietary cleaning protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Dispenser Market |
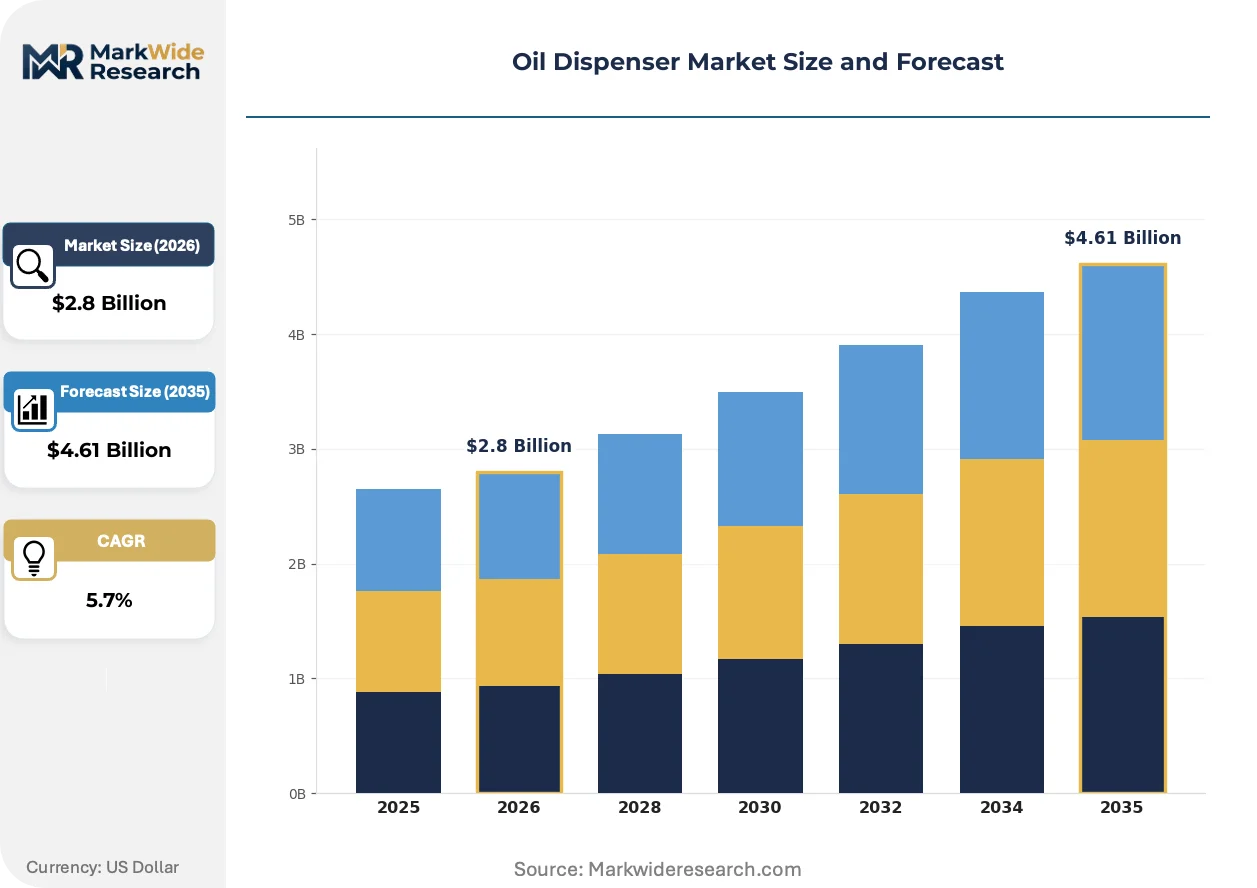
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Manual, Automatic, Pneumatic, Gravity Application: Automotive, Industrial, Marine, Commercial Material: Metal, Plastic, Composite, Rubber Installation: Wall-mounted, Mobile, Stationary, Portable |
| Companies Covered | OXO International Ltd., Prepara, Libbey Inc., Casabella, Emmeistar, IKEA, Bormioli Rocco, Harold Import Co., Tablecraft Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Dispenser Market Evolving Landscape
Dispenser technology is bifurcating between connected precision systems for industrial lubricant management and simplified mechanical formats for foodservice, with material science advances enabling thinner-walled stainless steel constructions without sacrificing corrosion resistance.
Piezoelectric dosing mechanisms are fragmenting traditional pump-based dispenser architectures in high-precision automotive and aerospace maintenance applications. Tier-1 suppliers in Stuttgart and Munich are piloting solid-state flow control for synthetic lubricants. This shift is fragmenting the installed base between electromechanical legacy systems and solid-state replacements with fewer wear components.
REACH Annex XVII restrictions on intentionally added microplastics are compelling reformulation of dispenser components across EU member states. Manufacturers must eliminate certain polymer additives from nozzle tips and valve seats. Food-grade dispenser segments in France and Spain are accelerating stainless steel and ceramic component adoption ahead of enforcement deadlines.
Foodservice procurement departments are consolidating vendor relationships and demanding multi-year total-cost-of-ownership contracts rather than transactional equipment purchases. Large contract catering operators in the United Kingdom and Netherlands are unbundling dispenser supply from broader kitchen-equipment packages. This consolidation is most visible in institutional catering contracts for healthcare and education facilities.
Oil Dispenser Market Segmentation
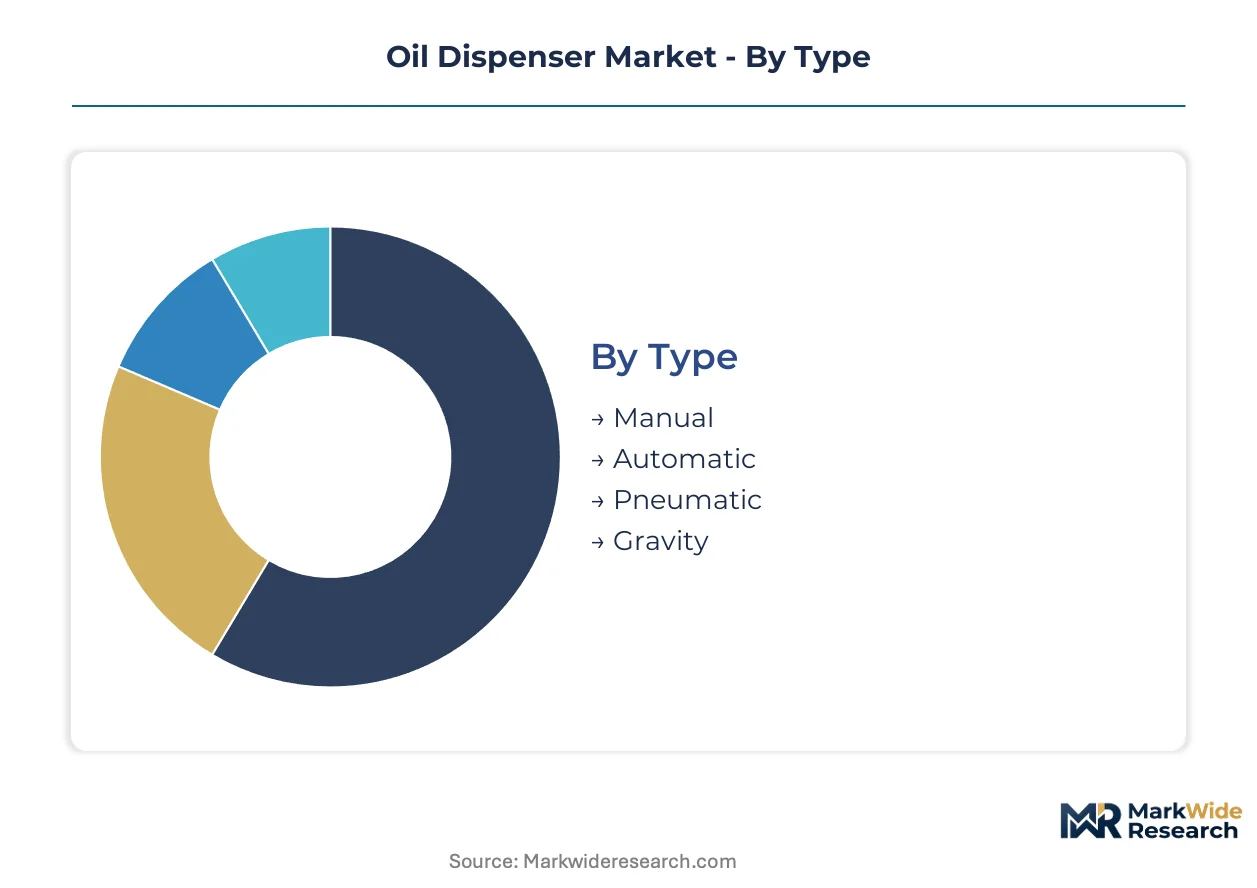
Oil dispenser procurement channels diverge sharply by operational intensity. Foodservice buyers favor mechanical simplicity and minimal maintenance, while industrial maintenance contracts demand precision dosing and connectivity integration.
Type:
Channel mix varies by capital intensity: manual units dominate mass-market retail and foodservice catalogs, while automatic and pneumatic systems flow through industrial distributor networks and direct OEM procurement.
- Manual:Gravity-fed or pump-actuated mechanisms requiring no electrical power, constructed with food-grade polymers or coated metals for corrosion resistance. Demand concentrates in commercial kitchens across Germany and France, where EFSA compliance deadlines are disqualifying older polycarbonate vessels and redirecting procurement toward certified stainless steel alternatives.
- Automatic:Electromechanical or sensor-triggered dispensing systems with programmable flow rates and integrated metering. Automotive workshops in Stuttgart and Munich generate sustained demand for calibrated metal dispensers serving synthetic lubricant specifications, with precision manufacturing clusters requiring consistent dosing accuracy for warranty compliance.
- Pneumatic:Compressed-air-driven systems delivering high-volume dispensing for heavy-equipment service bays.
- Gravity:Simple elevated-reservoir designs common in cost-sensitive institutional catering procurement.
By volume, manual leads. By growth pace, automatic is climbing the fastest.
Application:
Cost tier stratification separates premium precision systems from standardized mechanical formats across end-use verticals.
- Automotive:Calibrated dispensers for engine oils, transmission fluids, and synthetic lubricants requiring viscosity-specific flow control. Germany's passenger vehicle fleet density and industrial machinery base sustain demand for metal-constructed units with drip-free nozzle mechanisms, with Tier-1 suppliers piloting solid-state flow control in Stuttgart maintenance facilities.
- Commercial:Food-grade vessels for culinary oil storage and portion control in professional kitchens. United Kingdom and Netherlands contract catering operators are unbundling dispenser supply from broader kitchen-equipment packages, demanding multi-year total-cost-of-ownership contracts with verified lifecycle documentation.
- Industrial:Heavy-duty systems for manufacturing plant lubrication circuits and hydraulic fluid management.
- Marine:Corrosion-resistant alloy dispensers for engine rooms with salt-exposure specifications.
Automotive commands the highest unit margins. Commercial delivers the steepest expansion trajectory as EFSA migration limits force replacement cycles.
Material:
Supply concentration in Italian borosilicate and German stainless steel creates geographic dependency for premium segments.
- Metal:Stainless steel 304 and 316 grades with FDA-certified silicone gaskets for direct food contact. Precision-engineered variants serve both automotive workshops and high-end culinary environments in Germany, where dual-carbon compliance deadlines are accelerating capital deployment into energy-efficient metal-forming processes.
- Plastic:Cost-engineered polymer formats occupying price-sensitive commercial kitchen procurement channels, though REACH Annex XVII microplastic restrictions are compelling reformulation of nozzle tips and valve seats ahead of enforcement deadlines.
- Composite:Multi-material constructions combining corrosion resistance with weight reduction for specialized industrial applications.
- Rubber:Gasket and seal components subject to PFAS substitution complexity under evolving restrictions.
Metal dominates durability-critical applications. Plastic retains volume leadership in transactional procurement.
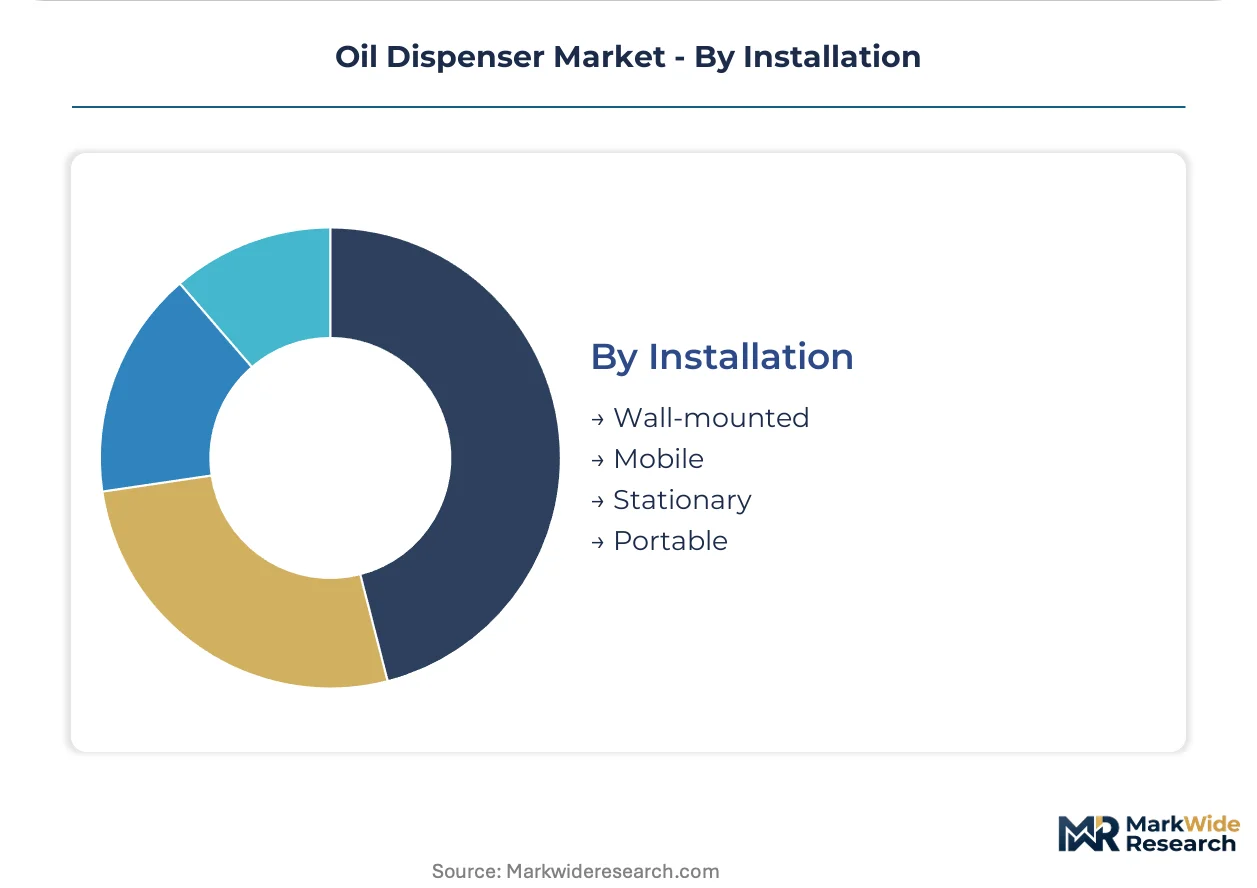
Installation:
Maturity gradients separate established stationary formats from emerging connected mobile systems.
- Wall-mounted:Fixed-position units maximizing counter space in compact commercial kitchens. France and Spain are accelerating stainless steel and ceramic component adoption ahead of REACH enforcement deadlines, with healthcare and education facilities consolidating vendor relationships.
- Mobile:Wheeled or cart-based systems enabling flexible positioning across service bays. Central and Eastern European markets exhibit underpenetrated infrastructure relative to Western saturation, with Poland and Czechia foodservice investment creating positioning opportunities for compliant suppliers.
- Stationary:Floor-mounted industrial systems with integrated secondary containment.
- Portable:Hand-carried formats for field maintenance and remote lubrication tasks.
Wall-mounted holds the largest installed base. Mobile formats are gaining share fastest as IoT-enabled flow monitoring converges with precision dosing mechanisms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany exhibit low price elasticity for precision-engineered stainless steel dispensers, while foodservice operators in Poland and Czechia remain highly sensitive to unit costs. This demand-elasticity contrast shapes regional procurement patterns and supplier positioning strategies across European markets.
Germany
Automotive workshop density and commercial kitchen upgrading sustain demand for calibrated metal dispensers. EFSA migration limits are disqualifying polycarbonate vessels from foodservice procurement pipelines. Stuttgart and Munich precision manufacturing clusters are piloting solid-state flow control systems for synthetic lubricant specifications.
United Kingdom
Contract catering operators are unbundling dispenser supply from broader kitchen-equipment packages. CSRD reporting requirements are driving large foodservice operators toward dispensers with verified lifecycle carbon footprints. Healthcare and education facilities in England are consolidating vendor relationships around multi-year total-cost-of-ownership contracts.
France
Healthcare catering contracts are accelerating stainless steel and ceramic component adoption ahead of REACH Annex XVII enforcement deadlines. ANSM food-contact material oversight is tightening certification requirements for silicone gaskets. Paris and Lyon institutional foodservice markets are demanding compliant wall-mounted formats for compact kitchen layouts.
Poland
Underpenetrated commercial kitchen infrastructure relative to Western European saturation creates first-mover positioning opportunities. Foodservice investment is accelerating across Warsaw and Kraków metropolitan areas. Cost-sensitive procurement channels favor plastic formats, though EFSA-aligned upgrading is redirecting some demand toward certified stainless steel alternatives.
Italy
Integrated borosilicate manufacturing in the Veneto region anchors European glass-dispenser supply chains. EU Green Deal dual-carbon compliance deadlines are accelerating capital deployment into energy-efficient glass-melting processes. Localized energy cost spikes in northern Italy create vulnerability for premium glass-dispenser production continuity.
Oil Dispenser Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the oil dispenser sector. The market structure is moderately fragmented, with distinct tiers separating precision-engineered metal specialists from mass-market plastic fabricators. Three strategic archetypes dominate: design-centric consumer brands, integrated glass manufacturers, and cost-engineered retail distributors. Competitive moves concentrate on portfolio diversification into compliant material formats and geographic expansion into underpenetrated Central European markets.
Within the design-centric tier, OXO International Ltd. and Prepara exemplify consumer-facing innovation archetypes. Bormioli Rocco occupies a position representing integrated European glass manufacturing heritage. IKEA anchors the cost-engineered, captive-distribution archetype with multi-continent retail presence. Libbey Inc. and Casabella sit within mid-market positioning between premium design and mass accessibility.
| Leading Market Players |
|---|
| OXO International Ltd. |
| Prepara |
| Libbey Inc. |
| Casabella |
| Emmeistar |
| IKEA |
| Bormioli Rocco |
| Harold Import Co. |
| Tablecraft Products Company |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day order-to-delivery windows for precision-engineered stainless steel dispensers concentrate pricing power with Italian and German manufacturers, compressing margins for distributors unable to secure forward capacity commitments. This lead-time band reflects dual-carbon compliance investments in energy-efficient metal-forming processes that constrain near-term supply elasticity.
Pricing Analysis
After-market service contracts and multi-year total-cost-of-ownership agreements generate lifetime value exceeding initial equipment sales by significant multiples. Three-tier pricing structure across premium certified-stainless, standard commercial-grade, and economy polymer formats separates procurement channels. Cost compression in economy plastic tiers is intensifying because REACH Annex XVII reformulation mandates are accelerating raw material substitution timelines. Institutional catering operators in France and the United Kingdom exhibit lowest price sensitivity, while independent foodservice buyers in Poland and Czechia remain highly elastic.
Supply Chain Analysis
Italy and Germany anchor European dispenser manufacturing through integrated borosilicate glass-melting in the Veneto region and precision metal-forming in Baden-Württemberg. Stainless steel 304 and 316 grades, FDA-certified silicone gaskets, and ceramic valve components constitute critical input dependencies. Single-source vulnerability concentrates in Italian borosilicate supply chains exposed to localized energy cost spikes. Distribution runs through industrial distributor networks for automotive and pneumatic systems, while captive retail channels and direct foodservice procurement dominate commercial kitchen segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as IoT-enabled flow monitoring transforms standalone dispensers into connected lubricant management nodes, with interoperability requirements favoring suppliers offering predictive maintenance software integration.
For Market Incumbents: Secure backward integration into certified silicone gasket manufacturing to insulate margins from PFAS substitution complexity. Lock in multi-year borosilicate supply agreements with Veneto-region glassworks ahead of EU Green Deal dual-carbon compliance deadlines. Solid-state flow control technologies from Stuttgart precision clusters threaten electromechanical legacy architectures.
For New Entrants and Emerging Players: Differentiate on CSRD-compliant lifecycle documentation and verified carbon footprint certification for contract catering operators in the Netherlands and United Kingdom. Target underpenetrated Central European markets—Poland, Czechia, and Romania—where EFSA-aligned upgrading is redirecting procurement toward compliant stainless steel alternatives. Pursue direct-to-institutional sales bypassing consolidated distributor networks.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automatic and pneumatic dispenser sub-segments as piezoelectric dosing mechanisms displace traditional pump architectures. Long-term viability favors suppliers with demonstrated FDA and EFSA parallel certification capabilities and captive IoT platform development. The signal to watch is Tier-1 automotive supplier adoption of solid-state flow control in Stuttgart and Munich maintenance facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gasket Manufacturing | Captive silicone production insulates margins from REACH PFAS substitution timelines. |
| IoT Platform Development | Predictive maintenance offerings capture recurring revenue from industrial lubricant contracts. |
| CSRD Compliance Certification | Verified lifecycle documentation unlocks large foodservice operator procurement pipelines. |
| Central European Geographic Expansion | First-mover positioning in Poland and Czechia leverages EFSA-aligned replacement cycles. |
| Solid-State Flow Control R&D | Piezoelectric dosing mechanisms fragment legacy pump architectures in automotive applications. |
Research Methodology
Initial hypotheses were tested against primary input from foodservice procurement directors, automotive maintenance facility managers, commercial kitchen equipment distributors, and regulatory affairs specialists at stainless steel fabricators, then refined through secondary validation. Trade data from Eurostat and national customs authorities, EFSA migration limit documentation, SEC filings from listed kitchen equipment manufacturers, and industry association reports from Cefic and Foodservice Equipment Association sources anchored quantitative triangulation. Bottom-up demand modeling across manual, automatic, and pneumatic dispenser categories converged with top-down market sizing.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within each segmentation dimension: dispenser type, application vertical, material grade, and installation format. CAGRs were derived from installed base replacement cycles, EFSA compliance deadline enforcement schedules, and automotive workshop density projections. Forecast inputs incorporate synthetic lubricant specification shifts in German precision manufacturing clusters and REACH Annex XVII enforcement timelines for microplastic additives.
Material uncertainties—nickel and chromium price volatility, Italian energy cost spikes, PFAS substitution validation delays—sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and supply chain continuity. Recalibration cycles align with material shifts in EFSA migration limit revisions and EU Green Deal dual-carbon compliance milestone dates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Composite Overwrapped Pressure Vessels (Copvs) Market
Fuels
North America Bunker Fuel Market
Fuels
Global Wood Gas Generator Market
Fuels
Hybrid Propellants Market
Fuels
Canada Coal Market
Fuels
Palm Methyl Ester Market
Fuels
North America Commercial Aircraft Aviation Fuel Market
Fuels
South America Defense Aircraft Aviation Fuel Market
Fuels
Coal Gasification Market
Fuels
Waste-Derived Pyrolysis Oil Market
Fuels
Renewable Heating Fuels Market
Fuels
Turbine Drip Oil Market
Fuels
Mobile Gas Pumping System Market
Fuels
Italy Automotive Engine Oils Market
Fuels
Carbonizers Market
Fuels
Alcohol-To-Jet (ATJ) Fuel Market