
 Emergency Food Market | 2026-2036
Emergency Food Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency Food Market Intelligence
Emergency food distribution through retail stores is fragmenting as online platforms and direct-to-consumer channels capture procurement from traditional outlets. Mountain House leverages its freeze-drying expertise to sustain premium positioning in outdoor and preparedness segments. Wise Company anchors its competitive stance through bulk bucket packaging that dominates warehouse club channels. Augason Farms differentiates via deep SKU breadth spanning grains, dairy, and complete meals.
Emergency food comprises shelf-stable nutrition products engineered for extended storage without refrigeration, typically achieving 10–25 year shelf lives through moisture reduction, oxygen exclusion, and thermal processing in barrier packaging. The category serves civilian preparedness, institutional stockpiling, and field deployment where conventional supply chains face disruption. Freeze-dried meals command premium positioning due to lightweight logistics and flavor retention, while ready-to-eat packets drive volume through military and disaster relief procurement. Government agencies represent a concentrated margin pool where multi-year contracts favor suppliers with USDA certification and SQF-compliant facilities.
The FDA governs nutritional content claims and allergen labeling under FALCPA, while the USDA inspects commercial emergency food production through its FSIS arm for products containing meat or poultry. Military procurement falls under Defense Logistics Agency specifications that mandate precise caloric density, shelf-life testing protocols, and packaging durability under extreme conditions. Stakeholders must monitor evolving FEMA preparedness grant allocations and shifting defense ration modernization priorities to align capacity investments with institutional demand trajectories.
Market Dynamics
NATO military procurement expansion is compressing supplier qualification timelines while FEMA preparedness grant cycles create demand spikes that strain freeze-drying and retort production capacity. Shelf-life certification bottlenecks at USDA FSIS facilities now govern entry velocity more than capital availability.
Growth Catalysts
- Defense Logistics Agency ration modernization:Multi-year shelf-stable contracts require SQF-compliant facilities, pulling private capital into thermal processing and barrier packaging upgrades.
- FEMA coordination protocols:Pre-positioned stockpile mandates in the United States generate concentrated procurement volumes that validate long-lead equipment investments.
- Freeze-drying yield improvements:Vacuum sublimation cycle optimization cuts energy input per kilogram, expanding addressable price points in civilian preparedness segments.
Market Restraints
- Aluminum foil laminate supply concentration:Three domestic converters control high-barrier pouch supply, exposing ration packagers to input volatility when defense contracts surge.
- USDA FSIS inspection queue:Meat-containing meal kits face 14-18 month certification timelines, freezing formulation pipelines regardless of R&D completion.
- Retort pouch substitution pressure:Aseptic carton and glass jar formats compete for institutional shelf-stable contracts where weight logistics matter less.
Strategic Opportunities
- Direct-to-consumer subscription channels:Monthly preparedness box models bypass retail slotting fees and capture lifetime value through auto-renewal nutrition planning.
- Inflation Reduction Act domestic content incentives:Clean energy manufacturing credits extend to food processing equipment, reducing capex burden for US-based thermal processing expansion.
- Plant-protein ration development:Pea and mycelium protein isolates meet emerging NATO allergen-reduction specifications while opening kosher and halal procurement pools.
Industry Challenges
- Retort operator skill scarcity:Thermal processing certification programs at community colleges cannot match demand for validated process authority personnel.
- Legacy ERP integration with track-and-trace mandates:USDA Bioengineered Food Disclosure compliance requires lot-level serialization that strains paper-based inventory systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emergency Food Market |
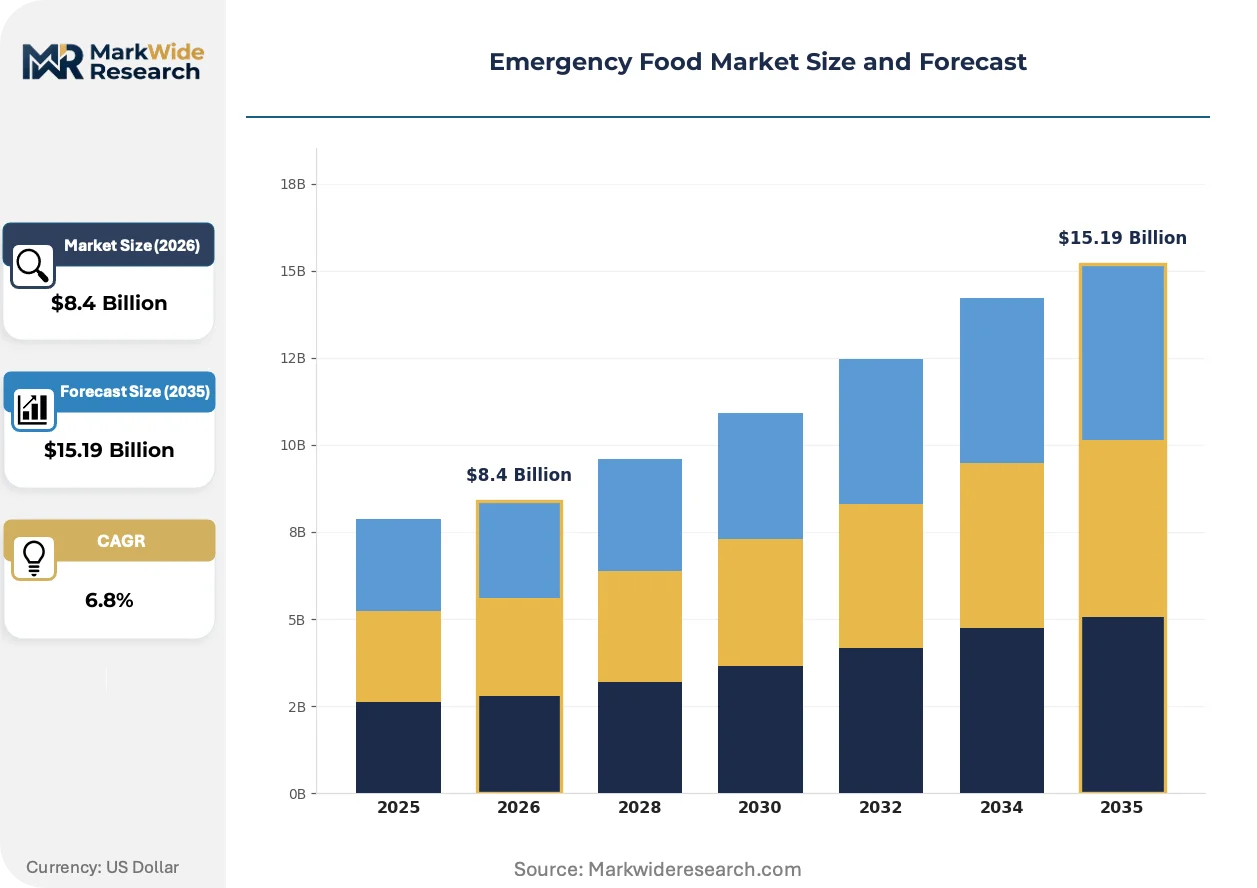
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freeze-Dried Meals, Canned Goods, Ready-to-Eat Packets, Snacks Distribution Channel: Retail Stores, Online Platforms, Emergency Supply Outlets, Government Agencies End User: Households, NGOs, Military, Disaster Relief Organizations Packaging Type: Buckets, Pouches, Cans, MREs |
| Companies Covered | Legacy Food Storage, Nutrient Survival, Mountain House, Valley Food Storage, 4Patriots, Augason Farms, Wise Company, Ready Hour, ReadyWise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency Food Market Strategic Shifts & Innovations
Active packaging intelligence and protein diversification are rewriting formulation priorities. Suppliers now compete on oxygen scavenger integration and mycelium protein functionality rather than shelf-life extension alone.
High-barrier multilayer films are migrating from aluminum-oxide-coated PET to bio-based ethylene vinyl alcohol copolymers. Military packagers in the United States and Germany are piloting these structures for 10-year ration applications. The shift is compressing reliance on aluminum supply chains while demanding new accelerated aging protocols.
The EU Green Deal packaging waste regulations now mandate recyclability thresholds for food contact materials by 2030. Emergency food exporters to Europe must reformulate barrier layers or forfeit institutional contracts. French and Dutch defense procurement offices are already inserting circularity scoring into technical evaluation criteria.
Preparedness buyers now favor modular calorie-bank systems over complete meal kits. Outdoor retailers and urban preppers assemble custom nutrition stacks from component SKUs rather than accepting fixed-menu buckets. This unbundling is most visible in Pacific Northwest and Rocky Mountain states where earthquake and wildfire risk concentrates hobbyist demand.
Emergency Food Market Segmentation
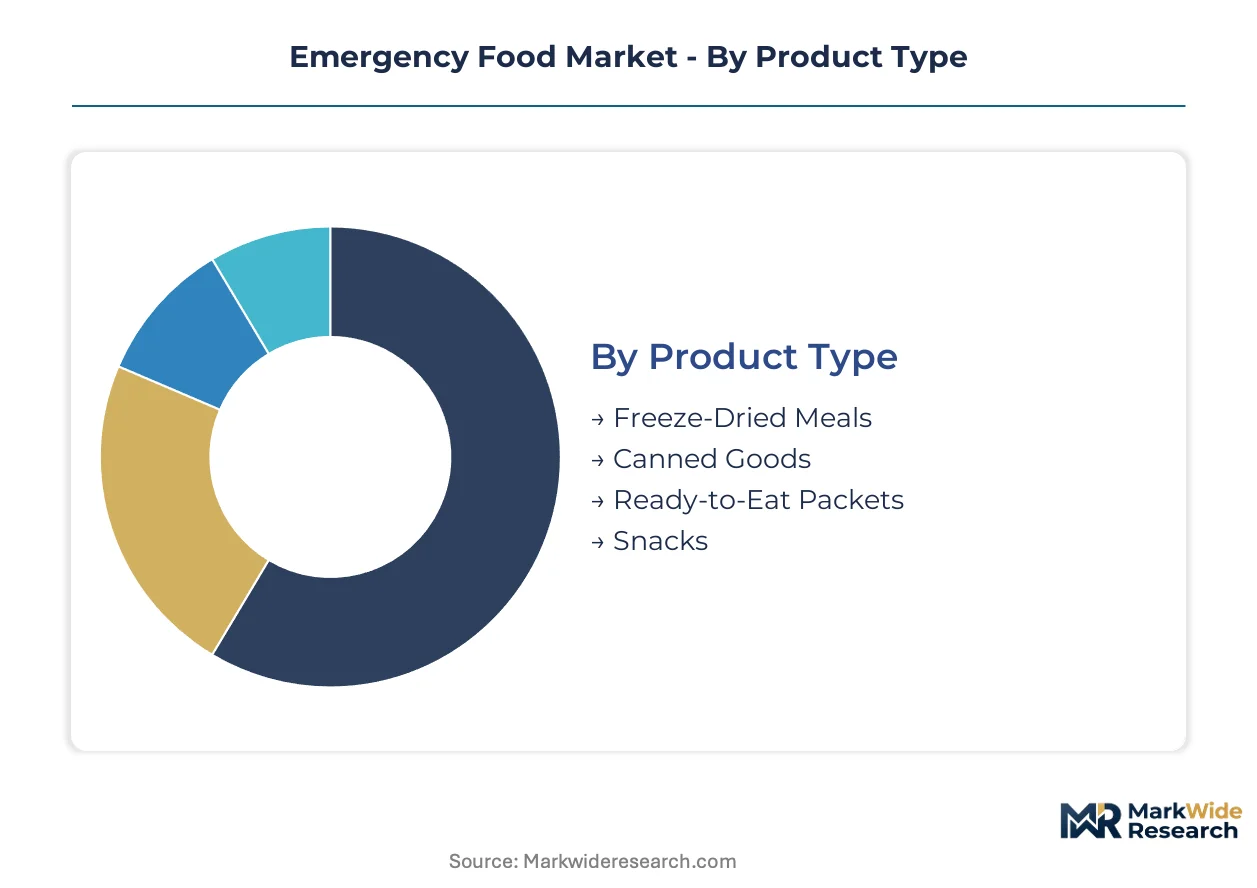
Emergency food segmentation reveals how shelf-life engineering, procurement protocols, and logistics constraints split demand across incompatible supply chains. Each dimension carries distinct margin profiles and qualification barriers that determine supplier viability.
Product Type:
Use-case spectrum spans ultralight expedition nutrition to mass-casualty institutional feeding, with thermal processing intensity and moisture reduction degree determining addressable channels.
- Freeze-Dried Meals:Vacuum sublimation removes 98% moisture while preserving cellular structure, enabling 25-year shelf stability. Demand concentrates in Pacific Northwest preparedness retail and NATO special operations procurement, where weight-to-calorie ratio governs pack-out decisions. Premium positioning reflects energy-intensive batch processing and oxygen-scavenger pouch integration.
- Canned Goods:Thermal processing in tinplate or aluminum vessels achieves commercial sterility through retort sterilization. Institutional stockpiling in FEMA-designated corridors and rural Mormon community procurement sustain volume, though pallet density disadvantages limit military adoption.
- Ready-to-Eat Packets:Retort pouches with aluminum foil laminates deliver ambient-stable nutrition without rehydration. Military and disaster relief procurement drives volume through Defense Logistics Agency indefinite-delivery contracts.
- Snacks:High-energy bars and nut mixes target recreational outdoor users with shorter shelf-life tolerance and flavor-forward formulation.
The dominant share belongs to Ready-to-Eat Packets, while Freeze-Dried Meals is closing the gap fastest.
Distribution Channel:
Cost tier stratification separates high-touch retail slotting from automated direct fulfillment, with government procurement operating on sealed-bid protocols that bypass commercial pricing entirely.
- Retail Stores:Big-box outdoor chains and warehouse clubs demand palletized display packaging and promotional allowance budgets that freeze out smaller formulators. Mountain states and Florida hurricane corridors show highest sell-through velocity.
- Online Platforms:Direct-to-consumer subscriptions and marketplace listings bypass slotting fees while capturing lifetime value through auto-renewal preparedness planning. SEO competition for "long-term food storage" keywords drives customer acquisition costs upward.
- Emergency Supply Outlets:Specialized preparedness retailers in Utah, Idaho, and Texas offer curated SKU breadth and in-person consultation that converts first-time buyers.
- Government Agencies:FEMA, Defense Logistics Agency, and state emergency management offices issue multi-year indefinite-quantity contracts with SQF certification and USDA inspection prerequisites that filter supplier pools.
Online Platforms command expanding share through subscription economics, while Government Agencies deliver the steepest margin premiums for qualified suppliers.
End User:
Volume concentration varies by procurement mechanism, from fragmented household preparedness budgeting to concentrated military ration modernization programs with congressional appropriation cycles.
- Households:Individual and family-level stockpiling responds to localized risk perception—earthquake zones, hurricane corridors, wildland-urban interface. Purchase timing correlates with disaster events and election cycles.
- NGOs:Catholic Relief Services, World Vision, and similar organizations procure for international disaster response, prioritizing low-cost caloric density over extended shelf life.
- Military:Defense Logistics Agency manages shelf-stable ration contracts with precise nutritional specifications, packaging durability standards, and three-year menu rotation mandates.
- Disaster Relief Organizations:State-level emergency management agencies and Red Cross chapters maintain pre-positioned stockpiles with FEMA grant funding, requiring rapid deployment logistics.
Military procurement anchors contract value, while Households represent the broadest addressable base with highest customer acquisition variance.
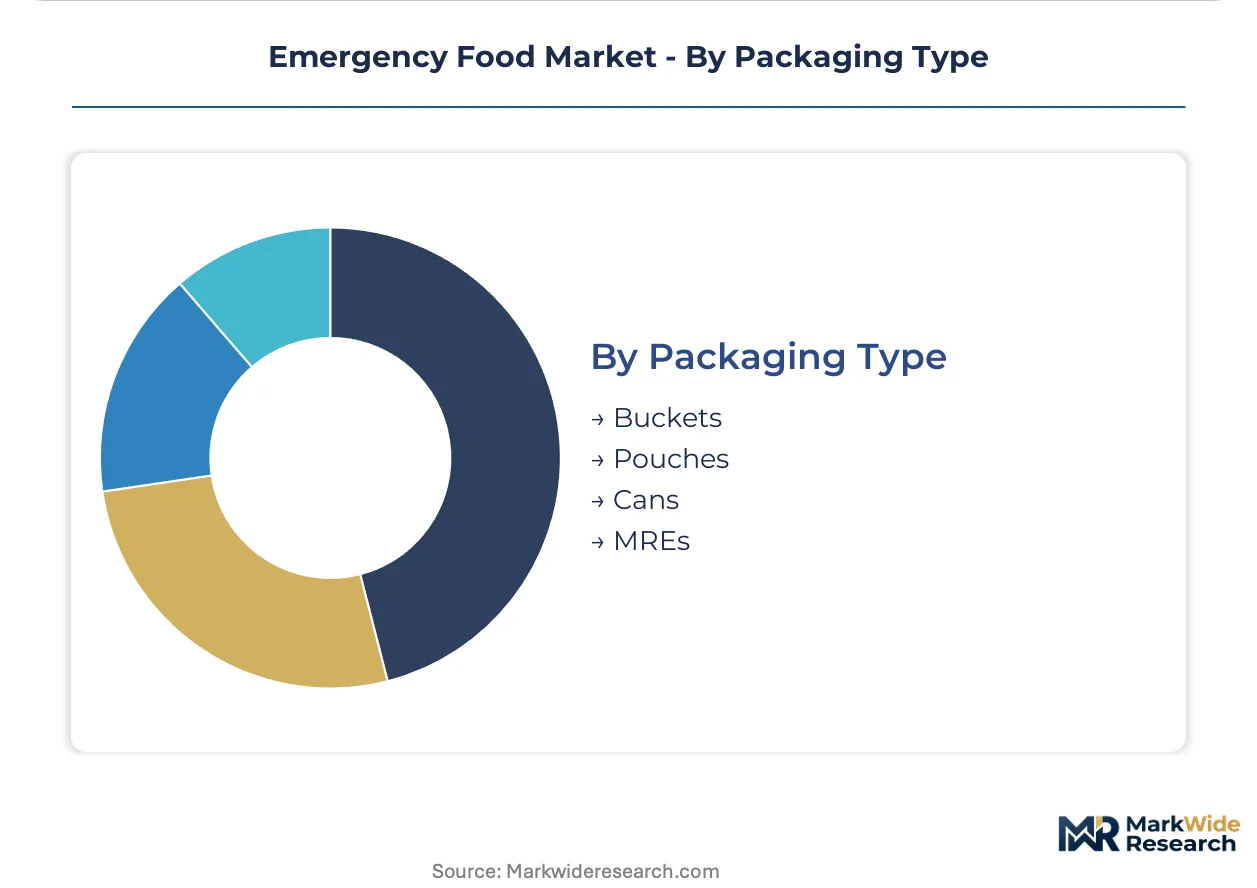
Packaging Type:
Supply concentration in aluminum foil laminate and retort pouch manufacturing creates input bottlenecks that constrain formulation flexibility across all container formats.
- Buckets:Polypropylene pails with gamma-sealed lids dominate warehouse club and direct-to-consumer channels, offering stackable logistics and moisture barrier protection for bulk grain and meal kit assortments.
- Pouches:Multilayer aluminum-oxide-coated or EVOH barrier films enable lightweight field deployment. Military and outdoor recreation segments drive specification evolution toward puncture resistance and tear-notch accessibility.
- Cans:Tinplate and aluminum two-piece containers sustain institutional procurement where opening tool availability is assumed and weight constraints are secondary.
- MREs:Meal, Ready-to-Eat cases integrate entree, side, accessory, and flameless ration heater in military-specific packaging with NSN cataloging and palletized deployment configuration.
Buckets retain dominant civilian share through retail visibility, while Pouches gain ground fastest in military specification updates and ultralight outdoor segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors North American emergency food logistics, handling containerized freeze-dried ingredients and retort pouch materials that feed domestic thermal processing clusters.
United States
FEMA pre-positioned stockpile mandates drive concentrated procurement volumes along hurricane corridors and seismic zones. The FDA and USDA FSIS enforce shelf-life certification standards that govern formulation pipelines regardless of R&D completion. Utah's Wasatch Front hosts the densest cluster of freeze-drying facilities and preparedness retail distribution centers.
Germany
Bundeswehr ration modernization programs expand contracts for lightweight field nutrition with extended stability requirements. The EU Green Deal packaging waste regulations mandate recyclability thresholds by 2030, forcing barrier layer reformulation. Bavaria's food technology corridor pilots bio-based ethylene vinyl alcohol copolymers for military ration applications.
United Kingdom
Strategic stockpiling protocols for island supply disruption scenarios sustain institutional demand for ambient-stable nutrition. Food Standards Agency allergen labeling requirements align with emerging NATO allergen-reduction specifications. The Midlands manufacturing belt concentrates retort pouch assembly and military contract fulfillment operations.
Japan
Metropolitan earthquake preparedness drives household-level stockpiling with strict space-constraint specifications favoring compact packaging. METI industrial standards govern extended shelf-life claims and accelerated aging protocols. The Chubu region around Nagoya hosts specialized barrier film converters serving defense and civilian preparedness markets.
Australia
Bushfire and flood response frameworks generate state-level emergency management procurement with rapid deployment requirements. Food Standards Australia New Zealand enforces nutritional content verification for institutional contracts. Queensland's food processing corridor specializes in retort production for Pacific disaster relief supply chains.
Emergency Food Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying thermal processing capacity and barrier packaging substrates. The vendor base arranges across three functional tiers: freeze-drying platform operators, retort pouch assemblers, and bulk ingredient processors. Strategic archetypes include vertically integrated preparedness brands, contract manufacturing specialists, and private-label warehouse club suppliers. Dominant competitive moves center on SQF certification acquisition for government contract eligibility and direct-to-consumer subscription channel development.
Within the vertically integrated tier, Mountain House and Wise Company exemplify platform control spanning formulation through branded distribution. Augason Farms anchors the SKU breadth archetype with component-level assortment strategies. These three entities represent contrasting approaches to civilian preparedness segmentation: expedition-grade positioning, warehouse club volume capture, and modular calorie-bank systems respectively.
| Leading Market Players |
|---|
| Legacy Food Storage |
| Nutrient Survival |
| Mountain House |
| Valley Food Storage |
| 4Patriots |
| Augason Farms |
| Wise Company |
| Ready Hour |
| ReadyWise |
| Others |
Cost & Logistics Intelligence
The Port of Long Beach freight corridor shapes cost dynamics across the emergency food value chain, compressing margins for inland freeze-drying operators while enabling price differentiation between SQF-certified government suppliers and uncertified civilian entrants.
Pricing Analysis
Volume-discount tiering structures separate Defense Logistics Agency contract holders from direct-to-consumer subscription operators. Three-tier pricing stratifies across expedition-grade freeze-dried meals, warehouse club bulk buckets, and economy retort pouches for institutional procurement. Price differentiation hinges on USDA FSIS certification status and barrier packaging specification. Cost compression in the economy tier intensifies as aluminum foil laminate supply tightens. Household preparedness buyers exhibit highest price sensitivity, while NATO military procurement shows inelastic demand for qualified suppliers.
Supply Chain Analysis
Supplier-financing facilities from domestic aluminum converters now extend 90-day terms to ration packagers facing Defense Logistics Agency contract surges. Raw material sourcing draws from domestic grain processors, Southeast Asian retort film manufacturers, and domestic freeze-drying equipment fabricators. High-barrier pouch supply concentrates among three domestic converters, creating single-source vulnerability for military contractors. Distribution runs through FEMA-designated pre-positioned stockpile depots, warehouse club fulfillment centers, and direct-to-consumer subscription fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Emergency food incumbents face substitution pressure from aseptic carton and glass jar formats competing for institutional shelf-stable contracts where weight logistics matter less.
For Market Incumbents: Entrench SQF certification advantages by accelerating USDA FSIS inspection queue navigation through dedicated regulatory affairs staffing. Secure captive aluminum foil laminate supply via long-term offtake agreements with domestic converters before defense contract surges trigger allocation constraints. Barrier packaging specification control is the critical defensive lever against retort pouch substitution. For New Entrants and Emerging Players: Establish a beachhead in modular calorie-bank component SKUs serving Pacific Northwest and Rocky Mountain preparedness retailers where earthquake and wildfire risk concentrates hobbyist demand. Target plant-protein ration development for emerging NATO allergen-reduction specifications, opening kosher and halal procurement pools underserved by legacy suppliers. Direct-to-consumer subscription channels offer the most penetrable go-to-market angle bypassing retail slotting fees. For Investors and Strategic Acquirers: Contract manufacturing specialists with spare freeze-drying capacity represent the optimal acquisition archetype for platform integrators seeking rapid government contract eligibility. Long-term viability across the projection horizon depends on alignment with FEMA preparedness grant cycles and Defense Logistics Agency ration modernization priorities. The signal to monitor is USDA FSIS inspection queue clearance velocity as a leading indicator of formulation pipeline throughput.| Strategic Initiative | Industry Significance |
|---|---|
| SQF Certification Acquisition | Unlocks Defense Logistics Agency and FEMA contract eligibility for multi-year shelf-stable procurement. |
| Direct-to-Consumer Subscription Launch | Captures lifetime value through auto-renewal preparedness planning while bypassing retail slotting fees. |
| Plant-Protein Ration Development | Meets NATO allergen-reduction specifications while opening kosher and halal institutional procurement pools. |
| Backward Integration into Barrier Packaging | Reduces exposure to aluminum foil laminate supply concentration among three domestic converters. |
| Freeze-Drying Capacity Expansion | Addresses NATO military procurement demand spikes that strain vacuum sublimation production scheduling. |
Research Approach
Findings reconcile primary fieldwork against secondary review of USDA FSIS inspection records, Defense Logistics Agency contract award databases, and FEMA preparedness grant allocation reports. Primary interviews engaged freeze-drying facility operators, retort pouch packaging engineers, military procurement officers at the Defense Logistics Agency, and preparedness retail category managers. Secondary validation drew from customs import data for aluminum foil laminate substrates, SEC filings for publicly traded food storage companies, and EU Green Deal packaging waste regulation drafts. Bottom-up capacity assessments triangulated against top-down procurement volume estimates.
Forecast inputs span freeze-dried meal, canned goods, ready-to-eat packet, and snack segments across military, household, NGO, and disaster relief end users. Modeled dimensions include shelf-life engineering intensity, distribution channel cost structure, and packaging format logistics constraints. CAGRs derive from equipment capacity expansion pipelines, FEMA grant appropriation trajectories, and NATO defense ration modernization program timelines. Industry-specific inputs capture freeze-drying yield improvement curves and retort operator certification program graduation rates.
Stress conditions across aluminum supply chain disruption, USDA FSIS inspection queue extension, and Defense Logistics Agency contract cancellation scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding FEMA preparedness grant continuity and NATO military procurement expansion. Macroeconomic contraction, regulatory delay, or breakthrough in alternative barrier packaging technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Gluten Substitute Market
Alternative Food Sources
Europe Emergency Food Market
Alternative Food Sources
Single Cell Protein Market
Alternative Food Sources
Vegan Ham Market
Alternative Food Sources
Flaxseed Based Egg Replacement Market
Alternative Food Sources
Vegan Casing Market
Alternative Food Sources
Fungal Protein Market
Alternative Food Sources
North America Meat Substitutes Market
Alternative Food Sources
Fishless Fillets Market
Alternative Food Sources
Vegan Egg Substitute Market
Alternative Food Sources
Egg Replacers Market
Alternative Food Sources
Edible Insects Market
Alternative Food Sources
Carragean Alternatives Market
Alternative Food Sources
Fat Substitutes Market
Alternative Food Sources
Mycoprotein Market
Alternative Food Sources
Algae Products Market