
 Food Serving Equipment Market | 2026-2036
Food Serving Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Food Serving Equipment Market Foresight
Multi-source procurement for heating elements and electronic controls is shifting toward vertically integrated supply arrangements among top manufacturers. The Middleby Corporation leverages captive manufacturing of conveyor ovens and warming cabinets to protect margin pools. Ali Group sustains broad geographic coverage through decentralized brand portfolios across Europe and Asia. Hoshizaki Corporation anchors its position through specialized ice-making and refrigeration expertise that extends into complementary serving systems.
Food serving equipment encompasses heated and refrigerated apparatus designed to maintain safe food temperatures between 140°F and 165°F for hot holding, or below 41°F for cold display, using forced-air convection, conductive heating plates, or thermoelectric cooling modules. Stainless steel dominates material selection for commercial durability and cleanability, though tempered glass is displacing metal in front-of-house display applications where visual merchandising drives purchase decisions. Buffet stations and food warmers capture the largest installed base across institutional end users, while beverage dispensers represent the fastest replacement cycle due to shorter mechanical lifespans and flavor contamination risks. Display cases concentrate margin pools in premium hospitality venues where custom sizing and LED integration command price premiums.
NSF International standards govern food-contact surface safety and electrical compliance across North American installations, while EU energy-efficiency labeling under the Ecodesign Directive restricts power consumption for heated holding cabinets in European commercial kitchens. India's BIS certification mandates thermal performance testing for imported warming equipment, creating compliance barriers for non-domestic suppliers. Stakeholders must monitor evolving refrigerant regulations under the EU F-Gas Regulation and corresponding state-level rules in California and New York that will force equipment redesigns for refrigerated serving lines.
Market Dynamics
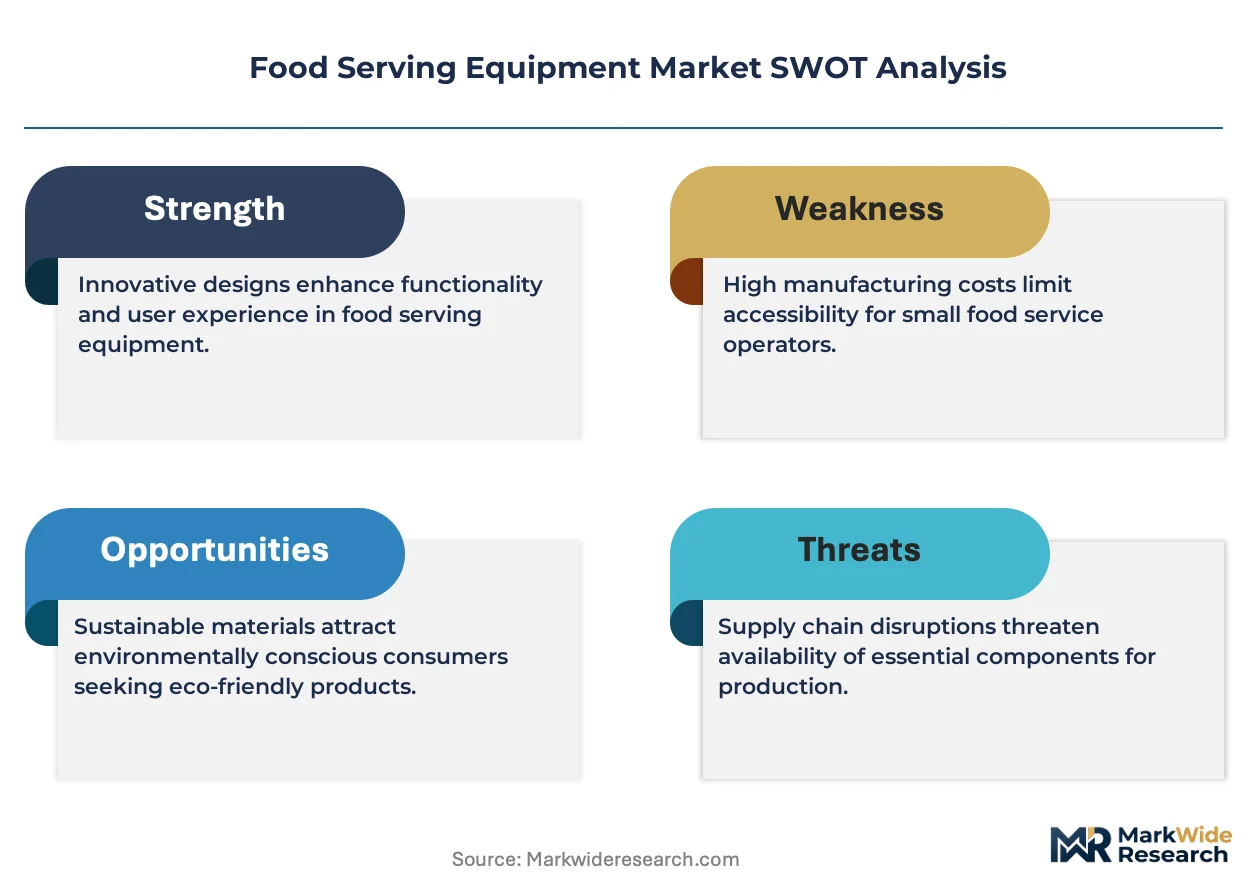
NSF International certification requirements and EU energy-efficiency mandates are compressing product development cycles while fragmenting supplier compliance costs across export-dependent manufacturers. Stainless steel supply concentration in specific Asian mill clusters amplifies input cost volatility for mid-scale equipment fabricators.
Growth Catalysts
- Commercial kitchen modernization:India's PLI scheme for food processing infrastructure is accelerating replacement of legacy warming cabinets in institutional canteens and hotel chains.
- Forced-air convection technology:Quick-service restaurants in Southeast Asia specify these systems to maintain precise temperature bands for extended holding periods.
- F-Gas Regulation:The EU's phasedown of hydrofluorocarbon refrigerants is forcing redesigns of refrigerated display cases, creating upgrade demand across hospitality venues.
Market Restraints
- Nickel price volatility:Stainless steel 304 grade depends on nickel inputs whose price swings compress fabrication margins unpredictably.
- Single-source controller supply:Programmable logic modules for temperature management concentrate among Taiwanese semiconductor fabricators.
- Electrochemical corrosion limits:Salt-air environments in coastal Southeast Asia degrade heating element longevity below warranty thresholds.
Strategic Opportunities
- Thermoelectric cooling convergence:Solid-state Peltier modules paired with IoT sensors enable portable cold-holding units for catering and outdoor events.
- Sub-Saharan Africa underpenetration:Hotel construction in Nigeria and Kenya lacks standardized food-safety equipment procurement channels.
- California refrigerant rules:State-level mandates ahead of federal timelines create early-mover positioning for compliant refrigerated serving lines.
Industry Challenges
- Multi-certification timelines:Simultaneous NSF, CE marking, and BIS testing extends product launch cycles by eight to fourteen months.
- Legacy control integration:Kitchen management software from established vendors lacks API compatibility with new warming equipment telemetry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Serving Equipment Market |
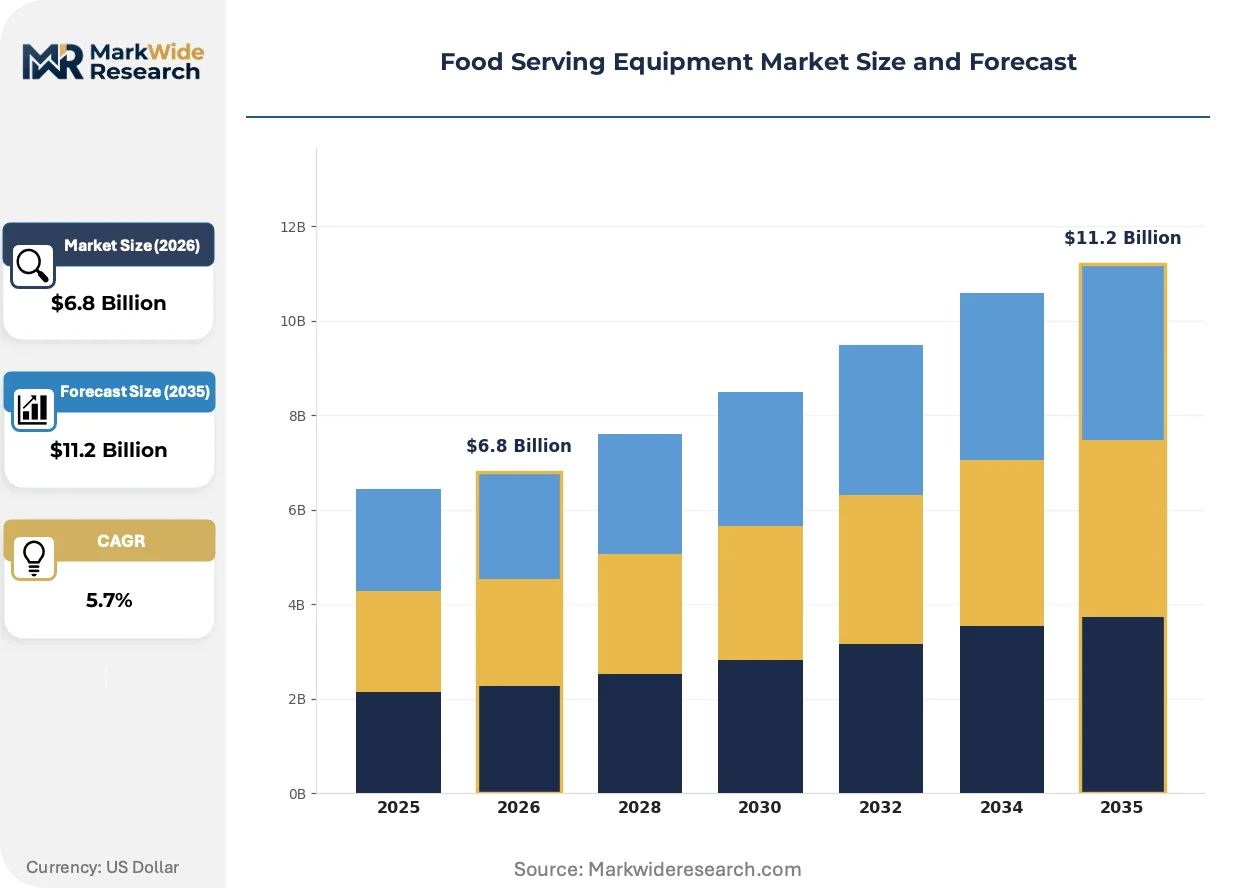
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
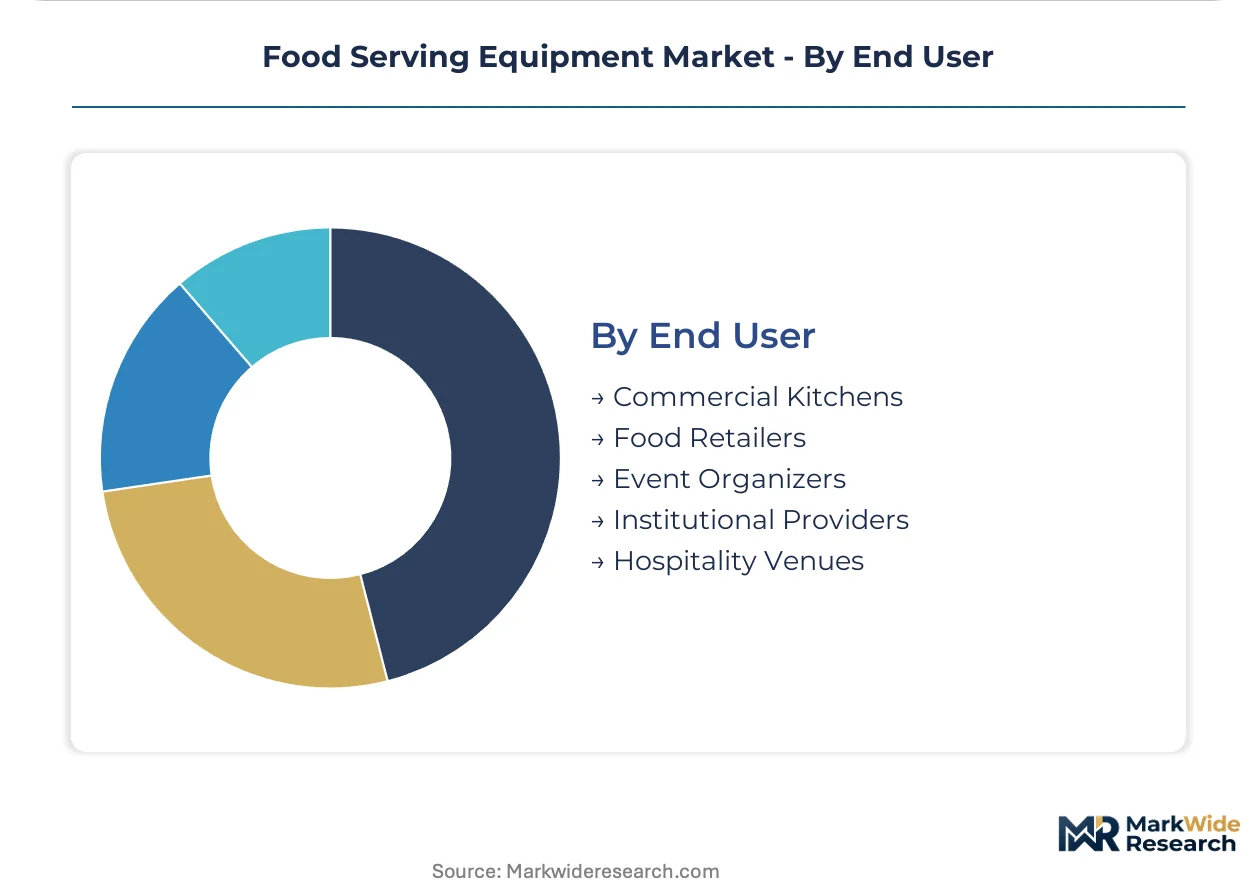
| Segmentation | Product Type: Display Cases, Beverage Dispensers, Food Warmers, Buffet Stations, Salad Bars Material: Stainless Steel, Tempered Glass, Plastic, Aluminum, Wood Application: Restaurants, Catering Services, Hotels, Cafeterias, Food Trucks End User: Commercial Kitchens, Food Retailers, Event Organizers, Institutional Providers, Hospitality Venues |
| Companies Covered | The Middleby Corporation, Ali Group, Illinois Tool Works, Welbilt, Hoshizaki Corporation, Duke Manufacturing, The Vollrath Company, Dover Corporation, AB Electrolux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Serving Equipment Market Shifts & Advancements
Tempered glass front panels and smart-sensor networks are reconfiguring equipment design priorities away from pure thermal performance toward visual merchandising and predictive maintenance capabilities.
Induction warming plates are absorbing countertop footprint previously allocated to traditional conductive heating elements. Full-service restaurants in premium hospitality segments specify these systems for precise zone control and reduced surface temperatures. The technology is absorbing margin from conventional warming drawer categories as buyers prioritize energy metering and rapid heat recovery.
The EU F-Gas Regulation is mandating refrigerant transitions in refrigerated display cases and cold-holding cabinets. Equipment manufacturers must redesign compressor architectures and thermal insulation packages to accommodate lower-global-warming-potential alternatives. European hospitality chains are responding by accelerating replacement cycles ahead of 2027 phase-down deadlines.
Direct procurement from manufacturer digital platforms is displacing traditional foodservice equipment distributors for standardized warming cabinets. Mid-sized restaurant groups in the United States and Germany now specify configurations online and coordinate installation through third-party logistics providers. This channel compression is most visible in replacement demand for beverage dispensers and buffet warmers with shorter mechanical lifespans.
Food Serving Equipment Market Segmentation
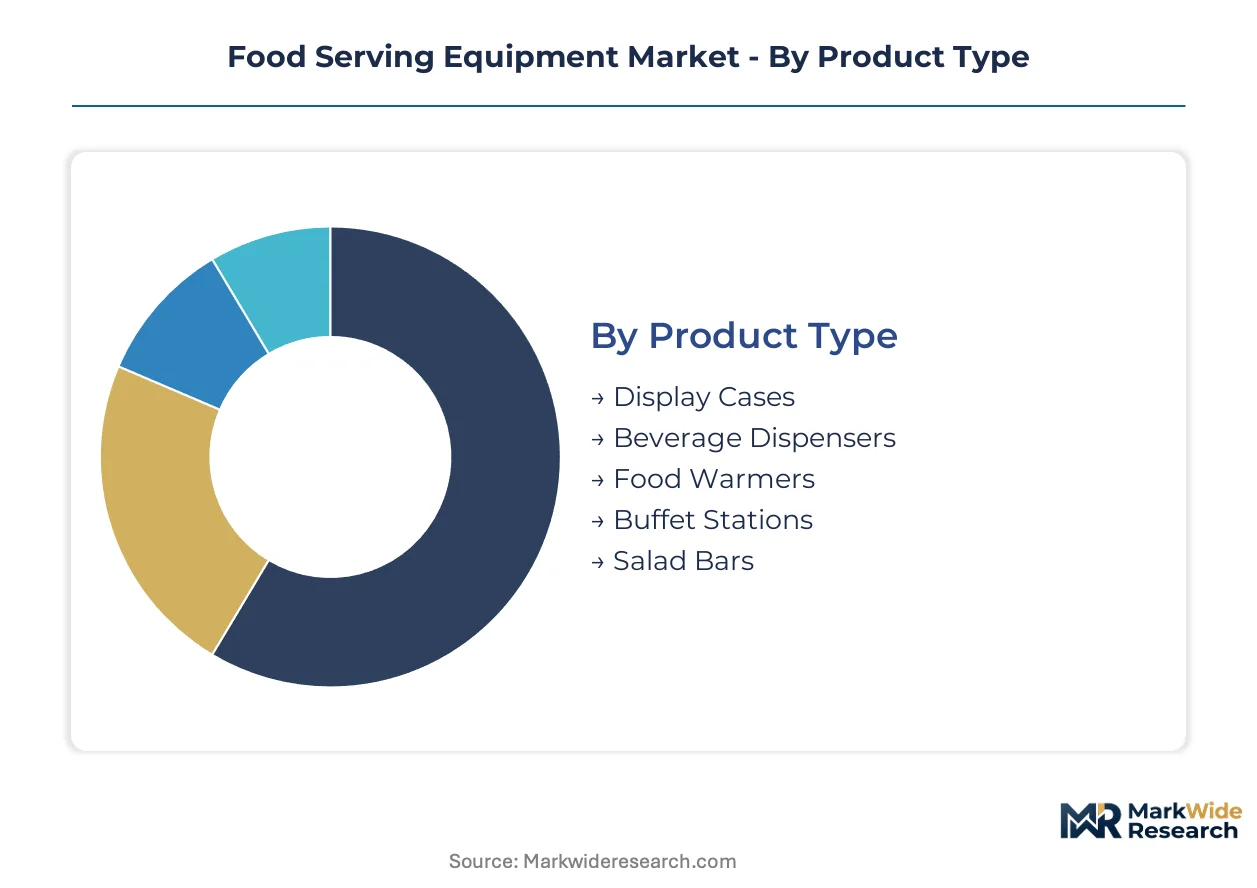
Equipment segmentation in this market tracks divergent paths between integrated kitchen systems and standalone front-of-house units. Material choices and application contexts determine whether serving equipment embeds into fixed infrastructure or operates as portable, redeployable assets.
Product Type:
Standalone warming and cooling units dominate replacement demand, while integrated buffet systems anchor new construction specifications.
- Display Cases:Refrigerated and non-refrigerated enclosures with LED illumination and tempered glass panels. Hotels in Southeast Asia specify these for lobby grab-and-go concepts where visual merchandising drives impulse purchases. NSF International certification requirements extend procurement timelines for imported units.
- Beverage Dispensers:Forced-air or ice-bank cooling systems for juice, coffee, and carbonated drinks. Quick-service restaurants in India replace these most frequently due to flavor contamination risks and shorter mechanical lifespans. The F-Gas Regulation is forcing refrigerant transitions in chilled dispenser architectures.
- Food Warmers:Conductive heating plates or infrared lamp assemblies for countertop hot holding.
- Buffet Stations:Modular warming and cooling combinations for self-service dining layouts.
- Salad Bars:Refrigerated wells with sneeze guards and portion-control accessories.
Food warmers lead volumes today; beverage dispensers are gaining share fastest.
Material:
Cost tiers separate premium hospitality specifications from institutional procurement focused on durability-per-dollar.
- Stainless Steel:304 and 316 grades for food-contact surfaces and structural frames. Commercial kitchens across Southeast Asia specify this for corrosion resistance in high-humidity environments. Nickel price volatility compresses fabrication margins unpredictably.
- Tempered Glass:Heat-treated panels for front-of-house visibility and thermal shock resistance. Full-service restaurants in premium segments prioritize this material where customer sightlines influence purchase decisions. EU energy-efficiency labeling drives demand for glass-insulated warming cabinets.
- Plastic:Polypropylene and polycarbonate components for lightweight, portable units.
- Aluminum:Extruded frames and heat-dissipating elements for induction warming systems.
- Wood:Aesthetic cladding for front-of-house buffet presentations in hospitality venues.
Stainless steel anchors the installed base; tempered glass is climbing the fastest.
Application:
Volume concentration varies by mobility requirements and regulatory exposure across fixed versus mobile foodservice operations.
- Restaurants:Full-service and limited-service establishments with permanent kitchen infrastructure. India's commercial kitchen modernization programs under the PLI scheme accelerate replacement of legacy warming cabinets in chain restaurants. BIS certification creates compliance barriers for non-domestic suppliers.
- Hotels:Property-wide foodservice from banquet halls to in-room dining. Hospitality venues in Nigeria and Kenya lack standardized procurement channels, creating underpenetration for premium equipment categories. California's state-level refrigerant rules ahead of federal timelines shape early-mover positioning.
- Catering Services:Off-premise event foodservice requiring portable and rapid-deployment equipment.
- Cafeterias:Institutional high-volume feeding with standardized portion control and throughput optimization.
- Food Trucks:Mobile operations with severe space constraints and electrical load limitations.
Restaurants dominate current procurement; hotels show the steepest expansion trajectory.
End User:
Customer type determines whether equipment purchases centralize through procurement departments or fragment across decentralized operators.
- Commercial Kitchens:Centralized food production facilities for multi-outlet restaurant groups and ghost kitchen operators. Multi-certification timelines for simultaneous NSF, CE marking, and BIS testing extend product launch cycles by eight to fourteen months.
- Hospitality Venues:Hotels, resorts, and conference centers with banquet and à la carte operations. Custom sizing and LED integration in display cases command price premiums in this segment. Direct procurement from manufacturer digital platforms is displacing traditional distributors.
- Food Retailers:Supermarkets and convenience stores with prepared food and hot holding programs.
- Event Organizers:Temporary foodservice contractors for festivals, weddings, and corporate functions.
- Institutional Providers:Schools, hospitals, and correctional facilities with mandated nutrition and safety protocols.
Commercial kitchens represent the largest addressable base; hospitality venues are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless steel mill clusters across China's Jiangsu and Zhejiang provinces anchor global supply chains for commercial kitchen fabrication. Demand concentration in Southeast Asian quick-service restaurants and India's institutional modernization programs drives regional procurement patterns. Regulatory divergence between NSF standards, EU Ecodesign mandates, and India's BIS certification fragments compliance architectures across export markets.
United States
Quick-service restaurant chains and institutional foodservice operators drive replacement demand for warming cabinets and beverage dispensers. NSF International certification governs food-contact surface safety and electrical compliance for commercial installations. Chicago and Dallas-Fort Worth metropolitan areas concentrate distributor networks and commercial kitchen design firms serving multi-unit operators.
China
Domestic hotel construction and food processing infrastructure expansion absorb output from specialized manufacturers. GB standards and evolving energy-efficiency regulations under MIIT supervision shape product specifications for domestic market entry. Guangdong and Shandong provinces host fabrication clusters supplying both domestic foodservice operators and export markets.
Germany
Premium hospitality venues and full-service restaurant groups specify energy-efficient warming systems with LED integration and glass display elements. EU Ecodesign Directive restrictions on power consumption for heated holding cabinets force equipment redesigns. North Rhine-Westphalia and Bavaria concentrate manufacturer headquarters and engineering centers serving European distribution networks.
India
PLI scheme incentives for food processing infrastructure accelerate replacement of legacy warming equipment in institutional canteens and hotel chains. BIS certification mandates thermal performance testing for imported equipment, creating compliance barriers for non-domestic suppliers. Maharashtra and Karnataka states lead commercial kitchen modernization in metro hospitality and corporate foodservice sectors.
Japan
Compact equipment formats for space-constrained urban restaurants and convenience store foodservice drive demand for precision-controlled warming systems. METI energy-efficiency guidelines and JIS standards govern commercial kitchen equipment specifications. Kanto and Kansai regions concentrate end-user demand from dense metropolitan foodservice operations.
Food Serving Equipment Market Competitive Landscape
Global majors compete with regional champions across certification compliance and supply chain integration dimensions. The vendor base organizes around three tiers: diversified industrial conglomerates with captive distribution, specialized foodservice equipment pure-plays, and regional fabricators serving protected domestic markets. Strategic moves concentrate on backward integration into heating element and controller supply, plus digital platform deployment for direct procurement channels.
Among diversified industrial groups, The Middleby Corporation and Illinois Tool Works occupy positions spanning multiple equipment categories and geographic markets. Ali Group exemplifies the decentralized brand portfolio archetype through European and Asian market presence. Hoshizaki Corporation anchors the specialization vector through focused expertise extending from core refrigeration into complementary serving systems.
| Leading Market Players |
|---|
| The Middleby Corporation |
| Ali Group |
| Illinois Tool Works |
| Welbilt |
| Hoshizaki Corporation |
| Duke Manufacturing |
| The Vollrath Company |
| Dover Corporation |
| AB Electrolux |
| Others |
Supply & Pricing Matrix
Nickel price volatility in stainless steel 304 grade feeds directly into three-tier pricing structures across premium, standard, and economy equipment tiers, with Asian mill concentration in Jiangsu and Zhejiang provinces amplifying cost pass-through to mid-scale fabricators serving institutional buyers.
Pricing Analysis
Input-cost pass-through from nickel and semiconductor controller markets is compressing margins unpredictably for mid-tier warming cabinet manufacturers. NSF certification and EU Ecodesign compliance tiers separate premium hospitality specifications from economy institutional procurement, with price differentiation anchored in thermal performance testing and energy metering capabilities. Pricing pressure stems from Indian PLI scheme incentives accelerating domestic production scale. Quick-service restaurant chains in Southeast Asia exhibit highest price sensitivity due to volume procurement leverage, while premium hotel operators in Germany and Japan absorb certification premiums for LED-integrated display systems.
Supply Chain Analysis
Dual-sourcing requirements for programmable logic modules are forcing equipment manufacturers to qualify secondary Taiwanese semiconductor fabricators beyond primary controller suppliers. Stainless steel 304 and 316 grades draw from concentrated mill capacity in China, with tempered glass sourcing anchored in domestic Chinese and German specialty producers. Single-source vulnerability in heating element electromechanical assemblies creates exposure to salt-air degradation failures in coastal Southeast Asian installations. Distribution runs through manufacturer digital platforms displacing traditional foodservice equipment distributors for standardized warming cabinets and beverage dispensers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU F-Gas Regulation phase-down deadlines and India's BIS certification mandates are forcing replacement cycles and redesign investments across hospitality and institutional channels.
For Market Incumbents: Hedge nickel price exposure through long-term offtake agreements with Jiangsu mill clusters and captive controller inventory buffers against Taiwanese semiconductor supply constraints. Deepen backward integration into heating element production to protect margin pools from electrochemical corrosion warranty claims in Southeast Asian coastal deployments. Prioritize API development for kitchen management software compatibility to defend against telemetry-integrated new entrants. For New Entrants and Emerging Players: Begin with thermoelectric cooling modules for portable catering applications where incumbent refrigeration expertise does not extend. Target underpenetrated hotel construction in Nigeria and Kenya through direct procurement platform partnerships bypassing fragmented distributor networks. Anchor go-to-market positioning on California state-level refrigerant compliance ahead of federal timelines to capture early-mover specification lock-in. For Investors and Strategic Acquirers: Roll-up economics work for regional fabricators with BIS certification capabilities because India's PLI scheme is accelerating domestic replacement demand while creating compliance barriers for non-certified imports. Five-to-ten-year viability hinges on refrigerant transition engineering capacity and IoT sensor integration competencies. Monitor F-Gas Regulation enforcement timing as the inflection signal for refrigerated display case replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Elements | Middleby Corporation's captive manufacturing of warming cabinets protects margin pools from nickel volatility. |
| Digital Platform Deployment | Direct procurement channels displace traditional distributors for standardized beverage dispensers in US and German markets. |
| Refrigerant Transition Engineering | EU F-Gas Regulation compliance redesigns create upgrade demand across European hospitality venue replacement cycles. |
| Certification Portfolio Expansion | Simultaneous NSF, CE marking, and BIS qualification extends product launch timelines but locks out non-compliant competitors. |
| IoT Sensor Integration | Predictive maintenance telemetry differentiates premium warming systems in full-service restaurant specifications. |
Research Methodology
Direct dialogue with commercial kitchen equipment procurement directors, NSF International certification engineers, hotel foodservice operations managers, and stainless steel mill procurement leads grounded primary intelligence, cross-referenced with EU Ecodesign Directive filings, BIS thermal performance test records, SEC 10-K equipment segment disclosures, and foodservice distributor customs data. Bottom-up and top-down triangulation validated volume estimates across product categories.
Analytical lenses combined bottom-up equipment shipment modeling with top-down foodservice capital expenditure patterns across the projection horizon. Segmentation dimensions tracked product type, material grade, application context, and end-user procurement centralization. CAGRs derived from replacement cycle analysis, regulatory deadline impacts, and modernization program spend trajectories. Forecast inputs incorporated F-Gas Regulation phase-down schedules and PLI scheme incentive disbursement timing.
Several conditions sit outside the modeled scope, including geopolitical trade restriction escalations affecting stainless steel tariff structures and unanticipated refrigerant technology breakthroughs altering compressor redesign economics. Forecasts reflect assumptions about certification timeline stability and nickel price band persistence. Deviation in EU F-Gas enforcement rigor or Indian BIS testing capacity expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Draught Beer Chiller Market
Food Service Equipment
Ice Cube Tray Market
Food Service Equipment
Commercial Hot Dog Cooker Market
Food Service Equipment
Smart Food Scale Market
Food Service Equipment
Food Display Counter Market
Food Service Equipment
Scroll Chiller Market
Food Service Equipment
Refrigerated Counter Market
Food Service Equipment
Sheet Pan Racks Market
Food Service Equipment
North America Countertop Ice Makers Market
Food Service Equipment
Food Trays and Bowls Market
Food Service Equipment
Autonomous One-Pot Cooking System Market
Food Service Equipment
Europe Commercial Dishwashers Market
Food Service Equipment
Commercial Rotisserie Oven Market
Food Service Equipment
Gas Commercial Deep Fryers Market
Food Service Equipment
Rapid Cook-High Speed Ovens Market
Food Service Equipment
Mobile Food Warmer Market