
 Bread Processing Equipment Market | 2026-2036
Bread Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Bread Processing Equipment Market Outlook
Aftermarket service revenue is tilting from standalone spare parts toward predictive maintenance contracts bundled with IoT-enabled oven diagnostics. Bühler Group leverages its digital service platform to lock in multi-year agreements with industrial bakeries across Europe. GEA Group Aktiengesellschaft sustains competitive position through captive production of heat exchanger subsystems for its proofer lines. The Middleby Corporation anchors North American presence through restaurant chain relationships that specify standardized baking equipment footprints.
Bread processing equipment encompasses industrial machinery designed to transform raw dough into finished baked products through controlled mixing, fermentation, thermal treatment, and post-bake handling, with oven systems typically operating between 180°C and 300°C depending on product format and crust development requirements. Mixers occupy the largest installed base due to universal need across all production scales, though induction-based thermal systems represent the fastest-growing technology segment as energy efficiency mandates tighten operational cost structures. Ovens and proofers concentrate margin pools because thermal uniformity specifications and humidity control systems create higher barriers to supplier switching than mechanical mixing or slicing equipment.
The EU F-Gas Regulation and REACH compliance frameworks constrain refrigerant selection in proofing environments and material composition in food-contact surfaces, respectively, forcing equipment redesign cycles that favor European-certified suppliers. The US FDA's Current Good Manufacturing Practice regulations for baked goods dictate sanitation-accessible design standards that influence equipment geometry and clean-in-place system integration. China's GB standards for food machinery safety add a third compliance layer for suppliers serving export-oriented production lines. Stakeholders must monitor how fragmented national energy efficiency labeling schemes reshape procurement criteria before committing to platform standardization strategies.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant-dependent proofing equipment lifecycles while simultaneously accelerating capital rotation toward electric thermal systems in industrial baking clusters across Germany and neighboring states.
Growth Catalysts
- Artisan bakery expansion:Independent craft bakeries in France and Italy are scaling automated mixing and portioning lines to meet retail distribution contracts without sacrificing product differentiation.
- REACH compliance redesign:Equipment manufacturers are capturing replacement demand by engineering food-contact surfaces that eliminate restricted substances ahead of enforcement deadlines.
- Induction thermal technology:Energy efficiency mandates in Germany's industrial baking corridor are pulling investment away from conventional gas-fired ovens toward precision-controlled electric systems.
Market Restraints
- Stainless steel input volatility:Equipment fabricators face margin compression from commodity price swings in 304 and 316-grade alloys essential for food-grade construction.
- Heat exchanger supply concentration:Captive production of thermal subsystems by integrated equipment makers limits sourcing flexibility for mid-scale oven assemblers.
- Proofing chamber retrofit complexity:Existing refrigeration architectures resist cost-effective conversion to F-Gas-compliant alternatives, extending replacement timelines.
Strategic Opportunities
- IoT-enabled predictive maintenance:Digital service platforms bundling remote diagnostics with spare parts fulfillment are capturing multi-year contract value from industrial bakeries.
- In-store supermarket baking:Retail chains are specifying standardized equipment footprints that favor modular oven and proofer configurations with rapid installation protocols.
- Clean-in-place integration:Sanitation-accessible design meeting FDA Current Good Manufacturing Practice standards opens procurement pathways into North American export-oriented production lines.
Industry Challenges
- Thermal engineering talent scarcity:Equipment manufacturers compete for specialists capable of optimizing induction coil placement and humidity control algorithms in high-throughput ovens.
- Multi-jurisdiction certification sequencing:Parallel compliance with EU F-Gas, REACH, and China's GB standards extends product development cycles and strains regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bread Processing Equipment Market |
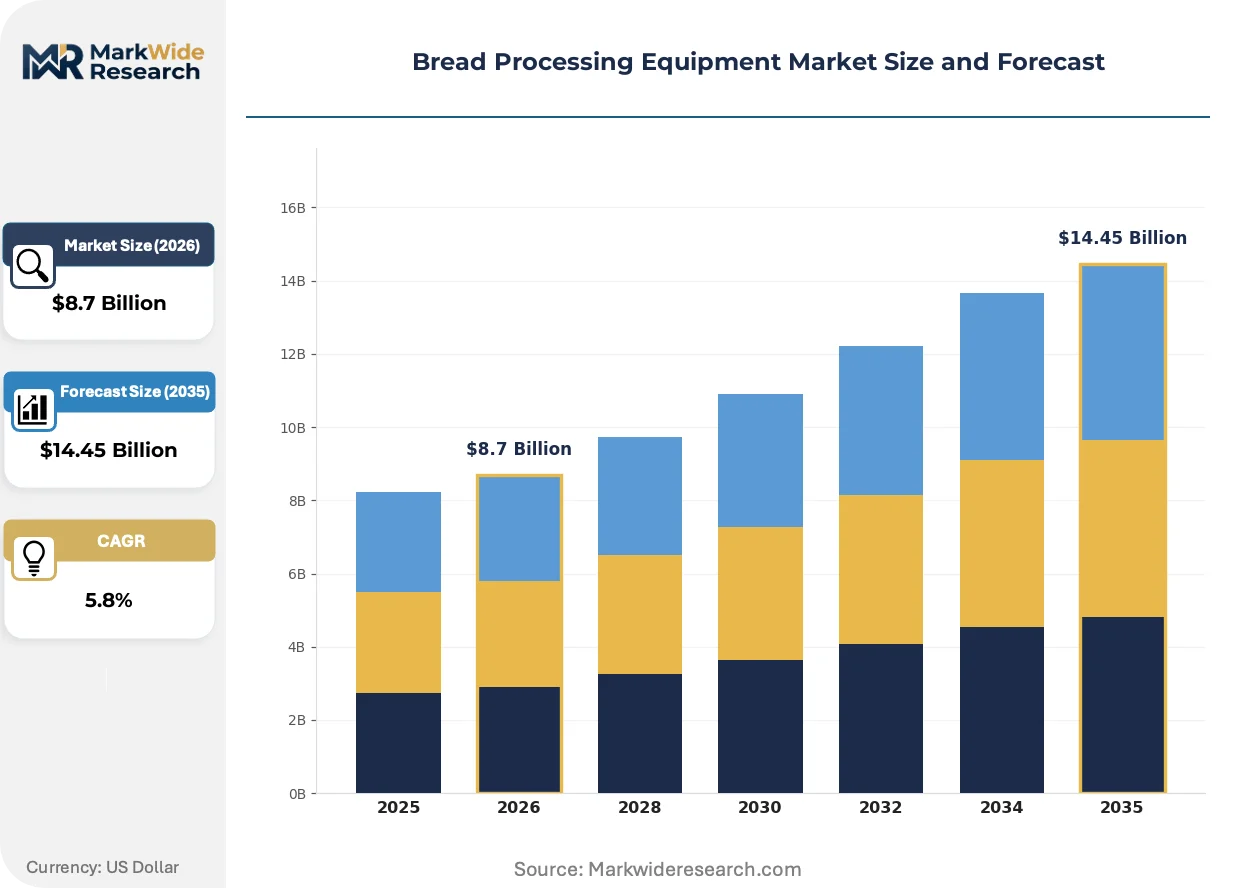
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mixers, Ovens, Proofers, Slicers Technology: Convection, Electric, Gas, Induction End User: Bakeries, Restaurants, Supermarkets, Catering Services Installation: On-site, Mobile, Modular, Custom-built |
| Companies Covered | GEA Group Aktiengesellschaft, Bühler Group, The Middleby Corporation, Ali Group S.r.l., JBT Corporation, Baker Perkins, Heat and Control, Inc., RHEON Automatic Machinery Co. Ltd, Markel Food Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bread Processing Equipment Market Strategic Shifts
Equipment architecture is converging around electrification and data connectivity, with thermal system design and service delivery models undergoing simultaneous transformation.
Induction-based oven technology is hybridizing conventional radiant and convective heat transfer with electromagnetic coil arrays that enable zone-specific temperature profiling. Mid-scale industrial bakeries in Germany and the Netherlands are piloting these systems to satisfy corporate carbon reduction commitments. The technology is hybridizing equipment procurement criteria by merging energy efficiency mandates with precision baking performance specifications.
The EU F-Gas Regulation is forcing refrigerant-dependent proofing equipment toward obsolescence through scheduled hydrofluorocarbon phase-down quotas. Equipment manufacturers must redesign thermal management subsystems using natural refrigerants or electric alternatives to maintain market access. Proofing lines serving frozen dough operations face the steepest compliance costs and shortest retrofit windows.
Aftermarket service contracts are displacing transactional spare parts sales as the dominant revenue mechanism for oven and proofer suppliers. Industrial bakeries in France and Belgium are negotiating multi-year agreements bundling predictive maintenance with guaranteed uptime performance. This shift concentrates margin capture among suppliers with established digital infrastructure and field service density.
Bread Processing Equipment Market Segmentation
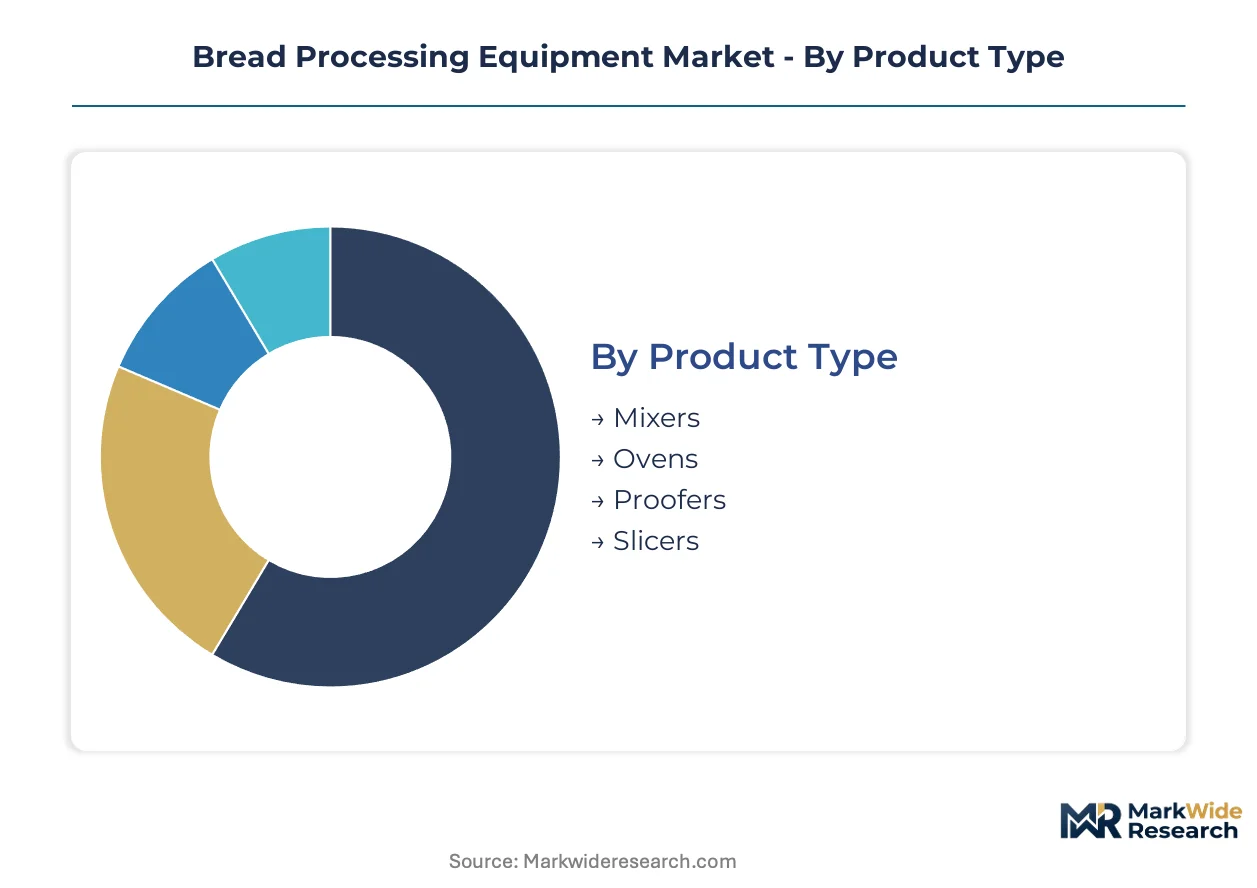
Equipment segmentation in bread processing reveals distinct capital rotation cycles across product categories. Cycle time variance between mixing assets and thermal systems directly shapes supplier revenue stability and aftermarket service attach rates.
Product Type:
Mixers turn over on the longest replacement cycles due to mechanical simplicity, while thermal equipment faces accelerated obsolescence from refrigerant regulations and efficiency mandates.
- Mixers:Universal dough preparation systems utilizing planetary, spiral, or horizontal agitator configurations. Demand concentrates in artisan bakery clusters across France and Italy where automated portioning lines scale output without sacrificing product differentiation. Mixers anchor the volume base while ovens gain share at the steepest rate.
- Ovens:Thermal treatment systems operating between 180°C and 300°C through radiant, convective, or electromagnetic heat transfer. Industrial baking corridors in Germany and the Netherlands are pulling investment toward induction-based electric alternatives to satisfy corporate carbon reduction commitments.
- Proofers:Controlled-humidity fermentation chambers managing dough expansion prior to thermal treatment. EU F-Gas Regulation compliance costs compress replacement timelines for refrigerant-dependent systems serving frozen dough operations.
- Slicers:Post-bake portioning equipment employing band or reciprocating blade mechanisms. Mid-scale bakeries specify sanitation-accessible designs meeting FDA Current Good Manufacturing Practice standards for North American export lines.
Ovens dominate margin capture due to thermal engineering complexity, while proofers face the steepest regulatory-driven replacement pressure.
Technology:
Cost tier stratification separates premium precision systems from standard gas-fired alternatives, with induction commanding price premiums that narrow as production scale increases.
- Convection:Forced-air thermal systems circulating heated air for uniform crust development. Standard configuration for in-store supermarket baking operations requiring rapid installation protocols and modular footprints.
- Electric:Resistive heating elements providing consistent temperature profiles. Expanding most quickly in Germany's industrial baking corridor where energy efficiency mandates tighten operational cost structures.
- Gas:Combustion-based thermal systems utilizing natural gas or propane feedstocks. Cost-sensitive bakeries in Southern Europe retain installed base despite carbon reduction pressures.
- Induction:Electromagnetic coil arrays enabling zone-specific temperature profiling and rapid thermal response. Precision baking performance specifications merge with energy efficiency mandates in premium equipment procurement.
Electric systems anchor the volume base while induction gains share at the steepest rate.
End User:
Application-specific requirements drive divergent equipment specifications, from high-throughput continuous lines to batch-flexible craft installations.
- Bakeries:Dedicated bread production facilities spanning artisan craft operations to industrial-scale plants. Automated mixing and portioning lines scale output across France and Italy without sacrificing product differentiation.
- Restaurants:Foodservice operations requiring compact footprint equipment with rapid cycle capabilities. Standardized equipment specifications from restaurant chains anchor North American procurement patterns.
- Supermarkets:In-store baking operations demanding modular configurations with rapid installation protocols. Retail chains specify standardized footprints that favor oven and proofer bundles.
- Catering Services:Mobile and event-based food preparation requiring portable or temporary installations. Volume concentration remains fragmented relative to fixed-site operations.
Bakeries anchor the volume base while supermarkets gain share at the steepest rate.
Installation:
Customer type segmentation separates capital-intensive permanent installations from flexible deployment models serving variable demand patterns.
- On-site:Permanent fixed installations integrated into dedicated production facilities. Industrial baking clusters across Germany drive premium replacement cycles for built-in thermal systems.
- Mobile:Transportable equipment configurations for temporary or event-based production. Catering services and seasonal operations utilize trailer-mounted or skid-based thermal systems.
- Modular:Prefabricated subsystems enabling rapid assembly and future expansion. In-store supermarket baking operations specify standardized modules for accelerated deployment timelines.
- Custom-built:Engineered-to-order installations for specialized product formats or facility constraints. High-margin niche serving regional bread varieties with non-standard processing requirements.
On-site installations anchor the volume base while modular configurations gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabricators cluster near industrial baking corridors where energy efficiency mandates and refrigerant phase-downs accelerate capital rotation. Germany's southern manufacturing belt anchors European supply, while artisan bakery automation drives procurement in France and Italy.
Germany
Industrial baking clusters around Munich and Stuttgart drive premium replacement cycles for thermal systems. The EU F-Gas Regulation compresses refrigerant-dependent proofing equipment lifecycles, pulling investment toward electric alternatives. Bavaria's equipment makers capture this transition through induction-based oven platforms.
France
Artisan bakeries scale automated mixing and portioning lines to meet retail distribution contracts without sacrificing product differentiation. REACH compliance redesigns eliminate restricted substances from food-contact surfaces ahead of enforcement deadlines. Paris and Lyon anchor procurement concentration for mid-scale automated lines.
Italy
Craft baking traditions merge with automation investments in Emilia-Romagna and Lombardy. ECHA substance restrictions force material composition changes in dough-contact components. Bologna and Milan host equipment specification decisions for regional bakery cooperatives.
United States
Restaurant chain relationships specify standardized baking equipment footprints across North American procurement. FDA Current Good Manufacturing Practice regulations dictate sanitation-accessible design standards. Chicago and Dallas-Fort Worth concentrate foodservice equipment distribution.
Netherlands
Mid-scale industrial bakeries pilot induction-based thermal systems to satisfy corporate carbon reduction commitments. National energy efficiency labeling schemes reshape procurement criteria for thermal equipment. Rotterdam and Eindhoven anchor baking technology testing and validation.
Bread Processing Equipment Market Competitive Environment
Integrated thermal system specialists and modular equipment fabricators split the market along technology complexity lines. Supplier concentration remains moderate, with captive heat exchanger production creating sourcing barriers for mid-scale oven assemblers. Two archetypes dominate: full-line providers bundling digital service platforms with thermal equipment, and component specialists controlling critical subsystems. Competitive moves center on predictive maintenance contract capture and geographic expansion through restaurant chain specification relationships.
Among European-integrated industrial equipment groups, GEA Group Aktiengesellschaft and Bühler Group occupy positions spanning thermal subsystem design through aftermarket service bundling. The Middleby Corporation anchors North American presence. These three exemplify the full-line archetype, with European players emphasizing regulatory compliance engineering and the US-based entity leveraging foodservice chain standardization. RHEON Automatic Machinery Co. Ltd represents the Asia-Pacific fabrication segment, while Ali Group S.r.l. and JBT Corporation sit within diversified food equipment portfolios where bread processing constitutes one vertical among several.
| Leading Market Players |
|---|
| GEA Group Aktiengesellschaft |
| Bühler Group |
| The Middleby Corporation |
| Ali Group S.r.l. |
| JBT Corporation |
| Baker Perkins |
| Heat and Control, Inc. |
| RHEON Automatic Machinery Co. Ltd |
| Markel Food Group |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in standard gas-fired oven manufacturing across Southern Europe is compressing margins and forcing suppliers toward premium electric thermal systems where utilization rates remain tighter and pricing power persists.
Pricing Analysis
Aftermarket service contracts now generate the dominant lifetime value stream, with multi-year predictive maintenance agreements bundling IoT diagnostics and spare parts fulfillment capturing recurring revenue that transactional equipment sales cannot match. Pricing stratifies across premium, standard, and economy tiers based on thermal precision specifications and energy efficiency certification levels. Cost compression in mid-scale mixer segments is intensifying because stainless steel input volatility erodes fabricator margins. Artisan bakeries in France and Italy exhibit the highest price sensitivity due to capital constraints, while industrial baking clusters in Germany accept premium pricing for induction-based systems that satisfy corporate carbon commitments.
Supply Chain Analysis
Upstream feedstock dependencies center on 304 and 316-grade stainless steel alloys sourced primarily from Germany, Italy, and China, with electromagnetic coil arrays for induction systems drawing from specialized winding operations in the Netherlands and Japan. Heat exchanger subsystems rest on captive production by integrated equipment makers, creating sourcing barriers for mid-scale oven assemblers. Single-source vulnerability concentrates in precision humidity control components serving proofer lines. Distribution runs through direct OEM relationships with industrial bakeries and foodservice equipment distributors anchoring North American procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal engineering talent capable of optimizing induction coil placement and humidity control algorithms has become the critical scarce capability, with equipment manufacturers competing aggressively for specialists who can bridge electromagnetic design with baking performance specifications.
For Market Incumbents: Insulate market position by deepening in-house production of heat exchanger subsystems to reduce dependency on external thermal component suppliers, while accelerating certification investment for EU F-Gas and REACH compliance to outpace regulatory redesign cycles that favor established European-certified suppliers. For New Entrants and Emerging Players: Mid-scale industrial bakeries in the Netherlands and Belgium piloting induction-based thermal systems represent the most penetrable entry point, with modular proofer configurations for in-store supermarket baking operations offering a secondary white-space target; pursue specification relationships with retail chain procurement teams that demand rapid installation protocols. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across induction-based oven platforms as electromagnetic component costs and specialized engineering headcount requirements escalate. Long-term viability over the next decade favors targets with established digital service infrastructure and field service density capable of capturing predictive maintenance contract value. Watch for inflection signals in EU F-Gas enforcement timelines that accelerate replacement demand for refrigerant-dependent proofing equipment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Exchanger Production | Captive supply of thermal subsystems locks in margin capture and limits competitor sourcing flexibility. |
| IoT-Enabled Predictive Maintenance Platform Launch | Digital service infrastructure secures multi-year contracts with industrial bakeries across France and Belgium. |
| Induction Thermal Technology Licensing Agreement | Electromagnetic coil expertise from Netherlands-based engineering partners accelerates platform development. |
| REACH Compliance Certification Investment | Food-contact surface redesign ahead of ECHA enforcement deadlines opens replacement demand in Italy. |
| Supermarket Chain Specification Partnership | Standardized modular footprints with rapid installation protocols anchor recurring procurement from retail baking operations. |
Study Parameters
Desk research of trade association publications, customs and trade flow databases, and equipment manufacturer technical documentation preceded structured interviews with plant engineers at industrial bakeries, procurement leads at foodservice equipment distributors, aftermarket service heads at OEMs, and regulatory affairs specialists at thermal system fabricators. Bottom-up equipment shipment data triangulated against top-down baking capacity expansion announcements across Germany, France, Italy, and the Netherlands.
Assumptions around EU F-Gas phase-down enforcement intensity and corporate carbon reduction commitment timelines were held fixed while energy price volatility and stainless steel alloy cost trajectories were stress-tested across scenarios. Segmentation modeling spanned product type, thermal technology, end-user application, and installation configuration. CAGRs were derived from installed base turnover analysis and replacement cycle compression effects. Forecast inputs incorporated regulatory compliance cost curves and induction technology adoption rates from pilot installations.
Macroeconomic conditions sit as an overlay; deviation in industrial energy pricing or stainless steel commodity costs would shift the trajectory of equipment procurement decisions across cost-sensitive bakery segments. Cross-checking against EIA industrial electricity price benchmarks and European steel exchange pricing is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Non-Thermal Food Processing Market
Food Processing Equipment
North America Commercial Sous Vide Machine Market
Food Processing Equipment
Industrial Planetary Mixers Market
Food Processing Equipment
Ice Flaking Machine Market
Food Processing Equipment
Magnetic Grill Market
Food Processing Equipment
Small Brewery Equipment Market
Food Processing Equipment
Portioning Machines Market
Food Processing Equipment
Bottled Water Processing Equipment Market
Food Processing Equipment
Ice-Cream Maker Market
Food Processing Equipment
Spray Dryer Market
Food Processing Equipment
Commercial Oven Market
Food Processing Equipment
Industrial Fryers Market
Food Processing Equipment
Smart Bread Maker Market
Food Processing Equipment
Alternative Protein Processing Equipment Market
Food Processing Equipment
High-Pressure Processing Equipment Market
Food Processing Equipment
Conveyor Ovens and Impinger Ovens Market