
 Europe Emergency Food Market | 2026-2036
Europe Emergency Food Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Emergency Food Market Foresight
Freeze-drying technician shortages across Central Europe are redrawing production capacity maps for emergency food manufacturers. European Freeze Dry Ltd leverages its UK-based lyophilization expertise to sustain long-term supply contracts with British and Scandinavian defense buyers. Nestlé S.A. anchors continental distribution through its existing packaged-foods logistics network. Katadyn Products Inc differentiates via water-purification-adjacent emergency nutrition kits that appeal to alpine and maritime rescue services.
Emergency food denotes shelf-stable nutrition products engineered for deployment during crises, typically achieving five-to-twenty-five-year stability through dehydration, retort processing, or freeze-drying with moisture content below five percent. These products serve civil defense agencies, humanitarian organizations, and individual preppers requiring caloric density without refrigeration infrastructure. Meals dominate product-type value pools due to institutional bulk procurement, while pouches capture the fastest-growing packaging segment as military and outdoor sectors prioritize weight reduction. Online retail channels are expanding fastest among distribution pathways, though direct sales to government agencies still occupy the deepest margin pools through multi-year framework agreements.
EU regulation shapes this market through EFSA nutritional labeling mandates, REACH compliance for packaging materials, and the EU Civil Protection Mechanism that coordinates cross-border stockpile standards. Germany's Federal Office of Civil Protection and Disaster Assistance enforces specific shelf-life and allergen protocols that filter which suppliers qualify for federal tenders. Stakeholders must monitor how the EU Green Deal's packaging-waste directives will alter permissible materials for long-duration storage without compromising barrier properties.
Market Dynamics
Freeze-drying capacity constraints across Central Europe are forcing emergency food manufacturers to reconfigure production footprints and sourcing strategies. Germany's federal stockpiling mandates create predictable demand anchors, while EFSA nutritional labeling rules and REACH packaging compliance filter supplier eligibility for institutional contracts.
Growth Catalysts
- EU Civil Protection Mechanism coordination:Cross-border stockpile standardization enables manufacturers to scale production across multiple member states without duplicating certification efforts.
- Alpine rescue services:Mountain emergency units in Switzerland and Austria are expanding lightweight nutrition kit procurement for high-altitude rapid response.
- Retort pouch technology:Advances in multi-layer barrier films extend shelf stability without refrigeration, opening institutional procurement to new supplier categories.
Market Restraints
- Lyophilization equipment scarcity:Freeze-dryer manufacturing lead times stretch 18-24 months, capping expansion speed for European producers.
- Energy cost volatility:Natural gas price swings in Germany directly impact thermal processing economics for retort and dehydration lines.
- Allergen protocol fragmentation:Divergent national interpretations of EU Food Information to Consumers Regulation create compliance friction for cross-border tenders.
Strategic Opportunities
- Nordic civil defense modernization:Sweden and Finland are rebuilding strategic stockpiles, creating first-mover advantages for compliant suppliers.
- Maritime rescue channel expansion:Coastal agencies from Portugal to Norway are standardizing compact emergency rations for vessel-based deployment.
- EU Green Deal packaging transition:Biodegradable barrier materials development offers differentiation for tenders with sustainability weighting.
Industry Challenges
- Freeze-drying technician scarcity:Specialized lyophilization operators command premium wages across Central Europe, constraining shift capacity.
- Multi-jurisdiction certification timelines:Parallel approvals for BBfS (Germany), ANSES (France), and ISS (Italy) extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Emergency Food Market |
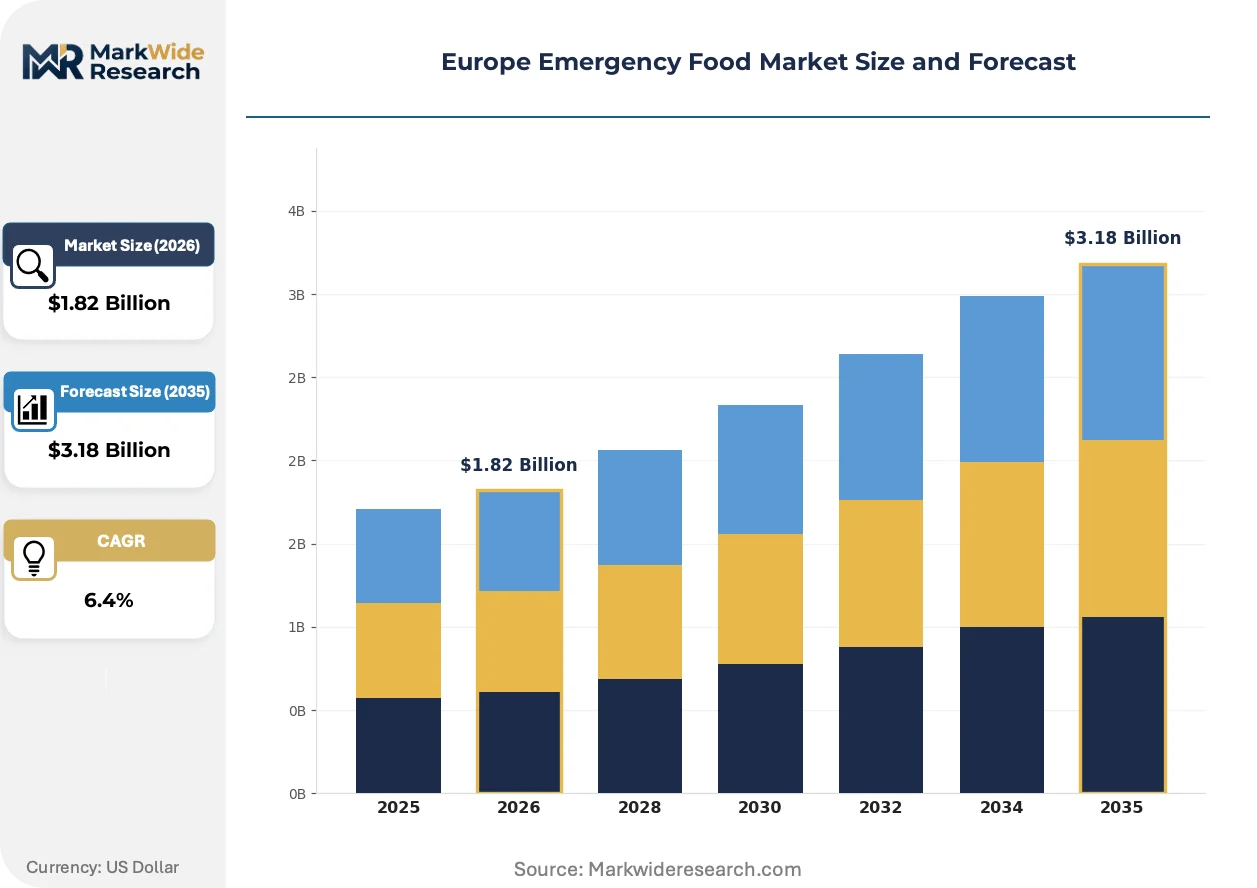
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meals, Snacks, Beverages, Supplements Packaging Type: Cans, Pouches, Boxes, Bulk Packaging Distribution Channel: Supermarkets, Online Retail, Emergency Supplies, Direct Sales End User: Households, Government Agencies, NGOs, Disaster Response Teams |
| Companies Covered | Melograno SRL, Malton Foods Limited, European Freeze Dry Ltd, SOS Food Lab Inc, Readywise, Katadyn Products Inc, Expedition Foods Limited, Nestlé S.A., Lyofood SP Z.O.O, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Emergency Food Market Shifts & Advancements
Production technology and regulatory frameworks are diverging in ways that favor specialized over diversified emergency food suppliers. Shelf-life extension methods, packaging material compliance, and procurement channel structures are each undergoing distinct transformations.
Advanced lyophilization is bifurcating the European manufacturing base between high-capacity freeze-drying specialists and retort-dependent generalists. German and Scandinavian defense buyers are consolidating contracts with technicians possessing proprietary sublimation cycle expertise. This technology compression is marginalizing second-tier producers lacking in-house lyophilization capabilities.
REACH compliance for packaging materials is tightening barrier property requirements for long-duration storage applications. ECHA substance restrictions on certain plasticizers and coatings force reformulation of multi-layer pouches. Italian and Spanish civil defense agencies are responding by embedding material certification requirements directly into tender specifications.
Institutional buyers are fragmenting procurement across framework agreements and spot purchasing channels. German federal stockpiling maintains multi-year direct contracts, while French regional authorities experiment with consolidated purchasing platforms. This channel divergence is most visible in Benelux, where Dutch provincial governments pilot dynamic procurement against Belgian federal centralized buying.
Europe Emergency Food Market Segmentation
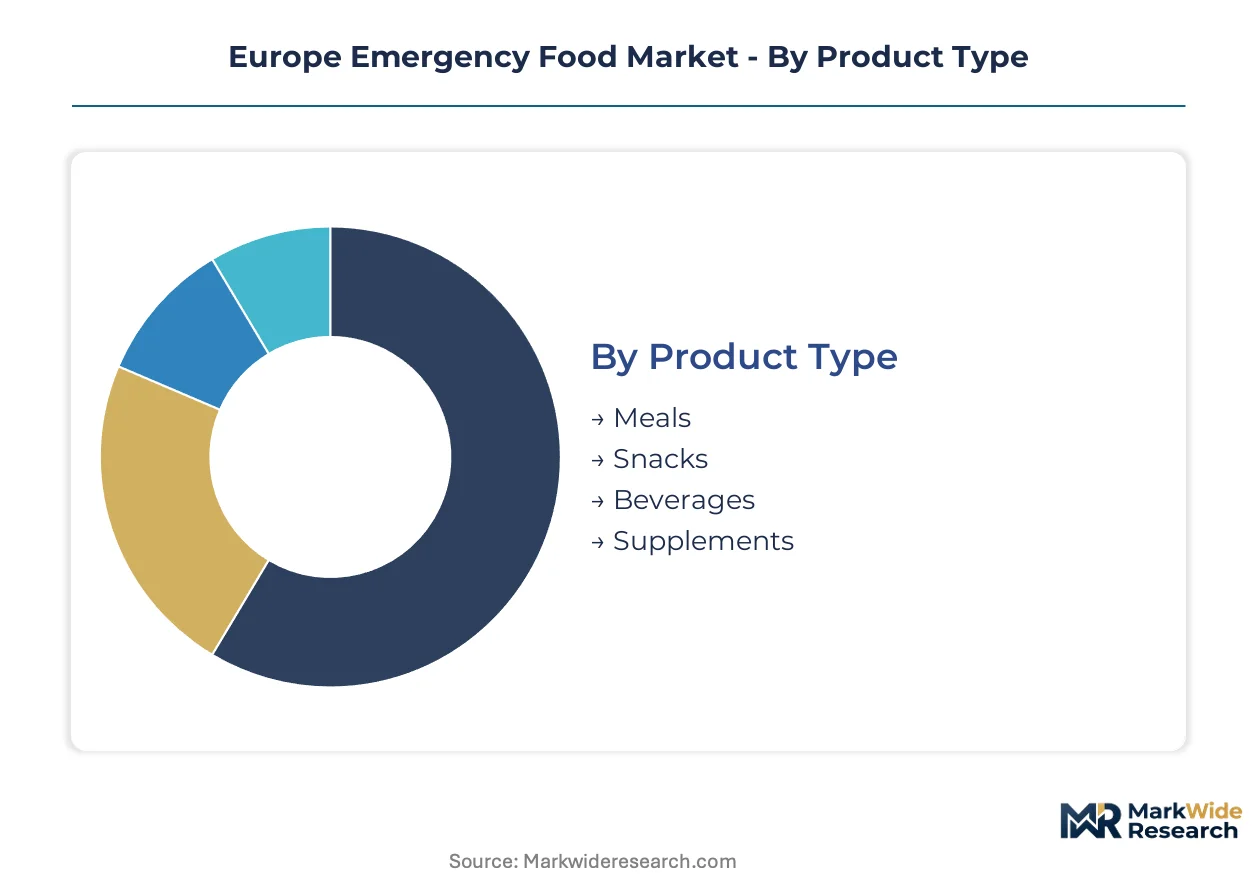
Emergency food segmentation in Europe reflects divergent procurement economics across institutional and civilian channels. Product stability requirements and packaging logistics create distinct margin architectures that suppliers must navigate to qualify for multi-year framework agreements.
Product Type:
Margin pools concentrate in complete meal solutions where caloric density and nutritional completeness justify premium institutional pricing.
- Meals:Complete caloric units combining proteins, carbohydrates, and micronutrients in single-serve formats. German federal stockpiling mandates and French regional civil defense programs anchor demand, with freeze-dried configurations commanding procurement preference for alpine and maritime deployment scenarios.
- Snacks:High-energy bars and compressed nutrient formats designed for rapid consumption without preparation. Scandinavian defense buyers and Swiss alpine rescue services are expanding lightweight procurement for mobile response units where weight reduction outweighs per-calorie cost considerations.
- Beverages:Electrolyte solutions and powdered drink mixes for hydration support.
- Supplements:Vitamin and mineral concentrates for nutritional gap coverage in extended emergencies.
Meals hold installed capacity. Snacks are rotating up the share rankings.
Packaging Type:
Packaging economics pivot on barrier material costs and shelf-life certification complexity rather than unit production speed.
- Pouches:Multi-layer polymer and aluminum laminate structures achieving fifteen-to-twenty-five-year stability through oxygen and moisture exclusion. Benelux procurement pilots and Portuguese maritime agencies are prioritizing pouch formats for vessel-based and rapid-deployment scenarios where space efficiency determines logistics costs.
- Cans:Tinplate and aluminum containers with retort sterilization for wet meal preservation. Italian and Spanish civil defense stockpiles maintain can-based procurement for underground storage facilities where mechanical durability outweighs weight penalties.
- Boxes:Composite cardboard structures with internal barrier liners for bulk dry goods.
- Bulk Packaging:Industrial containers for institutional feeding operations and warehouse staging.
Pouches are climbing the fastest in procurement volume. Cans retain entrenched position in southern European bunkering infrastructure.
Distribution Channel:
Channel selection determines payment terms and certification burden more than absolute revenue scale.
- Direct Sales:Multi-year framework agreements with federal and regional civil defense agencies. Germany's BBfS and France's ANSES compliance requirements filter supplier eligibility, creating margin protection for established contractors with parallel certification across multiple jurisdictions.
- Online Retail:E-commerce platforms serving individual preppers and outdoor enthusiasts. Nordic and British consumers are expanding purchase frequency through specialized emergency preparedness retailers, though order values remain below institutional thresholds.
- Supermarkets:Mass retail placement for consumer awareness and occasional purchase.
- Emergency Supplies:Specialized retailers serving professional responders and industrial safety officers.
Direct sales holds installed capacity. Online retail is rotating up the share rankings.
End User:
User category segmentation maps to procurement sophistication and specification stringency rather than absolute volume.
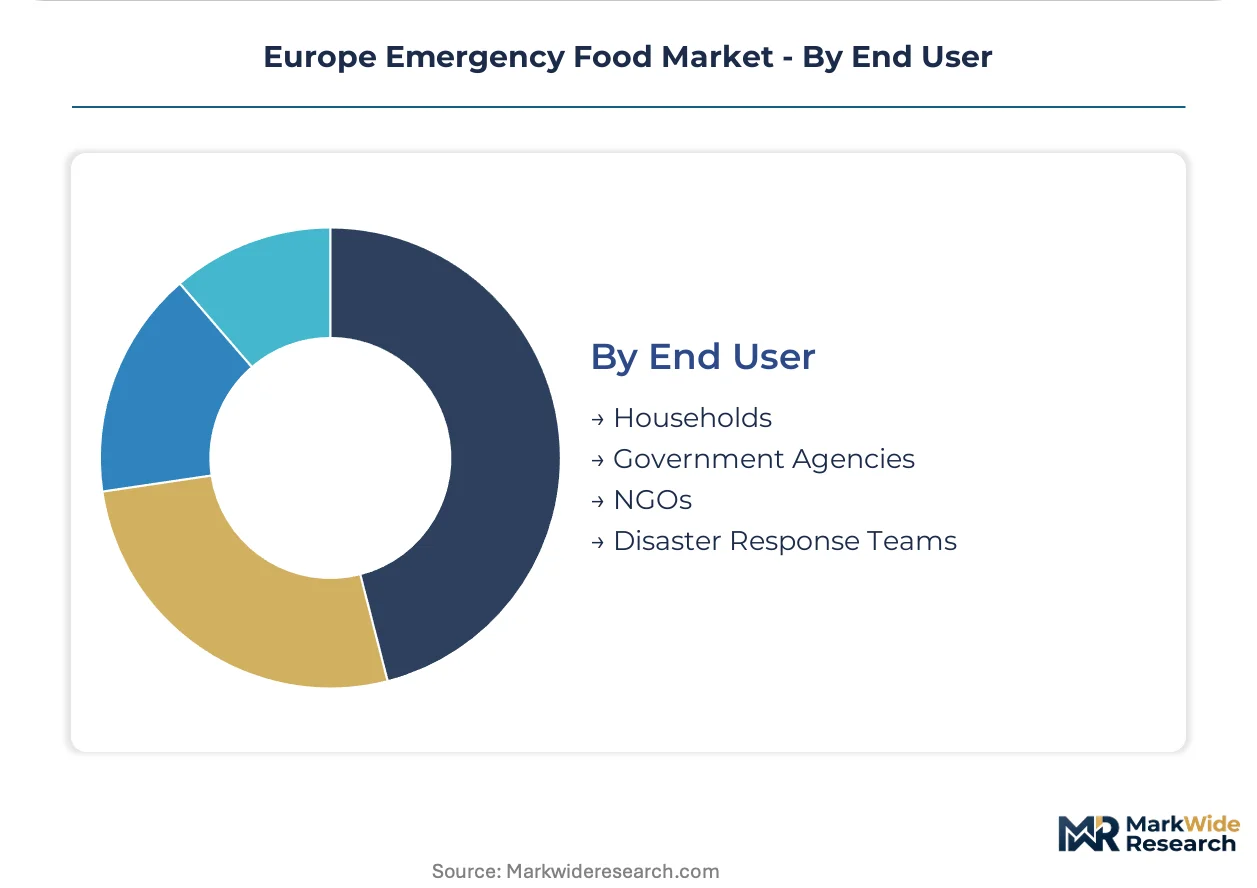
- Government Agencies:Federal and regional civil defense authorities with mandatory stockpiling obligations. Germany, France, and Italy enforce distinct shelf-life and allergen protocols that filter supplier pools, with EFSA nutritional labeling and REACH packaging compliance serving as baseline entry requirements.
- Disaster Response Teams:Professional rapid-response units requiring lightweight, rapid-preparation formats. Alpine rescue services in Switzerland and Austria and maritime units from Norway to Portugal are standardizing compact nutrition kits for high-mobility deployment.
- Households:Individual consumers purchasing for personal emergency preparedness.
- NGOs:Humanitarian organizations operating cross-border relief programs.
Government agencies hold installed capacity. Disaster response teams are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Emergency food consumption across Europe splits between federal stockpiling mandates in Germany and mobile procurement patterns in Alpine and maritime zones. Southern European bunkering infrastructure favors canned formats, while Nordic buyers prioritize lightweight pouch configurations for rapid deployment scenarios.
Germany
Federal civil defense mandates and BBfS procurement frameworks anchor continental demand volume. The Federal Office of Civil Protection and Disaster Assistance enforces shelf-life protocols that filter supplier eligibility for multi-year framework agreements. Production clusters concentrate in Bavaria and North Rhine-Westphalia where lyophilization specialists serve defense stockpiling contracts.
France
Regional civil defense authorities and ANSES nutritional labeling requirements shape procurement specifications. French alpine rescue services in Auvergne-Rhône-Alpes are expanding lightweight nutrition kit procurement for high-altitude rapid response. The Île-de-France corridor hosts distribution hubs coordinating cross-border tenders under EU Civil Protection Mechanism standards.
Italy
Underground storage infrastructure and ISS allergen protocols maintain can-based procurement preferences distinct from northern European formats. Civil defense stockpiles in Lombardy and Emilia-Romagna emphasize mechanical durability for bunker deployment. Italian tender specifications increasingly embed REACH-compliant packaging material certifications.
Sweden
Strategic stockpile rebuilding programs and MSB modernization initiatives create first-mover opportunities for compliant suppliers. Swedish defense buyers prioritize freeze-dried configurations for arctic deployment scenarios. Industrial capacity concentrates around Stockholm and Gothenburg corridors serving Nordic civil defense networks.
Switzerland
Alpine rescue services and REGA air rescue operations drive demand for compact, rapid-preparation nutrition formats. Swissmedic standards and federal civil protection coordination filter supplier pools for mountain emergency units. The Swiss Plateau hosts specialized manufacturers serving both domestic and cross-border Alpine rescue contracts.
Europe Emergency Food Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier controlling distribution networks and the lower tier competing on lyophilization expertise or niche format specialization. The market structure bifurcates between freeze-drying specialists with proprietary sublimation capabilities and retort-dependent generalists serving southern European bunkering demand. Strategic archetypes include integrated packaged-foods conglomerates, dedicated lyophilization technicians, and water-purification-adjacent nutrition kit assemblers. Dominant competitive moves center on multi-year framework agreement capture and freeze-drying capacity expansion to serve defense procurement timelines.
Among UK-based lyophilization specialists, European Freeze Dry Ltd exemplifies the technician archetype with sustained supply positioning toward British and Scandinavian defense buyers. Nestlé S.A. anchors the integrated tier through continental distribution infrastructure derived from existing packaged-foods logistics networks. Katadyn Products Inc occupies a distinct position linking water purification expertise to emergency nutrition kit assembly for alpine and maritime rescue services.
| Leading Market Players |
|---|
| Melograno SRL |
| Malton Foods Limited |
| European Freeze Dry Ltd |
| SOS Food Lab Inc |
| Readywise |
| Katadyn Products Inc |
| Expedition Foods Limited |
| Nestlé S.A. |
| Lyofood SP Z.O.O |
| Others |
Supply & Pricing Matrix
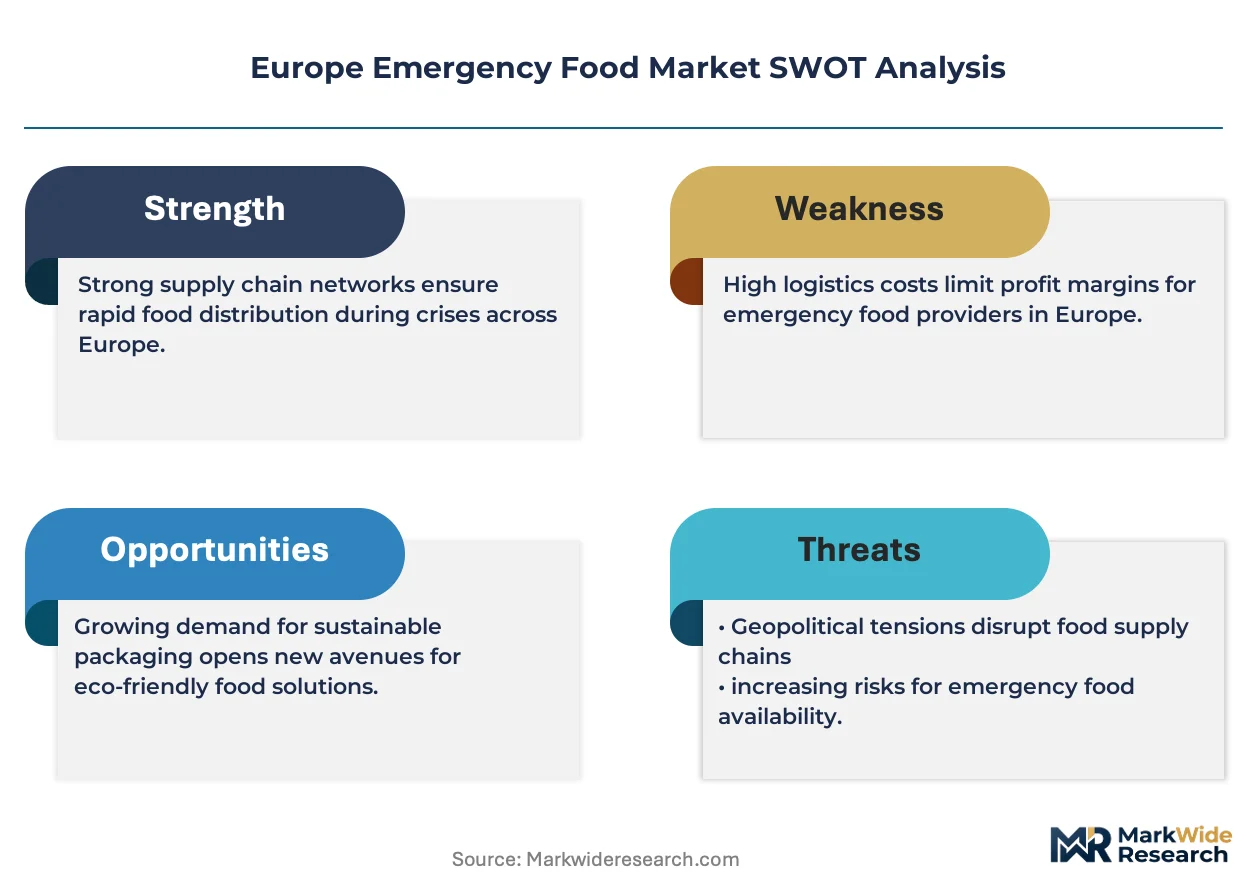
Eighteen-to-twenty-four-month freeze-dryer manufacturing lead times concentrate supply-side leverage among established European lyophilization specialists, compressing pricing power for second-tier producers while amplifying margin protection for incumbents with captive capacity and multi-year framework agreements with German federal buyers.
Pricing Analysis
Long-term offtake contracts dominate institutional procurement, with Germany's BBfS and France's ANSES-compliant suppliers commanding premium pricing through certification tier differentiation and volume scale guarantees. Price differentiation rests on REACH packaging compliance grade and freeze-drying expertise depth, with energy cost volatility in German thermal processing lines intensifying margin pressure across retort-dependent tiers. Government agencies exhibit lowest price sensitivity due to mandatory stockpiling obligations, while individual preppers through online retail channels drive hardest bargain scrutiny.
Supply Chain Analysis
Germany and the United Kingdom anchor freeze-dried meal production through Bavarian lyophilization clusters and British defense-contractor facilities. Raw material flows draw from specialized barrier film suppliers in Benelux and aluminum laminate sources in Southern Europe. Single-source vulnerability concentrates in freeze-drying equipment manufacturing, where limited European vendors control sublimation chamber production. Distribution runs through dual-channel architecture: direct federal framework agreements for institutional volume, specialized emergency preparedness retailers for civilian segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European emergency food markets are recovering from pandemic-era stockpile depletion cycles, with government replenishment mandates across Germany, Sweden, and Finland creating predictable demand anchors through the mid-2020s.
For Market Incumbents: Fortify lyophilization capacity positions in Germany and Scandinavia through technician training pipelines and equipment order backlogs, as freeze-drying specialist scarcity threatens shift expansion for competitors lacking proprietary sublimation cycle expertise. Deepen REACH-compliant packaging material certifications ahead of EU Green Deal transition deadlines to preempt tender disqualification. For New Entrants and Emerging Players: Lead with maritime rescue and alpine rapid-response formats where standardization gaps exist between Portuguese coastal agencies and Swiss REGA air rescue operations. Nordic civil defense modernization programs in Sweden and Finland offer most penetrable institutional entry points for compliant suppliers, with water-purification-adjacent nutrition kit assembly providing differentiated go-to-market positioning. For Investors and Strategic Acquirers: Carve-out targets emerge from packaged-foods conglomerates seeking to divest non-core emergency nutrition divisions amid portfolio rationalization pressures. Long-term viability favors specialized lyophilization technicians with defense-contractor relationships over retort-dependent generalists facing energy cost volatility. Watch freeze-drying equipment order backlogs as inflection signal for capacity-constrained pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Freeze-Drying Capacity Expansion | German and Scandinavian defense buyers consolidate contracts with technicians possessing proprietary sublimation expertise. |
| REACH-Compliant Packaging Transition | ECHA substance restrictions force multi-layer pouch reformulation for Italian and Spanish bunker storage tenders. |
| Alpine Rescue Format Development | Swiss REGA and Austrian mountain emergency units standardize compact rapid-preparation nutrition kits. |
| Nordic Civil Defense Framework Capture | Sweden's MSB modernization and Finnish strategic stockpile rebuilding create first-mover procurement advantages. |
| Maritime Rescue Channel Standardization | Coastal agencies from Portugal to Norway align compact ration specifications for vessel-based deployment. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with freeze-drying technicians, civil defense procurement officers at Germany's BBfS and France's ANSES, alpine rescue logistics coordinators, and barrier film packaging engineers. Secondary validation drew from EFSA nutritional labeling databases, ECHA REACH substance restriction registers, EU Civil Protection Mechanism tender documentation, and customs records for freeze-dried food trade flows. Bottom-up production capacity estimates triangulated against top-down federal stockpiling mandate aggregations.
Across the analysis window, the forecasting framework modeled product-type segmentation by shelf-life technology, packaging format by barrier material compliance tier, distribution channel by contract structure, and end-user category by procurement sophistication level. CAGRs derived from trajectory alignment between historical replenishment cycle patterns and announced civil defense modernization program budgets. Industry-specific inputs included lyophilization equipment lead time observations and natural gas price elasticity assumptions for German thermal processing economics.
Forecasts assume regulatory continuity in EFSA nutritional labeling, REACH packaging compliance, and EU Civil Protection Mechanism coordination standards; material policy shifts in allergen protocol harmonization or Green Deal packaging waste directives would require re-modeling. Specific risks include freeze-drying technician wage inflation, multi-jurisdiction certification timeline extensions, and energy cost volatility in German production clusters. Recalibration cycles align with material shifts in federal stockpiling mandate announcements and civil defense modernization program disbursements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Gluten Replacer Market
Alternative Food Sources
Plant-Based Compound Feed Market
Alternative Food Sources
Monoprotein Market
Alternative Food Sources
Corn-Based Protein Market
Alternative Food Sources
Global Algal Oil Market
Alternative Food Sources
Food Cultures Market
Alternative Food Sources
Algae Oil Market
Alternative Food Sources
Egg Replacers Market
Alternative Food Sources
Emergency Food Market
Alternative Food Sources
South America Fat Replacers Market
Alternative Food Sources
Vegan Tuna Market
Alternative Food Sources
Bioengineered Food Market
Alternative Food Sources
Spirulina Market
Alternative Food Sources
Egg Substitutes Market
Alternative Food Sources
Vegetable Waste Products Market
Alternative Food Sources
Gluten Substitute Market