
 Algae Products Market | 2026-2036
Algae Products Market Size, Share, and Industry Trends Forecast 2026-2036
Algae Products Market Intelligence
EU REACH registration is broadening compliance costs for imported algae extracts. Cargill, Incorporated leverages its global supply chain to secure multi-origin spirulina feedstock. Algatechnologies anchors its position through specialized astaxanthin cultivation in Israel's Arava Desert. BASF SE differentiates via fermentation-derived omega-3 platforms that compete with traditional fish oil sources.
Algae products comprise biomass or extracts from photosynthetic organisms, typically cultivated in open ponds or closed photobioreactors with controlled pH, salinity, and light exposure, then processed into proteins, lipids, pigments, or hydrocolloids for industrial and consumer applications. Spirulina and chlorella dominate the dietary supplement channel, while carrageenan and agar sustain mature food-grade thickener margins. Nutraceuticals and food and beverage applications absorb the fastest volume growth as clean-label formulators replace synthetic additives with algae-derived alternatives.
EFSA novel food assessments, FDA GRAS notifications, and China's NMPA health food blue-hat registration collectively determine which strains enter commercial channels and at what compliance cost. The EU F-Gas Regulation indirectly pressures algae-derived bioplastic investments by restricting conventional polymer feedstocks. Stakeholders must track regulatory divergence between jurisdictions to avoid stranded formulation investments.
Market Dynamics
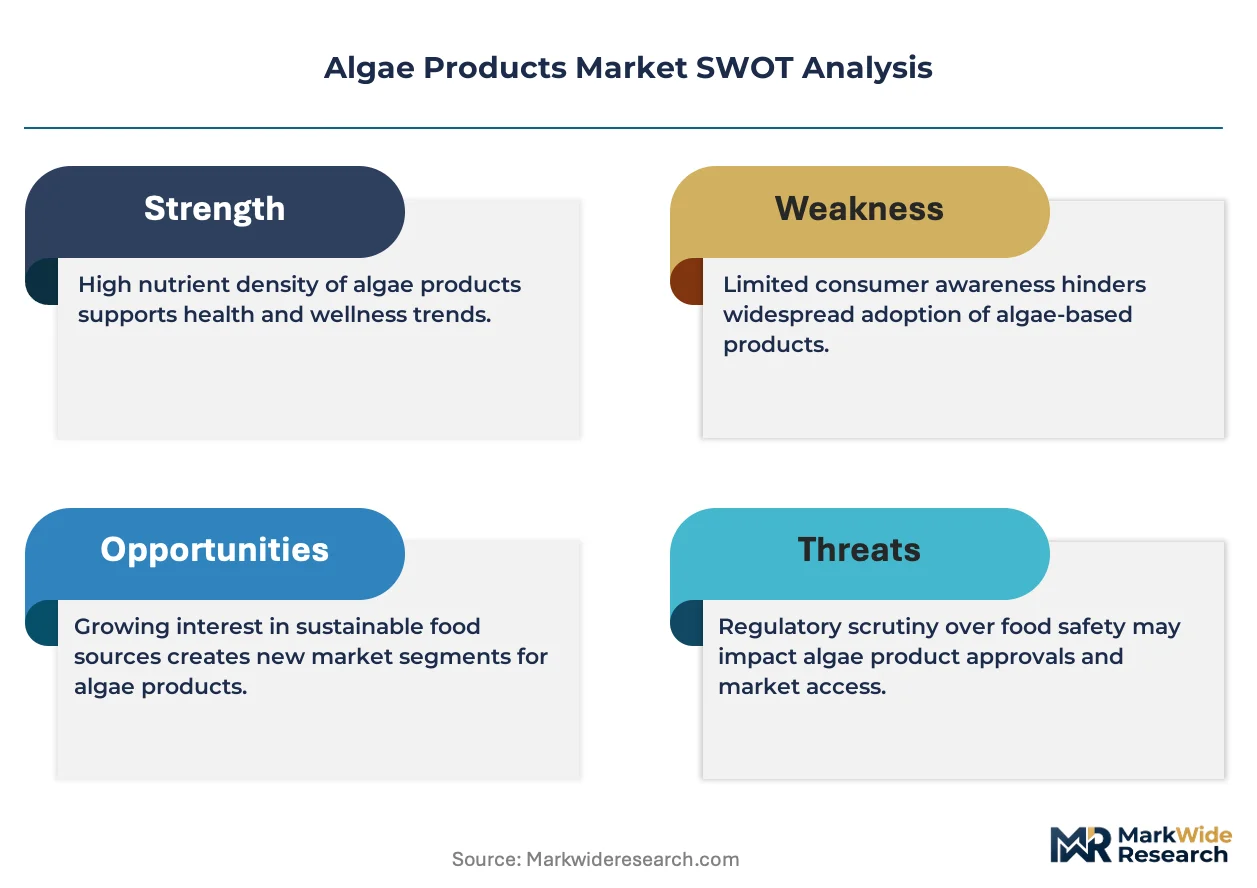
Closed photobioreactor deployment is compressing contamination rates while elevating capital intensity, forcing processors to choose between volume scale and batch purity. EFSA novel food pathways now determine which strains reach European nutraceutical channels.
Growth Catalysts
- EFSA Novel Food Framework:Standardized safety assessments for spirulina and chlorella accelerate strain approval timelines across EU member states, reducing regulatory arbitrage between national markets.
- Clean-Label Formulation:Food and beverage manufacturers replace synthetic colorants and thickeners with algae-derived hydrocolloids, pulling volume through carrageenan and agar substitution.
- Shandong Processing Clusters:Kelp concentration in China's coastal province generates feedstock proximity for Asian cosmetics formulators, compressing logistics costs for hydrocolloid extraction.
Market Restraints
- Input Cost Volatility:Nitrogen and phosphorus fertilizer prices swing with natural gas benchmarks, directly pressuring open-pond cultivation economics where nutrient dosing is less precise.
- Supply Concentration Risk:Astaxanthin production clusters in Israel's Arava Desert and Hawaii create single-point vulnerability for high-value carotenoid supply.
- Technical Limitation:Cell wall disruption efficiency for chlorella remains below 85% in mechanical processing, leaving bioavailable protein locked in indigestible biomass.
Strategic Opportunities
- Brazilian Aquafeed Expansion:ANVISA feed additive approvals for algae-derived omega-3 open formulation pathways for salmon and shrimp producers seeking fish oil alternatives.
- Fermentation Platform Convergence:Heterotrophic cultivation using sugar feedstocks decouples production from sunlight constraints, enabling year-round output in temperate climates.
- Direct-to-Consumer Subscription:Powder and capsule brands bypass wholesale distribution, capturing margin through recurring revenue models in wellness-focused demographics.
Industry Challenges
- Phycologist Talent Scarcity:Strain optimization and contamination response require specialized algae biology expertise that outpaces university pipeline output.
- GRAS Timeline Compression:FDA notification review periods for novel strains extend 18-24 months, freezing commercial launch schedules for US-targeted ingredients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Algae Products Market |
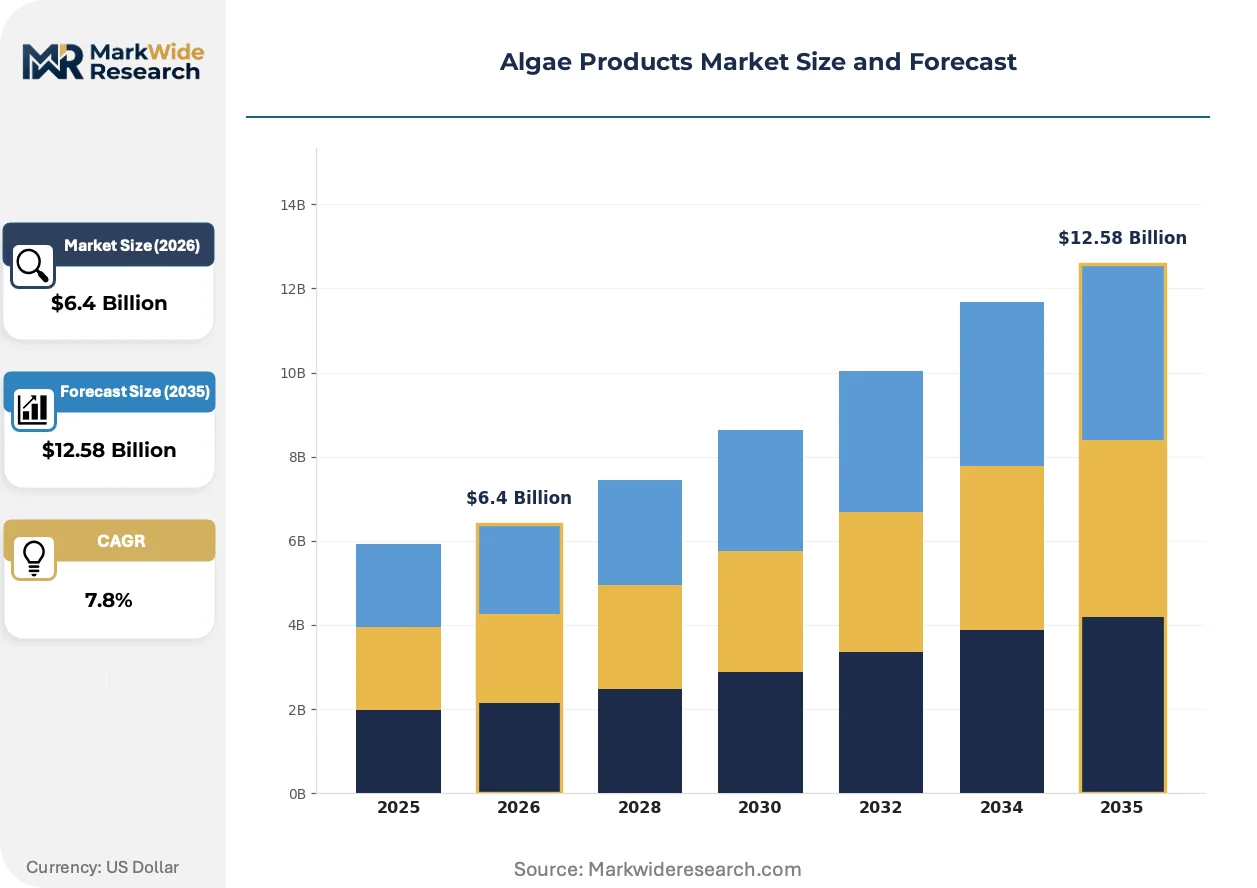
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $12.58 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spirulina, Chlorella, Kelp, Dulse, Carrageenan, Agar End Use Industry: Pharmaceuticals, Cosmetics, Animal Feed, Biofertilizers, Nutraceuticals, Food & Beverage Application: Dietary Supplements, Wastewater Treatment, Bioplastics, Biofuel Production, Fertilizer, Cosmetics Formulation Packaging Type: Bulk Bags, Bottles, Sachets, Tins, Jars, Blister Packs |
| Companies Covered | Cargill, Incorporated, Cyanotech Corporation, Corbion, BASF SE, dsm-firmenich, Algatechnologies, Earthrise Nutritionals, Archer Daniels Midland Company, Cellana Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Algae Products Market Strategic Shifts & Innovations
Photobioreactor engineering and downstream processing advances are fragmenting the traditional pond-dominant supply base. Regulatory science is catching up to strain diversity, while buyer procurement patterns favor traceable, single-origin biomass.
Hybrid photobioreactor designs combine closed tubular systems with open raceway finishing stages, balancing contamination control against capital efficiency. Mid-scale nutraceutical processors in Germany and California adopt these configurations to serve organic-certified product lines. The technology is modularizing facility expansion, allowing producers to add production capacity in 10,000-liter increments rather than committing to 50,000-liter ponds.
EU REACH registration requirements for imported algae extracts expand compliance documentation to include full toxicological profiles and environmental fate data. Importers from Indonesia and Chile face elevated testing costs that domestic EU cultivators avoid. Small-volume specialty extractors are consolidating to share registration burdens, while large integrated players absorb costs through captive laboratory capacity.
Cosmetics formulators now require chain-of-custody documentation from cultivation through extraction, replacing spot-market purchasing with multi-year offtake agreements. This specification compression favors vertically integrated producers with in-house quality certification over trading-house intermediaries. The shift is most pronounced in South Korean skincare manufacturing, where ingredient storytelling drives consumer premium willingness.
Algae Products Market Segmentation
Algae product specifications vary sharply across downstream applications, with nutraceutical buyers demanding protein content certification while cosmetics formulators prioritize pigment stability. Processing infrastructure investments align tightly with segment selection, as photobioreactor configurations differ for carotenoid extraction versus hydrocolloid recovery.
Product Type:
Buyers differentiate primarily by protein concentration thresholds and cultivation system compatibility, with premium nutraceutical contracts specifying closed-system biomass only.
- Spirulina:Cyanobacterial biomass containing 60-70% protein by dry weight, cultivated in open raceways or closed tubular photobioreactors. German nutraceutical manufacturers under EFSA novel food guidelines now mandate irradiation documentation and heavy metal testing for every batch, compressing supplier qualification timelines.
- Chlorella:Single-celled green algae with rigid cell walls requiring mechanical or enzymatic disruption for protein bioavailability. China's Shandong province hosts the largest processing clusters, where local equipment makers have specialized in bead-milling technology that achieves 80-85% cell wall breakage rates.
- Kelp:Brown macroalgae harvested from coastal farms, valued for alginate and fucoidan extraction. Japanese and South Korean cosmetics houses source specifically from Hokkaido and Jeju Island for ingredient storytelling.
- Dulse:Red macroalgae with savory flavor profile, used in plant-based meat formulations and specialty food seasonings. Irish and French Atlantic harvesters dominate supply.
- Carrageenan:Sulfated polysaccharide extracted from red algae, functioning as gelling and stabilizing agent. Indonesian and Philippine processors serve global dairy and meat processing industries.
- Agar:Gel-forming polysaccharide from Gelidium and Gracilaria species, essential for microbiological culture media and confectionery. Moroccan and Portuguese harvesters supply European laboratories.
Spirulina leads volumes today; chlorella is gaining share fastest among premium supplement lines.
End Use Industry:
Margin structures diverge dramatically, with pharmaceutical and nutraceutical channels absorbing 40-60% raw material premiums over commodity food-grade applications.
- Pharmaceuticals:Algae-derived excipients and active pharmaceutical ingredients requiring GMP certification and batch-level traceability. FDA and EMA inspections dominate supplier selection.
- Cosmetics:Astaxanthin and fucoxanthin for anti-aging formulations, with South Korean manufacturers driving chain-of-custody documentation requirements from cultivation through final formulation.
- Animal Feed:Omega-3 enrichment for aquaculture and poultry, with Brazilian salmon producers seeking ANVISA-approved algae oil alternatives to fish meal.
- Biofertilizers:Seaweed extracts for agricultural biostimulants, concentrated in India's coastal states where smallholder adoption is expanding fastest.
- Nutraceuticals:Protein powders, capsules, and functional foods commanding premium pricing based on organic certification and strain-specific health claims. German and US buyers dominate procurement.
- Food & Beverage:Natural colorants, hydrocolloids, and protein fortification for clean-label formulations. European manufacturers substitute algae-derived alternatives for synthetic additives under EU Green Deal pressures.
Nutraceuticals capture the steepest margin expansion; biofertilizers show the fastest volume climb in emerging markets.
Application:
Technical performance specifications determine procurement patterns, with bioplastic and biofuel applications requiring lipid content above 30% dry weight.
- Dietary Supplements:Tablets, capsules, and powders targeting protein, antioxidant, and mineral supplementation. Direct-to-consumer subscription models bypass wholesale distribution in US and German markets.
- Wastewater Treatment:Algal biomass cultivation for nutrient recovery and heavy metal sequestration from industrial effluent. Municipal utilities in Israel and California deploy hybrid photobioreactor systems.
- Bioplastics:Polyhydroxyalkanoates and polylactic acid feedstocks from high-lipid strains. EU F-Gas Regulation restrictions on conventional polymers indirectly support investment.
- Biofuel Production:Biodiesel and aviation fuel precursors from microalgal lipids, with fermentation-platform developers in Brazil and Singapore advancing heterotrophic cultivation.
- Fertilizer:Seaweed-based soil amendments and foliar sprays, with Indian and Chinese agricultural cooperatives driving volume through government subsidy programs.
- Cosmetics Formulation:Pigments, moisturizers, and anti-aging actives requiring cosmetic-grade extraction and preservative-free stabilization.
Dietary supplements anchor current revenue; bioplastics application is expanding most quickly as polymer substitution accelerates.
Packaging Type:
Channel economics dictate format selection, with bulk bags serving ingredient manufacturers while unit-dose formats capture retail margin.
- Bulk Bags:500-1000 kg flexible intermediate bulk containers for industrial processors and formulators. Food and feed manufacturers in China's Shandong province receive kelp and spirulina in this format.
- Bottles:HDPE and glass containers for tablet and capsule retail distribution. German and US supplement brands specify child-resistant closures and desiccant inserts.
- Sachets:Single-serve powder packets for convenience positioning in Asian markets. South Korean and Japanese direct-to-consumer brands favor this format.
- Tins:Metal containers for premium whole-leaf seaweed and specialty food positioning. Irish and French Atlantic dulse harvesters use this format for gourmet retail.
- Jars:Wide-mouth containers for protein powders and bulk supplements. US warehouse clubs and European pharmacy chains stock this format.
- Blister Packs:Unit-dose thermoformed packaging for pharmaceutical and clinical trial applications. FDA and EMA serialization requirements drive specification.
Bulk bags dominate tonnage today; sachets are climbing fastest in direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phycologist talent pools concentrate in coastal research corridors where universities maintain dedicated algae biology programs and pilot-scale cultivation facilities.
United States
California's nutraceutical formulators drive demand for organic-certified spirulina and chlorella powders. FDA GRAS notification timelines for novel strains extend 18-24 months, freezing commercial launch schedules for domestic-targeted ingredients. The Imperial Valley hosts open-pond cultivation clusters serving West Coast dietary supplement brands.
Germany
EFSA novel food assessments determine which microalgal strains reach European nutraceutical channels. German manufacturers now mandate irradiation documentation and heavy metal testing for every spirulina batch under tightened guidelines. Bavarian processing facilities specialize in closed photobioreactor configurations for organic-certified product lines.
China
Shandong province's kelp processing clusters compress logistics costs for Asian cosmetics formulators seeking hydrocolloid feedstock. NMPA health food blue-hat registration governs strain entry into commercial channels. Local equipment makers in Qingdao have specialized in bead-milling technology for chlorella cell wall disruption.
Brazil
ANVISA feed additive approvals for algae-derived omega-3 open formulation pathways for salmon and shrimp producers. Aquaculture operations in Santa Catarina state seek fish oil alternatives for premium export certification. Heterotrophic cultivation platforms in São Paulo advance year-round output independent of sunlight constraints.
Israel
The Arava Desert anchors high-value astaxanthin production through specialized cultivation in controlled photobioreactor environments. Single-point vulnerability concerns persist for global carotenoid supply. Kibbutz-based research facilities collaborate with international cosmetics houses on chain-of-custody documentation requirements.
Algae Products Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across cultivation technology and downstream extraction capabilities. The vendor base stratifies between integrated agricultural processors, dedicated algae biotechnology firms, and fermentation-platform developers. Three archetypes dominate: global ingredient distributors with captive supply agreements, desert-based carotenoid specialists leveraging extreme climate conditions, and fermentation-technology developers decoupled from photosynthetic constraints. Competitive moves concentrate on multi-year offtake agreements with cosmetics formulators and modular photobioreactor capacity expansion.
Among diversified agricultural processors, Cargill, Incorporated and Archer Daniels Midland Company represent scale-driven supply chain integrators securing multi-origin feedstock. BASF SE anchors the fermentation-platform tier through heterotrophic cultivation capabilities. Algatechnologies exemplifies the climate-specialist archetype through Arava Desert-based operations.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Cyanotech Corporation |
| Corbion |
| BASF SE |
| dsm-firmenich |
| Algatechnologies |
| Earthrise Nutritionals |
| Archer Daniels Midland Company |
| Cellana Inc |
| Others |
Cost & Logistics Intelligence
EU Green Deal sustainability mandates gate qualified supply and premium-tier pricing access, as EFSA novel food certification and organic cultivation documentation become non-negotiable entry requirements for European nutraceutical buyers. Clean-label procurement specifications from German and South Korean formulators now exclude uncertified biomass, compressing supplier pools and elevating price premiums for compliant originators.
Pricing Analysis
Bundle-unbundle service splits separate spot-market biomass from multi-year offtake agreements with embedded quality certification and chain-of-custody documentation. Three-tier pricing structure across premium, standard, and economy levels tracks cultivation system type, with closed photobioreactor output commanding raw material premiums over open-pond supply. Price differentiation hinges on organic certification status and irradiation documentation depth. Cost compression in standard-tier chlorella runs through mechanical cell-wall disruption inefficiencies. Contract feed manufacturers show highest price sensitivity; cosmetics formulators absorb steepest premiums for single-origin astaxanthin.
Supply Chain Analysis
Regional distribution centers in Germany, California, and China's Shandong province anchor warehouse-distribution layers, with hub-and-spoke patterns radiating to cosmetics clusters in South Korea and aquafeed processors in Brazil. Cultivation concentrates in Israel's Arava Desert, Hawaii, and Shandong's coastal zones. Raw material flows draw from nitrogen and phosphorus fertilizer inputs, sugar feedstocks for heterotrophic platforms, and coastal kelp harvests. Single-source vulnerability for high-value carotenoid supply creates structural risk exposure. Distribution runs through vertically integrated processors with captive laboratory capacity rather than trading-house intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with buyer procurement patterns shifting decisively toward premium specifications that bundle traceability, organic certification, and strain-specific health claims.
For Market Incumbents: Anchor market position through backward integration into closed photobioreactor capacity in Germany and California, securing organic-certified output pools that emerging pond-dominant competitors cannot replicate. Absorb EFSA novel food registration costs through captive laboratory infrastructure, creating compliance moats against smaller extractors facing consolidation pressure. Defend against fermentation-platform developers by emphasizing photosynthetic origin storytelling in cosmetics channels. For New Entrants and Emerging Players: Enter via Brazilian aquafeed formulation partnerships, where ANVISA approval pathways for algae-derived omega-3 remain underpenetrated relative to saturated nutraceutical channels. Target direct-to-consumer subscription models in US wellness demographics, bypassing wholesale distribution margin compression. Lead with heterotrophic cultivation platforms in temperate climates, decoupling production from sunlight constraints that limit incumbent geographic flexibility. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale processors with EFSA registration completed but lacking downstream brand equity, offering tuck-in consolidation upside for integrated players. Long-term viability over the next decade rests on regulatory science keeping pace with strain diversity expansion. Watch FDA GRAS notification timeline compression as the inflection signal indicating whether US market entry accelerates or remains frozen.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Registration | Unlocks EU nutraceutical channel access for spirulina and chlorella strains. |
| Closed Photobioreactor Expansion | Compresses contamination rates while elevating organic certification premiums. |
| Heterotrophic Cultivation Platform | Decouples production from sunlight constraints via sugar feedstock conversion. |
| Multi-Year Offtake Agreements | Replaces spot-market purchasing with chain-of-custody documentation for cosmetics formulators. |
| Direct-to-Consumer Subscription Launch | Captures retail margin through recurring revenue models in wellness-focused demographics. |
Research Approach
Bottom-up nutraceutical and cosmetics demand modeling reconciled against top-down cultivation capacity tracking forms the analytical core of this study. Primary interviews with phycologists at Israeli kibbutz research facilities, procurement leads at German supplement manufacturers, regulatory affairs directors navigating EFSA pathways, and South Korean cosmetics formulators were cross-validated against secondary sources including EFSA novel food approvals database, FDA GRAS notification filings, ANVISA feed additive registers, and trade flow records from Indonesian carrageenan processors. Customs data from China's Shandong province and NMPA health food blue-hat registrations provided supply-side triangulation.
Historical trendline analysis of photobioreactor deployment rates, strain approval timelines, and substitution patterns for synthetic additives informed projection frameworks across the analysis window. Segmentation dimensions modeled include cultivation system type, end-use industry channel, certification tier, and regional regulatory cluster. CAGRs were derived from slope analysis of volume trajectories adjusted for input cost volatility in nitrogen and phosphorus markets. Forecast inputs incorporated phycologist talent pipeline constraints and GRAS review period extensions.
Inputs from EFSA, FDA, and NMPA regulatory databases were available through the study window; gaps in real-time strain-level production data from Israeli and Hawaiian astaxanthin facilities introduce uncertainty bands around high-value carotenoid supply forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Mycoprotein Market
Alternative Food Sources
Emergency Food Market
Alternative Food Sources
Edible Packaging Market
Alternative Food Sources
Teff Products Market
Alternative Food Sources
Flaxseed Based Egg Market
Alternative Food Sources
Black Soldier Fly (BSF) Market
Alternative Food Sources
Meal Replacement Bars Market
Alternative Food Sources
Vegan Tuna Market
Alternative Food Sources
Low Calorie Rice Market
Alternative Food Sources
South American Algae Protein Market
Alternative Food Sources
Vegan Ham Market
Alternative Food Sources
North America Edible Insects Market
Alternative Food Sources
Vegetable Proteins Market
Alternative Food Sources
Fish Meal Alternative Market
Alternative Food Sources
Single Cell Oil Market
Alternative Food Sources
Gluten Substitute Market