
 Vegan Casing Market | 2026-2036
Vegan Casing Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Casing Market Analytics
Multi-source procurement for hydrocolloid feedstocks is decoupling from traditional single-source collagen dependence across European sausage casing supply chains. Viscofan Group leverages its Spanish manufacturing base to sustain vertically integrated cellulose output. Kalle GmbH anchors German market access through specialized alginate formulations. Euroduna Food Ingredients GmbH competes on pea protein extrusion technology tailored to mid-sized meat substitute producers.
Vegan casing denotes edible or non-edible tubular membranes manufactured from plant-derived hydrocolloids—typically 20-50 micrometer wall thickness, 15-40 millimeter calibrated diameters, and moisture retention capacities exceeding 85%—engineered to mimic the tensile strength and snap of animal-derived intestines during thermal processing. Alginate and pea protein formulations are capturing the fastest expansion as meat substitute manufacturers demand thermally stable casings that withstand smokehouse cycles above 70 degrees Celsius. Cellulose retains volume leadership in processed foods where cost-sensitive industrial buyers prioritize throughput over premium mouthfeel.
EU Green Deal sourcing requirements, EFSA novel food approvals, and REACH chemical compliance collectively constrain raw material qualification timelines and elevate documentation burdens for new entrants. FDA GRAS self-affirmation pathways shape US market access for alginate and seaweed-derived alternatives, though FSIS labeling scrutiny limits direct claims on finished sausage products. Stakeholders must monitor evolving enzymatic cross-linking patents and biopolymer blend ratios as the primary battleground for performance differentiation and margin capture.
Market Dynamics
EU Green Deal mandates are forcing alginate and pea protein casing qualification timelines to compress while REACH documentation burdens multiply, restructuring supplier-buyer power balances across European food processing supply chains.
Growth Catalysts
- EFSA Novel Food Pathways:Streamlined approvals for seaweed-derived hydrocolloids are accelerating alginate casing commercialization for meat substitute manufacturers in Western Europe.
- Clean-Label Reformulation:Mid-sized plant-based sausage producers are mandating ingredient transparency that eliminates animal-derived collagen from supplier specifications.
- Enzymatic Cross-Linking:Patent-protected biopolymer binding technologies are improving thermal stability above 70 degrees Celsius, enabling smokehouse processing parity with traditional casings.
Market Restraints
- Input Cost Volatility:Seaweed harvest fluctuations and pea protein concentrate shortages are compressing margins for hydrocolloid casing producers dependent on agricultural commodity cycles.
- Supply Concentration Risk:Spanish cellulose manufacturing clusters control upstream viscose supply, creating single-source vulnerability for industrial buyers prioritizing cost-sensitive throughput.
- Technical Performance Gaps:Moisture retention above 85% during extended thermal cycles remains inconsistent across plant-based formulations versus collagen benchmarks.
Strategic Opportunities
- Underpenetrated German Mid-Tier:Specialized alginate formulations tailored to mid-sized meat substitute producers outside Viscofan's vertical integration capture represent serviceable white space.
- FDA GRAS Self-Affirmation:US market entry pathways for alginate alternatives bypass lengthy pre-market approvals, enabling faster geographic diversification for European suppliers.
- Biopolymer Blend Convergence:Combining pea protein with carrageenan or konjac is unlocking texture profiles that expand beyond sausage applications into plant-based seafood analogs.
Industry Challenges
- Cross-Functional Talent Scarcity:Food science expertise spanning hydrocolloid chemistry, thermal processing engineering, and regulatory affairs commands premium compensation and extends hiring cycles.
- Certification Timeline Compression:EFSA novel food dossier preparation and REACH chemical safety documentation require 18-24 month investment horizons that strain working capital for new entrants.
- Legacy Equipment Retrofit Costs:Existing collagen casing production lines demand capital-intensive modification to handle alginate viscosity profiles and moisture sensitivity during extrusion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Casing Market |
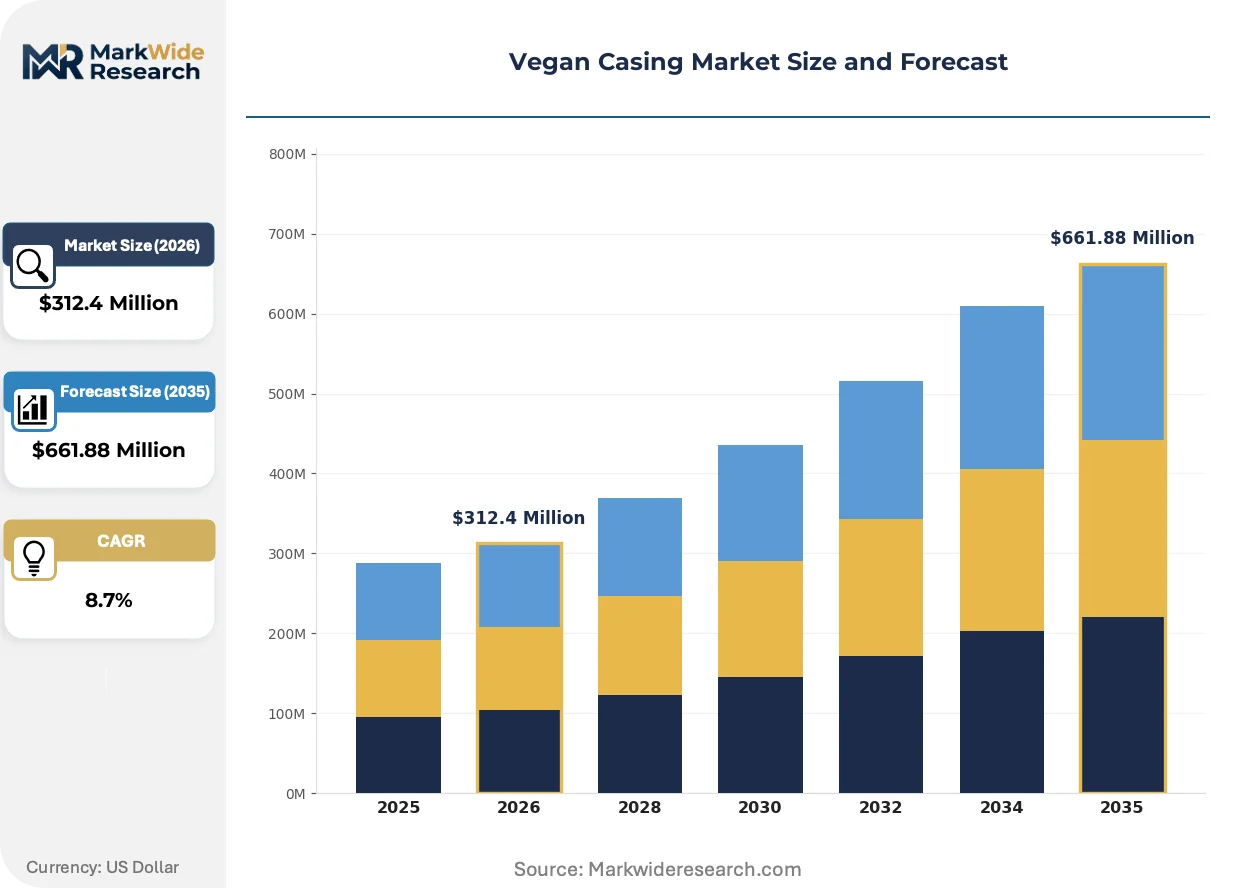
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulose, Alginates, Seaweed, Pea Protein Application: Processed Foods, Meat Substitutes, Dairy Alternatives, Snack Foods End User: Food Manufacturers, Restaurants, Retailers, Home Cooks Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Viscofan Group, Soreal-Ilou, Kalle GmbH, Ruitenberg Ingredients B.V., The Sausage Maker Inc., Weschenfelder Direct Limited, Ennio International, Promar, Euroduna Food Ingredients GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Casing Market Evolving Landscape
Biopolymer formulation science is compressing performance gaps between plant-derived and animal-derived casings while regulatory documentation requirements reshape competitive moats around supplier qualification capabilities.
Enzymatic cross-linking of alginate-carrageenan blends is consolidating thermal stability benchmarks previously exclusive to collagen. Mid-sized meat substitute manufacturers in Germany and the Netherlands are adopting these formulations at accelerated qualification cycles. The technology is consolidating supplier tiers by eliminating performance-based switching costs that previously protected incumbent animal-derived casing producers.
REACH chemical compliance and EFSA novel food approval requirements are tightening raw material traceability standards. Documentation burdens for new hydrocolloid entrants now exceed 24-month qualification windows. Specialty alginate suppliers with established dossier libraries are capturing disproportionate share among reformulating Western European food processors.
Direct procurement contracts between casing formulators and plant-based meat brands are displacing traditional distributor intermediaries. Large sausage manufacturers are unbundling specification-setting from volume purchasing to secure supply chain transparency. This pattern concentrates most visibly in German and Dutch food processing hubs where clean-label mandates have become non-negotiable tender requirements.
Vegan Casing Market Segmentation
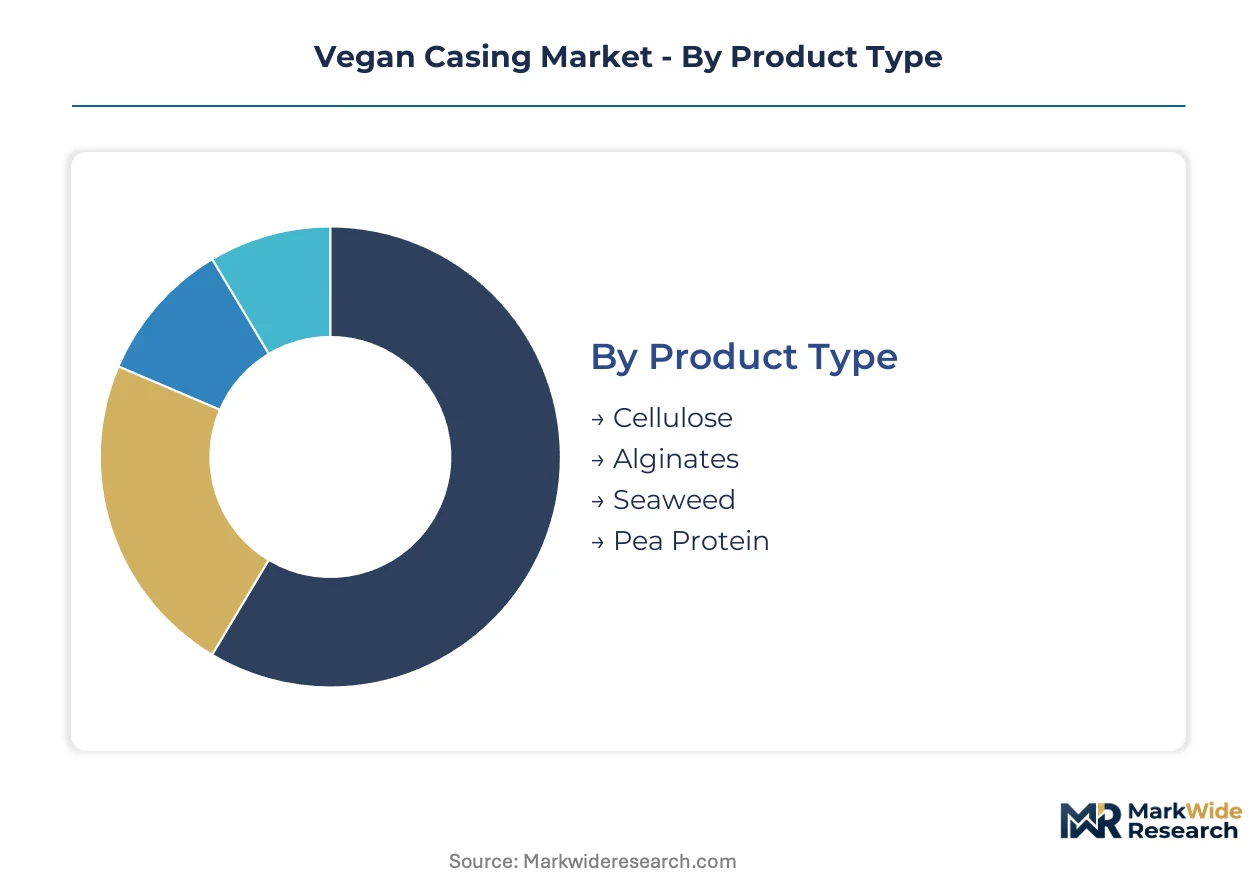
Vegan casing procurement decisions hinge on certification requirements that vary sharply by material chemistry and end-use exposure. EFSA novel food approvals for seaweed-derived inputs and REACH documentation for hydrocolloid blends create divergent qualification burdens across segment boundaries.
Product Type:
EFSA novel food pathways and REACH chemical dossier requirements split this category by raw material origin—marine-derived inputs face distinct approval timelines versus agricultural feedstocks.
- Cellulose:Wood-pulp derived viscose membranes deliver calibrated diameters from 15-40 millimeters with moisture retention above 85%. Spanish manufacturing clusters supply industrial food processors prioritizing cost-sensitive throughput over premium mouthfeel.
- Alginates:Seaweed-extracted hydrocolloids form thermally stable casings withstanding smokehouse cycles above 70 degrees Celsius. German meat substitute manufacturers are scaling alginate purchases as EU Green Deal sustainability mandates tighten ingredient sourcing standards.
- Seaweed:Whole-marine biomass formulations leverage novel food approval streams for direct consumer-facing claims.
- Pea Protein:Legume-derived extrusions require enzymatic cross-linking patents to achieve tensile parity with collagen benchmarks.
Cellulose sits at the top of the volume ranking, with alginates climbing the fastest.
Application:
Clean-label reformulation intensity and thermal processing demands segment this category by performance threshold and ingredient transparency requirements.
- Processed Foods:Industrial sausage production tolerates functional compromises in exchange for cost efficiency and supply security.
- Meat Substitutes:Plant-based sausage manufacturers mandate thermally stable casings that survive extended smokehouse exposure without compromising snap or bite. Western European food processing hubs concentrate demand where reformulation has become standard practice.
- Dairy Alternatives:Fermented analog applications require moisture barriers distinct from meat-processing specifications.
- Snack Foods:Bite-sized format producers prioritize uniform diameter calibration and rapid production line compatibility.
Processed Foods maintains volume leadership, with Meat Substitutes expanding most quickly.
End User:
Specification authority and procurement scale separate this category—large manufacturers set supplier qualification standards that cascade downstream.
- Food Manufacturers:Direct procurement contracts unbundle specification-setting from volume purchasing to secure supply chain transparency. Large sausage manufacturers in Germany and the Netherlands are displacing traditional distributor intermediaries.
- Restaurants:Foodservice operators demand consistent performance across batch sizes with minimal preparation complexity.
- Retailers:Private-label brands impose clean-label mandates as non-negotiable tender requirements.
- Home Cooks:Consumer-packaged formats prioritize convenience and instructional clarity over industrial performance metrics.
Food Manufacturers command the largest procurement volumes, with Retailers gaining share fastest.
Distribution Channel:
Supply chain transparency requirements and order fragmentation costs determine channel viability for different casing formats and customer scales.
- Online Retail:Digital platforms serve specialty ingredient buyers seeking small-batch alginate and pea protein formulations with documented provenance.
- Supermarkets:Mass-market retail chains consolidate procurement for standardized cellulose grades across multiple supplier relationships.
- Specialty Stores:Gourmet food retailers curate premium hydrocolloid options targeting artisanal meat substitute producers.
- Direct Sales:Large food manufacturers negotiate direct contracts with casing formulators to bypass distributor markups and secure volume commitments.
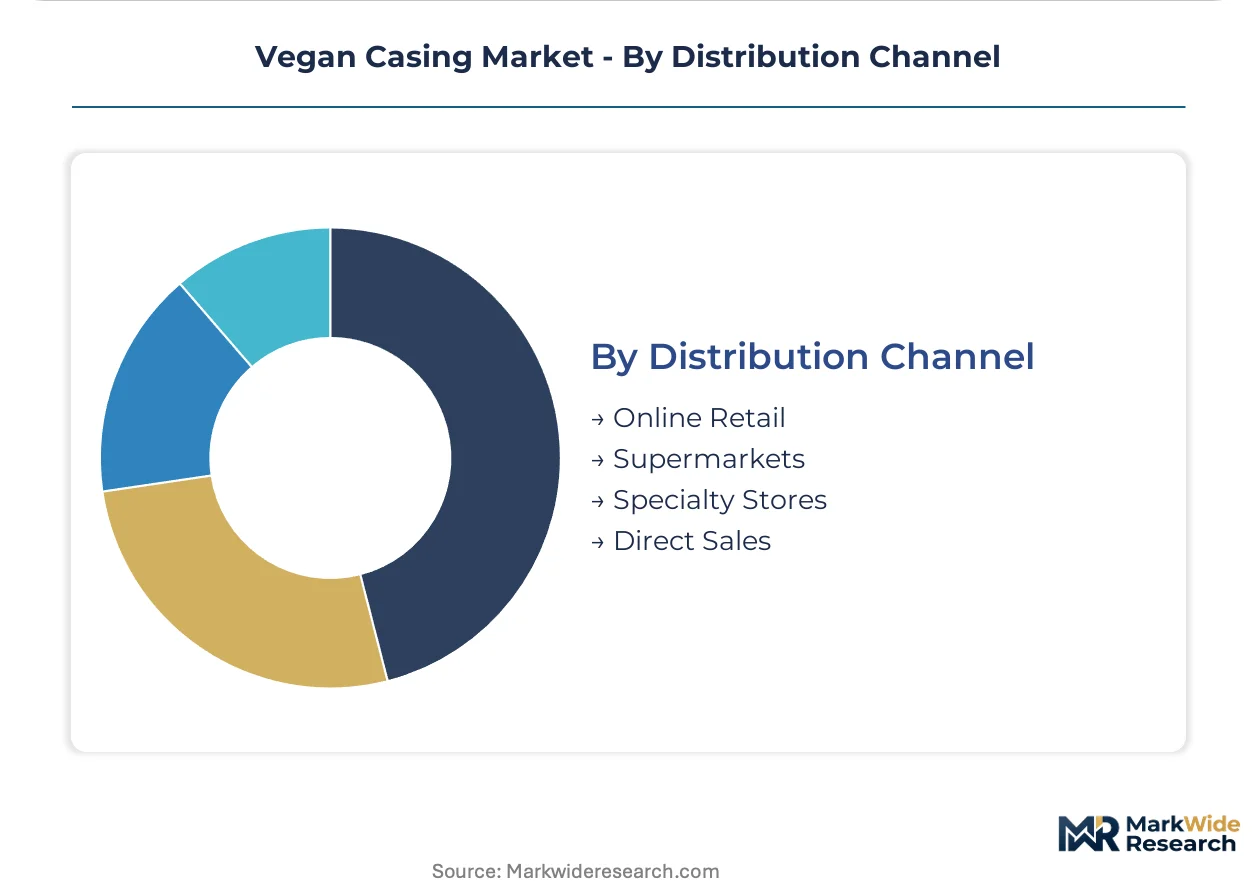
Direct Sales dominates volume flows, with Online Retail expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German food processing clusters concentrate alginate casing procurement as EU Green Deal mandates reshape ingredient sourcing standards across Western European supply chains.
Germany
Meat substitute manufacturers in Baden-Württemberg and Lower Saxony are scaling alginate purchases to meet clean-label tender requirements. EFSA novel food dossiers for seaweed-derived hydrocolloids now dominate supplier qualification timelines. Stuttgart-based industrial buyers are unbundling specification-setting from volume purchasing to secure supply chain transparency.
Spain
Cellulose production clusters around Barcelona and Valencia supply cost-sensitive industrial processors across Southern Europe. REACH chemical compliance documentation for viscose-derived membranes creates regulatory moats for established Spanish manufacturers. Madrid-headquartered food brands are consolidating procurement through direct contracts rather than distributor intermediaries.
Netherlands
Plant-based sausage producers in the Randstad region demand thermally stable casings withstanding smokehouse cycles above 70 degrees Celsius. EU Green Deal sustainability mandates have tightened to non-negotiable status in Dutch tender specifications. Eindhoven-area food technology hubs are piloting enzymatic cross-linking patents for pea protein-alginate blends.
United Kingdom
Mid-sized meat substitute manufacturers in the Midlands are reformulating to eliminate collagen from supplier specifications. The Food Standards Agency's novel food consultation pathways are compressing approval timelines for seaweed-derived alternatives. London-based retail chains are imposing clean-label mandates as mandatory procurement criteria.
France
Artisanal sausage producers in Auvergne-Rhône-Alpes are adopting premium hydrocolloid casings for gourmet positioning. ANSM and DGCCRF oversight of food contact materials elevates documentation burdens for new hydrocolloid entrants. Lyon-area food processing clusters are negotiating direct procurement contracts with alginate formulators.
Vegan Casing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized alginate and pea protein formulations for premium meat substitute applications. The supplier base stratifies between vertically integrated cellulose manufacturers, hydrocolloid specialists with EFSA dossier libraries, and regional extrusion technology providers. Three archetypes dominate: Spanish cellulose incumbents with captive viscose supply, German alginate formulators anchored in industrial customer relationships, and mid-tier European ingredient houses competing on qualification speed. Competitive moves center on backward integration into seaweed harvesting and enzymatic cross-linking patent licensing.
Among German specialists, Kalle GmbH and Euroduna Food Ingredients GmbH exemplify the hydrocolloid formulation archetype, occupying positions tied to regional industrial customer access. Viscofan Group represents the vertically integrated standard, anchoring volume supply through Spanish manufacturing concentration. These three entities illustrate the structural division between cost-driven cellulose throughput and premium alginate performance positioning.
| Leading Market Players |
|---|
| Viscofan Group |
| Soreal-Ilou |
| Kalle GmbH |
| Ruitenberg Ingredients B.V. |
| The Sausage Maker Inc. |
| Weschenfelder Direct Limited |
| Ennio International |
| Promar |
| Euroduna Food Ingredients GmbH |
| Others |
Value Network & Pricing Analysis
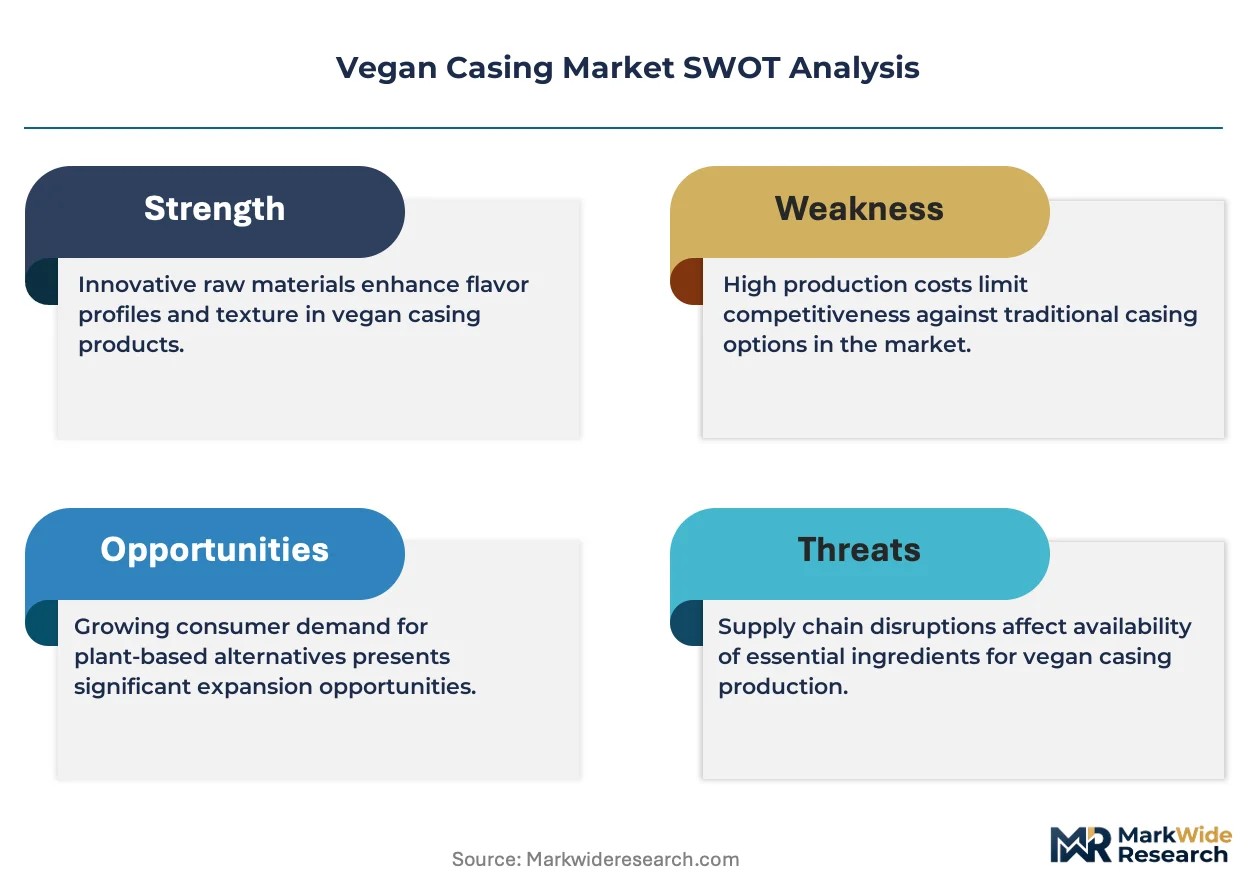
Enzymatic cross-linking patent licensing is simultaneously elevating R&D amortization costs for premium alginate formulations and fragmenting supply concentration among specialized German hydrocolloid formulators. This technology transition compresses margin structures for cellulose incumbents while rewarding EFSA-qualified alginate suppliers with pricing power anchored in 24-month dossier investments.
Pricing Analysis
Seaweed harvest volatility and pea protein concentrate shortages drive input-cost pass-through into alginate casing quotations. Three-tier pricing structure across premium enzymatic-cross-linked, standard thermally-stable, and economy cellulose grades separates performance tiers. Cost compression in standard cellulose intensifies because Spanish manufacturing clusters prioritize throughput volume over margin capture. Industrial food manufacturers exhibit highest price sensitivity, while mid-sized German meat substitute producers accept premium tiers for clean-label compliance.
Supply Chain Analysis
Freight cost differentials between Spanish cellulose manufacturing clusters and German alginate formulators shape procurement geography for Western European food processors. Supply draws from Spain, Germany, and the Netherlands as primary production hubs. Raw material dependencies center on Norwegian seaweed biomass, French pea protein concentrate, and wood-pulp viscose feedstocks. Single-source vulnerability concentrates in Spanish viscose supply controlled by vertically integrated cellulose incumbents. Distribution runs through direct procurement contracts displacing traditional distributor intermediaries among large sausage manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vegan casing market functions as a stable compounder, with EU Green Deal regulatory mandates ensuring sustained ingredient reformulation demand across European food processing supply chains.
For Market Incumbents: Deploy enzymatic cross-linking patent licensing to defend margin position against emerging alginate specialists. Capture backward integration into Norwegian seaweed harvesting to secure feedstock cost control. Accelerate EFSA dossier library expansion to extend qualification-timeline advantages over new hydrocolloid entrants. For New Entrants and Emerging Players: Launch via direct sales contracts targeting mid-sized German meat substitute manufacturers outside Viscofan's vertical integration capture. Exploit white space in specialized pea protein-carrageenan blends for plant-based seafood analogs. Pursue FDA GRAS self-affirmation pathways for faster US geographic diversification versus European regulatory timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier alginate formulators with established EFSA dossiers but limited backward integration. Long-term viability favors suppliers bridging hydrocolloid chemistry expertise with thermal processing engineering capability. Watch enzymatic cross-linking patent expiration schedules as inflection signal for competitive margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Harvesting | Captures Norwegian biomass supply to reduce alginate feedstock cost volatility. |
| EFSA Novel Food Dossier Expansion | Extends 24-month qualification moats against new hydrocolloid market entrants. |
| Enzymatic Cross-Linking Patent Licensing | Unlocks thermal stability above 70 degrees Celsius for smokehouse parity. |
| Direct Procurement Contract Negotiation | Bypasses distributor markups for large German sausage manufacturer accounts. |
| FDA GRAS Self-Affirmation Pathway | Accelerates US market entry timelines versus European pre-market approval requirements. |
Research Methodology
Multiple input streams — regulatory filing databases, hydrocolloid trade flow records, and food processor procurement disclosures — were reconciled to construct segment-level estimates. Primary interviews with alginate formulator R&D directors, sausage manufacturer procurement leads, EFSA regulatory consultants, and seaweed biomass traders informed qualification timeline and cost structure assumptions. Secondary validation drew from REACH chemical safety dossiers, EU Green Deal implementation reports, and Spanish cellulose production statistics. Bottom-up casing volume estimates and top-down meat substitute market sizing were cross-referenced for triangulation.
Historical capacity expansion patterns were cross-referenced against expert panel input on enzymatic cross-linking adoption curves across the projection horizon. Segmentation modeling spanned material chemistry, thermal performance tier, end-use application, and customer scale dimensions. CAGRs were derived from slope analysis of ingredient substitution trajectories and regulatory mandate implementation schedules. Forecast inputs incorporated EFSA novel food approval velocity, pea protein concentrate supply elasticity, and clean-label tender penetration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under seaweed harvest disruption or REACH documentation requirement expansion. Model outputs reflect assumptions on EU Green Deal enforcement consistency and alginate thermal performance gap closure rates. A model refresh is warranted upon material change in EFSA novel food pathway streamlining or enzymatic cross-linking patent landscape shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Vegan Sashimi Market
Alternative Food Sources
Global Algal Oil Market
Alternative Food Sources
Africa Potato Protein Market
Alternative Food Sources
North America Meat Substitutes Market
Alternative Food Sources
Flour Substitutes Market
Alternative Food Sources
Vegan Eggs Market
Alternative Food Sources
Middle East and Africa Meal Replacement Products Market
Alternative Food Sources
Global Alternative Protein Market
Alternative Food Sources
North America Precision Fermentation Market
Alternative Food Sources
Asia-Pacific Meat Substitutes Market
Alternative Food Sources
Precision Fermentation Market
Alternative Food Sources
North America Meal Products Replacement Market
Alternative Food Sources
United States Hemp Protein Market
Alternative Food Sources
North America Algae Protein Market
Alternative Food Sources
North America Edible Insects Market
Alternative Food Sources
Algae Products Market