
 Nutritional Oil Powder Market | 2026-2036
Nutritional Oil Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Nutritional Oil Powder Market Outlook
Subscription-based replenishment models for nutritional oil powders is expanding how manufacturers monetize customer relationships beyond one-time transactions. ABITEC leverages its lipid chemistry expertise to supply specialized oil powder bases for sports nutrition brands. Bioriginal Food & Science Corp anchors its position through vertically integrated flaxseed and hemp oil sourcing from North American growers. Stepan Company differentiates via microencapsulation technology that extends product stability in challenging formulation environments.
Nutritional oil powder comprises spray-dried or freeze-dried lipid droplets encapsulated within carbohydrate or protein matrices, typically achieving 50-70% oil load with particle sizes between 100-300 microns for optimal dispersibility in beverages and dry mixes. The ingredient serves industrial formulators seeking to infuse omega fatty acids, medium-chain triglycerides, or plant sterols into shelf-stable products without liquid oil handling constraints. MCT oil powders lead product type demand due to ketogenic diet proliferation and rapid gastric emptying properties prized by athletes. Sports nutrition and dietary supplements command the dominant application share, while skin care represents an emerging margin pool as cosmetic brands adopt oil powders for anhydrous balm formulations.
FDA GRAS self-affirmation pathways and EFSA novel food authorizations shape ingredient market access timelines for nutritional oil powders entering American and European supply chains. BIS quality certification requirements in India and NMPA registration protocols in China add compliance layers for exporters targeting Asia-Pacific expansion. Stakeholders must monitor evolving clean-label thresholds and encapsulation technology patents that could redraw competitive boundaries in functional ingredient supply.
Market Dynamics
Microencapsulation technology maturation is redistributing competitive advantage from commodity lipid suppliers toward formulation-technology specialists who command premium positioning through oxidative stability guarantees.
Growth Catalysts
- Ketogenic Diet Proliferation:Athletes and metabolic health consumers in the United States are pulling MCT oil powders into pre-workout and meal-replacement formats at accelerating velocity.
- EFSA Novel Food Pathways:Streamlined authorization timelines for algae-derived omega powders are unlocking European sports nutrition and infant formula applications previously gated by safety data requirements.
- Spray-Drying Equipment Advances:German and Japanese engineering firms have reduced particle size variance below 50 microns, improving dispersibility in ready-to-mix beverages.
Market Restraints
- Marine Oil Input Volatility:Peruvian anchovy harvest fluctuations and Antarctic krill quota restrictions transmit directly into DHA powder cost structures.
- Chinese Encapsulant Concentration:Over 60% of modified starch and gum arabic supply for oil powder matrices originates from Shandong and Guangdong provinces, creating single-geography vulnerability.
- Flavor Masking Limitations:Fish and algae oil powders above 30% load retain perceptible off-notes that constrain inclusion rates in mainstream food applications.
Strategic Opportunities
- Brazilian Sports Nutrition:ANVISA's 2023 updated supplement regulations created compliance clarity that multinational brands are exploiting to localize production.
- Cosmetic Anhydrous Formulations:Skin care brands are adopting squalane and jojoba oil powders for solid balm and stick formats that eliminate preservative systems.
- Subscription Replenishment Models:Direct-to-consumer channels for personalized omega-MCT blends are capturing lifetime value beyond transactional supplement sales.
Industry Challenges
- Microencapsulation Talent Scarcity:Formulation chemists with simultaneous expertise in lipid chemistry and spray-drying process control command compensation premiums that strain mid-tier manufacturer margins.
- GRAS Self-Affirmation Complexity:FDA notification pathways for novel oil sources require 18-24 month toxicology investments that delay revenue recognition.
- Clean-Label Threshold Compression:Retailer and influencer-driven demands for "no maltodextrin" formulations are forcing costly matrix substitutions with protein or fiber carriers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutritional Oil Powder Market |
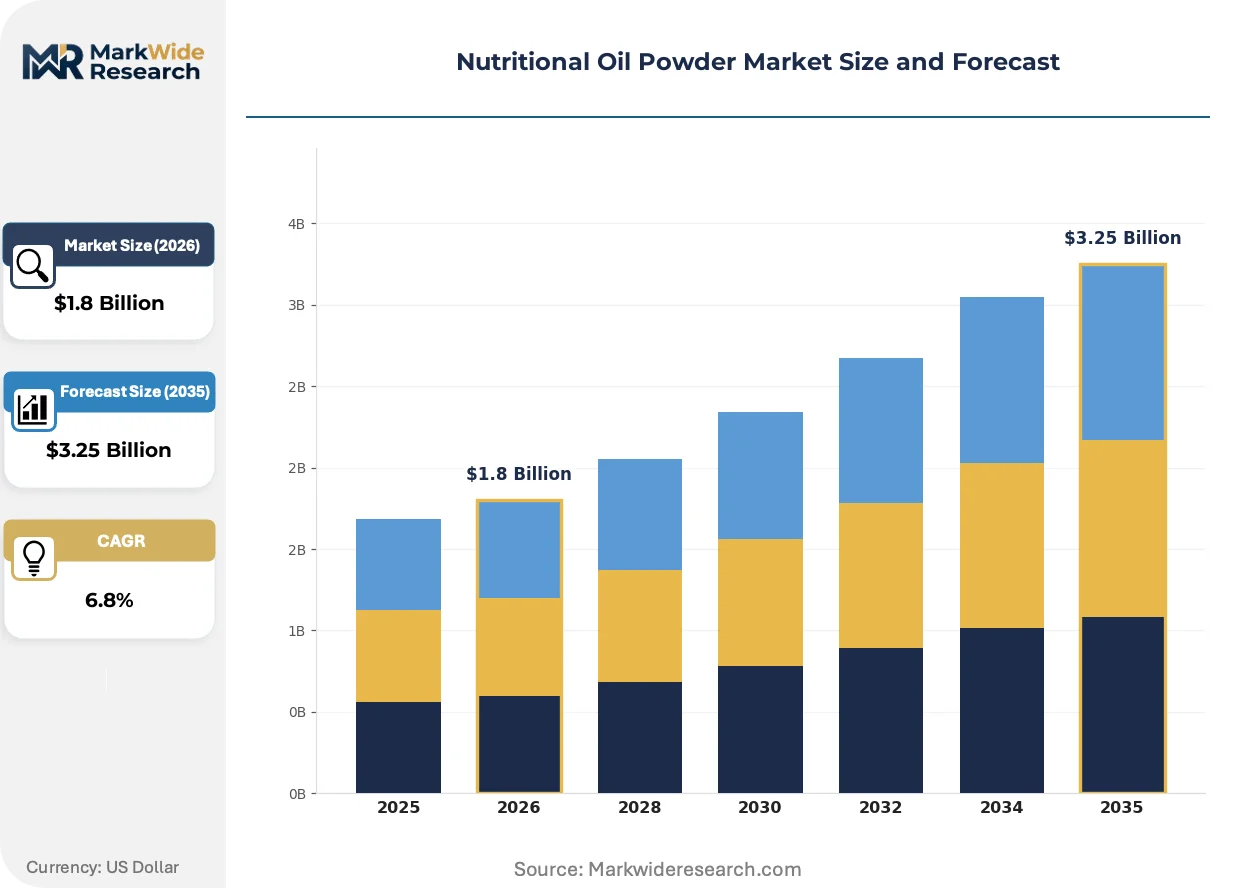
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MCT Oil, Flaxseed Oil, Hemp Oil, Olive Oil End User: Fitness Enthusiasts, Physicians, Nutritionists, Athletes Application: Sports Nutrition, Dietary Supplements, Skin Care, Food Products Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops |
| Companies Covered | ABITEC, Bioriginal Food & Science Corp, ARJUNA NATURAL PVT LTD, ConnOils LLC, Crestchem Limited, STEPAN COMPANY, THE GREEN LABS LLC, SMScor, Ming Chyi Biotechnology Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutritional Oil Powder Market Strategic Shifts
Formulation science convergence with precision nutrition platforms is collapsing the traditional separation between ingredient supply and finished-product customization. Technology providers and contract manufacturers are capturing margin that commodity suppliers previously controlled.
Coacervation-based microencapsulation is decentralizing production capability away from centralized spray-drying towers toward modular, lower-capital equipment footprints. Regional contract manufacturers in the United States and Germany are adopting these systems to offer localized oil powder production with 48-hour turnaround on custom formulations. This technology shift is compressing minimum order quantities from 10-ton batches toward 500-kilogram runs, enabling niche positioning for emerging brands.
EFSA's updated guidance on novel food safety assessments for fermented oil sources is accelerating European market entry timelines for microbial DHA and ARA powders. The regulation reduces required toxicology study packages when production organisms have established safety histories. Infant formula and medical nutrition segments in Germany and the Netherlands are the primary beneficiaries, with several suppliers advancing pipeline products toward 2025-2026 launches.
Direct-to-consumer genetic testing integration is reconfiguring how athletes and wellness consumers select omega-3 to omega-6 ratios in personalized powder subscriptions. Brands are partnering with nutrigenomics platforms to algorithmically match EPA/DHA blends to individual APOE and FADS gene variants. This behavioral shift concentrates highest-value demand in the United States and United Kingdom where testing penetration exceeds 8% of supplement-active households.
Nutritional Oil Powder Market Segmentation
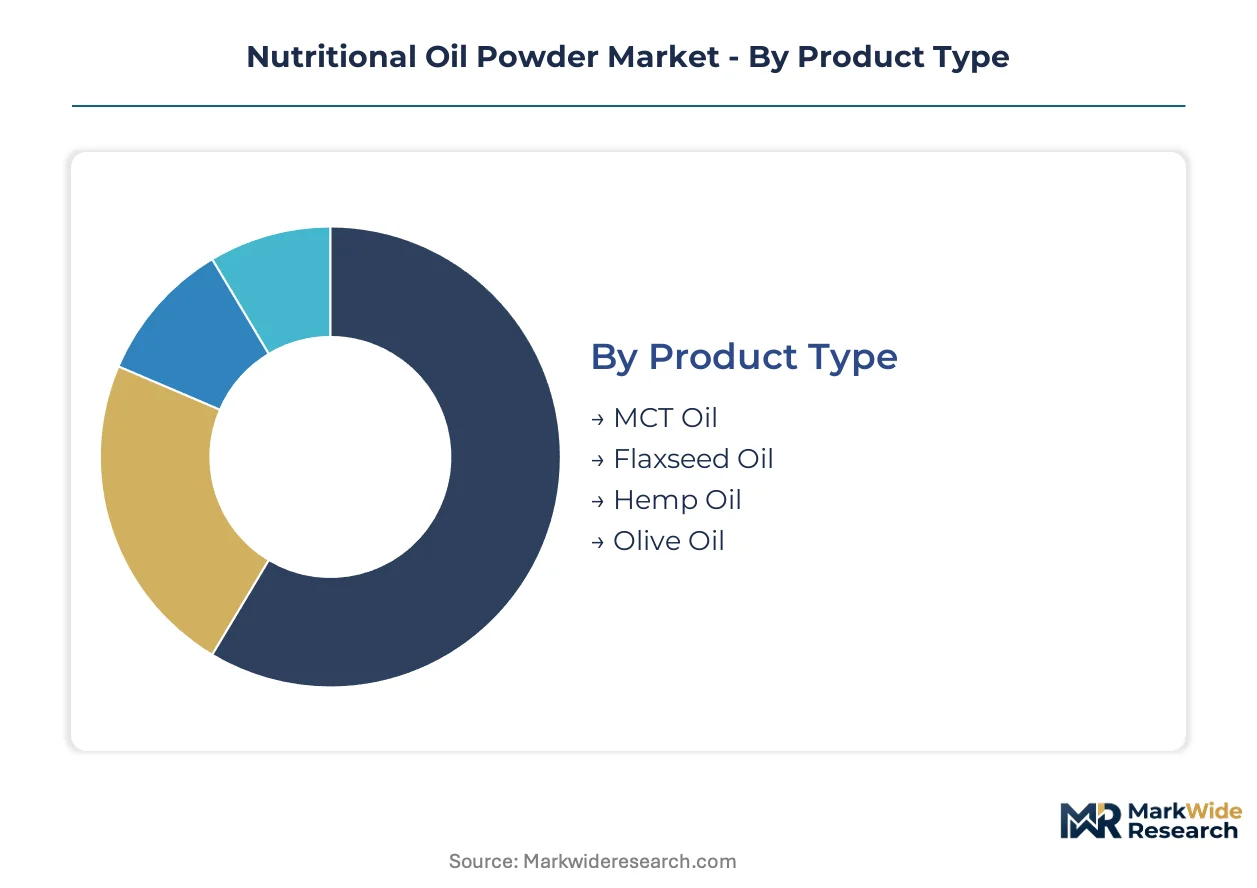
Segmentation in nutritional oil powders reveals how formulation requirements diverge across ketogenic athletes seeking rapid energy delivery versus cosmetic formulators demanding anhydrous stability. Purchase decisions hinge on oil load percentages, dispersibility thresholds, and carrier matrix transparency rather than price alone.
Product Type:
Buyers prioritize gastric emptying speed and oxidation resistance when selecting lipid sources for powder conversion.
- MCT Oil:Derived from fractionated coconut or palm kernel oil, C8-C10 triglycerides achieve 70% oil loads with rapid ketone body conversion. Demand concentrates among CrossFit communities and biohacking segments in the United States where pre-workout ketone elevation drives repeat purchase.
- Flaxseed Oil:Cold-pressed alpha-linolenic acid sources require nitrogen-flushed microencapsulation to prevent linolenic acid degradation. Organic certification premiums attract functional food manufacturers in Germany seeking EFSA-compliant novel food positioning.
- Hemp Oil:3:1 omega-6 to omega-3 ratio appeals to clean-label formulators avoiding fish-derived alternatives.
- Olive Oil:High oleic acid variants suit Mediterranean diet positioning in specialty retail channels.
MCT oil leads on scale; hemp oil leads on momentum.
End User:
Professional credentialing and performance benchmarking shape specification intensity across buyer types.
- Fitness Enthusiasts:Self-directed consumers purchasing through direct-to-subscription channels prioritize convenience and flavor masking over clinical validation. Volume concentrates in United States metropolitan markets with established ketogenic diet communities.
- Athletes:NCAA, Olympic, and professional competitors demand NSF Certified for Sport or Informed Sport verification. Procurement runs through team nutritionists and performance directors with quarterly contract structures.
- Physicians:Functional medicine practitioners prescribe condition-specific EPA/DHA ratios for metabolic syndrome protocols.
- Nutritionists:Registered dietitians influence institutional purchasing for hospital and corporate wellness programs.
Athletes dominate contract value; fitness enthusiasts dominate transaction velocity.
Application:
Formulation environment constraints—aqueous versus anhydrous, shelf-stable versus refrigerated—determine encapsulant selection and particle engineering.
- Sports Nutrition:Pre-workout powders and meal replacements require instant dispersibility below 150 microns. MCT oil powders command premium positioning in ketogenic and cyclical ketogenic protocols.
- Skin Care:Solid balm and stick formats adopt squalane and jojoba oil powders to eliminate water-phase preservatives. European cosmetic brands in France and Germany are expanding anhydrous product lines.
- Dietary Supplements:Softgel replacement powders target consumers with dysphagia or plant-based preferences.
- Food Products:Bakery and beverage applications face inclusion rate ceilings due to lipid oxidation during thermal processing.
Sports nutrition anchors volume; skin care captures margin expansion.
Distribution Channel:
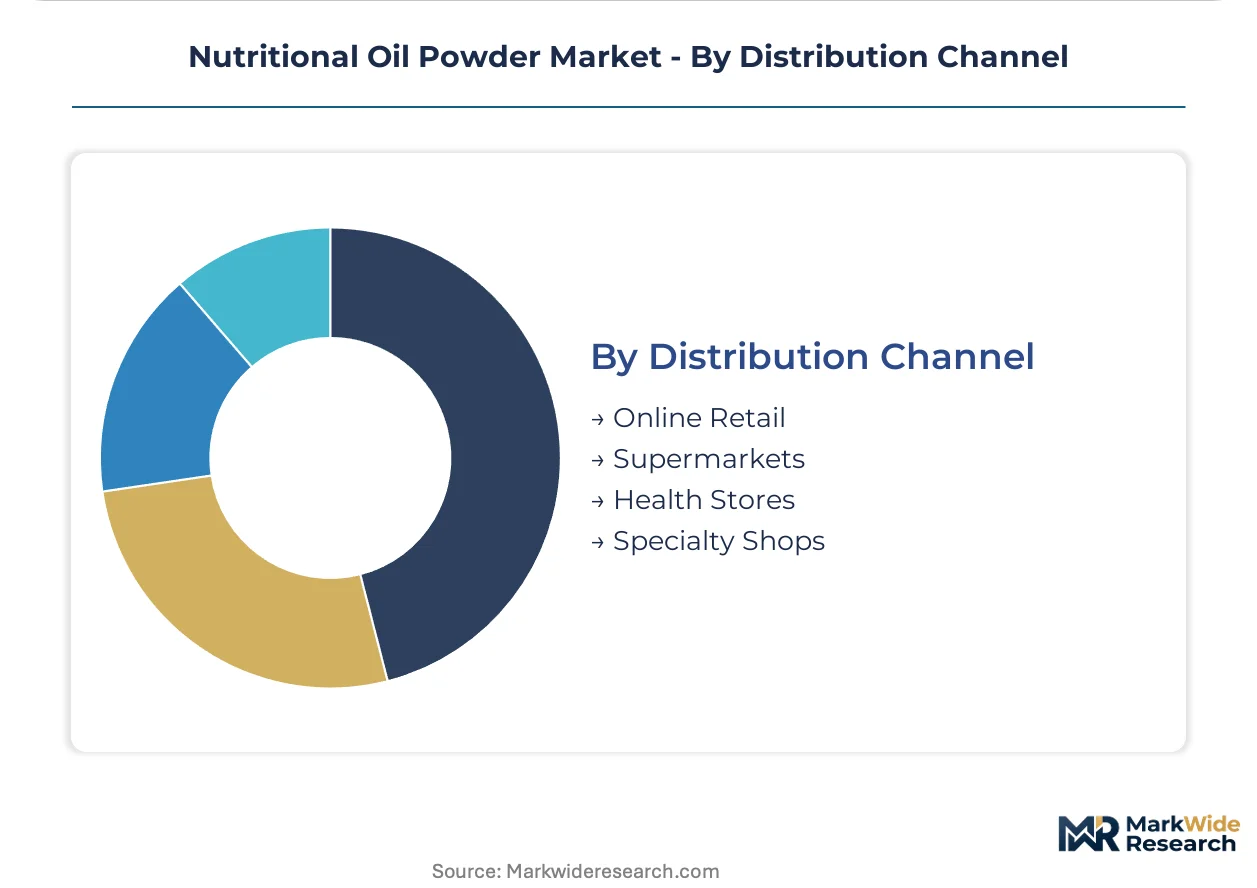
Channel selection reflects purchase frequency, education requirements, and subscription attach rates.
- Online Retail:Amazon, brand-direct sites, and specialized platforms enable personalized omega-MCT blending with nutrigenomic integration. Subscription models capture lifetime value through algorithmic replenishment timing.
- Health Stores:GNC, Vitamin Shoppe, and independent retailers provide tactile evaluation and staff consultation for first-time buyers. Shelf placement near protein powders drives impulse attachment.
- Supermarkets:Mass-market penetration remains limited by price positioning and consumer education gaps.
- Specialty Shops:CrossFit boxes, yoga studios, and sports medicine clinics facilitate practitioner-endorsed trial.
Online retail leads on revenue concentration; health stores lead on customer acquisition efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between FDA GRAS self-affirmation pathways and EFSA novel food timelines is redistributing production capacity toward jurisdictions with faster market access. Manufacturers are locating spray-drying operations where compliance cost gaps favor speed-to-market over input proximity.
United States
Ketogenic diet communities in California and Texas pull MCT oil powder volumes through direct-to-subscription channels. FDA GRAS self-affirmation allows rapid commercialization of new lipid sources without pre-market notification delays. Greater Boston hosts microencapsulation R&D clusters where contract manufacturers serve sports nutrition brands with 48-hour formulation turnaround.
Germany
EFSA novel food authorizations for algae-derived omega powders unlock infant formula and medical nutrition applications. German engineering firms in Bavaria supply precision spray-drying equipment achieving sub-50-micron particle consistency. The Frankfurt-Rhine-Main corridor concentrates lipid chemistry specialists serving European functional food manufacturers.
China
NMPA registration protocols for imported oil powder ingredients create compliance barriers that domestic producers exploit. Shandong and Guangdong provinces supply over 60% of modified starch and gum arabic encapsulants globally. Yangtze River Delta contract manufacturers are upgrading to coacervation-based systems for regional brand clients.
Brazil
ANVISA's 2023 supplement regulation updates clarified import and localization requirements for multinational sports nutrition brands. São Paulo and Rio de Janeiro metro areas concentrate fitness enthusiast demand and CrossFit box distribution networks. Local contract manufacturers are installing German-origin spray-drying towers to serve Mercosur regional expansion.
India
BIS quality certification requirements for food-grade oil powders add testing layers for exporters targeting institutional buyers. Maharashtra and Gujarat house oleochemical processing clusters with backward integration into domestic palm and coconut oil supply. Functional medicine practitioners in Bengaluru and Hyderabad prescribe condition-specific omega blends, driving physician-channel demand.
Nutritional Oil Powder Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with technology-integrated suppliers capturing margin that commodity lipid traders cannot access. The vendor base organizes into three tiers: multinational ingredient houses with captive encapsulation capabilities, regional contract manufacturers with modular production systems, and pure-play lipid suppliers dependent on external powder conversion. Strategic moves concentrate on microencapsulation patent licensing and backward integration into algae or plant oil cultivation to secure input cost control.
Within the technology-specialist tier, Stepan Company and ABITEC exemplify formulation-chemistry positioning where oxidative stability guarantees command premium pricing. Bioriginal Food & Science Corp occupies a distinct archetype as a vertically integrated operator with North American oilseed sourcing control. These three entities represent the competitive spectrum from process technology dominance through supply chain captivity, with each archetype attracting different buyer types based on specification intensity and volume scale.
| Leading Market Players |
|---|
| ABITEC |
| Bioriginal Food & Science Corp |
| ARJUNA NATURAL PVT LTD |
| ConnOils LLC |
| Crestchem Limited |
| STEPAN COMPANY |
| THE GREEN LABS LLC |
| SMScor |
| Ming Chyi Biotechnology Ltd |
| Others |
Value Chain & Pricing Dynamics
Modified starch and gum arabic encapsulant costs from Shandong and Guangdong provinces cascade through three pricing tiers downstream, with bulk contract manufacturers capturing margin compression while premium-positioned brands pass through carrier matrix substitutions to sports nutrition and cosmetic formulators seeking clean-label positioning.
Pricing Analysis
Distributor margin layers separate premium microencapsulation specialists from commodity oil powder traders, with price differentiation resting on oxidative stability guarantees and NSF Certified for Sport verification tiers. Pricing pressure stems from clean-label threshold compression forcing maltodextrin-to-protein carrier substitutions. Fitness enthusiasts purchasing through direct-to-subscription channels exhibit highest price sensitivity, while cosmetic formulators for anhydrous balms demonstrate lowest sensitivity due to margin capture in finished goods.
Supply Chain Analysis
Ocean freight cost volatility from Peruvian anchovy harvest regions and Antarctic krill extraction zones transmits directly into DHA powder landed costs across United States, German, and Chinese processing hubs. Raw material dependencies center on fractionated coconut and palm kernel oils for MCT production, cold-pressed flaxseed from North American growers, and algae-derived DHA from fermentation facilities. Single-geography vulnerability concentrates in Chinese encapsulant supply, creating tariff-exposure risk. Distribution runs through regional contract manufacturers with modular coacervation systems enabling 48-hour custom formulation turnaround.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in microencapsulation technology licensing and backward integration into captive algae or plant oil cultivation, as oxidative stability guarantees command premium positioning unavailable to commodity lipid traders.
For Market Incumbents: Extend microencapsulation patent portfolios into coacervation-based modular systems to defend against regional contract manufacturers capturing formulation-margin share. Add capacity in Bavaria and Greater Boston clusters where lipid chemistry talent concentration supports 48-hour turnaround guarantees. Investment in EFSA novel food authorization capabilities creates regulatory moats against emerging algae-oil competitors. For New Entrants and Emerging Players: Cosmetic formulators seeking anhydrous squalane and jojoba oil powders for solid balm formats represent the most penetrable white-space target, with European brands in France and Germany expanding product lines fastest. Brazilian sports nutrition localization following ANVISA's 2023 regulation updates offers geographic entry with lower compliance barriers than NMPA-registered China imports. Go-to-market through direct-to-consumer nutrigenomic platform partnerships enables personalized omega-MCT blend subscriptions with algorithmic replenishment timing. For Investors and Strategic Acquirers: Consolidation pressure builds where microencapsulation talent scarcity strains mid-tier manufacturer margins and technology-specialist suppliers command valuation premiums over commodity traders. Long-term viability favors acquisition targets with captive supply of algae or plant oils and established EFSA or FDA regulatory pathways. The signal to watch is coacervation equipment adoption rates among regional contract manufacturers, indicating technology diffusion and margin compression timelines for centralized spray-drying operators.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Patent Licensing | Stepan Company's oxidative stability guarantees demonstrate premium pricing power unavailable to commodity suppliers. |
| Backward Integration into Algae Cultivation | Bioriginal's North American oilseed sourcing control captures input cost stability versus marine oil volatility. |
| Coacervation Equipment Adoption | German and United States regional manufacturers compress minimum order quantities from 10-ton toward 500-kilogram runs. |
| EFSA Novel Food Authorization Investment | Streamlined pathways for fermented DHA unlock infant formula applications in Germany and the Netherlands. |
| Nutrigenomic Platform Partnership | APOE and FADS gene variant matching concentrates highest-value demand in United States and United Kingdom testing markets. |
Study Parameters
Coverage spans United States, Germany, China, Brazil, and India, with primary inputs from each combining interviews with spray-drying process engineers, sports nutrition brand formulation directors, cosmetic R&D chemists, and regulatory affairs specialists managing EFSA novel food and FDA GRAS pathways. Secondary validation draws from customs trade data for encapsulant imports, SEC filings of publicly traded lipid suppliers, EFSA novel food authorization databases, and NMPA registration disclosure records. Bottom-up segment sizing triangulates against top-down macroeconomic indicators for functional food and supplement consumption.
Granularity-level modeling disaggregates volume and value across oil type, application environment, end-user credentialing intensity, and distribution channel subscription attach rates throughout the projection horizon. CAGRs derive from segment-specific adoption curves weighted by regulatory pathway timelines and technology diffusion rates. Industry-specific forecast inputs include ketogenic diet community penetration metrics from direct-to-consumer channels and coacervation equipment installation rates at regional contract manufacturers.
Inputs from EFSA authorization databases and NMPA registration disclosures were available through the study window; gaps in real-time proprietary formulation cost structures at private contract manufacturers introduce uncertainty bands around margin compression estimates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Fitness Cookies Market
Nutritional Supplements
Milk Powder for Pregnant Women Market
Nutritional Supplements
Folic Acid Market
Nutritional Supplements
Ready-To-Use Therapeutic Food Market
Nutritional Supplements
Activated Charcoal Supplement Market
Nutritional Supplements
Marine Collagen Market
Nutritional Supplements
North America Insoluble Dietary Fibers Market
Nutritional Supplements
Multi Nutritional Supplement Market
Nutritional Supplements
Cognition Supplements Market
Nutritional Supplements
Global Nootropics Brain Supplements Market
Nutritional Supplements
Phytonutrients Market
Nutritional Supplements
Pulse Protein Market
Nutritional Supplements
Asia Pacific Nutraceuticals Market
Nutritional Supplements
Tocotrienol Market
Nutritional Supplements
Medium-Chain Triglycerides Market
Nutritional Supplements
Vegan Collagen Powder Market