
 Egg Replacers Market | 2026-2036
Egg Replacers Market Size, Share, and Industry Trends Forecast 2026-2036
Egg Replacers Market Intelligence
North American ingredient processors is hardening as corn and soy protein concentrate output expands to serve bakery reformulation. Cargill Inc. leverages its oilseed processing infrastructure to supply lecithin-based emulsifiers that mimic egg functionality in cake and muffin applications. Kerry Group plc sustains competitive advantage through integrated flavor systems that mask off-notes in pea protein egg replacers. Corbion NV specializes in microbial fermentation-derived solutions that deliver foaming stability without allergen labeling burdens.
Egg replacers comprise functional ingredient systems formulated from plant proteins, starches, hydrocolloids, or microbial biomass to replicate the emulsification, foaming, binding, and coagulation properties of whole eggs or egg components in food production. These systems typically achieve equivalent performance at dosage rates between 0.5% and 3.0% by weight of finished product, depending on the target application and base formulation chemistry. Powder formats currently anchor volume demand among commercial bakers seeking extended shelf stability and freight efficiency, while liquid concentrates capture margin pools in ready-to-use industrial channels serving food manufacturers with continuous processing lines. Aquafaba-derived solutions represent the fastest-growing product type as chickpea processing byproduct availability scales with expanding hummus and roasted chickpea production.
FDA labeling requirements for egg allergen declarations and USDA school nutrition standards shape product development priorities for domestic manufacturers serving institutional channels. EPA biofuel mandates indirectly influence egg replacer economics by diverting soy oil and corn starch toward renewable diesel feedstocks, tightening supply for food-grade ingredient fractions. EU REACH chemical registration protocols and EFSA novel food assessments create compliance thresholds that filter entrants into European commercial markets. Stakeholders must monitor how carbon accounting frameworks from ISO 14064 and evolving SEC climate disclosure rules reposition plant-based egg alternatives against conventional egg supply chains in enterprise procurement decisions.
Market Dynamics
Plant-based protein extraction technologies are compressing formulation costs while FDA allergen labeling mandates and USDA school nutrition standards pull institutional procurement toward certified egg alternatives. Commercial bakers now face simultaneous pressure to reformulate for clean-label compliance and cost stability.
Growth Catalysts
- USDA School Nutrition Standards:K-12 institutional foodservice operators must source egg alternatives to meet sodium and saturated fat targets, creating mandated procurement pipelines for powdered replacers in breakfast applications.
- Aquafaba Processing Scale:Chickpea wet-milling expansion generates abundant byproduct streams, lowering raw material costs for foaming-stable egg alternatives in vegan bakery segments.
- Commercial Baker Consolidation:Large-scale facilities in the United States centralize ingredient purchasing, driving bulk liquid concentrate adoption through freight efficiency and continuous processing line compatibility.
Market Restraints
- EPA Biofuel Diversion:Renewable diesel mandates siphon soy oil and corn starch feedstocks, tightening food-grade supply and inflating input costs for lecithin and starch-based replacers.
- Functional Performance Gaps:Pea protein isolates exhibit inferior heat-set gelation compared to whole eggs, limiting complete substitution ratios in high-moisture cake systems without hydrocolloid supplementation.
- EU REACH Registration Burden:ECHA chemical dossier requirements and EFSA novel food assessments impose multi-year compliance timelines that filter smaller ingredient developers from European commercial markets.
Strategic Opportunities
- India FSSAI Clean-Label Window:India's packaged bakery sector remains underpenetrated by functional egg alternatives, offering first-mover positioning as urban consumers shift toward ingredient transparency.
- Precision Fermentation Convergence:Microbial biomass platforms combining synthetic biology with industrial bioprocessing enable animal-identical protein production without allergen labeling, unlocking premium positioning.
- Direct-to-Manufacturer Digital Channels:B2B ingredient marketplaces bypass traditional distributor markups, allowing replacer suppliers to capture margin pools previously allocated to foodservice intermediaries.
Industry Challenges
- Food Chemist Talent Scarcity:Formulation expertise bridging plant protein chemistry and bakery process engineering remains concentrated at legacy ingredient houses, constraining R&D velocity at emerging suppliers.
- ISO 17025 Certification Timelines:Third-party laboratory accreditation for allergen-free verification extends 12-18 months, delaying market entry for fermentation-derived novel proteins.
- Legacy Equipment Retrofit Costs:Powder-to-liquid handling system conversions require capital outlays that strain mid-cap baker margins during reformulation transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egg Replacers Market |
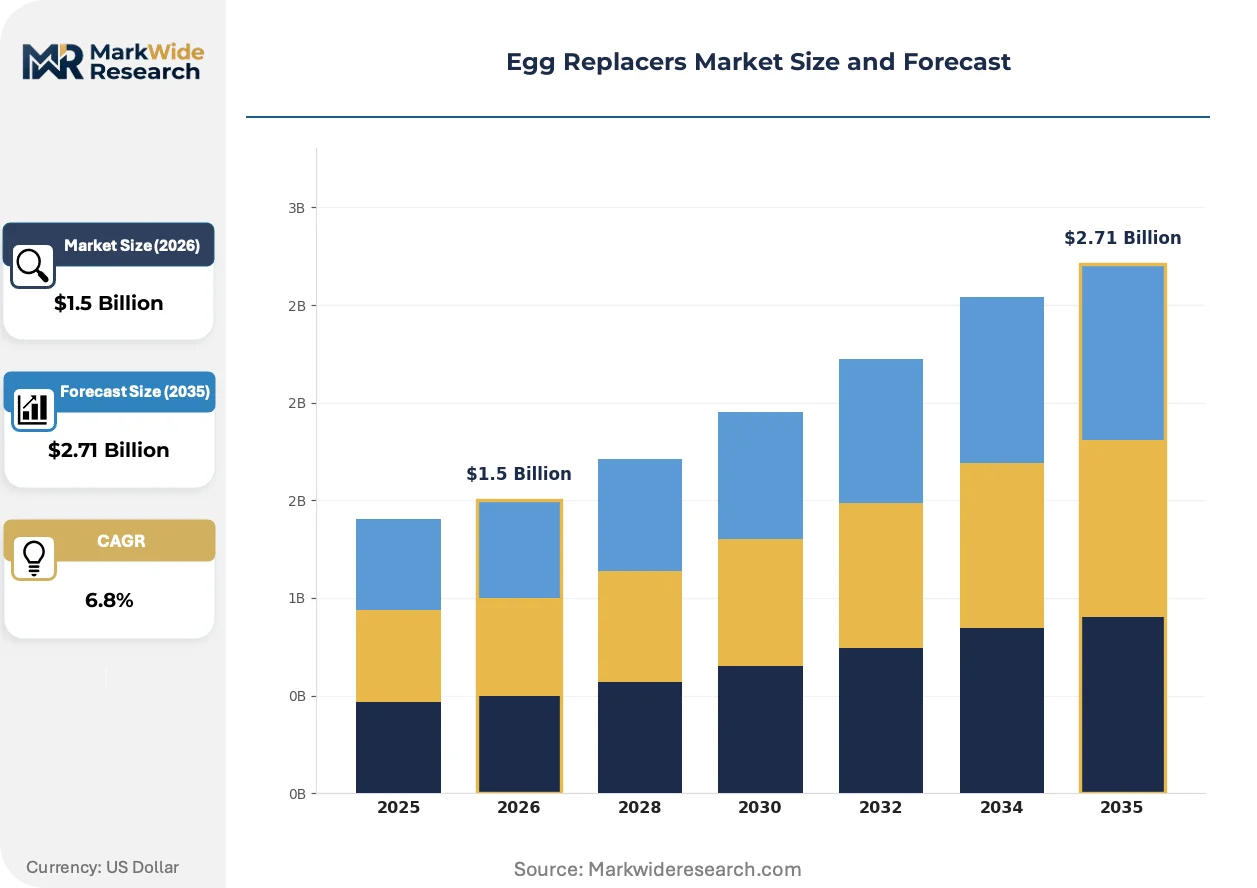
| Market Size in 2026 | $1.5 Billion |
| Market Size in 2035 | $2.71 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aquafaba, Flaxseed, Chia Seeds, Silken Tofu Application: Baking, Cooking, Dairy Alternatives, Protein Supplements Form: Liquid, Powder, Granule, Paste End User: Households, Commercial Bakers, Food Manufacturers, Health Conscious Consumers |
| Companies Covered | Ingredion Incorporated, Cargill Inc., Archer Daniels Midland Company, IFF (DuPont N&B), Tate & Lyle PLC, Kerry Group plc, Corbion NV, JUST Inc. (Eat Just), Puratos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egg Replacers Market Strategic Shifts & Innovations
Extraction and fermentation platforms are collapsing the cost-performance gap between plant-derived systems and conventional eggs. Three concurrent developments are restructuring how formulators source functional ingredients.
High-pressure processing of pulse proteins is rewriting emulsification economics. This technology disrupts native protein structures to expose hydrophobic domains, achieving egg-equivalent binding at lower dosage rates. Industrial bakeries in the United States are retrofitting ingredient prep lines to accommodate these concentrates. The shift is compressing reliance on soy and corn legacy supply chains.
EU Green Deal carbon accounting protocols are mandating Scope 3 emissions disclosure across food manufacturing supply chains. This regulatory pressure forces enterprise procurement teams to document ingredient carbon intensity. Egg replacer suppliers with verified ISO 14064 footprints gain preferred vendor status in European contract negotiations.
Food manufacturers are unbundling ingredient specification from legacy distributor relationships. Direct technical partnerships with replacer developers now precede volume commitments, replacing catalog-based purchasing. This behavioral shift concentrates contract value with suppliers offering integrated application support rather than commodity positioning.
Egg Replacers Market Segmentation
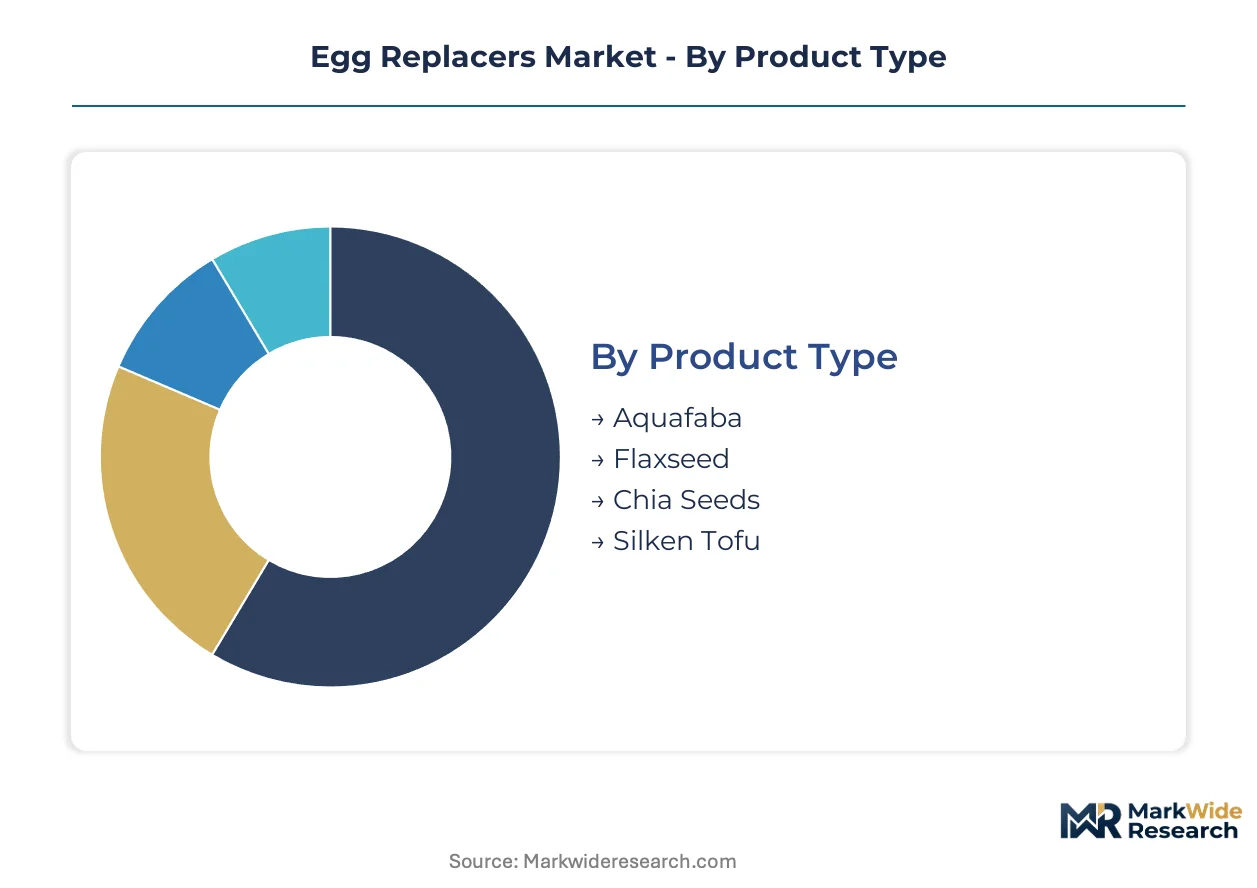
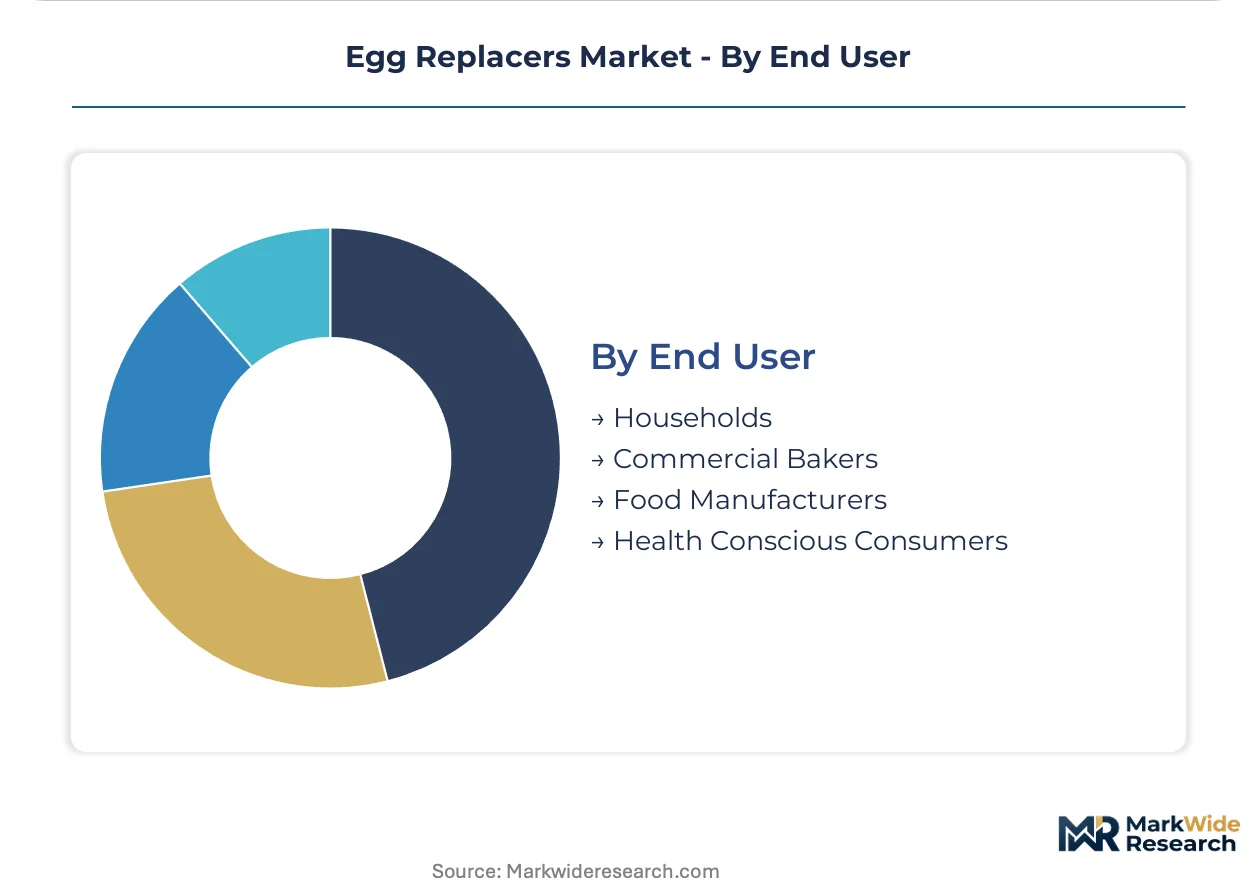
Egg replacer segmentation reflects divergent technical requirements across artisanal and industrial production environments. Formulators must balance clean-label consumer preferences against the functional specifications of continuous processing lines. Each category reveals distinct procurement patterns between commodity-scale buyers and specialty ingredient seekers.
Product Type:
Standardization dominates commodity pulse proteins while aquafaba remains a specialty ingredient with variable supply chains.
- Aquafaba:Chickpea processing byproduct containing soluble proteins and polysaccharides that replicate egg white foaming at whipping rates exceeding 200% volume expansion. Commercial bakers in the United States source this through direct partnerships with hummus manufacturers to secure volume commitments. Supply fluctuates with chickpea harvest cycles and wet-milling capacity.
- Flaxseed:Ground whole seed or extracted mucilage forms viscous gels through hydration, binding moisture in muffin and quick-bread matrices at substitution ratios of 1:3 (flax:water to egg). Household consumers in Germany and the Netherlands drive retail demand for pre-ground formats with nitrogen-flushed packaging.
- Chia Seeds:Mucilaginous hydrocolloid extraction yields transparent gels suitable for clean-label applications requiring visual clarity.
- Silken Tofu:Soy protein coagulum provides emulsification and moisture retention in dense cake systems and vegan custards.
Leading the category by volume: Flaxseed. Growing fastest: Aquafaba.
Application:
Volume concentration separates industrial reformulation from niche dietary positioning.
- Baking:Sponge cake, bread, and pastry applications require precise aeration control where lecithin-starch synergies replace egg foam structures. Food manufacturers in California and Illinois operate dedicated ingredient prep lines for liquid concentrate dosing at 0.5-2.0% inclusion rates.
- Cooking:Scramble and omelet analogs utilize mung bean protein isolates with methylcellulose for heat-set gelation mimicking coagulated egg curds.
- Dairy Alternatives:Ice cream and custard bases incorporate replacers for emulsion stability without cholesterol labeling.
- Protein Supplements:Powdered blends target athletic nutrition with complete amino acid profiles from multiple plant sources.
Baking commands procurement volume. Protein Supplements climb the fastest.
Form:
Freight economics and shelf stability dictate format selection across distribution channels.
- Liquid:Ready-to-pump concentrates integrate into continuous mixing operations without hydration delays. Commercial bakers prefer tanker-delivered bulk formats with 6-month refrigerated shelf life.
- Powder:Spray-dried proteins and starch blends offer 18-24 month ambient stability for international shipment and inventory flexibility.
- Granule:Agglomerated particles improve dispersibility in high-shear mixing environments.
- Paste:Pre-hydrated hydrocolloid systems suit small-batch artisanal producers lacking ingredient prep infrastructure.
Powder dominates cross-border trade. Liquid gains share fastest in domestic industrial channels.
End User:
Scale thresholds separate price-sensitive commodity buyers from premium-positioned specialty purchasers.
- Commercial Bakers:Large-scale facilities centralize purchasing through annual contracts with penalty clauses for supply interruption. These buyers prioritize lot-to-lot consistency and technical service support over unit cost minimization.
- Food Manufacturers:CPG companies reformulate legacy products for allergen-free positioning and carbon footprint reduction targets.
- Households:Retail consumers select single-ingredient options (flax, chia) based on recipe familiarity and pantry versatility.
- Health Conscious Consumers:Specialty buyers seek organic certification and single-origin supply chain documentation.
Commercial Bakers lead procurement volume. Food Manufacturers expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwestern corn and soybean belts anchor North American ingredient supply chains for starch and protein concentrates serving bakery reformulation. Regional procurement patterns diverge sharply between bulk industrial channels and specialty clean-label segments.
United States
Commercial bakers in Illinois and California operate dedicated liquid concentrate dosing lines for continuous cake production. FDA allergen labeling mandates and USDA school nutrition standards institutionalize egg alternative procurement in K-12 foodservice. Minneapolis-St. Paul hosts major oilseed processing infrastructure supplying lecithin-based emulsifiers to national bakery chains.
Germany
Household consumers in Bavaria and North Rhine-Westphalia drive retail demand for pre-ground flaxseed formats with nitrogen-flushed packaging. EU REACH chemical registration protocols and EFSA novel food assessments filter ingredient developer entry into commercial markets. Cologne-Düsseldorf corridor concentrates R&D facilities for microbial fermentation-derived egg alternatives.
India
Urban packaged bakery sectors in Maharashtra and Karnataka remain underpenetrated by functional egg alternatives despite rising ingredient transparency preferences. FSSAI clean-label regulations create compliance windows for first-mover suppliers. Mumbai-Pune industrial belt hosts emerging contract manufacturing capacity for plant protein extraction.
Netherlands
Amsterdam-Rotterdam logistics hubs facilitate aquafaba concentrate distribution across European vegan bakery channels. EU Green Deal carbon accounting protocols mandate Scope 3 emissions disclosure that favors suppliers with verified ISO 14064 footprints. Wageningen University corridor anchors precision fermentation research for animal-identical protein production.
United Kingdom
London and Southeast England concentrate demand for organic-certified single-ingredient egg replacers among health-conscious specialty buyers. ECHA chemical dossier requirements impose multi-year compliance timelines for novel ingredient market entry. Midlands manufacturing belt hosts retrofit liquid handling infrastructure for industrial bakery reformulation.
Egg Replacers Market Key Industry Players
Global majors compete with regional champions across formulation technology and distribution reach. Market structure tilts toward consolidated ingredient houses with captive oilseed processing infrastructure, though specialist fermentation startups capture premium positioning. Three archetypes dominate: diversified agribusiness conglomerates with backward integration into protein extraction, integrated flavor and nutrition houses with application technical service capabilities, and synthetic biology platforms leveraging precision fermentation for novel protein production. Capacity expansion in chickpea wet-milling and strategic partnerships between ingredient suppliers and hummus manufacturers represent dominant competitive moves.
Within the agribusiness conglomerate tier, Cargill Inc. and Archer Daniels Midland Company exemplify players with oilseed processing infrastructure anchoring supply security. Kerry Group plc occupies a position among integrated flavor and nutrition specialists masking off-notes in plant protein systems. Corbion NV represents the microbial fermentation archetype delivering allergen-free solutions through industrial bioprocessing platforms.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Cargill Inc. |
| Archer Daniels Midland Company |
| IFF (DuPont N&B) |
| Tate & Lyle PLC |
| Kerry Group plc |
| Corbion NV |
| JUST Inc. (Eat Just) |
| Puratos |
| Others |
Cost & Logistics Intelligence
High-pressure processing of pulse proteins is collapsing extraction costs while simultaneously concentrating supply leverage among North American oilseed processors with captive infrastructure. This technology transition rewards ingredient houses with backward integration into corn and soy protein concentrate production, compressing margins for toll-dependent formulators.
Pricing Analysis
Technical service bundling separates premium-tier suppliers from commodity competitors, with application support and formulation troubleshooting included in annual contracts rather than unbundled as hourly consulting. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ISO 17025-accredited allergen-free verification commanding substantial premiums over conventional plant protein systems. Pricing pressure stems from EPA biofuel mandates diverting soy oil and corn starch toward renewable diesel feedstocks, tightening food-grade supply. Commercial bakers with centralized purchasing power exhibit lowest price sensitivity, while mid-cap artisanal producers face acute margin compression during equipment retrofit transitions.
Supply Chain Analysis
Chickpea wet-milling output draws from India, Turkey, and the United States as primary aquafaba source markets, with hummus manufacturers controlling byproduct stream allocation. Soy protein isolate, lecithin, and modified starch constitute critical input dependencies for emulsification and binding functionality. Single-source vulnerability concentrates in Midwestern corn and soybean processing infrastructure, where weather-induced crop shortfalls cascade through bakery reformulation supply chains. Distribution runs through B2B ingredient marketplaces bypassing traditional foodservice intermediaries, allowing direct technical partnerships between replacer developers and commercial baker procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egg replacer market entry operates as a cost-of-compliance story, with FDA allergen labeling mandates and ISO 17025 certification timelines erecting barrier-to-entry moats that protect incumbent positions against unverified commodity suppliers.
For Market Incumbents: To counter precision fermentation startups capturing premium allergen-free positioning, established ingredient houses should deepen captive oilseed processing infrastructure in the United States corn belt and accelerate ISO 14064 carbon footprint verification for European contract eligibility. Technical service capabilities must expand to include integrated flavor masking systems that neutralize pea protein off-notes without hydrocolloid supplementation. For New Entrants and Emerging Players: Contract manufacturing partnerships with hummus processors offer the most penetrable channel for aquafaba concentrate supply security, particularly in underpenetrated Indian urban packaged bakery sectors where FSSAI clean-label windows remain open. Direct-to-manufacturer digital channels enable margin capture previously allocated to distributor intermediaries, with application-specific formulation support replacing catalog-based selling. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified agribusiness conglomerates seeking oilseed processing backward integration or integrated flavor houses requiring plant protein masking capabilities. Five-to-ten year viability hinges on fermentation-derived protein cost curves achieving parity with extraction-based systems. The signal to watch is USDA school nutrition standard revisions expanding mandated egg alternative procurement beyond current breakfast application boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| Chickpea Wet-Milling Capacity Expansion | Secures aquafaba byproduct streams for foaming-stable vegan bakery formulations. |
| Precision Fermentation Platform Development | Enables animal-identical protein production without FDA allergen labeling burdens. |
| ISO 14064 Carbon Footprint Certification | Qualifies suppliers for EU Green Deal procurement preferences in European markets. |
| Direct-to-Manufacturer Digital Channel Launch | Bypasses foodservice distributor markups to capture margin pools in industrial channels. |
| Integrated Flavor System Acquisition | Masks off-notes in pea protein isolates for clean-label bakery applications. |
Research Approach
Independent corroboration across food manufacturing procurement directors, commercial bakery R&D heads, and ingredient distributor category managers underwrites the qualitative findings, with secondary validation drawing from FDA allergen labeling guidance documents, USDA school nutrition program procurement data, EPA renewable fuel standard filings, and SEC climate disclosure rulemaking records. Bottom-up volume modeling triangulates against top-down expenditure analysis across the egg replacer value chain.
Comparable historical reference periods spanning pre-pandemic baseline through supply chain disruption phases anchor the forecast window, with segmentation modeling across product type, application, form, and end-user dimensions. CAGRs derive from ingredient inclusion rate trajectories in commercial baking reformulation, EPA biofuel mandate impact projections on food-grade feedstock availability, and institutional procurement pipeline commitments under USDA nutrition standards. Fermentation-derived protein cost curves and carbon accounting framework adoption rates constitute industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen EFSA novel food assessment timeline extensions, chickpea harvest cycle disruptions affecting aquafaba supply, and rapid precision fermentation cost breakthroughs. Forecasts reflect assumptions around regulatory stability and feedstock allocation continuity. A small set of named triggers warrants ongoing watch: EPA renewable volume obligation adjustments, EU REACH registration burden modifications, and ISO 17025 laboratory accreditation backlog resolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Mock Meat Market
Alternative Food Sources
Products from Food Waste Market
Alternative Food Sources
Global Algal Oil Market
Alternative Food Sources
Africa Protein Market
Alternative Food Sources
Meat Alternative Market
Alternative Food Sources
Carragean Alternatives Market
Alternative Food Sources
Gluten Substitute Market
Alternative Food Sources
Quinoa Protein Market
Alternative Food Sources
South American Algae Protein Market
Alternative Food Sources
Fungal Protein Market
Alternative Food Sources
Spirulina Beverages Market
Alternative Food Sources
Edible Insects Market
Alternative Food Sources
Vegan Ham Market
Alternative Food Sources
Plant-Based Compound Feed Market
Alternative Food Sources
Plant-Based Squalene Market
Alternative Food Sources
Seitan Market