
 Food Logistics Market | 2026-2036
Food Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Food Logistics Market Intelligence
Real-time IoT sensor networks is reconfiguring temperature governance across refrigerated transport corridors. Lineage Logistics leverages automated warehouse robotics to sustain throughput density in frozen storage facilities. Americold Logistics anchors its competitive position through vertical ownership of cold storage assets across North American protein hubs. NewCold Advanced Cold Logistics B.V. differentiates via purpose-built automated high-bay warehouses that eliminate conventional forklift dependency.
Food logistics encompasses the specialized movement, storage, and handling of perishable and non-perishable food products under controlled conditions, typically requiring maintenance of temperature bands between minus twenty-five degrees Celsius and plus fifteen degrees Celsius depending on product category, with primary commercial purpose of preserving nutritional integrity and safety from farm or production facility through retail or foodservice endpoint. Cold chain services currently command premium margin pools due to energy intensity and asset scarcity, while transportation segments face structural pressure from fuel cost volatility and driver availability constraints. IoT-enabled tracking systems represent the fastest-growing technology segment as shippers demand granular visibility into dwell times and temperature excursions.
The FDA enforces Hazard Analysis Critical Control Point protocols and Sanitary Transportation rules that mandate documented temperature controls for refrigerated cargo, while the USDA oversees interstate meat and poultry inspection regimes that directly determine facility access and routing eligibility. The EPA regulates refrigerant chemistries under phasedown schedules that compel cold chain operators to retrofit or replace equipment using hydrofluorocarbon alternatives. Stakeholders must monitor evolving state-level food waste diversion mandates that could reshape reverse logistics requirements and packaging recovery obligations.
Market Dynamics
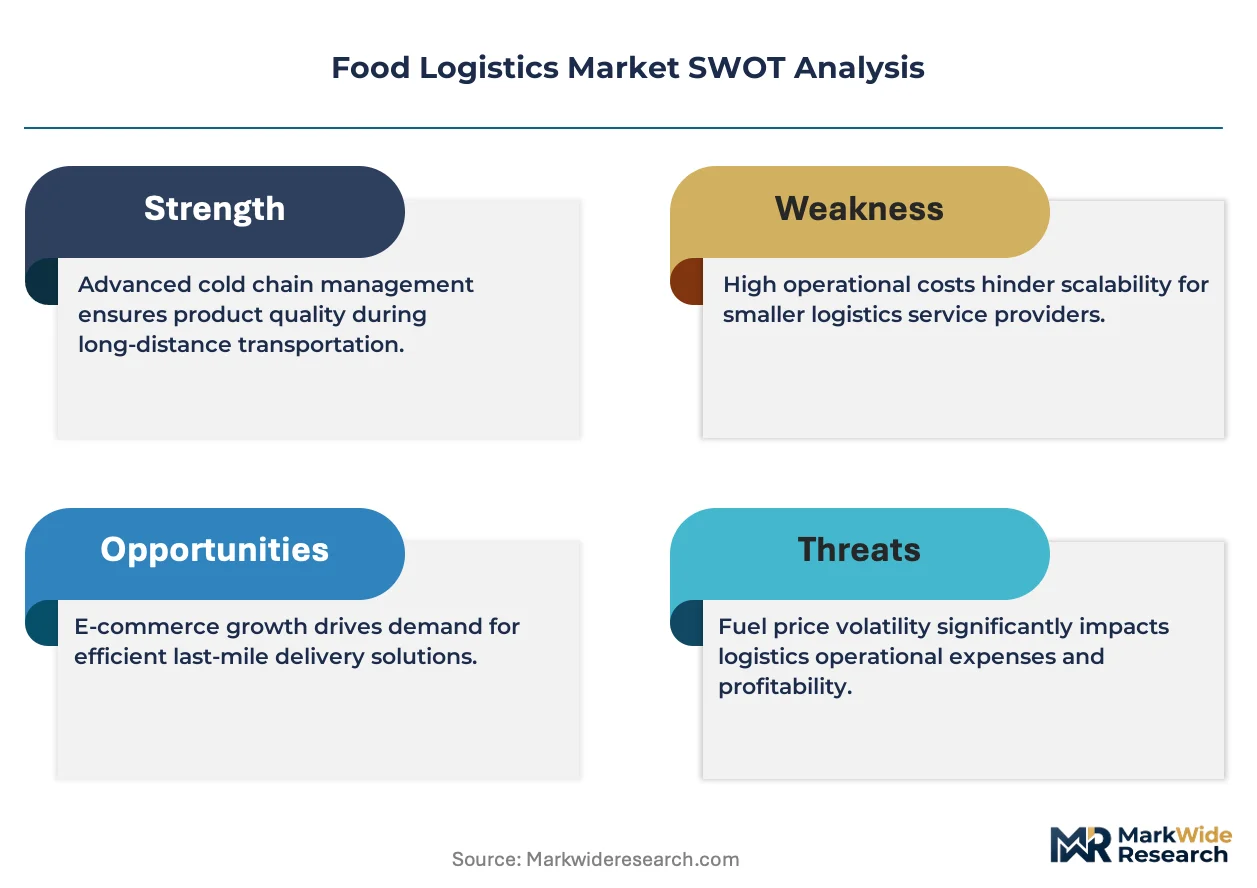
Real-time temperature governance is restructuring capital deployment across refrigerated transport corridors as shippers absorb FDA traceability mandates and energy costs compress margin pools in frozen warehousing.
Growth Catalysts
- FSMA Rule 204:The FDA's enhanced traceability requirements for domestic and imported food shipments force warehouse operators to upgrade digital inventory systems, expanding demand for integrated cold chain platforms.
- Online grocery fulfillment:E-commerce penetration in fresh and frozen categories drives construction of micro-fulfillment centers with automated temperature zones in dense urban corridors.
- Automated high-bay architecture:Purpose-built vertical warehouses eliminate conventional forklift dependency, lifting pallet density per cubic meter and reducing labor exposure to sub-zero environments.
Market Restraints
- Diesel price volatility:Refrigerated trucking operations face margin compression from fuel cost swings that contract operators cannot fully pass through to shippers under annual rate agreements.
- Driver availability constraints:The commercial driver's license pipeline remains constricted, limiting fleet expansion even where refrigerated trailer capacity exists.
- Hydrofluorocarbon phaseout:EPA refrigerant regulations under phasedown schedules compel cold storage operators to retrofit or replace equipment, stranding capital in legacy mechanical systems.
Strategic Opportunities
- India cold chain infrastructure:The country's food processing corridor expansion and FSSAI safety mandates create demand for integrated refrigerated warehousing and last-mile distribution networks.
- Pharmaceutical convergence:Temperature-sensitive biologics distribution requirements overlap with food cold chain capabilities, opening asset utilization for dual-use facilities.
- Food waste diversion mandates:State-level organic waste regulations in California and New York reshape reverse logistics requirements, creating packaged services for expired product recovery and nutrient recycling.
Industry Challenges
- Refrigeration technician scarcity:Specialized mechanical expertise for ammonia and CO2 cascade systems remains concentrated among aging workforces, constraining maintenance throughput.
- IoT integration complexity:Legacy warehouse management systems require middleware layers to ingest real-time sensor telemetry, extending deployment timelines and inflating IT capital budgets.
- Multi-temperature certification:Facilities seeking simultaneous USDA, FDA, and organic certifications face overlapping audit schedules and conflicting documentation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Logistics Market |
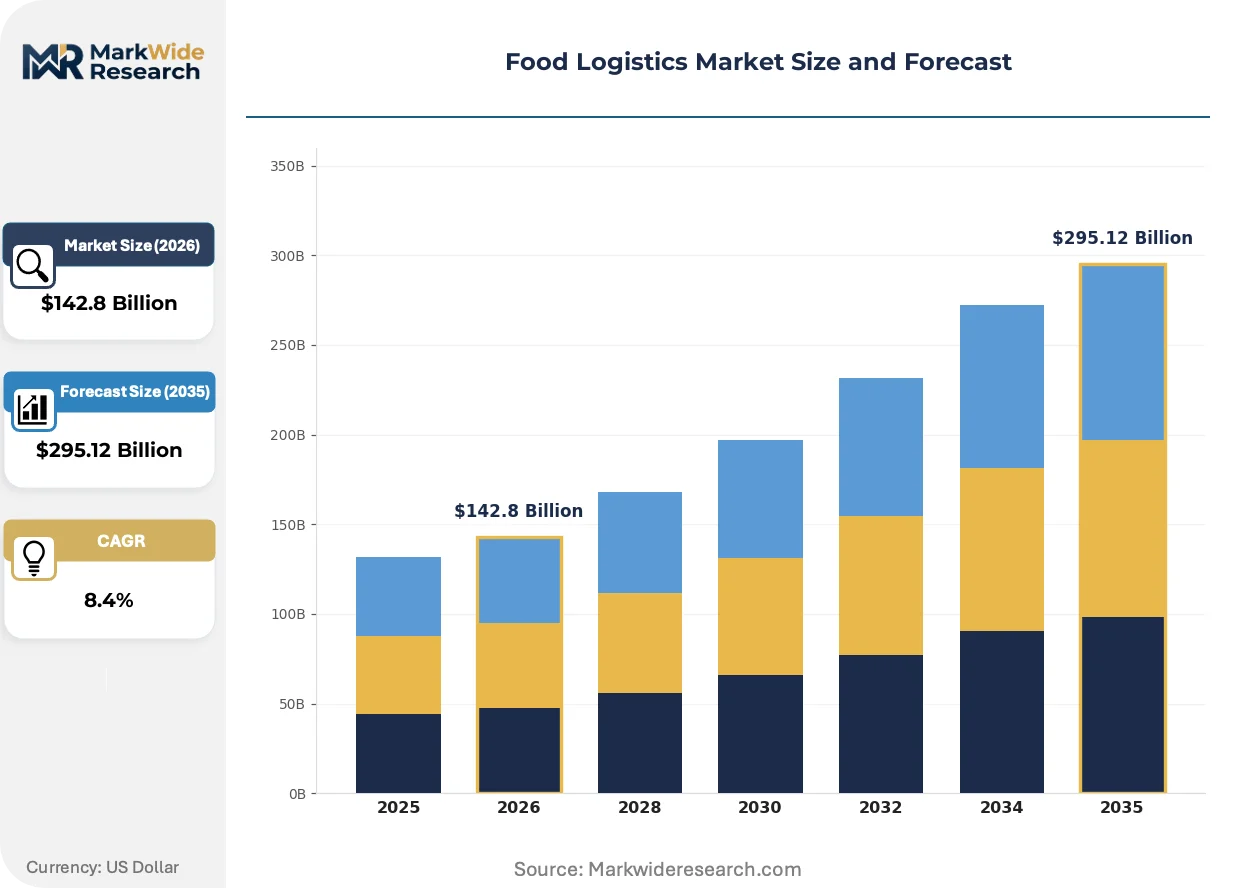
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $295.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Cold Chain, Distribution Technology: IoT, GPS Tracking, Automation, Blockchain End User: Retail, Restaurants, Food Manufacturers, Wholesalers Packaging Type: Refrigerated Containers, Insulated Packaging, Boxes, Pallets |
| Companies Covered | NewCold Advanced Cold Logistics B.V., Nichirei Logistics Group, Inc., Lineage Logistics, LLC, Preferred Freezer Services, LLC, Kloosterboer Group B.V., Americold Logistics LLC, VersaCold Logistics Services (Canada) Inc., Agro Merchants Group LLC, Sysco Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Logistics Market Strategic Shifts & Innovations
Digital infrastructure is displacing manual temperature logging across the food logistics value chain, compressing compliance costs while enabling predictive intervention before product degradation occurs.
Blockchain-enabled traceability is digitizing custody documentation from farm to retail shelf. Large produce shippers and protein processors are mandating distributed ledger integration for supplier qualification. This architecture compresses recall scope from days to hours when contamination events trigger FDA investigations.
The EPA's phasedown of hydrofluorocarbon refrigerants under AIM Act schedules is forcing equipment replacement decisions. Cold storage operators face compressed depreciation timelines on existing mechanical systems. Facilities in California and Texas are responding with early adoption of transcritical CO2 and ammonia systems to preempt regulatory deadlines.
Direct-to-restaurant distribution is fragmenting procurement patterns as independent operators bypass broadline distributors. Regional produce aggregators and specialty protein suppliers are building captive delivery fleets. This shift concentrates most visibly in metropolitan corridors with dense independent restaurant populations, particularly in Florida and the Pacific Northwest.
Food Logistics Market Segmentation
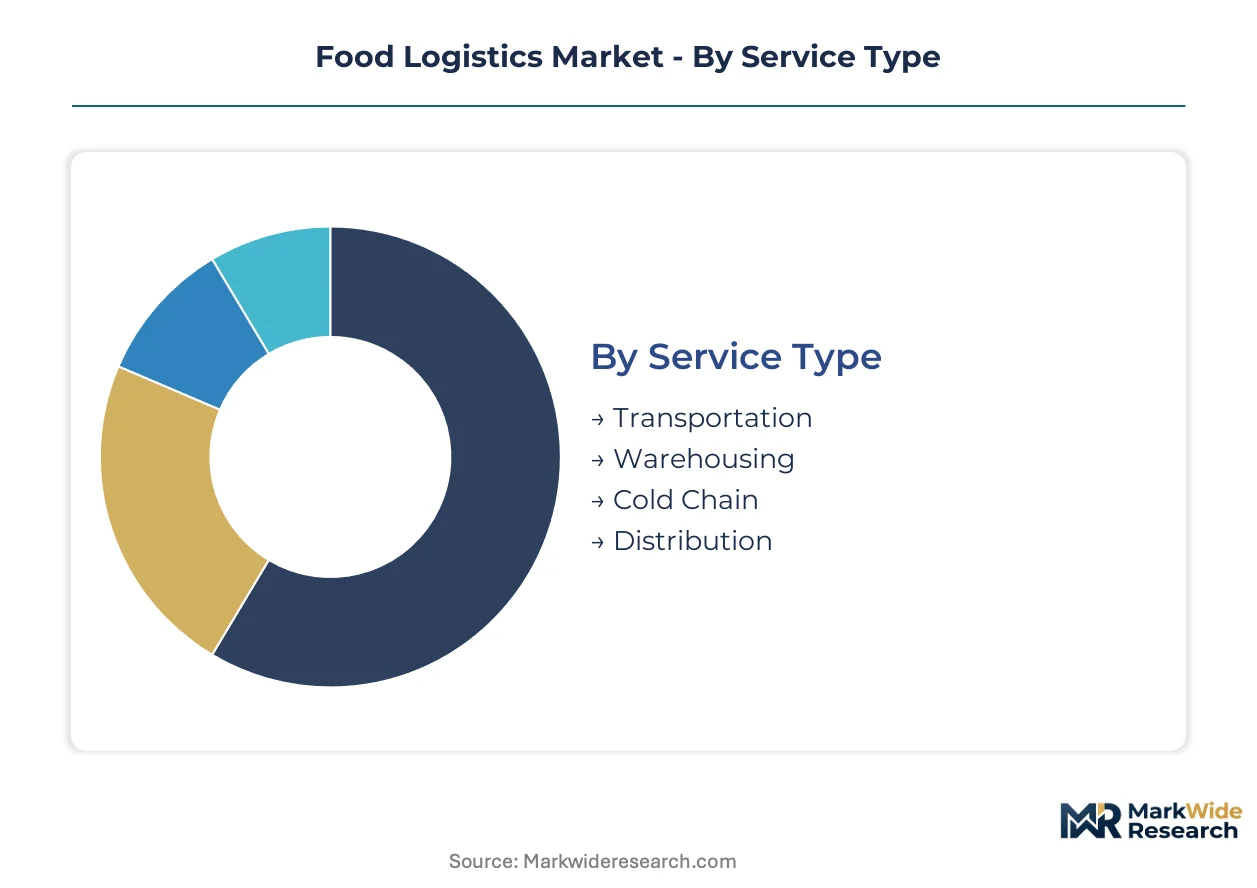
Food logistics segmentation reveals distinct operational profiles across service modes and customer interfaces. Each category carries differentiated margin structures, regulatory exposure, and capital intensity that shape vendor positioning and buyer procurement patterns.
Service Type:
Cold chain operations demand the most intensive after-sales monitoring, with temperature excursion response protocols and equipment uptime guarantees extending service obligations well beyond delivery completion.
- Cold Chain:Temperature-controlled corridors spanning minus twenty-five to plus fifteen degrees Celsius preserve nutritional integrity across frozen proteins, fresh produce, and dairy. California's Central Valley and Gulf Coast protein clusters absorb the highest concentration of refrigerated warehousing investment due to FSMA Rule 204 traceability mandates and port proximity. Energy intensity and ammonia system maintenance scarcity compress margins while creating defensive moats for operators with captive technician networks.
- Transportation:Refrigerated trucking and intermodal movements connect production zones to distribution nodes under documented temperature bands. Diesel price volatility and commercial driver's license pipeline constraints limit fleet expansion despite trailer availability, forcing contract operators into fuel surcharge negotiations that erode rate stability.
- Warehousing:Ambient and temperature-controlled storage facilities manage inventory velocity for manufacturers and retailers. Automated high-bay architectures eliminate forklift dependency and lift pallet density per cubic meter, though legacy facilities face stranded capital from EPA hydrofluorocarbon phasedown schedules.
- Distribution:Consolidated fulfillment and cross-dock operations coordinate multi-temperature product mixing for retail and foodservice endpoints. Micro-fulfillment centers in dense urban corridors serve online grocery penetration, particularly in metropolitan clusters with high independent restaurant density.
Cold Chain holds the largest share; momentum sits with Distribution as direct-to-restaurant procurement fragments traditional broadline channels.
Technology:
Technology deployment stratifies sharply by customer scale, with enterprise shippers demanding integrated platforms while mid-market operators prioritize point solutions with lower integration burden.
- IoT:Real-time sensor networks transmit temperature, humidity, and location telemetry from transport assets and warehouse zones. FDA traceability mandates and insurance risk reduction drive adoption fastest among protein processors and produce distributors with high product liability exposure.
- Automation:Warehouse robotics and automated storage and retrieval systems sustain throughput density in frozen environments while reducing labor exposure to sub-zero conditions. Purpose-built vertical warehouses from specialized constructors eliminate conventional forklift dependency entirely.
- GPS Tracking:Fleet telematics provide location visibility and route optimization for refrigerated transport corridors. Integration with temperature logging creates unified custody documentation required by FSMA Sanitary Transportation rules.
- Blockchain:Distributed ledger architectures digitize custody documentation from farm to retail shelf. Large produce shippers mandate supplier qualification through blockchain integration, compressing recall scope from days to hours during FDA contamination investigations.
IoT holds the largest share; Automation is gaining share fastest as labor scarcity and energy costs accelerate warehouse robotics deployment.
End User:
End-user procurement patterns diverge between centralized volume contracting and fragmented spot purchasing, with corresponding differences in logistics provider relationship depth and service level agreement complexity.
- Retail:Grocery chains and mass merchandisers operate dedicated distribution networks with multi-temperature zones for ambient, chilled, and frozen categories. Online grocery fulfillment drives construction of micro-fulfillment centers with automated temperature controls in dense urban corridors.
- Restaurants:Independent operators increasingly bypass broadline distributors for direct procurement from regional produce aggregators and specialty protein suppliers. Florida and Pacific Northwest metropolitan corridors exhibit the most visible fleet buildouts by captive delivery operators.
- Food Manufacturers:Processed food and beverage producers require integrated inbound ingredient and outbound finished goods logistics with HACCP-compliant temperature documentation. Co-packing and contract manufacturing relationships create complex multi-party custody chains.
- Wholesalers:Broadline distributors consolidate procurement for independent retailers and foodservice operators, though market share pressure from direct sourcing is forcing consolidation and specialized niche repositioning.
Retail holds the largest share; Restaurants are expanding most quickly as independent operator procurement fragmentation reshapes channel economics.
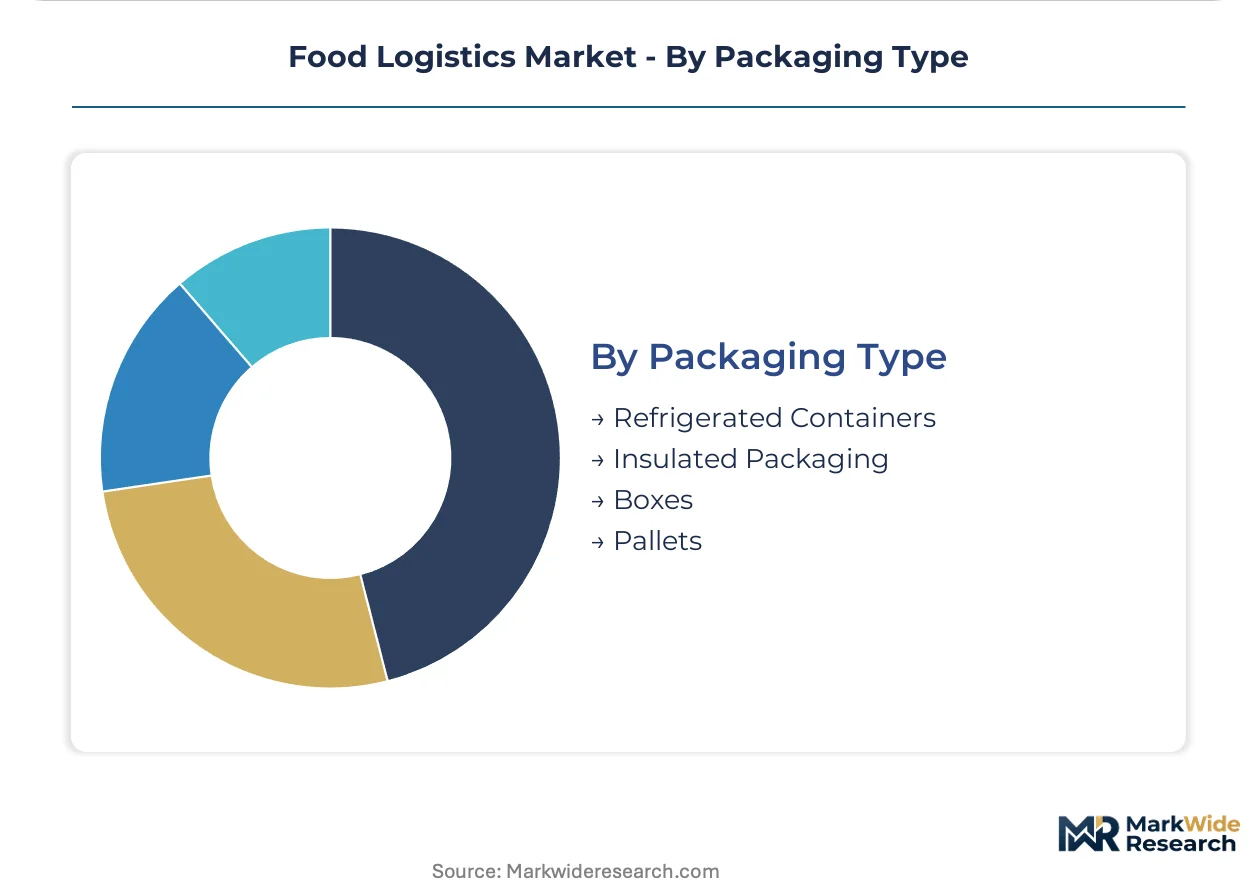
Packaging Type:
Packaging selection directly determines temperature maintenance duration, handling compatibility, and regulatory compliance pathway across transport modes.
- Refrigerated Containers:Active temperature-controlled units maintain precise thermal bands for international and domestic intermodal movements. Port congestion and dwell time variability in California and Gulf Coast clusters drive demand for extended-duration refrigeration capability.
- Insulated Packaging:Passive thermal protection systems using phase-change materials and vacuum panels protect temperature-sensitive products during last-mile distribution. Pharmaceutical convergence with food cold chain requirements expands addressable applications for qualified packaging systems.
- Boxes:Corrugated fiberboard containers dominate ambient and short-duration chilled movements. State-level food waste diversion mandates in California and New York create reverse logistics requirements for packaging recovery and nutrient recycling.
- Pallets:Unit load platforms enable forklift and automated system handling across warehouse and transport environments. Plastic pallet pooling systems face competition from RFID-enabled asset tracking for high-value cold chain movements.
Refrigerated Containers holds the largest share; Insulated Packaging shows steepest expansion trajectory as pharmaceutical distribution requirements overlap with food logistics capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are redirecting cold chain investment toward port-proximate corridors and inland distribution nodes. Countries with processing proximity to agricultural origins capture logistics value that transshipment hubs forfeit. Regulatory divergence on traceability and refrigerant chemistry is fragmenting equipment standards across trade lanes.
United States
FSMA Rule 204 traceability mandates and e-commerce grocery penetration drive refrigerated warehousing construction. The EPA's AIM Act hydrofluorocarbon phasedown compels equipment retrofit timelines. California's Central Valley and Gulf Coast protein clusters concentrate automated cold storage investment near Los Angeles and Houston port complexes.
Germany
EU Green Deal carbon border adjustments and F-Gas Regulation refrigerant restrictions reshape temperature-controlled logistics economics. The EFSA enforces strict cold chain documentation for cross-border food movements. The Rhine-Ruhr corridor and Bavarian logistics hubs anchor automated high-bay warehouse deployment for Central European distribution.
China
Domestic consumption upgrading and fresh food e-commerce expansion accelerate cold chain infrastructure buildout. NMPA and SAMR enforce strengthened food safety traceability for imported and domestic products. The Yangtze River Delta and Pearl River Delta concentrate automated warehousing investment near Shanghai and Shenzhen processing zones.
India
FSSAI safety mandate enforcement and food processing corridor expansion create integrated cold chain demand. The PLI scheme subsidizes cold storage and refrigerated transport asset deployment. Maharashtra and Gujarat absorb concentrated warehousing investment near Mumbai and Ahmedabad agricultural processing clusters.
Brazil
Protein export growth and domestic retail modernization drive refrigerated logistics capacity expansion. ANVISA enforces temperature documentation for pharmaceutical-food convergence shipments. São Paulo state and Paraná concentrate cold storage development near Santos port and southern agricultural production zones.
Food Logistics Market Key Industry Players
On the supply side, the industry is consolidating around operators with captive cold storage assets and automated warehouse capabilities. Scale advantages concentrate in firms controlling port-proximate real estate and ammonia system expertise. Three archetypes dominate: vertically integrated temperature-controlled real estate owners, automated high-bay specialists, and broadline distributors building captive cold chain networks. Competitive dynamics center on M&A-driven geographic densification and strategic partnerships with protein processors seeking dedicated capacity.
Within the automated high-bay tier, NewCold Advanced Cold Logistics B.V. and Lineage Logistics, LLC exemplify purpose-built vertical warehouse strategies that eliminate conventional forklift dependency. Americold Logistics LLC anchors the integrated real estate owner archetype through captive cold storage assets across North American protein hubs. These three entities represent distinct capital deployment models: European automation-first expansion, US-based M&A-driven consolidation, and temperature-controlled real estate platform scaling.
| Leading Market Players |
|---|
| NewCold Advanced Cold Logistics B.V. |
| Nichirei Logistics Group, Inc. |
| Lineage Logistics, LLC |
| Preferred Freezer Services, LLC |
| Kloosterboer Group B.V. |
| Americold Logistics LLC |
| VersaCold Logistics Services (Canada) Inc. |
| Agro Merchants Group LLC |
| Sysco Corporation |
| Others |
Cost & Logistics Intelligence
California's Central Valley cold storage concentration anchors margin capture for automated warehouse operators, while diesel price volatility in Gulf Coast corridors compresses transportation tier profitability. Retail grocery chains wield procurement leverage through dedicated distribution networks, forcing contract renegotiation on fuel surcharge pass-throughs.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across refrigerated warehousing, with three-tier pricing stratification across FSMA-certified, HACCP-compliant, and standard temperature-controlled tiers. Price differentiation hinges on certification level and geographic delivery cost, with California and Texas port-proximate facilities commanding premiums. Pricing pressure stems from EPA hydrofluorocarbon retrofit mandates stranding capital in legacy mechanical systems. Independent restaurant operators exhibit highest price sensitivity, while protein processors with contamination liability exposure demonstrate lowest.
Supply Chain Analysis
Export-control restrictions on ammonia system compressors and CO2 cascade components limit equipment flows from Germany and Japan into domestic retrofit programs. Cold chain infrastructure draws from concentrated steel fabrication in China, specialized refrigeration engineering in Germany, and control systems manufacturing in Japan. Single-source vulnerability sits with ammonia technician networks concentrated among aging workforces. Distribution runs through port-proximate warehousing clusters feeding inland distribution nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward retail grocery chains consolidating procurement through dedicated distribution networks, fragmenting broadline distributor market share.
For Market Incumbents: Build captive technician network moats through apprenticeship programs targeting ammonia and CO2 cascade system expertise. Expand automated high-bay capacity in California Central Valley and Gulf Coast protein clusters to preempt FSMA Rule 204 compliance demand. Defend against emerging cold chain platform entrants by securing long-term protein processor capacity commitments. For New Entrants and Emerging Players: India's Maharashtra and Gujarat food processing corridors offer underpenetrated white-space for integrated refrigerated warehousing and last-mile distribution buildout. Target pharmaceutical-food convergence facilities serving temperature-sensitive biologics with dual-use cold chain capabilities. Pursue joint venture structures with regional produce aggregators bypassing broadline channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automated high-bay specialists requiring geographic densification capital. Long-term viability centers on facilities with transcritical CO2 or ammonia systems preempting EPA phasedown deadlines. Monitor state-level organic waste diversion mandate adoption as inflection indicator for reverse logistics service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Automated High-Bay Capacity Expansion | Lineage Logistics and NewCold deployments eliminate forklift dependency while lifting pallet density in California protein hubs. |
| Transcritical CO2 System Retrofit | Early EPA AIM Act compliance preempts refrigerant phasedown deadlines stranding legacy mechanical assets. |
| Blockchain Traceability Integration | Large produce shippers mandate distributed ledger qualification compressing FDA recall scope from days to hours. |
| Micro-Fulfillment Center Buildout | Urban automated temperature zones serve online grocery penetration in dense metropolitan corridors. |
| Pharmaceutical Convergence Partnership | Temperature-sensitive biologics distribution opens dual-use facility utilization for cold chain operators. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA FSMA guidance documents, EPA refrigerant phasedown schedules, and customs trade data. Cold chain operators, protein processor logistics directors, retail grocery procurement managers, and refrigeration equipment OEMs provided operational perspective. Bottom-up facility capacity tallies triangulate against top-down segment revenue estimates.
Forecast inputs include temperature-controlled warehouse construction permits, refrigerated trailer fleet registrations, and IoT sensor deployment trajectories. Segmentation dimensions span service type, technology adoption tier, end-user procurement pattern, and packaging format. CAGRs derive from logistic curve fitting to infrastructure investment cycles and regulatory compliance deadlines. Energy cost projections and driver availability constraints inform transportation segment trajectory.
Practitioners should monitor EPA refrigerant regulation acceleration and state-level food waste mandate expansion for early signals. Forecasts reflect assumptions regarding FSMA Rule 204 enforcement timelines and e-commerce grocery penetration rates. Material shifts in hydrofluorocarbon phasedown schedules or cold chain technician pipeline constraints would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Commercial Ice Dispenser Market
Food Service
Oman Food Service Market
Food Service
Cutting Boards Market
Food Service
Supermarkets Market
Food Service
Global Cafe and Bars Market
Food Service
Aquarium Protein Skimmers Market
Food Service
Food Trucks Market
Food Service
Smoker Grill Market
Food Service
US Food Service Market
Food Service
United Kingdom Cafes & Bars Market
Food Service
China Online Food Delivery Market
Food Service
Commercial Tableware Services Market
Food Service
Restaurant Griddle Market
Food Service
Food Service Gloves Market
Food Service
Canada Food Service Market
Food Service
Middle East Smokeless Indoor Grills Market