
 Japan Plant Protein Market | 2026-2036
Japan Plant Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Plant Protein Market Foresight
Multi-source procurement of raw materials is broadening as Japanese manufacturers reduce dependence on North American soy imports. Fuji Oil Holdings Inc. leverages its domestic crushing infrastructure to secure consistent supply of locally processed soy and rapeseed proteins. Kikkoman Corporation anchors the fermented protein segment through its traditional miso and soy sauce-derived ingredient platforms. DAIZ Inc. differentiates through germination technology that enhances amino acid profiles in soybean processing.
Japan Plant Protein encompasses isolates, concentrates, and textured extractions derived from legumes, cereals, and oilseeds, typically containing protein contents ranging from 50% to 90% by dry weight, serving primarily as functional ingredients in reformulated foods. Soy protein retains the largest volume position due to established supply chains and consumer familiarity, though pea protein exhibits the fastest trajectory as allergen-free positioning gains traction among health-conscious consumers. Rice protein occupies a premium niche where hypoallergenic claims command higher margin pools in nutritional supplements directed at athletes and restricted-diet populations.
METI's Food Industry Vision and the Consumer Affairs Agency's labeling standards for plant-based foods shape product development pathways and marketing claims in Japan. JIS standards for food-grade protein specifications further constrain import quality and domestic manufacturing protocols. Stakeholders must monitor evolving F-Gas regulation impacts on extrusion and texturization equipment energy profiles, as carbon accounting pressures intensify across the supply base.
Market Dynamics
Protein diversification mandates from METI are compressing reformulation timelines across Japanese food manufacturing, forcing ingredient suppliers to accelerate functional validation while domestic crushing capacity constraints intensify raw material competition.
Growth Catalysts
- Tokyo-Osaka corridor concentration:Retail and foodservice channel clustering in this corridor creates dense demand aggregation that rewards localized production investments and shortens distribution lead times for perishable extruded proteins.
- METI's Food Industry Vision:This policy framework explicitly targets protein source diversification, directing public R&D funding toward fermentation and extrusion infrastructure that reduces import dependency.
- Germination technology maturation:Enzymatic pre-processing of soybeans enhances amino acid bioavailability, allowing finished products to meet Japan's FOSHU functional food claims with reduced additive requirements.
Market Restraints
- North American soy import dependency:Currency volatility and trade friction expose Japanese crushers to margin compression when dollar-denominated soybean contracts reprice.
- JIS specification rigidity:Food-grade protein standards constrain import sourcing flexibility, disqualifying lower-cost Asian suppliers lacking certification infrastructure.
- Animal protein price competitiveness:Domestic pork and poultry production subsidies maintain retail price gaps that slow consumer switching toward plant-based alternatives.
Strategic Opportunities
- Kyushu agricultural belt underpenetration:Southern Japan's food manufacturing base lacks dedicated plant protein extrusion facilities, creating first-mover advantages for regional crushing investments.
- F-Gas Regulation compliance services:Carbon accounting pressures on extrusion equipment energy profiles open consulting and retrofit revenue streams for engineering specialists.
- Direct-to-manufacturer ingredient platforms:Bypassing traditional trading house intermediaries allows protein suppliers to capture margin pools previously absorbed by Mitsubishi Corporation and Itochu Corporation food divisions.
Industry Challenges
- FOSHU certification timeline compression:Functional food claims require 12-18 month PMDA review cycles that misalign with quarterly product development schedules.
- Extrusion technician scarcity:High-shear texturization equipment operation demands specialized training unavailable through standard food engineering curricula.
- Legacy miso fermentation integration:Traditional koji-based protein processing workflows resist automation, constraining throughput scaling for heritage-positioned brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Plant Protein Market |
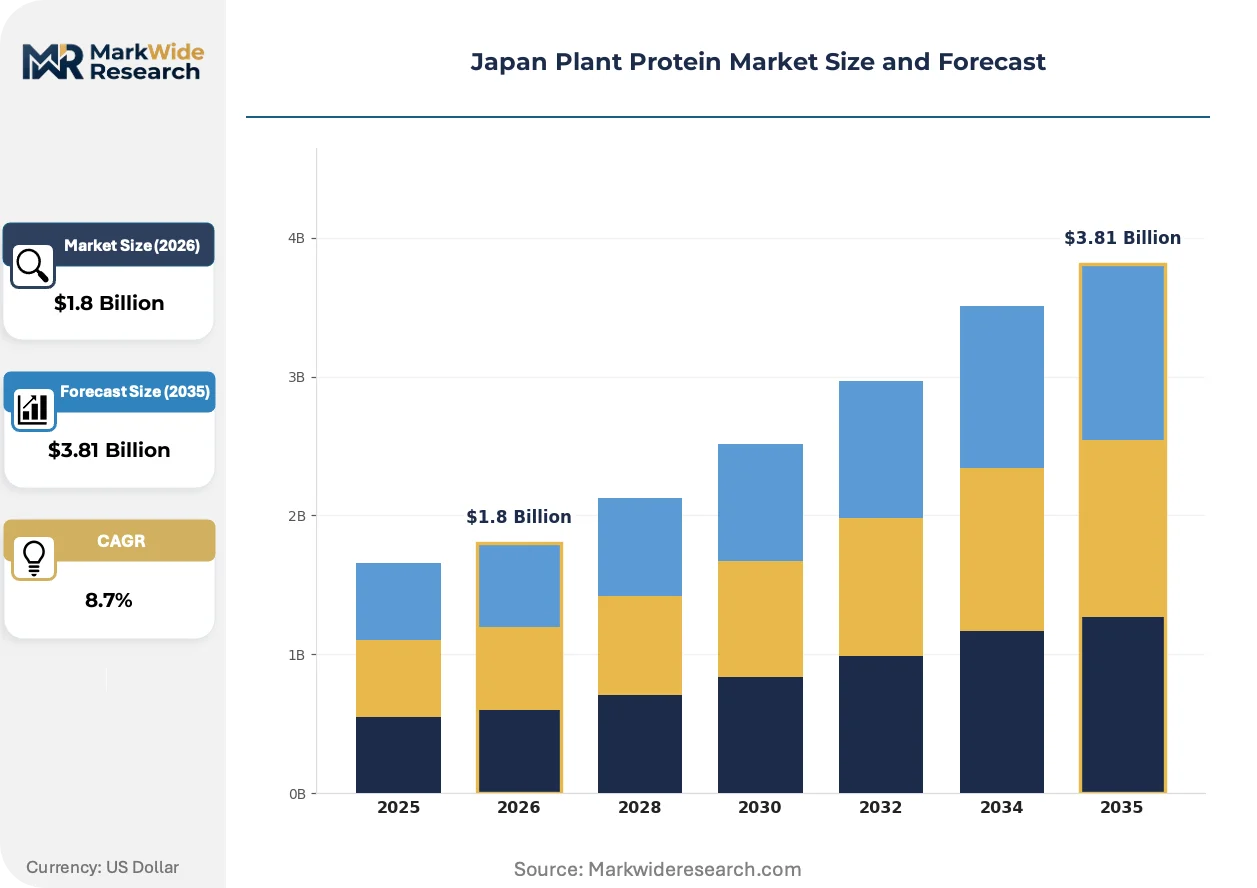
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pea Protein, Soy Protein, Rice Protein, Wheat Protein Application: Nutritional Supplements, Meat Alternatives, Dairy Alternatives, Bakery Products End User: Health-Conscious Consumers, Athletes, Vegans, Food Industry Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Direct Sales |
| Companies Covered | Archer Daniels Midland Company, DuPont de Nemours Inc., Cargill Incorporated, Roquette Frères, Fuji Oil Holdings Inc., Kikkoman Corporation, Marukome Co. Ltd., Otsuka Foods Co. Ltd., DAIZ Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Plant Protein Market Shifts & Advancements
Functional ingredient positioning is displacing commodity protein trading as the dominant value capture mechanism, with Japanese manufacturers prioritizing amino acid optimization and allergen-free claims over bulk tonnage.
Extrusion technology is integrating advanced shear-control systems that modulate protein fiber alignment during high-moisture processing. Sports nutrition formulators in Osaka prefecture are adopting these systems at pilot scale. The technology is integrating texture-matching capabilities that compress development cycles for whole-muscle meat analogs from 24 months to under 12.
METI's sustainable food system promotion policies now explicitly reference protein diversification targets in corporate carbon disclosure guidelines. Food manufacturers must document Scope 3 emissions from livestock-derived ingredients, elevating plant-based alternatives in procurement scorecards. Mid-tier bento and ready-meal producers in the Kanto region are reformulating first, driven by convenience store chain sustainability mandates.
Ingredient procurement is consolidating toward multi-year offtake agreements that transfer price risk to crushing facilities. Large-scale foodservice operators in Tokyo are bypassing spot markets entirely, locking in 36-month rapeseed protein supply contracts. This pattern concentrates most visibly among institutional catering networks serving prefectural government facilities and university hospital systems.
Japan Plant Protein Market Segmentation
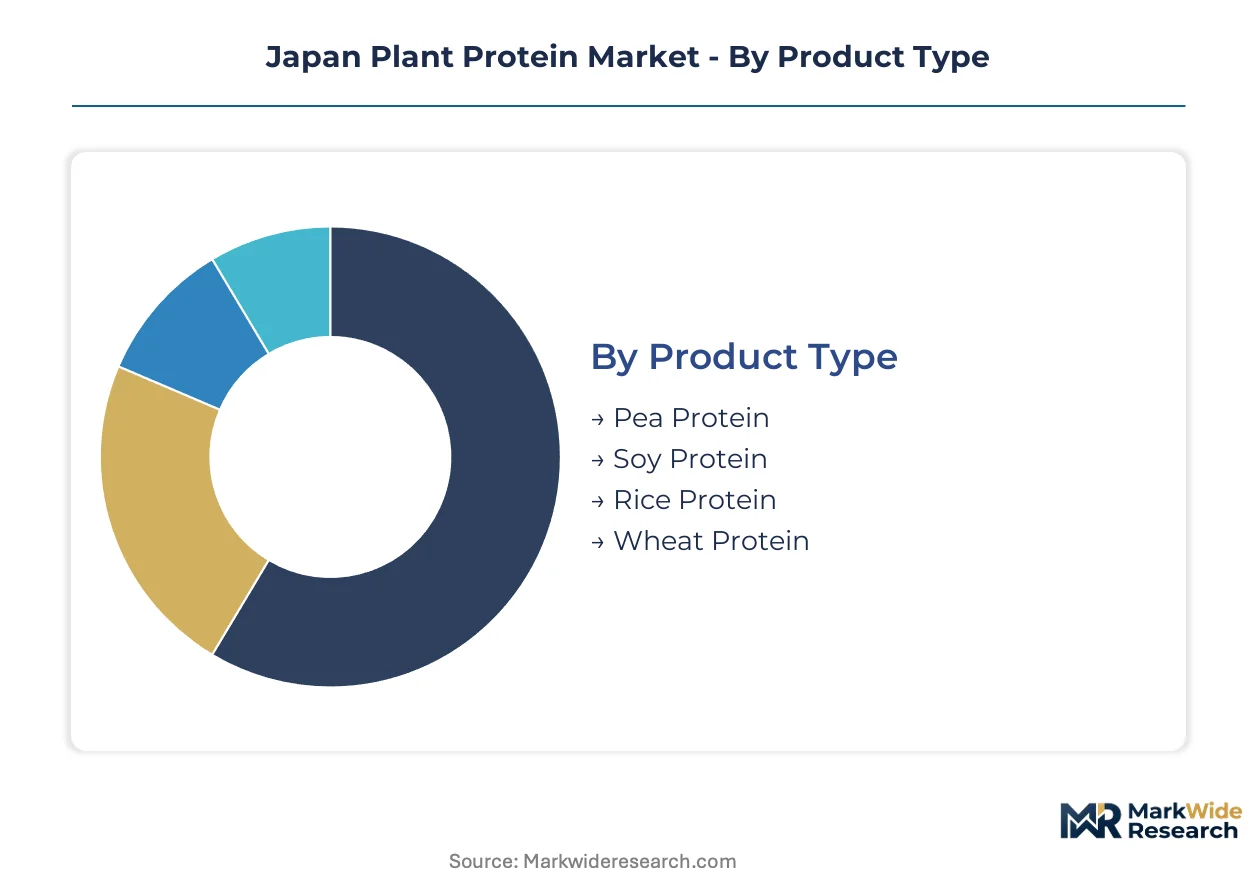
Segmentation in the Japan Plant Protein Market reveals how protein diversification policies reshape procurement patterns across distinct product categories and channel structures. Manufacturers align formulation strategies with end-user priorities spanning functional nutrition claims to sustainability credentials.
Product Type:
Upgrade cycles in protein ingredient portfolios accelerate as Japanese food manufacturers replace commodity soy isolates with higher-margin functional alternatives.
- Soy Protein:Isolates and concentrates containing 70-90% protein by dry weight anchor existing supply chains through established crushing infrastructure. Demand concentrates in traditional miso fermentation and textured meat analog applications across the Tokyo-Osaka corridor, constrained by North American import dependency and currency exposure.
- Pea Protein:Hypoallergenic isolates with balanced essential amino acid profiles capture reformulation interest from allergen-sensitive positioning. Sports nutrition manufacturers in Osaka prefecture drive adoption fastest, prioritizing FOSHU-eligible functional claims over commodity tonnage.
- Rice Protein:Premium-grade concentrates serve restricted-diet populations through hypoallergenic supplement formulations.
- Wheat Protein:Gluten-rich concentrates support bakery texture modification and specialized nutrition bars.
Soy protein sits at the top of the volume ranking, with pea protein climbing the fastest.
Application:
Cost tier differentiation separates premium functional claims from commodity bulk applications in Japanese food manufacturing procurement decisions.
- Nutritional Supplements:Powder and ready-to-drink formats targeting protein diversification mandates from METI. Demand concentrates among athletes and health-conscious consumers in metropolitan prefectures where convenience store sustainability mandates drive reformulation.
- Meat Alternatives:Extruded texturized proteins with fiber alignment matching whole-muscle structure. Foodservice operators in Tokyo lock in multi-year offtake agreements, compressing development cycles through advanced shear-control extrusion systems.
- Dairy Alternatives:Fermented protein bases for yogurt and beverage analogs leveraging traditional koji processing workflows.
- Bakery Products:Functional wheat and rice protein fortification addressing shelf-life and texture requirements.
Meat alternatives command premium procurement attention, with nutritional supplements expanding most quickly through direct-to-manufacturer platform consolidation.
End User:
Customer type segmentation maps directly to distribution channel density and margin capture potential across Japan's retail landscape.
- Health-Conscious Consumers:Middle-income urban households prioritizing clean-label and functional food claims. Channel concentration in Tokyo-Osaka health food stores and premium supermarket protein sections rewards localized production investments.
- Athletes:Performance-focused protein consumers demanding amino acid-optimized isolates. Osaka prefecture sports nutrition formulators adopt germination-enhanced soy platforms at pilot scale for FOSHU certification pathways.
- Vegans:Ethically motivated consumers driving allergen-free and sustainability-positioned product selection.
- Food Industry:Institutional procurement from bento and ready-meal producers responding to convenience chain carbon disclosure requirements.
Health-conscious consumers anchor volume demand, with athletes gaining share fastest through specialized formulation partnerships.
Distribution Channel:
Supply concentration patterns determine margin distribution between trading house intermediaries and direct manufacturer relationships.
- Online Retail:Direct-to-consumer platforms capturing subscription-based protein powder sales. Metro Tokyo logistics density supports same-day delivery expectations for perishable extruded products.
- Supermarkets:Mass-market penetration through private-label plant-based meat and dairy alternatives. Channel clustering in the Kanto region accelerates reformulation timelines for mid-tier producers.
- Health Food Stores:Premium positioning for hypoallergenic rice protein and specialized supplement formulations.
- Direct Sales:Institutional catering and foodservice contracts bypassing traditional trading house structures.
Supermarkets dominate volume throughput, with direct sales climbing fastest as large-scale operators execute multi-year offtake agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Tokyo-Osaka corridor concentrates Japan's plant protein demand through dense retail and foodservice channel clustering. METI's protein diversification policies and PMDA's FOSHU certification framework shape regional investment patterns across domestic manufacturing zones.
Kanto/Tokyo
Health-conscious consumer density drives premium protein supplement demand through convenience store sustainability mandates. METI's Food Industry Vision directs public R&D funding toward fermentation infrastructure in this corridor. Sports nutrition formulators in Saitama prefecture adopt germination-enhanced soy platforms for accelerated FOSHU pathways.
Kansai/Osaka
Advanced shear-control extrusion systems compress meat analog development cycles from 24 months to under 12. JIS food-grade protein specifications constrain import sourcing flexibility for regional manufacturers. Textured protein pilot facilities in Hyogo prefecture serve foodservice operators executing multi-year offtake agreements.
Chubu/Nagoya
Traditional miso fermentation workflows anchor heritage-positioned protein processing in this manufacturing belt. PMDA's 12-18 month functional food review cycles misalign with quarterly product schedules for regional brands. Industrial food producers in Aichi prefecture reformulate bento lines responding to convenience chain carbon disclosure requirements.
Kyushu
Southern Japan's agricultural base lacks dedicated plant protein extrusion facilities, creating first-mover investment opportunities. F-Gas Regulation compliance pressures on equipment energy profiles elevate carbon accounting requirements for new facilities. Regional crushing investments in Fukuoka prefecture target rapeseed protein supply security for institutional catering networks.
Hokkaido
Domestic soybean cultivation expansion reduces North American import dependency for northern crushers. Currency volatility exposure on dollar-denominated contracts drives localized procurement strategies. Agricultural cooperatives in the Tokachi sub-region experiment with germination technology licensing from specialized technology providers.
Japan Plant Protein Market Competitive Landscape
Global majors compete with regional champions across ingredient supply and functional formulation dimensions. The market structures around three tiers: multinational trading houses with established import networks, domestic crushing specialists leveraging local infrastructure, and technology-focused startups commercializing novel processing methods. Competitive moves concentrate on multi-year offtake agreement execution and germination technology licensing partnerships.
Within the domestic specialist tier, Fuji Oil Holdings Inc. and Kikkoman Corporation exemplify established infrastructure players, while DAIZ Inc. occupies a position among technology-driven innovators. Archer Daniels Midland Company represents global supply chain integration. These anchors illustrate how market participants align with METI policy vectors and corridor-specific demand aggregation patterns.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| DuPont de Nemours Inc. |
| Cargill Incorporated |
| Roquette Frères |
| Fuji Oil Holdings Inc. |
| Kikkoman Corporation |
| Marukome Co. Ltd. |
| Otsuka Foods Co. Ltd. |
| DAIZ Inc. |
| Others |
Supply & Pricing Matrix
METI's corporate carbon disclosure guidelines gate qualified supply access for premium-tier protein ingredients, compressing margins for non-compliant crushers while rewarding certified facilities with pricing power in institutional procurement channels. Foodservice operators now demand Scope 3 documentation that disqualifies spot-market sourcing, forcing price stratification between verified low-carbon supply and commodity alternatives.
Pricing Analysis
Input-cost pass-through from dollar-denominated North American soybean contracts exposes Japanese crushers to margin compression when currency volatility strikes, though multi-year offtake agreements increasingly transfer this risk downstream to foodservice operators. Three-tier pricing structure across FOSHU-certified functional, standard food-grade, and commodity feed-tier proteins separates premium amino acid-optimized isolates from bulk concentrates. Price differentiation hinges on germination-enhanced bioavailability claims and JIS certification status. Pricing pressure stems from domestic pork subsidy programs that maintain animal protein retail gaps. Institutional catering networks show lowest price sensitivity due to locked contract structures, while mid-tier bento producers face acute cost compression.
Supply Chain Analysis
Soybean supply rests on North American crushing capacity, Canadian rapeseed processors, and emerging Australian pea protein extraction facilities. Raw material flows draw from imported genetically modified soybeans, domestic non-GMO cultivation contracts in Hokkaido, and germination technology licensing inputs. Single-source vulnerability concentrates in Tokyo-Osaka corridor distribution nodes where perishable extruded proteins require same-day delivery infrastructure. Distribution runs through Mitsubishi Corporation and Itochu Corporation trading house networks, though direct-to-manufacturer platforms are eroding this intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where functional FOSHU certification and carbon-verified supply chains displace commodity tonnage. Health-conscious consumers in metropolitan prefectures now prioritize amino acid-optimized isolates over bulk concentrates, rewarding manufacturers with germination technology and fermentation infrastructure.
For Market Incumbents: Deploy germination technology licensing as a defensive moat against pea protein entrants. Secure multi-year offtake agreements with Kyushu institutional catering networks before regional crushing capacity expands. Invest in FOSHU certification pipelines to maintain premium positioning as METI tightens carbon disclosure requirements. Backward integration into Hokkaido soybean cultivation reduces currency exposure on North American imports.
For New Entrants and Emerging Players: Launch via direct-to-manufacturer ingredient platforms that bypass entrenched trading house structures. Target Kyushu's underpenetrated extrusion facility gap with regional crushing investments focused on rapeseed protein security. Exploit F-Gas Regulation compliance services as a consulting revenue wedge before carbon accounting mandates harden. Sports nutrition formulators in Osaka present the most penetrable segment for allergen-free pea protein positioning.
For Investors and Strategic Acquirers: Roll-up economics work for germination technology specialists because METI's protein diversification mandates compress customer acquisition timelines for functional ingredient platforms. Five-to-ten year viability favors facilities with integrated fermentation and extrusion infrastructure over pure trading plays. Watch PMDA FOSHU certification queue lengths as an inflection signal for premium pricing power concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Germination Technology Licensing | DAIZ Inc.'s enzymatic pre-processing patents enable amino acid bioavailability claims that accelerate FOSHU pathways. |
| Multi-year Offtake Agreements | Tokyo foodservice operators bypass spot markets entirely, locking in 36-month supply security with regional crushers. |
| Kyushu Regional Crushing Investment | Southern Japan's agricultural belt lacks dedicated extrusion facilities, creating first-mover advantages for supply security plays. |
| F-Gas Compliance Retrofit Services | Carbon accounting pressures on extrusion equipment energy profiles open engineering consulting revenue streams. |
| Direct-to-Manufacturer Platform Launch | Bypassing Mitsubishi Corporation and Itochu Corporation intermediaries captures margin pools previously absorbed by trading houses. |
Research Methodology
Bottom-up foodservice procurement modeling reconciled against top-down crushing capacity tracking forms the analytical core of this study. Primary interviews with ingredient procurement managers at bento producers, sports nutrition formulators, and institutional catering directors combined with extrusion equipment operators and germination technology licensors. Secondary validation drew from METI Food Industry Vision policy documents, PMDA FOSHU certification databases, JIS food-grade protein specifications, and customs import records for soybean and rapeseed shipments. Triangulation between demand-side offtake contract analysis and supply-side facility capacity assessments anchors forecast precision.
Input-output matrix framing maps protein source diversification across soy, pea, rice, and wheat categories against end-use applications spanning meat alternatives, nutritional supplements, dairy analogs, and bakery fortification. Segmentation dimensions include product type, application channel, end-user archetype, and distribution structure. CAGRs derive from facility capacity expansion announcements, germination technology licensing velocity, and METI policy implementation timelines. Forecast inputs incorporate FOSHU certification queue dynamics and F-Gas Regulation compliance cost trajectories for extrusion equipment.
Forecast precision tightens around the base case; tail outcomes carry wider variance under currency volatility spikes or North American trade friction scenarios. Assumptions reflect documented protein diversification mandates, carbon disclosure guideline adoption curves, and crushing infrastructure investment patterns. Regulatory timeline slippage at PMDA or METI funding reallocation represent specific revision triggers. A small set of policy implementation velocity, germination technology licensing rates, and institutional procurement contract conversion warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Asia-Pacific Plant-Based Seafood Market
Plant Based Food
US Plant-Based Meat Market
Plant Based Food
Plant-Based Shrimp Market
Plant Based Food
Vegan Spaghetti Market
Plant Based Food
China Plant-Based Food and Beverages Market
Plant Based Food
Kava Root Extract Market
Plant Based Food
Oat-Based Cereals Market
Plant Based Food
Plant-Based Sausages Market
Plant Based Food
India Plant Protein Market
Plant Based Food
Targeting Pod Market
Plant Based Food
Plant Based Collagen Market
Plant Based Food
Plant Based Ice Cream Market
Plant Based Food
Vegan Pasta Market
Plant Based Food
Dandelion Root Extract Market
Plant Based Food
Oat Protein Market
Plant Based Food
Plant-Based Vegan Eggs Market