
 Carragean Alternatives Market | 2026-2036
Carragean Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Carragean Alternatives Market Analytics
Seaweed harvesters in Southeast Asia are decoupling from traditional carrageenan output as climate variability disrupts raw material reliability. CP Kelco leverages its bacterial fermentation infrastructure to produce gellan gum as a direct textural substitute. Tate & Lyle anchors European supply chains through its pectin extraction facilities in Slovakia and Denmark. Sea6 Energy competes with offshore seaweed cultivation systems designed for alternative hydrocolloid streams.
Carrageenan alternatives comprise plant-derived and microbial hydrocolloids that provide gelling, thickening, and stabilizing functionality in formulated products, typically achieving gel strengths between 200-800 g/cm² depending on extraction method and botanical source. Pectin dominates food and beverage applications where low-methoxyl variants enable calcium-set gels in dairy analogs, while agar occupies premium segments requiring thermo-reversible gels with high melting points. Xanthan gum extends into industrial formulations where pseudoplastic flow behavior controls viscosity under shear stress.
FDA GRAS self-determination pathways govern novel hydrocolloid introductions in the United States, while EFSA novel food evaluations create entry barriers for emerging seaweed extracts in European formulations. BIS certification requirements in India mandate compositional testing for imported gum substitutes used in packaged foods. Stakeholders must monitor evolving allergen labeling rules for emerging marine and fungal-derived alternatives as jurisdictions diverge on precautionary thresholds.
Market Dynamics
Formulators in plant-based dairy are accelerating substitution of seaweed-derived stabilizers as EFSA evaluations restrict certain carrageenan variants, redirecting procurement toward land-based hydrocolloids with verified clean-label credentials.
Growth Catalysts
- EFSA phased restrictions:The European Union's additive evaluations are compelling manufacturers to reformulate with pectin and agar alternatives that bypass pending regulatory scrutiny.
- Bacterial fermentation infrastructure:Microbial gellan gum production leverages existing biotechnology assets to deliver consistent textural performance independent of marine harvest variability.
- Clean-label budget expansion:German food manufacturers have increased ingredient investment allocations specifically for hydrocolloid substitutes with transparent supply chains.
Market Restraints
- Raw material volatility:Seaweed harvesters in Southeast Asia face climate-driven supply interruptions that destabilize traditional carrageenan pricing and availability.
- EFSA novel food barriers:Emerging seaweed extracts encounter prolonged safety assessment timelines that delay European market entry for innovative alternatives.
- Gel strength performance gaps:Certain agar variants fail to match carrageenan's elasticity in high-fat dairy analogs, limiting direct substitution ratios.
Strategic Opportunities
- India BIS certification pathway:Compositional testing mandates for imported gum substitutes create first-mover advantage for suppliers establishing certified local distribution.
- Calcium-set dairy analogs:Low-methoxyl pectin enables clean-label gelation in oat and almond milk formulations where consumers reject phosphate additives.
- Offshore seaweed cultivation:Dedicated alternative hydrocolloid streams from controlled marine systems reduce dependency on wild harvest ecosystems.
Industry Challenges
- Allergen labeling divergence:Jurisdictions apply inconsistent precautionary thresholds for fungal and marine-derived alternatives, complicating multi-market packaging compliance.
- Extraction method standardization:Gel strength variation between 200-800 g/cm² across botanical sources requires batch-specific formulation recalibration by R&D teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carragean Alternatives Market |
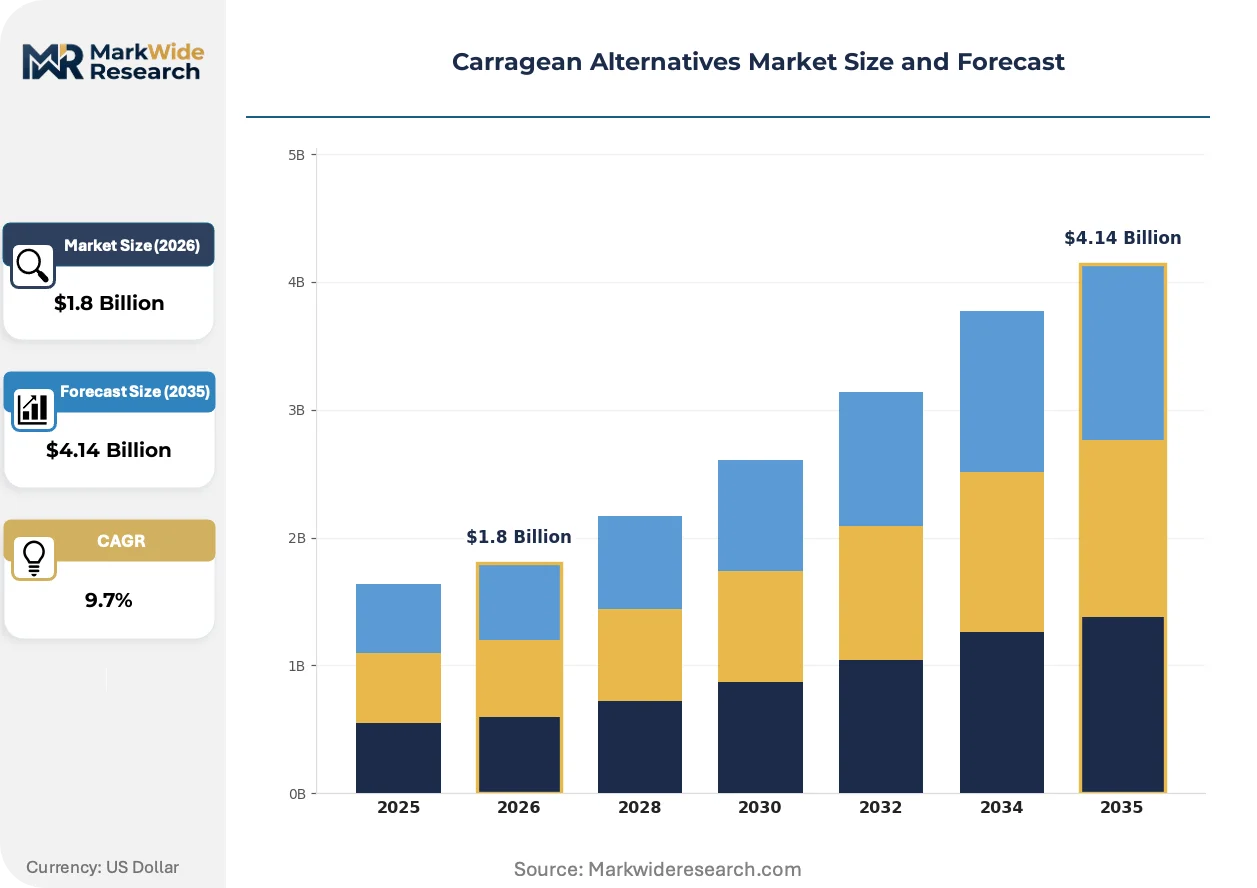
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agar, Pectin, Gum Arabic, Xanthan Application: Food & Beverage, Personal Care, Pharmaceuticals, Textiles Form: Powder, Liquid, Granules, Flakes End User: Food Manufacturers, Cosmetic Brands, Health Companies, Industrial Users |
| Companies Covered | Tate & Lyle, CP Kelco, DSM-Firmenich, Univar Solutions, Gelymar, Sea6 Energy, Sway, Umaro Foods, Carbonwave, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carragean Alternatives Market Evolving Landscape
Bacterial fermentation platforms and precision extraction methods are compressing development cycles for hydrocolloid alternatives, while regulatory divergence between FDA self-determination and EFSA novel food pathways is fragmenting go-to-market strategies by geography.
Precision fermentation of gellan gum is expanding into high-value dairy analog applications where thermo-reversible gelation and pseudoplastic flow control justify premium positioning. Plant-based cheese manufacturers in North America are adopting these microbial hydrocolloids at accelerated rates. The technology is expanding into clean-label formulations previously dominated by modified starches.
EFSA's additive re-evaluation framework is compelling European formulators to maintain dual formulation portfolios pending final carrageenan classification. Food manufacturers in Germany and France are pre-emptively shifting procurement to pectin suppliers with established GRAS-equivalent dossiers. This regulatory friction is compressing supplier qualification timelines and favoring hydrocolloid producers with existing European extraction infrastructure.
Direct sourcing relationships between food manufacturers and hydrocolloid extractors are displacing traditional ingredient distributor intermediaries. Large plant-based dairy brands are negotiating volume commitments with Slovak and Danish pectin facilities to secure supply priority. This channel consolidation is most visible in Germany, where clean-label ingredient budgets have centralized procurement authority at headquarters level rather than regional purchasing offices.
Carragean Alternatives Market Segmentation
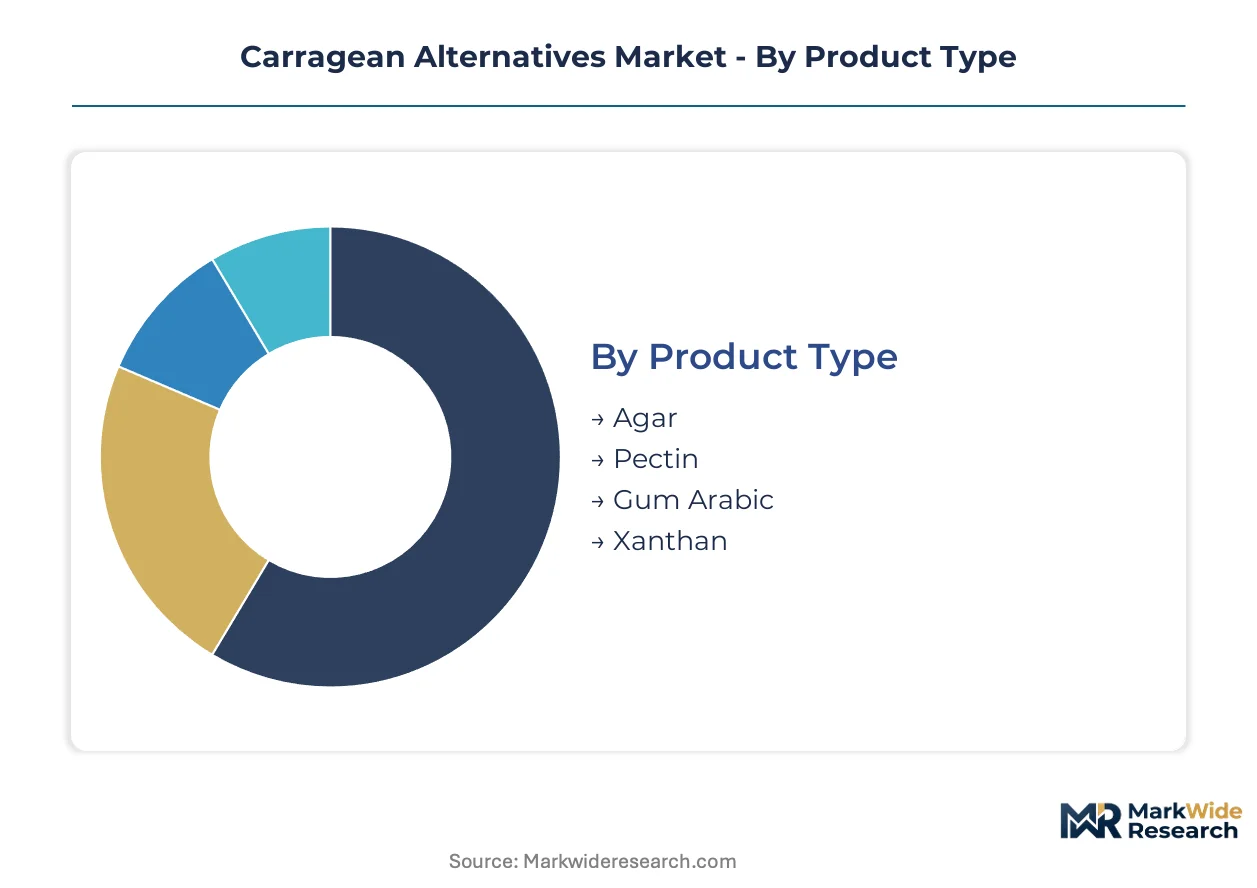
Carrageenan alternatives span distinct functional categories where integration depth varies sharply. Some hydrocolloids operate as standalone stabilizers while others demand co-formulation with complementary ingredients to achieve target textures.
Product Type:
Standalone hydrocolloids dominate high-volume applications where single-ingredient solutions reduce formulation complexity, while embedded systems require precise synergy between multiple texturizers.
- Pectin:Low-methoxyl and high-methoxyl variants extracted from citrus peel and apple pomace provide calcium-dependent or acid-set gelation. Demand concentrates in German dairy analog manufacturing where clean-label credentials command procurement priority amid EFSA additive scrutiny.
- Agar:Thermo-reversible gels from red algae (Gelidium and Gracilaria species) deliver melting points above 85°C with exceptional clarity. Premium confectionery and microbiological media applications in France and Japan absorb supply from controlled cultivation operations.
- Xanthan:Xanthomonas campestris fermentation yields pseudoplastic polysaccharides with salt and pH stability across industrial formulations.
- Gum Arabic:Acacia senegal and Acacia seyal exudates provide emulsification in beverage systems and encapsulation matrices for flavor oils.
Pectin leads volumes today; agar is gaining share fastest.
Application:
Cost tier stratification separates commodity-scale food manufacturing from premium-positioned personal care and pharmaceutical segments where purity grades justify 3-5x ingredient premiums.
- Food & Beverage:Plant-based dairy, confectionery, and beverage stabilization consume the majority of hydrocolloid volumes. North American oat milk formulators specify low-methoxyl pectin for calcium-set gels that replace phosphate additives rejected by clean-label consumers.
- Pharmaceuticals:USP-grade agar and gellan gum serve as tablet binders, controlled-release matrices, and microbiological culture media where endotoxin limits apply. FDA drug master file requirements extend supplier qualification timelines beyond standard food-grade protocols.
- Personal Care:Hydrocolloids provide rheology modification in creams and suspensions for mineral sunscreens.
- Textiles:Sizing and printing paste applications consume technical-grade alternatives where gel strength tolerances are less stringent.
Food and beverage commands the largest revenue pool; pharmaceuticals is expanding most quickly.
Form:
Supply concentration among extraction facilities favors powder processing for shelf stability and freight efficiency, while liquid concentrates serve formulators seeking hydration time reduction.
- Powder:Spray-dried and roller-dried hydrocolloid powders with standardized particle size distributions enable precise dosing in automated batching systems. German and Slovak pectin facilities ship predominantly powder grades to European compounders.
- Liquid:Pre-hydrated gum dispersions eliminate dust exposure and reduce mixing time in high-throughput dairy processing lines.
- Granules:Intermediate particle sizes balance dissolution speed with storage stability for mid-scale manufacturers.
- Flakes:Traditional agar presentation for laboratory and artisan food applications where visual quality assessment matters.
Powder dominates current procurement; liquid forms are climbing fastest in dairy processing.
End User:
Customer type determines specification stringency and contract structure, with multinational food manufacturers imposing traceability requirements that exclude smaller extractors.
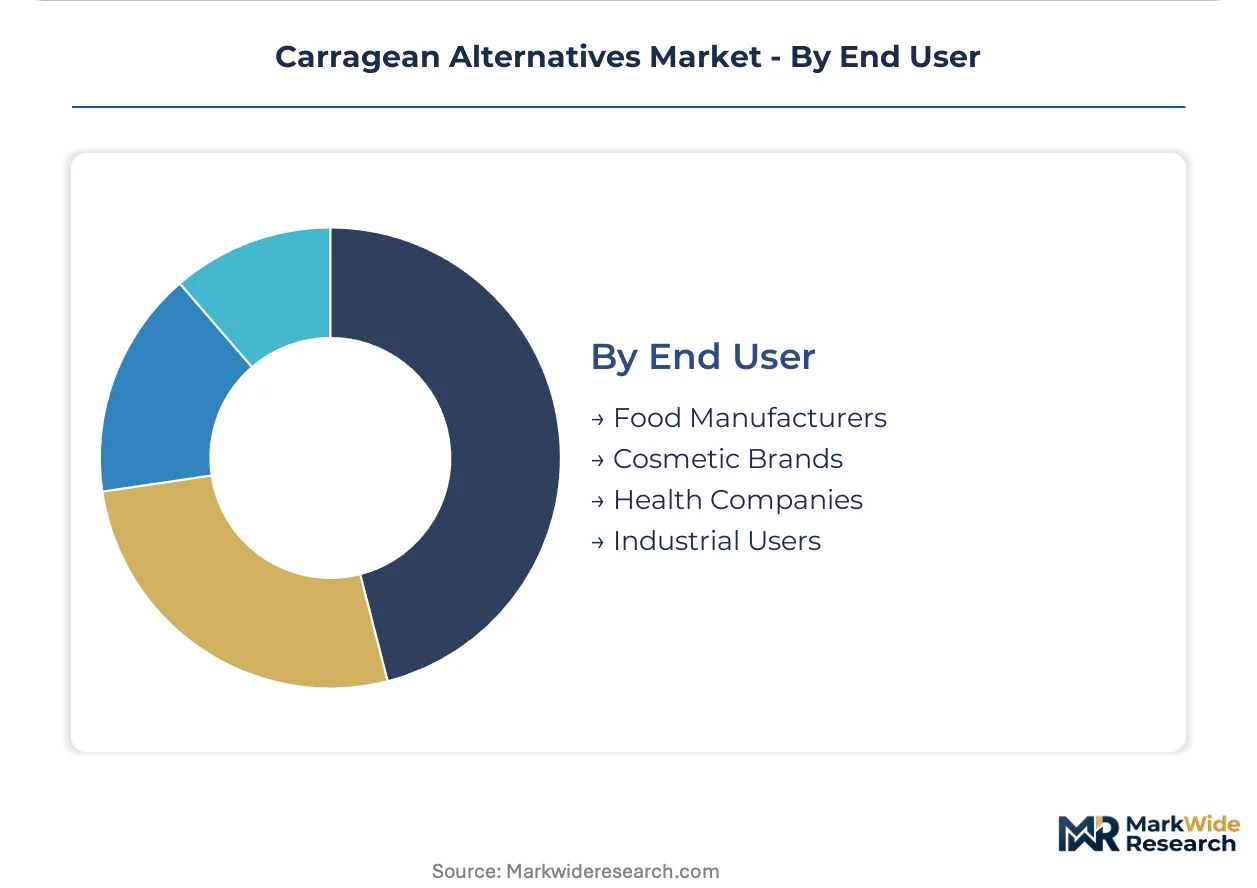
- Food Manufacturers:Plant-based dairy brands in North America and Europe negotiate direct supply agreements with pectin and gellan gum producers to bypass distributor margins and secure volume allocation.
- Cosmetic Brands:Clean beauty positioning drives preference for fermentation-derived hydrocolloids with marine-free claims.
- Health Companies:Nutraceutical encapsulation and probiotic delivery systems specify pharmaceutical-grade gums.
- Industrial Users:Textile, paper, and oilfield applications consume technical-grade alternatives where price sensitivity exceeds purity requirements.
Food manufacturers lead absolute consumption; cosmetic brands are expanding specification fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between FDA self-determination and EFSA novel food pathways is driving production migration toward jurisdictions with lower compliance costs. Manufacturers are relocating extraction capacity to exploit these cost-of-compliance gaps while maintaining market access.
United States
Plant-based dairy brands in California and the Pacific Northwest are accelerating gellan gum adoption for oat milk stabilization. FDA GRAS self-determination pathways enable rapid ingredient introductions without pre-market approval delays. Seattle-area food technology clusters house fermentation facilities supplying microbial hydrocolloids to North American formulators.
Germany
Clean-label ingredient budgets at major food manufacturers have expanded procurement allocations for pectin alternatives. EFSA additive re-evaluations are compelling reformulation away from pending carrageenan restrictions. Bavarian and North Rhine-Westphalian processing facilities anchor European pectin supply chains through direct manufacturer agreements.
India
Domestic packaged food manufacturers are qualifying imported gum substitutes under BIS certification mandates. FSSAI compositional testing requirements for hydrocolloids create entry barriers for uncertified suppliers. Maharashtra and Gujarat industrial corridors concentrate extraction facility investments targeting pharmaceutical-grade agar production.
China
SAMR food additive regulations are tightening documentation requirements for seaweed-derived stabilizers used in dairy analogs. GB standards for hydrocolloid purity are diverging from international specifications. Yangtze River Delta chemical processing zones house fermentation capacity expanding into microbial polysaccharide alternatives.
Brazil
ANVISA food additive registrations are extending timelines for novel hydrocolloid market entry. Domestic confectionery manufacturers are qualifying agar suppliers from controlled cultivation operations. São Paulo state industrial parks concentrate beverage formulation facilities driving stabilizer demand.
Carragean Alternatives Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue fermentation-derived and marine-cultivation niches. The supplier base stratifies between extraction-based incumbents with agricultural raw material dependencies and biotechnology platforms leveraging bacterial production. Three archetypes dominate: pectin extractors with citrus peel supply chains, fermentation specialists with gellan gum capacity, and seaweed cultivators with controlled marine systems. Capacity expansion and direct supply contracting represent the primary competitive vectors as manufacturers bypass distributor intermediaries.
Within the biotechnology tier, CP Kelco exemplifies fermentation infrastructure deployment for microbial hydrocolloid production. Tate & Lyle occupies a position among established European extractors with pectin processing assets in Slovakia and Denmark. Sea6 Energy represents the marine cultivation archetype through offshore seaweed systems designed for alternative hydrocolloid streams.
| Leading Market Players |
|---|
| Tate & Lyle |
| CP Kelco |
| DSM-Firmenich |
| Univar Solutions |
| Gelymar |
| Sea6 Energy |
| Sway |
| Umaro Foods |
| Carbonwave |
| Others |
Value Network & Pricing Analysis
EU Green Deal sustainability mandates gate qualified supply access for carrageenan alternatives, with carbon footprint disclosures and marine stewardship certifications now prerequisites for premium-tier pricing eligibility at major European food manufacturers.
Pricing Analysis
Distributor margins of 12-18 percent on standard hydrocolloid grades compress to 6-9 percent under direct-to-manufacturer volume contracts negotiated by North American plant-based dairy brands. Pricing stratifies across pharmaceutical-grade, food-grade, and technical-grade tiers where USP certification commands 3-4x multiples over industrial applications. Cost compression in standard pectin grades is intensifying as Slovak and Danish extraction facilities expand output. Private-label food manufacturers exhibit highest price sensitivity; pharmaceutical encapsulation specialists show lowest.
Supply Chain Analysis
Ocean freight rates from Southeast Asian seaweed harvesting zones to European compounding facilities constitute 15-22 percent of delivered agar costs, driving procurement regionalization toward Baltic and North Sea pectin sources. Raw material supply draws from citrus peel processors in Mexico and Brazil, apple pomace streams from European cider production, and controlled Gracilaria cultivation in Indonesia and the Philippines. Single-source vulnerability concentrates in red algae biomass for premium agar variants. Distribution runs through integrated ingredient houses and direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EFSA additive re-evaluations are accelerating substitution timelines and compressing supplier qualification windows for clean-label hydrocolloid procurement.
For Market Incumbents: Anticipate bacterial fermentation platforms displacing extraction-based supply for high-value dairy analog applications. Secure backward integration into citrus peel supply chains in Mexico and Brazil to defend margin position against raw material volatility. Invest in dual-certification dossiers spanning FDA GRAS self-determination and EFSA novel food pathways to maintain European market access. For New Entrants and Emerging Players: Precision fermentation of gellan gum offers technology-first entry into thermo-reversible gelation segments where incumbent extraction infrastructure carries higher carbon intensity. Target pharmaceutical-grade agar production in India where BIS certification creates first-mover advantage under FSSAI compositional testing mandates. Pursue direct supply contracting with California oat milk brands seeking marine-free clean-label positioning. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale extraction specialists with unutilized fermentation retrofit capacity and established European regulatory dossiers. Five-to-ten year viability hinges on regulatory divergence persisting between FDA and EFSA pathways. Monitor EFSA final carrageenan classification timing as inflection indicator for substitution demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citrus Peel Supply | Mexican and Brazilian pomace sourcing secures low-methoxyl pectin feedstock for calcium-set dairy analogs. |
| Fermentation Capacity Expansion | Microbial gellan gum production at CP Kelco leverages existing biotechnology assets independent of marine harvest variability. |
| Dual-Certification Dossier Investment | Parallel FDA GRAS and EFSA novel food submissions reduce go-to-market fragmentation across Atlantic markets. |
| Direct Supply Contracting | Volume commitments with German dairy analog manufacturers displace distributor intermediaries and secure allocation priority. |
| Offshore Seaweed Cultivation Systems | Sea6 Energy's controlled marine platforms reduce dependency on wild harvest ecosystems facing climate-driven disruption. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with hydrocolloid procurement directors at plant-based dairy manufacturers, extraction facility operations managers in Slovakia and Denmark, regulatory affairs specialists navigating EFSA novel food pathways, and bacterial fermentation platform engineers. Secondary validation draws from FDA GRAS notification databases, EFSA additive re-evaluation dossiers, BIS certification registries, and customs trade data on hydrocolloid imports. Bottom-up volume modeling triangulates against top-down market sizing across ingredient spending categories.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. Segmentation dimensions include hydrocolloid source type, functional application, purity grade tier, and regional regulatory cluster. CAGRs derive from trend extrapolation of substitution ratios in plant-based dairy, adjusted for EFSA timeline uncertainty and clean-label budget expansion at German food manufacturers. Industry-specific inputs incorporate gel strength performance benchmarks and extraction yield differentials between botanical sources.
The model holds under sustained regulatory divergence between FDA self-determination and EFSA novel food pathways; deviation in harmonized global additive standards or accelerated carrageenan safety clearance would shift substitution velocity assumptions. A model refresh is warranted upon material change in EFSA final classification timing or marine biomass harvest disruption severity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Corn-Based Protein Market
Alternative Food Sources
Insect Snacks Market
Alternative Food Sources
Mycoprotein Market
Alternative Food Sources
Teff Products Market
Alternative Food Sources
Africa Fat Replacers Market
Alternative Food Sources
Low Carbs Vegan Food Market
Alternative Food Sources
Spirulina Market
Alternative Food Sources
Vegan Caviar Market
Alternative Food Sources
United States Hemp Protein Market
Alternative Food Sources
Organic Gluten Substitutes Market
Alternative Food Sources
Fat Replacers Market
Alternative Food Sources
Hemp-Based Products Market
Alternative Food Sources
Seitan Market
Alternative Food Sources
Algal Protein Market
Alternative Food Sources
Vegetable Waste Products Market
Alternative Food Sources
Vegan Egg Substitute Market