
 Fat Substitutes Market | 2026-2036
Fat Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
Fat Substitutes Market Analytics
The fat substitutes sector is rebalancing as premium clean-label formulations split from commodity-grade ingredients on price and sourcing transparency. Cargill Incorporated leverages its global oilseed processing network to secure consistent feedstock for lipid analog production. Kerry Group PLC differentiates through taste-modulation technologies that mask off-notes in protein-based fat replacers. Tate & Lyle PLC anchors its position in specialty starches with modified amylopectin structures designed for bakery fat mimetic applications.
Fat substitutes are functional ingredients engineered to replicate the mouthfeel, lubricity, and flavor release of conventional fats while delivering reduced caloric density or modified nutritional profiles; these materials typically achieve 0.5–4.0 kcal/g versus 9 kcal/g for triglycerides through carbohydrate polymer matrices, protein microparticulation, or structured lipid architectures. Their primary commercial purpose centers on enabling food manufacturers to meet reformulation targets for reduced-fat and reduced-calorie product lines without sacrificing sensory acceptance. Protein-based substitutes command attention in dairy and beverage applications where emulsion stability and creaminess prove critical, while starch-based systems dominate baked goods and sauces where moisture retention and viscosity control drive performance. Gum-based fat replacers occupy narrower but higher-margin niches in dressings and premium sauces where rheological precision justifies ingredient cost premiums.
The FDA governs fat substitute safety through GRAS notifications and food additive petitions, while the USDA oversees their use in meat and poultry products through FSIS labeling standards; EFSA evaluates novel fat replacers under the EU novel food regulation, creating dual compliance pathways for suppliers serving transatlantic markets. WHO's REPLACE action framework on trans fat elimination indirectly channels demand toward approved fat substitute categories by restricting partially hydrogenated oil availability. Stakeholders must monitor evolving definitions of "healthy" nutrient content claims across jurisdictions, as these directly determine which fat substitute technologies qualify for front-of-package labeling advantages.
Market Dynamics
Reformulation mandates from FDA and EFSA are compressing decision timelines for processed food manufacturers, forcing simultaneous substitution of saturated fats and elimination of residual trans fats across retail product portfolios.
Growth Catalysts
- WHO REPLACE Framework:The trans fat elimination protocol restricts partially hydrogenated oil availability, redirecting bakery and frying fat demand toward structured lipid alternatives and carbohydrate-based replacers.
- Clean-Label Protein Microparticulation:Dairy processors deploy advanced wet-milling technologies to create sub-micron protein particles that replicate triglyceride mouthfeel in reduced-fat cheese and yogurt applications.
- Germany's Bakery Sector:EU-wide fat composition standards under EFSA enforcement are accelerating ingredient substitution decisions among Central European baked goods manufacturers.
Market Restraints
- Soybean Oil Price Volatility:Feedstock cost swings for lipid analog production compress margins for commodity-grade fat substitute suppliers dependent on oilseed derivatives.
- Modified Starch Supply Concentration:Specialty amylopectin production clusters in Midwestern US corn processing regions, creating geographic single-point vulnerability for bakery fat mimetic sourcing.
- Taste-Masking Technical Ceiling:Protein-based replacers in beverage applications encounter persistent off-note challenges that limit substitution rates below sensory acceptance thresholds.
Strategic Opportunities
- India Processed Food Expansion:FSSAI's evolving standards on fat content claims create first-mover advantage for suppliers establishing local production of clean-label carbohydrate replacers.
- Cell-Cultured Fat Convergence:Precision fermentation-derived lipid structures are converging with plant-based analog production, opening hybrid formulation pathways for premium meat alternatives.
- Direct-to-Manufacturer Digital Platforms:Ingredient marketplaces bypass traditional distributor networks, enabling smaller fat substitute developers to access mid-sized food processors previously locked by volume minimums.
Industry Challenges
- GRAS Notification Timeline Compression:FDA's evolving safety review standards for novel lipid architectures extend pre-market approval cycles, straining R&D-to-commercialization cash flow.
- Cross-Functional Formulation Expertise Gap:Shortage of technologists trained in both rheology and flavor chemistry slows pilot-scale optimization of multi-component fat mimetic systems.
- Dual Jurisdiction Compliance Burden:Suppliers serving transatlantic markets must simultaneously satisfy FDA GRAS pathways and EFSA novel food assessments, duplicating toxicology and exposure studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fat Substitutes Market |
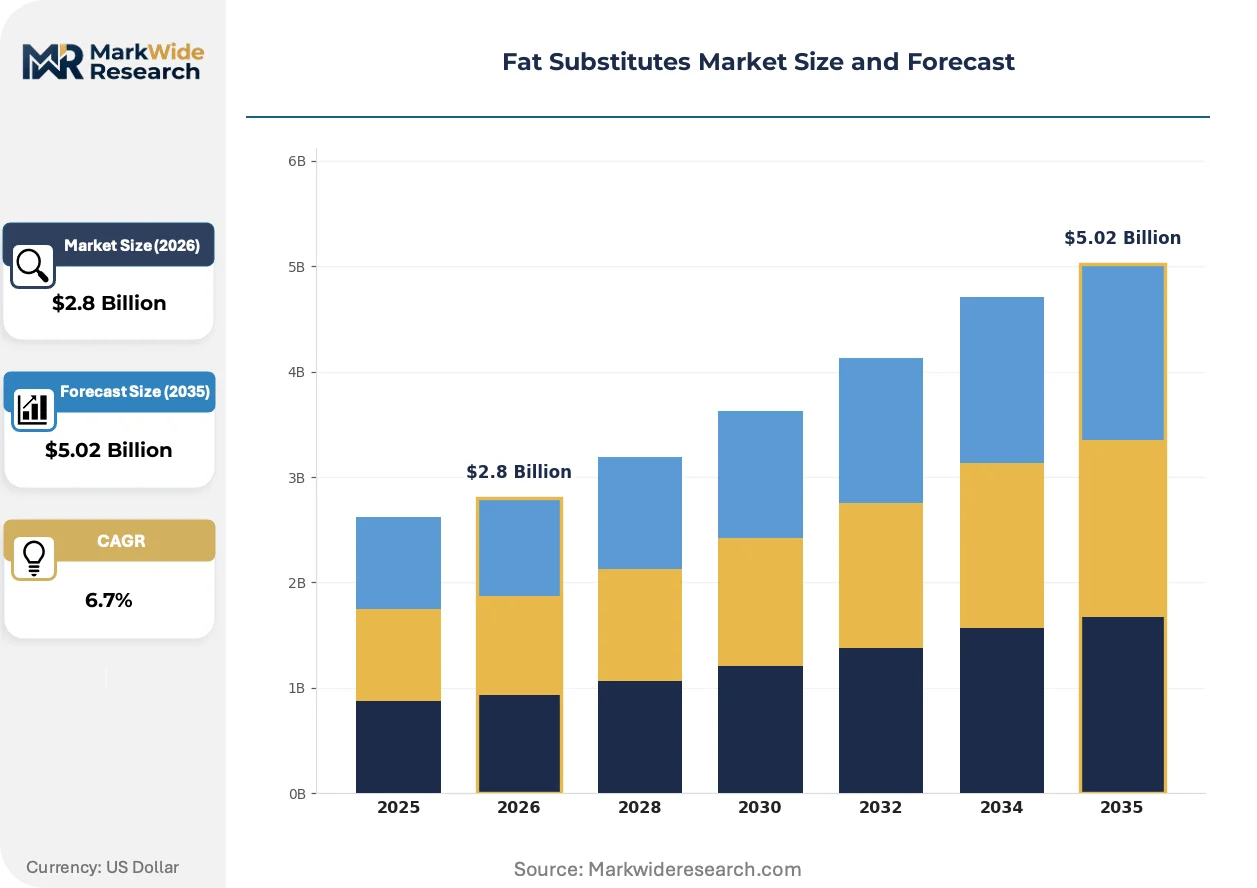
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starch-Based, Protein-Based, Gum-Based, Fat-Based End User: Food Manufacturers, Beverage Producers, Snack Companies, Dairy Processors Application: Baked Goods, Dressings, Dairy Products, Sauces Form: Powder, Liquid, Gel, Cream |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Kerry Group PLC, Tate & Lyle PLC, Ingredion Incorporated, FMC Corporation, DuPont de Nemours Inc., Koninklijke DSM N.V., CP Kelco U.S. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fat Substitutes Market Evolving Landscape
Active reformulation is fragmenting the supplier base into taste-modulation specialists and commodity feedstock processors, with technology ownership determining margin capture in premium versus standard product tiers.
Enzymatic interesterification is converging with zero-trans fat production requirements, enabling precise structuring of triglyceride chains without hydrogenation. Margarine and shortening manufacturers in North America and Western Europe are retrofitting production lines at accelerated pace. This convergence is compressing demand for legacy partially hydrogenated oils while elevating enzyme supplier influence in formulation decisions.
EFSA's updated nutrient profiling criteria for front-of-pack labeling are reshaping acceptable fat content thresholds across EU member states. Processed food manufacturers must now achieve dual compliance with national interpretive schemes and harmonized EU standards. Dairy and confectionery segments face the steepest reformulation curves, with German and French processors leading adaptation investments.
Ingredient co-development contracts are displacing spot purchasing for critical fat mimetic systems, with food manufacturers embedding suppliers earlier in product development cycles. This shift concentrates procurement influence among technical service-capable ingredient houses. The pattern is most pronounced in US and European bakery and sauce categories, where formulation lock-in creates switching costs.
Fat Substitutes Market Segmentation
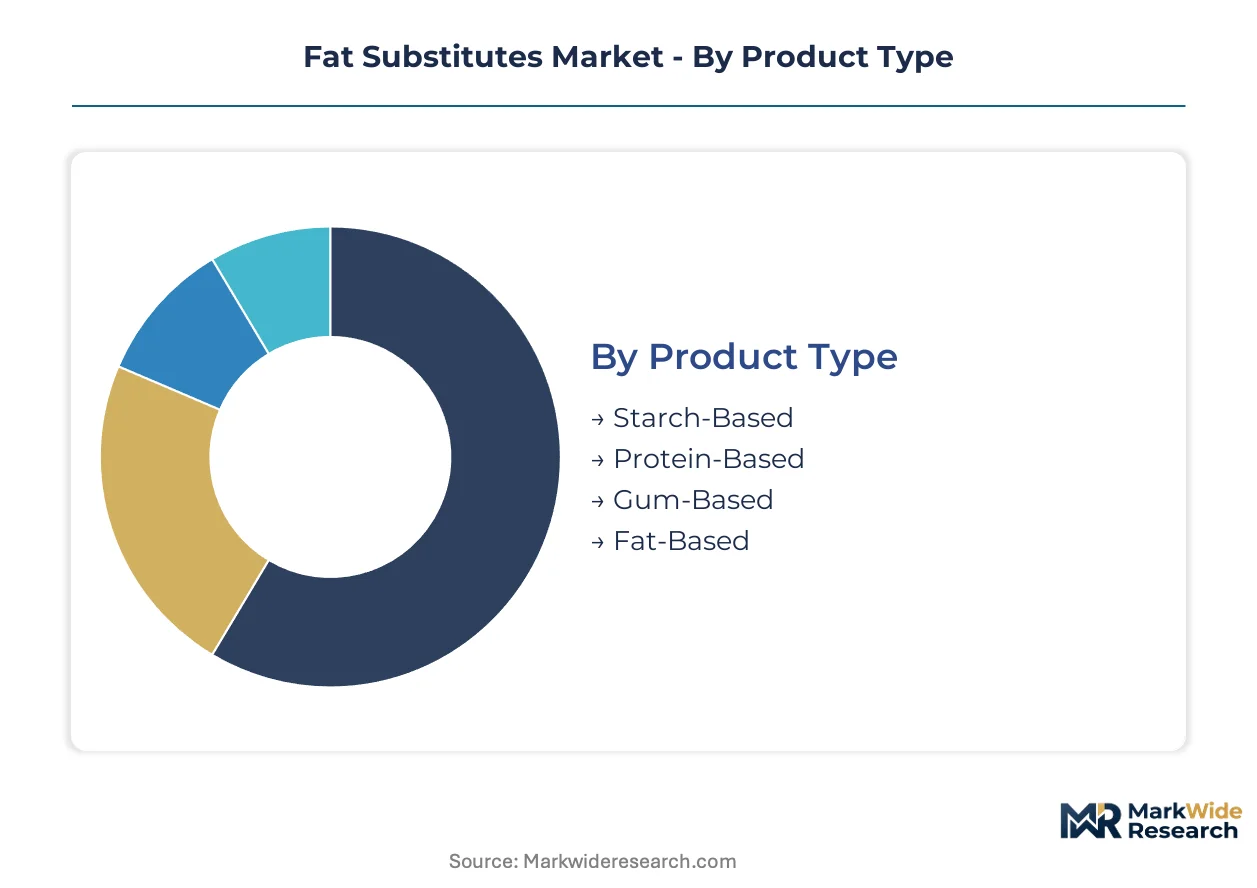
Segmentation in the fat substitutes market reveals how reformulation pressures fragment demand across technical performance tiers. Manufacturers select substitute categories based on specific mouthfeel requirements, thermal stability needs, and clean-label positioning targets rather than cost alone.
Product Type:
Upgrade cycles in fat substitute procurement favor platforms that solve multiple technical constraints simultaneously—moisture retention, emulsion stability, and clean-label compliance—rather than single-attribute solutions.
- Starch-Based:Modified amylopectin structures from corn and potato sources deliver viscosity control and moisture retention in reduced-fat bakery applications. German and US baked goods manufacturers concentrate procurement here due to EFSA and FDA alignment on modified starch regulatory status. Reformulation timelines compress as front-of-pack labeling rules tighten.
- Protein-Based:Microparticulated whey and plant proteins replicate fat globule mouthfeel through sub-micron particle engineering. Dairy processors in France and yogurt manufacturers in the United States drive specification intensity where creaminess thresholds prove hardest to satisfy. Wet-milling technology investments separate premium suppliers from commodity processors.
- Gum-Based:Xanthan and guar systems provide rheological precision in pourable dressings.
- Fat-Based:Structured lipids and lipid analogs replace trans fats in frying and shortening applications.
Volume placements concentrate in Starch-Based systems; the faster expansion belongs to Protein-Based formulations.
End User:
Cost tier stratification separates multinational reformulation programs with dedicated R&D partnerships from mid-tier buyers dependent on distributor technical support.
- Food Manufacturers:Processed food conglomerates run parallel reformulation tracks for saturated fat reduction and trans fat elimination across retail portfolios. Cargill and Kerry Group embed technical service teams directly in client pilot facilities. FDA nutrition labeling updates and EFSA nutrient profiling force synchronized global specification changes.
- Dairy Processors:Cheese and yogurt producers face steepest sensory acceptance thresholds where protein-based replacers must mask off-notes while maintaining emulsion stability. German and French dairy cooperatives lead adaptation investments under EU-wide fat composition standards. Clean-label positioning drives premium pricing tolerance.
- Beverage Producers:Reduced-fat dairy beverages and meal replacements source fat mimetics for viscosity without opacity.
- Snack Companies:Extruded and fried snack manufacturers prioritize lipid analogs for frying stability.
Procurement volume clusters with Food Manufacturers; Dairy Processors are gaining share fastest as reformulation intensity deepens.
Application:
Application-specific performance requirements create technology lock-in where switching costs rise with formulation complexity and regulatory filing investments.
- Baked Goods:Cakes, pastries, and bread systems demand fat replacers that maintain aeration structure and crumb softness through freeze-thaw cycles. US and German bakery manufacturers specify modified starches with precise amylose-amylopectin ratios. EFSA front-of-pack criteria and FDA serving-size updates compress decision timelines.
- Dairy Products:Ice cream, cheese, and yogurt applications require fat mimetics that replicate crystallization behavior and flavor release kinetics. French ice cream producers and US Greek yogurt manufacturers drive protein-based system development. Emulsion stability under high-shear processing separates qualified suppliers.
- Dressings:Pourable and spoonable dressings prioritize gum-based systems for suspension and pour viscosity.
- Sauces:Hot-fill and retort sauces demand thermal stability in carbohydrate-based fat replacers.
Formulation activity concentrates in Baked Goods; Dairy Products show the steepest expansion trajectory as clean-label positioning intensifies.
Form:
Supply concentration in powder processing infrastructure creates geographic sourcing constraints that liquid and gel formats circumvent through distributed compounding.
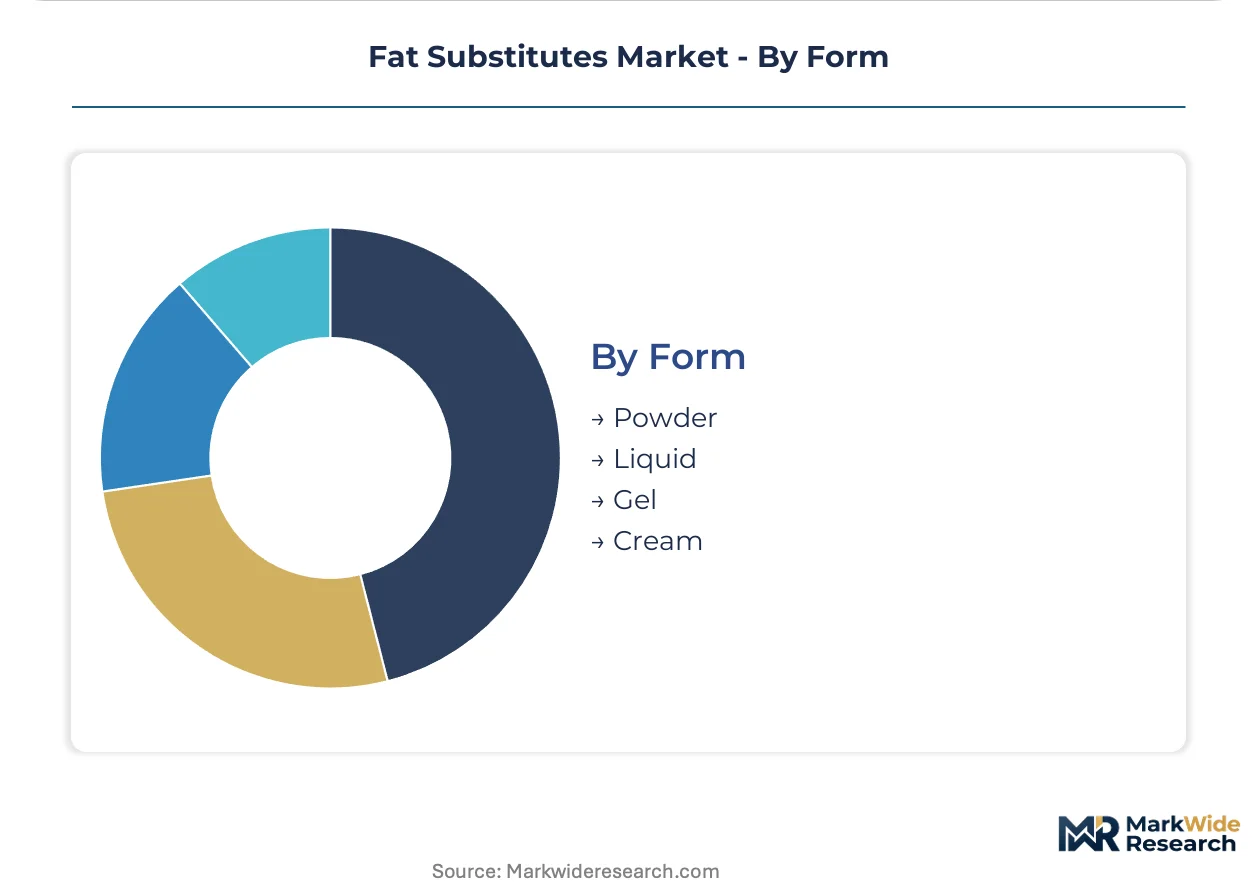
- Powder:Spray-dried and agglomerated formats dominate bakery and dry-mix applications where storage stability and handling efficiency outweigh hydration requirements. Midwestern US corn processing clusters and European potato starch facilities anchor supply. Freight economics favor regional sourcing for high-volume users.
- Liquid:Pumpable concentrates serve beverage and sauce manufacturers with continuous processing lines and automated dosing systems. US dairy processors and German dressing manufacturers prefer liquid protein microparticulates for inline blending efficiency. Cold-chain requirements limit distribution radius.
- Gel:Pre-hydrated gum systems target small-batch sauce and premium dressing producers.
- Cream:High-solids emulsions replicate dairy fat functionality in spoonable applications.
Shipments concentrate in Powder; Liquid is climbing the fastest as continuous processing adoption spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American fat substitute procurement through its concentration of corn wet-milling infrastructure and proximity to Midwestern starch processing clusters. The city's logistics networks distribute modified amylopectin systems to bakery manufacturers across the Great Lakes and Eastern Seaboard corridors.
United States
Reformulation mandates from FDA nutrition labeling updates compress decision timelines for processed food conglomerates headquartered in Chicago and Minneapolis. The agency's GRAS notification pathway governs novel lipid architecture approvals, creating pre-market bottlenecks for structured fat developers. Corn processing clusters in Iowa and Illinois supply feedstock for commodity-grade starch replacers serving domestic baked goods manufacturers.
Germany
EFSA-enforced EU-wide fat composition standards accelerate ingredient substitution among Bavarian and North Rhine-Westphalian dairy cooperatives. The European Food Safety Authority's nutrient profiling criteria reshape acceptable thresholds for front-of-pack labeling claims. Cologne and Frankfurt host technical service teams from major ingredient houses embedding directly in client pilot facilities for bakery reformulation programs.
France
Dairy processors in Brittany and the Rhône-Alpes region deploy protein-based fat replacers to meet clean-label positioning targets in yogurt and cheese applications. ANSM oversees novel food assessments alongside EFSA harmonized standards. Paris-based food technology clusters drive specification intensity for emulsion stability under high-shear processing conditions.
India
FSSAI's evolving standards on fat content claims create procurement urgency among Mumbai and Ahmedabad processed food manufacturers. The Food Safety and Standards Authority of India mandates trans fat limits that redirect demand toward carbohydrate-based replacers. Gujarat's specialty starch production facilities expand capacity to serve domestic bakery and snack reformulation programs.
Japan
Tokyo-Osaka food manufacturers integrate enzymatic interesterification technologies to eliminate residual trans fats from margarine and shortening portfolios. METI guidelines on functional food labeling influence clean-label positioning strategies. Kansai-region ingredient distributors concentrate procurement influence for gum-based systems serving premium dressing and sauce segments.
Fat Substitutes Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology ownership and technical service capabilities. The supplier base fragments between global oilseed processors with captive feedstock security and specialized ingredient houses with taste-modulation expertise. Three archetypes dominate: integrated agribusiness conglomerates controlling upstream raw material supply, application-focused technology developers with embedded formulation support, and regional specialists serving single-country regulatory pathways. Competitive moves concentrate on co-development contract capture and enzymatic processing capacity expansion.
Among integrated agribusiness conglomerates, Cargill Incorporated and Archer Daniels Midland Company exemplify feedstock-secured positioning through oilseed processing networks. Kerry Group PLC represents the application-technology archetype with taste-modulation capabilities. These three entities anchor the competitive structure by spanning commodity-grade supply and premium formulation services.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Kerry Group PLC |
| Tate & Lyle PLC |
| Ingredion Incorporated |
| FMC Corporation |
| DuPont de Nemours Inc. |
| Koninklijke DSM N.V. |
| CP Kelco U.S. Inc. |
| Others |
Value Network & Pricing Analysis
Family-owned Midwestern corn wet-milling specialists anchor commodity-grade starch replacer supply, their concentrated ownership enabling disciplined capacity utilization that buffers spot-price volatility even as enzyme and protein microparticulation developers extract premiums through captive technical service relationships.
Pricing Analysis
Yield-based pricing anchors fat substitute procurement contracts, with food manufacturers paying premiums tied to finished-product sensory acceptance rates rather than input volumes. Three-tier pricing structure across premium, standard, and economy levels separates taste-modulation-enabled protein systems from commodity modified starches and unbranded gum replacers. Cost compression in commodity carbohydrate tiers is intensifying because soybean oil feedstock volatility transmits downstream through lipid analog producers. Mid-sized bakery manufacturers prove most price-sensitive, while multinational dairy processors absorb premium protein-based systems to defend clean-label positioning.
Supply Chain Analysis
Regional distribution centers in Chicago, Rotterdam, and Singapore anchor hub-and-spoke patterns for powder-format starch replacers, with liquid protein concentrates requiring cold-chain spokes that limit radius economics. Supply concentrates in the United States, Germany, and India for modified amylopectin; enzymatic interesterification capacity clusters in the Netherlands and Japan. Feedstock dependence on Iowa and Illinois corn processing, coupled with Bavarian whey protein isolation, creates single-source vulnerability for bakery and dairy formulators. Distribution runs through ingredient houses with embedded technical service teams rather than commodity distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fat substitutes market reads as a cost-of-compliance story where FDA GRAS notification timelines and EFSA novel food assessments erect regulatory moats that favor incumbent players with dedicated toxicology and exposure study capabilities.
For Market Incumbents: Hedge against protein-based replacer commoditization by locking multi-year co-development contracts with dairy processors facing steepest reformulation curves under EU-wide fat composition standards. Backward integration into specialty enzyme production secures margin capture as enzymatic interesterification displaces legacy hydrogenation capacity. Cargill and Kerry Group's technical service embedding models create switching costs that emerging entrants struggle to replicate. For New Entrants and Emerging Players: Mid-sized Indian processed food manufacturers represent an underserved buyer archetype where FSSAI's evolving trans fat limits create first-mover advantage for clean-label carbohydrate replacer suppliers establishing local production. Direct-to-manufacturer digital platforms bypass traditional distributor volume minimums that previously locked out smaller developers. Gujarat's expanding specialty starch capacity offers co-manufacturing partnerships as a go-to-market angle without greenfield investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor application-focused technology developers with taste-modulation IP in Germany and France where EFSA nutrient profiling enforcement accelerates client formulation lock-in. Long-term viability hinges on enzymatic processing capacity ownership converging with precision fermentation-derived lipid structures. Watch for FDA GRAS notification backlog clearance as an inflection signal for novel lipid architecture commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Capacity Expansion | Retrofitting interesterification lines captures zero-trans fat demand from margarine manufacturers under FDA labeling pressure. |
| Co-Development Contract Capture | Embedding technical service teams in client pilot facilities creates formulation lock-in for Kerry Group and Tate & Lyle. |
| Precision Fermentation Lipid Convergence | Cell-cultured fat hybridization opens premium meat alternative pathways beyond plant-based analog limitations. |
| Regional Distribution Center Establishment | Cold-chain liquid concentrate hubs in dairy clusters reduce freight economics penalties for protein microparticulate suppliers. |
| Clean-Label Certification Investment | Non-GMO and organic amylopectin processing secures price premiums from German bakery manufacturers under EFSA front-of-pack rules. |
Research Methodology
Trade databases, regulatory filing repositories, and food industry association publications formed the secondary backbone, cross-referenced against primary interviews with ingredient procurement directors, dairy reformulation technologists, bakery R&D leads, and enzymatic processing engineers. Bottom-up volume estimates from application-level consumption patterns converged with top-down value assessments across product type and end-user segments.
Historical trendline analysis of modified starch and protein microparticulate shipment patterns informed projection frameworks across the analysis window, with segmentation modeling by product type, end user, application, and form. CAGRs derived from weighted average of demand elasticity coefficients and regulatory enforcement intensity indicators, incorporating enzyme supplier capacity expansion timelines and FSSAI compliance deadline schedules as industry-specific inputs.
Revisions become necessary when FDA GRAS notification standards tighten, EFSA novel food assessment timelines extend, or soybean oil price volatility exceeds historical bands. Forecasts reflect documented assumptions around regulatory enforcement consistency and feedstock cost transmission mechanisms. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Single Cell Oil Market
Alternative Food Sources
Insect Protein Market
Alternative Food Sources
Soy Leghemoglobin Market
Alternative Food Sources
Asia-Pacific Meat Substitutes Market
Alternative Food Sources
Upcycled Food Products Market
Alternative Food Sources
Low Calorie Rice Market
Alternative Food Sources
Flour Substitutes Market
Alternative Food Sources
Egg Replacers Market
Alternative Food Sources
Global Algal Oil Market
Alternative Food Sources
Microalgae Based Products Market
Alternative Food Sources
Dunaliella Salina Market
Alternative Food Sources
Seitan Market
Alternative Food Sources
Vegan Sashimi Market
Alternative Food Sources
Edible Packaging Market
Alternative Food Sources
South American Algae Protein Market
Alternative Food Sources
Precision Fermentation Market