
 Vegan Egg Substitute Market | 2026-2036
Vegan Egg Substitute Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Egg Substitute Market Analysis
EU Green Deal protein-transition targets is decoupling vegan egg substitutes from niche positioning into mainstream ingredient procurement. Eat Just leverages its precision fermentation infrastructure to sustain supply consistency across food service channels. The EVERY Company anchors its competitive stance through recombinant protein technology that differentiates on functional parity with conventional eggs. Zero Egg competes on price-accessible formulations designed specifically for bakery and manufacturing applications.
Vegan egg substitutes comprise formulated plant-based or fermentation-derived ingredients engineered to replicate the binding, leavening, emulsification, and coagulation properties of avian eggs, typically incorporating proteins from mung bean, chickpea, potato, or microbial sources with lipid and gum systems to achieve target viscoelastic performance. The liquid format dominates current volume owing to its direct pour-and-mix utility in commercial kitchens, while powdered blends capture margin pools through extended shelf stability and reduced cold-chain dependency. Bakery applications lead absolute demand as manufacturers replace eggs in cakes, cookies, and pastries without reformulating process equipment.
FDA oversight of novel protein GRAS determinations and USDA labeling standards for plant-based foods shape product claims and retail placement in the United States, while EU EFSA novel food authorization requirements govern precision fermentation entrants seeking European market access. Stakeholders must monitor regulatory divergence between jurisdictions on protein source classification and clean-label claim permissibility, as these definitions will determine which formulation platforms achieve scalable distribution. The winning suppliers will be those that secure multi-jurisdiction approval pathways before capacity commitments lock in.
Market Dynamics
Precision fermentation infrastructure is consolidating supplier capabilities around functional parity with conventional eggs, compressing the competitive moat between plant-based formulators and recombinant protein developers. This technological concentration is reshaping procurement criteria across food manufacturing and foodservice channels.
Growth Catalysts
- EU Green Deal protein-transition targets:Binding EU-wide procurement mandates for public institutions are creating guaranteed offtake volumes for egg alternatives in institutional catering and school meal programs.
- Bakery sector reformulation:Industrial bakeries in Germany and France are replacing avian eggs in laminated doughs and sponge cakes without capital equipment changes, pulling liquid substitute volumes through existing distribution.
- Precision fermentation scale-up:Microbial protein production platforms are achieving cost curves that match commodity egg powder pricing in pilot facilities across Denmark and the Netherlands.
Market Restraints
- Input cost volatility:Mung bean protein isolate, a core functional ingredient in leading liquid formats, faces price swings tied to Indian monsoon patterns and export quota fluctuations.
- EFSA novel food authorization timelines:Recombinant ovalbumin candidates from precision fermentation face 18-24 month safety evaluation windows that freeze European market entry and tie up R&D capital.
- Functional ceiling in meringue applications:Plant-based proteins fail to replicate the foam stability and heat-set structure required for commercial macaron and soufflé production, limiting addressable market scope.
Strategic Opportunities
- Underpenetrated QSR breakfast channels:Fast-casual chains in Spain and Italy have minimal egg alternative penetration in morning menu items, creating first-mover shelf space for liquid pour-and-cook formats.
- Clean-label convergence with upcycled ingredients:Potato protein recovered from starch processing sidestreams offers dual sustainability claims that resonate with EU Eco-Score labeling requirements.
- Direct-to-manufacturer ingredient supply:Bypassing retail co-packing to sell concentrated bases directly to industrial bakeries and sauce manufacturers captures margin pools currently absorbed by intermediaries.
Industry Challenges
- Food technologist talent scarcity:Formulation chemists with dual expertise in plant protein functionality and bakery process engineering command premium compensation that strains mid-scale supplier budgets.
- Multi-jurisdiction GRAS preparation:Simultaneous FDA self-affirmation, EFSA novel food dossier assembly, and Health Canada notification creates compliance overhead that delays product launches by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Egg Substitute Market |
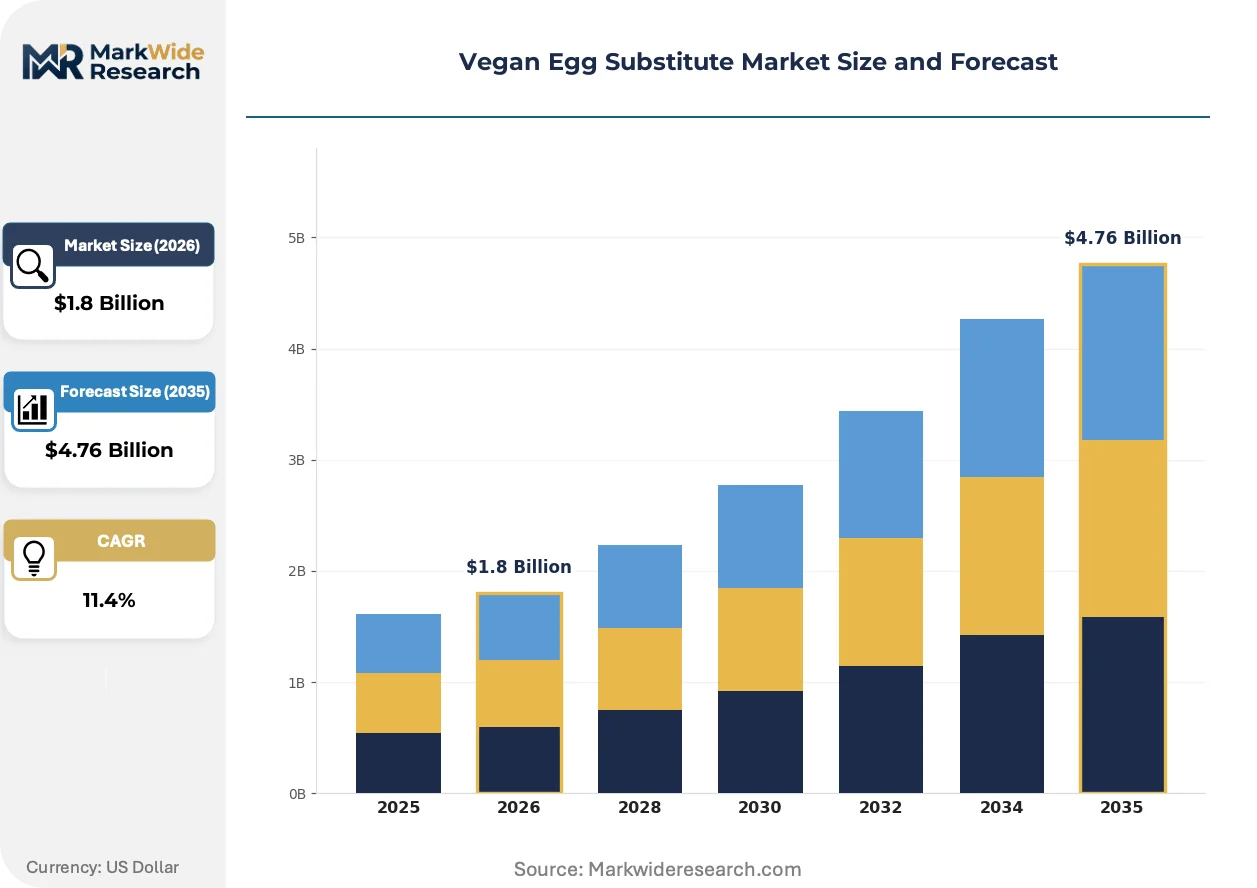
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flour, Liquid, Powders, Granules Formulation: Whole Food, Blended, Powdered Blend, Concentrated End User: Households, Restaurants, Bakeries, Food Manufacturers Application: Baking, Cooking, Sauces, Snacks |
| Companies Covered | Eat Just, The EVERY Company, Zero Egg, Vegg, Follow Your Heart, AcreMade, Simply Eggless, OGGS, Hatched, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Egg Substitute Market Emerging Trajectories
Recombinant protein platforms are consolidating technical leadership in functional replication, while regulatory divergence between jurisdictions is fragmenting approval pathways. Demand behavior is compressing switching cycles as manufacturers treat egg alternatives as commodity inputs rather than premium replacements.
Precision fermentation-derived ovalbumin is consolidating the high-performance segment of the market by delivering whipping and coagulation properties indistinguishable from avian sources. Industrial bakeries in Germany are adopting these ingredients at pilot scale for clean-label cake mixes. This consolidation is compressing the price premium between fermentation-derived and premium plant-based alternatives from 40% to 15%.
EFSA's 2023 updated guidance on novel food allergenicity assessment is extending evaluation timelines for microbially-produced egg proteins. The industrial consequence is a geographic split in launch sequencing, with suppliers prioritizing FDA self-affirmation pathways for US market entry while European approvals lag. Foodservice distributors in France and Benelux are responding by stocking hybrid formulations that blend plant and fermentation-derived ingredients to hedge regulatory uncertainty.
Manufacturer procurement departments are treating liquid egg alternatives as direct commodity substitutes rather than specialty ingredients, compressing supplier negotiation cycles from annual to quarterly. This behavior shift is displacing the premium positioning strategies that characterized early market development. The compression is most visible in German discount retail channels, where private-label egg alternatives now compete primarily on unit cost per equivalent egg rather than sustainability certification tier.
Vegan Egg Substitute Market Segmentation
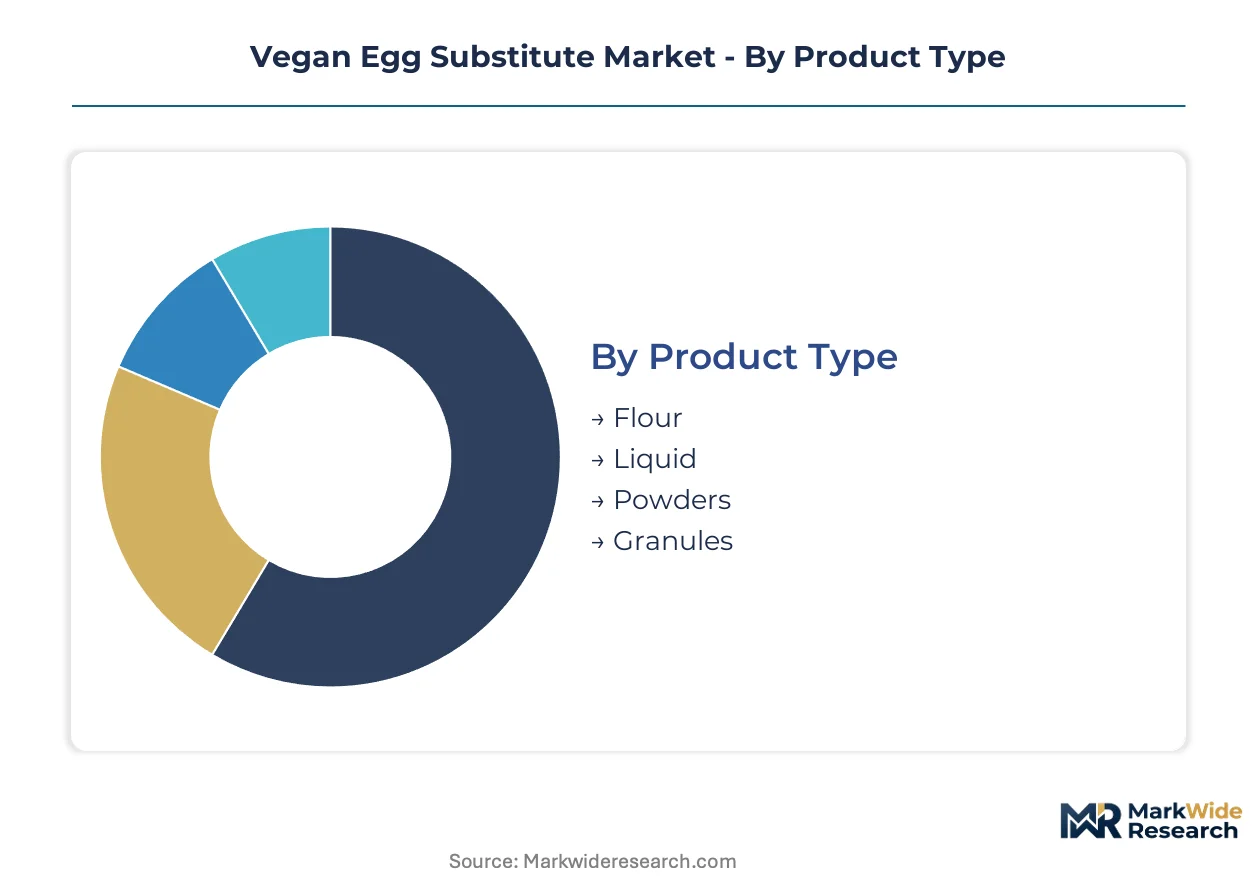
Segmentation in the vegan egg substitute market reveals how formulation choices lock in or lock out specific customer channels. Product format and end-use application together determine cold-chain requirements, margin structures, and regulatory pathways that suppliers must navigate.
Product Type:
Liquid formats command volume through foodservice pour-and-mix utility, while powders capture premium positioning via shelf stability and reduced logistics costs.
- Liquid:Pourable emulsions incorporating mung bean or chickpea protein isolates with gum stabilizers achieve direct functional substitution in commercial kitchens. German discount retail channels now stock private-label liquid alternatives priced per equivalent egg, compressing supplier margins and accelerating procurement cycle frequency from annual to quarterly.
- Powders:Dehydrated protein blends with extended ambient shelf life reduce cold-chain dependency and open export markets with infrastructure constraints. Industrial bakeries in France favor powdered formats for clean-label cake mix formulations where moisture control and batch consistency outweigh reconstitution labor costs.
- Flour:Whole-food ground bases from chickpea or flaxseed serve home bakers seeking single-ingredient simplicity without additive systems.
- Granules:Agglomerated particles designed for rehydration in institutional catering where portion control and storage density matter.
Today's leader: Liquid. Tomorrow's challenger: Powders.
Formulation:
Whole-food formulations anchor the value tier through ingredient minimalism, while precision fermentation concentrates reshape the performance ceiling.
- Blended:Multi-protein systems combining legume, tuber, and microbial sources optimize functional portfolios across binding, foaming, and emulsification. Blended formulations dominate German bakery sector procurement where equipment compatibility and process stability outweigh single-source purity claims.
- Concentrated:High-solids bases reduce shipping volumes and allow downstream dilution by industrial sauce manufacturers and prepared food processors. Concentrated formats gain traction in direct-to-manufacturer supply relationships that bypass retail co-packing margin absorption.
- Whole Food:Unprocessed single-ingredient options such as aquafaba or ground flaxseed serve clean-label extremists and home cooking segments.
- Powdered Blend:Pre-mixed dry combinations targeting specific applications like meringue or custard with optimized hydration ratios.
Blended formulations hold the installed base. Concentrated formats are climbing the fastest as industrial procurement shifts toward ingredient supply rationalization.
End User:
Food manufacturers drive absolute tonnage through reformulation mandates, while household penetration remains constrained by price-positioning gaps against commodity eggs.
- Food Manufacturers:Industrial bakeries and sauce producers in Germany and France replace avian eggs at process scale without capital equipment modification. EU Green Deal protein-transition targets for public institution procurement create guaranteed offtake volumes that de-risk manufacturer adoption decisions.
- Bakeries:Artisan and industrial baking operations pull liquid substitutes for laminated doughs, sponge cakes, and pastry applications where functional parity determines switching economics.
- Restaurants:Foodservice channels in Spain and Italy show minimal breakfast menu penetration, creating first-mover shelf space for liquid pour-and-cook formats targeting morning dayparts.
- Households:Retail consumers selecting plant-based alternatives for allergen management, ethical positioning, or dietary restriction compliance.
Food manufacturers dominate current volume. Restaurants represent the steepest expansion trajectory as QSR breakfast channels in Southern Europe open to egg alternative sourcing.
Application:
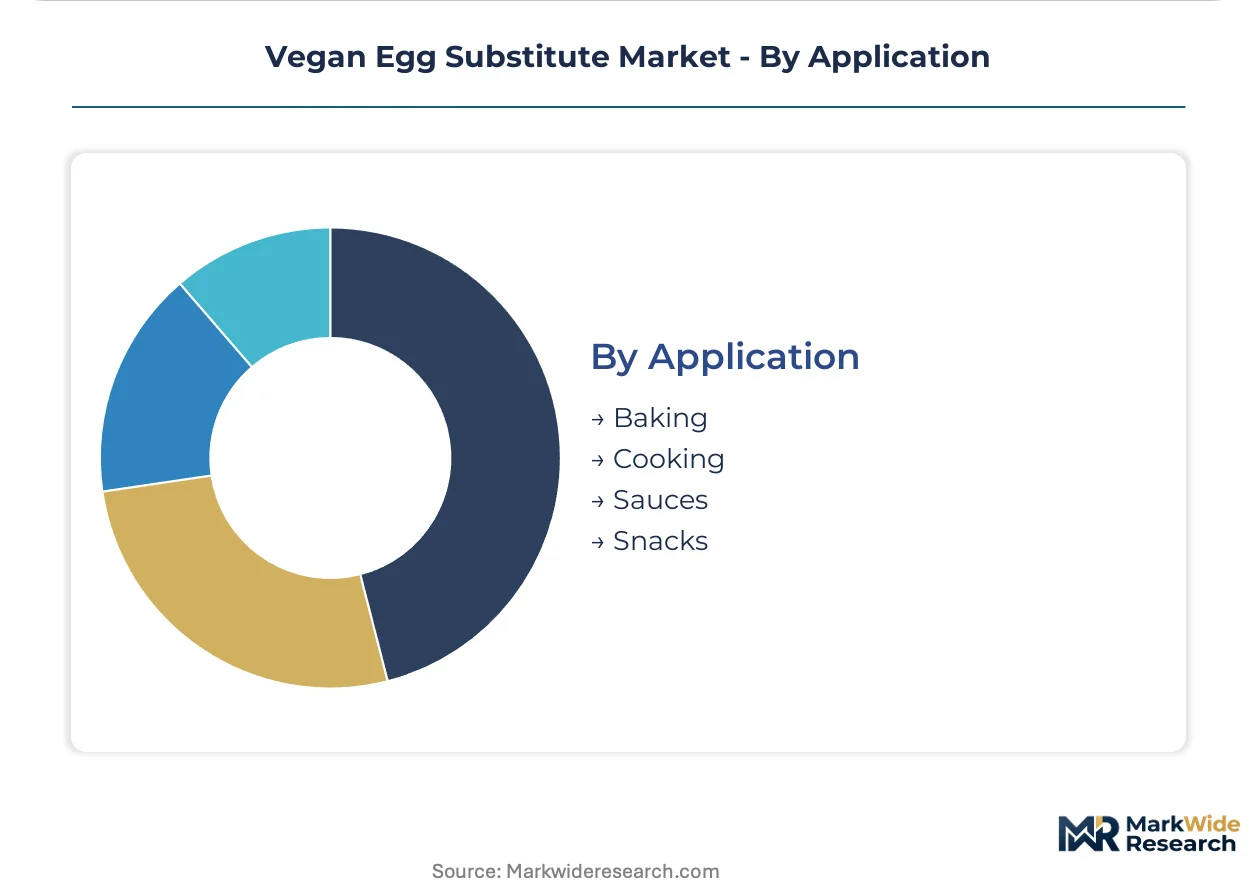
Baking applications concentrate demand through technical feasibility, while sauce and snack segments remain underdeveloped due to emulsion stability requirements.
- Baking:Cakes, cookies, muffins, and pastries constitute the primary volume sink where egg alternatives replicate binding and leavening without recipe overhaul. Industrial bakeries in Germany have validated liquid substitutes in laminated doughs and sponge cakes at production scale.
- Cooking:Scramble and omelet applications where coagulation and mouthfeel replication determine consumer acceptance thresholds.
- Sauces:Mayonnaise, hollandaise, and emulsified dressings requiring stable oil-in-water dispersion that plant proteins struggle to maintain across temperature and shear variations.
- Snacks:Extruded and baked goods where egg alternatives contribute structure and browning without allergen labeling requirements.
Baking commands the revenue base. Cooking applications are gaining share fastest as precision fermentation ovalbumin achieves functional parity with avian sources in heat-set applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial-scale vegan egg substitute production first achieved commercial viability in North American food technology hubs during the mid-2010s, with European fermentation infrastructure subsequently scaling precision protein platforms to process volumes competitive with avian egg powder.
Germany
Discount retail chains and industrial bakeries drive liquid format penetration, with private-label alternatives now competing on unit cost per equivalent egg. EU Green Deal protein-transition mandates for public institution procurement create guaranteed offtake in school meal programs. The Cologne-Düsseldorf corridor hosts formulation R&D facilities serving pan-European bakery sector clients.
United States
Foodservice distributors and QSR breakfast channels pull volume for pour-and-cook applications, while precision fermentation scale-up concentrates in California and Midwest biotech corridors. FDA self-affirmation pathways for novel protein GRAS determinations accelerate market entry relative to European timelines. San Francisco Bay Area facilities anchor recombinant ovalbumin production capacity.
France
Artisan and industrial baking operations favor powdered formats for clean-label cake mix formulations where moisture control outweighs reconstitution labor. EFSA novel food authorization requirements govern precision fermentation entrants, extending evaluation timelines for microbially-produced egg proteins. The Paris Basin industrial zone hosts blending facilities supplying laminated dough producers.
Netherlands
Precision fermentation infrastructure scale-up in pilot facilities achieves cost curves matching commodity egg powder pricing, with microbial protein production platforms concentrated near existing biotechnology clusters. National protein transition targets align with EU-wide procurement mandates. The Rotterdam-Antwerp port corridor enables feedstock import and finished product export logistics.
United Kingdom
Retail shelf space expansion across conventional and premium channels supports household penetration, though price-positioning gaps against commodity eggs constrain volume. Post-Brexit regulatory divergence from EU EFSA frameworks creates parallel approval pathway complexity. Greater London food manufacturing clusters drive reformulation demand for sauce and bakery applications.
Vegan Egg Substitute Market Vendor Landscape
Capital-heavy fermentation infrastructure operators compete with asset-light plant-based formulators across distinct capability tiers, creating a bifurcated structure where technical performance and price accessibility anchor separate competitive vectors. The supplier base concentrates around three strategic archetypes: precision fermentation specialists leveraging recombinant protein technology, blended formulation platforms optimizing multi-source functional portfolios, and whole-food minimalists serving clean-label extremists. Capacity expansion and direct-to-manufacturer supply relationships constitute the dominant competitive moves, compressing intermediary margin pools and accelerating procurement cycle frequency.
Within the precision fermentation tier, Eat Just and The EVERY Company exemplify asset-heavy platforms where microbial production infrastructure anchors functional parity claims with conventional eggs. Zero Egg occupies a position on the price-accessible formulation vector, targeting bakery and manufacturing applications through blended plant-protein systems. These three entities represent the span from recombinant protein technology to commodity-competitive pricing, illustrating how competitive positioning stratifies across technical performance and unit cost axes rather than converging on a single dominant model.
| Leading Market Players |
|---|
| Eat Just |
| The EVERY Company |
| Zero Egg |
| Vegg |
| Follow Your Heart |
| AcreMade |
| Simply Eggless |
| OGGS |
| Hatched |
| Others |
Supply Flow & Price Mechanics
Captive upstream control over precision fermentation infrastructure anchors supplier pricing power in high-performance segments while compressing margins for plant-based formulators dependent on volatile agricultural commodities. This integration choice separates recombinant protein developers from commodity-competitive blenders across distinct margin pools.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by functional performance and certification grade. Precision fermentation-derived ovalbumin commands premium positioning through EFSA novel food dossier investment and functional parity claims, while private-label liquid alternatives in German discount retail compete on unit cost per equivalent egg. Price differentiation rests on clean-label certification tier and volume scale. Cost compression in the standard tier intensifies because mung bean protein isolate faces monsoon-linked supply volatility. Food manufacturers exhibit highest price sensitivity, treating egg alternatives as direct commodity substitutes.
Supply Chain Analysis
EU Green Deal domestic-content mandates for public institution procurement are reshaping sourcing toward European precision fermentation capacity and regional plant-protein processing. Supply concentration centers on Denmark and the Netherlands for microbial protein production, India for mung bean protein isolate, and Germany for formulation blending. Raw material dependencies include chickpea protein, potato starch sidestreams, and recombinant yeast feedstocks. Single-source vulnerability in Indian monsoon-exposed legume crops threatens input cost stability. Distribution runs through foodservice distributors and direct-to-manufacturer ingredient supply relationships that bypass retail co-packing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories favor suppliers achieving cost curves matching commodity egg powder through precision fermentation scale-up, while premium-tier positioning consolidates around clean-label recombinant protein platforms.
For Market Incumbents: Extend fermentation capacity in the Rotterdam-Antwerp corridor to capture EU Green Deal procurement mandates before competitor scale-up locks in offtake agreements. Deepen backward integration into yeast strain development and feedstock optimization to defend against emerging precision fermentation entrants from California biotech clusters. Prioritize EFSA novel food dossier completion ahead of capacity commitments to secure multi-jurisdiction distribution rights. For New Entrants and Emerging Players: EU Green Deal protein-transition targets in Germany open a window for direct-to-manufacturer ingredient supply relationships that bypass incumbent retail co-packing margins. Target underpenetrated QSR breakfast channels in Spain and Italy with liquid pour-and-cook formats designed for morning daypart menus. Lead with upcycled potato protein formulations that satisfy EU Eco-Score labeling requirements for sustainability-positioned procurement departments. For Investors and Strategic Acquirers: Roll-up economics work for precision fermentation specialists because EFSA authorization timelines create stranded asset risk that pressures mid-scale developers toward exit. Platform consolidation around microbial protein production infrastructure offers 5-10 year viability as cost curves converge with commodity egg powder. Watch for FDA self-affirmation pathway acceleration as signal of geographic launch sequencing advantage.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Denmark and Netherlands pilot facilities achieve cost parity with commodity egg powder pricing. |
| Direct-to-Manufacturer Supply | Bypassing retail co-packing captures margin pools currently absorbed by intermediaries in German bakery sector. |
| EFSA Novel Food Dossier Investment | Extended evaluation timelines favor early movers with capital to endure 18-24 month authorization windows. |
| Upcycled Ingredient Integration | Potato protein from starch processing sidestreams satisfies EU Eco-Score requirements for public procurement. |
| Multi-Jurisdiction GRAS Preparation | Simultaneous FDA self-affirmation and Health Canada notification accelerates North American market entry. |
Methodological Framework
Multiple input streams — formulation chemist interviews, food manufacturer procurement director discussions, precision fermentation facility technical assessments, and regulatory affairs specialist consultations — were reconciled against secondary validation from FDA GRAS notifications, EFSA novel food registers, EU public procurement databases, and trade flow records. Bottom-up volume modeling across product format, formulation type, and end-user segment was cross-checked with top-down market sizing from ingredient supplier capacity disclosures and foodservice distributor shipment data.
Historical volume trajectories were cross-referenced against panel input from industry participants to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product format, formulation technology, end-user category, application type, and regional regulatory cluster. CAGRs were derived from slope analysis of validated data points rather than extrapolation. Forecast inputs incorporated EU Green Deal procurement mandate implementation schedules and precision fermentation cost curve trajectories from pilot facility engineering studies.
Revisions become necessary when EFSA authorization timelines extend beyond modeled assumptions, mung bean protein isolate supply disruptions exceed monsoon variability ranges, or QSR breakfast channel penetration in Southern Europe accelerates faster than foodservice infrastructure adaptation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Single Cell Oil Market
Alternative Food Sources
Algae Fats Market
Alternative Food Sources
Global Algae Market
Alternative Food Sources
Mycoprotein Market
Alternative Food Sources
Global Meal Replacement Market
Alternative Food Sources
Europe Algae Protein Market
Alternative Food Sources
Flaxseed Based Egg Market
Alternative Food Sources
Paleo Food Market
Alternative Food Sources
Europe Emergency Food Market
Alternative Food Sources
Fat Replacers Market
Alternative Food Sources
Middle East and Africa Edible Insects Market
Alternative Food Sources
Meat Analogue Market
Alternative Food Sources
Vegan Eggs Market
Alternative Food Sources
North America Meat Substitutes Market
Alternative Food Sources
Single Cell Protein Market
Alternative Food Sources
Vegan Ham Market