
 Gluten Substitute Market | 2026-2036
Gluten Substitute Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten Substitute Market Analytics
Enzymatic modification of plant proteins is reshaping how manufacturers replicate gluten's viscoelastic network in baked goods. Cargill leverages its North American grain processing infrastructure to supply modified starches at industrial scale. DSM anchors its position through fermentation-derived hydrocolloids that improve dough extensibility. Ingredion competes across multiple substitute categories with tapioca and rice-derived solutions.
Gluten substitutes comprise functional ingredients engineered to mimic the protein matrix of wheat gluten through viscoelastic binding, moisture retention, and gas-holding capacity in leavened systems. These materials typically incorporate hydrocolloids such as xanthan or guar gum at 0.5-2% inclusion rates, combined with modified starches or legume flours, to restore structural integrity in formulations lacking native gluten. Starches currently lead the product type landscape due to their cost position and clean-label acceptance among industrial bakeries. Binders represent the fastest-expanding category as precision-formulation demands intensify in frozen dough and par-baked segments.
The FDA enforces gluten-free labeling standards below 20 ppm, compelling manufacturers to validate substitute purity across supply chains. The USDA's National Organic Program shapes ingredient sourcing for premium-positioned alternatives. EFSA's novel food assessments in Europe create entry barriers for emerging protein sources. Stakeholders must monitor how evolving thresholds for gluten detection and emerging genome-edited crops alter formulation economics and competitive moats.
Market Dynamics
Enzymatic modification of plant proteins is collapsing the performance gap between wheat gluten and alternative binders, forcing ingredient suppliers to recalibrate R&D budgets toward precision fermentation and extrusion technologies that replicate viscoelastic networks at industrial scale.
Growth Catalysts
- Clean-label mandates:EFSA's novel food assessments in Europe are accelerating validated ingredient pipelines for hydrocolloid suppliers seeking premium positioning in reformulated bakery applications.
- Artisan bakery demand:Germany's traditional baking sector is driving volume for starch-hydrocolloid blends as craft producers adapt heritage recipes to gluten-free specifications without texture degradation.
- Fermentation platforms:Microbial-derived proteins from precision fermentation are expanding functional property libraries beyond conventional plant extraction methods.
Market Restraints
- Input cost volatility:Tapioca starch prices fluctuate with Thai cassava harvest cycles, compressing margins for manufacturers dependent on Southeast Asian supply chains.
- Technical ceiling:Current hydrocolloid systems fail to replicate gluten's extensibility in high-hydration artisan breads above 80% water content.
- Regulatory fragmentation:Divergent gluten thresholds between FDA's 20 ppm standard and Codex Alimentarius guidelines complicate export qualification for multi-territory producers.
Strategic Opportunities
- Underpenetrated geographies:India's FSSAI is finalizing gluten-free labeling rules, creating first-mover advantages for suppliers establishing local formulation partnerships ahead of enforcement.
- Regulatory tailwinds:The EU Green Deal's bioeconomy incentives are channeling capital toward upcycled protein streams from brewing and oilseed processing side streams.
- Channel innovation:Direct-to-bakery technical service models are displacing traditional distributor networks in North American industrial baking corridors.
Industry Challenges
- Formulation talent scarcity:Rheology specialists with gluten-free systems expertise command premium compensation, constraining mid-tier ingredient houses.
- Certification timelines:Organic certification under USDA's National Organic Program requires 18-24 month supply chain audits, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten Substitute Market |
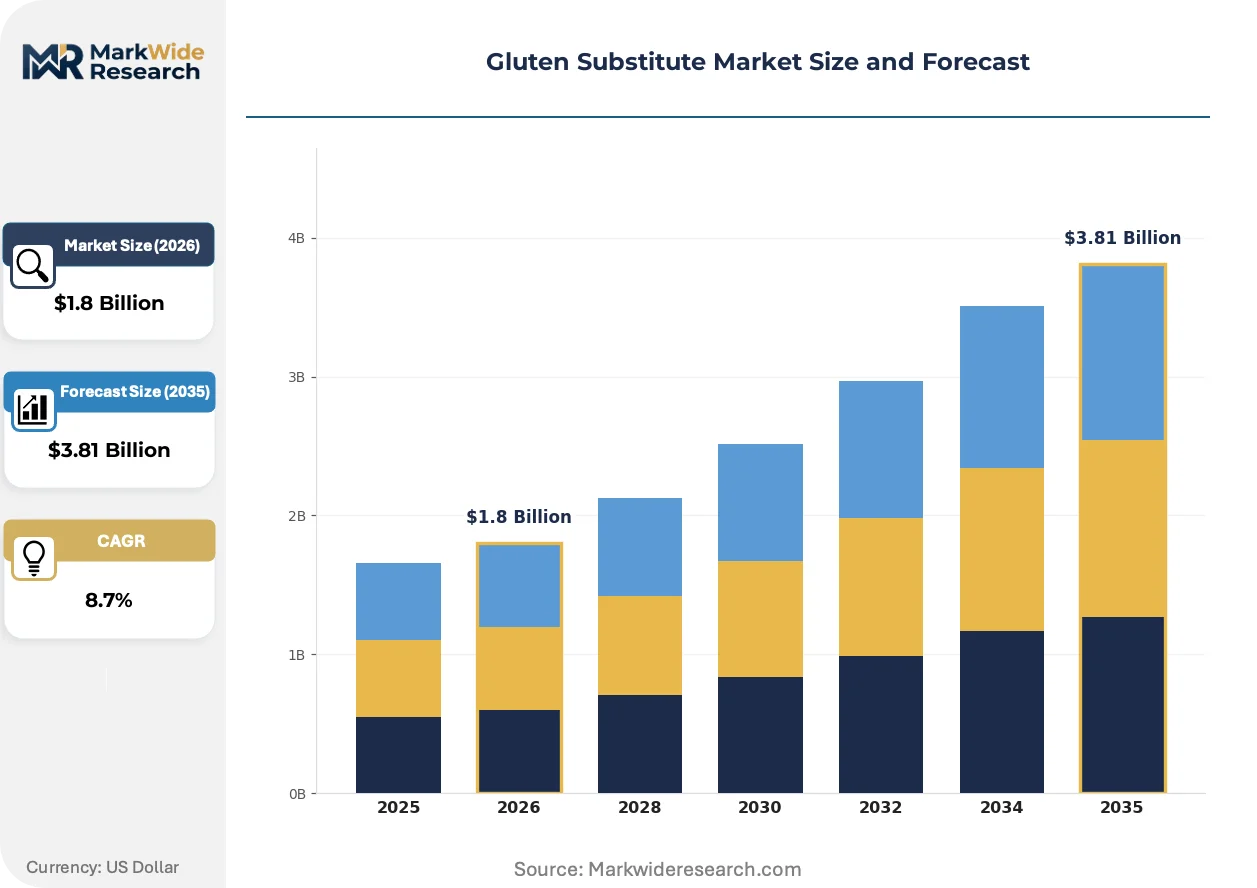
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flours, Starches, Binders, Fiber Form: Powder, Liquid, Granular, Sheet Application: Baking, Snacks, Sauces, Pastas End User: Food Industry, Restaurants, Households, Bakeries |
| Companies Covered | Cargill, ADM, Ingredion, DSM, CP Kelco, DowDuPont, Fufeng Group, Deosen Biochemical, Jungbunzlauer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten Substitute Market Evolving Landscape
Protein engineering and regulatory harmonization are converging to redefine acceptable performance thresholds for wheat alternatives in leavened systems. Three developments warrant particular attention from formulation teams and procurement functions.
Extrusion-cooked pulse proteins are collapsing the cost-performance tradeoff that has historically confined legume flours to premium niche applications. Industrial bakeries in the United States are adopting these materials at inclusion rates of 15-25% in pan bread formulations, compressing the price differential between conventional and gluten-free product lines to under fifteen percent at shelf.
REACH registration requirements for novel hydrocolloids are tightening purity documentation obligations for European suppliers. Manufacturers must now submit full toxicological dossiers for modified starches derived from non-traditional feedstocks, extending time-to-market by twelve to eighteen months and favoring incumbent players with established regulatory affairs infrastructure.
Buyer concentration among North American bakery chains is consolidating technical specification authority into centralized procurement functions. These organizations are unbundling ingredient sourcing from technical service contracts, forcing suppliers to compete on formulation support separately from commodity pricing in contract negotiations across Midwest production facilities.
Gluten Substitute Market Segmentation
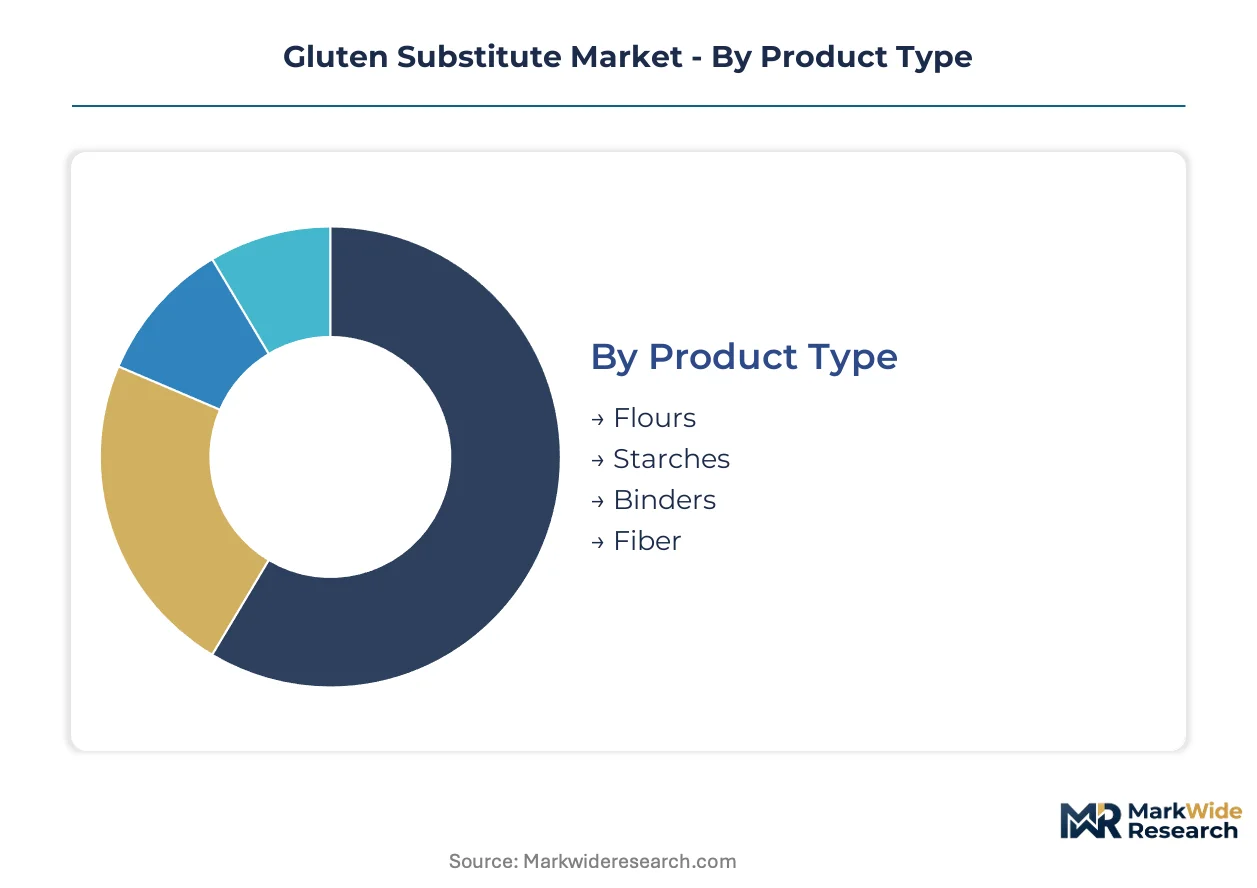
Gluten substitute procurement cycles vary dramatically by ingredient stability and reformulation complexity. Manufacturers must align inventory strategies with segment-specific turnover patterns while balancing technical service investments against margin profiles.
Product Type:
Starches turn inventory fastest due to commodity pricing volatility and bulk bakery contracts, while binders sit longest as specialized formulations require extended qualification cycles.
- Starches:Modified tapioca and rice-derived starches constitute the volume foundation, typically blended at 15-40% inclusion rates to restore crumb structure. Industrial bakeries in the United States specify these materials in annual tenders with price-adjustment clauses tied to Thai cassava harvests.
- Binders:Hydrocolloid systems incorporating xanthan, guar, or locust bean gum replicate gluten's viscoelastic network at 0.5-2% dosages. Frozen dough manufacturers in Germany drive specification intensity as par-baked formats demand extended freeze-thaw stability without syneresis.
- Flours:Legume, nut, and ancient grain flours provide protein fortification and flavor differentiation in premium positioning.
- Fiber:Resistant starches and soluble fiber fractions enhance nutritional claims while contributing limited structural function.
Starches anchors the volume base while binders gains share at the steepest rate.
Form:
Powdered formats dominate cost-sensitive applications where hydration control is managed at the bakery level, while liquid concentrates command premium positioning in continuous-process manufacturing.
- Powder:Spray-dried and agglomerated powders offer extended shelf stability and flexible dosing across batch sizes. Artisan bakers in Germany prefer this format for heritage recipe adaptation.
- Liquid:Pre-hydrated hydrocolloid suspensions eliminate dust handling and ensure complete dispersion in high-speed mixing environments. North American industrial bakery chains specify these for automated dosing systems.
- Granular:Intermediate particle sizes bridge dissolution speed and storage stability for mid-scale manufacturers.
- Sheet:Pre-formed edible films and wafers serve niche applications in layered desserts and enrobed snacks.
Powder commands the installed base while liquid formats are expanding most quickly in automated production corridors.
Application:
Baking applications consume the highest absolute volumes with quarterly reformulation cycles, whereas sauce applications turn slowly as emulsion stability requirements lock specifications for multi-year periods.
- Baking:Bread, cake, and pastry formulations demand the most complex substitute portfolios to replicate gluten's gas-holding and crumb-setting functions. FDA's 20 ppm gluten-free labeling threshold forces validation protocols that extend procurement timelines.
- Snacks:Extruded and sheeted snack matrices tolerate higher inclusion rates of pulse flours due to lower moisture content and different structural failure modes. Clean-label positioning drives rapid ingredient rotation.
- Sauces:Viscosity modification and freeze-thaw stability dominate specification criteria with limited tolerance for texture variation.
- Pastas:Sheeted and extruded noodle formats require specialized starch-protein interactions to prevent cooking loss and surface stickiness.
Baking anchors the volume base while snacks gains share at the steepest rate.
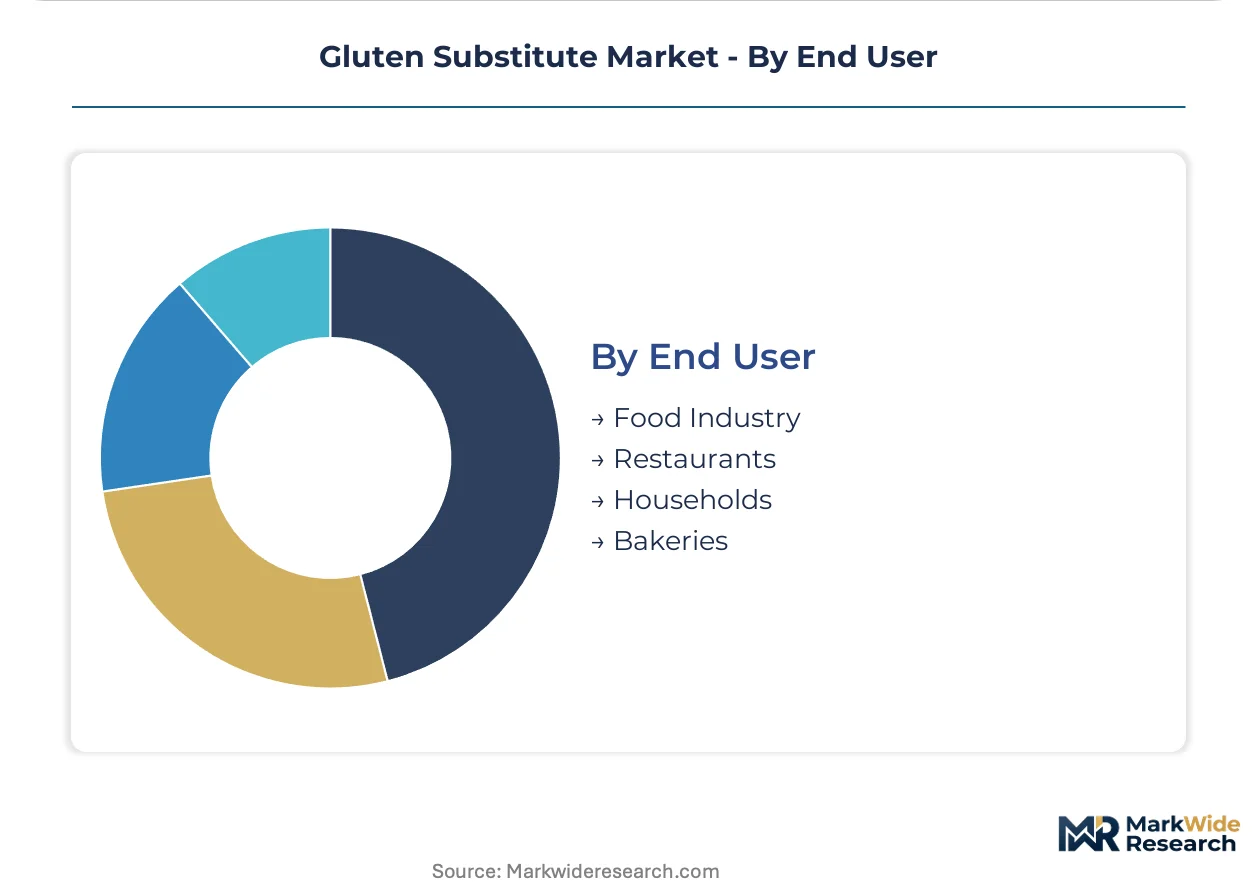
End User:
Food industry procurement operates on 12-18 month contract cycles with technical service bundling, while household purchasing through retail channels turns fastest as consumer trial drives brand switching.
- Food Industry:CPG manufacturers and co-packers specify substitutes through centralized procurement functions with unbundled technical service contracts. EFSA novel food assessments constrain European formulation pipelines.
- Bakeries:Industrial and artisan producers represent the most specification-intensive segment, with Germany's traditional craft sector driving hydrocolloid innovation.
- Restaurants:Foodservice distributors consolidate demand across regional chains with limited in-house formulation capability.
- Households:Retail consumers purchase pre-blended substitutes through grocery and e-commerce channels with minimal technical support expectations.
Food industry anchors the volume base while bakeries gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial bakery chains in the United States centralize procurement decisions, while artisan craft bakers in Germany drive hydrocolloid innovation through heritage recipe reformulation. These buyer archetypes shape regional demand patterns and regulatory compliance requirements across national markets.
United States
FDA's 20 ppm gluten-free labeling threshold compels manufacturers to validate substitute purity across extended supply chains. Industrial bakery chains in the Midwest specify modified starches through centralized procurement functions with unbundled technical service contracts. Chicago and Minneapolis production corridors concentrate frozen dough manufacturing for par-baked distribution.
Germany
Artisan bakers in Bavaria and Baden-Württemberg reformulate traditional recipes with hydrocolloid and starch blends to preserve texture integrity. EFSA novel food assessments create entry barriers for emerging protein sources entering European formulation pipelines. Munich's craft baking sector anchors specification intensity for freeze-thaw stable binders.
India
FSSAI's pending gluten-free labeling rules create first-mover positioning for suppliers establishing local formulation partnerships ahead of enforcement. Maharashtra and Gujarat industrial zones attract ingredient houses building technical service capabilities for domestic bakery expansion. Mumbai-based co-packers drive demand for cost-optimized starch blends in emerging gluten-free product lines.
China
SAMR's food safety standards for gluten-free claims tighten domestic manufacturing compliance requirements. Zhengzhou and Jinan production clusters concentrate modified starch processing for regional bakery supply. Shandong Province's cassava processing infrastructure supports tapioca-derived substitute manufacturing at industrial scale.
Brazil
ANVISA's food allergen labeling regulations shape import qualification for hydrocolloid suppliers entering South American markets. São Paulo state's industrial baking corridor concentrates demand for clean-label starch alternatives in packaged bread formulations. Campinas and Sorocaba production zones anchor technical service deployment for regional formulation support.
Gluten Substitute Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Consolidated grain processors leverage North American infrastructure to supply modified starches at commodity scale, while fermentation-derived specialists anchor premium positioning through hydrocolloid innovation. Strategic moves concentrate on backward integration into raw material sourcing and geographic expansion through technical service partnerships.
Within the channel-controlling tier, Cargill and ADM exemplify grain-processing incumbents with captive supply chain infrastructure. DSM occupies a position among fermentation-derived specialists leveraging microbial platforms for functional ingredient development. Ingredion sits within the diversified starch specialist archetype competing across multiple substitute categories with tapioca and rice-derived solutions.
| Leading Market Players |
|---|
| Cargill |
| ADM |
| Ingredion |
| DSM |
| CP Kelco |
| DowDuPont |
| Fufeng Group |
| Deosen Biochemical |
| Jungbunzlauer |
| Others |
Value Network & Pricing Analysis
Thai cassava belt freight corridors linking Bangkok port to North American industrial bakeries transmit Thai harvest volatility directly into Midwest contract renegotiations, compressing margins for tapioca-dependent suppliers while rewarding buyers with multi-source starch portfolios.
Pricing Analysis
Cost-plus contracts with Thai cassava price indexation dominate industrial bakery procurement, creating transparency that limits supplier margin expansion. Price differentiation rests on organic certification grade and freeze-thaw performance tier, with USDA National Organic Program validation commanding substantial premia over conventional grades. Pricing pressure intensifies in the standard tier as extrusion-cooked pulse proteins collapse the cost-performance gap with wheat gluten. Industrial bakery chains exhibit the highest price sensitivity due to unbundled technical service contracts, while artisan German bakers prioritize texture integrity over unit cost.
Supply Chain Analysis
Upstream cassava cultivation concentrates in Thailand, Indonesia, and Vietnam, with Shandong Province processing infrastructure providing regional tapioca starch manufacturing for Chinese bakery supply. Modified starch production draws from Thai raw material flows, fermentation-derived hydrocolloids rest on European and North American microbial platform capacity, and legume flour extrusion systems are anchored in United States and Canadian pulse-growing regions. Single-source vulnerability runs through Thai cassava harvest cycles, where drought or disease triggers rapid input cost spikes. Distribution runs through direct-to-bakery technical service models displacing traditional distributor networks in North American industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among North American industrial bakery chains that unbundle ingredient sourcing from technical service contracts, fragmenting supplier pricing authority across separate negotiation tables.
For Market Incumbents: Pre-empt margin compression from extrusion-cooked pulse proteins by accelerating backward integration into cassava processing assets in Southeast Asia and securing organic certification capacity ahead of competitor qualification cycles. Lock in multi-year offtake agreements with German artisan baking cooperatives before novel hydrocolloid entrants clear EFSA assessments. For New Entrants and Emerging Players: Establish a beachhead in India's FSSAI pre-enforcement formulation partnerships, where domestic bakery expansion outpaces local hydrocolloid technical service coverage. Target Mumbai-based co-packers with cost-optimized starch blend portfolios priced below Cargill and ADM commodity tiers, leveraging regional cassava sourcing through Shandong Province trading relationships. For Investors and Strategic Acquirers: Fermentation-derived hydrocolloid specialists with established REACH dossiers represent the most defensible acquisition archetype, given twelve-to-eighteen month registration barriers for novel modified starches. Monitor EFSA novel food approval timelines as the critical inflection signal—accelerated clearances for microbial proteins would compress premium positioning windows for incumbent suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cassava Processing | Captive Thai raw material supply insulates margins against harvest volatility and indexation risk. |
| Precision Fermentation Platform Expansion | DSM and microbial specialists extend functional property libraries beyond conventional plant extraction limits. |
| Direct-to-Bakery Technical Service Deployment | Chicago and Minneapolis corridor concentration enables specification influence at centralized procurement functions. |
| Organic Certification Pipeline Investment | USDA National Organic Program validation opens premium positioning in clean-label reformulation segments. |
| EFSA Novel Food Assessment Preparation | Full toxicological dossiers for emerging proteins secure twelve-to-eighteen month first-mover advantages in Europe. |
Research Methodology
The analysis maps starch, binder, flour, and fiber substitute categories, each validated through formulation scientists at industrial bakeries, procurement directors at North American bakery chains, rheology specialists at ingredient houses, and regulatory affairs managers navigating FDA and EFSA compliance. Primary interview insights triangulate against secondary sources including FDA gluten-free labeling guidance documents, EFSA novel food assessment registers, Thai Ministry of Commerce cassava export statistics, and USDA National Organic Program certification databases. Bottom-up volume builds from application-specific inclusion rates and bakery production data converge with top-down market sizing from trade flow analysis.
Assumptions regarding FDA enforcement continuity, Thai cassava yield stability, and EFSA assessment timeline norms were held fixed across the projection horizon, while scenarios varied pricing indexation clauses, organic certification adoption curves, and precision fermentation scale-up rates. Segmentation modeling incorporates product type stability profiles, form-based dissolution requirements, application reformulation cycle lengths, and end-user procurement centralization patterns. CAGRs derive from segment-level volume trajectories weighted by price tier mix, with enzyme modification adoption curves and frozen dough segment growth serving as key industry-specific demand inputs.
Stress conditions across Thai drought frequency, EFSA backlog accumulation, and industrial bakery chain consolidation velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including regulatory threshold revisions, genome-edited crop commercialization, and hydrocolloid system performance ceilings in high-hydration applications. Cross-checking against customs trade data for modified starch and hydrocolloid import flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Fat Replacers Market
Alternative Food Sources
Fish Oil Alternatives Market
Alternative Food Sources
Plant-Based Compound Feed Market
Alternative Food Sources
Europe Duckweed Protein Market
Alternative Food Sources
Vegetable Waste Products Market
Alternative Food Sources
Konjac Market
Alternative Food Sources
Global Alternative Protein Market
Alternative Food Sources
Products from Food Waste Market
Alternative Food Sources
North America Insect Protein Market
Alternative Food Sources
Europe Algae Protein Market
Alternative Food Sources
North America Meat Substitutes Market
Alternative Food Sources
Synthetic Food Market
Alternative Food Sources
North America Edible Insects Market
Alternative Food Sources
Dunaliella Salina Market
Alternative Food Sources
North America Meal Products Replacement Market
Alternative Food Sources
Global Konjac Glucomannan Market