
 Single Cell Protein Market | 2026-2036
Single Cell Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Single Cell Protein Market Intelligence
Fermentation-to-formulation integration is narrowing the cost gap between single cell protein and conventional feed ingredients. Koninklijke DSM N.V. leverages its industrial biotechnology heritage to control upstream fermentation assets. Calysta Inc. anchors its position through methane-to-protein platforms tailored for aquaculture nutrition. Lallemand Inc. specializes in yeast-derived SCP formulations for ruminant and monogastric feed applications.
Single cell protein denotes microbial biomass cultivated via controlled fermentation of carbohydrates, hydrocarbons, or gases, typically containing 50-80% crude protein on a dry weight basis with favorable amino acid profiles for animal and human nutrition. Yeast-derived SCP currently occupies the largest production volume share due to established downstream processing infrastructure and GRAS status in multiple jurisdictions. Bacteria-based SCP, particularly methanotroph and hydrogenotroph strains, represents the fastest-expanding product type as energy feedstock diversification reduces input cost volatility. Animal feed commands the dominant end-user segment, though nutraceutical applications for SCP isolates are gaining traction among ingredient suppliers seeking protein fortification alternatives.
EFSA novel food assessments, FDA GRAS notifications, and EU Feed Hygiene Regulation 183/2005 collectively determine market access timelines and product labeling requirements for SCP manufacturers. REACH compliance for process chemicals and substrate traceability standards further shape production economics and geographic sourcing decisions. Stakeholders must monitor regulatory divergence between jurisdictions on genetically modified versus non-GMO strain classifications, as this distinction will determine facility location strategies and capital allocation priorities.
Market Dynamics
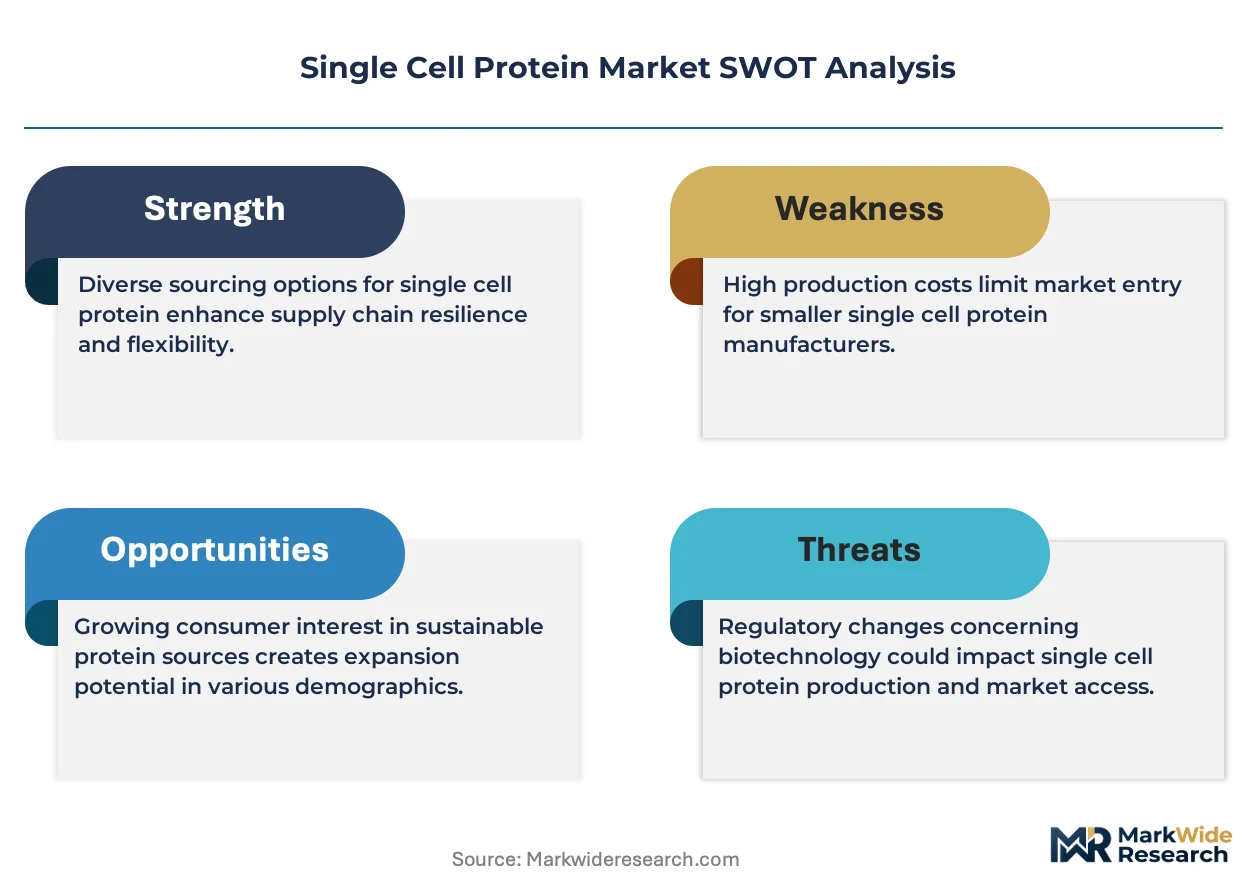
Fermentation scale-up economics and feedstock diversification are compressing unit production costs for microbial biomass, narrowing the competitive gap against fishmeal and soy protein concentrates in formulated feeds.
Growth Catalysts
- EFSA novel food pathways:Accelerated safety assessment protocols under EU Regulation 2015/2283 are compressing time-to-market for bacterial biomass ingredients in human and animal nutrition applications.
- Methane-to-protein platforms:Industrial biotechnology hubs in Denmark are deploying captured biogas and natural gas feedstocks to decouple protein production from agricultural land use constraints.
- Aquaculture formulation demand:Salmon and shrimp feed producers are expanding SCP procurement contracts to reduce exposure to Peruvian anchovy fishery volatility and South American soybean price swings.
Market Restraints
- Input cost volatility:Natural gas and methanol price fluctuations directly impact methanotroph fermentation economics, compressing margin buffers for gas-to-protein operators.
- Downstream processing concentration:Spray-drying and cell-rupture equipment supply concentrates among German and Swiss engineering firms, creating capex bottlenecks for new market entrants.
- Regulatory fragmentation:Divergent GMO strain classifications between FDA, EFSA, and China's SAMR force facility-specific compliance architectures that inflate capital deployment timelines.
Strategic Opportunities
- Pet food premiumization:North American and European companion animal brands are sourcing yeast-derived SCP for hypoallergenic protein positioning in veterinary-recommended formulations.
- Hydrogenotroph expansion:Electrolysis-coupled fermentation using green hydrogen feedstocks opens carbon-negative protein production pathways aligned with EU Green Deal industrial decarbonization mandates.
- Direct-to-feedmill distribution:Bypassing traditional ingredient traders through bulk silo installations at aquaculture and poultry integration sites captures margin previously allocated to distribution intermediaries.
Industry Challenges
- Bioprocess engineering talent scarcity:Industrial fermentation scale-up expertise concentrates among veterans of pharmaceutical and enzyme manufacturing, constraining operational expansion for protein-focused ventures.
- GRAS notification timelines:FDA substantiation requirements for new microbial strains extend 18-24 months, delaying revenue recognition for novel bacterial biomass categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Cell Protein Market |
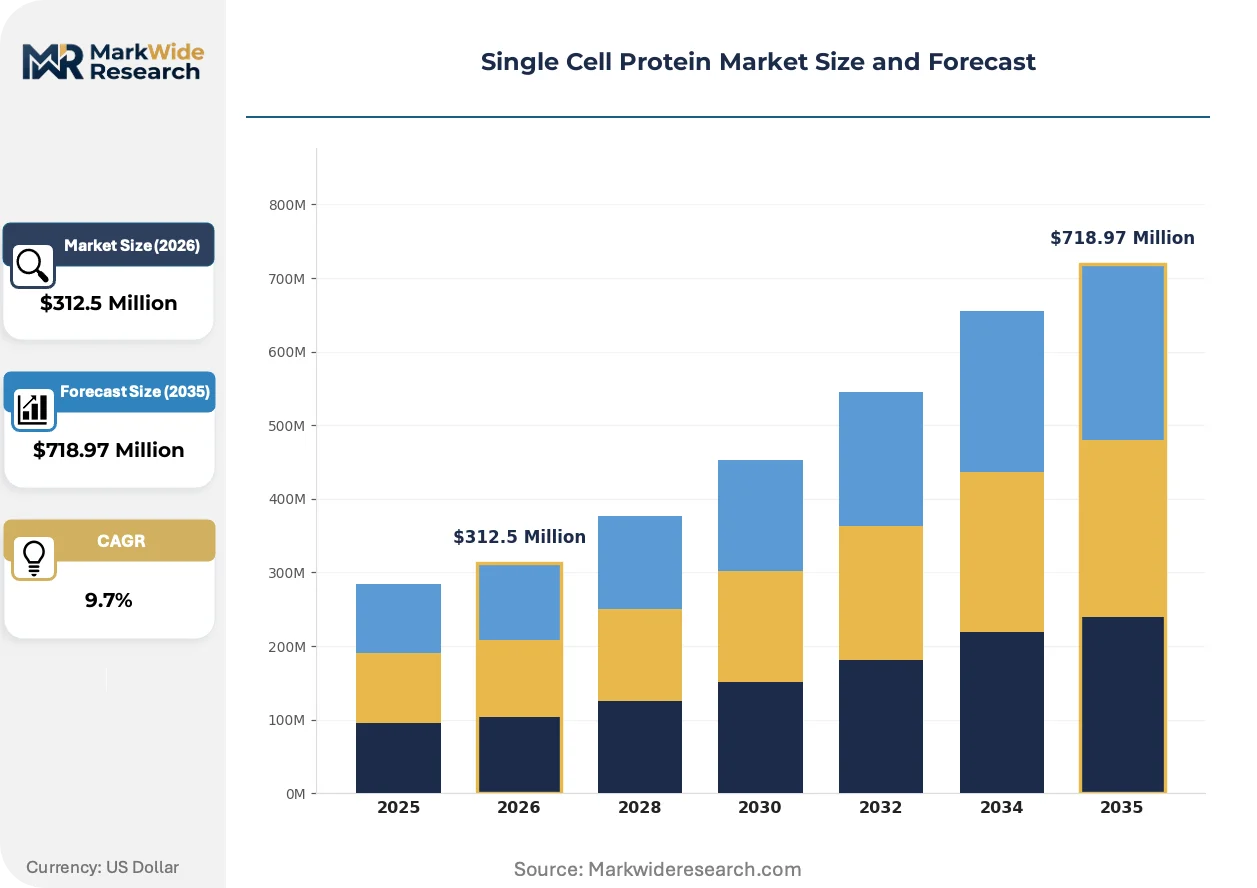
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $718.97 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacteria, Yeast, Fungi, Algae End User: Food Industry, Animal Feed, Nutraceuticals, Biofuels Form: Powder, Liquid, Granules, Pellets Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Koninklijke DSM N.V., Lesaffre, Cargill Incorporated, Calysta Inc., Angel Yeast Co. Ltd., Archer Daniels Midland Company, Lallemand Inc., Unibio A/S, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Cell Protein Market Strategic Shifts & Innovations
Continuous fermentation and real-time metabolite monitoring are displacing batch processing paradigms, enabling titer consistency that meets specification-grade requirements for precision animal nutrition.
Gas fermentation using methanotroph and hydrogenotroph strains is collapsing the capital intensity gap between biological and chemical protein synthesis. Aquafeed formulators in Norway and Chile are qualifying these ingredients at commercial inclusion rates. The technology is collapsing legacy assumptions that microbial biomass cannot achieve cost parity with commodity protein meals.
REACH compliance for process chemicals and substrate traceability standards under EU Feed Hygiene Regulation 183/2005 are reshaping sourcing decisions for fermentation media. Manufacturers must document supply chain provenance for nitrogen and mineral inputs. Yeast-derived SCP processors with integrated substrate production are capturing preference share among risk-averse European feed compounders.
Buyer consolidation among salmon farming integrators is compressing supplier qualification cycles and shifting procurement toward multi-year offtake agreements with volume commitments. Norwegian and Scottish aquaculture operators are demanding specification-grade consistency that matches fishmeal digestibility coefficients. This behavioral shift favors fermentation operators with analytical capabilities and captive quality assurance infrastructure over commodity traders.
Single Cell Protein Market Segmentation
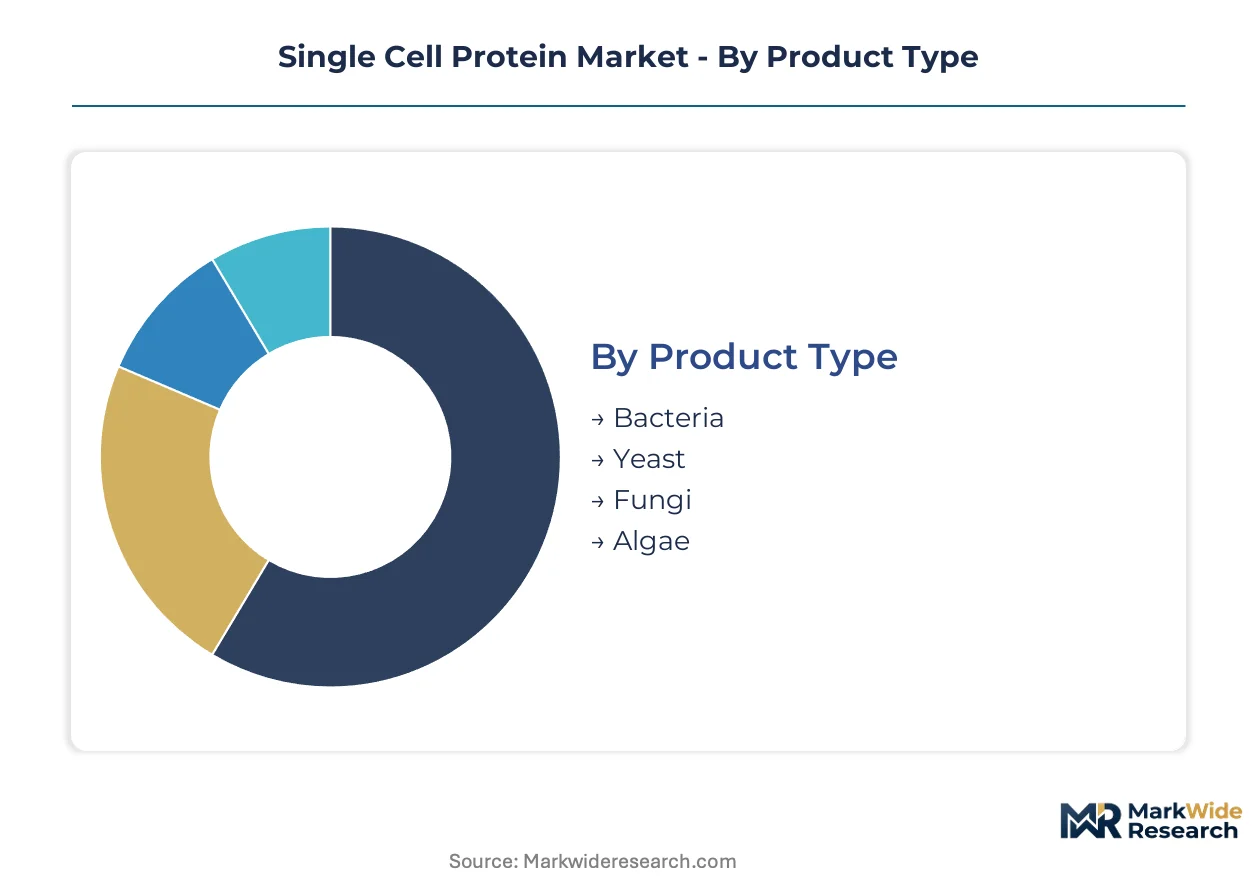
Single cell protein markets fragment across biological source, application intensity, and physical handling requirements. Each segmentation axis reveals distinct margin structures and regulatory exposure profiles that determine facility investment decisions.
Product Type:
Mature fermentation platforms coexist with emerging gas-based bioprocesses, creating a technology gradient from established downstream infrastructure to frontier scale-up economics.
- Yeast:Saccharomyces cerevisiae and Kluyveromyces marxianus strains deliver 50-60% protein content with complete amino acid profiles and established GRAS status across FDA and EFSA jurisdictions. Feed compounders in Denmark and the Netherlands specify yeast-derived SCP for salmonid diets requiring consistent digestibility coefficients. The segment leverages existing brewery and ethanol facility infrastructure for capital-efficient capacity expansion.
- Bacteria:Methanotroph and hydrogenotroph platforms achieve 70-80% crude protein with favorable methionine-lysine ratios for poultry and aquaculture nutrition. Methylococcus capsulatus fermentation using captured biogas feedstocks is scaling in Danish industrial biotechnology clusters, decoupling production from agricultural land constraints. Regulatory pathways under EFSA novel food assessments remain the primary velocity limiter for human-grade applications.
- Fungi:Filamentous fungal biomass including Fusarium venenatum offers textured protein structures suitable for meat analog applications. The segment occupies niche positioning between feed-grade commodity volumes and premium food ingredient specifications.
- Algae:Spirulina and Chlorella strains provide protein alongside omega-3 fatty acids and pigment compounds, commanding nutraceutical premiums that offset higher cultivation costs relative to heterotrophic fermentation.
Yeast handles the majority of throughput; bacteria is the fastest mover on share.
End User:
Application intensity varies from bulk commodity substitution to precision formulation with specification-grade consistency requirements.
- Animal Feed:Aquaculture integrators in Norway and Chile specify SCP inclusion rates of 10-15% in salmon and shrimp diets, displacing fishmeal volumes exposed to Peruvian anchovy fishery volatility. Poultry and swine nutritionists evaluate bacterial biomass for amino acid density advantages over soybean meal.
- Food Industry:EFSA novel food authorizations under EU Regulation 2015/2283 govern human-grade SCP deployment, with mycoprotein from Fusarium venenatum holding established approvals. Bakeries and meat alternative manufacturers source yeast extracts for umami depth and protein fortification.
- Nutraceuticals:Algae-derived protein isolates target sports nutrition and clinical nutrition segments with combined protein-omega positioning. The segment demands organic certification and heavy metal testing protocols that filter supplier qualification.
- Biofuels:Residual microbial biomass from ethanol and biogas operations enters protein recovery pathways, though amino acid profiles and nucleic acid content limit inclusion rates in premium feed applications.
Animal feed commands the dominant volume position; nutraceuticals posts the steepest expansion trajectory on margin intensity.
Form:
Physical state determines handling infrastructure compatibility and shelf stability trade-offs across distribution distances.
- Powder:Spray-dried SCP with moisture content below 8% enables bulk silo storage and pneumatic conveying at aquaculture feed mills and poultry integration sites. The form dominates commercial procurement specifications.
- Liquid:Live yeast suspensions and fermented broths serve ruminant feed applications where fresh delivery radius constraints apply. Tanker logistics limit geographic reach to fermentation-adjacent dairy regions.
- Granules:Agglomerated particles improve flowability and reduce dust generation during feed mill handling, commanding modest premiums for compounder operational efficiency gains.
- Pellets:Compressed forms with binding agents suit specialty aquafeed and pet food extrusion processes, though heat treatment during pelleting requires protein digestibility validation.
Powder captures the bulk of commercial movement; liquid forms face radius constraints that concentrate supply adjacent to production assets.
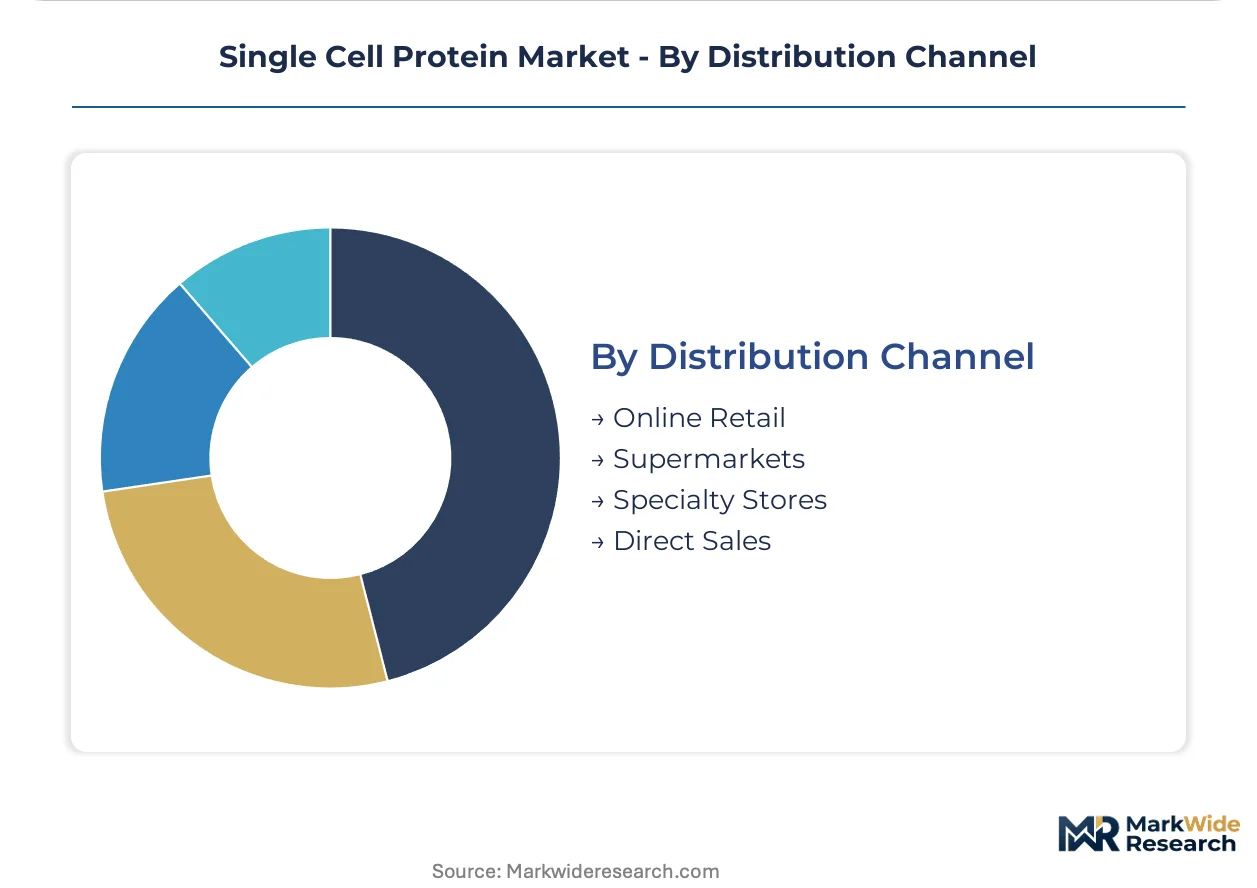
Distribution Channel:
Channel selection reflects customer scale, technical service requirements, and certification documentation intensity.
- Direct Sales:Multi-year offtake agreements with salmon farming integrators and poultry protein suppliers specify volume commitments, quality assurance protocols, and substrate traceability documentation under EU Feed Hygiene Regulation 183/2005. Technical service teams coordinate fermentation scheduling with feed mill inventory cycles.
- Specialty Stores:Human-grade SCP isolates and algae protein powders reach sports nutrition consumers through dedicated health food retail, with organic and non-GMO certifications driving shelf placement.
- Online Retail:Direct-to-consumer protein powders and supplement formulations bypass traditional ingredient trading margins, though cold chain requirements constrain liquid product availability.
- Supermarkets:Mycoprotein meat alternatives and yeast extract spreads occupy refrigerated and ambient grocery sections, with placement decisions driven by slotting fees and velocity guarantees.
Direct sales anchor the volume base; online retail is climbing fastest on consumer protein curiosity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Salmon farming integrators in Norway and aquafeed compounders in Denmark concentrate procurement authority for specification-grade single cell protein. These buyer archetypes drive regional capacity deployment and regulatory engagement strategies.
Denmark
Aquafeed formulators and industrial biotechnology clusters anchor demand for methane-to-protein platforms. EFSA novel food assessments under EU Regulation 2015/2283 accelerate safety protocols for bacterial biomass ingredients. Copenhagen and Kalundborg fermentation hubs deploy captured biogas feedstocks to decouple protein production from agricultural land constraints.
Norway
Salmon farming integrators specify SCP inclusion rates of 10-15% in feed diets to reduce fishmeal exposure. REACH compliance requirements shape substrate traceability standards for fermentation media imports. Bergen and Trondheim aquafeed R&D centers qualify bacterial biomass at commercial inclusion rates for precision nutrition.
United States
Pet food premiumization and poultry integration drive yeast-derived SCP procurement for hypoallergenic positioning. FDA GRAS notification timelines extend 18-24 months for novel microbial strains, delaying revenue recognition. Midwest fermentation facilities and California pet food innovation clusters concentrate production and formulation expertise.
Germany
Downstream processing equipment supply concentrates among engineering firms in Baden-Württemberg and Bavaria, creating capex bottlenecks for new entrants. EU Feed Hygiene Regulation 183/2005 governs substrate documentation requirements. Munich and Stuttgart industrial biotechnology centers specialize in spray-drying and cell-rupture technology for specification-grade output.
China
Aquaculture expansion and livestock protein demand drive bacterial biomass evaluation for amino acid density advantages. SAMR regulations on genetically modified strain classifications force facility-specific compliance architectures. Qingdao and Guangdong fermentation corridors scale yeast and algae platforms for domestic feed compounders.
Single Cell Protein Market Key Industry Players
Channel-controlling players compete with product-specialist players for procurement relationships with aquaculture integrators and feed compounders. The market structure consolidates around fermentation operators with captive downstream processing assets and ingredient traders with formulation technical service capabilities. Three strategic archetypes dominate: industrial biotechnology heritage firms with upstream fermentation control, gas-to-protein platform specialists with methane feedstock access, and yeast-derived formulation providers with GRAS status leverage. Competitive moves concentrate on multi-year offtake agreements with volume commitments and backward integration into substrate production.
Within the industrial biotechnology tier, Koninklijke DSM N.V. and Evonik Industries AG exemplify fermentation heritage players with upstream asset control. Among gas-to-protein specialists, Calysta Inc. occupies a position representing methane feedstock platform deployment. Lallemand Inc. anchors the yeast-derived formulation archetype with established GRAS positioning across multiple jurisdictions.
| Leading Market Players |
|---|
| Koninklijke DSM N.V. |
| Lesaffre |
| Cargill Incorporated |
| Calysta Inc. |
| Angel Yeast Co. Ltd. |
| Archer Daniels Midland Company |
| Lallemand Inc. |
| Unibio A/S |
| Evonik Industries AG |
| Others |
Cost & Logistics Intelligence
Undercapacity in Danish methanotroph fermentation facilities is tightening supplier pricing power and accelerating contract indexation to natural gas benchmarks. Buyers face compressed negotiation leverage as capacity utilization rates climb above threshold levels that trigger automatic price escalators.
Pricing Analysis
Cost-plus contracts with natural gas indexation dominate bacterial biomass procurement, linking unit prices to Henry Hub and TTF benchmarks with quarterly adjustments. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-authorized strains from feed-grade bacterial biomass and residual yeast derivatives. Pricing pressure stems from methanol feedstock volatility in hydrogenotroph platforms, squeezing margin buffers for operators without captive gas supply. Aquaculture integrators exhibit lowest price sensitivity due to fishmeal substitution economics, while biofuel residual biomass buyers face highest elasticity.
Supply Chain Analysis
Upstream feedstock sourcing concentrates in Denmark, Norway, and the Netherlands for methane and biogas capture infrastructure. Nitrogen and mineral media inputs draw from German chemical suppliers and Baltic fertilizer producers. Single-source vulnerability runs through Swiss and German spray-drying equipment manufacturers, creating capex bottlenecks for new fermentation capacity. Distribution runs through direct silo installations at aquaculture feed mills, bypassing traditional ingredient traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment creates durable barriers. EFSA novel food authorization timelines and FDA GRAS notification requirements embed switching costs that protect incumbent positions.
For Market Incumbents: Insulate margin structures through backward integration into biogas capture infrastructure and substrate production. Lock in multi-year offtake agreements with Norwegian salmon farming integrators before hydrogenotroph competitors achieve scale. Threat: Electrolysis-coupled fermentation platforms with green hydrogen feedstocks could disrupt methane-based cost structures within the analysis window. For New Entrants and Emerging Players: Southeast Asian aquaculture markets offer the most penetrable white-space opportunity, with Vietnamese and Indonesian shrimp feed compounders seeking fishmeal alternatives without established SCP supplier relationships. Target direct-to-feedmill distribution models with bulk silo installations rather than competing through commodity trading channels. Go-to-market angle: Partner with regional fermentation engineering firms to bypass German equipment supply bottlenecks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among bacterial biomass operators with EFSA novel food authorizations and multi-year aquaculture offtake agreements. Long-term viability favors platforms with feedstock flexibility across methane, hydrogen, and syngas inputs. Acquisition target archetype: Mid-scale methanotroph operators with Danish or Norwegian facility locations and pending regulatory approvals. Signal to watch: Acceleration in FDA GRAS notification submissions for novel hydrogenotroph strains indicates competitive pressure timing.| Strategic Initiative | Industry Significance |
|---|---|
| Feedstock Diversification | Dual methane-hydrogen capability insulates Calysta and Unibio from natural gas price volatility. |
| Regulatory Pre-Approval Investment | Early EFSA engagement compresses time-to-market for bacterial biomass in human nutrition applications. |
| Direct Silo Installation | Bypassing traders captures 8-12 percentage points of margin for fermentation operators with logistics capital. |
| Continuous Fermentation Retrofit | Real-time metabolite monitoring upgrades enable specification-grade consistency for Norwegian aquafeed qualification. |
| Downstream Processing Integration | Captive spray-drying capacity eliminates German engineering firm dependency and accelerates capacity deployment. |
Research Approach
Cross-validation between primary fermentation operator interviews and secondary trade flow data anchors the qualitative findings. Conversations with aquafeed formulators, bioprocess engineering directors, and EFSA regulatory consultants combined with customs records, EU Feed Hygiene Regulation enforcement reports, and SEC filings from publicly traded industrial biotechnology firms. Bottom-up capacity modeling and top-down protein substitution demand estimates triangulate volume outputs.
Calibration against historical fishmeal-soybean price spreads and fermentation facility commissioning timelines validates projection trajectories. Segmentation dimensions span biological source, end-use application intensity, physical form specifications, and regional regulatory cluster variations across the modeling period. CAGRs derive from capacity expansion announcements, offtake contract volumes, and feed formulation substitution elasticity parameters. Industry-specific inputs include biogas capture infrastructure deployment rates and EFSA novel food assessment queue lengths.
Practitioners should monitor natural gas price volatility, EFSA authorization timeline shifts, and hydrogenotroph scale-up announcements for early signals of forecast revision. Cross-checking against FAO fishmeal production statistics and aquaculture feed formulation databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Africa Protein Market
Alternative Food Sources
Artificial Meat Market
Alternative Food Sources
North America Fat Replacers Market
Alternative Food Sources
Vegan Casing Market
Alternative Food Sources
Vegan Eggs Market
Alternative Food Sources
Quinoa Protein Market
Alternative Food Sources
Asia-Pacific Algae Protein Market
Alternative Food Sources
Teff Products Market
Alternative Food Sources
North America Algae Protein Market
Alternative Food Sources
Insect Snacks Market
Alternative Food Sources
North America Meal Products Replacement Market
Alternative Food Sources
Seitan Market
Alternative Food Sources
Fish Oil Alternatives Market
Alternative Food Sources
Black Soldier Fly (BSF) Market
Alternative Food Sources
Africa Fat Replacers Market
Alternative Food Sources
Mock Meat Market