
 Vegan Ham Market | 2026-2036
Vegan Ham Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Ham Market Analytics
Aftermarket recipe development revenue is tilting from independent foodservice consultants toward in-house R&D teams at major plant-protein manufacturers. Tofurky leverages decades of seitan expertise to sustain premium positioning in North American natural retail channels. Nestlé anchors European volume through The Vegetarian Butcher brand, which dominates Dutch retail and foodservice distribution. Lightlife Foods competes in the sliced-deli segment with clean-label positioning that emphasizes short ingredient lists.
Vegan ham denotes a plant-based cured meat analogue formulated from wheat gluten, soy or pea protein isolates, and beet-derived colorants to replicate the texture, sliceability, and smoky flavor profile of conventional pork ham, typically achieving protein contents of 15-25 grams per 100-gram serving through extrusion or shear-cell processing. The product serves commercial kitchens and retail consumers seeking direct substitution in cold-cut applications without altering preparation workflows. Sliced formats lead retail velocity due to grab-and-go convenience, while blocks command higher per-unit margins in foodservice bulk procurement. Pea protein isolates are displacing soy in premium formulations as allergen-labeling requirements tighten across European and North American markets.
EU EFSA novel-food authorization pathways and USDA FSIS labeling guidelines shape ingredient disclosure standards and restrict terms like "ham" in certain member states, compelling reformulation and rebranding investments. REACH chemical safety protocols and FDA GRAS self-affirmation processes govern the acceptability of emerging binders and fermentation-derived flavor precursors. Stakeholders must monitor evolving nomenclature regulations that could force category-wide packaging overhauls and trigger consumer confusion at the point of purchase.
Market Dynamics
EU Green Deal agricultural transition subsidies are forcing plant-protein manufacturers to abandon soy-intensive formulations and rebuild supply chains around pea protein and domestic European pulse cultivation.
Growth Catalysts
- EU Green Deal subsidies:Financial incentives for protein-crop diversification accelerate domestic sourcing of yellow peas and fava beans, reducing import dependency on North American soy.
- Clean-label ingredient standards:REACH-compliant colorants and binders unlock shelf-space expansion in German and Dutch discounter chains previously closed to artificial-additive formulations.
- Shear-cell processing:This extrusion alternative achieves fibrous textures without high-energy inputs, enabling mid-scale manufacturers to enter the sliced-deli segment.
Market Restraints
- Pea protein supply concentration:Processing capacity clusters in France and northern Germany, creating bottlenecks when harvest volatility strikes the Baltic growing regions.
- Beet-derived colorant cost volatility:Sugar-sector competition for red beetroot squeezes pigment supply and inflates formulation costs during European harvest shortfalls.
- EFSA novel-food authorization timelines:Fermentation-derived flavor precursors face 18-24 month safety assessments, freezing pipeline innovation for startups lacking regulatory affairs budgets.
Strategic Opportunities
- Quick-service sandwich chains:Untapped procurement contracts with pan-European operators offer volume anchors for manufacturers achieving consistent sliceability at scale.
- Foodservice block formats:Bulk ham analogues for commercial kitchens command per-kilogram premiums over retail sliced packs while requiring simpler packaging compliance.
- EU Green Deal carbon-accounting mandates:Upcoming Scope 3 disclosure requirements favor regional pulse-protein suppliers over transatlantic soy importers.
Industry Challenges
- Extrusion technician scarcity:Shear-cell and high-moisture extrusion expertise concentrates at a handful of European research institutes, forcing manufacturers to poach talent or fund university partnerships.
- Dual-labeling compliance:USDA FSIS and EFSA divergent nomenclature rules compel parallel packaging runs, inflating inventory complexity for cross-Atlantic suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Ham Market |
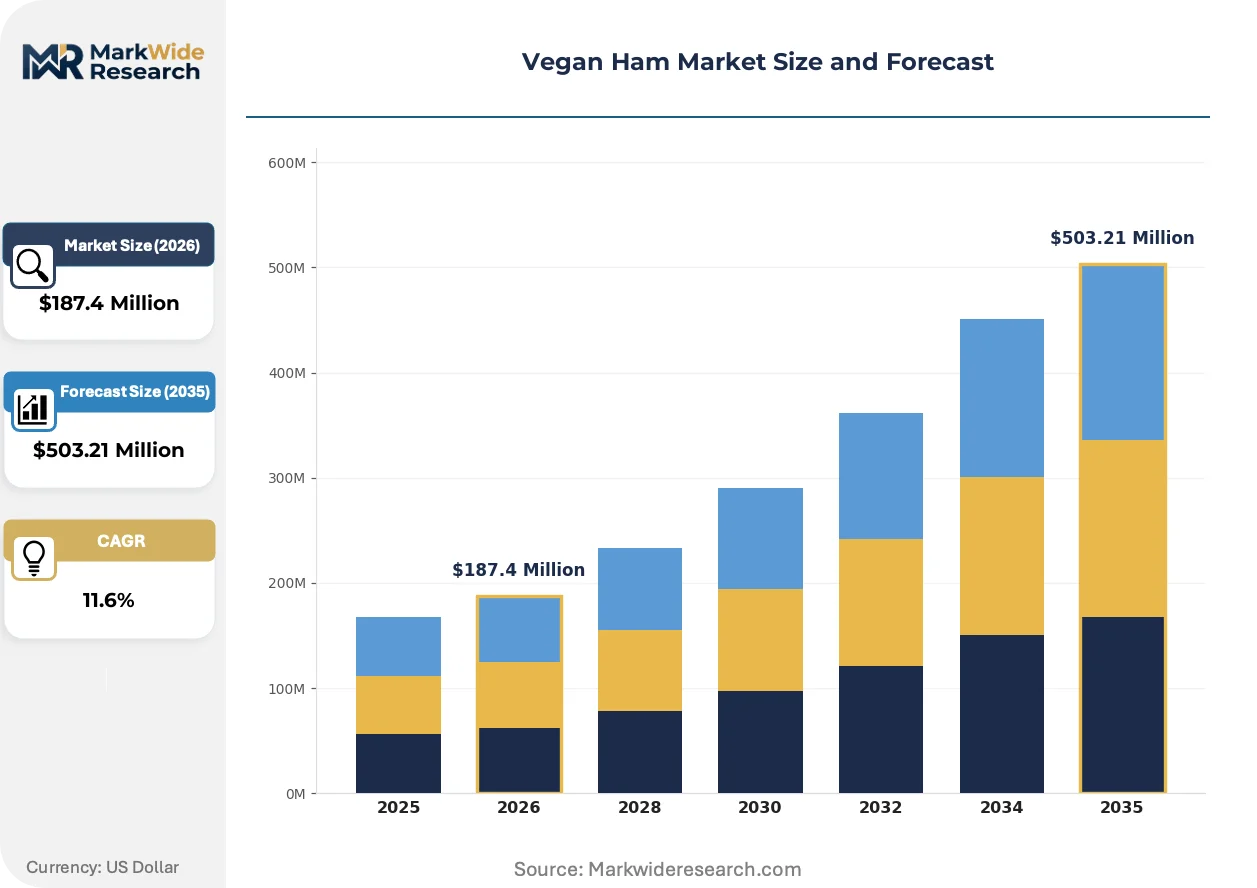
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slices, Blocks, Cured, Spreadable Material: Seitan, Tofu, Pea Protein, Soy Protein Distribution Channel: Supermarkets, Online Retail, Health Stores, Food Service Application: Sandwiches, Salads, Dishes, Snacks |
| Companies Covered | Tofurky, Lightlife Foods, Yves Veggie Cuisine, Gardein, Nestlé, The Vegetarian Butcher, Quorn Foods, Alpha Foods, Vbites Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Ham Market Evolving Landscape
Formulation science and processing hardware are converging to solve the texture-authenticity gap that has long constrained cold-cut applications, while regulatory pressure on ingredient provenance accelerates supply-chain regionalization.
Pea protein isolate technology is hybridizing with traditional wheat gluten matrices to achieve the elastic bite and slice cohesion that single-protein systems cannot deliver. German and Dutch retail buyers are specifying these hybrid formulations in private-label tenders. The resulting ingredient complexity is compressing margins for pure-play soy processors unable to retrofit extrusion lines.
REACH chemical safety protocols now mandate granular disclosure of fermentation-derived binder origins, compelling reformulation of legacy products. Manufacturers must document supply-chain provenance for enzymatically treated starches. Dutch foodservice distributors are demanding REACH-compliant certification as a procurement gate, filtering out non-European suppliers.
Retail deli counters are consolidating supplier relationships around three-contractor models that bundle vegan ham with other plant-based sliced meats. German discounters pioneered this procurement compression, and Belgian and Austrian chains are adopting identical frameworks. The shift favors manufacturers with extrusion versatility across multiple analogue categories.
Vegan Ham Market Segmentation
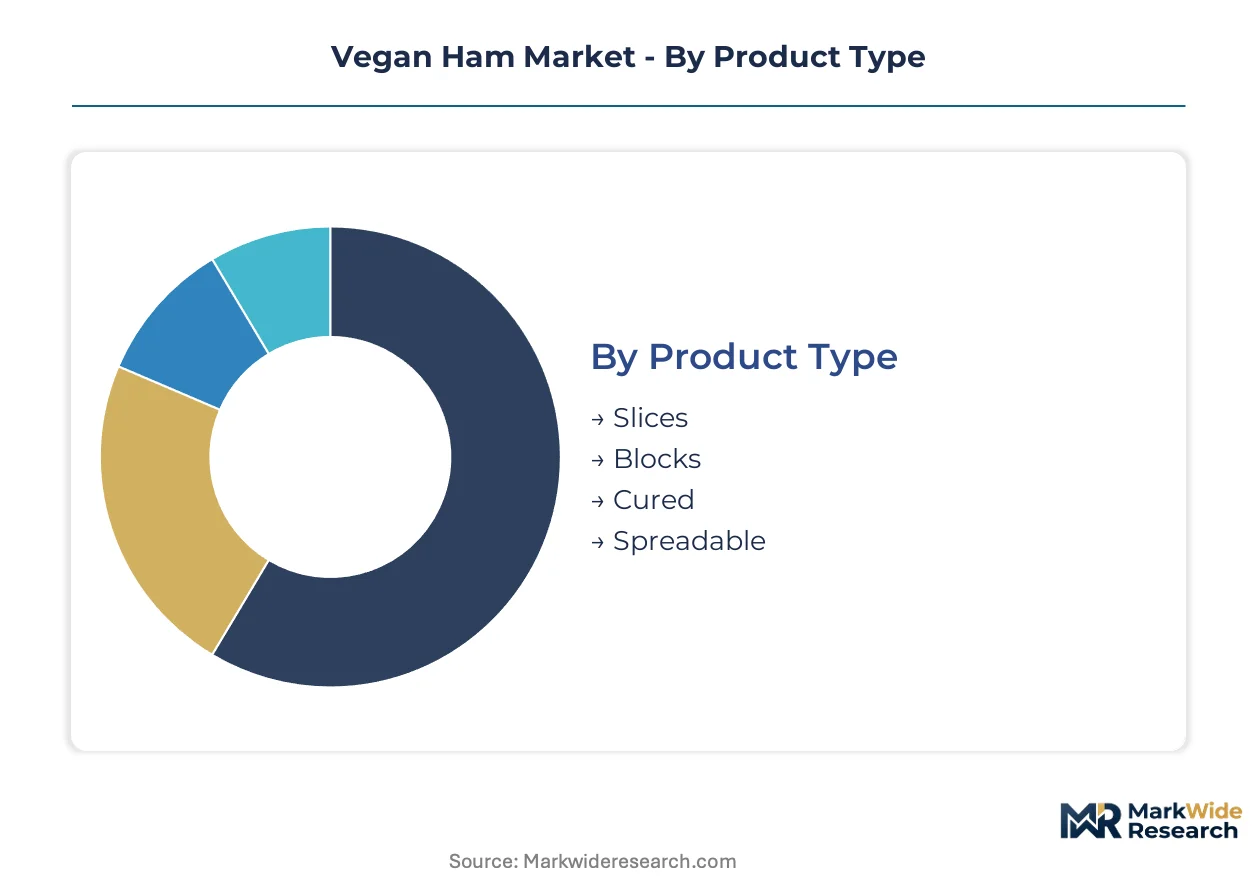
Vegan ham segmentation reveals how texture requirements and distribution economics split the market into distinct procurement channels. Each category reflects divergent technical specifications and margin structures that manufacturers must balance.
Product Type:
The use-case spectrum spans grab-and-go retail convenience to bulk commercial kitchen preparation, with format choice dictating extrusion investment and packaging compliance burdens.
- Slices:Thin-cut formats achieve 15-25 gram protein targets through high-moisture extrusion, delivering the fibrous layering essential for cold-cut sandwich applications. German and Dutch discounter chains specify precise sliceability tolerances in private-label tenders, rejecting batches with cohesion failures. Established volume favors slices; emerging adoption favors blocks.
- Blocks:Bulk formats for commercial slicing operations command per-kilogram premiums while bypassing retail packaging complexity. Foodservice distributors in the Netherlands bundle block vegan ham with other plant-based deli analogues under consolidated procurement contracts. Blocks reduce unit packaging costs by 60% versus pre-sliced retail equivalents.
- Cured:Smoked and brined variants replicate traditional preservation aesthetics for premium positioning in natural retail channels.
- Spreadable:Pâté-style formulations target charcuterie board applications with lower protein density and higher fat mimetic content.
Format selection directly determines extruder capital allocation and regulatory labeling obligations.
Material:
Protein base selection concentrates around allergen-labeling economics and EU Green Deal sourcing mandates, with hybrid matrices gaining technical preference over single-protein systems.
- Pea Protein:Isolate formulations displace soy in premium European lines as REACH-compliant clean-label positioning tightens. French and German processing clusters now dominate pea protein capacity, though Baltic harvest volatility creates intermittent supply squeezes. Pea protein carries the steepest expansion trajectory among base materials.
- Seitan:Wheat gluten matrices deliver the elastic bite and slice cohesion that single-protein systems cannot achieve alone. Tofurky's decades of seitan expertise anchor premium positioning in North American natural retail, though European formulators increasingly blend seitan with pea isolates for hybrid performance.
- Soy Protein:Legacy formulations face procurement pressure as EU agricultural transition subsidies accelerate domestic pulse cultivation over imported soy.
- Tofu:Coagulated soy curd bases serve East Asian recipe traditions and lower-price-tier applications with softer texture profiles.
Material migration is compressing margins for pure-play soy processors unable to retrofit hybrid extrusion lines.
Distribution Channel:
Channel economics separate high-velocity retail from relationship-driven foodservice procurement, with compliance requirements filtering supplier participation.
- Supermarkets:Sliced-format velocity concentrates in German discounter chains that have mainstreamed private-label vegan deli meats through aggressive pricing and prominent placement. Retail deli counters now stock plant-based ham alongside conventional offerings, with three-contractor bundling models consolidating supplier relationships.
- Food Service:Commercial kitchen procurement favors block formats with simpler packaging compliance and bulk pricing structures. Quick-service sandwich chains across Germany, the United Kingdom, and the Netherlands represent untapped volume anchors for manufacturers achieving consistent sliceability.
- Online Retail:Direct-to-consumer channels serve niche dietary segments with subscription models and refrigerated last-mile logistics.
- Health Stores:Natural retail channels prioritize clean-label positioning and short ingredient lists, rewarding seitan and fermented protein innovations.
Supermarket penetration is stabilizing; foodservice contract acquisition is accelerating.
Application:
End-use differentiation reflects preparation workflow integration, with cold-cut substitution dominating volume and hot-dish applications demanding thermal stability.
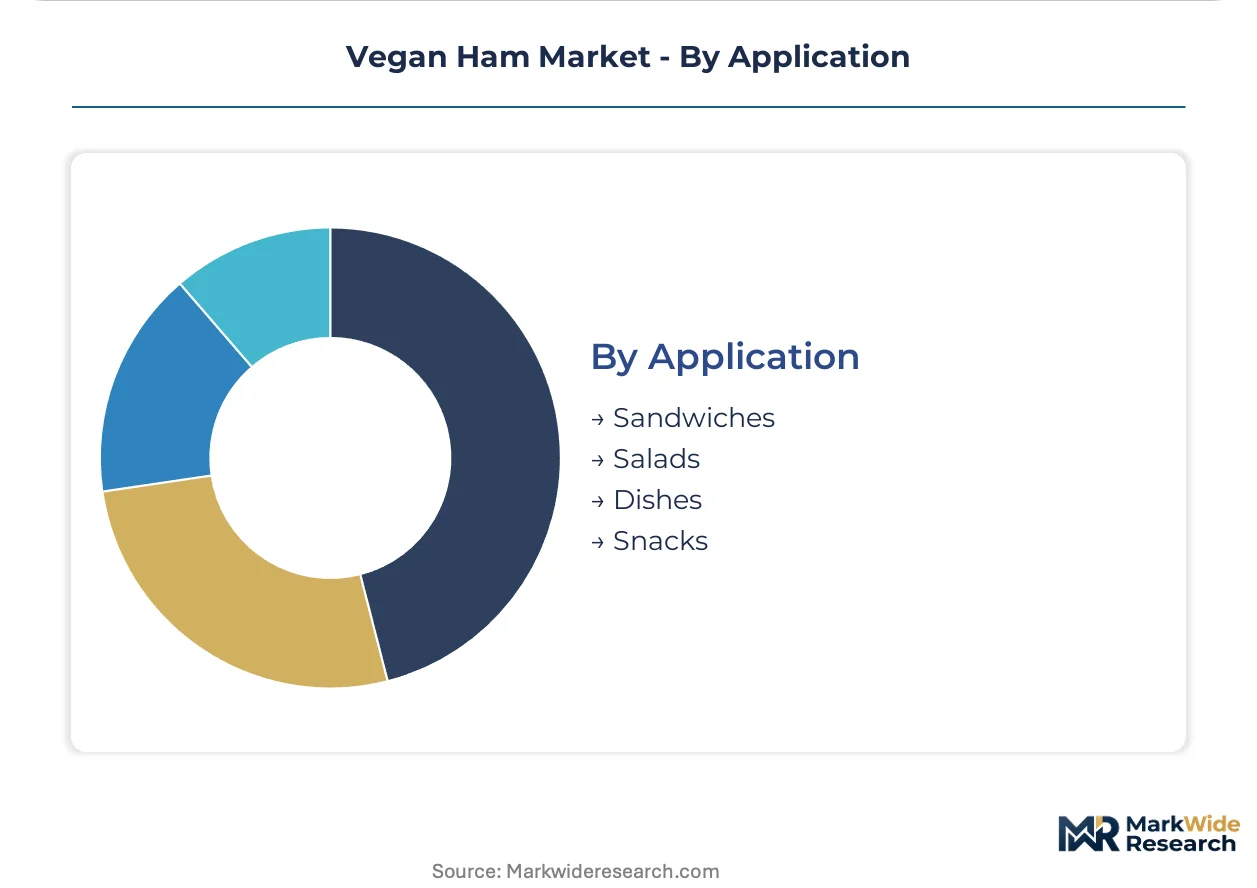
- Sandwiches:Cold-cut slicing applications command the largest volume share, requiring precise texture engineering for layer separation without crumbling. Shear-cell processing enables mid-scale manufacturers to enter this segment with lower energy inputs than traditional extrusion.
- Dishes:Cooked applications demand thermal stability and moisture retention under heat, specifications that hybrid protein matrices increasingly satisfy.
- Salads:Diced and julienne formats for foodservice salad bars prioritize color retention and low syneresis.
- Snacks:Portable formats with extended ambient shelf life target convenience retail with modified atmosphere packaging.
Sandwich substitution maintains volume leadership; dish integration is gaining technical feasibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German consumers favor sliced retail formats for grab-and-go convenience, while Dutch foodservice buyers prefer bulk blocks for commercial kitchen slicing operations. British quick-service chains integrate vegan ham into hot sandwich workflows, diverging from the cold-cut dominance elsewhere. French retail channels emphasize cured and smoked variants for premium charcuterie positioning.
Germany
Discounter chains Aldi and Lidl have mainstreamed private-label vegan sliced meats through aggressive pricing and prominent deli-counter placement. EU Green Deal agricultural transition subsidies accelerate domestic yellow pea cultivation, reducing soy import dependency. The Berlin-Brandenburg corridor hosts shear-cell processing research institutes that train extrusion technicians for mid-scale manufacturers entering the sliced-deli segment.
Netherlands
Foodservice distributors bundle block-format vegan ham with other plant-based deli analogues under consolidated three-contractor procurement models. REACH chemical safety protocols mandate granular disclosure of fermentation-derived binder origins, filtering out non-European suppliers. The Eindhoven-Randstad logistics cluster anchors cold-chain distribution for refrigerated plant-based meats across Benelux markets.
United Kingdom
Quick-service sandwich chains stock plant-based ham alternatives alongside conventional offerings, creating untapped volume anchors for manufacturers achieving thermal stability. EFSA novel-food authorization timelines for emerging flavor precursors extend 18-24 months, freezing pipeline innovation for startups lacking regulatory affairs budgets. Greater London's foodservice procurement offices specify consistent sliceability tolerances in supplier tenders.
France
Premium retail channels prioritize cured and smoked variants that replicate traditional charcuterie aesthetics for natural food stores. ANSM enforces strict clean-label ingredient standards that compress margins for artificial-additive formulations. The Île-de-France region concentrates pea protein isolate processing capacity, though Baltic harvest volatility creates intermittent supply squeezes for French formulators.
United States
Natural retail channels reward decades of seitan expertise with premium positioning for wheat-gluten-based formulations. USDA FSIS labeling guidelines restrict certain nomenclature terms, compelling parallel packaging runs that inflate inventory complexity for cross-Atlantic suppliers. The Pacific Northwest and Northeast corridor anchor distribution for refrigerated plant-based deli meats in independent grocery channels.
Vegan Ham Market Competitive Landscape
Capability concentration sits with heritage seitan specialists and extrusion-technology innovators; scale advantage sits with diversified food conglomerates with existing retail distribution networks. The vendor base separates into three strategic archetypes: protein-technology pure-plays with formulation IP, multinational CPG platforms leveraging existing deli-meat infrastructure, and private-label manufacturers serving discounter chains. Dominant competitive moves include portfolio diversification into hybrid protein matrices and geographic expansion through foodservice contract acquisition.
Within the heritage specialist tier, Tofurky and Lightlife Foods exemplify decades of accumulated seitan and extrusion expertise that anchors premium positioning in North American natural retail. Nestlé occupies a scale-driven position through The Vegetarian Butcher brand, which exemplifies how multinational CPG platforms leverage existing European retail and foodservice distribution. These three represent the capability-scale spectrum that defines competitive positioning in formulated plant-based deli meats.
| Leading Market Players |
|---|
| Tofurky |
| Lightlife Foods |
| Yves Veggie Cuisine |
| Gardein |
| Nestlé |
| The Vegetarian Butcher |
| Quorn Foods |
| Alpha Foods |
| Vbites Foods |
| Others |
Value Network & Pricing Analysis
Baltic harvest volatility in yellow pea cultivation determines both premium-tier pricing spreads and the geographic shape of European protein sourcing. Manufacturers facing supply squeezes during poor harvests absorb margin compression or pass costs downstream, while consistent supply anchors contract pricing stability for foodservice block formats.
Pricing Analysis
Long-term offtake agreements dominate procurement between major plant-protein manufacturers and Dutch-German foodservice distributors, insulating against spot-market beet-derived colorant volatility. Three-tier pricing structure across premium seitan-based, standard hybrid-protein, and economy soy-intensive formulations reflects certification grade and volume scale differentials. Pricing pressure stems from REACH compliance costs filtering non-European suppliers from Dutch retail tenders. Discounter chains exhibit highest price sensitivity; natural retail channels tolerate premium positioning for clean-label credentials.
Supply Chain Analysis
REACH chemical safety protocols restrict fermentation-derived binder flows from non-European origins, concentrating upstream processing in France, Germany, and the Netherlands. Wheat gluten draws from established European milling infrastructure; pea protein isolate capacity clusters in northern France and the Berlin-Brandenburg corridor; beet-derived colorants hinge on sugar-sector harvest cycles. Single-source vulnerability concentrates in Baltic pea cultivation regions exposed to climate volatility. Distribution runs through the Eindhoven-Randstad cold-chain cluster serving Benelux markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward consolidated three-contractor procurement models at German and Dutch discounter chains, compressing supplier margins while rewarding extrusion versatility across multiple analogue categories.
For Market Incumbents: Build formulation IP moats around hybrid pea-seitan matrices that achieve sliceability tolerances specified in private-label tenders. Invest in shear-cell processing capacity within the Berlin-Brandenburg research corridor to capture technician talent before mid-scale competitors. Secure backward integration into domestic yellow pea cultivation to offset Baltic harvest volatility and anchor supply commitments to Dutch foodservice distributors.
For New Entrants and Emerging Players: Build out foodservice block-format production targeting quick-service sandwich chains across the United Kingdom and Netherlands, the most penetrable volume segment outside retail consolidation. Emphasize thermal stability specifications for hot-sandwich workflows that diverge from cold-cut dominance elsewhere. Pursue direct procurement relationships with commercial kitchen distributors rather than competing for shelf space in saturated German discounter channels.
For Investors and Strategic Acquirers: EFSA novel-food authorization timelines reshapes the acquisition landscape by freezing pipeline innovation for undercapitalized startups lacking regulatory affairs budgets. Long-term viability favors targets with established GRAS self-affirmation pathways and REACH-compliant certification documentation. Prioritize shear-cell processing expertise concentrated at European research institutes. Watch Baltic harvest yield reports as inflection indicators for pea protein supply squeezes and margin compression events.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Protein Matrix Development | Pea-seitan formulations satisfy German discounter sliceability tolerances while displacing legacy soy systems. |
| Shear-Cell Processing Scale-Up | Lower-energy extrusion alternatives enable mid-scale manufacturers to enter the sliced-deli segment profitably. |
| Domestic Pulse Cultivation Partnerships | EU Green Deal subsidies accelerate French and German yellow pea sourcing, reducing transatlantic soy dependency. |
| REACH Compliance Certification | Granular binder-origin documentation unlocks Dutch foodservice procurement gates previously closed to non-European suppliers. |
| Foodservice Block Format Expansion | Bulk formats command per-kilogram premiums over retail sliced packs while bypassing complex packaging compliance. |
Research Methodology
A spread of perspectives from plant-protein R&D directors, foodservice procurement managers at Dutch distributors, regulatory affairs leads at major CPG platforms, and extrusion technology specialists converged on the working assumptions. Primary interviews combined with secondary validation from EFSA novel-food authorization databases, REACH chemical safety protocol filings, EU agricultural subsidy records, and Benelux cold-chain logistics reports. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Demand-supply balance framing anchored the forecast framework, with segmentation across product format, protein base material, and distribution channel dimensions modeled throughout the projection horizon. CAGRs derived from iterative reconciliation of foodservice contract velocity data and retail scanner panel trends. Shear-cell processing adoption curves and EU Green Deal agricultural transition subsidy disbursement patterns served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by pea protein pure-plays or sudden EFSA regulatory acceleration would shift outcomes. Cross-checking against customs data on European pulse protein imports and Dutch foodservice distributor procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Egg Replacers Market
Alternative Food Sources
Corn-Based Protein Market
Alternative Food Sources
Low Calorie Rice Market
Alternative Food Sources
Algal Protein Market
Alternative Food Sources
Mushroom Protein Market
Alternative Food Sources
Flaxseed Based Egg Market
Alternative Food Sources
Mock Meat Market
Alternative Food Sources
Algae Products Market
Alternative Food Sources
Fishless Fillets Market
Alternative Food Sources
Africa Fat Replacers Market
Alternative Food Sources
Global Konjac Glucomannan Market
Alternative Food Sources
Vegan Tuna Market
Alternative Food Sources
Sugar Alternative Market
Alternative Food Sources
Africa Potato Protein Market
Alternative Food Sources
Europe Algae Protein Market
Alternative Food Sources
Synthetic Food Market