
 Fungal Protein Market | 2026-2036
Fungal Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Fungal Protein Market Analysis
Modular ingredient bundling is realigning procurement decisions across the fungal protein value chain. Quorn Foods leverages mycelium-based whole-cut formats to anchor its position in European retail. MycoTechnology competes through bitter-blocking protein extracts that extend formulation flexibility for beverage applications. DSM sustains technology leadership through fermentation-derived nutritional protein platforms.
Fungal protein comprises biomass cultivated from filamentous fungi, typically achieving protein content between 40% and 60% dry weight through submerged fermentation or solid-state cultivation. The primary commercial purpose centers on delivering complete amino acid profiles with favorable digestibility for human and animal nutrition. Mycelium-based formats dominate volume due to established processing infrastructure and consumer familiarity in meat alternative applications. Protein isolates command premium positioning within sports nutrition and therapeutic use cases where purity thresholds exceed standard food-grade specifications. Extracts concentrate margin pools in functional foods as bioactive compounds gain formulation traction.
The FDA oversees Generally Recognized As Safe determinations for novel fungal protein ingredients entering US commerce, while EMA frameworks govern mycelium-derived bioactive classifications for nutraceutical claims in Europe. EFSA novel food assessments shape market access timelines for European launches, creating compliance differentiation between established and emerging suppliers. Stakeholders must monitor evolving protein labeling standards and fermentation carbon accounting methodologies as procurement criteria harden across institutional buyers.
Market Dynamics
Precision fermentation scale-up is compressing production economics for mycelium-derived proteins, forcing legacy suppliers to retool facilities or cede share to biotech entrants with modular bioreactor architectures.
Growth Catalysts
- EU Novel Food Regulation:Streamlined safety assessments for mycelium ingredients accelerate European market entry timelines for fermentation-derived protein formats.
- Meat alternative reformulation:Food manufacturers replace soy and pea isolates with fungal proteins to improve texture profiles and reduce allergen labeling burdens.
- German precision fermentation clusters:Concentrated R&D infrastructure and downstream processing capabilities anchor continental supply security for alternative protein brands.
Market Restraints
- Feedstock cost volatility:Glucose and agricultural waste streams face competing demand from biofuels and biochemical sectors, squeezing input cost stability for submerged fermentation.
- Single-source bioreactor dependency:Stainless steel fermentation vessel supply concentrates among German and Danish engineering firms, creating equipment delivery bottlenecks.
- Protein functionality gaps:Mycelium biomass exhibits weaker gelling and emulsification properties versus animal proteins, limiting clean-label applications in dairy alternatives.
Strategic Opportunities
- Pet food nutrition:Underpenetrated companion animal protein applications offer formulation flexibility with lower purity thresholds than human-grade specifications.
- US FDA GRAS self-determination:Streamlined safety notification pathways reduce regulatory lag versus novel food assessments, enabling faster commercialization for domestic suppliers.
- Hybrid meat-fungal blends:Convergence of cultivated meat scaffolding with mycelium biomass creates intermediate products bridging price and acceptance gaps.
Industry Challenges
- Fermentation process engineering talent:Scarcity of specialists bridging fungal physiology with industrial bioprocessing slows facility commissioning and yield optimization.
- EFSA novel food dossier preparation:Extensive toxicology and compositional data requirements extend compliance timelines and capital lock-up for European market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fungal Protein Market |
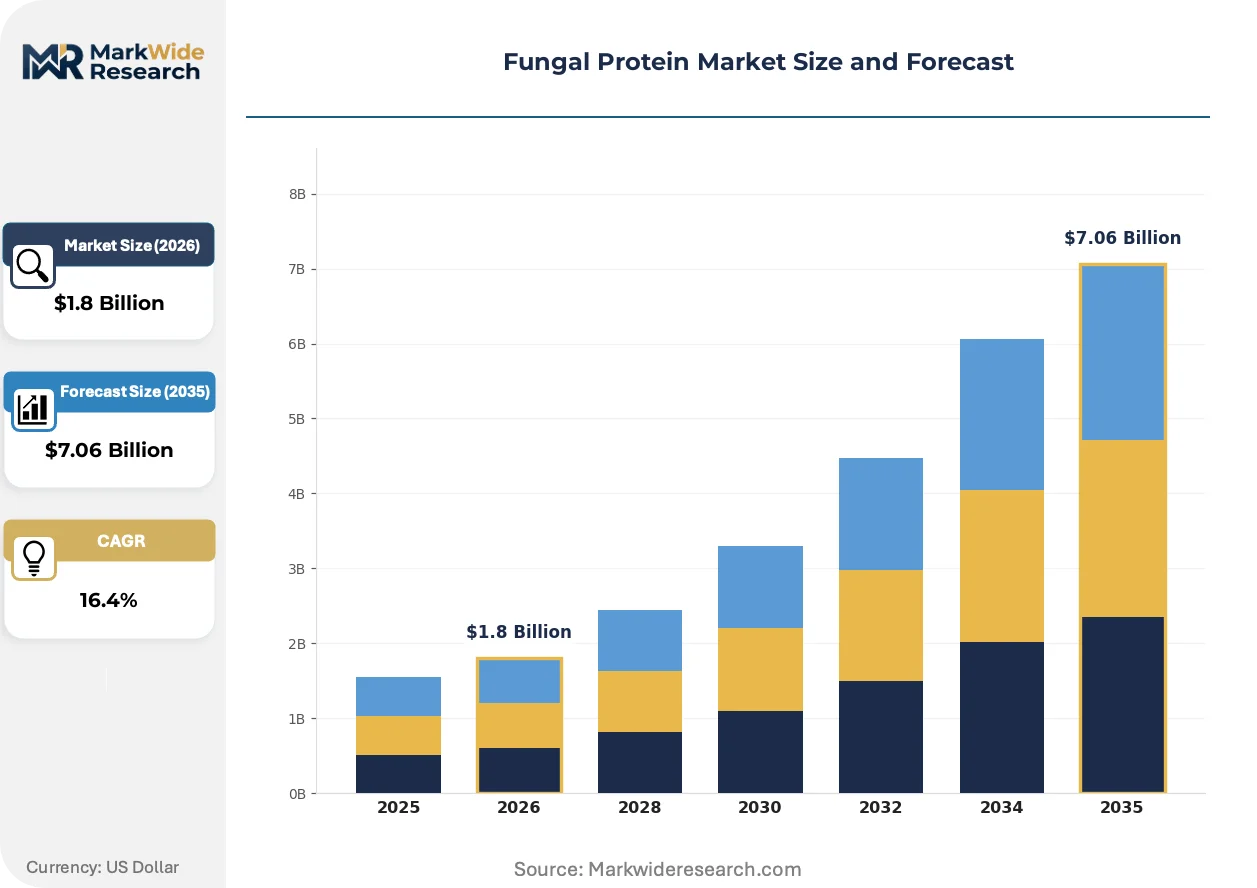
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mycelium, Fungal Biomass, Extracts, Protein Isolate Application: Food Supplements, Animal Feed, Meat Alternatives, Nutraceuticals Use Case: Dietary, Functional Foods, Sports Nutrition, Therapeutic Packaging Type: Bags, Bottles, Sachets, Bulk Containers |
| Companies Covered | Quorn Foods, MycoTechnology, Marlow Foods, DSM, Angel Yeast, Kerry Group, Lallemand, Lesaffre Group, Halcyon Proteins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fungal Protein Market Emerging Trajectories
Continuous processing architectures and AI-driven bioprocess control are collapsing batch-to-batch variability, enabling food manufacturers to specify tighter protein functionality guarantees in procurement contracts.
Submerged fermentation with automated perfusion systems is unifying upstream biomass production with downstream extraction in single-train facilities. Contract manufacturers in the Netherlands and Denmark are adopting these integrated platforms to reduce cycle times. This unification is compressing capital intensity thresholds, allowing mid-scale entrants to achieve cost parity with established solid-state operations.
REACH registration requirements for novel protein byproducts are tightening purity specifications for waste stream valorization. Industrial enzyme suppliers must now document full substance identity across fermentation metabolites. Sports nutrition brands sourcing European-manufactured isolates face extended supplier qualification timelines as ECHA compliance documentation becomes mandatory in procurement checklists.
Ingredient specification sheets now embed carbon intensity metrics alongside nutritional parameters, reflecting institutional buyer mandates for Scope 3 emissions transparency. Foodservice distributors in Germany and France are rejecting suppliers lacking third-party verified fermentation carbon accounting. This behavioral shift is fragmenting procurement pools between certified and uncertified biomass sources, creating premium tiering in B2B contract negotiations.
Fungal Protein Market Segmentation
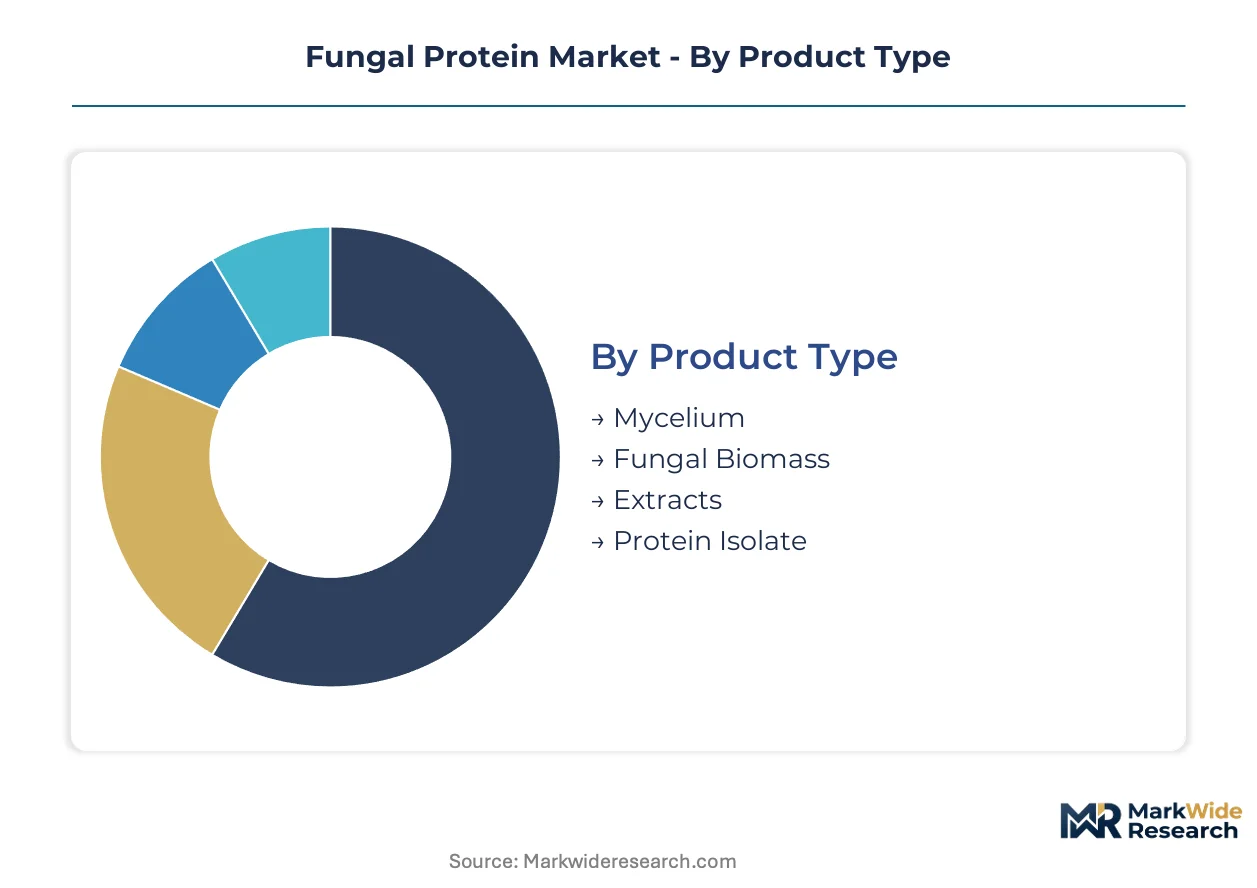
Fungal protein suppliers configure production assets around format-specific processing requirements. Product type determines fermentation architecture, while application dictates purity thresholds and regulatory pathway selection.
Product Type:
Submerged fermentation versus solid-state cultivation creates divergent capital intensity and yield profiles across formats.
- Mycelium:Whole biomass cultivated from filamentous fungi delivers complete protein matrices with fiber content between 25% and 35% dry weight. Meat alternative manufacturers in Germany and the Netherlands concentrate procurement here, drawn by established texture-processing infrastructure and EU Novel Food approval precedents.
- Protein Isolate:Purified fractions achieving 80% to 90% protein concentration through aqueous extraction and membrane filtration. Sports nutrition brands and therapeutic formula developers specify isolates for amino acid profile precision, though EFSA novel food dossiers extend European commercialization timelines.
- Fungal Biomass:Dried and milled fermentation output retaining cellular structure for whole-food applications. Pet food manufacturers leverage biomass for companion animal nutrition with lower purity thresholds than human-grade specifications.
- Extracts:Concentrated bioactive compounds including beta-glucans and ergothioneine. Functional beverage formulators in France and Belgium specify bitter-blocking protein extracts to reduce masking agent requirements.
Mature deployment sits with Mycelium. Newer deployment is concentrated in Protein Isolate.
Application:
End-use specifications fragment procurement pools across human nutrition, animal feed, and pharmaceutical adjacents.
- Meat Alternatives:Whole-cut mycelium formats anchor retail positioning for European plant-based brands reformulating away from soy isolates. Texture profile requirements drive specification of strain-specific biomass with aligned fiber orientation.
- Food Supplements:Capsule and tablet applications demand standardized protein content and low endotoxin levels. German contract manufacturers dominate toll processing capacity for supplement-grade fungal ingredients.
- Animal Feed:Aquaculture and poultry sectors trial fermented biomass as fishmeal and soy replacement. Feed conversion ratio validation trials concentrate in Denmark and Norway.
- Nutraceuticals:Immune-modulating and antioxidant claims require EMA bioactive classification for European market access. Dossier preparation costs filter supplier participation.
Volume concentration favors Meat Alternatives. Margin expansion concentrates in Nutraceuticals.
Use Case:
Consumer benefit positioning determines formulation complexity and pricing tier access.
- Dietary:General wellness applications with basic protein fortification claims. Mass-market retail distribution in Germany and France absorbs volume from established mycelium suppliers.
- Functional Foods:Gut health and satiety positioning drives inclusion in fermented beverages and bakery. Dutch ingredient houses lead concept development for functional food brands.
- Sports Nutrition:Leucine content and digestibility scoring determine specification for powder and ready-to-drink formats. Third-party certification requirements extend supplier qualification cycles.
- Therapeutic:Clinical nutrition and medical food applications demand batch-level traceability and contaminant testing. Hospital and pharmacy channel access requires national health service listing in target markets.
Mainstream adoption clusters in Dietary. Premium positioning concentrates in Therapeutic.
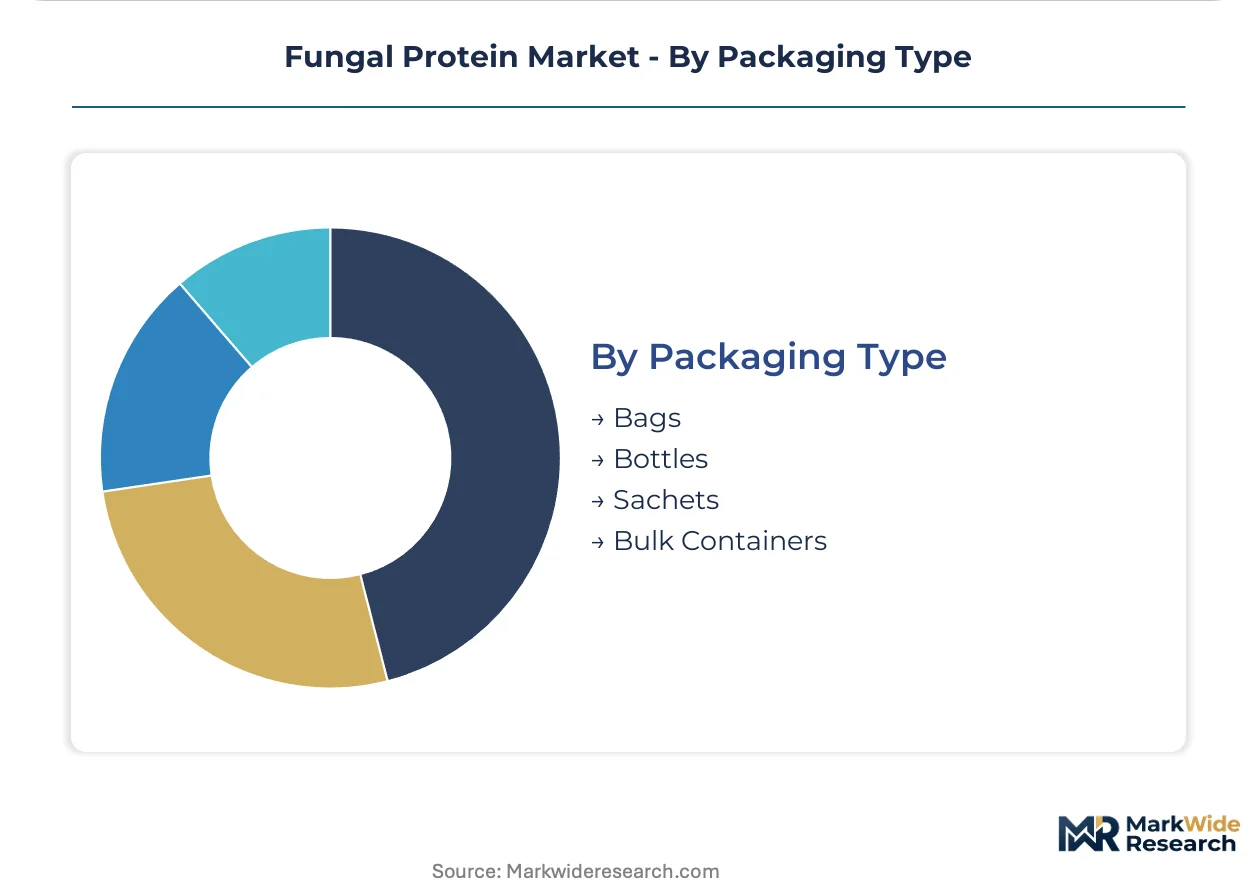
Packaging Type:
Downstream logistics and shelf-life requirements shape material selection and unit economics.
- Bulk Containers:Intermediate bulk containers and flexible intermediate bulk bags serve industrial food manufacturers with integrated processing lines. German precision fermentation clusters optimize for bulk outbound logistics.
- Bags:Multi-layer laminated pouches for retail and foodservice distribution. Oxygen barrier specifications vary by protein format sensitivity.
- Bottles:Rigid packaging for liquid extracts and ready-to-drink applications. PET and glass formats compete on sustainability credentials and supply chain circularity.
- Sachets:Single-serve units for sports nutrition and travel formats. Flexible packaging converters in the Netherlands specialize in portion-controlled fungal protein sachets.
Industrial scale concentrates in Bulk Containers. Consumer convenience innovation clusters in Sachets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Northern Europe while consumption concentrates in German and French retail channels. Precision fermentation infrastructure in the Netherlands and Denmark supplies biomass to formulation facilities across the continent. This geographic split creates logistics arbitrage opportunities for integrated operators.
Germany
Meat alternative manufacturers in Berlin and Hamburg drive procurement volumes for mycelium biomass. The Federal Office of Consumer Protection and Food Safety enforces EFSA novel food compliance timelines for new fermentation-derived ingredients. Precision fermentation clusters in North Rhine-Westphalia anchor continental supply security through integrated bioreactor networks and downstream processing capabilities.
Netherlands
Contract manufacturers serving pan-European food brands concentrate toll-processing demand for fungal protein isolates. REACH registration requirements for fermentation metabolites tighten supplier qualification protocols. Eindhoven-based bioprocess engineering firms deploy continuous processing architectures that compress batch-to-batch variability for sports nutrition applications.
Denmark
Aquaculture feed trials in Copenhagen and Aarhus generate demand for fermented biomass as fishmeal replacement. The Danish Veterinary and Food Administration coordinates with EFSA on novel protein safety assessments. Stainless steel fermentation vessel engineering concentrates among Danish suppliers, creating equipment delivery bottlenecks for capacity expansion projects.
France
Functional beverage formulators in Paris and Lyon specify bitter-blocking protein extracts to reduce masking agent requirements. ANSM governs bioactive classification for nutraceutical claims involving immune-modulating compounds. Auvergne-Rhône-Alpes hosts pilot facilities bridging mycelium cultivation with clinical nutrition validation for therapeutic use cases.
United Kingdom
Retail distribution networks for plant-based whole-cuts absorb established mycelium supply from heritage fermentation operations. The Food Standards Agency maintains novel food consultation pathways parallel to EFSA procedures. Greater Manchester and Birmingham processing hubs reformulate legacy soy-dependent product lines with fungal protein to improve texture profiles and reduce allergen labeling burdens.
Fungal Protein Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across differentiated technology vectors. Tier-one suppliers leverage captive fermentation capacity and downstream extraction infrastructure to defend margin positions. Three archetypes dominate: integrated biotech platforms with modular bioreactor architectures, legacy ingredient houses with solid-state cultivation heritage, and contract manufacturers offering toll-processing flexibility. Capacity expansion and strategic partnerships constitute the primary competitive moves, with biotech entrants pursuing offtake agreements with established food brands.
Within the heritage fermentation tier, Quorn Foods and Marlow Foods occupy positions anchored by decades of consumer familiarity with mycelium-based formats. DSM exemplifies the diversified nutrition platform archetype, spanning fermentation-derived protein across human and animal applications. MycoTechnology represents the functional extract specialist segment, competing through bioactive compound concentration rather than bulk biomass volume.
| Leading Market Players |
|---|
| Quorn Foods |
| MycoTechnology |
| Marlow Foods |
| DSM |
| Angel Yeast |
| Kerry Group |
| Lallemand |
| Lesaffre Group |
| Halcyon Proteins |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between EFSA novel food dossier holders and uncertified biomass suppliers manifests in contract pricing spreads and procurement pool fragmentation across German and Dutch foodservice channels. This bifurcation concentrates supply security premiums with integrated fermentation operators while squeezing toll-dependent processors on both input costs and offtake pricing power.
Pricing Analysis
Margin tightening in protein isolate tiers reflects extended EFSA compliance timelines and capital lock-up for European market access. Three-tier pricing structure across premium, standard, and economy levels separates therapeutic-grade isolates with batch-level traceability from food-grade biomass and pet nutrition specifications. Cost-down pressure on mycelium biomass accelerates as precision fermentation scale-up compresses unit economics. Food manufacturers exhibit highest price sensitivity in bulk procurement contracts, while nutraceutical brands absorb premiums for EMA bioactive classifications.
Supply Chain Analysis
Specialized fermentation process engineering talent scarcity in North Rhine-Westphalia and Eindhoven clusters constrains facility commissioning speed and bioreactor network expansion. Supply concentration centers on Germany, the Netherlands, and Denmark for precision fermentation infrastructure and stainless steel vessel engineering. Raw material dependencies draw from agricultural glucose streams, nitrogen sources, and membrane filtration equipment. Single-source bioreactor vulnerability creates equipment delivery bottlenecks for capacity expansion. Distribution runs through German precision fermentation clusters to pan-European formulation facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
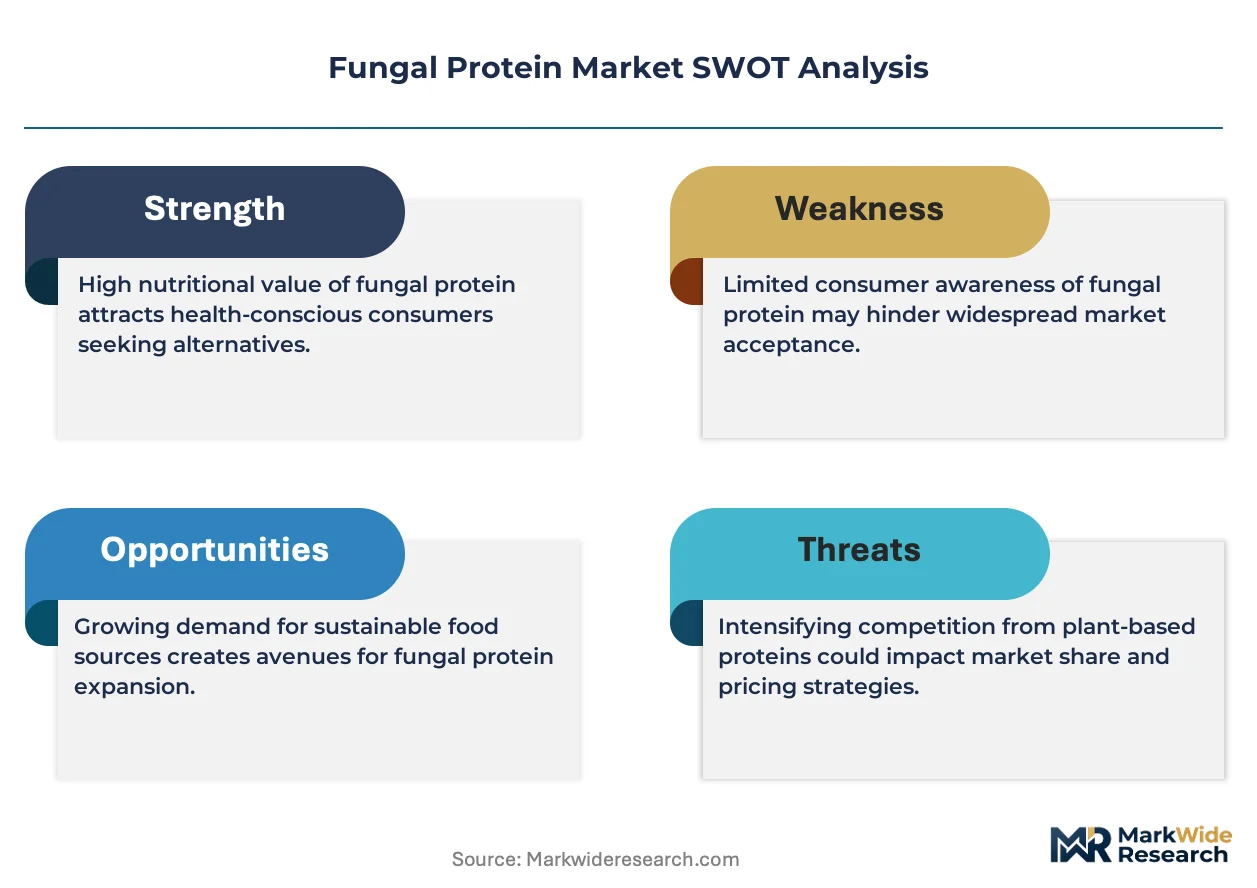
This market functions as a vertical-integration race where captive fermentation capacity and downstream extraction infrastructure determine margin capture. Players pursue upstream control over bioreactor networks and novel food certification assets to defend pricing power.
For Market Incumbents: Lock in supply security through captive bioreactor capacity additions in German precision fermentation clusters. Deepen backward integration into glucose feedstock sourcing to buffer agricultural commodity volatility. Defend against modular biotech entrants by accelerating EFSA novel food dossier completions for strain-specific biomass formats.
For New Entrants and Emerging Players: Continuous processing architecture with AI-driven bioprocess control offers formulation flexibility guarantees that differentiate against legacy batch operations. Pet food nutrition applications present the most penetrable segment given lower purity thresholds and faster qualification cycles. Pursue offtake agreements with established European meat alternative brands lacking captive fermentation assets.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated biotech platforms possessing modular bioreactor architectures and EFSA approval precedents given EU Novel Food Regulation acceleration. Long-term viability hinges on fermentation carbon accounting certification and Scope 3 emissions transparency. Watch for institutional buyer mandates rejecting uncertified biomass as inflection indicator for procurement pool consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Completion | Accelerates European commercialization timelines for mycelium-derived protein formats. |
| Continuous Processing Architecture Deployment | Collapses batch-to-batch variability for sports nutrition and therapeutic applications. |
| Backward Integration into Feedstock Supply | Buffers glucose cost volatility from competing biofuel and biochemical demand. |
| Fermentation Carbon Accounting Certification | Unlocks premium tiering in German and French institutional procurement negotiations. |
| Hybrid Meat-Fungal Blend Development | Bridges price and acceptance gaps between cultivated meat scaffolding and biomass formats. |
Methodological Framework
Document review covered EFSA novel food register entries, REACH registration filings, and fermentation equipment engineering specifications, complemented by interviews with precision fermentation facility operators, food manufacturer procurement leads, sports nutrition brand formulators, and ECHA compliance consultants. Secondary validation drew from EU trade statistics, customs records for fermentation equipment imports, and SEC filings of diversified nutrition platforms. Bottom-up capacity modeling and top-down consumption estimates were triangulated against panel input.
Cross-referencing historical capacity expansion patterns with expert panel assessments anchored projections across the analysis window. Segmentation dimensions modeled include product type, application, use case, and packaging format alongside regional regulatory cluster. CAGRs were derived from supply-demand balance analysis and technology diffusion curves. Industry-specific forecast inputs incorporated EFSA approval timeline distributions and fermentation carbon accounting adoption rates.
Several conditions sit outside the modeled scope, including abrupt regulatory reclassification of mycelium-derived bioactives, feedstock supply disruptions from agricultural commodity shocks, and breakthroughs in competing protein technologies. Forecasts reflect documented assumptions about EFSA processing efficiency and precision fermentation scale-up economics. Material deviation in EFSA novel food assessment timelines or institutional buyer certification mandates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Gluten-Free Meat Substitutes Market
Alternative Food Sources
Algae Fats Market
Alternative Food Sources
South American Algae Protein Market
Alternative Food Sources
Algae Products Market
Alternative Food Sources
Vegan Sashimi Market
Alternative Food Sources
Low Calorie Rice Market
Alternative Food Sources
Vegetable Proteins Market
Alternative Food Sources
North America Meat Substitutes Market
Alternative Food Sources
Edible Packaging Market
Alternative Food Sources
Edible Insects Market
Alternative Food Sources
Mock Meat Market
Alternative Food Sources
Global Alternative Protein Market
Alternative Food Sources
Meat Analogue Market
Alternative Food Sources
North America Meal Products Replacement Market
Alternative Food Sources
Bioengineered Food Market
Alternative Food Sources
Single Cell Protein Market