
 Mycoprotein Market | 2026-2036
Mycoprotein Market Size, Share, and Industry Trends Forecast 2026-2036
Mycoprotein Market Outlook
ISO 22000 food safety management certification is collapsing the supplier base to a smaller cohort of qualified mycelium processors. Marlow Foods Limited leverages decades of Quorn brand heritage to anchor UK retail shelf presence. Nature's Fynd sustains proprietary extremophile fungal strains that differentiate its fermentation platform. ENOUGH competes on industrial-scale biomass production capacity in European food manufacturing supply chains.
Mycoprotein denotes filamentous fungal biomass cultivated via submerged fermentation, typically achieving protein contents of percent dry weight comparable to conventional meat, and serves as a complete-protein ingredient for meat analogues and nutritional fortification. Textured mycelium dominates food manufacturer procurement due to superior fibrous mouthfeel replication in burger and nugget applications. Mushroom-based protein leads nutritional supplements as adaptogenic positioning drives premium pricing. Quorn retains mature retail consumer recognition but faces margin compression from private-label mycoprotein entrants in frozen product aisles.
The European Food Safety Authority governs Novel Food dossier evaluations that gate mycoprotein ingredient commercialization across EU member states. The FDA exercises Generally Recognized As Safe determination authority over fungal fermentation inputs entering US food supply chains. BIS nutritional labeling standards in India shape export compliance burdens for mycoprotein powder formulations. Stakeholders must monitor evolving precision fermentation regulatory taxonomies that could recategorize mycelium-derived proteins under distinct approval pathways.
Market Dynamics
Fermentation capacity scarcity is compressing margins as food manufacturers compete for limited mycelium biomass supply from qualified ISO 22000-certified processors. This supply bottleneck concentrates pricing power among industrial-scale producers while locking out smaller entrants.
Growth Catalysts
- EU Novel Food Framework:Streamlined dossier evaluations under EFSA guidance are accelerating mycoprotein ingredient approvals across member states, reducing time-to-market for new entrants.
- Food Service Channel Expansion:Quick-service restaurants and institutional catering operations are integrating mycoprotein analogues into core menu offerings, driving volume pull-through from downstream buyers.
- Precision Fermentation Advances:Continuous bioprocessing technologies are improving biomass yields per fermentation run, lowering unit economics for mycelium-derived protein production.
Market Restraints
- Feedstock Cost Volatility:Glucose and nitrogen substrate prices fluctuate with agricultural commodity cycles, squeezing processor margins during input price spikes.
- Supply Concentration Risk:Mycelium biomass production clusters in a handful of EU-based fermentation facilities, creating geographic vulnerability to regional energy or logistics disruptions.
- Regulatory Fragmentation:Divergent approval pathways between FDA GRAS determinations and EFSA Novel Food classifications force dual compliance investments for cross-Atlantic suppliers.
Strategic Opportunities
- Indian Nutritional Fortification:BIS labeling standards for protein-enriched foods create a compliance-aligned entry point for mycoprotein powder formulations in dietary supplement applications.
- Hybrid Meat Formulations:Blended mycoprotein-animal protein products offer a transitional positioning for flexitarian consumers resistant to fully plant-based alternatives.
- Pet Food Applications:Premium pet nutrition brands are evaluating mycelium biomass as a novel protein source for hypoallergenic formulations, opening a non-human-food revenue stream.
Industry Challenges
- Fermentation Specialist Shortage:Industrial mycology and bioprocess engineering expertise remains concentrated in pharmaceutical and enzyme production sectors, forcing competitive recruitment for food-grade talent.
- Scale-Up Capital Intensity:Commercial fermentation facilities require nine-figure capital deployment for GMP-compliant infrastructure, constraining independent processor formation.
- Consumer Sensory Acceptance:Mycoprotein's characteristic texture and umami profile requires formulation expertise to mask in certain applications, demanding sustained R&D investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mycoprotein Market |
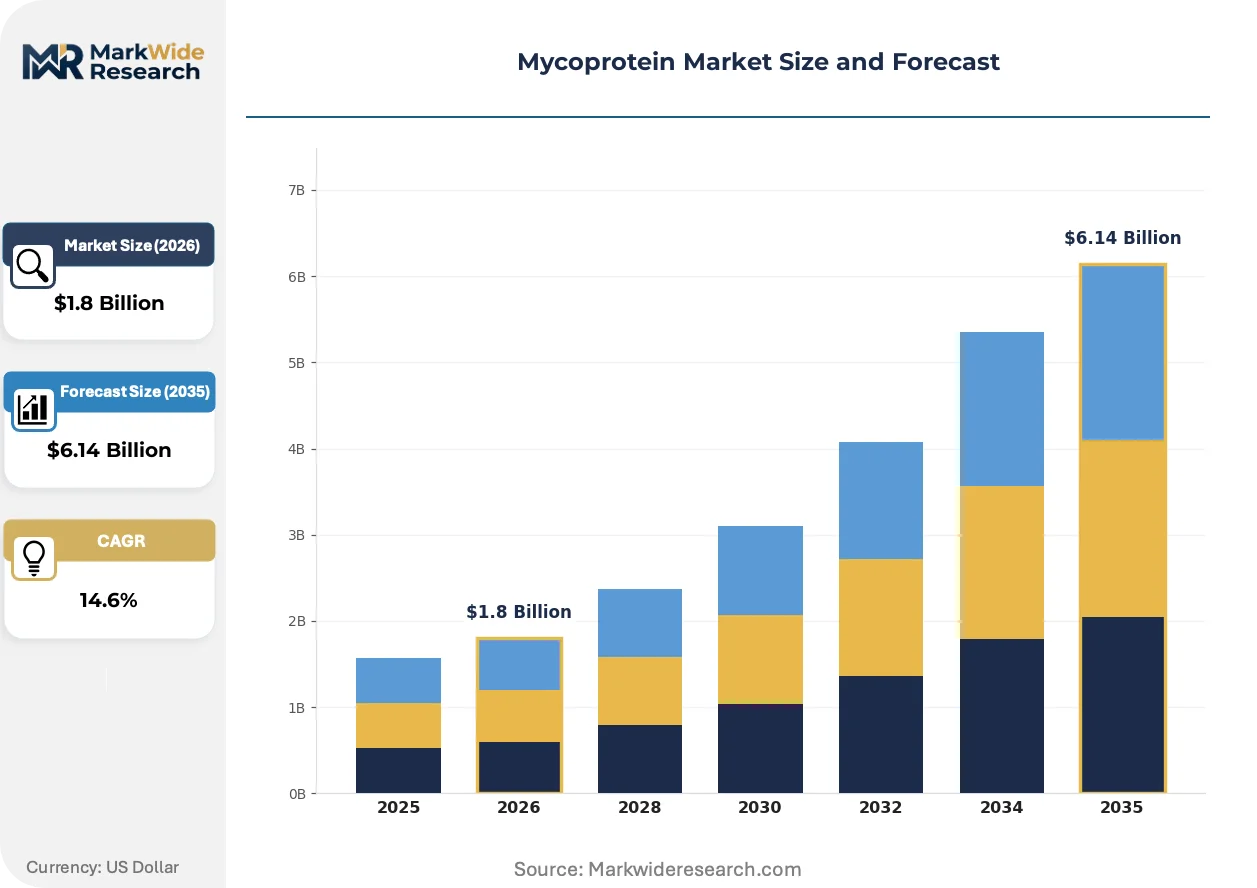
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quorn, MycoProtein, Mushroom-based Protein, Textured Mycelium End User: Food Service, Retail Consumers, Nutritional Supplements, Food Manufacturers Form: Frozen Products, Dry Powder, Ready-to-eat Meals, Snack Bars Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Direct Sales |
| Companies Covered | Nature's Fynd, Cargill, Inc., Marlow Foods Limited, KIDEMIS GmbH, Bright Green Partners B.V., ENOUGH, The Better Meat Co., Meati Foods, Inc., MycoTechnology, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mycoprotein Market Strategic Shifts
Bioprocess intensification is rewriting cost structures across mycelium protein manufacturing, while regulatory clarity and shifting procurement patterns are reordering competitive hierarchies in downstream channels.
Submerged fermentation with continuous harvesting is decomposing the batch-production paradigm that has dominated mycoprotein manufacturing for decades. Food ingredient buyers in the meat analogue sector are adopting this technology at pilot scale, with several European processors expanding continuous lines. This shift is decomposing the historical yield ceiling that constrained mycoprotein cost parity with soy and pea isolates.
EFSA's evolving guidance on whole-cell biomass characterization is tightening safety documentation requirements for novel mycelium strains entering European food supply chains. The regulation forces developers to invest in comprehensive toxicology and allergenicity datasets earlier in the commercialization cycle. Small-scale fermentation startups without pharmaceutical-grade documentation capabilities are retreating from EU market entry, ceding ground to established players with legacy safety dossiers.
Direct procurement contracts between food manufacturers and fermentation processors are displacing traditional ingredient distributor intermediaries in mycoprotein supply chains. Large meat analogue producers in Germany and the Netherlands are negotiating multi-year offtake agreements with biomass suppliers, securing volume allocations and price stability. This channel consolidation is most pronounced in frozen product manufacturing, where input cost predictability outweighs distributor logistics value.
Mycoprotein Market Segmentation
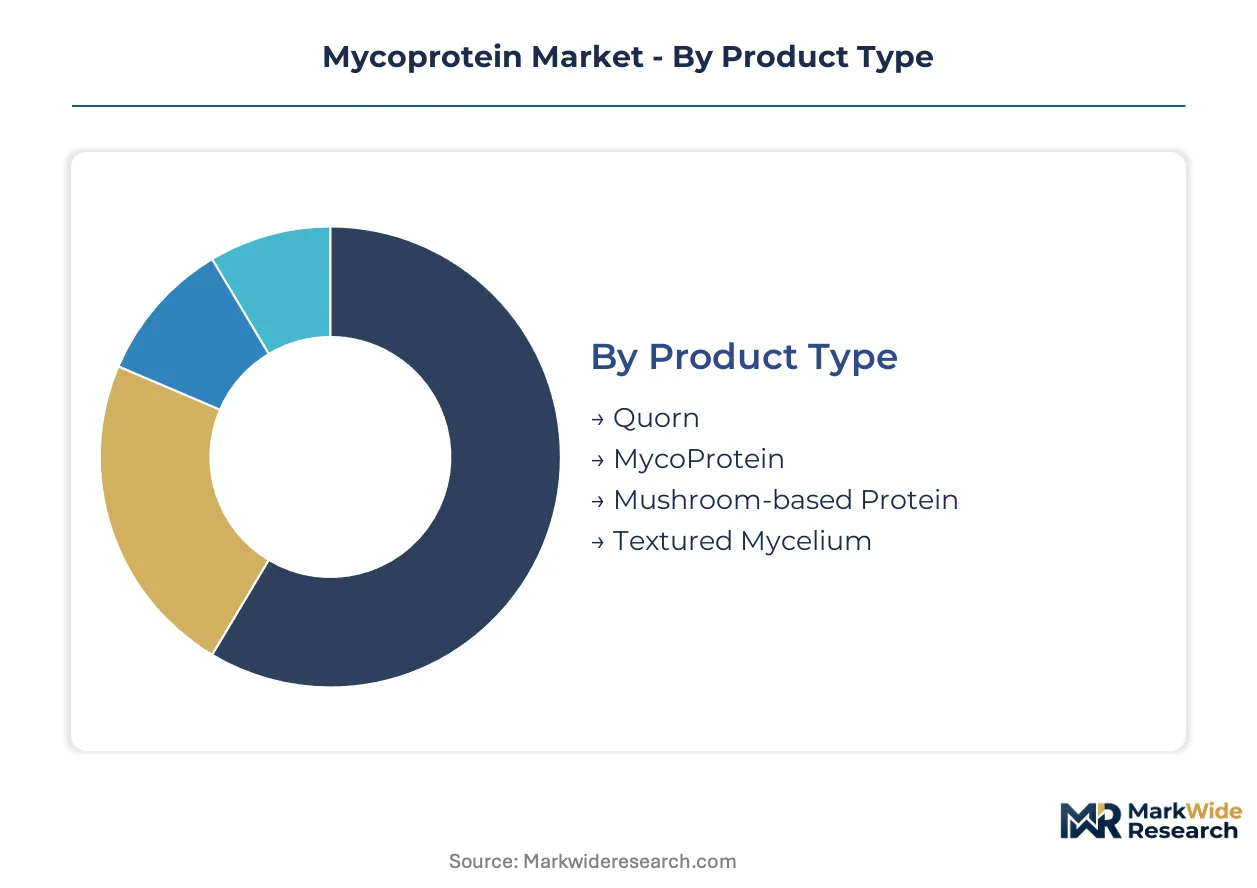
Product differentiation in mycoprotein hinges on fermentation methodology and downstream processing intensity. Each segment category reflects distinct margin structures and geographic demand patterns that shape supplier positioning.
Product Type:
Quorn dominates UK domestic consumption through retail heritage, while textured mycelium exports drive German and Dutch food manufacturing procurement.
- Quorn:Filamentous fungal biomass marketed under established retail branding with decades of UK consumer recognition. British supermarkets anchor volume, though margin pressure intensifies from private-label competitors in frozen aisles.
- Textured Mycelium:Fibrous biomass processed for meat analogue mouthfeel replication. German and Dutch food manufacturers concentrate procurement here for burger and nugget applications, prioritizing ISO 22000-certified suppliers.
- MycoProtein:Generic biomass ingredient positioned for B2B formulation flexibility.
- Mushroom-based Protein:Adaptogenic-positioned ingredient commanding premium pricing in nutritional supplements.
Textured mycelium holds the largest share; momentum sits with mushroom-based protein.
End User:
Channel economics diverge sharply: food service contracts deliver volume scale while nutritional supplements capture margin premiums.
- Food Manufacturers:Industrial buyers in Germany and the Netherlands negotiate multi-year offtake agreements directly with fermentation processors. Direct procurement displaces distributor intermediaries as volume predictability outweighs logistics services.
- Nutritional Supplements:Premium positioning around adaptogenic and complete-protein claims. BIS labeling compliance in India shapes export formulation requirements for powder-based products.
- Food Service:Quick-service restaurants and institutional catering drive volume pull-through.
- Retail Consumers:Frozen product aisles in UK supermarkets sustain mature demand.
Food manufacturers command the volume base; nutritional supplements are climbing the fastest.
Form:
Processing intensity determines cost tier: frozen products require cold chain infrastructure while dry powder enables export scalability.
- Frozen Products:Mycoprotein biomass preserved for extended shelf life in retail and food service channels. UK and German cold chain networks concentrate distribution, with margin compression from private-label entrants.
- Dry Powder:Dehydrated biomass for nutritional fortification and ingredient blending. Indian dietary supplement applications drive export demand aligned with BIS protein labeling standards.
- Ready-to-eat Meals:Formulated products requiring sustained R&D investment for sensory masking.
- Snack Bars:Convenience format targeting flexitarian positioning.
Frozen products retain the dominant position; dry powder shows steepest expansion trajectory.
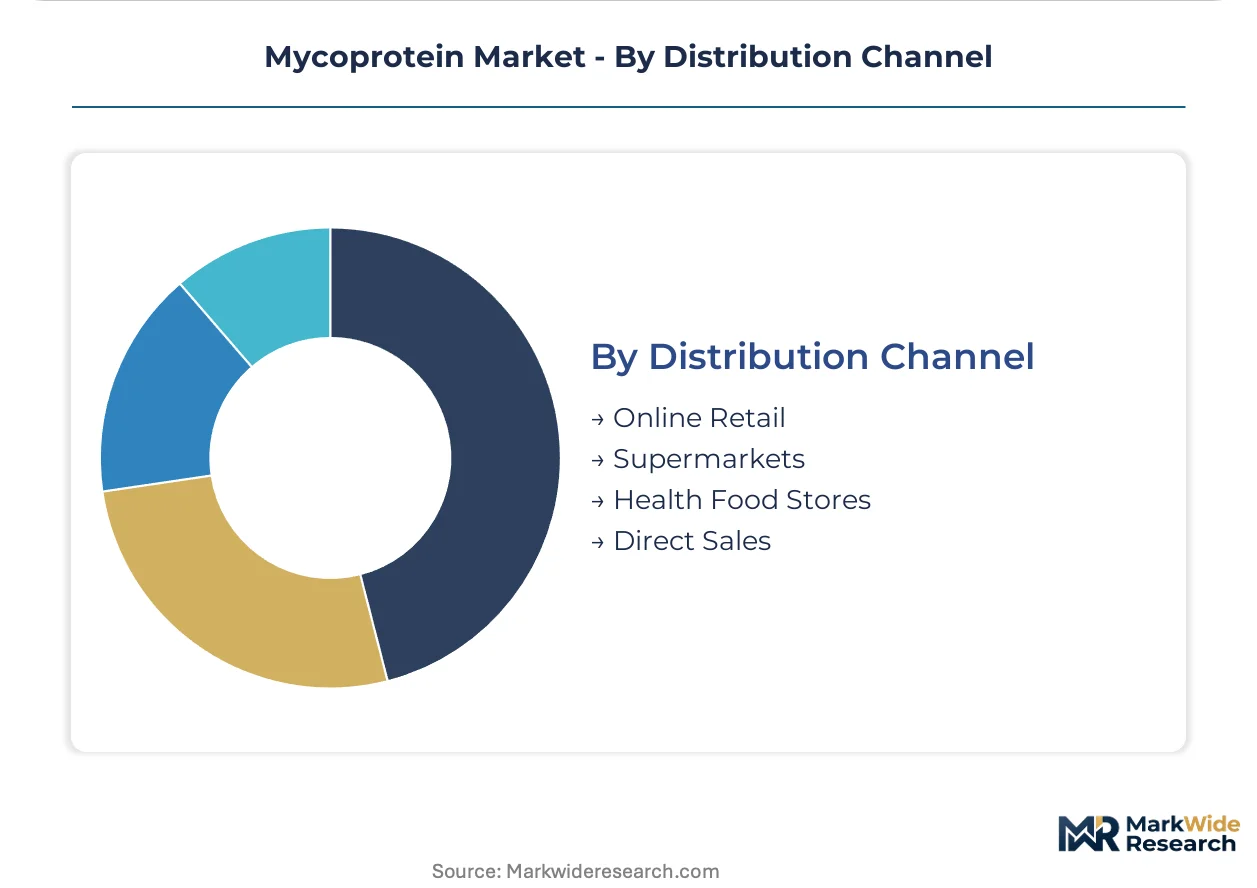
Distribution Channel:
Channel consolidation favors direct relationships over traditional intermediaries, particularly in industrial procurement.
- Direct Sales:Fermentation processors negotiate contracts directly with large meat analogue producers. German and Dutch manufacturers prioritize this channel for price stability and volume allocation security.
- Supermarkets:UK retail chains anchor Quorn brand presence with decades of shelf space allocation.
- Online Retail:Supplement-focused e-commerce enables geographic reach beyond established retail footprints.
- Health Food Stores:Premium positioning for adaptogenic and specialty protein products.
Direct sales capture the industrial volume; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Novel Food authorizations under EFSA guidance are accelerating mycoprotein commercialization timelines across member states. Germany, the United Kingdom, and the Netherlands concentrate demand within food manufacturing and retail channels. National protein diversification policies in India and regulatory clarity in the United States are opening parallel growth corridors outside European markets.
Germany
Industrial food manufacturers in North Rhine-Westphalia negotiate multi-year offtake agreements for textured mycelium biomass. The country's Federal Ministry of Food and Agriculture supports alternative protein development through dedicated innovation funding programs. Cologne and Düsseldorf anchor procurement clusters where ISO 22000-certified suppliers direct-sell to meat analogue producers.
United Kingdom
Retail frozen aisles sustain mature mycoprotein consumption anchored by decades of brand heritage. The Food Standards Agency governs novel food consultations that gate new strain introductions into British supply chains. Greater Manchester and the Midlands host fermentation capacity expansions serving both domestic supermarkets and export food service contracts.
Netherlands
Food ingredient distributors in Rotterdam and Amsterdam pivot toward direct procurement models as manufacturers bypass traditional intermediaries. The Dutch Food and Consumer Product Safety Authority aligns with EFSA guidance while maintaining national enforcement discretion over biomass characterization. Wageningen University partnerships concentrate bioprocess engineering talent for scale-up operations.
India
BIS nutritional labeling standards for protein-enriched foods shape export formulation requirements for mycoprotein powder supplements. The Food Safety and Standards Authority of India governs novel ingredient import clearances that gate commercial entry. Maharashtra and Karnataka dietary supplement manufacturers evaluate mycelium biomass for adaptogenic positioning in premium nutrition products.
United States
Precision fermentation startups secure FDA GRAS determinations for novel fungal strains entering American food supply chains. The agency's Generally Recognized As Safe notification process offers faster market entry than European Novel Food dossier requirements. California and Illinois fermentation facilities compete for food-grade talent previously concentrated in pharmaceutical enzyme production.
Mycoprotein Market Competitive Environment
Player mix skews toward heritage-brand incumbents and venture-backed biotech specialists. Market structure concentrates pricing power among ISO 22000-certified processors with commercial-scale fermentation infrastructure. Three archetypes dominate: established retail brand owners, industrial biomass suppliers, and precision fermentation technology platforms. Competitive moves center on capacity expansion and strategic partnerships that lock in multi-year offtake agreements.
Among European heritage players, Marlow Foods Limited anchors retail recognition through decades of UK supermarket presence. ENOUGH occupies a position as an industrial-scale biomass supplier serving food manufacturer procurement in Germany and the Netherlands. Nature's Fynd represents the technology-platform archetype with proprietary extremophile strain differentiation. These three exemplify how competitive positioning splits across consumer-facing branding, manufacturing scale, and fermentation IP rather than converging on a single winning model.
| Leading Market Players |
|---|
| Nature's Fynd |
| Cargill, Inc. |
| Marlow Foods Limited |
| KIDEMIS GmbH |
| Bright Green Partners B.V. |
| ENOUGH |
| The Better Meat Co. |
| Meati Foods, Inc. |
| MycoTechnology, Inc. |
| Others |
Value Chain & Pricing Dynamics
Continuous bioprocessing substitution for legacy batch fermentation is redrawing supply geography toward Rotterdam and Greater Manchester while collapsing unit economics that once protected incumbent pricing power. This technology transition concentrates biomass output in facilities with nine-figure capital deployment capacity, compressing margins for smaller ISO 22000-certified processors locked into older infrastructure.
Pricing Analysis
Certification level creates the primary spread between premium ISO 22000-validated biomass and standard-grade mycelium feedstock. Contract-based long-term offtake agreements dominate food manufacturer procurement, with pricing stratifying across pharmaceutical-grade documentation, food-grade certification, and uncertified commodity tiers. Cost compression in standard-grade supply is intensifying because private-label entrants in UK frozen aisles replicate Quorn-equivalent formulations at lower price points. Food manufacturers in Germany and the Netherlands exhibit lowest price sensitivity due to volume allocation security priorities, while nutritional supplement brands in India face acute pressure from BIS compliance costs layered onto import logistics.
Supply Chain Analysis
Port congestion at Rotterdam and container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for glucose and nitrogen substrate imports. Mycelium biomass production clusters in the Netherlands, United Kingdom, and Germany, with fermentation capacity expansion concentrated in North Rhine-Westphalia and Greater Manchester. Raw material dependencies rest on agricultural glucose from French and German beet processing, nitrogen substrates from ammonia crackers in Belgium, and specialty yeast extracts from Dutch suppliers. Single-source vulnerability permeates the qualified processor base, where ISO 22000 certification collapses the supplier cohort to a handful of industrial-scale facilities. Distribution runs through direct procurement contracts displacing traditional ingredient distributor intermediaries, particularly in frozen product manufacturing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mycoprotein market sits in early-cycle expansion, with precision fermentation advances and EU Novel Food framework streamlining combining to accelerate commercialization timelines beyond historical precedent.
For Market Incumbents: Compound brand heritage advantages through exclusive multi-year offtake agreements that lock in food manufacturer volume allocations before precision fermentation platforms achieve cost parity. Defend margin position by accelerating backward integration into glucose substrate production, neutralizing agricultural commodity cycle exposure that currently squeezes processor economics. Threats from venture-backed extremophile strain platforms demand sustained R&D investment in continuous bioprocessing yield improvements. For New Entrants and Emerging Players: Differentiate on proprietary strain characterization documentation that satisfies EFSA's evolving whole-cell biomass safety requirements, creating regulatory moats against undercapitalized competitors. Target Indian nutritional supplement applications as the most penetrable geography, where BIS labeling standards align with premium adaptogenic positioning and domestic fermentation capacity remains underdeveloped. A direct-to-supplement-manufacturer go-to-market angle bypasses entrenched European distributor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed precision fermentation platforms that have secured FDA GRAS determinations but face European Novel Food dossier timelines. Long-term viability in this market hinges on five-to-ten year horizon regulatory clarity and continuous bioprocessing yield trajectories. Acquisition targets with pharmaceutical-grade documentation capabilities and existing EFSA safety dossiers offer defensive positioning. The signal to watch is EFSA guidance publication on whole-cell biomass characterization, which will recategorize approval burdens and reorder competitive hierarchies.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioprocessing Scale-Up | Rotterdam and Manchester facilities deploying continuous harvesting lines decompose historical yield ceilings constraining cost parity. |
| EFSA Novel Food Dossier Investment | Comprehensive toxicology datasets for proprietary strains gate European commercialization against undercapitalized competitors. |
| Direct Procurement Contract Negotiation | German and Dutch meat analogue producers securing multi-year offtake agreements displace traditional distributor intermediaries. |
| Backward Integration into Feedstock Supply | Captive glucose production from beet processing neutralizes agricultural commodity cycle margin compression. |
| Indian BIS Compliance Alignment | Maharashtra and Karnataka supplement manufacturers evaluating mycelium powder for adaptogenic premium positioning. |
Study Parameters
The analysis maps textured mycelium, mushroom-based protein, Quorn-branded products, and generic MycoProtein ingredients, each validated through fermentation process engineers, food manufacturer procurement leads, regulatory affairs specialists at EFSA and FDA, and nutritional supplement formulators. Primary interviews with industrial mycologists and bioprocess engineering talent combined with secondary validation from EFSA Novel Food register entries, FDA GRAS notification database, BIS protein labeling standards documentation, and EU customs trade data. Bottom-up capacity assessments and top-down protein alternative market sizing triangulate volume and value outputs.
Consistency checks against external benchmarks validated projection outputs across the modeling period, with segmentation dimensions including fermentation methodology, downstream processing intensity, end-user channel economics, and geographic regulatory cluster. CAGRs derived from biomass yield trajectory modeling, capacity expansion announcements, and adoption curve analysis in food service and retail channels. Industry-specific inputs encompass continuous bioprocessing technology maturation timelines and EFSA guidance evolution on whole-cell biomass safety documentation.
Material uncertainties — regulatory reclassification of precision fermentation outputs, feedstock cost volatility from agricultural commodity cycles, and fermentation specialist talent scarcity — sit outside the modeled envelope. Forecasts reflect assumptions on technology adoption rates, certification barrier persistence, and channel consolidation trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Hemp-Based Products Market
Alternative Food Sources
Europe Upcycled Food Products Market
Alternative Food Sources
Egg Replacers Market
Alternative Food Sources
Insect Snacks Market
Alternative Food Sources
Asia-Pacific Fat Replacers Market
Alternative Food Sources
Middle East and Africa Meal Replacement Products Market
Alternative Food Sources
Spirulina Market
Alternative Food Sources
Global Algal Oil Market
Alternative Food Sources
Fish Meal Alternative Market
Alternative Food Sources
Global Alternative Protein Market
Alternative Food Sources
Mycoprotein Products Market
Alternative Food Sources
Microalgae Based Products Market
Alternative Food Sources
Emergency Food Market
Alternative Food Sources
Global Meal Replacement Shakes Market
Alternative Food Sources
Vegan Sashimi Market
Alternative Food Sources
Fishless Fillets Market